
 Motion Stimulation Therapy Market | 2026-2036
Motion Stimulation Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Motion Stimulation Therapy Market Foresight
Modular device configurations are rebalancing how buyers evaluate motion stimulation systems, with standalone units now bundling remote monitoring capabilities into single procurement decisions. Medtronic leverages its neuromodulation infrastructure to anchor premium integrated system offerings across hospital networks. Boston Scientific Corporation competes through specialized electrical stimulation devices that dominate interventional pain management channels. DJO Global sustains broad rehabilitation center penetration with vibration therapy units that occupy the mid-market equipment tier.
Motion stimulation therapy encompasses mechanical, electrical, and vibrational modalities that induce controlled musculoskeletal responses through frequencies typically ranging from 20 to 50 Hz for vibration platforms and 1 to 120 Hz for neuromuscular electrical stimulation. These interventions restore motor function, accelerate tissue repair, and modulate pain signaling in clinical and athletic populations. Electrical stimulation devices lead product type revenue due to established reimbursement codes, while remote monitoring solutions within delivery mode represent the fastest-expanding segment as telehealth infrastructure matures. Sports medicine commands disproportionate margin pools within therapy area segmentation because professional athletic organizations absorb premium pricing for accelerated recovery protocols.
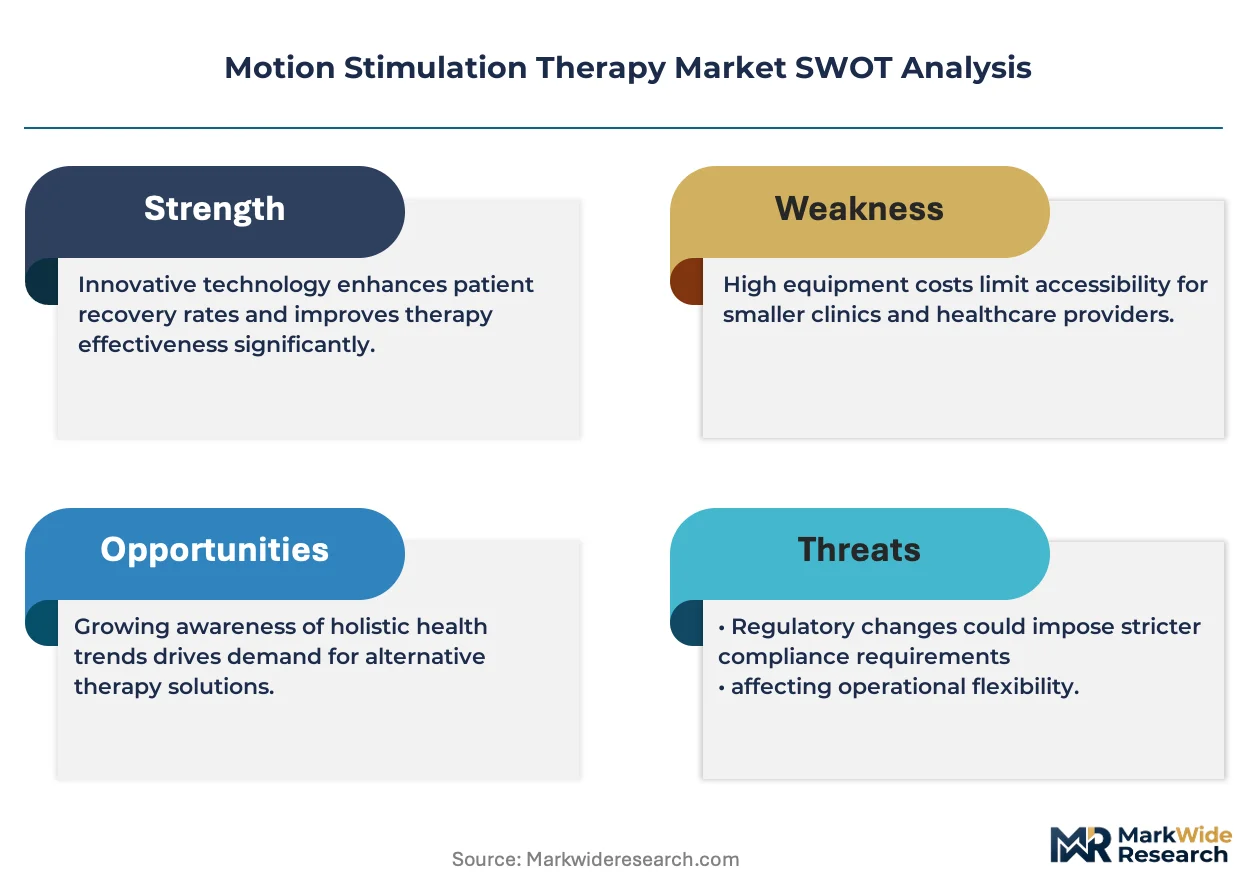
FDA 510(k) pathways govern electrical stimulation device approvals in the United States, while the EU MDR framework imposes clinical evidence requirements on neuromuscular devices marketed across European member states. ISO 13485 certification shapes supplier qualification standards for OEM partnerships and hospital procurement committees. Stakeholders must monitor evolving digital health regulations that will determine whether mobile application-integrated systems require separate software-as-medical-device classifications.
Market Dynamics
Remote patient monitoring infrastructure is compressing device procurement cycles across rehabilitation networks, bundling hardware and telemetry into unified purchasing decisions that bypass traditional equipment-only vendors.
Growth Catalysts
- FDA 510(k) Streamlining:Expedited clearance pathways for electrical stimulation devices reduce time-to-market for neuromuscular systems entering United States distribution channels.
- German Sports Medicine Integration:Vibration therapy protocols achieve institutional adoption within professional athletic recovery programs, creating concentrated demand clusters in Munich and Berlin clinic networks.
- Telehealth Infrastructure Maturation:Cloud-based remote monitoring capabilities enable real-time patient adherence tracking, expanding reimbursable service models beyond clinic walls.
Market Restraints
- EU MDR Clinical Evidence Burden:Expanded documentation requirements for neuromuscular devices marketed across European member states extend certification timelines and inflate regulatory compliance costs.
- Semiconductor Component Concentration:Precision signal processing chips for electrical stimulation units source predominantly from East Asian foundries, exposing supply chains to geopolitical disruption risk.
- Battery Chemistry Limitations:Lithium-ion energy density constraints restrict portable device operating duration, forcing trade-offs between treatment session length and wearable form factors.
Strategic Opportunities
- Home-Based Rehabilitation Expansion:Patient preference for domiciliary recovery settings creates whitespace for prescription-grade vibration platforms with insurance reimbursement pathways.
- ISO 13485-Certified OEM Partnerships:Outsourced manufacturing relationships with quality-certified suppliers enable mid-tier device makers to access hospital procurement committees previously gated by certification barriers.
- Digital Therapeutics Convergence:Integration of motion stimulation hardware with software-as-medical-device applications opens subscription revenue streams alongside capital equipment sales.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Shortage of specialists combining neuromuscular physiology expertise with embedded systems development constrains product innovation velocity.
- Legacy EMR Integration Complexity:Hospital information system compatibility requirements force costly customization workstreams for device data interoperability.
- Software-as-Medical-Device Classification Uncertainty:Evolving regulatory frameworks for mobile application-integrated systems create compliance planning ambiguity across development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motion Stimulation Therapy Market |
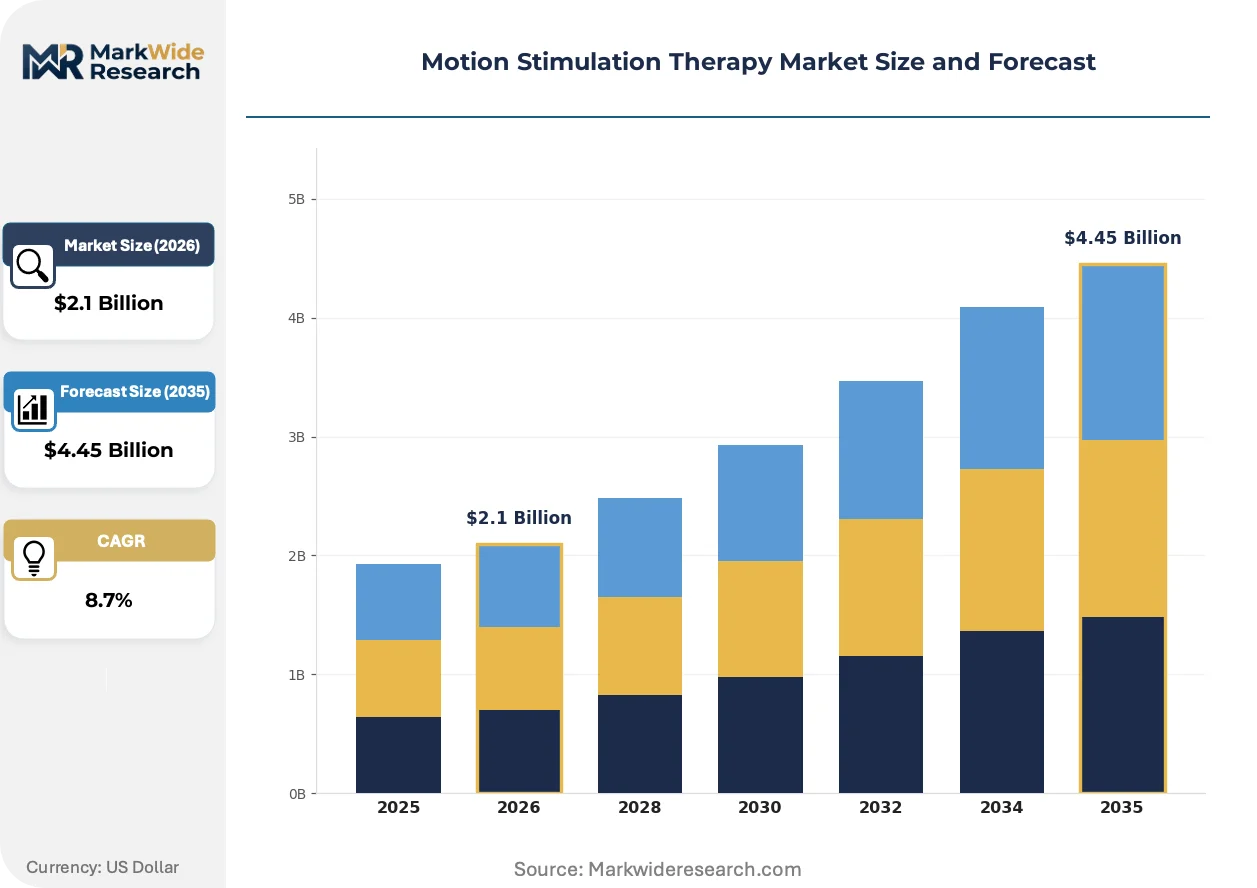
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Stimulation Devices, Vibration Therapy Units, Resistance Training Equipments, Neuromuscular Devices End User: Rehabilitation Centers, Sports Clinics, Home Care, Fitness Centers Therapy Area: Orthopedic Rehabilitation, Sports Medicine, Neurology, Geriatrics Delivery Mode: Standalone Devices, Mobile Applications, Integrated Systems, Remote Monitoring Solutions |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott Laboratories, LivaNova PLC, Nevro Corp, Cyberonics, DJO Global, NeuroPace, Innovative Neurotronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motion Stimulation Therapy Market Shifts & Advancements
Device architectures are converging around modular platforms that unify mechanical, electrical, and vibrational modalities within single hardware footprints, collapsing what were previously separate procurement categories.
Multi-modal stimulation hardware is consolidating previously distinct therapeutic categories into unified device platforms. Rehabilitation centers in the United States and Germany now specify combined electrical-vibration systems rather than standalone units. This convergence is compressing vendor count per facility and elevating technical specifications required for contract eligibility.
EU MDR implementation is recalibrating clinical evidence standards for neuromuscular devices marketed across European member states. Manufacturers must now submit expanded biocompatibility and performance documentation that exceeds predecessor Medical Device Directive requirements. German notified bodies report extended review queues, prompting some suppliers to prioritize United States FDA submissions over European market entry.
Athletic organizations are compressing vendor evaluation cycles and demanding outcome-guarantee provisions within equipment procurement contracts. Professional sports franchises in Germany now specify recovery-metric benchmarks as contractual conditions for vibration therapy platform purchases. This performance-accountability model is migrating from elite athletic settings into hospital outpatient rehabilitation departments.
Motion Stimulation Therapy Market Segmentation
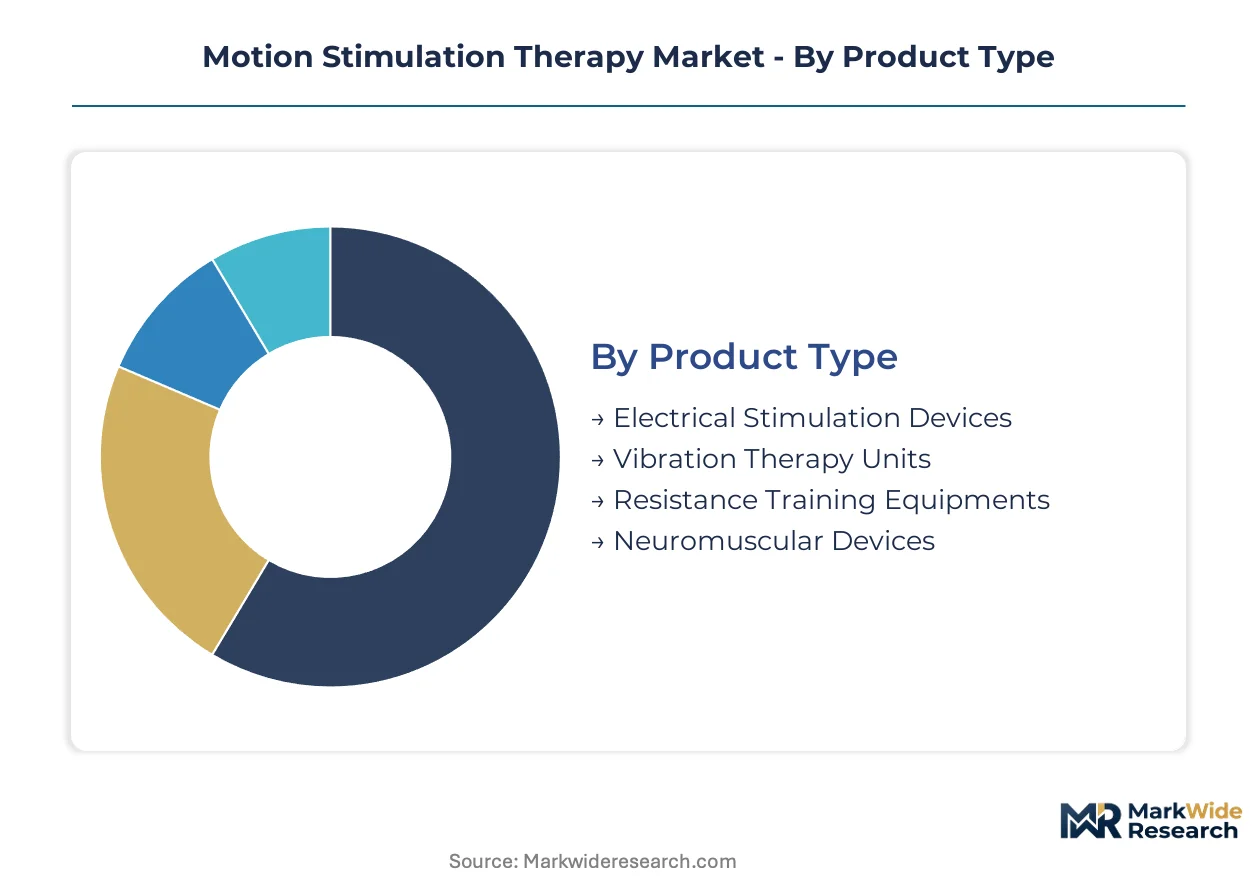
Motion stimulation therapy markets fragment across hardware architectures, care settings, therapeutic targets, and delivery interfaces. Procurement committees evaluate these dimensions simultaneously as bundled purchasing decisions replace single-modality acquisitions.
Product Type:
Integration depth separates standalone therapeutic units from embedded neuromodulation systems requiring surgical implantation or clinical supervision.
- Electrical Stimulation Devices:Surface electrode systems and implantable pulse generators deliver controlled current pulses to modulate pain signaling or restore motor function. Rehabilitation centers in the United States prioritize FDA-cleared units with established reimbursement codes for chronic pain management.
- Vibration Therapy Units:Platform and handheld devices generate mechanical oscillations at 20-50 Hz frequencies to stimulate proprioceptive response and accelerate tissue repair. German sports medicine clinics in Munich and Berlin specify these systems for athlete recovery protocols, absorbing premium pricing for performance-guaranteed outcomes.
- Resistance Training Equipments:Motor-assisted and pneumatic systems combine load-bearing exercise with motion guidance for post-surgical rehabilitation.
- Neuromuscular Devices:Functional electrical stimulation systems targeting specific muscle groups for paralysis or motor deficit conditions.
Electrical stimulation devices lead volumes today; remote monitoring solutions are gaining share fastest.
End User:
Cost tier stratification distinguishes capital-intensive institutional purchasers from price-sensitive individual consumers seeking home-based alternatives.
- Rehabilitation Centers:Hospital outpatient departments and standalone facilities specify multi-modal platforms with EMR integration capabilities. These buyers negotiate service contracts bundling hardware, maintenance, and outcome analytics under single procurement frameworks.
- Sports Clinics:Professional athletic organizations and private sports medicine practices demand vibration therapy systems with performance benchmarking provisions. German franchises now embed recovery-metric guarantees into equipment purchase agreements.
- Home Care:Prescription-grade devices for domiciliary recovery settings, constrained by insurance reimbursement pathway availability and battery chemistry limitations.
- Fitness Centers:Consumer-facing wellness facilities acquiring entry-level vibration platforms for general membership use.
Rehabilitation centers anchor institutional demand; home care represents the steepest expansion trajectory as telehealth infrastructure matures.
Therapy Area:
Application severity differentiates acute post-surgical protocols from chronic condition management requiring sustained intervention.
- Sports Medicine:Accelerated recovery programs for professional and amateur athletes targeting return-to-play timelines. Professional organizations absorb premium pricing for outcome-guaranteed equipment, creating concentrated margin pools.
- Orthopedic Rehabilitation:Post-surgical joint replacement and fracture recovery protocols emphasizing range-of-motion restoration. United States hospital networks specify electrical stimulation devices with established CPT reimbursement codes.
- Neurology:Stroke rehabilitation and neurodegenerative condition management requiring specialized neuromuscular electrical stimulation protocols.
- Geriatrics:Fall prevention and sarcopenia interventions targeting aging populations in institutional and community settings.
Sports medicine commands premium pricing; geriatrics is climbing the fastest as demographic aging concentrates demand.
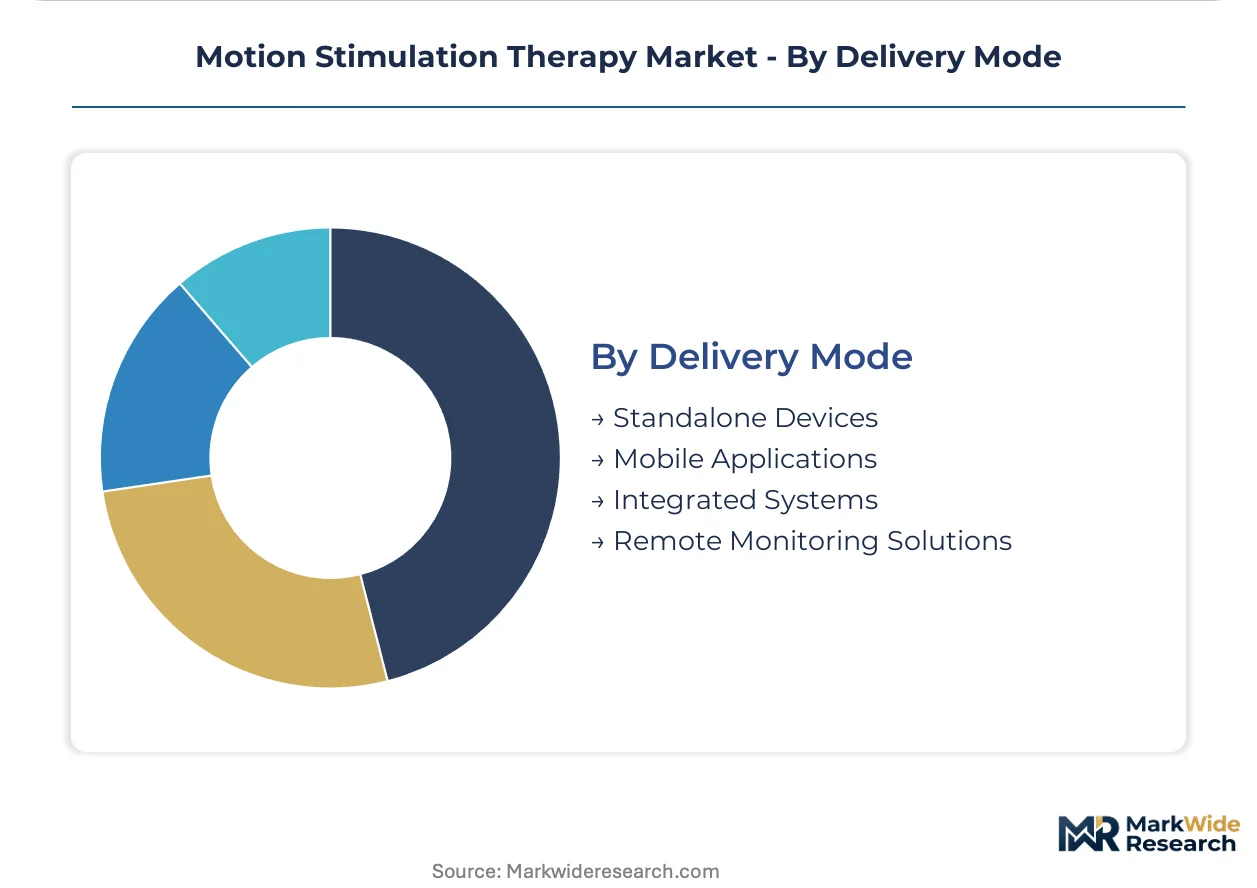
Delivery Mode:
Maturity gradients separate decades-established hardware categories from emerging digital health interfaces facing regulatory classification uncertainty.
- Standalone Devices:Traditional hardware units operating without network connectivity, dominating current installed bases but facing displacement pressure.
- Integrated Systems:Multi-modal platforms unifying electrical, vibrational, and mechanical stimulation within single footprints. Rehabilitation centers in Germany and the United States now specify these over discrete single-function units.
- Remote Monitoring Solutions:Cloud-connected devices enabling real-time adherence tracking and clinician oversight beyond clinic walls. FDA and EU MDR frameworks are evolving to address software-as-medical-device classification for these systems.
- Mobile Applications:Smartphone-integrated control interfaces and patient-facing software requiring separate regulatory evaluation under emerging digital health pathways.
Standalone devices retain installed base dominance; remote monitoring solutions are expanding most quickly as bundled procurement decisions accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Motion stimulation therapy originated in German sports medicine clinics during the 1990s, where vibration protocols were first systematized for athlete recovery. The United States subsequently scaled electrical stimulation device manufacturing through FDA-cleared reimbursement pathways. Today, demand clusters concentrate in rehabilitation hubs across Germany, the United States, Japan, and Australia.
United States
Hospital outpatient departments drive institutional procurement of multi-modal platforms with EMR integration capabilities. FDA 510(k) clearance pathways streamline market entry for neuromuscular electrical stimulation devices with established CPT reimbursement codes. Minneapolis and Boston anchor device development clusters where Medtronic and Boston Scientific Corporation maintain neuromodulation infrastructure.
Germany
Professional athletic organizations in Munich and Berlin specify vibration therapy systems with performance-guarantee provisions embedded in procurement contracts. EU MDR implementation through German notified bodies imposes expanded clinical evidence requirements on neuromuscular device manufacturers. The Bavarian sports medicine corridor concentrates demand for outcome-accountable equipment serving Bundesliga franchise recovery programs.
Japan
Aging demographics concentrate demand for geriatric fall-prevention and sarcopenia interventions in Tokyo and Osaka metropolitan rehabilitation networks. PMDA regulatory frameworks govern electrical stimulation device approvals with emphasis on biocompatibility documentation. The Kansai region hosts specialized neuromuscular research facilities integrating vibration protocols into stroke rehabilitation programs.
Australia
Private sports medicine practices in Sydney and Melbourne adopt vibration platforms for professional athlete return-to-play protocols. TGA regulatory pathways align with ISO 13485 certification standards for hospital procurement qualification. The Victorian rehabilitation technology corridor connects university research hospitals with device distribution networks serving the Australian Football League.
United Kingdom
NHS rehabilitation trusts in London and Manchester evaluate bundled procurement frameworks combining hardware, maintenance, and remote monitoring services. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR clinical evidence standards for neuromuscular devices. The Oxford-Cambridge medical technology arc hosts emerging digital health ventures developing software-integrated stimulation platforms.
Motion Stimulation Therapy Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with established neuromodulation infrastructure. Market concentration remains moderate, with premium integrated systems commanding hospital procurement committees while mid-tier vibration units serve price-sensitive rehabilitation networks. Three archetypes dominate: diversified conglomerates leveraging cross-divisional technology transfer, specialized neuromodulation pure-plays, and rehabilitation equipment generalists. Strategic moves center on ISO 13485-certified OEM partnerships and digital therapeutics convergence through software-as-medical-device integration.
Within the diversified conglomerate tier, Medtronic anchors premium integrated system offerings across United States hospital networks through its neuromodulation infrastructure. Boston Scientific Corporation occupies the specialized electrical stimulation position, with its product portfolio dominating interventional pain management channels. DJO Global exemplifies the rehabilitation equipment generalist archetype, sustaining broad penetration of vibration therapy units across mid-market institutional buyers. These three entities collectively represent the competitive spectrum from capital-intensive integrated systems to accessible single-modality platforms.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| LivaNova PLC |
| Nevro Corp |
| Cyberonics |
| DJO Global |
| NeuroPace |
| Innovative Neurotronics |
| Others |
Supply & Pricing Matrix
Captive semiconductor sourcing from East Asian foundries anchors both supply security and pricing power for electrical stimulation device manufacturers. This integration pattern forces trade-offs between treatment session duration and wearable form factors, compressing margins in portable device tiers while integrated hospital systems maintain premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared integrated systems from ISO 13485-certified mid-market units and uncertified consumer-grade alternatives. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because battery chemistry limitations force design compromises. Home care segments exhibit highest price sensitivity; sports medicine clinics absorb premium pricing for outcome-guaranteed equipment.
Supply Chain Analysis
Domestic-content mandates in the United States and Germany are reshaping sourcing for hospital procurement qualification. Precision signal processing chips draw from Taiwan, South Korea, and Japan; lithium-ion cells feed from China and South Korea. Single-source vulnerability concentrates in advanced neuromodulation chipsets. Distribution runs through GPO contracts and direct hospital system partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: FDA 510(k) streamlining in the United States offers faster time-to-market than EU MDR clinical evidence burdens, compressing European entry costs for capital-constrained entrants.
For Market Incumbents: Acquire remote monitoring software capabilities to defend against digital therapeutics disintermediation. Consolidate ISO 13485-certified OEM partnerships in Germany to preempt mid-tier competitors from hospital procurement committees. Prioritize EMR integration investments to lock in rehabilitation center switching costs. For New Entrants and Emerging Players: Enter via prescription-grade home care devices with insurance reimbursement pathways, the most penetrable whitespace as telehealth infrastructure matures. Target Australian and United Kingdom markets where TGA and MHRA pathways offer faster clearance than EU MDR queues. Deploy direct-to-clinic sales models bypassing established GPO contracts. For Investors and Strategic Acquirers: Roll-up economics work for specialized neuromodulation pure-plays because fragmented rehabilitation equipment generalists lack digital therapeutics integration capabilities. The five-to-ten year viability window favors platforms combining hardware with SaaS revenue streams. Watch FDA software-as-medical-device classification clarity as the inflection signal for digital health valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Expedited clearance pathways compress time-to-market for neuromuscular systems entering United States distribution. |
| EU MDR CE Marking Pathway | Expanded clinical evidence requirements extend certification timelines through German notified bodies. |
| Hospital System Partnership | Bundled procurement frameworks combining hardware, maintenance, and remote monitoring services lock in institutional demand. |
| Software Companion Development | Mobile application integration opens subscription revenue streams alongside capital equipment sales. |
| Reimbursement Strategy | Established CPT codes for electrical stimulation devices anchor United States hospital purchasing decisions. |
Research Methodology
Multiple input streams — primary interviews with rehabilitation center directors, biomedical engineers, and GPO contracts managers; secondary validation against FDA 510(k) filings, EU MDR submission databases, and hospital procurement records; and proprietary equipment shipment tracking — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured institutional purchasing criteria and vendor evaluation cycles across United States, German, and Australian markets.
Historical volume trajectories were cross-referenced against panel input from device manufacturers and regulatory consultants. The analytical framework models product type, end user, therapy area, and delivery mode dimensions across the analysis window. CAGRs were derived from segment-level growth rate reconciliation with macro healthcare expenditure trends and telehealth infrastructure deployment curves. Forecast inputs include reimbursement code expansion timelines and EU MDR notified body queue lengths.
Inputs from FDA pre-submission meetings and German sports medicine clinic procurement records were available through the study window; gaps in real-time EU MDR review duration data introduce uncertainty bands around European market entry timing assumptions. Forecasts reflect documented assumptions regarding telehealth reimbursement policy evolution and semiconductor supply chain stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
Home Rehabilitation Services Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market
Rehabilitation Services
Physiotherapy Services Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Brachial Plexus Injury Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
Neurorehabilitation Gaming Systems Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
US Physical Therapy Services Market
Rehabilitation Services
Global Gait Trainer Market