
 Physiotherapy Services Market | 2026-2036
Physiotherapy Services Market Size, Share, and Industry Trends Forecast 2026-2036
Physiotherapy Services Market Intelligence
Revenue from traditional, high-volume in-clinic sessions is fragmenting as specialized and digital-first models gain traction. FYZICAL leverages a franchise-based model to expand its geographic footprint across the United States. Meanwhile, digital native providers like Exakt Health specialize in app-based guidance for specific conditions such as running injuries. Established networks like Pivot Physical Therapy sustain their market position through a dense network of outpatient orthopedic clinics.
Physiotherapy services encompass a healthcare discipline aimed at restoring and maintaining patient mobility, function, and well-being. Practitioners use evidence-based techniques, including manual therapy and targeted exercise prescription, to address impairments and improve metrics like joint range of motion. Orthopedic rehabilitation continues to constitute the largest service type segment by volume. However, tele-rehabilitation is reshaping delivery models, offering new avenues for patient engagement and chronic condition management, while sports injury management commands higher service margins.
Provider credentialing and practice standards are governed by national and state-level bodies, such as provincial colleges in Canada and the Health and Care Professions Council in the UK. In the United States, HIPAA regulations impose strict data privacy requirements on tele-rehabilitation platforms, influencing technology adoption. Service providers must now strategically balance investments between physical clinic expansion and the development of secure, effective digital health platforms.
Market Dynamics
The central structural force is the bifurcation of service models between high-volume, geographically expanding physical clinics and hyper-specialized, digital-first providers. This dynamic fragments the traditional revenue base of general in-clinic sessions, forcing incumbents to adopt hybrid strategies.
Growth Catalysts
- Aging Demographics:Government healthcare policies in developed nations, including Germany, prioritize funding for geriatric care, directly increasing demand for physiotherapy services within residential and long-term care facilities to manage mobility and chronic conditions.
- Tele-rehabilitation Platforms:The integration of digital health technologies expands patient access, particularly for individuals in rural locations or with mobility limitations, and improves adherence to long-term management programs for chronic orthopedic and neurological conditions.
- Sports Medicine Demand:A focus on sports injury management and performance optimization commands higher service margins, attracting provider investment and specialization to serve a growing population of amateur and professional athletes.
Market Restraints
- Data Privacy Compliance:Stringent regulations like the Health Insurance Portability and Accountability Act (HIPAA) in the US impose significant cost and complexity on developing and operating tele-rehabilitation platforms, slowing technology adoption.
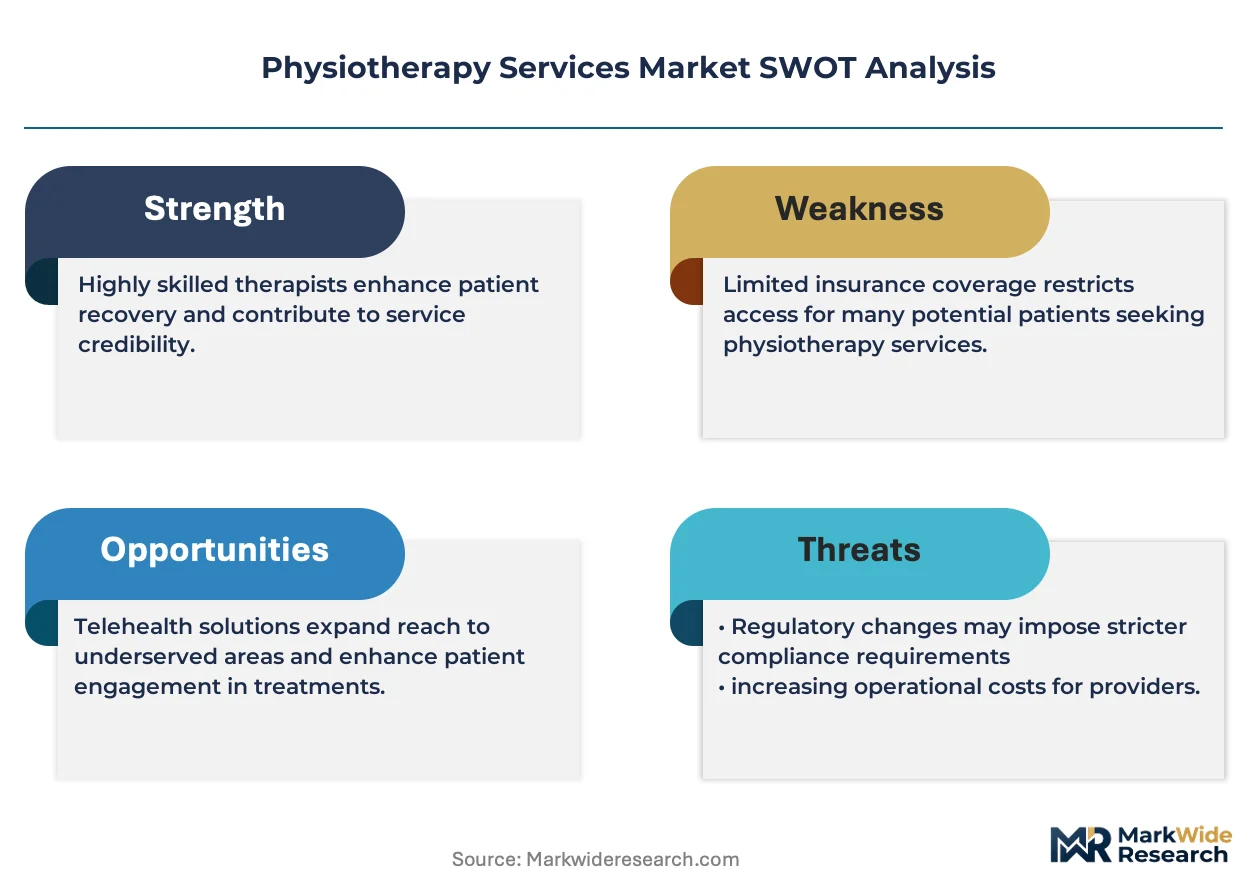
- Reimbursement Ambiguity:Payer and national health system reimbursement models often lag behind technological innovation, creating financial uncertainty for providers investing in novel digital or hybrid service delivery methods that lack established billing codes.
- Substitution from Wellness Apps:The proliferation of low-cost, direct-to-consumer fitness and wellness applications presents a substitution threat for non-acute conditions, attracting users who might otherwise seek professional physiotherapy for minor strains or general fitness.
Strategic Opportunities
- Niche Chronic Conditions:Developing specialized digital rehabilitation programs for underserved chronic conditions beyond orthopedics, such as long-COVID or other post-viral fatigue syndromes, offers a significant new growth vector for providers.
- Emerging Economies:Expansion of low-cost, mobile-first physiotherapy guidance into markets across Southeast Asia and Latin America, where healthcare infrastructure is developing and middle-class spending is rising, represents a substantial volume opportunity.
- AI and Wearable Integration:Converging AI-powered diagnostic software with data streams from patient wearables enables the creation of highly personalized, adaptive, and continuously monitored rehabilitation protocols, improving patient outcomes and demonstrating value to payers.
Industry Challenges
- Hybrid Skillset Scarcity:A persistent shortage of therapists proficient in both traditional hands-on manual techniques and the effective clinical application of digital health platforms creates a critical training and recruitment bottleneck for service providers.
- EHR Interoperability:Integrating new, specialized tele-rehabilitation software with legacy electronic health record (EHR) systems within hospitals and large clinic networks remains a major technical and operational barrier to seamless care coordination.
- Navigating Credentialing:The lack of standardized, international practitioner credentialing requires providers to navigate a complex and fragmented landscape of national and state-level requirements, such as those from the UK's HCPC, complicating expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Physiotherapy Services Market |
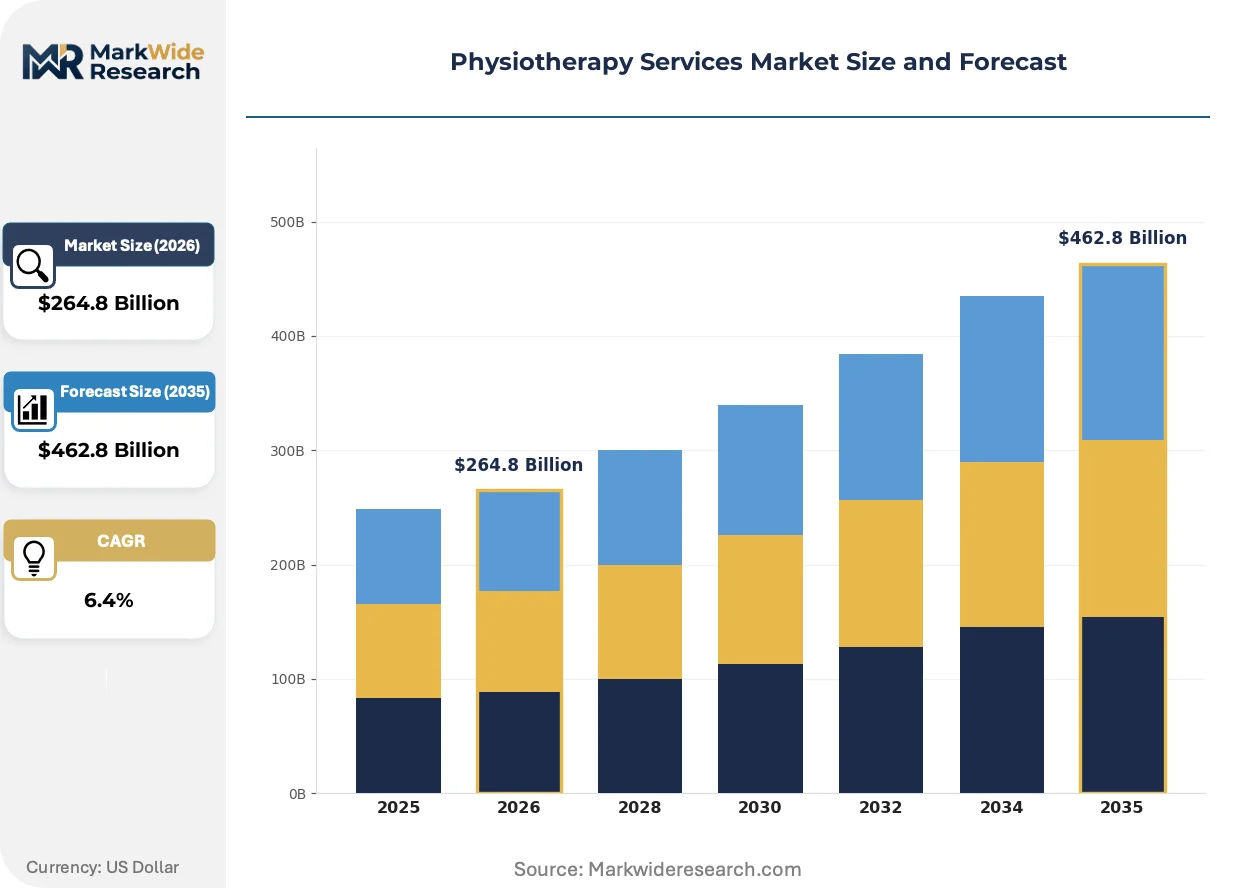
| Market Size in 2026 | $264.8 Billion |
| Market Size in 2035 | $462.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Orthopedic Rehabilitation, Neurological Therapy, Cardiopulmonary Restoration, Sports Injury Management, Pediatric Therapy Delivery Model: In-Clinic Sessions, Home Visits, Tele-rehabilitation, Community Wellness Programs, Corporate Health Initiatives End User: Patient Clinics, Rehabilitation Centers, Sports Academies, Elderly Care Facilities, Military Health Units Technology: Electrotherapy Devices, Therapeutic Ultrasound, Laser Therapy Equipment, Robotic Exoskeletons, Virtual Reality Systems |
| Companies Covered | Pivot Physical Therapy, Exakt Health, FYZICAL, Embodia, Movetru Ltd, Professional Physical Therapy, ApexNetwork Physical Therapy, One Body LDN, NovaCare Rehabilitation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Physiotherapy Services Market Strategic Shifts & Innovations
Service delivery is being fundamentally reconfigured, moving beyond the clinic walls. This evolution is driven by technological capabilities that enable more continuous and personalized patient engagement, shifting the focus from episodic treatment to ongoing health management and prevention.
Technology-Led Hybridization
Tele-rehabilitation platforms, incorporating video consultations and AI-driven exercise feedback, provide remote patient guidance. Major health systems and specialized orthopedic groups are adopting these tools to extend care post-discharge. This technology is hybridizing patient pathways, combining the convenience of remote monitoring with the necessity of in-clinic manual therapy for complex cases.
Regulatory Reclassification of Software
The EU's Medical Device Regulation (MDR) now classifies certain rehabilitation software as a medical device, requiring rigorous clinical evaluation and post-market surveillance. This regulation increases the compliance burden and development timeline for software-based physiotherapy tools. Digital health developers targeting the European market must now secure CE marking, aligning their products with higher safety and performance standards.
Consumerization of Care
Patient demand is shifting toward on-demand and consumer-driven care models, often bypassing traditional physician referral pathways. This change favors direct-to-consumer, app-based services for specific issues like running injuries or back pain, disintermediating the general practitioner role for certain conditions. This trend is most visible in metropolitan areas of the United States and the UK with high concentrations of digitally native users.
Physiotherapy Services Market Segmentation
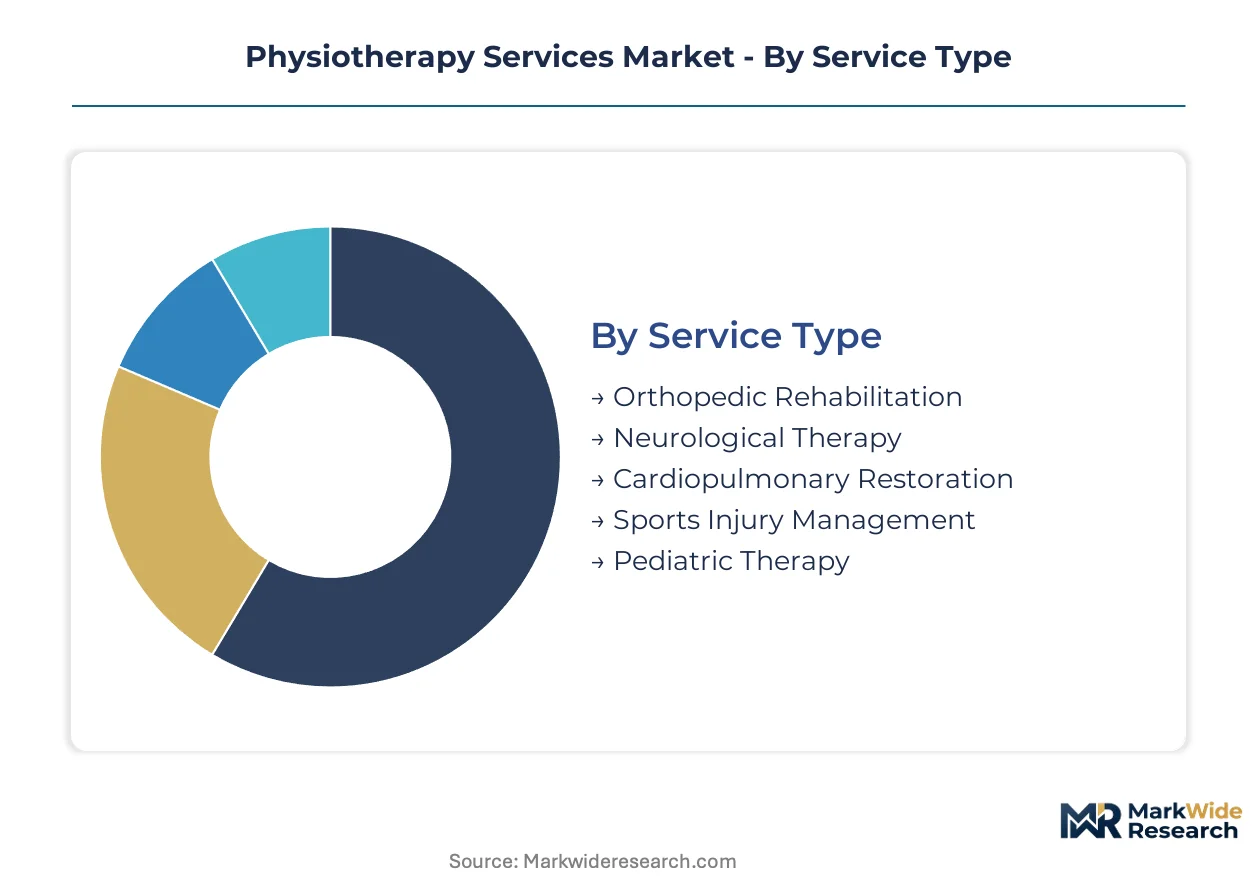
Understanding the diverse segments within the physiotherapy services market is crucial for strategic planning. This segmentation provides clarity on distinct service offerings, delivery mechanisms, and target populations. Analyzing these categories reveals where demand is concentrated and where innovation is driving new opportunities across the sector.
Service Type:
The spectrum of service types delineates the specialized therapeutic areas addressed by physiotherapy.
- Orthopedic Rehabilitation:This segment focuses on musculoskeletal conditions, including post-surgical recovery, fractures, and chronic joint pain. Demand concentrates in developed nations like Germany, driven by an aging population requiring mobility restoration and chronic condition management.
- Sports Injury Management:This involves specialized interventions for athletic injuries, performance enhancement, and preventative care for athletes. This area commands higher service margins, with significant demand from professional sports organizations and amateur athletic communities in the United States.
- Neurological Therapy:Addresses conditions affecting the brain, spinal cord, and nerves, such as stroke recovery or Parkinson's disease, requiring specialized rehabilitation protocols.
- Cardiopulmonary Restoration:Improves physical function for patients with heart or lung conditions, often post-cardiac event or for chronic respiratory issues.
- Pediatric Therapy:Provides specialized rehabilitative care for children with developmental delays, congenital conditions, or injuries.
Orthopedic Rehabilitation commands the established base. The steepest expansion runs through Sports Injury Management.
Delivery Model:
Application of different delivery methods determines patient access and operational efficiency within the market.
- In-Clinic Sessions:These involve traditional, direct patient-therapist interactions within a physical facility, offering comprehensive assessment and manual therapy. This model maintains a large volume base, particularly for complex cases requiring specialized equipment or hands-on techniques.
- Tele-rehabilitation:Utilizes digital platforms for remote consultations and exercise guidance, expanding access for rural patients. Demand accelerates in regions with robust digital infrastructure, like the United States, driven by convenience.
- Home Visits:Practitioners provide services in a patient's residence, catering to individuals with significant mobility limitations or post-discharge care needs.
- Community Wellness Programs:These initiatives offer group-based rehabilitation and preventative exercises in community settings, promoting broader public health engagement.
- Corporate Health Initiatives:Physiotherapy services within corporate environments, focusing on employee well-being, injury prevention, and ergonomic assessments.
In-Clinic Sessions remain the foundational delivery method. Expansion is gaining momentum within Tele-rehabilitation.
End User:
Customer type segmentation highlights distinct needs and funding mechanisms across various patient populations.
- Patient Clinics:These are primary outpatient settings where individuals seek general physiotherapy services for diverse conditions. This segment represents a significant volume of direct patient engagement, particularly in urban and suburban areas with accessible healthcare infrastructure.
- Elderly Care Facilities:These institutions provide specialized physiotherapy for geriatric residents, focusing on mobility, fall prevention, and chronic disease management. Demand concentrates in developed nations with aging demographics, like Germany.
- Rehabilitation Centers:Specialized facilities offering intensive, multidisciplinary rehabilitation programs for complex injuries or neurological conditions.
- Sports Academies:These facilities integrate physiotherapy services for injury prevention, performance optimization, and rapid recovery for athletes in training.
- Military Health Units:Provide rehabilitative care for service members with combat-related injuries, musculoskeletal issues, and post-traumatic stress.
Patient Clinics form the largest direct-to-consumer channel. The fastest-growing demand originates from Elderly Care Facilities.
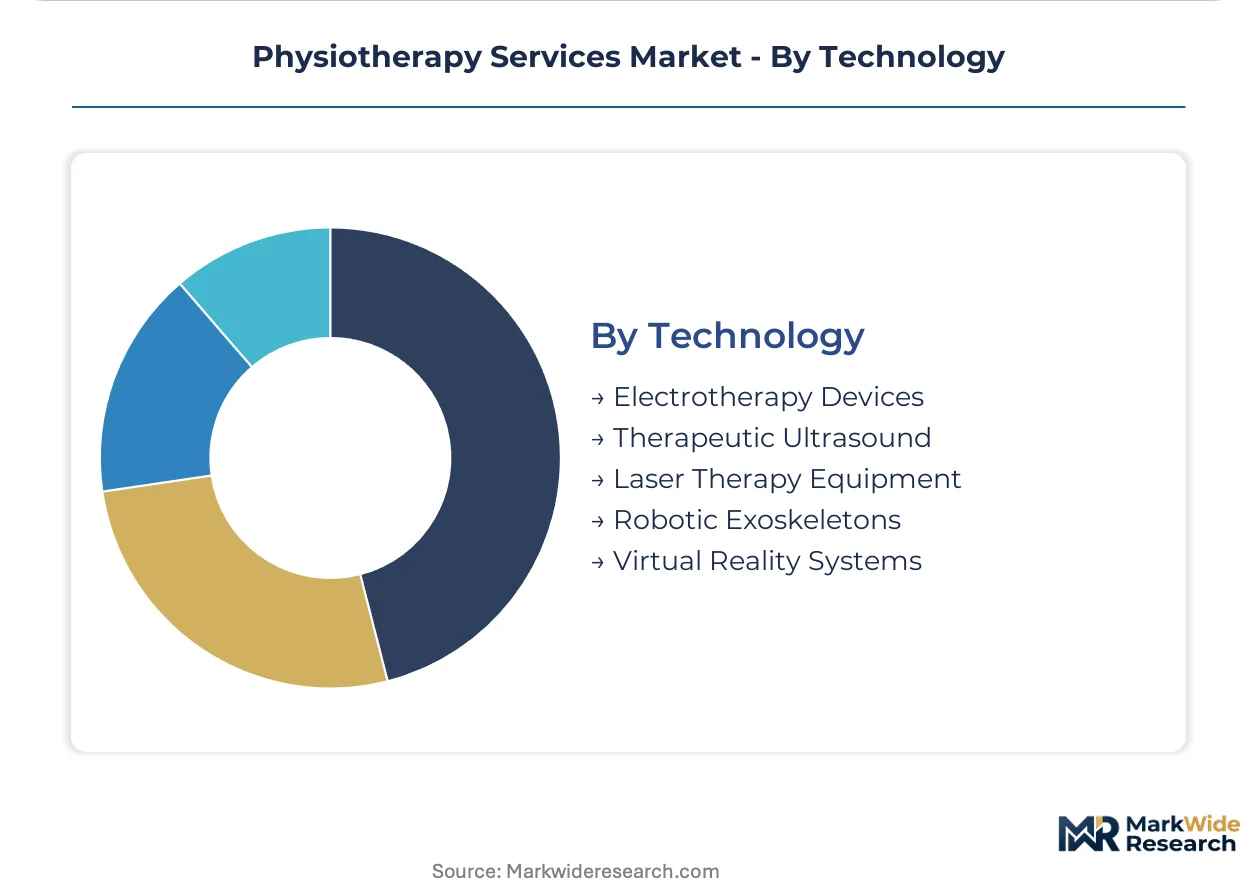
Technology:
Maturity and innovation in technology segments define the tools available for therapeutic intervention.
- Electrotherapy Devices:These tools use electrical stimulation for pain relief, muscle re-education, and tissue repair, representing a well-established modality in clinical practice. Their adoption is widespread across most physiotherapy clinics for acute and chronic pain management.
- Virtual Reality Systems:Immersive technologies offering engaging, gamified rehabilitation for neurological and orthopedic conditions, improving patient adherence. Investment rises in specialized rehabilitation centers for cognitive and motor skill retraining.
- Therapeutic Ultrasound:Utilizes high-frequency sound waves to promote tissue healing, reduce inflammation, and alleviate pain in various musculoskeletal conditions.
- Laser Therapy Equipment:Employs focused light energy to accelerate cellular repair, reduce pain, and decrease swelling in soft tissue injuries.
- Robotic Exoskeletons:Wearable robotic devices assisting patients with severe mobility impairments to regain walking function and improve motor control.
Electrotherapy Devices are a mature segment foundational to many practices. Virtual Reality Systems are experiencing rapid uptake for innovative patient engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for physiotherapy services exhibits varying elasticity across global markets. Buyers in developed nations often demonstrate lower price sensitivity due to robust public health funding and specialized care needs. Conversely, emerging economies present higher price elasticity, favoring scalable, lower-cost digital solutions. This bifurcation shapes investment and service delivery models globally.
Germany
Germany's demand for physiotherapy services stems from its aging population requiring extensive geriatric care. Government healthcare policies prioritize funding for mobility management and chronic condition support. The EU's Medical Device Regulation (MDR) influences software development for specialized clinics in Berlin.
United States
The United States sees significant demand for sports injury management and tele-rehabilitation services. HIPAA regulations impose strict data privacy requirements on digital health platforms. Major metropolitan areas like Los Angeles drive consumerization of care and the uptake of app-based services.
Canada
Canada's market relies on sustained demand for general mobility restoration and chronic condition management. Provincial colleges govern practitioner credentialing and practice standards. Cities such as Toronto are seeing development in specialized rehabilitation centers and hybrid care models.
United Kingdom
Demand in the United Kingdom is shifting towards consumer-driven care models and post-discharge rehabilitation. The Health and Care Professions Council (HCPC) oversees national credentialing. London's metropolitan areas are hotspots for digital-native users seeking app-based services for common issues.
Brazil
Brazil offers a substantial volume opportunity due to its rising middle-class spending and developing healthcare infrastructure. ANVISA, the national health surveillance agency, regulates medical devices and health services. Major cities like São Paulo are experiencing expansion in low-cost, mobile-first physiotherapy guidance.
Physiotherapy Services Market Key Industry Players
Capability concentration sits with one tier, emphasizing specialized digital solutions and niche expertise; scale advantage sits with another, focusing on broad geographic reach through traditional clinics. The market exhibits a tiered structure, from fragmented local providers to expanding national networks. Key archetypes include franchise-based operators, digital-first specialists, and established outpatient clinic chains. Dominant competitive moves involve rapid geographic expansion and the development of secure, effective digital health platforms.
Within the franchise-based expansion archetype, FYZICAL exemplifies a model for extending geographic footprint across the United States. Pivot Physical Therapy represents established networks sustaining their market position through a dense array of outpatient orthopedic clinics. Meanwhile, digital native providers like Exakt Health specialize in app-based guidance for specific conditions such as running injuries, demonstrating the shift towards hyper-specialized digital-first models. These companies collectively illustrate the strategic balance between physical clinic expansion and the integration of digital health solutions across the physiotherapy services market.
| Leading Market Players |
|---|
| Pivot Physical Therapy |
| Exakt Health |
| FYZICAL |
| Embodia |
| Movetru Ltd |
| Professional Physical Therapy |
| ApexNetwork Physical Therapy |
| One Body LDN |
| NovaCare Rehabilitation |
| Others |
Cost & Logistics Intelligence
Specialized rehabilitation equipment manufacturers in countries like Germany and the United States concentrate capability, influencing service delivery costs. This upstream concentration impacts margin pools for clinics investing in advanced therapeutic technologies.
Pricing Analysis
After-care support and long-term management programs drive significant lifetime value in physiotherapy. Pricing stratifies across premium, standard, and economy tiers, with value-based models for specialized interventions and subscription-based access for digital platforms. Quality of practitioner credentials and technology integration, such as VR systems, differentiate service costs. Pricing softness stems from substitution threats from low-cost wellness applications. Patients with non-acute conditions exhibit higher price sensitivity, while professional sports organizations prioritize specialized care.
Supply Chain Analysis
Regulatory classifications, such as the EU's Medical Device Regulation (MDR) for rehabilitation software, introduce compliance hurdles for technology flows. Specialized physiotherapy equipment often sources from Germany and the United States, while digital health platform development centers in the United States and the United Kingdom. The supply chain relies on a limited pool of therapists proficient in both manual techniques and digital health platforms. Hybrid skillset scarcity presents a structural risk. Distribution runs through established clinic networks, direct-to-consumer digital channels, and hospital partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A persistent shortage of therapists skilled in both traditional manual therapy and digital health platforms defines the physiotherapy services market. This dual proficiency gap creates a strategic imperative for all market participants.
For Market Incumbents: Entrench market position by investing heavily in upskilling existing therapist teams for digital platform proficiency. Acquire smaller, agile digital-first specialists to integrate new technological capabilities and counter revenue fragmentation from app-based services. Pursue advanced certifications for tele-rehabilitation platforms to ensure regulatory compliance and enhance service credibility. Expand clinic networks in underserved metropolitan areas to maintain physical presence.
For New Entrants and Emerging Players: Build out hyper-specialized digital rehabilitation programs targeting underserved chronic conditions like long-COVID. Focus on low-cost, mobile-first physiotherapy guidance in emerging economies such as Southeast Asia, representing a highly penetrable volume opportunity. Leverage AI-driven personalized exercise protocols as a core go-to-market angle to demonstrate value and improve patient outcomes. Develop partnerships with local healthcare providers for initial patient acquisition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed outpatient clinic networks seeking digital transformation. The market offers long-term viability, driven by aging demographics and rising chronic condition prevalence. Target digital-first providers with proven AI and wearable integration capabilities to enhance personalized care. A critical signal to watch is the expansion of established reimbursement codes for tele-rehabilitation services by national health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Therapist Training Programs | Addresses the critical skillset scarcity by developing practitioners proficient in both manual and digital therapies. |
| Tele-rehabilitation Platform Certification | Secures regulatory compliance (e.g., EU MDR) and enhances market trust for digital health solutions. |
| AI-Powered Diagnostic Software Integration | Creates highly personalized rehabilitation protocols, improving patient outcomes and demonstrating value to payers. |
| Emerging Market Digital Expansion | Captures substantial volume opportunities in regions with developing healthcare infrastructure and rising middle-class spending. |
| Specialized Chronic Condition Programs | Opens new growth vectors by addressing underserved patient populations beyond traditional orthopedic care. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings of this study. Primary insights gathered from physiotherapists, clinic owners, digital health platform developers, and regulatory affairs specialists inform the analysis. Secondary validation draws from national health statistics, medical device regulations like HIPAA and EU MDR. A rigorous bottom-up and top-down triangulation approach ensures data accuracy.
The calibration approach integrates quantitative modeling with qualitative market insights across the analysis window. Segmentation dimensions including service type, delivery model, end user, technology, and chronic condition focus were modeled. Compound Annual Growth Rates were derived from historical trends, identified market drivers, and expert consensus. Key forecast inputs include global aging population data and tele-rehabilitation platform adoption rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-first specialists or major health systems would shift outcomes. Projections reflect current technological trajectories and regulatory frameworks. Material shifts in major payer reimbursement policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
US Physical Therapy Services Market
Rehabilitation Services
Global Medical Rehabilitation Services Market
Rehabilitation Services
Global Home Rehabilitation Products and Services Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Global Neurorehabilitation Devices Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
Massage Therapy Services Market
Rehabilitation Services
Speech Therapy Services Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
Wearable Neurorehabilitation Devices Market
Rehabilitation Services
Rehabilitation Equipment Market