
 Neurorehabilitation Gaming Systems Market | 2026-2036
Neurorehabilitation Gaming Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Neurorehabilitation Gaming Systems Market Analysis
ISO 13485 certification for medical device quality management is redrawing competitive boundaries in neurorehabilitation gaming. MindMaze leverages its Swiss regulatory pedigree to anchor premium positioning in European hospital networks. Nintendo sustains consumer-scale manufacturing economics that competitors struggle to replicate for clinical-grade hardware. XRHealth differentiates through telehealth-integrated virtual reality deployments that extend reach into home care settings.
Neurorehabilitation gaming systems combine motion capture sensors, adaptive software algorithms, and immersive visual feedback to deliver repetitive, quantifiable therapeutic exercises for neurological impairment recovery. These platforms typically operate at frame rates exceeding 60 Hz to prevent motion sickness while tracking patient kinematics with sub-centimeter precision for clinical validity. Virtual Reality hardware captures the dominant share of product-type value pools due to its capital intensity and replacement cycles. Stroke Recovery applications lead clinical adoption volumes, though Cognitive Rehabilitation segments are expanding fastest as aging populations drive demand for dementia-intervention protocols. Home Care end users represent an emerging margin concentration point where direct-to-patient subscription models bypass institutional procurement friction.
FDA software-as-medical-device pathways and HIPAA data governance requirements shape product architecture decisions for vendors targeting United States reimbursement eligibility. The European Medical Device Regulation imposes clinical evidence thresholds that filter out consumer-grade entrants from professional rehabilitation channels. Stakeholders must monitor evolving CMS digital therapeutic reimbursement decisions that will determine whether home-based neurorehabilitation gaming achieves sustainable economics outside institutional settings.
Market Dynamics
Software-as-medical-device regulatory pathways are compressing time-to-market for adaptive algorithm developers while simultaneously raising clinical evidence thresholds that filter hardware-centric competitors from institutional procurement channels.
Growth Catalysts
- Medicare reimbursement codes:United States CMS digital therapeutic coverage decisions create predictable revenue streams for platform vendors targeting stroke recovery departments in tertiary hospitals.
- Motion capture precision standards:Sub-centimeter kinematic tracking requirements for clinical validity drive hardware refresh cycles and software subscription attach rates.
- Aging population dementia protocols:Cognitive rehabilitation segments expand fastest as healthcare systems deploy immersive interventions for early-stage neurodegenerative conditions.
Market Restraints
- Clinical-grade sensor costs:Optical and inertial motion capture components carry 4-8x premiums over consumer VR peripherals, constraining margin structure for mid-tier vendors.
- European Medical Device Regulation:MDR clinical evidence thresholds block consumer-grade hardware from professional rehabilitation channels, fragmenting addressable markets.
- Motion sickness thresholds:Frame rate requirements exceeding 60 Hz impose GPU and display specifications that resist cost-down engineering from mobile chipset suppliers.
Strategic Opportunities
- Home care subscription models:Direct-to-patient platforms bypass institutional procurement friction and capture recurring revenue from aging-in-place demographics.
- Telehealth-integrated VR deployments:Remote therapist oversight extends platform reach beyond hospital networks into rural and post-acute care settings.
- HIPAA-compliant cloud architectures:Data governance requirements for United States reimbursement eligibility create switching costs and platform stickiness for first movers.
Industry Challenges
- ISO 13485 certification timelines:Medical device quality management implementation extends product development cycles 18-24 months versus consumer electronics norms.
- Adaptive algorithm validation:FDA software-as-medical-device submissions require prospective clinical studies that strain capital reserves of pre-revenue developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neurorehabilitation Gaming Systems Market |
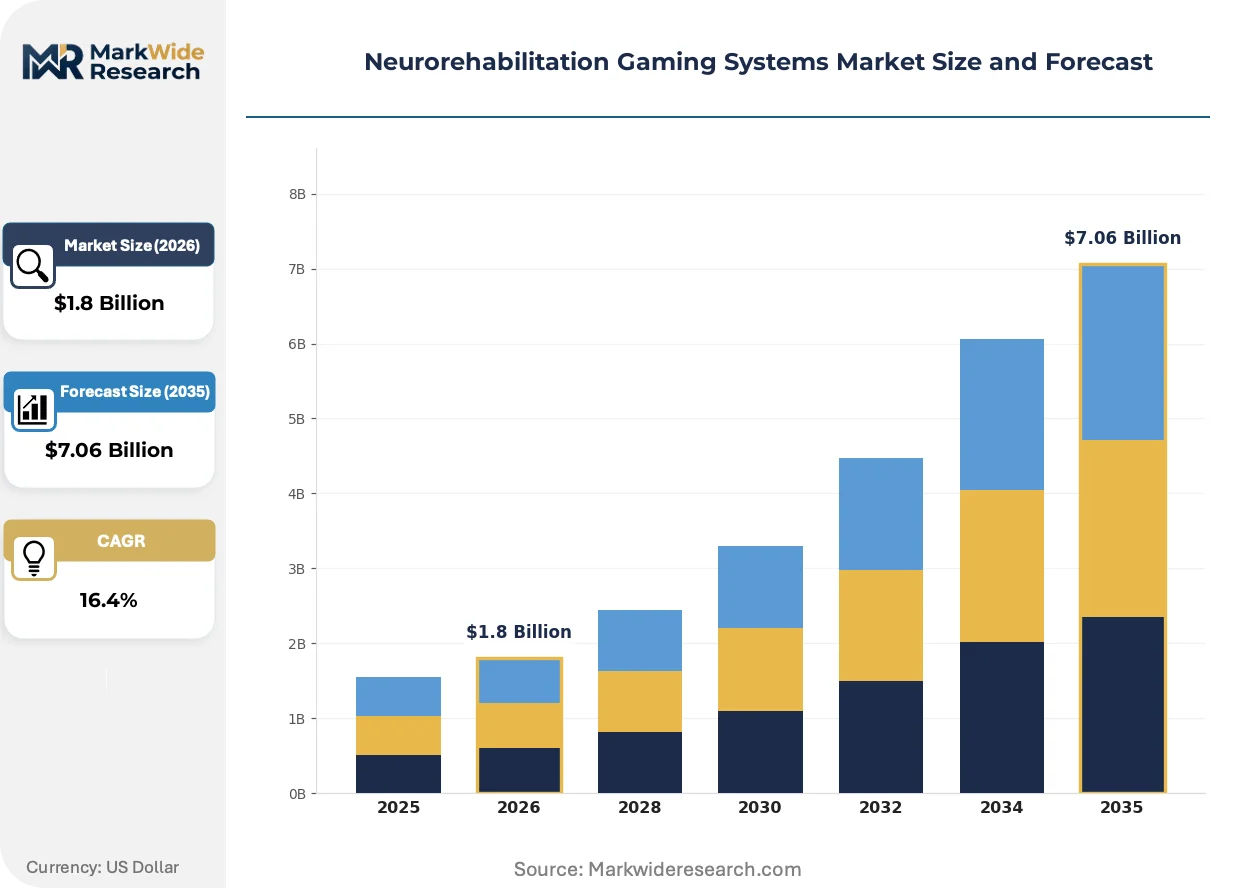
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Reality, Motion Sensors, Biofeedback Systems, Cognitive Games Application: Stroke Recovery, Motor Skill Rehabilitation, Cognitive Rehabilitation, Balance Training End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Technology: AR Systems, Gamification Techniques, Adaptive Algorithms, Wearable Devices |
| Companies Covered | MindMaze, Nintendo, Jintronix, XRHealth, Hocoma, Neofect, Bioness, Ekso Bionics, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neurorehabilitation Gaming Systems Market Emerging Trajectories
Immersive hardware architectures are converging with biometric sensing layers to enable closed-loop therapeutic adaptation, while regulatory frameworks mature to distinguish clinical-grade platforms from wellness applications.
Optical inside-out tracking is miniaturizing. These sensor arrays eliminate external base stations while maintaining sub-centimeter precision for upper-extremity rehabilitation protocols. Home care providers and outpatient clinics are adopting self-contained VR headsets at accelerating replacement cycles. The technology is miniaturizing hardware footprints and collapsing installation complexity that previously restricted deployments to dedicated therapy suites.
EU Medical Device Regulation post-market surveillance requirements are intensifying. Manufacturers must maintain clinical evidence portfolios across product lifecycles rather than single premarket submissions. Stroke recovery platforms with embedded adaptive algorithms face heightened scrutiny for software update validation. European hospital procurement committees are prioritizing vendors with established notified body relationships and systematic post-market clinical follow-up capabilities.
Hospital purchasing committees are unbundling hardware acquisition from software licensing and clinical support services. Institutional buyers negotiate three-year total cost of ownership contracts that separate capital equipment depreciation from per-patient session fees. This restructuring favors platform vendors with modular architectures and transparent usage-based pricing. United States health system consolidation accelerates the shift as integrated delivery networks standardize neurorehabilitation protocols across multiple facilities.
Neurorehabilitation Gaming Systems Market Segmentation
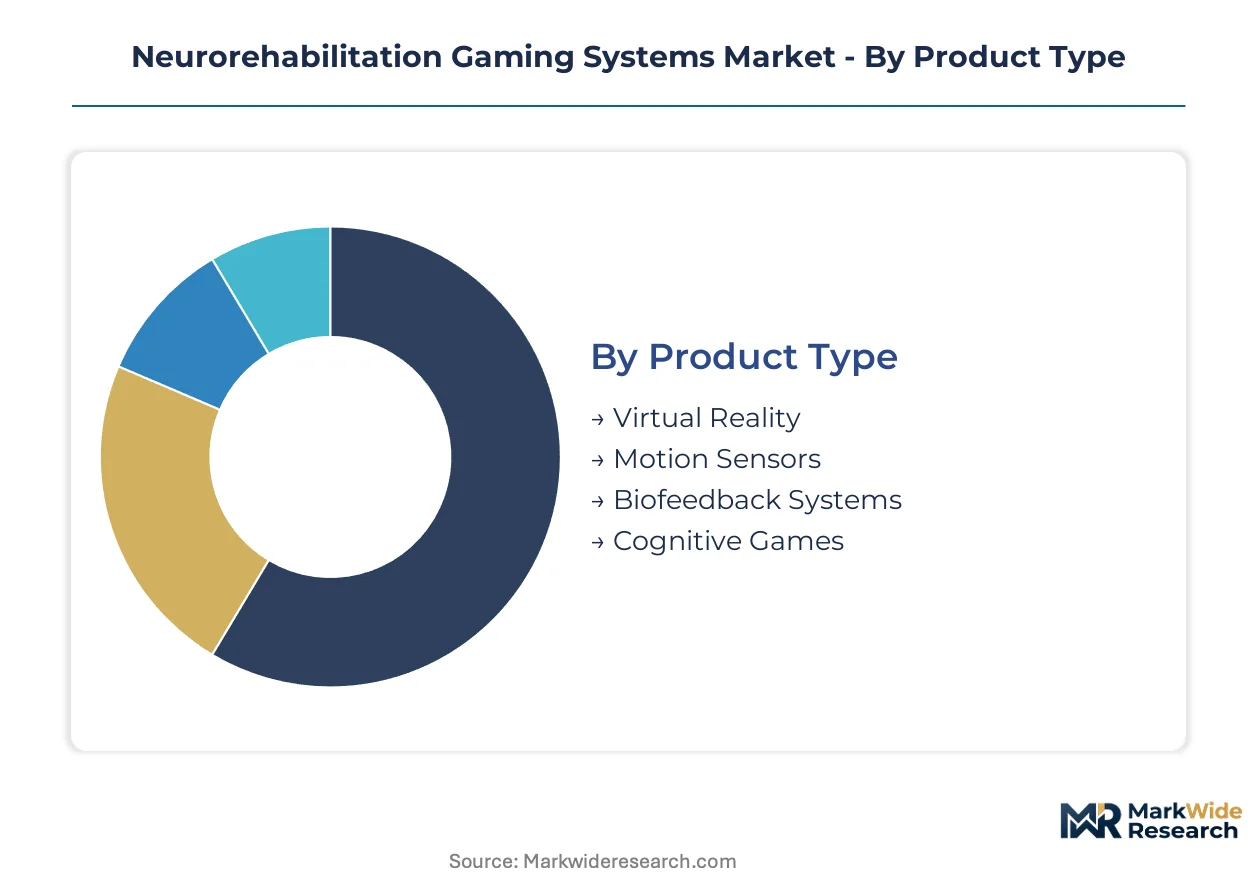
Neurorehabilitation gaming systems fragment across four critical dimensions where regulatory classification, clinical evidence requirements, and reimbursement pathways determine commercial viability. Product architecture decisions cascade through application targeting, end-user channel selection, and underlying technology stacks.
Product Type:
FDA software-as-medical-device pathways and EU MDR hardware classifications create divergent compliance burdens across physical form factors.
- Virtual Reality:Capital-intensive immersive headsets operating above 60 Hz frame rates with sub-centimeter kinematic tracking precision. Tertiary hospital stroke recovery departments in the United States concentrate procurement where Medicare reimbursement codes validate clinical utility.
- Motion Sensors:Optical and inertial tracking arrays capturing patient kinematics for upper-extremity rehabilitation protocols. European rehabilitation networks favor ISO 13485-certified hardware that satisfies MDR clinical evidence thresholds for professional channels.
- Biofeedback Systems:Physiological signal integration layers enabling closed-loop therapeutic adaptation.
- Cognitive Games:Software-centric interventions targeting dementia protocols with lower hardware barriers.
Established volume favors Virtual Reality; emerging adoption favors Cognitive Games.
Application:
Clinical adoption patterns align with reimbursement code availability and aging population disease burden across neurological conditions.
- Stroke Recovery:Dominant clinical volume driven by tertiary hospital procurement of immersive platforms for motor rehabilitation. United States health system consolidation accelerates protocol standardization across integrated delivery networks.
- Cognitive Rehabilitation:Fastest-expanding segment as healthcare systems deploy immersive interventions for early-stage neurodegenerative conditions in aging populations. Home care subscription models bypass institutional procurement friction for dementia-intervention protocols.
- Motor Skill Rehabilitation:Adaptive algorithm platforms targeting upper and lower extremity functional recovery.
- Balance Training:Vestibular and proprioceptive rehabilitation applications in fall-prevention protocols.
Institutional procurement concentrates in Stroke Recovery; direct-to-patient economics favor Cognitive Rehabilitation.
End User:
Channel economics shift dramatically between capital equipment depreciation models and recurring subscription revenue structures.
- Hospitals:Tertiary care institutions negotiate three-year total cost of ownership contracts separating hardware acquisition from per-patient session fees. United States integrated delivery networks standardize neurorehabilitation protocols across multiple facilities.
- Home Care:Direct-to-patient platforms capture recurring revenue from aging-in-place demographics where HIPAA-compliant cloud architectures create switching costs. CMS digital therapeutic reimbursement decisions determine sustainable economics outside institutional settings.
- Rehabilitation Centers:Outpatient facilities adopting self-contained VR headsets at accelerating replacement cycles.
- Clinics:Smaller-scale deployments constrained by clinical-grade sensor cost premiums.
Capital intensity favors Hospitals; margin expansion favors Home Care.
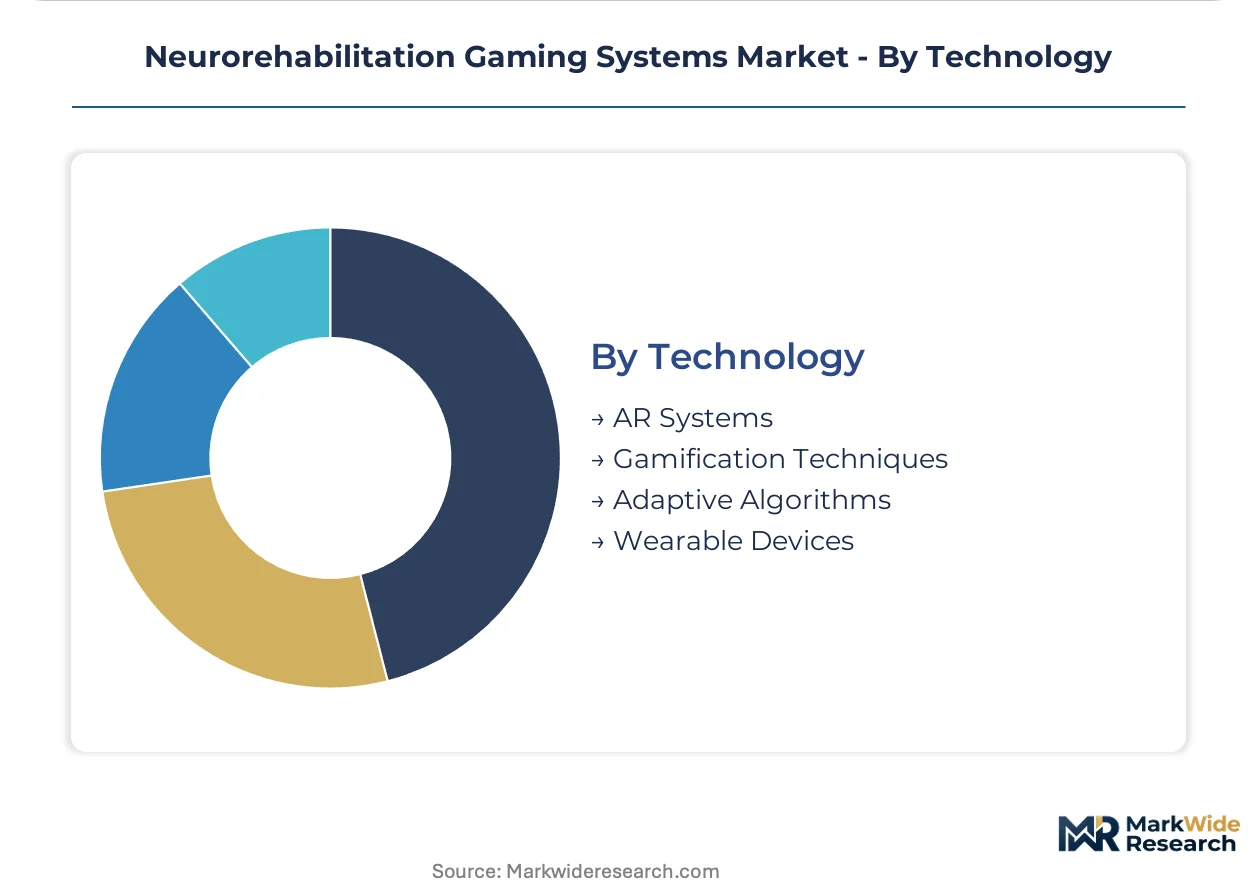
Technology:
Intellectual property concentration and validation timelines separate platform vendors from wellness application developers.
- Adaptive Algorithms:Software-as-medical-device submissions require prospective clinical studies that strain capital reserves of pre-revenue developers. FDA clearance pathways compress time-to-market for validated therapeutic adaptation engines.
- Wearable Devices:Miniaturized biometric sensing layers enabling closed-loop therapeutic adaptation in home care settings. Optical inside-out tracking eliminates external base stations while maintaining precision for upper-extremity protocols.
- AR Systems:Overlay architectures blending physical and digital rehabilitation environments.
- Gamification Techniques:Engagement mechanics driving patient adherence metrics for reimbursement validation.
Regulatory validation burdens favor Adaptive Algorithms; hardware miniaturization favors Wearable Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement codes in the United States and EU MDR clinical evidence thresholds are redrawing procurement boundaries across major neurorehabilitation markets. National regulators are compressing time-to-market for software-as-medical-device developers while filtering consumer-grade hardware from institutional channels.
United States
CMS digital therapeutic coverage decisions and health system consolidation drive tertiary hospital procurement of immersive platforms. FDA software-as-medical-device pathways compress clearance timelines for adaptive algorithm developers. The Greater Boston cluster anchors post-acute care innovation where telehealth-integrated VR deployments extend platform reach into home settings.
Germany
EU MDR clinical evidence thresholds and ISO 13485 certification requirements shape professional rehabilitation channel access. The national pharmaceutical regulator enforces post-market surveillance mandates across product lifecycles. The Baden-Württemberg industrial corridor concentrates notified body relationships and systematic clinical follow-up capabilities for stroke recovery platforms.
Switzerland
Swissmedic regulatory pedigree and premium hospital network positioning anchor European market entry strategies. The country's medical device quality framework filters consumer-grade competitors from professional channels. The Zurich-Geneva corridor hosts adaptive algorithm developers leveraging compressed validation timelines for software-centric therapeutic engines.
Japan
PMDA software-as-medical-device frameworks and aging population dementia protocols expand cognitive rehabilitation segments. METI industrial policy supports motion capture precision standards for clinical validity. The Tokyo-Osaka corridor concentrates hardware miniaturization capabilities for self-contained VR headsets in outpatient clinics.
United Kingdom
NICE technology appraisal pathways and NHS integrated care board procurement reshape total cost of ownership negotiations. The national data regulator enforces HIPAA-equivalent governance for cloud-based therapeutic platforms. The Cambridge-London corridor anchors telehealth-integrated deployments extending rural and post-acute care reach.
Neurorehabilitation Gaming Systems Market Vendor Landscape
Listed leaders compete with private specialists across regulatory certification and reimbursement eligibility dimensions. The vendor base fragments across three tiers: Swiss-certified premium platforms, Asian hardware-scale manufacturers, and venture-backed software-centric developers. Strategic archetypes include telehealth-integrated deployers, motion capture precision specialists, and direct-to-patient subscription operators. Dominant competitive moves encompass ISO 13485 certification acceleration and three-year total cost of ownership contract restructuring.
Within the regulatory-pedigree tier, MindMaze anchors premium positioning through Swiss medical device quality frameworks. Nintendo exemplifies consumer-scale manufacturing economics that clinical-grade competitors struggle to replicate. XRHealth occupies a position representing telehealth-integrated virtual reality deployment archetypes extending reach into home care settings.
| Leading Market Players |
|---|
| MindMaze |
| Nintendo |
| Jintronix |
| XRHealth |
| Hocoma |
| Neofect |
| Bioness |
| Ekso Bionics |
| Medtronic |
| Others |
Supply Flow & Price Mechanics
Consumer-scale VR manufacturing economics in Japan and Taiwan compress hardware cost floors while ISO 13485 certification timelines in Switzerland and Germany sustain premium pricing tiers for clinical-grade platforms. Scale advantages at Nintendo and Asian ODMs fragment procurement power across hospital purchasing committees negotiating three-year total cost of ownership contracts.
Pricing Analysis
Certification level creates the primary spread between premium Swissmedic-cleared platforms and consumer-grade wellness peripherals. Three-tier pricing structure separates FDA-cleared software-as-medical-device subscriptions from CE-marked hardware bundles and unregulated direct-to-consumer applications. Pricing pressure stems from Medicare reimbursement code uncertainty for home-based digital therapeutics. Home care end users exhibit highest price sensitivity; tertiary hospital stroke recovery departments demonstrate lowest sensitivity due to bundled procurement budgets.
Supply Chain Analysis
Taiwan and Japan anchor optical display and motion sensor fabrication for VR headsets, while Switzerland and Germany concentrate adaptive algorithm development and notified body certification services. The supply chain draws from Taiwanese GPU foundries, Japanese inertial MEMS suppliers, and Korean OLED panel manufacturers. Single-source vulnerability concentrates in specialized optical tracking arrays for sub-centimeter precision. Distribution runs through hospital GPO contracts in the United States and regional medical device distributors in European rehabilitation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-medical-device pathways and CMS reimbursement decisions are compressing commercialization timelines for adaptive algorithm developers, creating a high-growth disruption window for platforms that bridge clinical validity with home care economics.
For Market Incumbents: Shield institutional revenue streams by accelerating ISO 13485 certification for next-generation wearable form factors before venture-backed software developers achieve hardware parity. Deepen backward integration into optical sensor supply through exclusive partnerships with Taiwanese component suppliers to defend margin position against Asian manufacturing scale entrants. For New Entrants and Emerging Players: Differentiate on telehealth-integrated deployment architectures that extend therapist oversight into rural Medicare markets underserved by tertiary hospital networks. Target cognitive rehabilitation applications for aging-in-place demographics where direct-to-patient subscription models bypass GPO procurement friction and HIPAA-compliant cloud architectures create first-mover switching costs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among adaptive algorithm platforms with FDA-cleared software-as-medical-device status and established hospital system partnerships. Long-term viability favors vendors with modular hardware architectures that separate capital equipment from per-session software licensing. The signal to watch is CMS digital therapeutic coverage expansion into home care settings.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates time-to-market for adaptive algorithm developers seeking Medicare reimbursement eligibility. |
| Hospital System Partnership | Secures three-year total cost of ownership contracts across integrated delivery networks in United States. |
| CE Marking Pathway | Unlocks professional rehabilitation channel access under EU MDR clinical evidence thresholds. |
| Software Companion Development | Enables closed-loop therapeutic adaptation through biometric sensing layer integration. |
| Reimbursement Strategy | Aligns platform economics with evolving CMS digital therapeutic coverage decisions. |
Methodological Framework
Desk research of FDA 510(k) filings, EU MDR notified body databases, and hospital GPO contract disclosures preceded structured interviews with biomedical engineers, rehabilitation clinicians, purchasing committee directors, and digital therapeutic platform executives. Primary fieldwork with stroke recovery department heads and home care service operators combined with secondary validation against CMS Medicare reimbursement data and Swissmedic quality certification records. Bottom-up patient volume modeling and top-down healthcare IT spending triangulation anchored market sizing across product type and application segments.
Variance decomposition across technology stack, end-user channel, and regional regulatory cluster dimensions shaped analytical framework construction over the projection horizon. Segmentation modeling captured product type, application, end user, and technology dimensions with adaptive algorithm validation timelines and hardware replacement cycles as industry-specific forecast inputs. CAGRs derived from regression analysis of historical procurement volumes against reimbursement code expansion trajectories.
The analysis sits within stated boundaries; outcomes outside sustained CMS digital therapeutic coverage expansion or accelerated EU MDR software update validation protocols would require recalibration. Forecasts reflect assumptions regarding optical sensor cost curves and Medicare home care reimbursement parity with institutional settings. Recalibration cycles align with material shifts in FDA software-as-medical-device clearance timelines and European hospital procurement standardization across integrated delivery networks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Global Medical Rehabilitation Services Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
Massage Therapy Services Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
US Physical Therapy Services Market
Rehabilitation Services
Smart Portable Rehabilitation Devices Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Global Home Rehabilitation Products and Services Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
VR Stroke Rehabilitation Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
Rehabilitation Equipment Market