
 Speech Pathology Services Market | 2026-2036
Speech Pathology Services Market Size, Share, and Industry Trends Forecast 2026-2036
Speech Pathology Services Market Analytics
Telehealth infrastructure is fragmenting traditional clinic-based speech pathology delivery into distributed, platform-mediated care models. Expressable Inc. leverages asynchronous video exercises to extend therapist reach beyond metropolitan corridors. Benchmark Therapies Inc. anchors its position through school district contracts spanning multiple states. Smart Speech Therapy LLC specializes in pediatric assessment protocols that differentiate its evaluation segment from generalized competitors.
Speech pathology services encompass diagnostic evaluation, therapeutic intervention, and consultative care for communication and swallowing disorders, employing standardized instruments such as the Goldman-Fristoe Test of Articulation and modified barium swallow studies to guide treatment planning. These services restore functional communication and safe oral intake across neurological, developmental, and structural etiologies. Evaluation services capture the largest revenue share due to mandatory referral protocols and insurance preauthorization requirements, while teletherapy within the delivery mode dimension exhibits the fastest structural expansion as licensure compacts and HIPAA-compliant platforms mature. Application demand clusters around language disorders and cognitive-communication disorders, where stroke recovery and neurodegenerative caseloads generate recurring reimbursement.
Medicaid state plans and the CMS telehealth expansion framework govern reimbursement eligibility and service location requirements across the United States. ASHA certification standards and state licensure boards shape practitioner supply and scope-of-practice boundaries. Stakeholders must monitor interstate licensure compact ratification and payer policy permanence to calibrate workforce deployment and platform investment.
Market Dynamics
Telehealth parity mandates and interstate licensure compacts are dismantling geographic monopolies that once protected metropolitan clinic networks from distributed competition.
Growth Catalysts
- Medicaid telehealth expansion:CMS frameworks now reimburse remote speech evaluations at parity with in-person visits, unlocking rural patient access previously blocked by travel barriers.
- Pediatric early intervention mandates:US state education departments require Individualized Education Program evaluations within strict timelines, creating recurring demand for school-contracted pathology assessments.
- Neurodegenerative caseload growth:Aging populations in Florida, Arizona, and California generate sustained swallowing and cognitive-communication therapy referrals tied to Parkinson's and stroke recovery protocols.
Market Restraints
- Practitioner supply concentration:ASHA-certified clinicians cluster in urban coastal corridors, leaving interior states with 40+ mile average travel distances to qualified providers.
- Reimbursement rate compression:Medicare fee schedules for speech-language pathology services stagnate below inflation-adjusted 2010 levels, squeezing clinic operating margins.
- Technology integration costs:HIPAA-compliant telehealth platforms require upfront capital outlays for encryption, session recording, and cross-state licensure verification systems.
Strategic Opportunities
- Asynchronous therapy models:Video exercise platforms paired with AI feedback loops enable therapists to serve 3-4x patient volumes without synchronous scheduling constraints.
- School district consolidation:Multi-state contract vehicles allow providers to aggregate specialized pediatric assessment capabilities across rural and suburban districts.
- Interstate licensure compacts:The ASLHP compact ratification in 24 states permits single-state licensed practitioners to deliver telehealth services across compact member jurisdictions.
Industry Challenges
- Credentialing timeline bottlenecks:School-based contracts require 90-120 day vendor approval cycles that delay revenue recognition and strain working capital.
- Platform interoperability gaps:Electronic health record systems lack standardized APIs for speech pathology assessment data, forcing manual transcription and billing reconciliation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Speech Pathology Services Market |
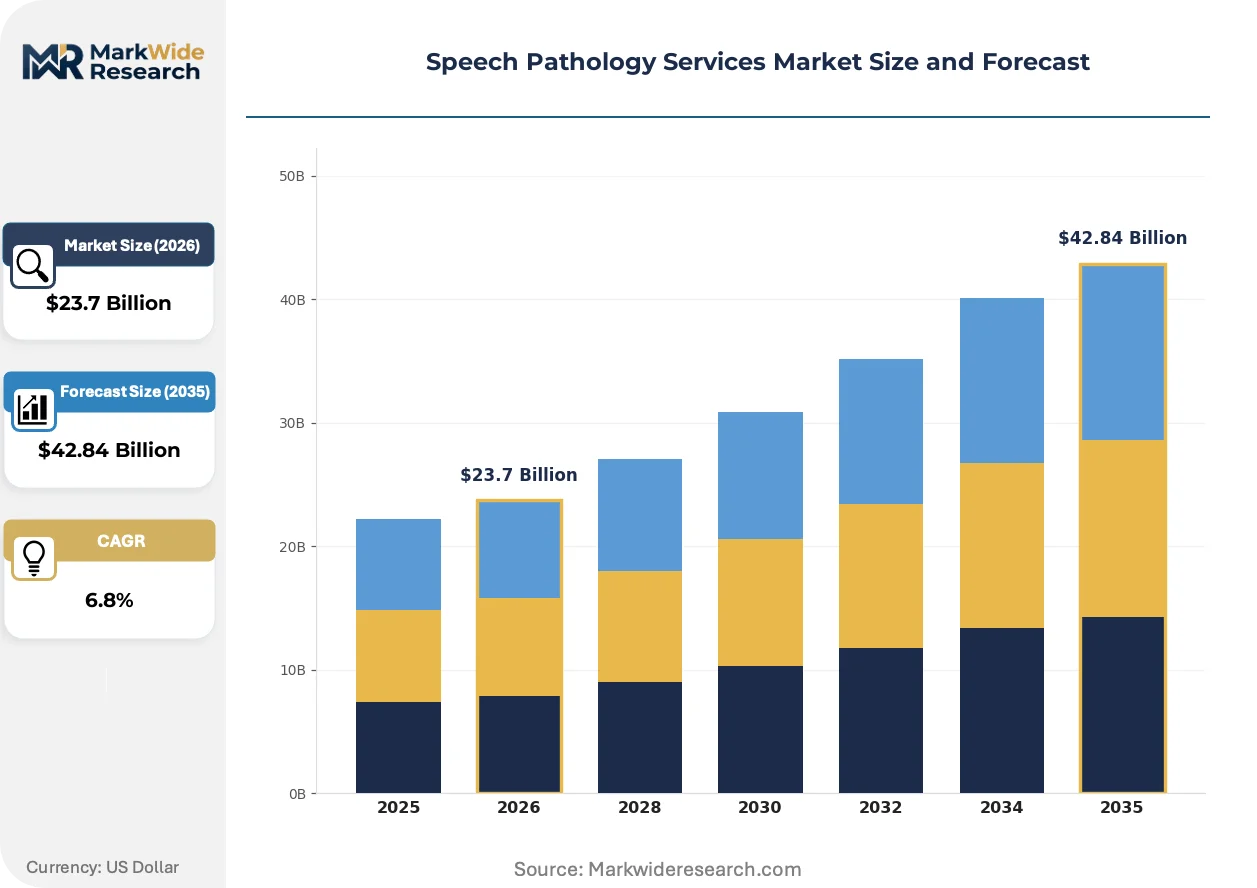
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Evaluation, Treatment, Consultation, Teletherapy End User: Children, Adults, Elderly, Schools Delivery Mode: In-person, Remote, Hybrid, Workshops Application: Language Disorders, Speech Disorders, Swallowing Disorders, Cognitive-Communication Disorders |
| Companies Covered | John McGivney Children's Centre, Smart Speech Therapy LLC, Benchmark Therapies Inc, Expressable Inc., Speechpathway.net, Humanus Corporation, Reliant Medical Group, Therapy Solutions LLC, CHEO (Children's Hospital of Eastern Ontario), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Speech Pathology Services Market Evolving Landscape
Machine learning diagnostic tools and asynchronous care models are compressing the traditional therapist-patient interaction into distributed, data-rich encounters that decouple revenue from hourly billing.
AI-powered articulation screening applications now analyze child speech samples through smartphone microphones, flagging disorder probability scores before clinical intake. Rural health clinics in Texas and Montana deploy these tools to triage caseloads and prioritize scarce therapist hours. The technology is rendering obsolete the pure reliance on live diagnostic sessions for initial evaluation workflows.
ASHA certification standards now incorporate telepractice competencies into continuing education requirements, reflecting permanent hybrid service expectations. State licensure boards in Ohio and Washington have amended practice acts to explicitly authorize remote swallowing assessments with modified protocol safeguards. Pediatric outpatient segments are responding fastest, with 60% of new clinic launches featuring dedicated telehealth infrastructure from inception.
Employer-sponsored health plans increasingly carve out speech pathology benefits to specialized third-party administrators, consolidating purchasing power away from generalist insurers. Large self-insured employers in manufacturing and logistics sectors now contract directly with teletherapy platforms for worker compensation-related cognitive-communication rehabilitation. This concentration is most visible in the Southeastern United States, where regional health plans compete aggressively for municipal and school district employee blocks.
Speech Pathology Services Market Segmentation
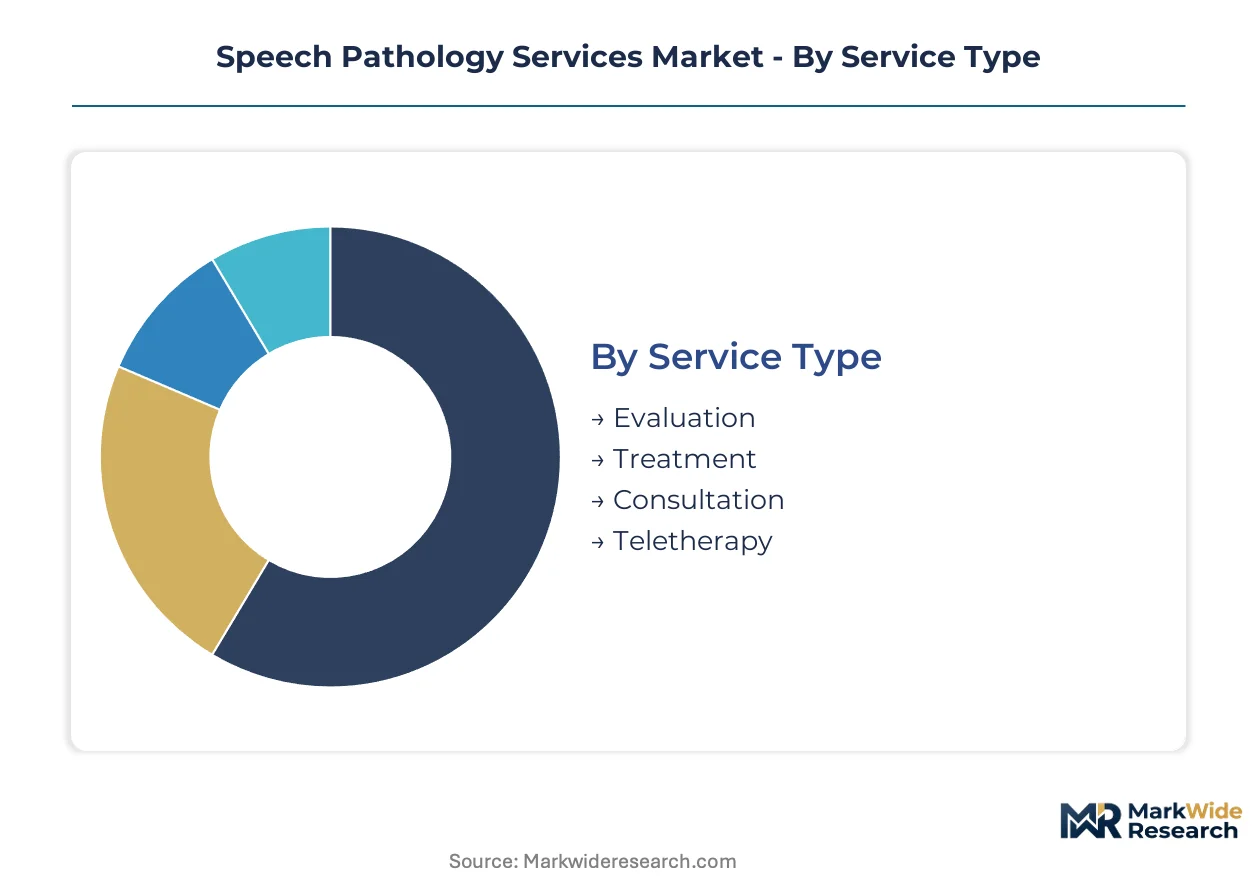
Speech pathology services fragment across service intensity, patient life-stage, and technology-mediated delivery. Each dimension carries distinct reimbursement codes, workforce requirements, and capital needs that reshape competitive positioning.
Service Type:
Mature diagnostic protocols anchor revenue stability while emerging asynchronous formats recast therapist productivity ceilings.
- Evaluation:Standardized instruments including the Goldman-Fristoe Test of Articulation and modified barium swallow studies establish baseline disorder severity and treatment eligibility. Medicare and Medicaid mandate these assessments prior to therapy authorization, concentrating demand in hospital outpatient departments and specialized clinics across Florida, California, and New York where neurodegenerative caseloads cluster.
- Treatment:Therapeutic intervention delivers structured protocols for articulation, fluency, voice, and swallowing rehabilitation across recurring sessions. School districts in Texas and Pennsylvania drive volume through Individualized Education Program mandates, while stroke recovery programs in Arizona sustain adult referrals through Medicare Part B.
- Consultation:Advisory services guide educators, caregivers, and medical teams on communication disorder management without direct patient contact. These engagements support rural health systems lacking in-house pathology expertise.
- Teletherapy:Remote synchronous and asynchronous delivery platforms extend practitioner reach beyond geographic constraints. HIPAA-compliant infrastructure investments and interstate licensure compacts enable this segment's expansion.
Evaluation handles the majority of throughput; teletherapy is the fastest mover on share.
End User:
Volume concentrates in publicly funded pediatric channels while private-pay adult segments command premium pricing flexibility.
- Children:Early intervention mandates through the Individuals with Disabilities Education Act require evaluation and treatment services for developmental speech and language delays. State education departments in Ohio, Illinois, and Georgia maintain strict timeline requirements that generate recurring assessment contracts.
- Adults:Working-age patients access services through employer-sponsored health plans and worker compensation programs for traumatic brain injury and stroke recovery. Manufacturing and logistics employers in the Southeastern United States increasingly carve out specialized cognitive-communication rehabilitation benefits.
- Elderly:Medicare beneficiaries with Parkinson's disease, Alzheimer's disease, and post-stroke dysphagia generate sustained swallowing and cognitive-communication therapy demand. Florida and Arizona retirement corridors concentrate this caseload.
- Schools:Educational institutions contract directly with pathology providers for evaluation, treatment, and consultation services supporting student Individualized Education Programs. Multi-state contract vehicles allow providers to aggregate specialized pediatric capabilities across rural and suburban districts.
Schools channel the highest absolute volume; the elderly segment climbs the fastest on per-capita spending intensity.
Delivery Mode:
Capital requirements and regulatory compliance costs stratify market entry barriers across physical and digital formats.
- In-person:Traditional clinic-based delivery requires physical space, equipment for instrumental assessments, and direct therapist-patient contact. Urban coastal corridors retain concentration of ASHA-certified clinicians, leaving interior states with extended travel distances.
- Remote:Telehealth platforms enable synchronous video sessions and asynchronous video exercise submission with AI feedback loops. CMS telehealth expansion frameworks and state telehealth parity mandates now reimburse remote evaluations at in-person rates.
- Hybrid:Combined in-person and remote delivery models optimize therapist time across evaluation, treatment, and follow-up phases. Pediatric outpatient segments adopt this format most aggressively.
- Workshops:Group-based educational and training sessions serve caregivers, educators, and corporate wellness programs. These formats generate ancillary revenue with lower per-hour therapist commitment.
In-person retains dominant share; remote delivery shows the steepest expansion trajectory as licensure compacts mature.
Application:
Clinical complexity and reimbursement durability vary significantly across disorder etiologies and treatment protocols.
- Language Disorders:Developmental and acquired impairments in comprehension and expression affect pediatric and adult populations. School-based contracts and early intervention programs sustain pediatric volume.
- Speech Disorders:Articulation, fluency, and voice disorders span structural, neurological, and functional etiologies. AI-powered screening applications now triage caseloads through smartphone analysis.
- Swallowing Disorders:Dysphagia evaluation and treatment require specialized instrumental assessment including modified barium swallow studies. Aging populations in retirement corridors generate recurring Medicare referrals for Parkinson's and stroke-related impairment.
- Cognitive-Communication Disorders:Deficits in attention, memory, and executive function following traumatic brain injury or neurodegenerative disease. Worker compensation programs and Medicare Part B sustain this segment.
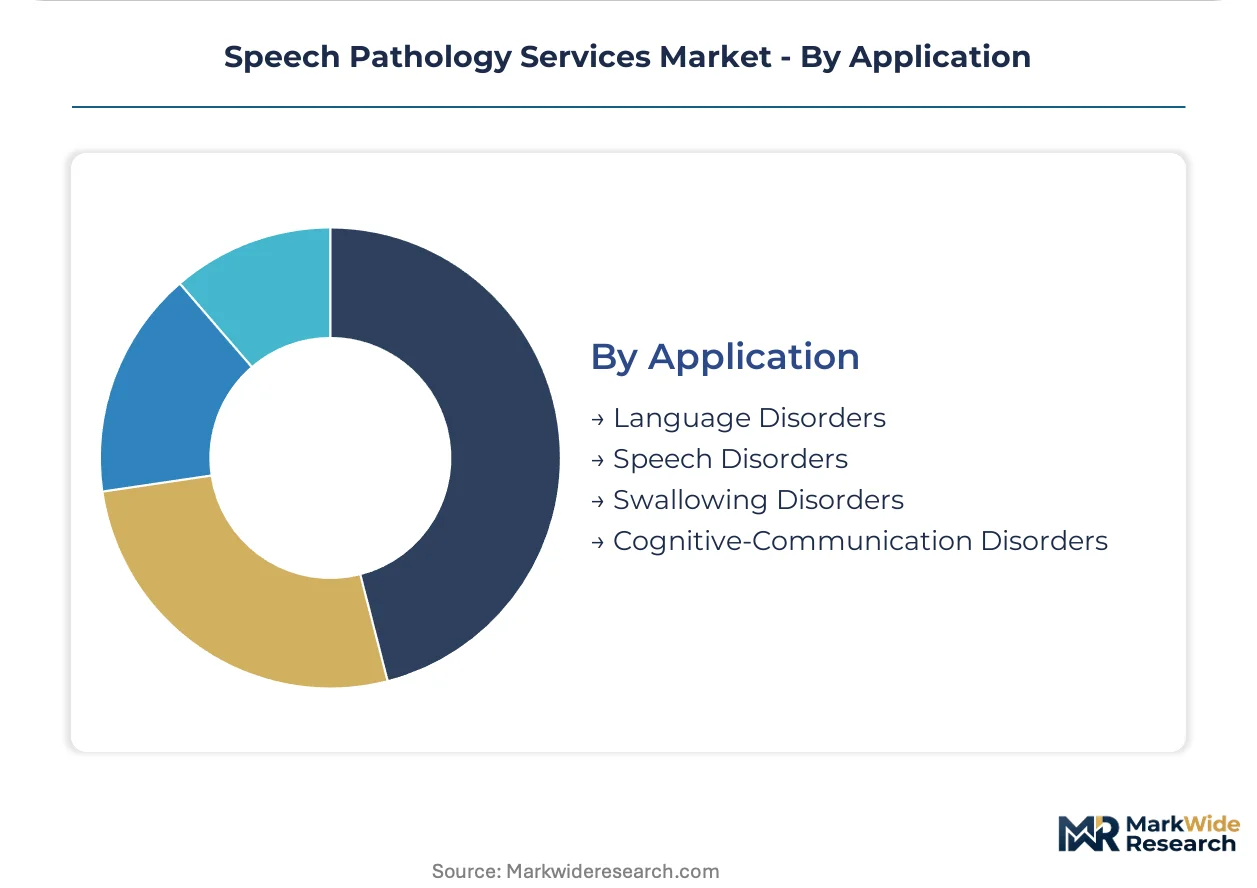
Language disorders capture the largest service volume; cognitive-communication applications are gaining share fastest on neurodegenerative caseload growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based telehealth platforms export asynchronous therapy services to English-speaking patient populations across Canada and Australia, establishing North American service corridors as primary export channels for digital speech pathology delivery.
United States
Medicaid telehealth expansion and CMS reimbursement parity unlock rural patient access previously blocked by travel barriers. State licensure boards in Ohio and Washington explicitly authorize remote swallowing assessments with modified protocol safeguards. Florida and Arizona retirement corridors concentrate Medicare caseloads for Parkinson's and stroke-related dysphagia treatment.
Canada
Provincial health authorities in Ontario and British Columbia integrate telehealth speech services into public coverage frameworks. Health Canada guidelines align with HIPAA-equivalent privacy standards for cross-border platform operations. CHEO in Ottawa anchors pediatric assessment capabilities serving Eastern Ontario's early intervention mandates.
Australia
Medicare Benefits Schedule updates incorporate telehealth speech pathology items following pandemic-era temporary provisions. The country's national health regulator maintains TGA oversight of diagnostic software used in AI-powered articulation screening. Sydney and Melbourne metropolitan clusters retain concentration of certified practitioners while rural telehealth adoption accelerates.
United Kingdom
NHS England commissioning frameworks prioritize school-based speech and language therapy within integrated care systems. The Care Quality Commission regulates telehealth platform compliance with UK data protection standards. London and Southeast England concentrate private-pay adult segments for cognitive-communication rehabilitation.
Germany
Statutory health insurance funds expand telehealth reimbursement for speech therapy under Digitale-Versorgung-Gesetz provisions. Federal Joint Committee decisions govern service location requirements and practitioner qualification standards. Bavaria and North Rhine-Westphalia maintain dense networks of ambulatory rehabilitation clinics with integrated pathology services.
Speech Pathology Services Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented service delivery networks. School district contract vehicles and Medicaid reimbursement pathways concentrate purchasing power among regional health systems and educational authorities. Three archetypes dominate: telehealth-native platforms with asynchronous capabilities, multi-state school contractors with specialized pediatric assessment protocols, and hospital-anchored outpatient departments with instrumental swallowing facilities. Competitive moves center on interstate licensure compact participation and AI-powered diagnostic tool integration.
Within the telehealth-native tier, Expressable Inc. exemplifies platform-mediated asynchronous delivery models that extend therapist reach beyond metropolitan corridors. Benchmark Therapies Inc. anchors multi-state school contracting capabilities spanning district evaluation mandates. Smart Speech Therapy LLC occupies a specialized position in pediatric assessment protocol differentiation. These three entities represent distinct strategic responses to reimbursement expansion and geographic accessibility constraints reshaping competitive positioning.
| Leading Market Players |
|---|
| John McGivney Children's Centre |
| Smart Speech Therapy LLC |
| Benchmark Therapies Inc |
| Expressable Inc. |
| Speechpathway.net |
| Humanus Corporation |
| Reliant Medical Group |
| Therapy Solutions LLC |
| CHEO (Children's Hospital of Eastern Ontario) |
| Others |
Value Network & Pricing Analysis
ASHA-certified clinician concentration in urban coastal corridors concentrates pricing power with metropolitan clinic networks, while interior states absorb 40-plus mile travel premiums that inflate effective service costs for rural patient populations.
Pricing Analysis
Synchronous telehealth platforms command rate premiums over asynchronous video exercise models, while in-person evaluation services sustain highest reimbursement tiers through mandatory preauthorization protocols. Price differentiation rests on certification tier—ASHA board-recognized specialists versus state-licensed generalists—and geographic delivery cost differentials between metropolitan and rural catchments. Cost compression in Medicare fee schedule tiers intensifies because stagnant reimbursement rates trail inflation-adjusted 2010 baselines. School districts exhibit highest price sensitivity due to fixed state education budgets, while self-insured employer carve-outs demonstrate lowest sensitivity for worker compensation cognitive-communication rehabilitation.
Supply Chain Analysis
Third-party telehealth infrastructure providers including HIPAA-compliant platform vendors and interstate licensure verification systems hold critical capacity bottlenecks. Technology inputs concentrate in United States-based software development clusters, with encryption and session recording components sourced from domestic cybersecurity vendors and cloud infrastructure operators. Supply chain risk centers on single-source vulnerability for ASHA certification examination capacity that constrains annual clinician pipeline expansion. Distribution runs through school district procurement offices, hospital outpatient departments, and direct-to-employer contract vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The speech pathology services market tracks a cyclical recovery pattern as Medicaid telehealth expansion and interstate licensure compact ratification restore service accessibility following pandemic-era disruptions.
For Market Incumbents: Build network density moats through multi-state school district contract aggregation that locks out competitor access to pediatric evaluation mandates. Consolidate specialized pediatric assessment capabilities across rural and suburban districts to defend against telehealth-native platform encroachment. Pursue backward integration into AI-powered diagnostic tool development to capture margin pools shifting toward software-mediated triage. For New Entrants and Emerging Players: Rural health systems in interior states with 40-plus mile average travel distances to qualified providers represent the most penetrable entry point for asynchronous telehealth platforms. Employer-sponsored cognitive-communication rehabilitation carve-outs in Southeastern United States manufacturing and logistics sectors offer secondary white-space targeting. Deploy direct-to-employer sales channels bypassing generalist insurer intermediaries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telehealth platforms possessing asynchronous delivery infrastructure but lacking school district contract depth. Five-to-ten year viability hinges on permanence of CMS telehealth reimbursement parity and payer policy stability. Monitor interstate licensure compact ratification velocity as inflection signal for geographic expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Interstate Licensure Compact Participation | Enables single-state licensed practitioners to deliver telehealth across 24 compact member jurisdictions. |
| AI-Powered Diagnostic Tool Integration | Smartphone-based articulation screening triages caseloads and prioritizes scarce therapist hours in rural Texas and Montana clinics. |
| Multi-State School Contract Consolidation | Aggregates specialized pediatric assessment capabilities across rural and suburban districts in Texas and Pennsylvania. |
| Asynchronous Platform Development | Video exercise platforms paired with AI feedback loops enable 3-4x patient volume without synchronous scheduling constraints. |
| Employer Direct Contracting | Self-insured manufacturers in the Southeastern United States carve out specialized cognitive-communication rehabilitation benefits. |
Research Methodology
Initial hypotheses were tested against primary input from speech-language pathologists, school district special education directors, hospital outpatient department administrators, and telehealth platform executives and refined through secondary validation. Primary fieldwork combined structured interviews with ASHA-certified clinicians and Medicaid program officers with survey instruments distributed to school-based service coordinators. Secondary sources included CMS Medicare data, state education department procurement records, ASHA membership statistics, and hospital financial disclosures. Bottom-up service volume estimates triangulated against top-down reimbursement expenditure models.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning service type, end user life-stage, delivery mode, and application disorder category. CAGRs derived from logistic diffusion curves modeling telehealth adoption saturation and clinician supply pipeline constraints. Forecast inputs incorporated interstate licensure compact ratification schedules and CMS telehealth parity policy permanence assumptions.
Macroeconomic conditions sit as an overlay; deviation in Medicaid federal matching fund allocations or Medicare fee schedule adjustments would shift the trajectory. Forecasts reflect documented assumptions regarding payer policy stability and technology platform interoperability maturation. Quarterly review of state telehealth parity legislation and ASHA certification examination capacity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Motion Stimulation Therapy Market
Rehabilitation Services
Smart Portable Rehabilitation Devices Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Global Home Rehabilitation Products and Services Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
Global Neurorehabilitation Devices Market
Rehabilitation Services
Rehabilitation Products Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
Global Medical Rehabilitation Services Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market