
 Rehabilitation Products Market | 2026-2036
Rehabilitation Products Market Size, Share, and Industry Trends Forecast 2026-2036
Rehabilitation Products Market Outlook
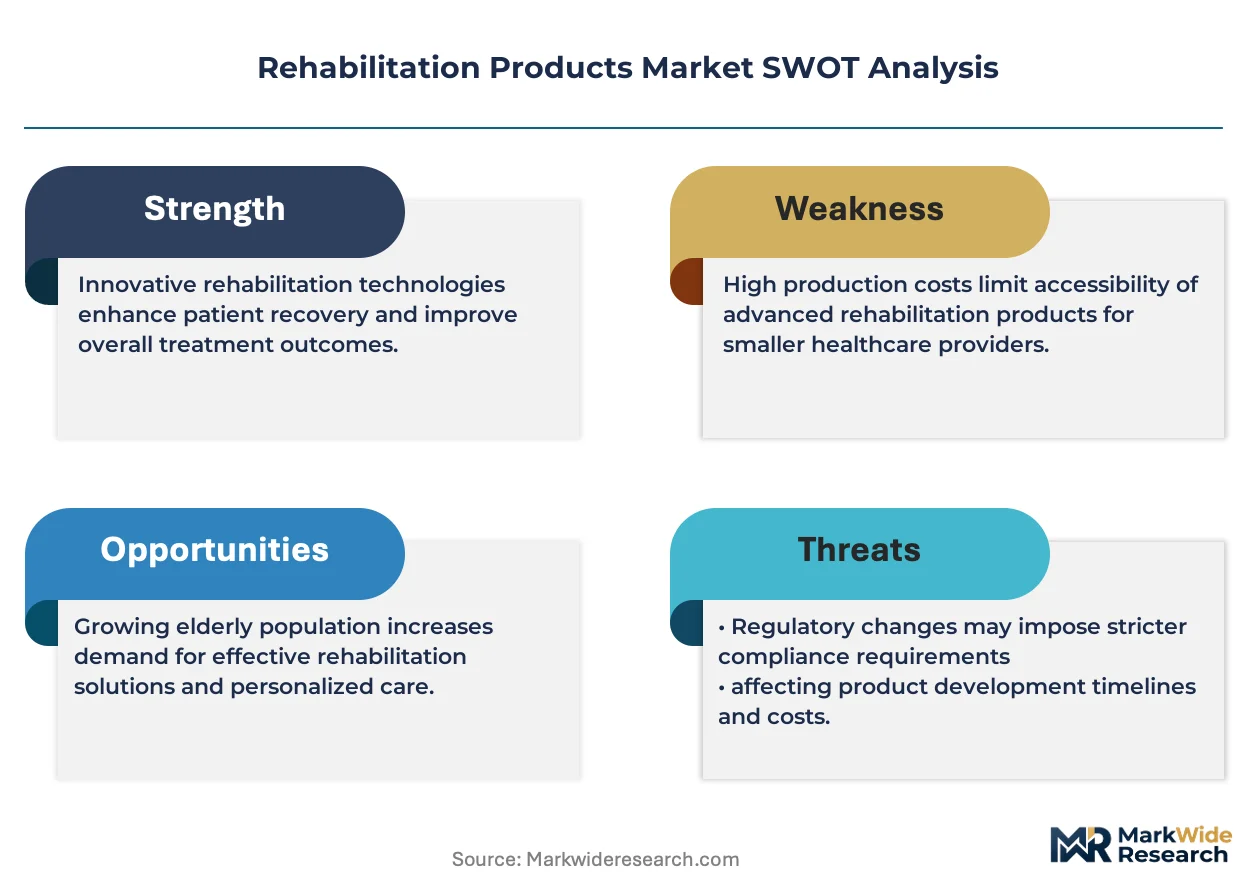
CE-marked and FDA-cleared device tiers is rotating toward higher-reimbursement clinical categories, pulling average selling prices upward across rehabilitation portfolios. Stryker Corporation leverages its hospital system integration to sustain placement rates for acute-care mobility platforms. Invacare Corporation anchors home care distribution through durable medical equipment networks that dominate Medicare Part B channels. DJO Global differentiates via orthopedic rehabilitation specialization that competes directly with physician-owned therapy practices.
Rehabilitation products encompass electromechanical and passive assistive devices engineered to restore motor function, reduce disability, and support therapeutic exercise protocols typically specified in ISO 13485 quality management frameworks. Their primary commercial purpose centers on reimbursable clinical outcomes measured by functional independence metrics in post-acute and ambulatory settings. Mobility aids and therapeutic equipment represent the mature revenue base where margin pools have compressed under group purchasing organization pressure. Wearable tech and robotic assistance segments are expanding fastest as hospitals seek labor-saving alternatives to manual therapy delivery.
FDA 510(k) pathways and EU MDR conformity requirements shape product development timelines and market access costs for rehabilitation device manufacturers. The Centers for Medicare and Medicaid Services reimbursement codes directly determine commercial viability for home-use rehabilitation technologies. Stakeholders must monitor how FDA breakthrough device designations and evolving CMS national coverage determinations redistribute capital toward robotic and wearable rehabilitation platforms.
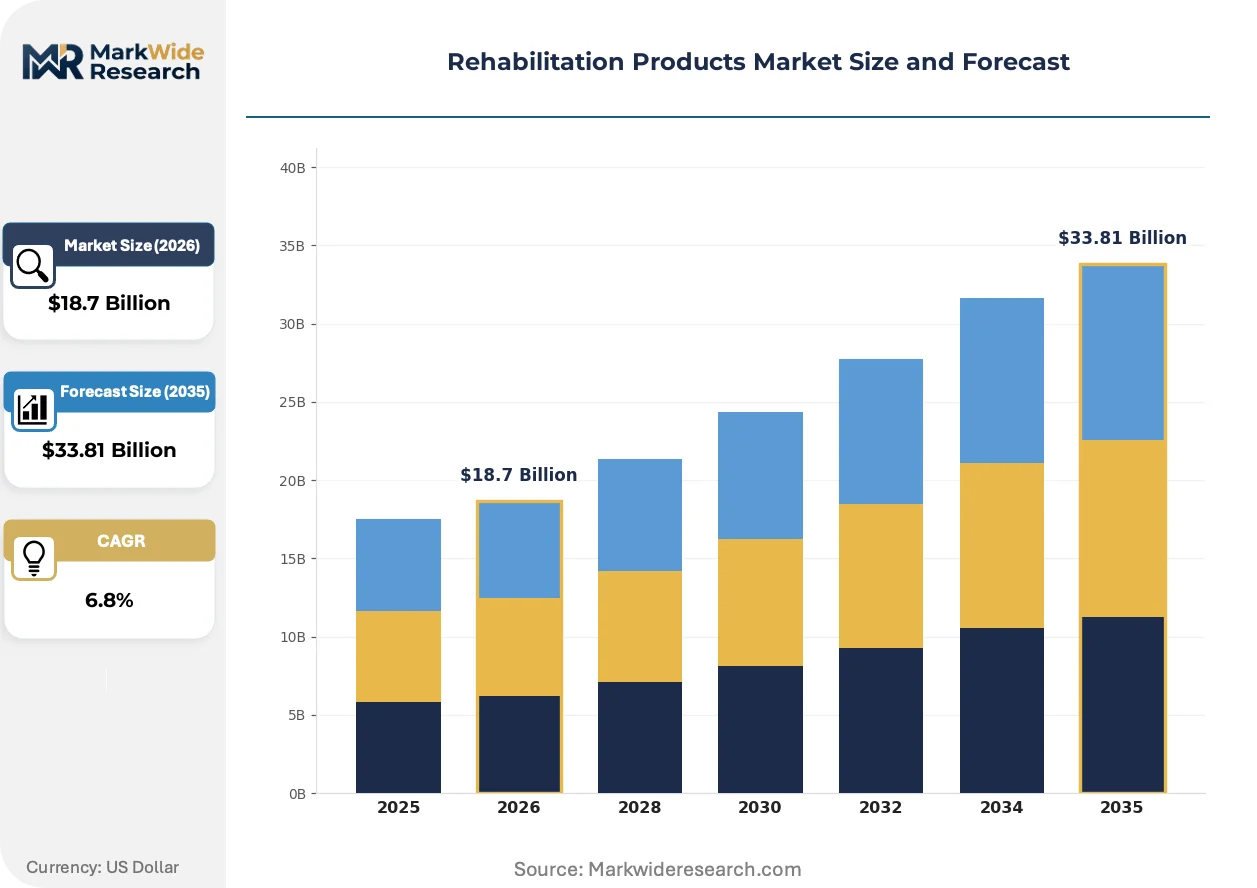
Market Dynamics
Medicare reimbursement expansion for outpatient rehabilitation devices is compressing hospital procurement cycles and redirecting capital toward home-deployable technologies. This structural pull is accelerating FDA breakthrough designations for wearable platforms while reshaping distributor relationships across acute and post-acute channels.
Growth Catalysts
- FDA Breakthrough Device Designation:Compressed review timelines for robotic exoskeletons are pulling venture capital into wearable rehabilitation platforms targeting spinal cord injury populations.
- Medicare Part B Expansion:Reimbursement code additions for durable medical equipment in home settings are unlocking procurement budgets for mobility aids and therapeutic exercise systems.
- Aging-in-Place Infrastructure:Japan's METI subsidies for home care robotics and Germany's Pflegeversicherung reforms are creating installed bases for assistive technology in residential environments.
Market Restraints
- EU MDR Conformity Costs:Extended clinical evidence requirements for Class IIa rehabilitation devices are stretching certification timelines to 18-24 months and elevating regulatory spend for mid-tier manufacturers.
- Semiconductor Supply Concentration:Dependency on Taiwan-based foundries for motor control chips in robotic exoskeletons is creating production bottlenecks and forcing order-to-delivery extensions.
- Manual Therapy Substitution Ceiling:Reimbursement gaps for AI-guided rehabilitation versus human-delivered physical therapy are limiting penetration in cash-constrained outpatient clinics.
Strategic Opportunities
- India PLI Scheme for Medical Devices:Production-linked incentives for domestic manufacturing are attracting contract assembly investments for export-oriented mobility aid production.
- Telehealth-Therapy Convergence:Integration of remote patient monitoring with prescription digital therapeutics is opening reimbursement pathways for algorithm-driven home rehabilitation programs.
- Direct-to-Consumer Channels:E-commerce platforms and specialized medical device marketplaces are bypassing traditional durable medical equipment distributors for cash-pay wellness segments.
Industry Challenges
- ISO 13485 Quality Talent Scarcity:Shortage of auditors and quality engineers with medical device regulatory experience is delaying supplier qualification and internal audit completion.
- Legacy EMR Integration Complexity:Proprietary data formats in hospital electronic medical record systems are forcing custom API development for rehabilitation device connectivity and outcome reporting.
- Patent Thickets in Haptic Feedback:Dense intellectual property landscapes around force-sensing resistors and vibrotactile actuators are complicating component sourcing and design-around engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rehabilitation Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exoskeletons, Mobility Aids, Orthotic Devices, Therapeutic Equipment End User: Hospitals, Rehabilitation Centers, Home Care, Sports Clinics Application: Physical Therapy, Occupational Therapy, Stroke Rehabilitation, Post-Surgery Recovery Technology: Wearable Tech, Virtual Reality, Robotic Assistance, Patient Monitoring Systems |
| Companies Covered | Stryker Corporation, Invacare Corporation, Medline Industries, DJO Global, Arjo, Dynatronics Corporation, Ekso Bionics, Drive DeVilbiss Healthcare, Enovis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rehabilitation Products Market Strategic Shifts
Sensor miniaturization and edge computing are enabling real-time biomechanical feedback loops that were previously confined to laboratory gait analysis. These advances are collapsing the functional gap between clinical-grade and consumer-accessible rehabilitation platforms.
Soft robotic actuators woven into textile substrates are supplanting rigid exoskeleton frames for upper-limb rehabilitation. Post-acute facilities in the United States are piloting these garments for stroke recovery protocols, drawn by reduced setup time and patient self-donning capability. The shift is compressing capital equipment cycles and opening subscription-based revenue models that displace outright purchase structures.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up for CE-marked rehabilitation devices. Manufacturers must now maintain active registries tracking device performance across diverse patient populations, elevating data infrastructure spend. German notified bodies are enforcing these provisions most stringently, creating competitive separation between firms with robust pharmacovigilance systems and those dependent on legacy complaint handling.
Hospital value analysis committees are consolidating vendor rosters for rehabilitation equipment, favoring suppliers with bundled service contracts spanning preventive maintenance and staff training. This concentration is squeezing standalone device manufacturers without field service networks. The pattern is most pronounced in United States integrated delivery networks, where procurement standardization across 10-15 facility systems is becoming a baseline qualification threshold.
Rehabilitation Products Market Segmentation
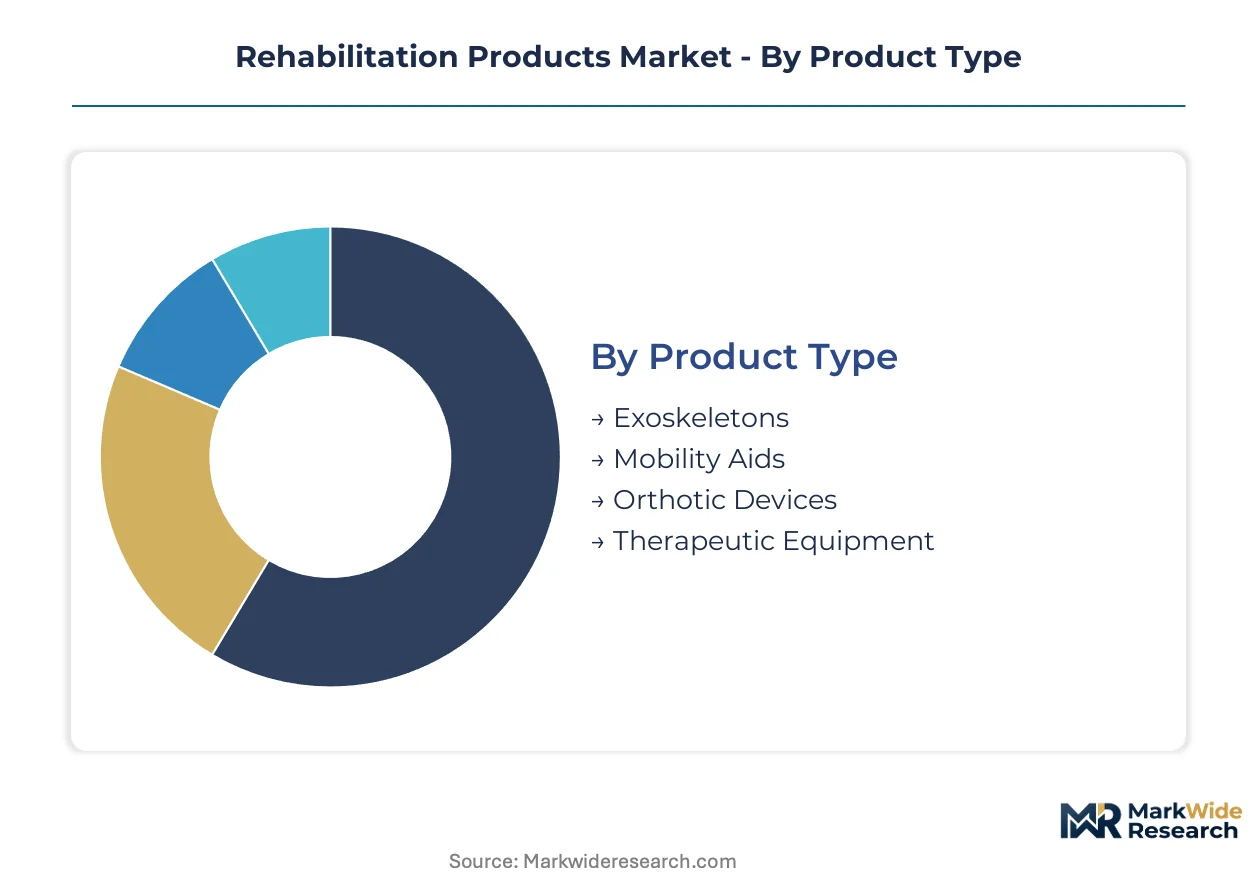
Rehabilitation product segmentation reflects divergent regulatory pathways and reimbursement codes that determine commercial viability across clinical and residential settings. Manufacturers must align portfolio architecture with distinct FDA 510(k) and EU MDR conformity requirements governing each category.
Product Type:
FDA breakthrough device designations and EU MDR classification tiers create divergent market access timelines and capital intensity across hardware categories.
- Exoskeletons:Powered robotic frames with motor-driven joints deliver gait assistance for spinal cord injury and stroke populations. Demand concentrates in United States rehabilitation centers pursuing Medicare reimbursement for outpatient neurorehabilitation protocols, constrained by semiconductor supply bottlenecks for motor control systems.
- Mobility Aids:Manual and powered wheelchairs, walkers, and canes constitute the mature revenue base where ISO 13485 quality management frameworks govern supplier qualification. Procurement runs through durable medical equipment networks serving Medicare Part B channels, with margin compression under group purchasing organization pressure.
- Orthotic Devices:Braces and splints fabricated from thermoplastic composites address joint stabilization and deformity correction.
- Therapeutic Equipment:Continuous passive motion machines and electrical stimulation devices support prescribed exercise protocols.
Established volume favors Mobility Aids; emerging adoption favors Exoskeletons.
End User:
Reimbursement infrastructure and capital deployment cycles vary sharply across institutional and residential care environments.
- Hospitals:Acute-care facilities with value analysis committees consolidate vendor rosters for rehabilitation equipment, favoring bundled service contracts spanning preventive maintenance and staff training. United States integrated delivery networks now require procurement standardization across 10-15 facility systems as baseline qualification.
- Rehabilitation Centers:Post-acute specialists pilot soft robotic textiles for stroke recovery, drawn by reduced setup time and patient self-donning capability. These garments are compressing capital equipment cycles and opening subscription-based revenue models.
- Home Care:Aging populations seeking independent recovery pathways are accelerating adoption of deployable therapeutic systems. Japan's METI subsidies and Germany's Pflegeversicherung reforms are creating installed bases for assistive technology in residential environments.
- Sports Clinics:Athlete-focused facilities prioritize rapid-return protocols and performance optimization.
Reimbursement concentration favors Hospitals; patient preference shifts favor Home Care.
Application:
Clinical outcome metrics and functional independence measurements determine reimbursement eligibility across therapeutic disciplines.
- Physical Therapy:Movement restoration protocols target strength, range of motion, and ambulation. Demand clusters in outpatient settings where CMS national coverage determinations dictate device procurement priorities for United States providers.
- Occupational Therapy:Activities-of-daily-living retraining focuses on upper-limb function and cognitive integration. Post-acute facilities are deploying soft robotic garments for self-care task practice, enabled by real-time biomechanical feedback from miniaturized sensors.
- Stroke Rehabilitation:Neuroplasticity-driven protocols require intensive, repetitive task practice.
- Post-Surgery Recovery:Joint replacement and cardiac procedure rehabilitation follows standardized clinical pathways.
Procedure volume favors Post-Surgery Recovery; neuroplasticity research investment favors Stroke Rehabilitation.
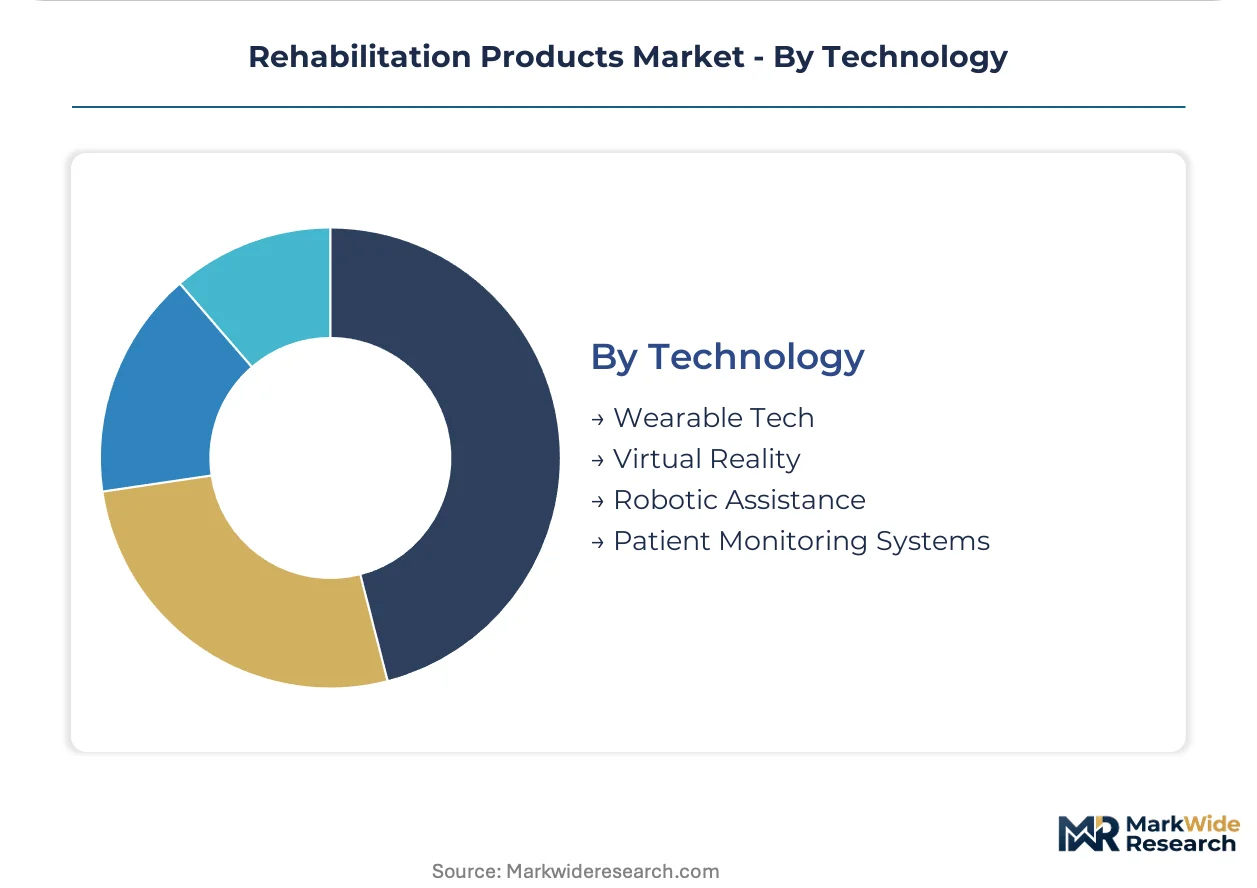
Technology:
Edge computing advances and sensor miniaturization are collapsing functional gaps between clinical-grade and consumer-accessible platforms.
- Wearable Tech:Textile-integrated soft actuators and force-sensing resistors enable continuous biomechanical monitoring. Patent thickets around haptic feedback components are complicating design-around engineering for mid-tier manufacturers.
- Virtual Reality:Immersive environments deliver engaging task practice for motor learning and cognitive rehabilitation.
- Robotic Assistance:Automated movement guidance reduces therapist labor intensity. FDA clearance pathway compression for breakthrough devices is pulling venture capital into platforms targeting spinal cord injury populations.
- Patient Monitoring Systems:Remote data capture supports telehealth-therapy convergence and algorithm-driven home rehabilitation programs.
Regulatory momentum favors Robotic Assistance; reimbursement pathway development favors Patient Monitoring Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in the United States, Germany, and Japan where reimbursement infrastructure and regulatory frameworks for medical devices are most developed. Taiwan-based semiconductor foundries anchor component sourcing for motor control systems in robotic exoskeletons. Regional differentiation stems from divergent aging demographics and healthcare financing models.
United States
Medicare Part B reimbursement expansion for durable medical equipment is accelerating home care procurement of mobility aids and therapeutic exercise systems. The FDA breakthrough device designation pathway is compressing review timelines for robotic exoskeletons targeting spinal cord injury populations. Minneapolis and Cleveland host concentrated rehabilitation device manufacturing clusters where Stryker Corporation and Invacare Corporation maintain integrated distribution networks.
Germany
Pflegeversicherung reforms are expanding long-term care insurance coverage for assistive technology in residential settings. EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up registries for CE-marked rehabilitation devices. The Stuttgart and Munich metropolitan regions anchor orthopedic rehabilitation equipment production where manufacturers navigate stringent notified body enforcement from German regulators.
Japan
METI subsidies for home care robotics are creating installed bases for assistive technology among aging-in-place populations. The PMDA regulatory framework governs medical device market access with specific pathways for software as a medical device in rehabilitation applications. The Kanto region surrounding Tokyo concentrates rehabilitation robotics development where soft actuator textile integration is advancing fastest.
China
NMPA medical device registration requirements are evolving to accommodate AI-guided rehabilitation platforms under revised classification rules. The country's national pharmaceutical regulator is streamlining review processes for innovative rehabilitation devices addressing stroke recovery protocols. The Yangtze River Delta manufacturing corridor is attracting contract assembly investments for export-oriented mobility aid production under domestic incentive programs.
India
PLI scheme production-linked incentives for medical devices are attracting contract manufacturing investments for mobility aid exports. CDSCO medical device regulations are harmonizing with international standards to facilitate market access for imported rehabilitation technologies. Gujarat and Maharashtra host emerging medical device manufacturing clusters where domestic assembly capacity is expanding for wheelchair and walker production.
Rehabilitation Products Market Competitive Environment
Concentration sits with diversified medical technology conglomerates and specialized rehabilitation equipment manufacturers. The vendor base spans three tiers: hospital-integrated platform suppliers, durable medical equipment distributors, and venture-backed robotics specialists. Strategic archetypes include acute-care placement specialists, home care channel anchors, and breakthrough device innovators. Competitive moves center on bundled service contract expansion and FDA breakthrough designation pursuit.
Among diversified medical technology conglomerates, Stryker Corporation exemplifies the hospital-integrated archetype through acute-care mobility platform placement. Invacare Corporation anchors home care distribution via durable medical equipment networks serving Medicare Part B channels. DJO Global occupies a position within orthopedic rehabilitation specialization competing with physician-owned therapy practices. These three entities represent distinct strategic vectors: hospital system integration, home care channel dominance, and clinical specialty focus.
| Leading Market Players |
|---|
| Stryker Corporation |
| Invacare Corporation |
| Medline Industries |
| DJO Global |
| Arjo |
| Dynatronics Corporation |
| Ekso Bionics |
| Drive DeVilbiss Healthcare |
| Enovis |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Taiwan-based semiconductor foundries directly shapes both component availability and price floors for motor control systems in robotic exoskeletons. This scale concentration creates asymmetric bargaining power where rehabilitation device manufacturers absorb cost volatility while Medicare reimbursement codes fix ceiling prices for end-user markets.
Pricing Analysis
Medicare Part B reimbursement codes dictate the pricing tier structure across rehabilitation product portfolios. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated robotic platforms from CE-marked clinical devices and uncertified consumer wellness products. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because group purchasing organizations consolidate hospital vendor rosters. Home care distributors exhibit highest price sensitivity; integrated delivery networks with bundled service contracts show lowest sensitivity.
Supply Chain Analysis
Order-to-delivery extensions for motor control chips now stretch 26-34 weeks, forcing rehabilitation device manufacturers to carry elevated safety stock. Component sourcing draws from Taiwan for semiconductors, China for rare-earth magnets in actuator motors, and Germany for precision mechanical subassemblies. Raw material dependencies center on neodymium, silicon wafers, and thermoplastic composites. Single-source vulnerability in Taiwan-based foundries creates production bottleneck exposure. Distribution runs through durable medical equipment networks serving Medicare Part B channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive advantage as interoperability between rehabilitation devices and hospital electronic medical record systems becomes a procurement gate. The shift from capital equipment sales to subscription-based service models rewards vendors with integrated data infrastructure.
For Market Incumbents: Compound defensive moats by deepening field service network density in United States integrated delivery networks and accelerating FDA breakthrough designation pursuit for robotic platforms. Threat from venture-backed soft robotics specialists demands response through certification investment in EU MDR Class IIa pathways. Vertical integration into semiconductor inventory buffers is the critical lever against Taiwan foundry concentration. For New Entrants and Emerging Players: Differentiate on telehealth-therapy convergence by building algorithm-driven home rehabilitation platforms that integrate remote patient monitoring with prescription digital therapeutics. White-space targets include India's PLI scheme contract manufacturing for export-oriented mobility aids and direct-to-consumer channels for cash-pay wellness segments. Go-to-market angle should emphasize bypassing traditional durable medical equipment distributors through specialized medical device marketplaces. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with subscription-based soft robotic textile deployments in post-acute stroke rehabilitation facilities. Long-term viability favors platform plays with embedded software components over pure hardware manufacturers. Acquisition target archetype: mid-tier manufacturers with ISO 13485 quality systems but underdeveloped pharmacovigilance infrastructure for EU MDR Article 10 compliance. Signal to watch is CMS national coverage determination expansion for AI-guided rehabilitation protocols.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Designation Pursuit | Compressed review timelines pull venture capital into spinal cord injury platforms. |
| CE Marking Pathway Investment | EU MDR conformity separates firms with robust clinical follow-up registries from competitors. |
| Hospital System Partnership | Integrated delivery network procurement standardization requires vendor consolidation across 10-15 facilities. |
| Software Companion Development | Algorithm-driven home rehabilitation programs open reimbursement pathways through telehealth convergence. |
| Reimbursement Strategy | Medicare Part B code additions directly determine commercial viability for home-use technologies. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with rehabilitation device executives, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body records, and hospital procurement contract repositories. Bottom-up product-level volume estimates triangulated with top-down market sizing across the segmentation framework.
Across the analysis window, the forecasting framework modeled volume and value outputs through disaggregation by product type, end-user setting, application discipline, and technology platform. CAGRs were derived from regression analysis of historical reimbursement expansion patterns and regulatory approval velocity. Industry-specific inputs included FDA breakthrough designation pipeline tracking and semiconductor foundry capacity utilization projections.
The analysis sits within stated boundaries; outcomes outside sustained Medicare reimbursement expansion or Taiwan foundry supply stabilization would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway compression and aging demographic trajectories. Semiconductor supply concentration and EU MDR enforcement stringency represent specific risk factors that could revise projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Asia-Pacific Repair and Rehabilitation Market
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
VR Stroke Rehabilitation Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Home Rehabilitation Products Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market
Rehabilitation Services
Massage Therapy Services Market
Rehabilitation Services
Portable Postpartum Rehabilitation Instrument Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Global Medical Rehabilitation Services Market