
 Brachial Plexus Injury Market | 2026-2036
Brachial Plexus Injury Market Size, Share, and Industry Trends Forecast 2026-2036
Brachial Plexus Injury Market Analysis
Specialized nerve graft production in the United States is rebalancing toward biologic and biosynthetic hybrid platforms. AxoGen leverages proprietary allograft processing to anchor the peripheral nerve repair segment. Integra LifeSciences sustains leadership in collagen-based nerve conduit technology through dedicated manufacturing scale. Johnson & Johnson competes across the full reconstructive surgical workflow, extending its position in microsurgical instruments and suture systems.
Brachial plexus injury encompasses damage to the network of nerves connecting the spinal cord to the shoulder, arm, and hand, typically resulting from traction, compression, or laceration trauma that disrupts motor and sensory signaling. Surgical intervention often employs nerve grafting, nerve transfer, or direct repair techniques requiring microsurgical precision and biocompatible scaffold materials to restore limb function. The treatment type dimension shows surgery capturing the deepest margin pools due to procedure complexity and implant intensity, while rehabilitation represents the fastest-growing category as value-based care models extend therapy duration. Patient age group segmentation reveals pediatric cases driving specialized surgical volume given the developmental plasticity of young nerve tissue.
FDA breakthrough device pathways and ISO 13485 quality management standards govern product development timelines and commercial access for nerve repair devices in the United States. The European Medicines Agency and Medical Device Regulation frameworks in Europe impose additional clinical evidence requirements that shape multinational market entry strategies. Stakeholders must monitor how regenerative medicine advanced therapy designations and evolving reimbursement benchmarks for functional restoration procedures reshape competitive positioning without assuming uniform payer acceptance across health systems.
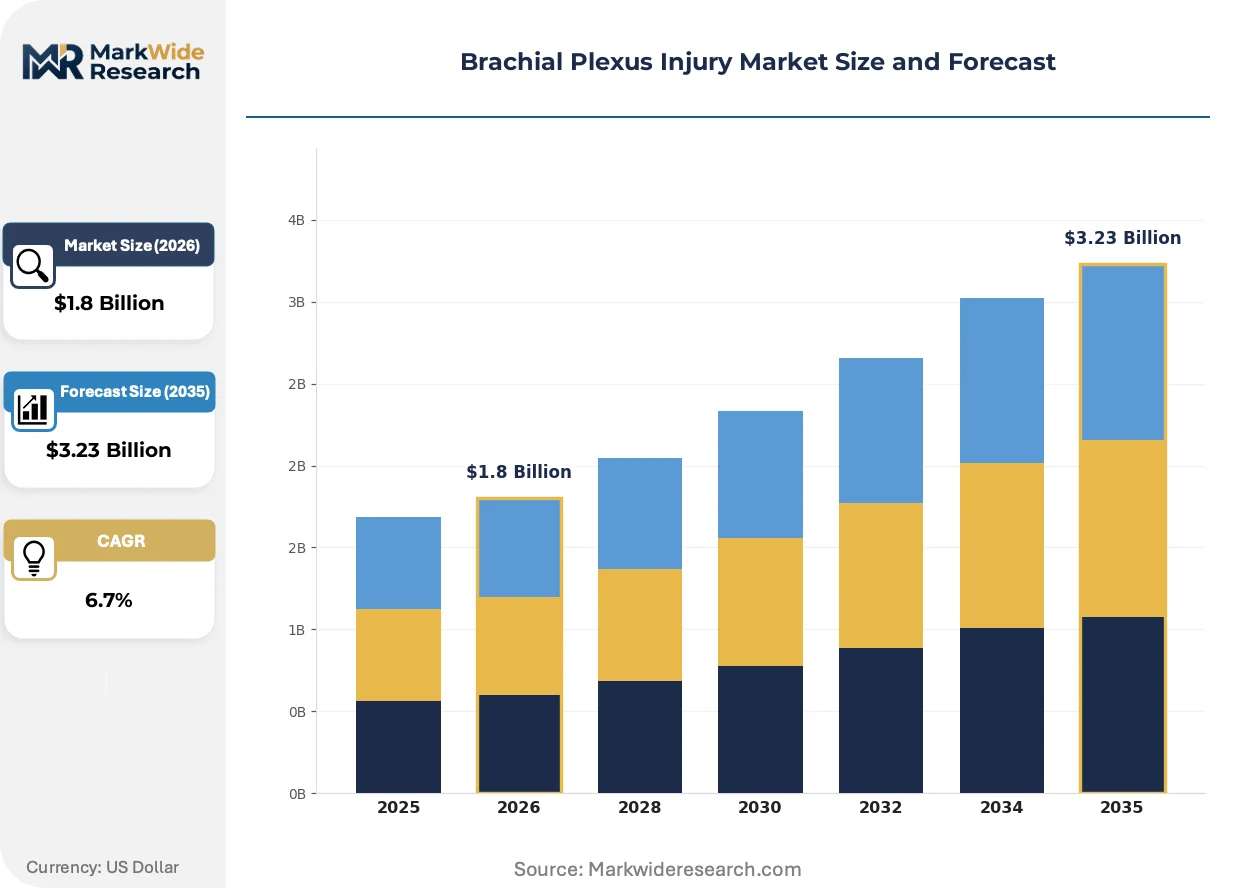
Market Dynamics
FDA breakthrough device designations for peripheral nerve grafts are compressing clinical validation timelines, pulling capital toward biologic scaffold platforms and specialized trauma center service lines.
Growth Catalysts
- Breakthrough Device Pathway:FDA's accelerated review mechanism for nerve repair implants reduces regulatory friction, enabling faster commercialization of allograft and biosynthetic conduit technologies.
- Trauma Center Expansion:Specialized orthopedic hospitals in the United States are building dedicated nerve repair service lines, deepening referral networks for complex brachial plexus reconstruction.
- Pediatric Surgical Volume:Young patients with developmental nerve plasticity drive specialized procedural demand, concentrating high-complexity cases in pediatric tertiary centers.
Market Restraints
- Allograft Supply Concentration:Human donor nerve tissue availability depends on specialized tissue bank networks, creating procurement bottlenecks for processed nerve grafts.
- Reimbursement Variability:CMS and private payer coverage for functional restoration procedures differs across health systems, fragmenting commercial access.
- Microsurgical Skill Scarcity:Nerve transfer and direct repair techniques require subspecialized training, limiting the pool of qualified surgeons.
Strategic Opportunities
- Rehabilitation Extension:Value-based care models in the United States are elongating therapy duration, expanding the addressable market for post-surgical rehabilitation services.
- Hybrid Scaffold Convergence:Collagen-synthetic composite conduits combine biocompatibility with mechanical tunability, opening new product categories between pure biologic and synthetic platforms.
- ISO 13485 Certification Arbitrage:Manufacturers with established quality management systems can leverage regulatory equivalency to accelerate European Medical Device Regulation compliance.
Industry Challenges
- Microsurgical Training Pipeline:Fellowship programs for peripheral nerve surgery produce limited annual graduates, constraining procedural capacity expansion.
- Graft Integration Uncertainty:Variable patient outcomes with processed allografts complicate surgeon preference formation and product loyalty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brachial Plexus Injury Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Physical Therapy, Medication, Rehabilitation Patient Age Group: Pediatric, Adolescent, Adult, Geriatric Severity Level: Mild, Moderate, Severe, Critical Recovery Stage: Acute, Subacute, Chronic, Late Phase |
| Companies Covered | GlaxoSmithKline, Novartis, Pfizer, AxoGen, Roche, AbbVie, Merck, Integra LifeSciences, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brachial Plexus Injury Market Emerging Trajectories
Biologic-synthetic hybrid nerve conduits are displacing single-material platforms, while regulatory pathways and procurement models simultaneously reshape competitive positioning across the value chain.
Processed allograft nerve grafts with proprietary decellularization protocols are electrifying the peripheral nerve repair segment, with trauma centers and specialized hand surgery units adopting these implants at accelerating velocity. The technology is compressing reliance on autograft harvest morbidity while enabling single-stage reconstruction of complex brachial plexus injuries.
European Medical Device Regulation clinical evidence requirements are tightening market entry standards for nerve repair devices, forcing manufacturers to generate additional safety and performance data. Multinational firms are responding by front-loading European clinical trials to secure CE marking ahead of notified body capacity constraints.
Hospital purchasing committees are consolidating vendor relationships for nerve repair implants, shifting procurement authority from individual surgeons to centralized supply chain functions. This concentration is most visible in United States health systems, where integrated delivery networks negotiate bundled pricing for grafts, conduits, and microsurgical instruments.
Brachial Plexus Injury Market Segmentation
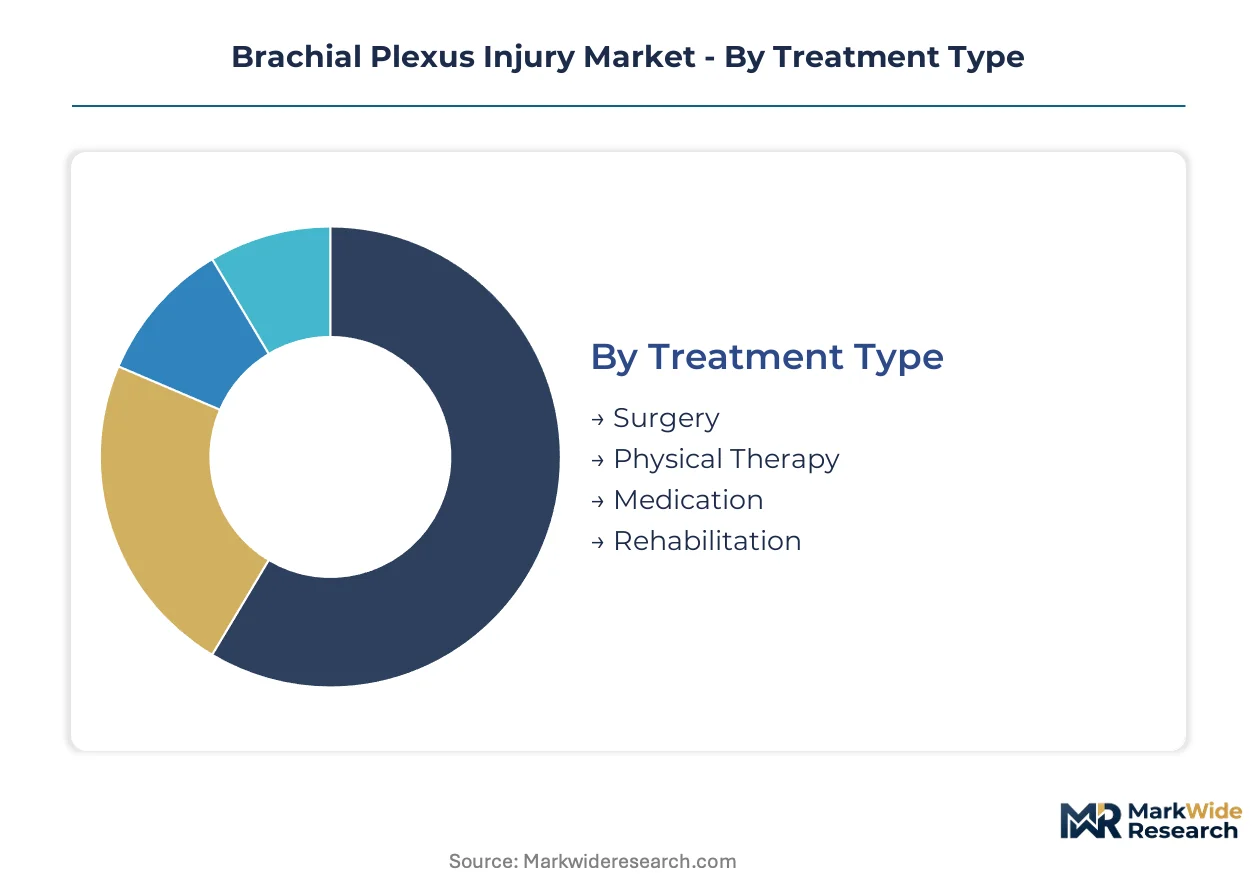
Segmentation in brachial plexus injury care reveals how treatment intensity, patient physiology, and recovery timelines fragment commercial opportunity across distinct service and product categories. Each dimension carries unique margin structures and regulatory requirements that shape vendor positioning.
Treatment Type:
Surgical intervention commands premium pricing due to implant intensity and microsurgical complexity, while rehabilitation services scale through volume-based care models.
- Surgery:Nerve grafting, nerve transfer, and direct repair procedures deploy allografts, conduits, and microsurgical instruments. Demand concentrates in Level I trauma centers across the United States where specialized reconstructive teams manage complex brachial plexus avulsion cases. CMS reimbursement variability and implant bundling pressures constrain margin expansion despite high procedural fees.
- Rehabilitation:Post-surgical occupational and physical therapy protocols extend functional recovery windows. Value-based care pilots in United States health systems are elongating authorized therapy duration, expanding addressable service hours per patient episode. This segment climbs fastest as payers shift toward outcomes-based functional restoration metrics.
- Physical Therapy:Early mobilization and neuromuscular re-education protocols prevent secondary complications.
- Medication:Neuropathic pain management and anti-inflammatory agents support adjunctive care pathways.
Today's leader: Surgery. Tomorrow's challenger: Rehabilitation.
Patient Age Group:
Developmental nerve plasticity creates divergent surgical candidacy and recovery expectations across life stages.
- Pediatric:Infants and children exhibit superior axonal regeneration capacity and cortical remapping potential. Tertiary pediatric centers in Boston, Philadelphia, and Cincinnati drive specialized surgical volume for obstetric brachial plexus palsy. Parental demand for functional restoration and developmental milestone achievement sustains high intervention rates.
- Adult:Motor vehicle collisions, motorcycle accidents, and industrial trauma generate acute surgical demand. United States trauma networks route adult patients to designated hand and peripheral nerve specialists based on injury complexity scoring.
- Adolescent:Sports-related traction injuries and all-terrain vehicle accidents predominate in this transitional category.
- Geriatric:Falls and low-energy trauma compound age-related nerve vulnerability and comorbidity burdens.
Pediatric cases sustain premium procedural economics; adult volume scales through trauma system penetration.
Severity Level:
Injury grade determines intervention intensity from conservative management to multi-stage reconstructive sequences.
- Severe:Complete nerve root avulsion from the spinal cord necessitates nerve transfer from donor nerves or free-functioning muscle transfer. These cases cluster at supraregional referral centers in the United States where microsurgical expertise and intraoperative electrodiagnostic capabilities converge. Procedural complexity and operative duration drive substantial reimbursement but require substantial capital investment.
- Moderate:Postganglionic ruptures and neuroma-in-continuity permit direct repair or interpositional grafting with more predictable outcomes.
- Mild:Neurapraxia and axonotmesis resolve through observation and conservative management in most cases.
- Critical:Pan-plexus injury with vascular compromise demands emergent multidisciplinary intervention.
Severe injuries concentrate margin capture; moderate cases expand addressable procedural volume.
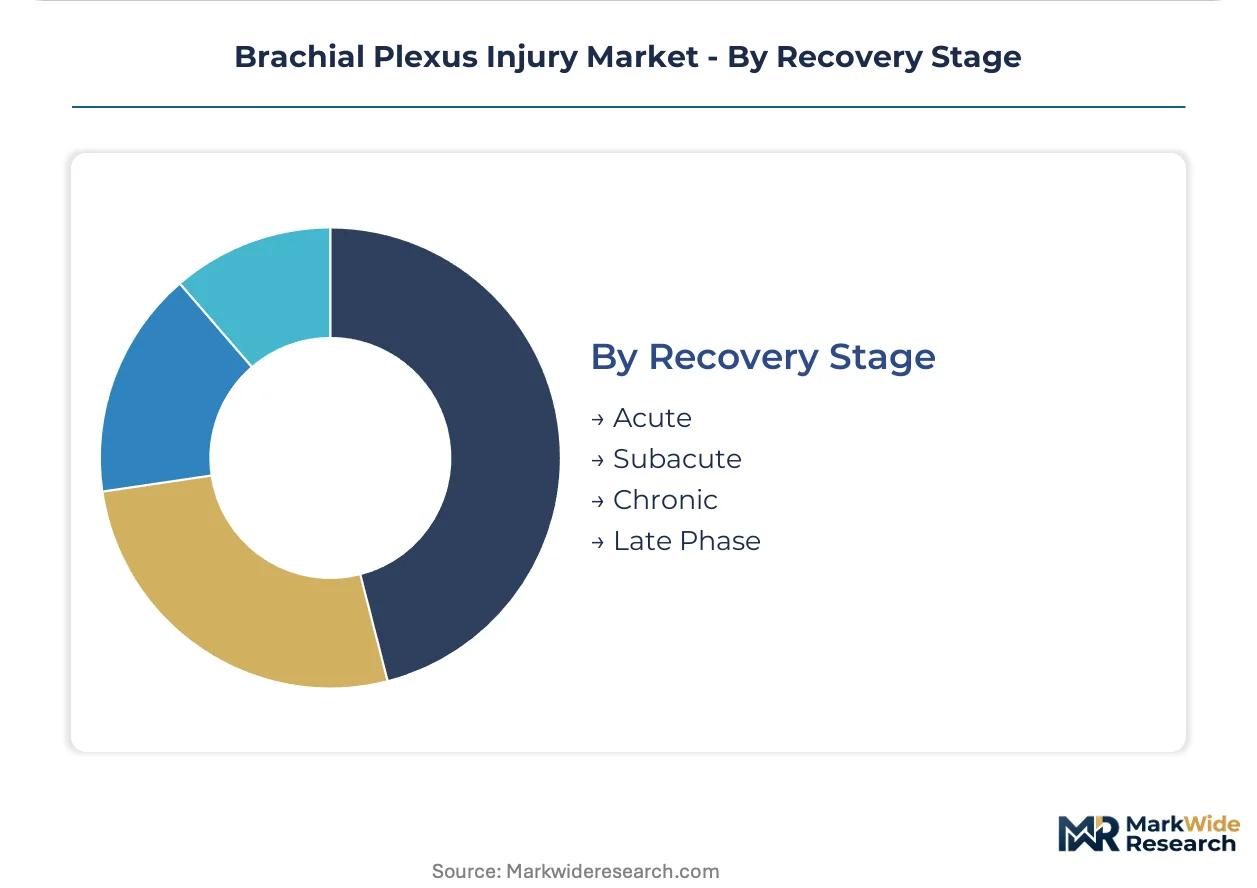
Recovery Stage:
Temporal progression from injury to functional restoration shapes service utilization patterns and payer authorization requirements.
- Acute:Immediate post-injury evaluation, imaging, and surgical decision-making occur within trauma pathways. United States emergency departments activate nerve surgery consultation protocols for high-mechanism injuries. Early intervention windows close within weeks, compressing diagnostic and referral timelines.
- Chronic:Established paralysis and joint contracture require secondary reconstructive procedures including tendon transfer and arthrodesis. These patients cycle through specialized hand therapy units for sustained functional optimization.
- Subacute:Serial electrodiagnostic testing guides conservative versus surgical management decisions.
- Late Phase:Salvage procedures address failed primary reconstruction or neglected presentation.
Acute stage governs surgical candidacy determination; chronic stage extends lifetime patient value through iterative intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics pull nerve graft manufacturing toward jurisdictions with streamlined quality management certification and favorable reimbursement pathways. Production migration concentrates where FDA breakthrough designations and ISO 13485 equivalency reduce time-to-market for biologic scaffold platforms.
United States
Level I trauma centers in Houston, Baltimore, and Los Angeles drive specialized surgical volume for complex brachial plexus reconstruction. FDA breakthrough device pathways compress clinical validation timelines for allograft processors seeking accelerated commercial access. The Texas Medical Center anchors the deepest concentration of microsurgical expertise and intraoperative electrodiagnostic capabilities.
Germany
Notified bodies in Munich and Stuttgart enforce Medical Device Regulation clinical evidence requirements that shape multinational market entry strategies. EMA frameworks impose additional safety and performance data generation obligations for peripheral nerve repair devices. The Baden-Württemberg medical technology cluster sustains leadership in precision manufacturing for microsurgical instruments.
Japan
PMDA review standards for regenerative medical products create distinct regulatory hurdles for allograft and biosynthetic conduit technologies. METI industrial policy supports domestic production of biocompatible scaffold materials through targeted R&D subsidies. The Kansai region hosts specialized orthopedic hospitals expanding nerve repair service lines for trauma and obstetric palsy cases.
India
CDSCO medical device rules govern import and local manufacture of nerve conduits and processed graft materials. CDSCO quality management system inspections align with ISO 13485 standards to facilitate export-oriented production. Tertiary centers in Delhi and Mumbai concentrate pediatric surgical volume for developmental nerve plasticity cases.
Switzerland
Swissmedic certification requirements for high-risk medical devices attract manufacturers seeking regulatory prestige in European markets. The country's bilateral agreements with the EU enable streamlined CE marking recognition for nerve repair implants. Basel and Zurich host contract manufacturers specializing in collagen-based conduit processing for global distribution.
Brachial Plexus Injury Market Vendor Landscape
United States producers anchor one tier; European specialists hold differentiated positions in regulatory-intensive segments. Market structure fragments across biologic scaffold processors, diversified surgical device conglomerates, and pharmaceutical incumbents with neuropathic pain portfolios. Three archetypes dominate: pure-play allograft processors, diversified reconstructive surgery platforms, and pain-management pharmaceutical suppliers. Consolidation activity concentrates in biologic-synthetic hybrid conduit technologies; strategic partnerships link tissue banks to specialized trauma center networks.
Among diversified medical technology conglomerates, Johnson & Johnson and Integra LifeSciences exemplify full-workflow positioning spanning microsurgical instruments through biocompatible scaffold materials. AxoGen represents the pure-play archetype focused exclusively on peripheral nerve repair through proprietary allograft processing protocols. Pharmaceutical incumbents including Pfizer and Novartis occupy distinct positions in adjacency segments addressing neuropathic pain management rather than surgical reconstruction.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Novartis |
| Pfizer |
| AxoGen |
| Roche |
| AbbVie |
| Merck |
| Integra LifeSciences |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
FDA quality system regulation compliance gates qualified supply access for processed allograft nerve grafts, with ISO 13485-certified manufacturers commanding premium-tier pricing while non-certified processors face exclusion from integrated delivery network procurement panels. This regulatory filtering concentrates pricing power among established biologic scaffold producers in the United States.
Pricing Analysis
Distributor margins for nerve repair implants typically range from 15-25 percent for standard allografts to 40-60 percent for proprietary decellularized nerve grafts with breakthrough device designation. Three-tier pricing structure across premium, standard, and economy levels reflects graft processing complexity, with AxoGen's Avance Nerve Graft and Integra's NeuraGen conduit occupying distinct price bands. Cost compression in the standard allograft tier is intensifying because hospital purchasing committees are consolidating vendor relationships and negotiating bundled pricing for graft-conduit-instrument sets. Pediatric tertiary centers exhibit lowest price sensitivity given parental demand for functional restoration, while community hospitals in United States trauma networks show highest sensitivity to per-unit graft costs.
Supply Chain Analysis
Microsurgical instrument manufacturing workforce availability in Germany's Baden-Württemberg cluster and Switzerland's Basel region underpins precision supply for nerve repair procedures. Human donor tissue procurement draws from specialized tissue bank networks in the United States, with secondary processing capacity concentrated in Florida and California manufacturing facilities. Collagen raw material sourcing rests on bovine and porcine supply chains subject to veterinary health regulatory restrictions in key export markets. Single-source vulnerability characterizes the processed allograft segment where AxoGen dominates proprietary decellularization protocol supply. Distribution runs through specialized surgical device distributors serving Level I trauma centers and integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brachial plexus injury market operates as a regulatory compounder where FDA breakthrough device designations for peripheral nerve grafts accelerate clinical validation timelines and pull capital toward qualified biologic scaffold platforms.
For Market Incumbents: To counter biosynthetic hybrid conduit entrants from diversified orthopedic device manufacturers, AxoGen should deepen backward integration into tissue bank procurement networks and expand in-house decellularization capacity in Florida processing facilities. Integra LifeSciences must defend collagen conduit positioning by accelerating CE marking pathways under European Medical Device Regulation frameworks before notified body capacity constraints tighten. For New Entrants and Emerging Players: Enter via pediatric obstetric brachial plexus palsy reconstruction, the most penetrable segment given developmental nerve plasticity and sustained parental demand for functional restoration at Boston Children's Hospital, Children's Hospital of Philadelphia, and Cincinnati Children's Hospital Medical Center. Target rehabilitation service line partnerships with value-based care pilots in United States health systems as the go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional tissue bank processors because FDA quality system regulation compliance creates scale advantages in allograft procurement and decellularization protocol standardization. Five-to-ten year viability hinges on regenerative medicine advanced therapy designation expansion for peripheral nerve repair. Watch FDA breakthrough device designation velocity for nerve transfer adjunct technologies as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerated review compresses commercialization timelines for allograft processors seeking United States market access. |
| CE Marking Under MDR | European clinical evidence requirements reshape multinational entry strategies for collagen conduit manufacturers. |
| Hospital System Partnership | Integrated delivery network bundling agreements consolidate procurement authority from individual surgeons. |
| Reimbursement Strategy | CMS functional restoration procedure coding determines commercial access across United States health systems. |
| Tissue Bank Integration | Backward control over donor nerve procurement reduces supply bottlenecks for processed allograft production. |
Methodological Framework
Direct dialogue with peripheral nerve surgeons, hospital purchasing committee members, tissue bank procurement directors, and biomedical engineers at Level I trauma centers grounded qualitative insights in clinical workflow realities. Secondary validation drew from FDA 510(k) and breakthrough device designation filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up and top-down triangulation cross-checked procedure volume estimates against implant shipment data and surgical facility capacity.
Bottom-up modeling anchored forecast outputs, with top-down macroeconomic and demographic validation ensuring cross-consistency across the projection horizon. Segmentation dimensions included treatment type, patient age group, injury severity level, and recovery stage, with United States regional trauma network penetration as an industry-specific overlay. CAGRs were derived from procedure volume growth trajectories and implant intensity per case, incorporating pediatric developmental plasticity effects and adult trauma incidence patterns as forecast inputs.
Inputs from FDA device classification databases and CMS procedure utilization files were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around implant pricing and volume estimates. Forecasts reflect assumptions regarding breakthrough device designation velocity, tissue bank network expansion, and value-based care pilot sustainability. Material deviation in FDA regulatory pathway timelines or CMS functional restoration reimbursement benchmarks warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Occupational and Physical Therapy Services Market
Rehabilitation Services
Speech Therapy Services Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
Global Home Rehabilitation Products and Services Market
Rehabilitation Services
Global Outpatient Rehabilitation Centers Market
Rehabilitation Services
Home Rehabilitation Services Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
Motion Stimulation Therapy Market
Rehabilitation Services
Exoskeleton and Rehabilitation Robot Safety and Performance Test Equipment Market
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
VR Stroke Rehabilitation Market
Rehabilitation Services
Neurorehabilitation Gaming Systems Market
Rehabilitation Services
Outpatient Rehabilitation Services Market