
 Home Rehabilitation Products Market | 2026-2036
Home Rehabilitation Products Market Size, Share, and Industry Trends Forecast 2026-2036
Home Rehabilitation Products Market Intelligence
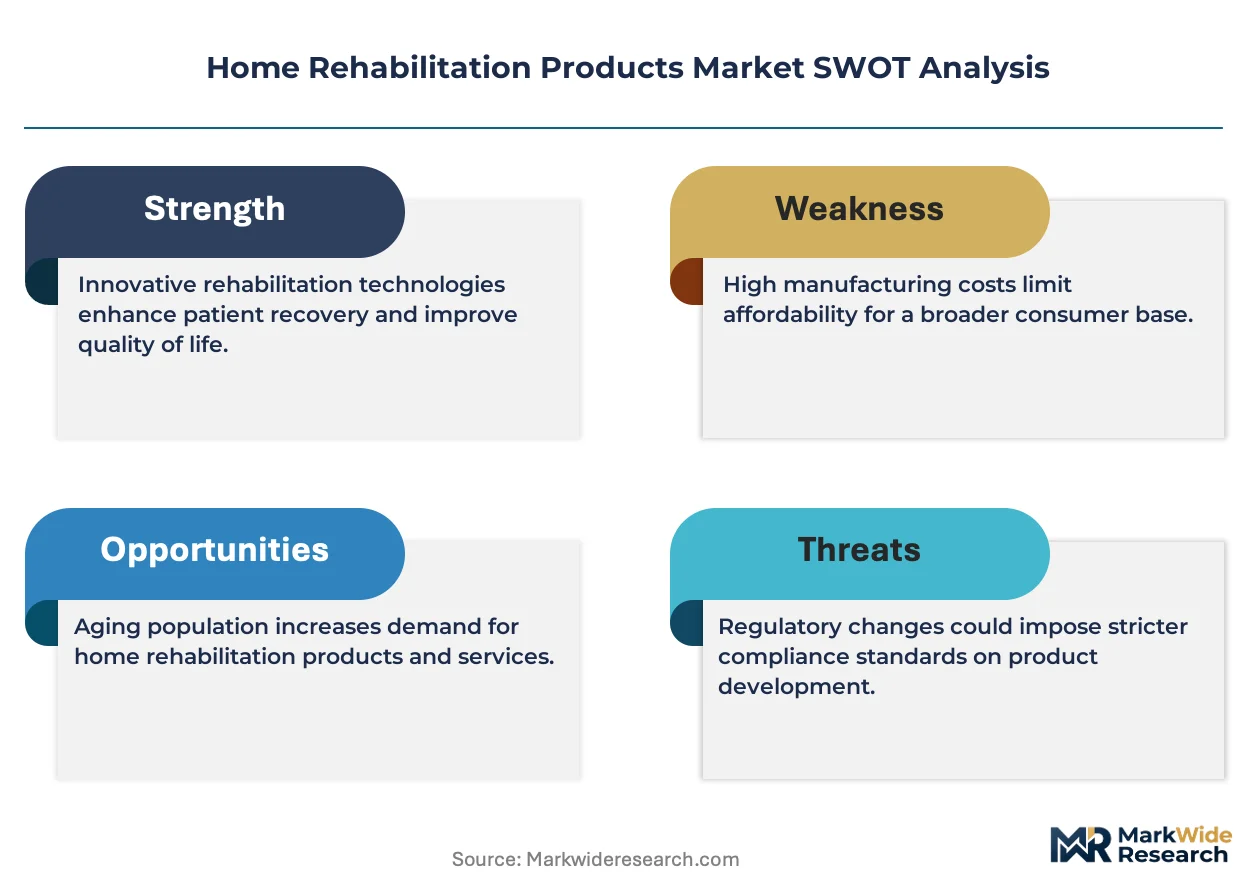
The home rehabilitation products market is rebalancing between premium robotic-assisted therapy systems and commodity-grade mobility aids as payers tighten reimbursement bands. Invacare Corporation dominates the powered wheelchair and seating category through extensive durable medical equipment dealer networks. Ekso Bionics Holdings, Inc. differentiates in the exoskeleton segment with FDA-cleared devices for stroke rehabilitation, sustaining premium positioning despite higher acquisition costs. Medline Industries, Inc. leverages its broad distribution infrastructure to compete across multiple product tiers simultaneously.
Home rehabilitation products encompass assistive and therapeutic devices engineered for patient recovery, functional restoration, and independence maintenance outside clinical facilities, typically featuring adjustable load capacities, biocompatible materials, and ergonomic interfaces rated for repeated residential use. Mobility aids constitute the largest installed base, though therapeutic devices are recording the fastest growth as sensor-enabled continuous passive motion units and neuromuscular electrical stimulation systems penetrate post-surgical protocols. Orthopedic supports retain stable margin pools due to recurring replacement cycles and direct-to-patient subscription models, while respiratory equipment demand concentrates among chronic obstructive pulmonary disease and post-COVID-19 syndrome populations.
FDA 510(k) clearance requirements and ISO 14971 risk management standards govern device commercialization in the United States, with the EPA additionally regulating antimicrobial claims on wound care and surface-contact products. The EU Medical Device Regulation mandates notified body certification for home-use therapeutic devices entering European markets, extending compliance timelines and elevating quality system investments. Stakeholders must monitor evolving CMS national coverage determinations for remote therapeutic monitoring, as reimbursement rulings will determine which connected rehabilitation modalities achieve scalable home deployment.
Market Dynamics
Reimbursement compression from Medicare and Medicaid is forcing manufacturers to choose between premium robotics and commodity hardware, splitting procurement strategies across hospital discharge planners and direct-to-consumer channels.
Growth Catalysts
- CMS Remote Therapeutic Monitoring:The 2022 national coverage determination for RTM codes now reimburses connected neuromuscular electrical stimulation and continuous passive motion devices, accelerating home deployment of sensor-enabled systems.
- Aging demographics in the United States:The 65-plus population expansion is reshaping durable medical equipment procurement, with hospital discharge planners prioritizing home-based recovery to reduce readmission penalties.
- ISO 13485 quality mandates:Harmonized quality system requirements across North American and European channels are enabling single-registration market entry, reducing compliance duplication for manufacturers.
Market Restraints
- Lithium-ion battery supply concentration:Powered wheelchair and mobility aid production depends on Chinese cell manufacturers, exposing margins to raw material volatility and export control friction.
- FDA 510(k) clearance timelines:Class II therapeutic device submissions now average 180 days, delaying commercialization for exoskeleton and robotic-assisted therapy entrants.
- Professional caregiver shortage:Home health agency staffing gaps limit effective utilization of complex rehabilitation equipment, suppressing demand for premium therapeutic modalities.
Strategic Opportunities
- Direct-to-patient subscription models:Orthopedic support manufacturers are bypassing durable medical equipment dealers through digital prescription platforms, capturing recurring revenue from replacement cycle demand.
- EU Medical Device Regulation notified body certification:Early MDR compliance investments by European manufacturers create competitive moats as extended timelines delay rival market entry.
- Sensor-telehealth convergence:Integration of continuous passive motion units with remote patient monitoring platforms opens new reimbursement pathways through Medicare Advantage plans.
Industry Challenges
- Biomedical engineering talent scarcity:Firmware development for sensor-enabled rehabilitation devices competes with broader medtech and consumer electronics sectors, elongating product development cycles.
- Legacy EHR integration complexity:Home rehabilitation data streams require HL7 FHIR compliance to interface with hospital discharge systems, adding middleware development costs.
- Antimicrobial claim substantiation:EPA registration for wound care and surface-contact products demands clinical validation timelines that conflict with rapid product refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Rehabilitation Products Market |
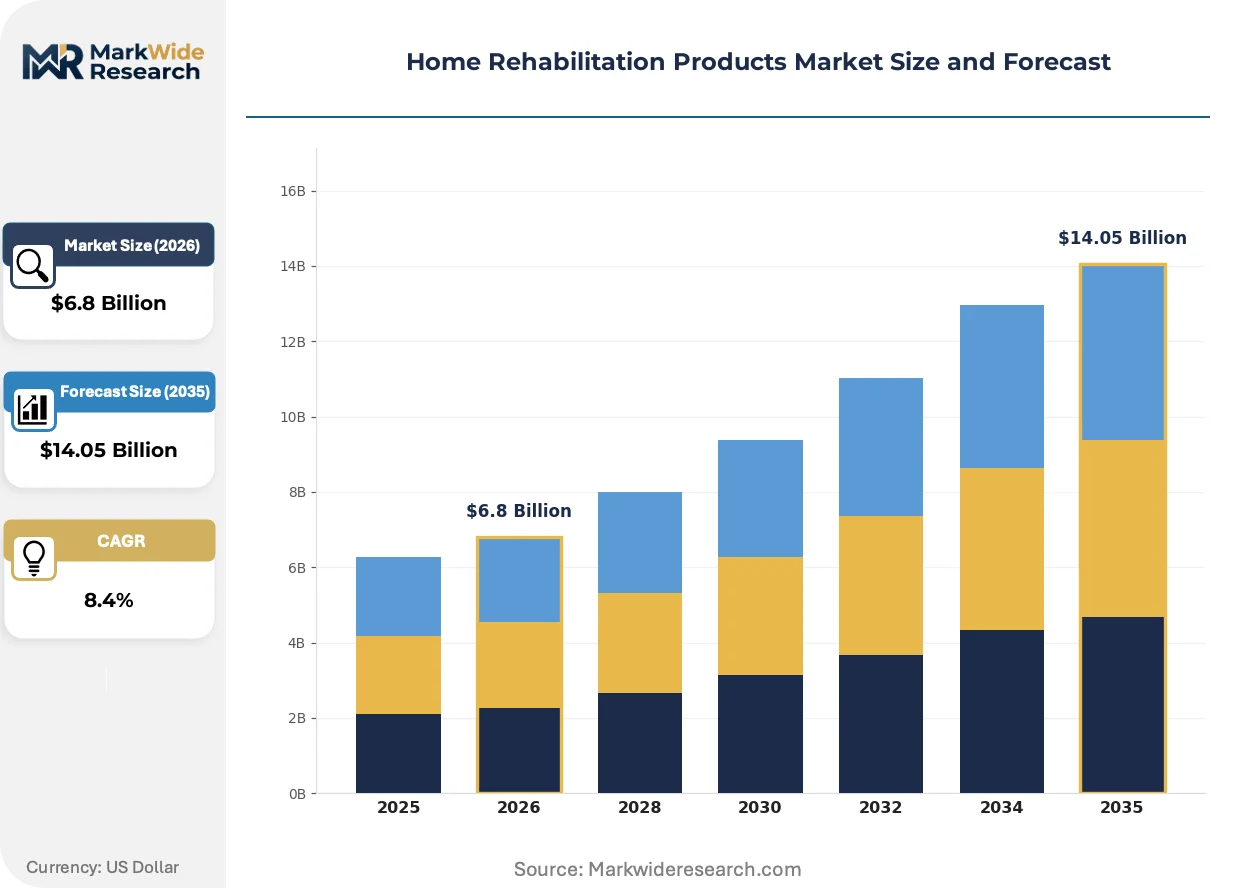
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobility Aids, Therapeutic Devices, Orthopedic Supports, Respiratory Equipment, Daily Living Aids Application: Stroke Recovery, Post-Surgery Care, Chronic Pain Management, Neurorehabilitation, Elderly Care End User: Patients, Caregivers, Home Health Agencies, Physical Therapists, Occupational Therapists Distribution Channel: Online Retailers, Medical Supply Stores, Direct Sales, Pharmacies, Healthcare Providers |
| Companies Covered | Ekso Bionics Holdings, Inc., Prism Medical, Invacare Corporation, Performance Health, AliMed, Inc., Medline Industries, Inc., Hocoma AG, Drive DeVilbiss Healthcare, DJO Global, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Rehabilitation Products Market Strategic Shifts & Innovations
Sensor-enabled continuous passive motion systems are compressing the boundary between clinical and residential rehabilitation, while regulatory frameworks for connected devices lag hardware innovation cycles.
Neuromuscular electrical stimulation platforms with embedded IMU sensors are integrating real-time kinematic feedback into post-surgical protocols. Orthopedic clinics in the United States are adopting these systems for anterior cruciate ligament reconstruction patients within 90 days of discharge. This integration is compressing the traditional 12-week clinical therapy model into hybrid home-clinic programs.
The EU Medical Device Regulation's 2021 enforcement is extending notified body certification timelines for home-use therapeutic devices entering European markets. Manufacturers must now demonstrate clinical evidence for software-as-a-medical-device components. Stroke rehabilitation exoskeletons face the most severe delays, with some submissions exceeding 24 months for CE marking completion.
Hospital discharge planners are consolidating vendor relationships around single-source durable medical equipment contracts that bundle mobility aids, respiratory equipment, and therapeutic devices. This concentration is displacing fragmented procurement across multiple specialty dealers. Medicare Advantage penetration in Florida and Arizona is accelerating this behavioral shift through value-based care incentives.
Home Rehabilitation Products Market Segmentation
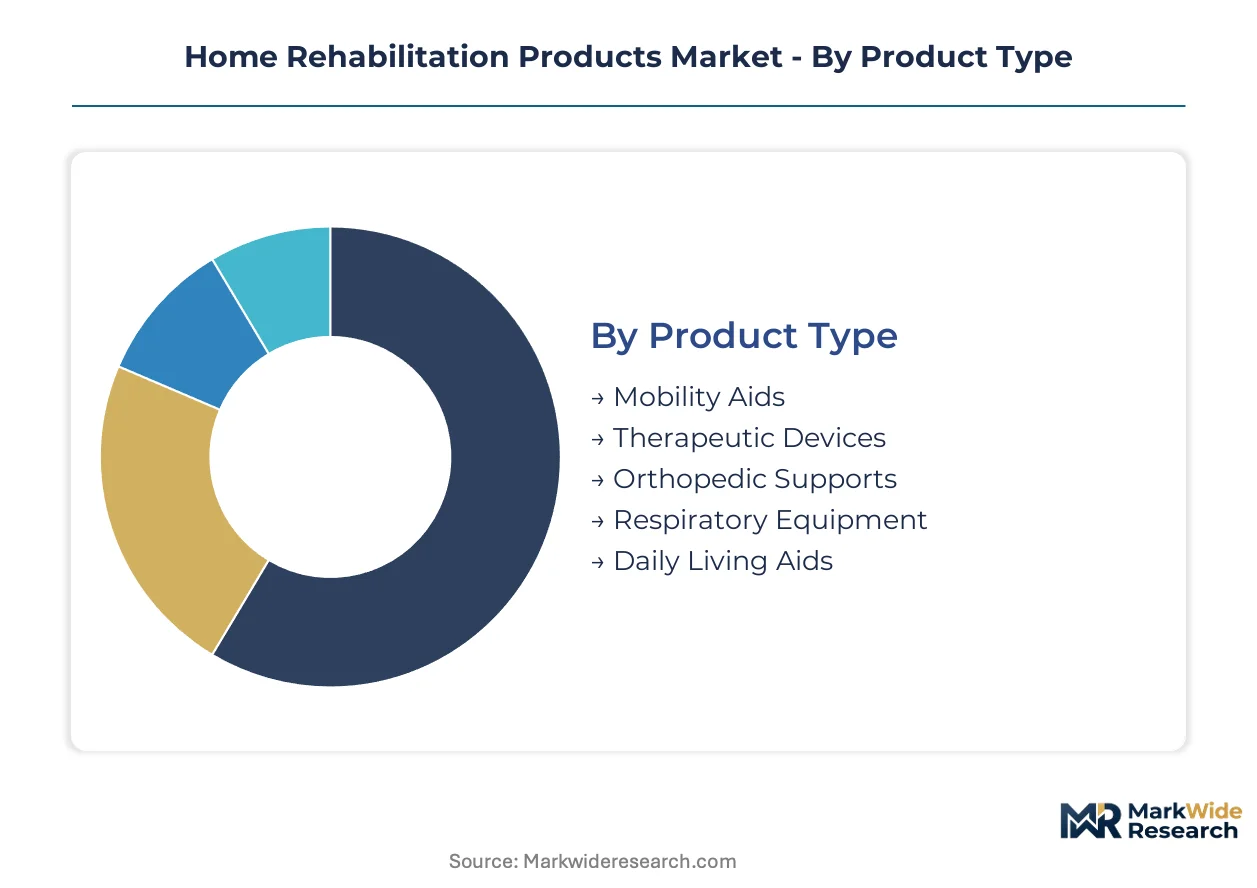
Segmentation in home rehabilitation products reveals divergent procurement patterns between acute recovery episodes and chronic condition management. Replacement cycles, reimbursement pathways, and caregiver capability constraints shape demand concentration across each dimension differently.
Product Type:
Upgrade cycles vary dramatically by product category, with powered mobility systems requiring capital replacement every five to seven years while consumable supports turn over quarterly.
- Mobility Aids:Powered wheelchairs, manual wheelchairs, walkers, and canes engineered for residential load ratings and doorway clearances. Hospital discharge planners in the United States prioritize these for reducing thirty-day readmission penalties, driving bundled procurement contracts.
- Therapeutic Devices:Continuous passive motion units, neuromuscular electrical stimulation systems, and robotic-assisted therapy platforms with embedded IMU sensors. Post-surgical protocols for anterior cruciate ligament reconstruction are absorbing these fastest as CMS Remote Therapeutic Monitoring codes now reimburse connected deployments.
- Orthopedic Supports:Braces, splints, and compression garments utilizing biocompatible polymers. Direct-to-patient subscription models are capturing recurring revenue from replacement cycle demand.
- Respiratory Equipment:Oxygen concentrators, nebulizers, and ventilators for chronic obstructive pulmonary disease and post-viral syndrome populations.
- Daily Living Aids:Reachers, dressing tools, and bath safety equipment for independence maintenance in aging-in-place scenarios.
Volume placements concentrate in Mobility Aids; the faster expansion belongs to Therapeutic Devices.
Application:
Clinical acuity determines equipment sophistication requirements, with high-intensity neurorecovery demanding robotic systems while chronic maintenance relies on simpler modalities.
- Stroke Recovery:Exoskeleton-assisted gait training and constraint-induced movement therapy protocols. FDA 510(k) clearance timelines averaging one hundred eighty days delay commercialization for robotic entrants in this segment.
- Post-Surgery Care:Continuous passive motion and cold therapy systems for joint replacement and spinal procedures. Home health agencies are expanding investment here as patient preference shifts toward recovery outside institutional settings.
- Chronic Pain Management:Transcutaneous electrical nerve stimulation and thermal therapy devices for long-term symptom control.
- Neurorehabilitation:Balance trainers and cognitive-motor integration platforms for traumatic brain injury and multiple sclerosis populations.
- Elderly Care:Fall prevention systems and adaptive equipment for functional decline management in aging-in-place contexts.
Post-Surgery Care dominates current placements; Stroke Recovery is climbing the fastest as exoskeleton technology penetrates residential settings.
End User:
Capability asymmetries between professional and lay users fragment product design requirements, with therapist-directed protocols tolerating complexity that overwhelms independent patients.
- Patients:Independent users operating equipment without professional supervision. Ergonomic interfaces and fail-safe mechanisms are essential for this group's effective utilization rates.
- Caregivers:Family members and informal aides managing equipment for dependent individuals. Training burden and maintenance simplicity drive purchasing decisions here.
- Home Health Agencies:Licensed organizations delivering skilled services under Medicare certification. Staffing shortages limit effective utilization of complex therapeutic modalities.
- Physical Therapists:Licensed professionals prescribing and monitoring home exercise programs with remote oversight capabilities.
- Occupational Therapists:Specialists in activities-of-daily-living adaptation selecting daily living aids and environmental modifications.
Patient-directed placements lead in volume; Home Health Agencies are gaining share fastest as Medicare Advantage penetration accelerates value-based procurement.
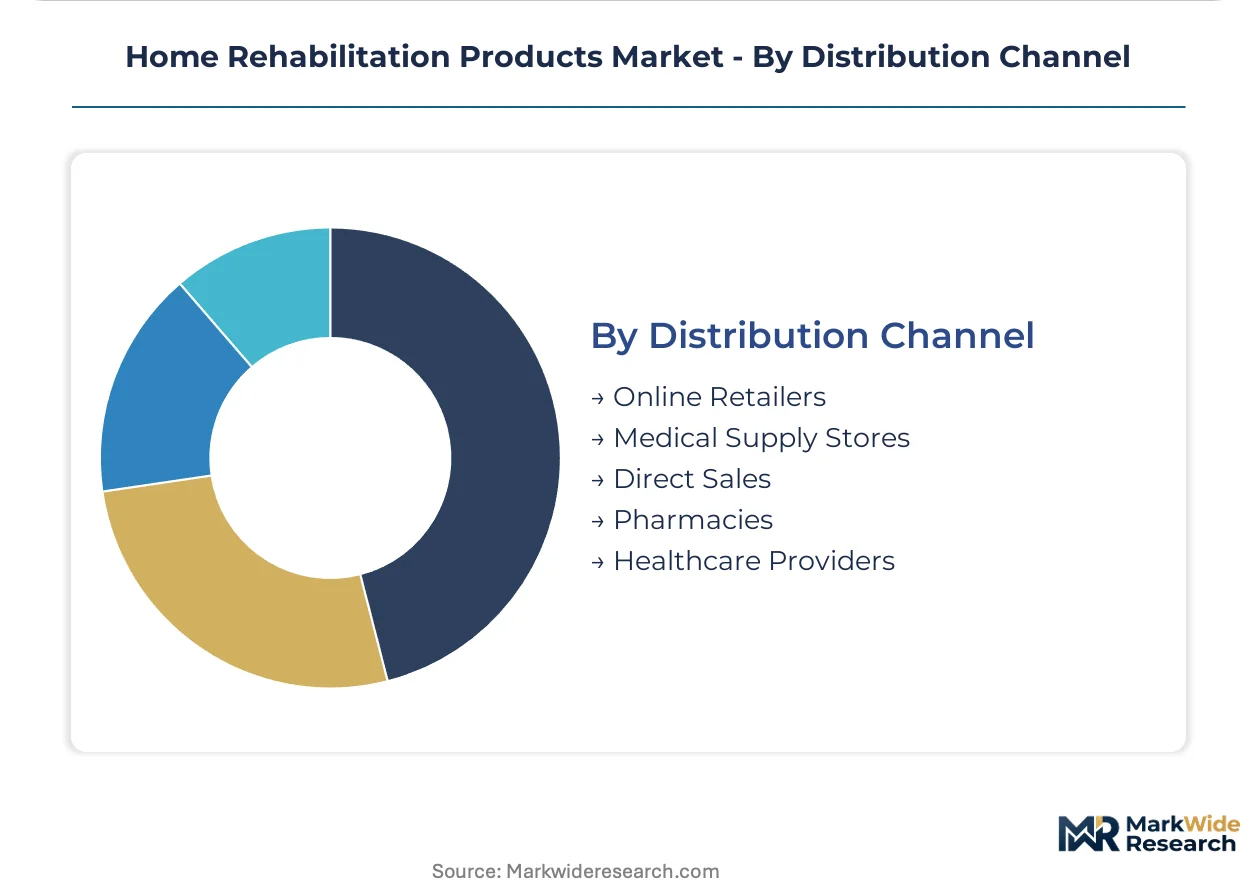
Distribution Channel:
Channel selection reflects reimbursement mechanics, with fee-for-service billing favoring traditional durable medical equipment dealers while direct models exploit cash-pay and subscription opportunities.
- Online Retailers:E-commerce platforms offering comparison shopping and home delivery for non-reimbursed products. Direct-to-patient subscription models for orthopedic supports are bypassing traditional dealers through these channels.
- Medical Supply Stores:Brick-and-mortar durable medical equipment dealers with Medicare accreditation. Hospital discharge planners are consolidating vendor relationships around single-source contracts bundling multiple product categories.
- Direct Sales:Manufacturer-to-patient transactions for premium therapeutic devices. Exoskeleton manufacturers utilize this channel to manage complex fitting and training requirements.
- Pharmacies:Retail drugstores with expanding durable medical equipment sections for convenience-driven purchases.
- Healthcare Providers:Hospital-affiliated discharge departments and outpatient clinics coordinating home equipment procurement.
Medical Supply Stores retain the largest placement volume; Online Retailers show the steepest expansion trajectory as digital prescription platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American home rehabilitation product distribution through its dense cluster of durable medical equipment manufacturers and Medicare-certified home health agencies serving the upper Midwest corridor.
United States
Hospital discharge planners in Florida and Arizona are consolidating vendor relationships around single-source contracts bundling mobility aids and therapeutic devices. CMS Remote Therapeutic Monitoring codes now reimburse connected neuromuscular electrical stimulation systems, accelerating sensor-enabled deployments. The Minneapolis-St. Paul corridor concentrates powered wheelchair manufacturing and durable medical equipment distribution infrastructure.
Germany
Stroke rehabilitation exoskeleton developers face extended EU Medical Device Regulation notified body certification timelines exceeding twenty-four months for CE marking completion. The country's national pharmaceutical regulator enforces stringent clinical evidence requirements for software-as-a-medical-device components. Baden-Württemberg hosts precision engineering clusters supplying robotic-assisted therapy platform components.
Japan
Tokyo's aging demographic density drives demand for fall prevention systems and adaptive daily living aids in aging-in-place scenarios. METI standards govern electrical safety for home-use therapeutic devices with embedded sensor arrays. The Kansai corridor around Osaka concentrates orthopedic support manufacturing with biocompatible polymer supply chains.
United Kingdom
NHS England procurement frameworks are shifting toward value-based rehabilitation equipment contracts that bundle post-surgical care devices across acute and community settings. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements post-Brexit for Class II therapeutic devices. The Southeast England corridor around London hosts digital health platforms enabling direct-to-patient subscription models for orthopedic supports.
China
Zhejiang Province manufacturers dominate lithium-ion cell production for powered mobility systems, exposing global supply chains to raw material volatility and export control friction. NMPA regulations govern domestic commercialization of continuous passive motion units and neuromuscular electrical stimulation platforms. The Yangtze River Delta clusters rehabilitation device assembly operations serving both domestic hospitals and export markets.
Home Rehabilitation Products Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the home rehabilitation products market, with durable medical equipment manufacturers maintaining captive production of powered mobility systems while therapeutic device specialists outsource sensor module fabrication. The vendor base splits between consolidated multi-category distributors and focused single-product developers. Three archetypes dominate: integrated durable medical equipment suppliers with Medicare accreditation networks, robotics specialists commercializing FDA-cleared exoskeletons, and direct-to-patient orthopedic support brands bypassing traditional dealers. Competitive moves concentrate on strategic partnerships with hospital discharge planning departments and portfolio diversification into connected remote monitoring platforms.
Within the integrated durable medical equipment tier, Invacare Corporation and Drive DeVilbiss Healthcare occupy positions spanning powered wheelchairs, respiratory equipment, and daily living aids through extensive dealer network relationships. Ekso Bionics Holdings, Inc. exemplifies the robotics specialist archetype, commercializing stroke rehabilitation exoskeletons through direct sales channels that manage complex fitting protocols. Medline Industries, Inc. represents the diversified distributor model, competing across multiple product tiers simultaneously through broad healthcare supply chain infrastructure. Hocoma AG anchors European therapeutic device development with Swiss precision engineering heritage.
| Leading Market Players |
|---|
| Ekso Bionics Holdings, Inc. |
| Prism Medical |
| Invacare Corporation |
| Performance Health |
| AliMed, Inc. |
| Medline Industries, Inc. |
| Hocoma AG |
| Drive DeVilbiss Healthcare |
| DJO Global, Inc. |
| Others |
Cost & Logistics Intelligence
Biomedical engineering talent scarcity in the Minneapolis-St. Paul corridor widens labor-cost differentials between sensor-embedded therapeutic device manufacturers and commodity mobility aid producers, translating into pronounced pricing-tier spreads across the home rehabilitation products landscape.
Pricing Analysis
Value-based pricing anchored to patient throughput outcomes governs robotic-assisted therapy platforms, while per-unit transactional models dominate powered wheelchairs and orthopedic supports. Price differentiation separates FDA-cleared Class II therapeutic devices with embedded IMU sensors from uncertified economy-grade daily living aids, with certification tier and after-sales service bundling as primary drivers. Cost compression in the commodity mobility tier is intensifying because Medicare Advantage plans are narrowing reimbursement bands for standard wheelchairs and walkers. Home health agencies exhibit the highest price sensitivity due to staffing shortages limiting capital deployment, whereas direct-to-patient subscribers for orthopedic supports demonstrate lower elasticity given replacement cycle recurrence.
Supply Chain Analysis
Workforce availability constraints in Zhejiang Province and the Yangtze River Delta are constraining lithium-ion cell production for powered mobility systems, while precision engineering clusters in Baden-Württemberg and the Minneapolis corridor face competing demand from automotive and aerospace sectors. Raw material dependencies center on Chinese lithium carbonate, South Korean electrolyte formulations, and German precision servo motors. Single-source vulnerability in Zhejiang's cathode material production exposes margins to export control friction. Distribution runs through Medicare-accredited durable medical equipment dealers for reimbursed products, with direct-to-patient digital platforms capturing growing share in cash-pay orthopedic supports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home rehabilitation products market reads as supply-constrained, with FDA 510(k) clearance timelines averaging one hundred eighty days propping pricing power for early-certification holders against delayed rival entry.
For Market Incumbents: Hedge against reimbursement compression by deepening backward integration into sensor module fabrication and securing captive lithium-ion supply agreements with South Korean cell manufacturers. Channel control through exclusive hospital discharge planner contracts protects against direct-to-patient subscription disintermediation. Priority investment in ISO 13485 quality system harmonization preserves single-registration market access across North American and European channels.
For New Entrants and Emerging Players: The mid-tier price-point gap between Ekso Bionics premium exoskeletons and commodity continuous passive motion units offers white-space capture opportunity in connected neuromuscular electrical stimulation systems. Post-surgical care applications for anterior cruciate ligament reconstruction patients represent the most penetrable segment given CMS Remote Therapeutic Monitoring code activation. Go-to-market execution through digital prescription platforms bypasses entrenched durable medical equipment dealer networks.
For Investors and Strategic Acquirers: The window for entry favors therapeutic device specialists with FDA-cleared software-as-a-medical-device components and established Medicare billing codes. Long-term viability over the next decade rests on reimbursement pathway durability rather than hardware innovation cycles alone. The signal to watch is CMS national coverage determination expansion for remote therapeutic monitoring beyond current neuromuscular electrical stimulation and continuous passive motion categories.
| Strategic Initiative | Industry Significance |
|---|---|
| CMS Reimbursement Strategy | Securing RTM code coverage for connected devices unlocks Medicare Advantage plan access. |
| FDA 510(k) Submission Acceleration | Early clearance for stroke rehabilitation exoskeletons builds competitive moats against European rivals. |
| Hospital System Partnership | Exclusive discharge planning contracts bundle mobility aids with therapeutic devices. |
| Software Companion Development | HL7 FHIR-compliant data streams enable integration with hospital EHR systems. |
| CE Marking Pathway Investment | EU MDR notified body certification creates barriers for delayed rival market entry. |
Research Approach
Multi-period observation of FDA 510(k) clearance timelines, CMS national coverage determinations, and ISO 13485 registration volumes anchored the trend analysis, supplemented by interviews with hospital discharge planners, biomedical engineers at therapeutic device manufacturers, Medicare reimbursement specialists, and durable medical equipment procurement managers. Secondary validation drew from FDA 510(k) database filings, CMS Medicare claims data, hospital procurement contract registries, and EU MDR notified body certification records. Bottom-up unit shipment estimates across mobility aids, therapeutic devices, orthopedic supports, respiratory equipment, and daily living aids were triangulated against top-down spending flows from Medicare and Medicare Advantage programs.
Input-output matrices mapped product category demand to raw material inputs including lithium-ion cells, biocompatible polymers, precision servo motors, and sensor arrays across the projection horizon. Segmentation dimensions encompassed product type, application, end user, and distribution channel, with additional modeling of reimbursement pathway eligibility tiers. CAGRs were derived from regression analysis against demographic drivers, reimbursement policy shifts, and regulatory timeline trajectories. Industry-specific forecast inputs included FDA review queue depth, EU MDR notified body capacity constraints, and home health agency staffing ratios.
Inputs from FDA clearance databases and CMS reimbursement bulletins were available through the study window; gaps in real-time home health agency staffing data introduce uncertainty bands around therapeutic device utilization rate assumptions. Forecasts reflect documented regulatory timeline trajectories and reimbursement policy assumptions. Material deviation in FDA 510(k) review staffing levels, lithium-ion export control enforcement, or CMS RTM code expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
US Physical Therapy Services Market
Rehabilitation Services
Global Women Health Rehabilitation Products Market
Rehabilitation Services
Exoskeleton and Rehabilitation Robot Safety and Performance Test Equipment Market
Rehabilitation Services
US Assisted Living Facility and Neurorehabilitation Market
Rehabilitation Services
Global Neurorehabilitation Devices Market
Rehabilitation Services
United States Behavioral Rehabilitation Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
Massage Therapy Services Market
Rehabilitation Services
Speech Therapy Services Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
Telerehabilitation Systems Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Speech Pathology Services Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market
Rehabilitation Services
Global Robotic Rehabilitation and Assistive Technologies Market