
 Telerehabilitation Systems Market | 2026-2036
Telerehabilitation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Telerehabilitation Systems Market Outlook
The capital-intensity gap between hardware-integrated and software-only providers is collapsing as sensor costs plummet and cloud infrastructure commoditizes. Hinge Health leverages its full-stack model combining wearable sensors with clinical coaching to sustain premium pricing. Koninklijke Philips N.V. anchors its position through enterprise hospital contracts that bundle telerehabilitation into broader patient monitoring ecosystems.
Telerehabilitation systems encompass software platforms, connected hardware, and wearable sensors that enable remote delivery of physical, occupational, and cognitive therapy through real-time video, motion tracking, and AI-guided exercise correction. These systems transmit kinematic data from inertial measurement units and depth cameras to therapists who adjust protocols without in-person visits. Software and AI-powered platforms currently capture the deepest margin pools due to recurring subscription economics and lower fulfillment costs. Hardware and wearable devices represent the fastest-growing revenue segment as home-based rehabilitation programs expand beyond post-surgical recovery into chronic condition management.
The FDA regulates these systems as Class II medical devices under 21 CFR 890, while HIPAA mandates encryption standards for all patient-generated kinematic data transmitted through commercial networks. The Centers for Medicare & Medicaid Services shapes demand directly through reimbursement codes for remote therapeutic monitoring, which determine whether health systems purchase these platforms or defer adoption. Stakeholders must monitor how FDA cybersecurity guidance evolves for connected rehabilitation devices, as compliance costs could reshape competitive economics between integrated and modular platform architectures.
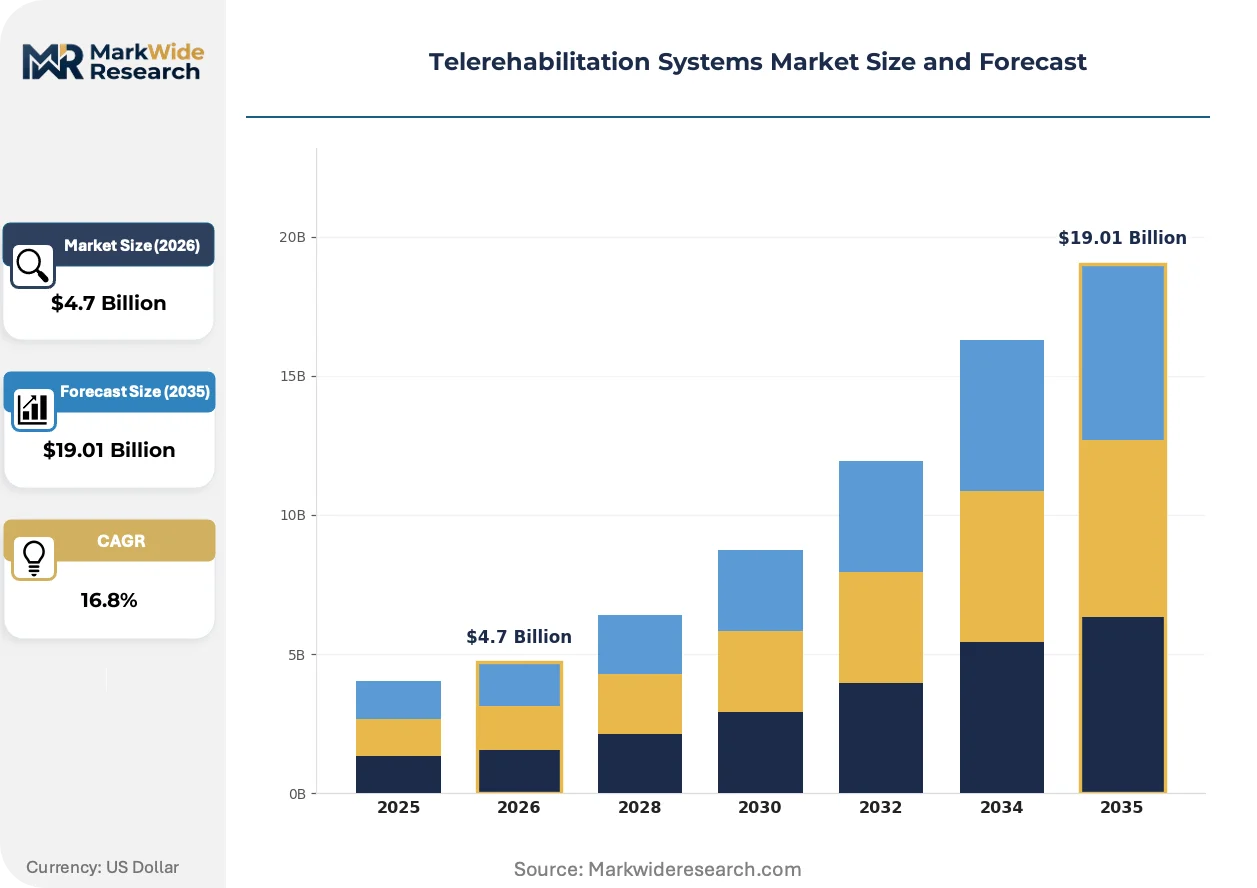
Market Dynamics
The FDA's cybersecurity enforcement for connected rehabilitation devices is compressing vendor economics and forcing platform architecture decisions that favor integrated hardware-software stacks over modular alternatives.
Growth Catalysts
- CMS Reimbursement Expansion:Remote therapeutic monitoring codes now cover kinematic data transmission from home-based sensors, pulling health systems into procurement cycles.
- Post-acute Care Protocol Integration:Discharge planners at skilled nursing facilities embed telerehabilitation into standard care pathways, creating institutional demand pull.
- Sensor Cost Collapse:Inertial measurement units and depth cameras have fallen below price thresholds that enable consumer-grade hardware to meet clinical accuracy standards.
Market Restraints
- HIPAA Encryption Burden:Patient-generated kinematic data requires end-to-end encryption across commercial networks, adding infrastructure costs that software-only vendors struggle to absorb.
- Cloud Infrastructure Concentration:Three hyperscale providers dominate hosting for real-time video and motion analytics, creating vendor lock-in risk for mid-size platform operators.
- Physical Therapy Substitution:Low-intensity wellness apps and unconnected home exercise equipment capture price-sensitive segments that might otherwise adopt clinical-grade systems.
Strategic Opportunities
- Chronic Condition Expansion:Parkinson's disease and multiple sclerosis programs remain underpenetrated relative to orthopedic recovery, offering volume growth outside saturated post-surgical segments.
- Occupational Therapy Convergence:Hand-tracking cameras and haptic gloves are merging remote physical rehabilitation with cognitive retraining for stroke patients.
- Enterprise Hospital Bundling:Patient monitoring ecosystem vendors can attach telerehabilitation modules to existing enterprise contracts without standalone sales cycles.
Industry Challenges
- Clinical Validation Timelines:Randomized controlled trials for AI-guided exercise correction require 18-24 month completion windows, delaying regulatory submissions.
- Therapist Workflow Integration:Remote platforms must embed into existing electronic health record systems, creating implementation friction that slows hospital adoption.
- Interoperability Certification:Multiple competing standards for kinematic data formats force vendors to maintain parallel integration layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telerehabilitation Systems Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Wearable Devices, Sensors End User: Patients, Healthcare Providers, Therapists, Rehabilitation Centers Technology: Video Conferencing, Mobile Applications, Virtual Reality, AI-Powered Platforms Delivery Mode: Remote Consultation, Self-Managed Programs, Real-Time Monitoring, Customized Plans |
| Companies Covered | Hinge Health, Koninklijke Philips N.V., American Well, MIRA Rehab Limited, SWORD Health, MindMaze, Tyromotion GmbH, Reflexion Health, Inc., Neuro Rehab VR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telerehabilitation Systems Market Strategic Shifts
Real-time motion capture and AI feedback loops are dissolving the boundary between clinic-grade and home-grade rehabilitation hardware, redistributing value toward software platforms that orchestrate distributed care teams.
Depth camera arrays paired with edge-computing processors are fragmenting the historical monopoly of marker-based motion capture systems in clinical settings. Outpatient physical therapy chains now deploy sub-$500 camera rigs that match the kinematic precision of $50,000 laboratory equipment. This price collapse is fragmenting vendor tiers, compressing margins for premium hardware manufacturers while expanding addressable volume for software platforms that normalize data across heterogeneous sensor inputs.
The FDA's 2023 cybersecurity guidance for Class II medical devices mandates pre-market submission of software bills of materials and vulnerability management protocols. Device manufacturers must now document third-party component provenance and maintain patch pipelines across multi-year deployment horizons. Rehabilitation platforms with integrated hardware stacks absorb these compliance costs more efficiently than modular vendors assembling third-party sensors, tilting competitive economics toward full-stack architectures in the United States market.
Health system procurement teams now unbundle after-sales clinical support from platform licensing, contracting separately for therapist training and protocol customization. This purchasing pattern shift squeezes vendors who bundled services into subscription pricing, forcing transparent cost separation between software access and professional services. The unbundling is most visible in United States hospital networks where value-analysis committees scrutinize recurring charges against measurable patient throughput gains.
Telerehabilitation Systems Market Segmentation
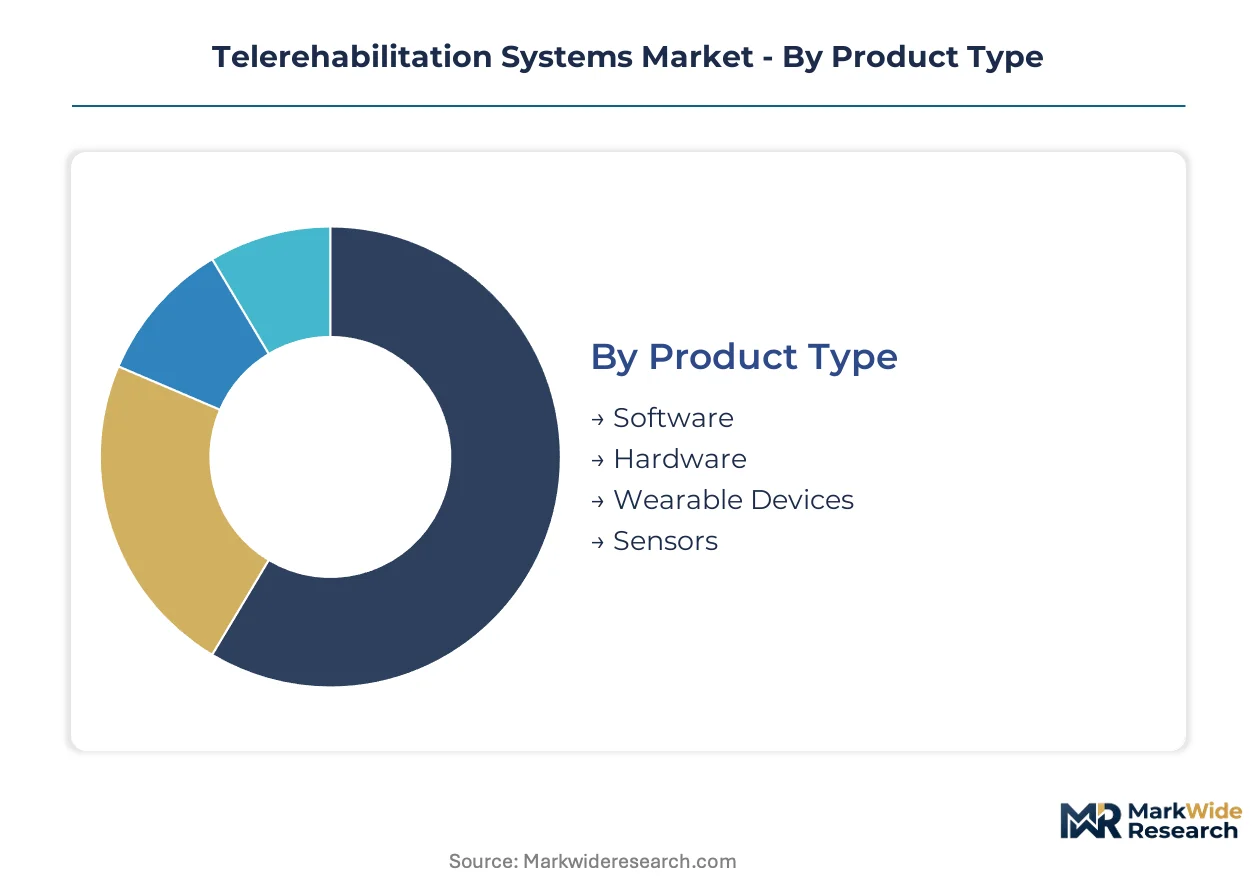
Telerehabilitation systems fragment across four intersecting dimensions that determine procurement economics. Product architecture choices separate capital-intensive hardware deployments from recurring software subscriptions, while end-user targeting shapes regulatory pathways and reimbursement eligibility.
Product Type:
Margin pools concentrate in software platforms that capture recurring subscription revenue with minimal incremental fulfillment cost.
- Software:Cloud-native platforms orchestrate therapist workflows, patient scheduling, and protocol libraries through web interfaces. Health systems in the United States prioritize these solutions for their integration with Epic and Cerner electronic health records, though HIPAA encryption requirements add infrastructure overhead that smaller vendors struggle to absorb.
- Hardware:Dedicated rehabilitation stations combine touchscreen displays with adjustable mounting systems for clinic deployment. Skilled nursing facilities embed these units into discharge protocols, creating institutional demand pull that sustains premium pricing despite longer sales cycles.
- Wearable Devices:Consumer-grade motion trackers now meet clinical accuracy thresholds for home-based programs.
- Sensors:Inertial measurement units and depth cameras transmit kinematic data to remote therapists.
The dominant share belongs to Software, while Wearable Devices is closing the gap fastest.
End User:
Volume concentration sits with institutional purchasers who command enterprise pricing and bundled service contracts.
- Patients:Direct-to-consumer adoption concentrates among Medicare beneficiaries eligible for remote therapeutic monitoring reimbursement. These users prioritize intuitive interfaces and minimal setup friction, driving platform designers toward smartphone-native experiences rather than dedicated hardware.
- Healthcare Providers:Hospital networks and accountable care organizations procure telerehabilitation as population health infrastructure. Their purchasing committees demand interoperability with existing patient monitoring ecosystems, favoring vendors with established enterprise relationships.
- Therapists:Licensed physical and occupational therapists use platforms to manage caseloads across dispersed geographies.
- Rehabilitation Centers:Outpatient chains deploy systems to extend reach into rural catchment areas.
Healthcare Providers command the largest procurement volume, though Patients are expanding most quickly as direct reimbursement pathways mature.
Technology:
Application maturity varies sharply, with established modalities competing against experimental interfaces for clinical validation.
- Video Conferencing:Synchronous two-way video remains the backbone of remote therapeutic relationships, requiring sub-150ms latency for real-time movement coaching. Platform vendors differentiate through integrated recording, annotation tools, and automated session documentation that feeds directly into clinical notes.
- AI-Powered Platforms:Machine learning models analyze motion capture data to flag form deviations and auto-adjust exercise difficulty. FDA 510(k) clearance timelines for these algorithms stretch 18-24 months, creating competitive moats for first movers with validated submissions.
- Mobile Applications:Native iOS and Android clients enable asynchronous program adherence tracking.
- Virtual Reality:Immersive environments for stroke rehabilitation and cognitive retraining remain in pilot deployment.
Video Conferencing anchors current utilization, while AI-Powered Platforms are gaining share fastest as validation studies complete.
Delivery Mode:
Customer type stratification separates clinically supervised interventions from self-directed wellness adjacent to regulated healthcare.
- Remote Consultation:Synchronous therapist-patient sessions replicate in-person evaluation through video and motion tracking. Medicare reimbursement codes specifically cover these encounters, pulling health systems into procurement cycles that bypass capital budget constraints.
- Real-Time Monitoring:Continuous kinematic transmission from home-based sensors enables asynchronous therapist oversight with intervention triggers. This model expands chronic condition management beyond post-surgical recovery, though data infrastructure costs challenge standalone software vendors.
- Self-Managed Programs:Pre-recorded exercise libraries with automated progression logic serve price-sensitive segments.
- Customized Plans:Protocol personalization engines adapt interventions to individual patient trajectories.
Remote Consultation holds established reimbursement advantage, while Real-Time Monitoring shows the steepest expansion trajectory as sensor costs collapse.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States driving institutional procurement through Medicare reimbursement while European markets prioritize GDPR-compliant home-based deployments and Asian healthcare systems favor hospital-integrated enterprise models.
United States
Hospital networks and accountable care organizations dominate procurement volume, embedding telerehabilitation into post-acute discharge protocols. The FDA's 2023 cybersecurity guidance for Class II medical devices mandates software bills of materials and vulnerability management protocols, compressing vendor economics toward integrated hardware-software stacks. The Boston-Cambridge corridor anchors innovation clusters where academic medical centers pilot AI-guided exercise correction platforms.
Germany
Rehabilitation clinics and statutory health insurers drive demand for CE-marked platforms that integrate with existing electronic health record infrastructure. The EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for software-as-a-medical-device, extending validation timelines for AI-powered motion analysis tools. The Baden-Württemberg region concentrates medical technology manufacturing, with Stuttgart-area firms supplying sensor hardware to platform vendors.
China
Tier-1 hospitals in Beijing and Shanghai deploy enterprise telerehabilitation systems for stroke rehabilitation and orthopedic recovery, while provincial health commissions pilot rural access programs. The National Medical Products Administration (NMPA) regulates connected rehabilitation devices under Class II medical device pathways, with cybersecurity standards tightening for data transmission across commercial networks. The Yangtze River Delta manufacturing base produces consumer-grade motion sensors that increasingly meet clinical accuracy thresholds.
Japan
Aging demographics and workforce shortages accelerate adoption of remote monitoring for chronic neurological conditions. The Ministry of Economy, Trade and Industry (METI) promotes digital health infrastructure through regulatory sandboxes that compress approval timelines for AI-powered rehabilitation software. The Kansai region around Osaka hosts medical device clusters where traditional rehabilitation equipment manufacturers pivot toward connected platform architectures.
United Kingdom
NHS Integrated Care Systems procure telerehabilitation as population health infrastructure, prioritizing interoperability with existing patient monitoring ecosystems. The Medicines and Healthcare products Regulatory Agency (MHRA) aligns post-Brexit device regulations with EU MDR frameworks while maintaining distinct UKCA marking requirements. London-based health technology assessment bodies evaluate cost-effectiveness evidence that determines platform reimbursement eligibility.
Telerehabilitation Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with full-stack vendors combining wearable sensors and clinical coaching commanding premium pricing against modular software-only alternatives. Market structure reflects a bifurcation between enterprise hospital contracts and direct-to-consumer reimbursement pathways. Three strategic archetypes dominate: integrated hardware-software platforms, cloud-native software specialists, and rehabilitation equipment incumbents pivoting to connected services. Competitive dynamics center on M&A activity consolidating sensor technology capabilities and strategic partnerships embedding platforms into broader patient monitoring ecosystems.
Among integrated platform providers, Hinge Health and Koninklijke Philips N.V. exemplify contrasting approaches to market positioning—Hinge Health representing the full-stack model combining wearable hardware with clinical services, while Philips anchors enterprise relationships through hospital system contracts that bundle telerehabilitation into broader patient monitoring portfolios. Tyromotion GmbH occupies a position within the European specialist tier, reflecting rehabilitation equipment manufacturing heritage adapted for connected platform delivery.
| Leading Market Players |
|---|
| Hinge Health |
| Koninklijke Philips N.V. |
| American Well |
| MIRA Rehab Limited |
| SWORD Health |
| MindMaze |
| Tyromotion GmbH |
| Reflexion Health, Inc. |
| Neuro Rehab VR |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure commoditization at the hyperscale tier has collapsed fixed-cost barriers for software-native entrants, compressing price floors for telerehabilitation platforms while concentrating supply leverage among sensor manufacturers with captive foundry relationships. This scale dynamic rewards integrated hardware-software vendors who internalize motion-capture component sourcing against modular competitors exposed to spot-market volatility.
Pricing Analysis
After-sales clinical support contracts now drive lifetime value as health system procurement teams unbundle professional services from platform licensing. Three-tier pricing structure across premium, standard, and economy levels separates enterprise hospital bundles with embedded therapist training from direct-to-consumer subscriptions with minimal setup assistance. Pricing pressure stems from sensor cost collapse enabling consumer-grade hardware to meet clinical accuracy thresholds. Small skilled nursing facilities exhibit highest price sensitivity, while accountable care organizations prioritize measurable patient throughput gains over sticker price.
Supply Chain Analysis
Inventory lead times for inertial measurement units have shortened from twelve weeks to four as Yangtze River Delta foundries expand MEMS fabrication capacity. Component sourcing draws from China for consumer-grade motion sensors, Germany for precision optical assemblies, and Taiwan for edge-computing processors. Single-source vulnerability concentrates in depth camera module supply where one dominant vendor controls time-of-flight chip architecture. Distribution runs through enterprise medical device distributors for hospital contracts and direct-to-consumer logistics for Medicare reimbursement-eligible patients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The telerehabilitation systems market represents a high-growth disruption as FDA cybersecurity mandates for Class II medical devices force architectural consolidation toward integrated hardware-software stacks.
For Market Incumbents: Secure enterprise hospital contract renewals by embedding telerehabilitation modules into existing patient monitoring ecosystems before modular software vendors achieve HIPAA-compliant encryption parity. Invest in captive sensor manufacturing partnerships to absorb FDA software bill of materials requirements more efficiently than competitors dependent on third-party component provenance. For New Entrants and Emerging Players: Anchor in chronic neurological condition management for Parkinson's disease and multiple sclerosis, segments that remain underpenetrated relative to saturated orthopedic recovery markets. Pursue direct-to-consumer reimbursement pathways for Medicare beneficiaries eligible for remote therapeutic monitoring codes, leveraging smartphone-native interfaces to minimize setup friction against incumbent hardware-heavy approaches. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors full-stack platforms combining wearable hardware with clinical coaching services over pure-software alternatives facing margin compression from cloud infrastructure commoditization. Target acquisition candidates with validated FDA 510(k) submissions for AI-guided exercise correction algorithms, as eighteen-to-twenty-four month regulatory timelines create durable competitive moats. Monitor CMS reimbursement code expansion for real-time kinematic monitoring as the critical demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Compliance | Software bill of materials documentation satisfies Class II device pre-market submission requirements under 21 CFR 890. |
| Hospital System Partnership | Epic and Cerner EHR integration embeds platforms into existing clinical workflows without standalone implementation friction. |
| Reimbursement Strategy | Remote therapeutic monitoring code coverage pulls health systems into procurement cycles bypassing capital budget constraints. |
| Sensor Hardware Integration | In-house motion-capture component sourcing absorbs FDA vulnerability management costs more efficiently than modular assembly. |
| AI Algorithm Validation | Randomized controlled trial completion enables 510(k) clearance for machine learning exercise correction tools. |
Study Parameters
A standing panel of physical therapy directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview rounds. Secondary validation drew from CMS Medicare reimbursement databases, FDA 510(k) submission records, hospital procurement contract filings, and connected medical device cybersecurity guidance documents. Bottom-up segment sizing triangulated against top-down macro health expenditure trends.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The forecast framework modeled deployment architecture, end-user institution size, therapeutic application area, integration complexity tier, and regional regulatory cluster as segmentation dimensions. CAGRs derived from fitted growth curves applied to sensor cost decline trajectories and reimbursement code expansion schedules.
Decision-makers should treat outputs as directional under sustained CMS reimbursement support and FDA cybersecurity enforcement continuity; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rehabilitation Services
Rehabilitation Therapy Services Market
Rehabilitation Services
Exoskeleton and Rehabilitation Robot Safety and Performance Test Equipment Market
Rehabilitation Services
Global Medical Rehabilitation Services Market
Rehabilitation Services
Rehabilitation Robots Market
Rehabilitation Services
Outpatient Rehabilitation Services Market
Rehabilitation Services
Behavioral Rehabilitation Market
Rehabilitation Services
Lower Extremity Rehabilitation Robotics Market
Rehabilitation Services
Brachial Plexus Injury Market
Rehabilitation Services
Speech Therapy Services Market
Rehabilitation Services
US Speech Therapy Market
Rehabilitation Services
Massage Therapy Services Market
Rehabilitation Services
Veterinary Rehabilitation Services Market
Rehabilitation Services
Rehabilitation Equipment Market
Rehabilitation Services
Motion Stimulation Therapy Market
Rehabilitation Services
Global Gait Trainer Market
Rehabilitation Services
United States Outpatient Rehabilitation Centers Market