
 Scabies Treatment Market | 2026-2036
Scabies Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Scabies Treatment Market Outlook
The scabies treatment landscape is restructuring around a sharp split between premium prescription formulations and mass-market permethrin commodities. Perrigo Company plc leverages its private-label manufacturing scale to dominate retail pharmacy shelves across North America. Galderma S.A. differentiates through dermatologist-channel specialization and higher-margin ivermectin portfolios. Teva Pharmaceuticals competes on generic oral therapy access, anchoring hospital procurement contracts in price-sensitive markets.
Scabies treatment encompasses pharmacological and environmental interventions targeting Sarcoptes scabiei infestation, with topical permethrin at five percent concentration remaining the first-line synthetic pyrethroid and oral ivermectin reserved for crusted or resistant cases. The primary purpose is mite eradication and symptom resolution across individual patients, institutional outbreaks, and mass drug administration campaigns. Topical creams occupy the largest revenue pool due to established clinical trust and over-the-counter availability, while oral medications represent the fastest-expanding segment driven by compliance advantages in community-wide treatment programs. Prescription delivery modes capture higher per-unit margins, though online pharmacy channels are displacing traditional retail volumes in post-pandemic purchasing patterns.
The FDA governs topical safety and labeling standards for over-the-counter scabicides, while the EMA's MDR framework imposes stricter clinical evidence requirements on European device-drug combination products. WHO guidelines on neglected tropical diseases shape demand in endemic regions by prioritizing ivermectin mass distribution. Stakeholders must monitor emerging resistance surveillance data and regulatory divergence between prescription and OTC classification thresholds to anticipate portfolio rebalancing requirements.
Market Dynamics
Climate-driven transmission season extension in tropical zones is forcing health systems to expand parasitology service capacity, while FDA's strengthened topical safety guidelines are compressing formulation timelines for over-the-counter permethrin products.
Growth Catalysts
- WHO Neglected Tropical Disease Guidelines:The organization's ivermectin mass distribution priority is creating procurement pull in endemic regions. National deworming campaigns in India are opening new treatment access points through urban slum upgrading programs.
- Oral Therapy Compliance Advantages:Community-wide treatment programs favor single-dose oral medications over multi-application topical regimens. Hospital procurement contracts in price-sensitive markets anchor generic oral therapy access.
- Dermatology Clinic Expansion:Specialized parasitology service lines are proliferating as transmission seasons lengthen. Climate shifts extend diagnostic and treatment windows in previously seasonal markets.
Market Restraints
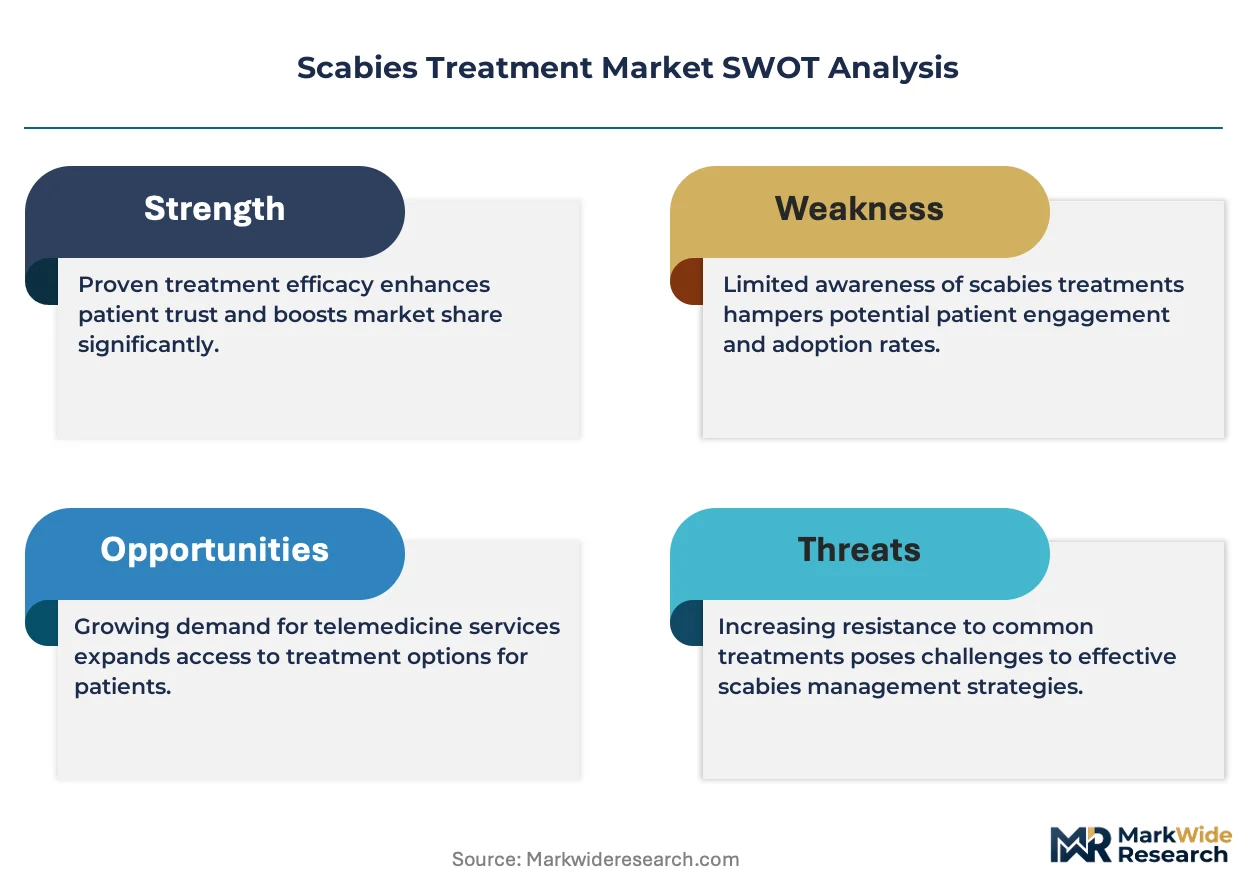
- Synthetic Pyrethroid Resistance Surveillance:Emerging mite resistance data is complicating first-line permethrin efficacy assumptions. Resistance monitoring requirements add regulatory compliance burden to formulation portfolios.
- Supply Concentration in Bulk Actives:Active pharmaceutical ingredient production for ivermectin concentrates in limited manufacturing geographies. Single-source dependencies create vulnerability in mass drug administration supply chains.
- EMA MDR Clinical Evidence Requirements:The European framework imposes stricter evidentiary standards on device-drug combination products. European market entry timelines extend for novel delivery mechanisms.
Strategic Opportunities
- Online Pharmacy Channel Displacement:Post-pandemic purchasing patterns favor direct-to-patient delivery over traditional retail pharmacy volumes. Digital prescription fulfillment captures margin from disintermediated distribution layers.
- Crusted Scabies Hospital Protocols:Institutional outbreak management creates demand for higher-margin prescription formulations. Inpatient settings require combination topical-oral therapy approaches.
- Climate Adaptation Health Funding:Multilateral climate-health financing mechanisms prioritize parasitic disease control in warming zones. Tropical zone health system strengthening programs incorporate scabies treatment infrastructure.
Industry Challenges
- Formulation Chemist Talent Scarcity:Specialized expertise in topical parasiticide stability and skin penetration is concentrated among aging specialist cohorts. Training pipeline gaps threaten R&D throughput for next-generation products.
- OTC-Prescription Classification Divergence:Regulatory thresholds for over-the-counter versus prescription status vary across national jurisdictions. Portfolio rebalancing requires jurisdiction-specific labeling and concentration strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scabies Treatment Market |
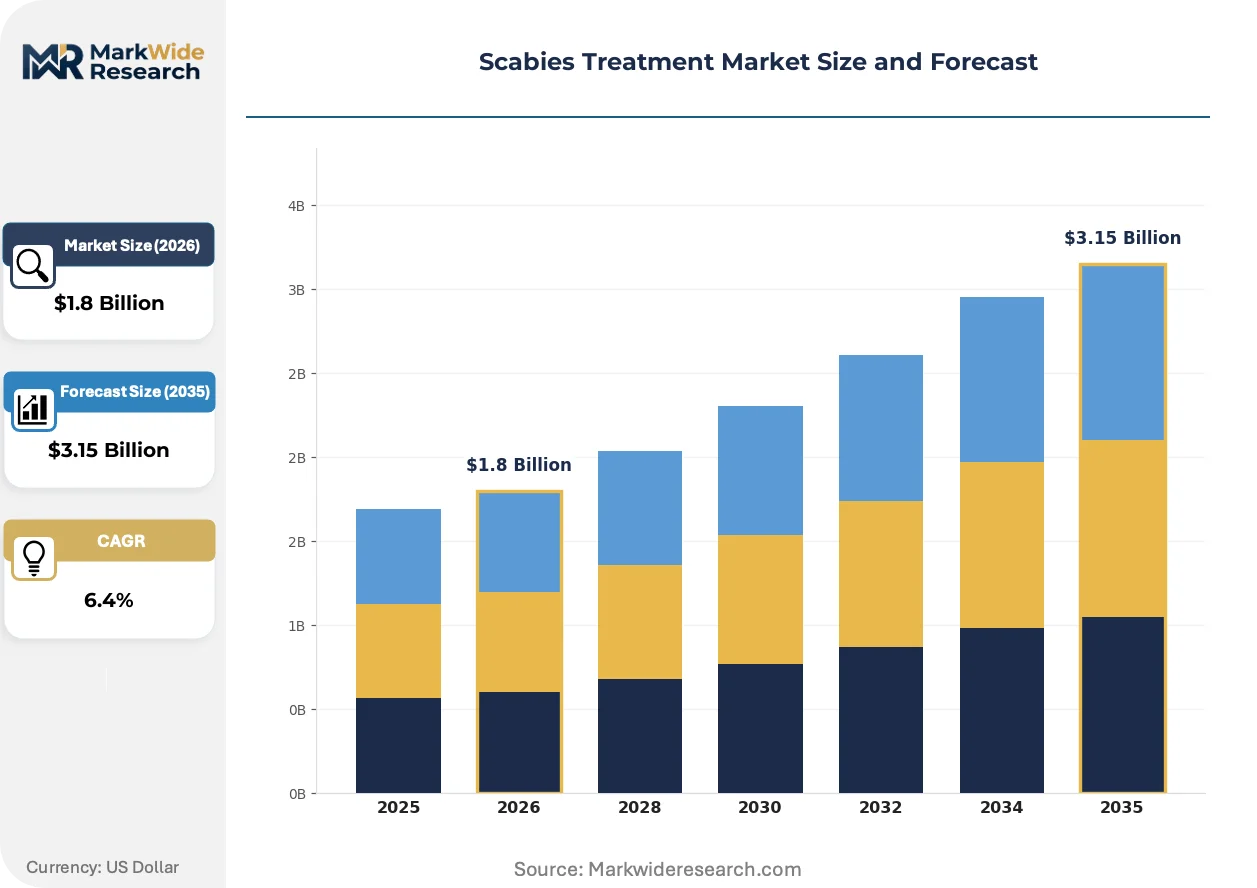
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Creams, Oral Medications, Lotions, Insecticidal Sprays Delivery Mode: Over-the-Counter, Prescription, Hospital Dispensed, Online Pharmacy End User: Hospitals, Clinics, Home Care, Pharmacies Treatment Duration: Single Dose, Multi-Day Treatment, Follow-Up Therapy, Maintenance Therapy |
| Companies Covered | Perrigo Company plc, Abbott, Galderma S.A., Cipher Pharmaceuticals, GlaxoSmithKline plc, Teva Pharmaceuticals, Sun Pharmaceutical, Dr. Reddy's Laboratories Limited, Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scabies Treatment Market Strategic Shifts
Formulation science is converging with digital health infrastructure to reshape how scabies therapies reach patients, while regulatory divergence between markets is fragmenting product development roadmaps.
Microencapsulated permethrin delivery systems are consolidating market preference among dermatology clinics seeking extended-release topical efficacy. Hospital procurement committees favor these formulations for crusted scabies protocols despite premium positioning. The technology is consolidating revenue concentration in prescription channels away from commoditized retail permethrin.
FDA's strengthened labeling requirements for over-the-counter scabicides are compressing formulation development timelines for private-label manufacturers. The agency's safety documentation demands now rival prescription product standards for certain concentration thresholds. North American retail pharmacy chains are responding by consolidating supplier relationships toward vertically integrated manufacturers with regulatory affairs depth.
Direct-to-patient telemedicine prescribing is displacing traditional clinic-based diagnosis and treatment initiation for uncomplicated infestations. Dermatology platforms in India and Southeast Asia bundle remote visual diagnosis with pharmacy fulfillment. This channel shift is most visible in urban slum populations where transportation barriers previously limited treatment completion rates.
Scabies Treatment Market Segmentation
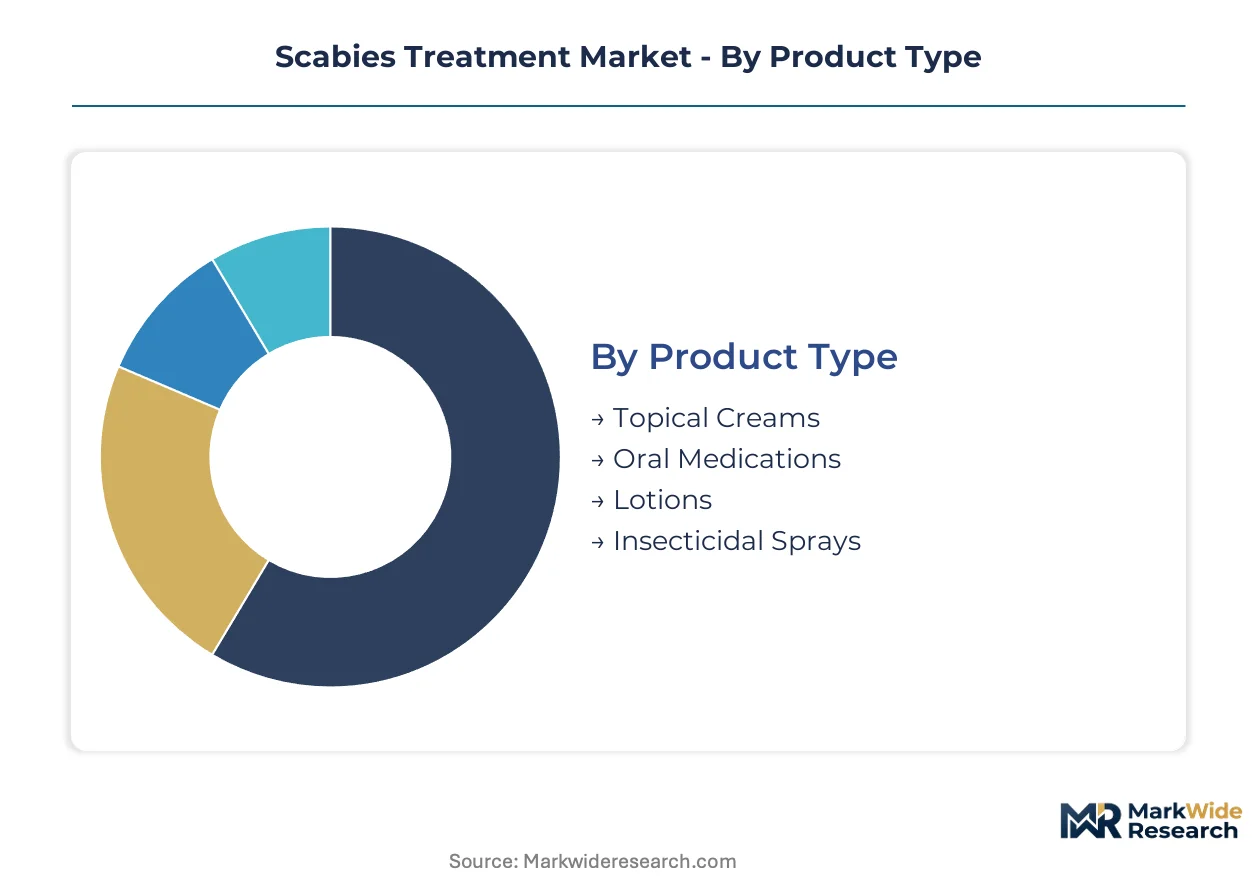
The scabies treatment market fragments across four dimensions that determine regulatory burden, channel economics, and patient compliance profiles. Each segmentation axis carries distinct certification requirements from FDA, EMA, and national regulators that shape manufacturer portfolio strategy.
Product Type:
FDA's strengthened topical safety guidelines and EMA's MDR framework impose tiered evidentiary demands across formulation categories, with prescription-grade products facing clinical trial requirements that OTC commodities bypass.
- Topical Creams:Five percent permethrin formulations remain the first-line synthetic pyrethroid standard. Demand concentrates in dermatology clinics across India and Southeast Asia, where established clinical trust supports premium positioning despite emerging resistance surveillance data.
- Oral Medications:Single-dose ivermectin tablets address crusted scabies and mass drug administration campaigns. Hospital procurement contracts in price-sensitive markets anchor generic access, while WHO neglected tropical disease guidelines drive endemic region demand.
- Lotions:Lower-viscosity alternatives target pediatric and sensitive-skin populations with reduced irritation profiles. These formulations occupy mid-tier pricing between commodity creams and prescription oral therapies.
- Insecticidal Sprays:Environmental decontamination products complement individual treatment protocols. Regulatory classification varies across jurisdictions, with some markets treating these as pesticide products under EPA or equivalent national frameworks.
Leading the category by volume: Topical Creams. Growing fastest: Oral Medications.
Delivery Mode:
Channel economics diverge sharply between prescription-captured margin pools and high-volume OTC commodities, with online pharmacy penetration reshaping traditional retail pharmacy revenue capture.
- Over-the-Counter:Retail pharmacy permethrin products face compressed formulation timelines under FDA's revised labeling standards. North American chains consolidate supplier relationships toward vertically integrated manufacturers with regulatory affairs depth.
- Prescription:Higher-margin formulations require physician diagnosis and carry stricter adverse event reporting obligations. These products generate superior per-unit economics despite lower absolute volume.
- Hospital Dispensed:Institutional outbreak management creates demand for combination topical-oral therapy approaches. Crusted scabies protocols in inpatient settings favor premium microencapsulated delivery systems.
- Online Pharmacy:Post-pandemic purchasing patterns favor direct-to-patient fulfillment. Dermatology platforms in India bundle remote visual diagnosis with pharmacy delivery, capturing margin from disintermediated distribution layers.
Prescription channels command highest per-unit margins. Online Pharmacy demonstrates steepest expansion trajectory.
End User:
Site-of-care determination drives treatment completion rates and regimen selection, with transportation barriers and clinical oversight requirements segmenting patient flows across settings.
- Hospitals:Inpatient settings manage severe crusted presentations and institutional outbreaks. These facilities require combination therapy protocols and maintain formulary committees that anchor procurement contracts.
- Clinics:Dermatology and parasitology service lines proliferate as climate shifts extend transmission seasons. Specialized clinics capture higher-margin prescription volumes through physician-channel relationships.
- Home Care:Self-administered topical regimens dominate uncomplicated infestations. Compliance challenges with multi-application schedules favor single-dose alternatives where available.
- Pharmacies:Retail and community pharmacy networks serve as primary access points for OTC permethrin. Urban slum upgrading programs in India leverage pharmacy infrastructure for treatment distribution.
Clinics generate highest prescription conversion rates. Home Care accounts for largest absolute patient volume.
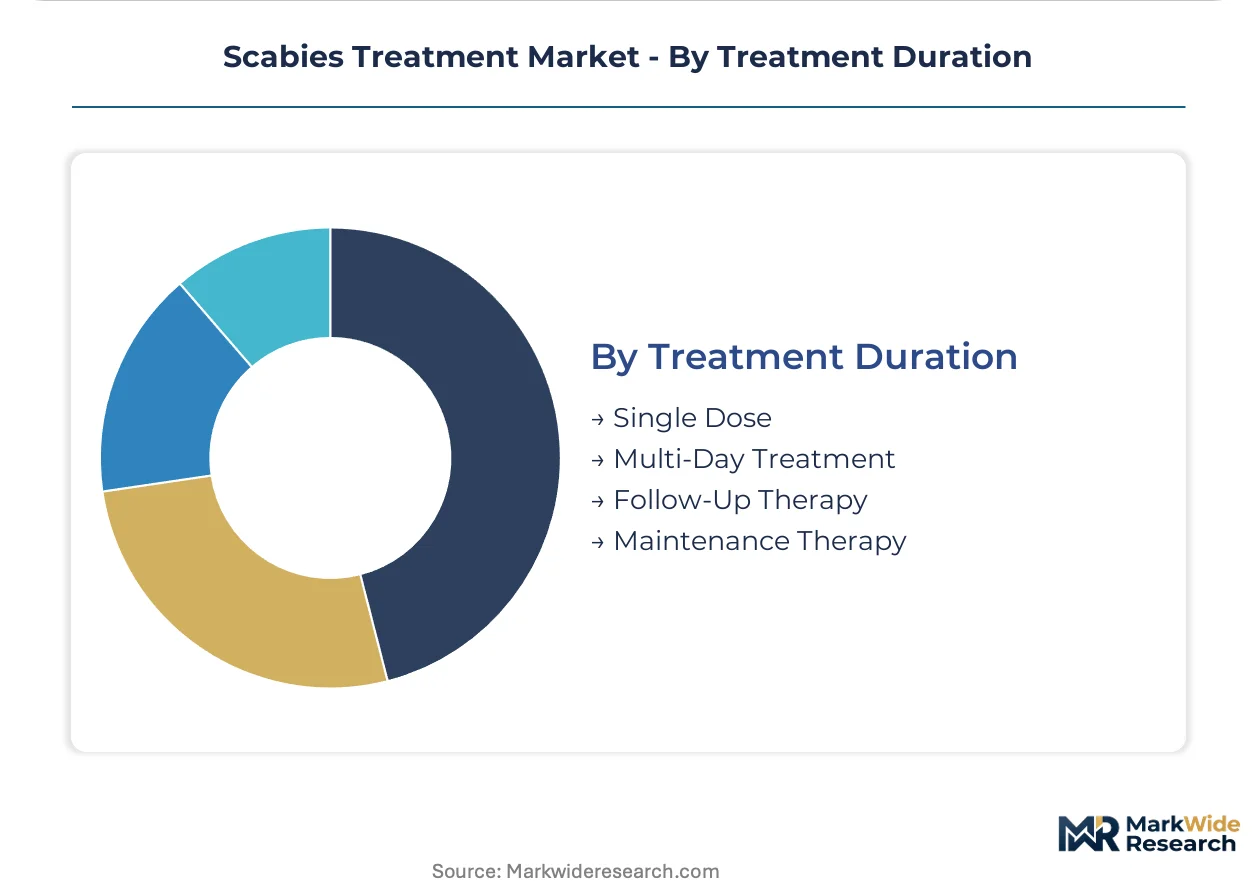
Treatment Duration:
Regimen complexity directly correlates with completion failure rates, driving preference for simplified dosing schedules in community-wide intervention programs.
- Single Dose:Oral ivermectin eliminates multi-application compliance barriers. Mass drug administration campaigns in endemic regions prioritize this approach for population-level impact.
- Multi-Day Treatment:Traditional topical permethrin requires repeat applications. Resistance monitoring requirements add regulatory compliance burden to these established regimens.
- Follow-Up Therapy:Reinforcement dosing addresses treatment failures and reinfestation cycles. These protocols concentrate in institutional outbreak settings with active surveillance.
- Maintenance Therapy:Prophylactic applications target high-transmission environments and immunocompromised populations. Evidence requirements for prophylactic claims vary across regulatory jurisdictions.
Single Dose protocols achieve highest completion rates. Follow-Up Therapy commands premium reimbursement in hospital settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors the scabies treatment demand surge through its dense urban slum corridors and national deworming campaign infrastructure. Climate adaptation health funding flows disproportionately toward Maharashtra's parasitology service expansion. The city's dermatology clinic networks process institutional outbreak protocols that shape formulation standards across South Asia.
United States
FDA's strengthened topical safety guidelines compress over-the-counter permethrin formulation timelines. Retail pharmacy chains consolidate supplier relationships toward vertically integrated manufacturers with regulatory affairs depth. Greater Boston's dermatology research clusters pioneer microencapsulated delivery systems for crusted scabies hospital protocols.
India
Urban slum upgrading programs and national deworming campaigns create new treatment access points through pharmacy infrastructure. CDSCO oversees generic oral therapy approvals that anchor hospital procurement contracts in price-sensitive markets. Telangana's Hyderabad corridor concentrates bulk active pharmaceutical ingredient production for ivermectin mass distribution.
Germany
EMA's MDR framework imposes stricter clinical evidence requirements on device-drug combination products entering European markets. Hospital formulary committees favor premium prescription formulations for institutional outbreak management. North Rhine-Westphalia's pharmaceutical manufacturing belt supplies microencapsulated permethrin systems to dermatology clinics across the continent.
Brazil
ANVISA regulates topical parasiticide classifications that determine prescription versus over-the-counter availability thresholds. Climate-driven transmission season extension forces health systems to expand parasitology service capacity year-round. São Paulo's public health laboratories coordinate resistance surveillance data collection that informs regional treatment guidelines.
United Kingdom
NHS procurement frameworks prioritize single-dose oral therapies for community-wide treatment program compliance advantages. MHRA adverse event reporting obligations shape post-market surveillance for prescription-grade products. London's hospital networks pilot telemedicine prescribing platforms that bundle remote diagnosis with pharmacy fulfillment.
Scabies Treatment Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the scabies treatment landscape. Vertically integrated pharmaceutical conglomerates control bulk active ingredient supply chains and regulatory submission infrastructure. Three strategic archetypes dominate: private-label manufacturers capturing retail pharmacy shelf space, dermatologist-channel specialists commanding premium prescription margins, and generic oral therapy suppliers anchoring hospital procurement contracts. Dominant competitive moves include backward integration into active pharmaceutical ingredient production and geographic expansion through telemedicine platform partnerships.
Among Ireland-based healthcare conglomerates, Perrigo Company plc exemplifies the private-label manufacturing archetype through its North American retail pharmacy dominance. Swiss dermatology specialists represented by Galderma S.A. occupy the premium prescription channel position. Israeli generic powerhouses such as Teva Pharmaceuticals anchor hospital procurement contracts in price-sensitive markets through oral therapy access programs.
| Leading Market Players |
|---|
| Perrigo Company plc |
| Abbott |
| Galderma S.A. |
| Cipher Pharmaceuticals |
| GlaxoSmithKline plc |
| Teva Pharmaceuticals |
| Sun Pharmaceutical |
| Dr. Reddy's Laboratories Limited |
| Mylan N.V. |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees' preference for single-dose oral therapies over multi-application topical regimens is compressing margins on commodity permethrin formulations while elevating ivermectin price premiums. This demand shift forces bulk active pharmaceutical ingredient suppliers to rebalance capacity toward oral therapy production, tightening supply availability for traditional topical manufacturers and amplifying price stratification between prescription and over-the-counter channels.
Pricing Analysis
Outcome-based pricing anchored to treatment completion rates separates premium single-dose oral therapies from economy-tier topical commodities. Price differentiation rests on FDA certification tier and volume procurement scale, with hospital formulary contracts commanding steepest discounts. Cost compression in retail permethrin intensifies because of private-label manufacturer consolidation. Community pharmacy buyers exhibit highest price sensitivity; institutional procurement managers prioritize compliance outcomes over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from WHO mass drug administration programs mandate multi-supplier qualification for ivermectin bulk actives, dispersing production across India, China, and the United States. Raw material dependencies center on avermectin fermentation feedstocks, pyrethroid precursors, and microencapsulation polymers. Single-source vulnerability concentrates in Hyderabad's API corridor, where flood or regulatory action would disrupt endemic region distribution. Distribution runs through national pharmacy networks and direct-to-patient telemedicine platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scabies treatment market consolidation accelerates as FDA's strengthened topical safety guidelines force smaller private-label manufacturers toward regulatory compliance investments they cannot sustain. Weaker players face exit pressure from vertically integrated competitors with captive regulatory affairs capabilities.
For Market Incumbents: Anticipate resistance surveillance data eroding permethrin efficacy claims by diversifying into microencapsulated delivery systems and oral therapy portfolios. Backward integration into ivermectin API production secures supply continuity for mass drug administration contracts. Channel control through telemedicine platform partnerships defends margin capture against retail pharmacy disintermediation. For New Entrants and Emerging Players: Capture underserved crusted scabies hospital protocols where combination therapy approaches command premium positioning. The most penetrable white space sits in climate adaptation health funding flows toward tropical zone parasitology service expansion. A direct-to-patient telemedicine bundling strategy bypasses entrenched retail pharmacy distribution barriers. For Investors and Strategic Acquirers: The window for entry favors generic oral therapy suppliers with established CDSCO or FDA regulatory dossiers and hospital procurement anchoring. Long-term viability hinges on mass drug administration campaign exposure and climate-health financing eligibility. Watch for ivermectin resistance surveillance data as the inflection indicator that would trigger portfolio rebalancing toward novel mechanism candidates.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | Broadens market access across FDA, EMA, and CDSCO jurisdictions for oral therapies. |
| Telemedicine Platform Partnership | Captures margin from disintermediated pharmacy distribution in urban slum corridors. |
| API Manufacturing Scale-Up | Reduces single-source vulnerability in ivermectin supply chains for WHO campaigns. |
| Microencapsulation Technology Licensing | Addresses emerging pyrethroid resistance through extended-release topical efficacy. |
| Climate-Health Funding Alignment | Positions products for multilateral financing mechanisms in warming tropical zones. |
Study Parameters
FDA filings, WHO neglected tropical disease guidelines, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with customs data on ivermectin API trade flows. Primary interviews with dermatology clinic directors, hospital formulary managers, CDSCO regulatory leads, and generic pharmaceutical procurement officers validated demand assumptions. Bottom-up patient volume estimates and top-down health expenditure allocations were triangulated across the analysis window.
Historical trendline analysis of treatment completion rates and resistance surveillance data informed the analytical framework across product type, delivery mode, end user, and treatment duration segmentation. CAGRs were derived from epidemiological modeling of climate-driven transmission season extension and health system capacity expansion. Forecast inputs incorporated WHO mass drug administration campaign schedules and national deworming program procurement volumes.
The model holds under stable regulatory classification thresholds and continued ivermectin efficacy; deviation in pyrethroid resistance prevalence or FDA OTC labeling requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
Spinal Cord Compression Market
Medical Treatment
Peanut Allergy Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Asthma Treatment Market
Medical Treatment
Meningococcal Meningitis Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Seropositive Rheumatoid Arthritis Treatment Market
Medical Treatment
Mercury Poisoning Treatment Market
Medical Treatment
Otoplasty Market
Medical Treatment
Porphyria Treatment Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Migraine Treatment Market