
 Nose Reconstruction Market | 2026-2036
Nose Reconstruction Market Size, Share, and Industry Trends Forecast 2026-2036
Nose Reconstruction Market Analysis
3D-printed patient-specific implants and computer-assisted surgical planning is tilting operative workflows toward pre-procedural customization. Stryker Corporation leverages its orthopedic digital surgery platform to extend planning tools into craniomaxillofacial applications. Johnson & Johnson anchors its position through broad suture and mesh portfolios that support graft fixation in complex reconstructions. Abbvie Inc. competes via its Allergan Aesthetics arm, which sustains channel access to plastic surgeons through combined filler and implant offerings.
Nose reconstruction encompasses surgical restoration of nasal form and function following trauma, oncologic resection, congenital deformity, or prior failed surgery, typically employing autologous cartilage grafts harvested from septum, ear, or rib, synthetic alloplasts such as porous polyethylene, or resorbable biologic scaffolds engineered to support tissue ingrowth and mechanical integrity. Open rhinoplasty retains dominance in revision and reconstructive cases where structural grafting demands full exposure, while non-surgical rhinoplasty using hyaluronic acid fillers captures fastest growth among younger patients seeking temporary dorsal augmentation without operative recovery. Biologics represents the smallest material segment but carries concentrated margin pools as hospitals negotiate premium pricing for decellularized matrices that reduce donor-site morbidity.
FDA 510(k) clearance pathways govern implantable alloplasts in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for permanent nasal implants sold in Europe. Health Canada and Australia's TGA align with ISO 10993 biocompatibility standards but maintain independent adverse event reporting systems that manufacturers must monitor for market access continuity. Stakeholders must weigh regulatory capital requirements against the pricing power of differentiated biologic graft platforms as reimbursement frameworks tighten across major markets.
Market Dynamics
The nose reconstruction market is restructuring around pre-surgical digital workflows that compress operative time and reduce revision rates. Computer-assisted planning is virtualizing graft templating, forcing manufacturers to bundle hardware with software subscriptions or lose procurement cycles to integrated platform vendors.
Growth Catalysts
- MFDS fast-track designation:South Korea's medical device regulator accelerates approval timelines for patient-matched implants, drawing manufacturers to establish local validation facilities.
- Autologous cartilage harvesting:Refinement of rib graft techniques through endoscopic approaches reduces donor-site morbidity and expands candidacy for complex reconstructions.
- Medical tourism clusters:Seoul's Gangnam district concentrates specialist density and post-operative care infrastructure, attracting international patients for revision rhinoplasty.
Market Restraints
- Silicone supply concentration:Medical-grade silicone production clusters in Northeast Asian chemical corridors, exposing implant manufacturers to input volatility and tariff friction.
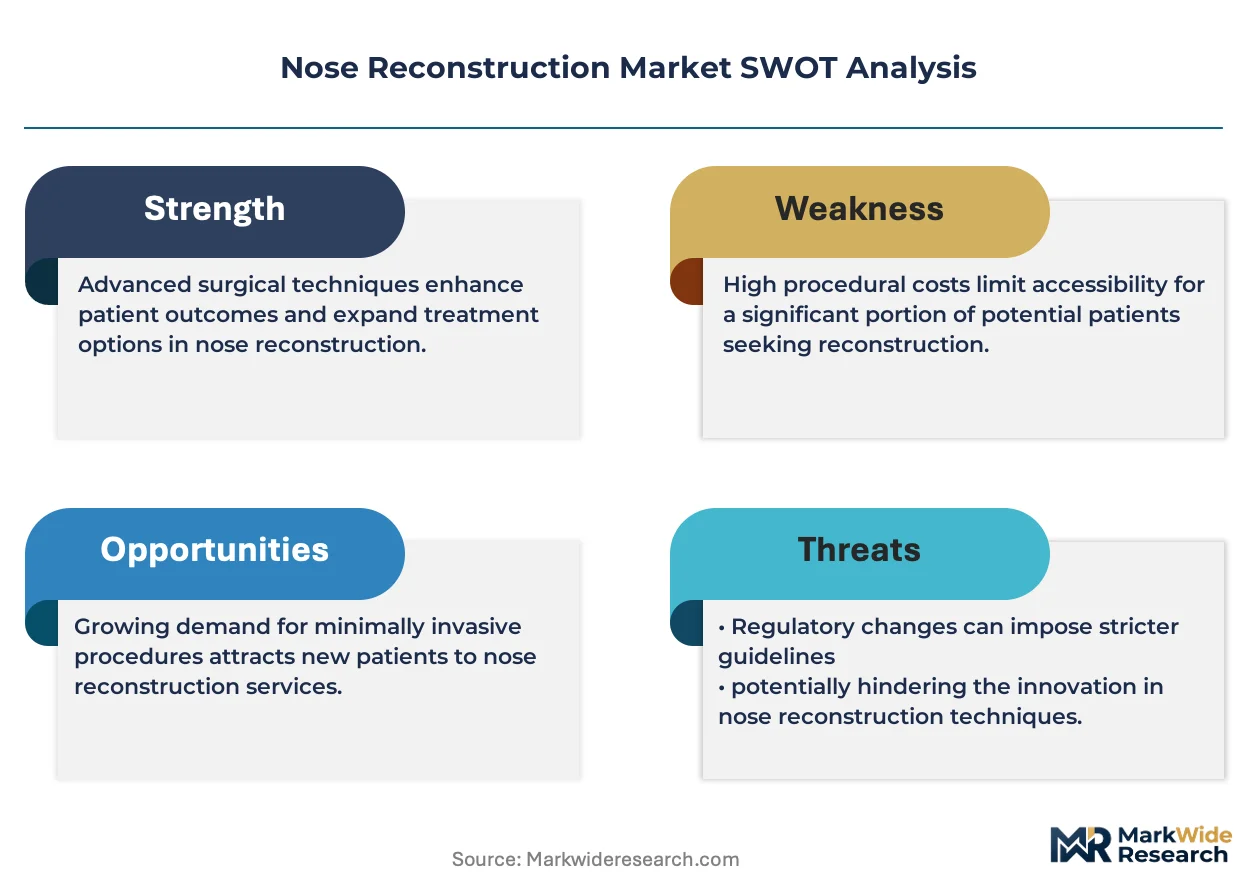
- EU MDR clinical evidence requirements:The European Medical Device Regulation mandates extended follow-up data for permanent nasal alloplasts, extending time-to-market by 18-24 months.
- Biologic scaffold cost structure:Decellularized matrices command 4-6x pricing multiples over synthetic alternatives, restricting adoption to tertiary academic centers with negotiated premium reimbursement.
Strategic Opportunities
- Telemedicine pre-consultation:Remote surgical planning and graft visualization via 3D imaging platforms opens access to patients in secondary US cities lacking specialist proximity.
- ISO 13485 certification harmonization:Convergence of quality management standards across FDA, Health Canada, and TGA pathways reduces duplicate audit burdens for multi-market entrants.
- Non-surgical maintenance protocols:Hyaluronic acid filler touch-up programs create recurring revenue attachment to primary surgical cases among younger patient cohorts.
Industry Challenges
- Craniofacial fellowship scarcity:The pipeline of surgeons trained in complex nasal reconstruction fails to match procedure volume growth, creating wait-time bottlenecks at high-volume centers.
- 510(k) predicate drift:FDA's tightening equivalence standards for porous polyethylene implants force sponsors toward de novo pathways with expanded clinical trial obligations.
- Implant tracking integration:Unique Device Identifier mandates require hospital IT systems to reconcile legacy inventory with new traceability protocols, delaying procurement approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nose Reconstruction Market |
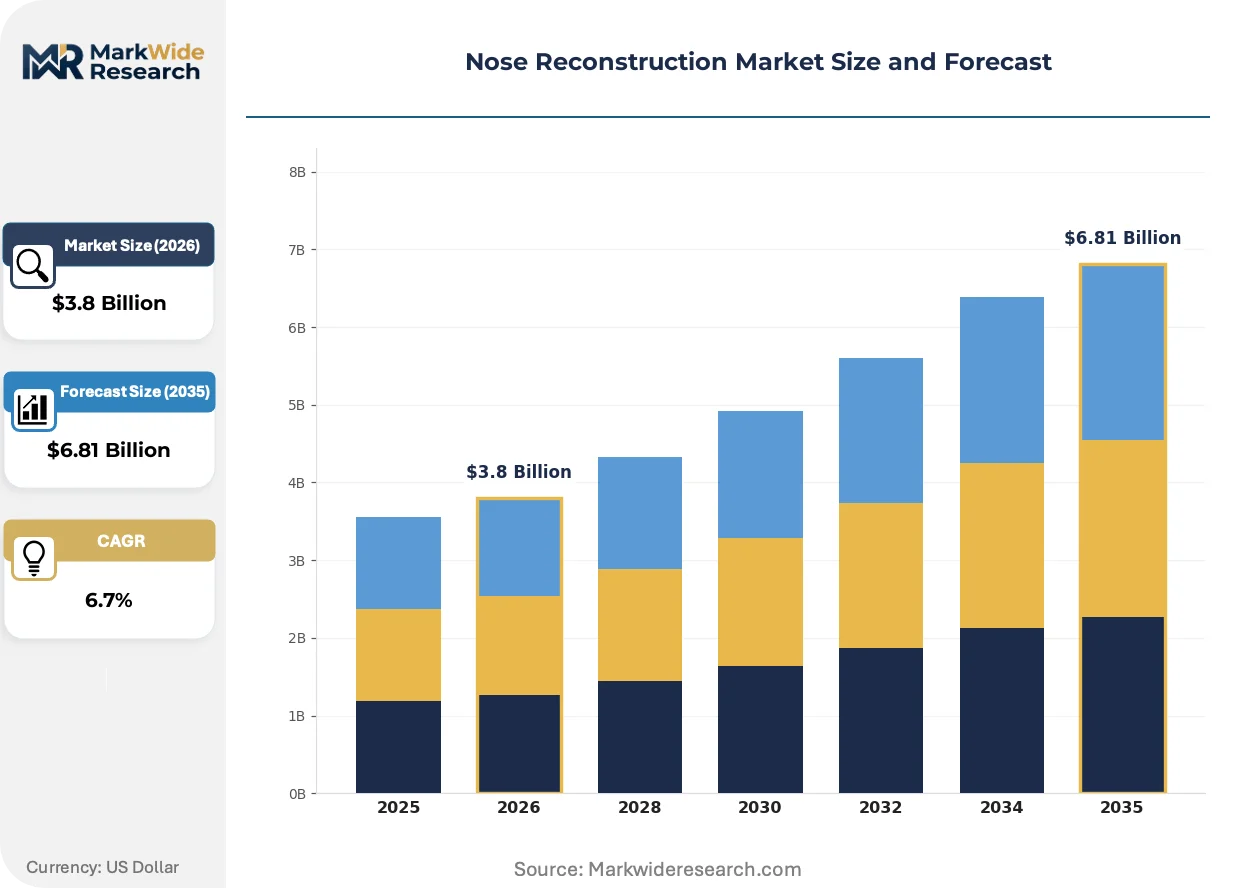
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Open Rhinoplasty, Closed Rhinoplasty, Revision Rhinoplasty, Non-Surgical Rhinoplasty Material: Synthetic Fillers, Grafts, Cartilage, Biologics Application: Reconstruction, Aesthetic Enhancement, Trauma Repair, Congenital Malformation End User: Plastic Surgeons, Otolaryngologists, Hospitals, Clinics |
| Companies Covered | Stryker Corporation, Implantech Associates, GC Aesthetics, Surgiform Technologies, Abbvie Inc., Johnson & Johnson, COMEG Medical Technologies, Sunset Cosmetic Surgery, Grover Aesthetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nose Reconstruction Market Emerging Trajectories
Digital fabrication and biologics manufacturing are converging to displace conventional graft harvesting and off-the-shelf implant selection. Three developments are compressing the traditional surgical planning cycle and redistributing value toward pre-operative service layers.
Patient-specific titanium mesh and porous polyethylene implants fabricated via electron beam melting are virtualizing the graft carving workflow that previously consumed 20-40 minutes of operative time. Academic medical centers in Germany and the United States are adopting these platforms for oncologic nasal reconstructions requiring precise orbital rim restoration. The technology is virtualizing the economic center of the procedure from the operating room toward the design studio, where biomedical engineers now capture margin previously retained by surgeons.
The FDA's updated guidance on silicone breast implants has triggered collateral scrutiny of silicone-based facial alloplasts, requiring manufacturers to submit enhanced rupture and migration data even for established product lines. This regulatory friction is compressing the competitive set to firms with sufficient balance sheet depth to fund extended post-market studies. European manufacturers are responding by accelerating bioresorbable scaffold development to circumvent permanent implant classification entirely.
Patients are fragmenting their care journey across multiple providers, seeking surgical planning from academic specialists while procuring aftercare and revision touch-ups through commercial aesthetic chains. This unbundling is eroding the traditional bundled pricing model that cross-subsidized complex reconstructions with simpler cosmetic cases. The pattern is most visible in South Korea and Thailand, where medical tourism intermediaries now disaggregate procedure components across competing facility networks.
Nose Reconstruction Market Segmentation
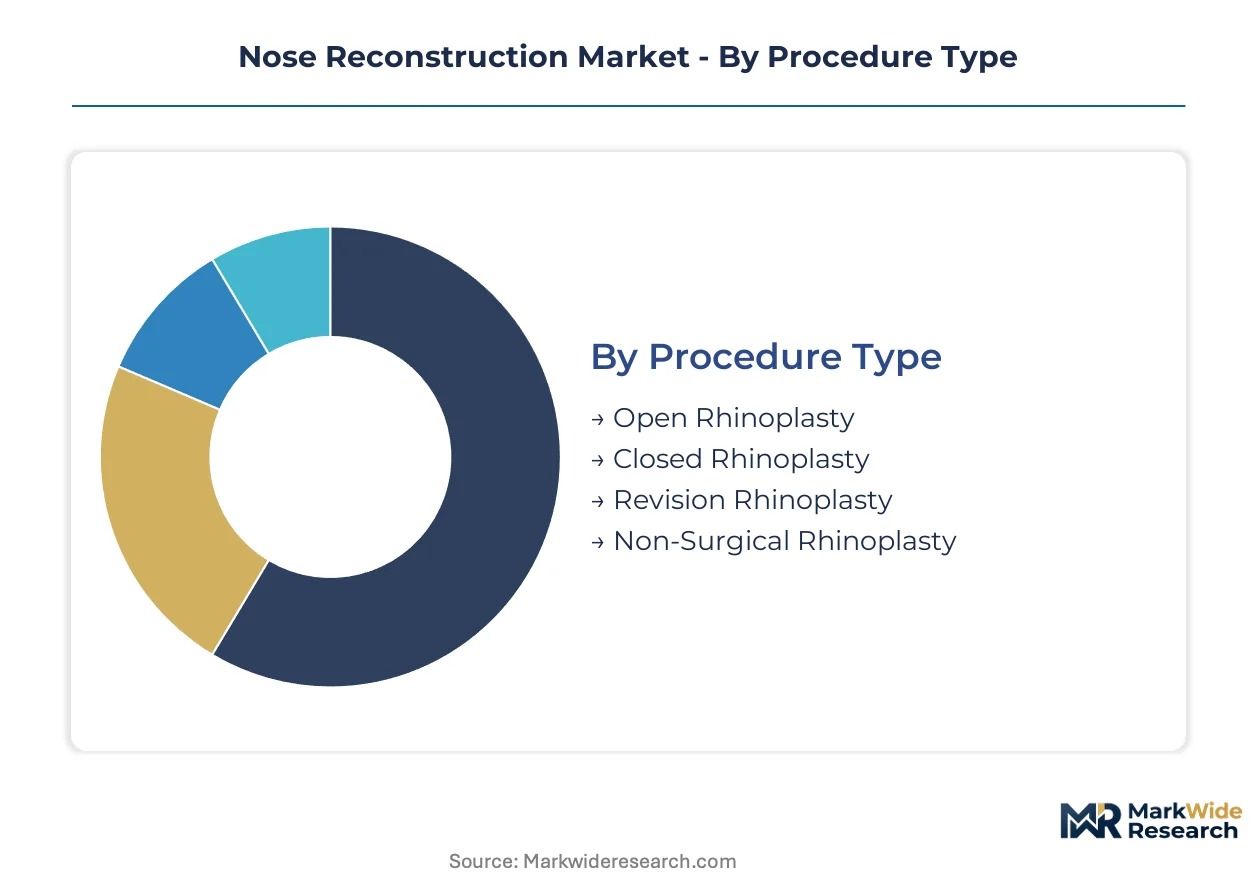
Nose reconstruction procedures fragment across four distinct dimensions, each capturing different margin structures and clinical workflows. Procedure type determines operative complexity and reimbursement tiers. Material selection drives supply chain exposure and regulatory pathway requirements. Application context shapes patient acquisition channels and outcome liability profiles. End-user concentration dictates distribution strategy and technical support intensity.
Procedure Type:
Cycle times compress from months-long surgical recovery to same-day filler dissolution, creating divergent inventory and staffing models across the category.
- Open Rhinoplasty:Full columellar incision delivers complete nasal framework exposure for structural grafting and complex tip reconstruction. Academic medical centers in Germany and South Korea concentrate demand as fellowship-trained surgeons handle oncologic resections and tertiary revision cases requiring rib cartilage harvest.
- Closed Rhinoplasty:Endonasal approaches preserve columellar integrity and reduce operative time for dorsal hump reduction and straightforward tip refinement. Private aesthetic clinics in Seoul's Gangnam district and Beverly Hills capture volume from patients prioritizing scar concealment and faster return to social visibility.
- Revision Rhinoplasty:Scar tissue dissection and graft salvage demand specialized instrumentation and extended operative blocks. Tertiary referral centers accumulate cases from failed primary procedures, with Seoul's specialist density attracting international medical tourism flows.
- Non-Surgical Rhinoplasty:Hyaluronic acid filler injection reshapes nasal dorsum and tip without operative recovery. Younger patient cohorts in urban US markets and European capitals drive uptake for temporary augmentation and bridge contouring.
Open rhinoplasty anchors the volume base while non-surgical rhinoplasty gains share at the steepest rate.
Material:
Cost tiers stratify from commodity-grade silicone to premium decellularized matrices, with procurement committees weighing biocompatibility data against budget cycle constraints.
- Synthetic Fillers:Cross-linked hyaluronic acid formulations enable reversible dorsal augmentation with enzymatic dissolution capability. Aesthetic clinic chains in Los Angeles and London standardize on specific rheology profiles for predictable tissue integration.
- Grafts:Porous polyethylene and silicone alloplasts provide permanent structural support without donor-site morbidity. FDA's tightened silicone guidance is extending 510(k) review timelines and compressing the competitive set to well-capitalized manufacturers.
- Cartilage:Autologous septal, auricular, and costal cartilage remains the gold standard for structural reconstruction. South Korean surgeons have refined endoscopic rib harvest techniques, reducing postoperative pain and expanding candidacy for complex cases.
- Biologics:Decellularized dermal matrices and engineered scaffolds support tissue ingrowth while resorbing over 12-24 months. Tertiary academic centers negotiate premium pricing for these products, restricting adoption to hospitals with carved-out reimbursement for donor-site morbidity reduction.
Cartilage grafting retains the highest procedure share while biologics expand most quickly among academic referral centers.
Application:
Patient acquisition channels diverge sharply between trauma emergency departments and elective aesthetic consultation suites, with reconstruction cases flowing through hospital networks and enhancement procedures concentrating in standalone facilities.
- Reconstruction:Oncologic resection and post-traumatic defect restoration demand multidisciplinary coordination with head and neck surgery. German university hospitals and US academic medical centers lead adoption of patient-specific titanium mesh for orbital rim and nasal sidewall restoration.
- Aesthetic Enhancement:Dorsal refinement, tip projection, and alar base modification drive elective procedure volume. Seoul's medical tourism infrastructure and Los Angeles celebrity-adjacent practices capture premium pricing for complex ethnic rhinoplasty.
- Trauma Repair:Acute nasal fracture reduction and septal hematoma evacuation require immediate operative access. Level I trauma centers in the US and major European capitals maintain 24-hour otolaryngology coverage for facial injury protocols.
- Congenital Malformation:Cleft lip and palate sequelae, hemifacial microsomia, and Binder syndrome reconstruction demand pediatric subspecialist coordination. Children's hospitals in Boston, Philadelphia, and London concentrate fellowship-trained craniofacial teams.
Aesthetic enhancement generates the highest absolute procedure count while reconstruction commands the steepest pricing multiples.
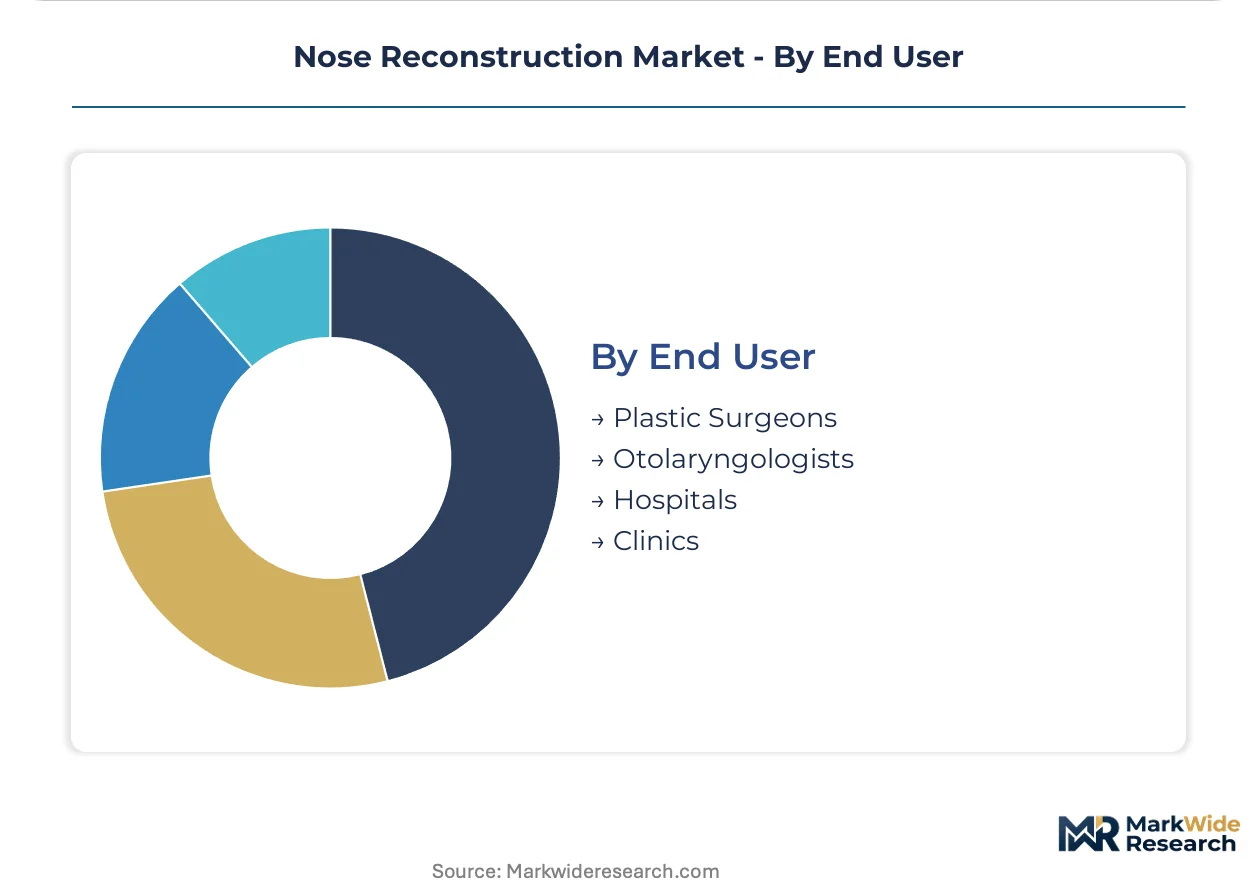
End User:
Procurement authority concentrates differently across settings, with hospital materials management committees governing implant selection while individual surgeons direct filler purchasing in private practice.
- Plastic Surgeons:Fellowship-trained aesthetic and reconstructive specialists handle complex revision cases and combined facial procedures. Private practice groups in Beverly Hills, Miami, and Seoul's Gangnam district invest in 3D imaging and surgical planning platforms.
- Otolaryngologists:Functional airway restoration and septorhinoplasty for breathing obstruction fall within ENT scope. US and German otolaryngology clinics are strengthening demand as patients seek combined cosmetic and functional outcomes.
- Hospitals:Inpatient facilities capture trauma, oncologic reconstruction, and congenital cases requiring general anesthesia and overnight observation. Academic medical centers in the US and Germany lead adoption of computer-assisted planning integration.
- Clinics:Ambulatory surgery centers and standalone aesthetic facilities handle primary rhinoplasty and non-surgical procedures. South Korea's clinic density supports medical tourism intermediaries that disaggregate procedure components across competing networks.
Hospitals anchor the revenue base while clinics capture volume at the fastest clip through non-surgical service expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean manufacturers export patient-specific implants to Germany and the United States, establishing Seoul as the dominant fabrication hub for complex nasal reconstruction hardware.
United States
Academic medical centers in Boston and Philadelphia drive demand for oncologic nasal reconstruction requiring orbital rim restoration. FDA 510(k) clearance pathways govern permanent alloplasts, with tightened equivalence standards pushing sponsors toward de novo submissions. The Greater Boston corridor concentrates fellowship-trained craniofacial teams adopting computer-assisted surgical planning platforms.
Germany
University hospitals in Heidelberg and Munich lead European adoption of patient-specific titanium mesh for post-resection defects. EU Medical Device Regulation mandates extended clinical evidence for permanent nasal implants, extending German manufacturers' time-to-market by 18-24 months. The Baden-Württemberg region anchors precision manufacturing clusters supplying electron beam melting equipment to medical device fabricators.
South Korea
International patients from China and Southeast Asia fuel demand for revision rhinoplasty in Seoul's Gangnam district. MFDS fast-track designation accelerates approval timelines for patient-matched implants, drawing manufacturers to establish local validation facilities. The Seoul Capital Area concentrates the highest specialist density globally for complex ethnic rhinoplasty procedures.
Japan
Aging demographics and trauma incidence sustain reconstructive procedure volume in Tokyo and Osaka metropolitan areas. PMDA regulatory requirements align with ISO 10993 biocompatibility standards but maintain independent adverse event reporting systems. The Kanto region hosts integrated medical tourism intermediaries connecting domestic patients to South Korean surgical centers.
Australia
Tertiary referral centers in Sydney and Melbourne negotiate premium pricing for decellularized matrices reducing donor-site morbidity. TGA alignment with ISO standards enables streamlined market access for biologic scaffold manufacturers. The New South Wales corridor concentrates pediatric craniofacial services handling congenital malformation sequelae.
Nose Reconstruction Market Vendor Landscape
On the supply side, the industry is consolidating around integrated digital surgery platforms that bundle hardware with software subscriptions. Tiered competitive dynamics separate multinational orthopedic conglomerates with craniomaxillofacial extensions from specialized aesthetic device manufacturers and regional biologic scaffold producers. Dominant competitive moves include strategic partnerships between implant fabricators and 3D printing service bureaus, plus portfolio diversification into resorbable scaffold categories to circumvent permanent implant regulatory classification.
Among diversified medical technology conglomerates, Stryker Corporation and Johnson & Johnson exemplify platform-centric archetypes leveraging orthopedic digital infrastructure for surgical planning tools. Abbvie Inc. occupies a distinct position through its Allergan Aesthetics arm, anchoring channel access to plastic surgeons via combined filler and implant portfolios. These three entities represent contrasting strategic vectors: hardware-software integration, broad graft fixation portfolios, and aesthetic channel density respectively.
| Leading Market Players |
|---|
| Stryker Corporation |
| Implantech Associates |
| GC Aesthetics |
| Surgiform Technologies |
| Abbvie Inc. |
| Johnson & Johnson |
| COMEG Medical Technologies |
| Sunset Cosmetic Surgery |
| Grover Aesthetics |
| Others |
Supply Flow & Price Mechanics
Undercapacity in medical-grade silicone purification facilities across Northeast Asian chemical corridors is compressing input availability for implant manufacturers while simultaneously elevating pricing power among raw material suppliers. This utilization squeeze propagates through the value chain, forcing device makers to absorb cost increases or risk procurement delays from concentrated feedstock sources.
Pricing Analysis
Next-generation patient-specific titanium mesh commands substantial premiums over conventional off-the-shelf porous polyethylene implants, while prior-generation silicone alloplasts face accelerating price erosion. Three-tier pricing structure across premium, standard, and economy levels stratifies by customization intensity and regulatory certification tier, with FDA 510(k) cleared biologics capturing the highest per-unit margins. Pricing pressure stems from EU MDR compliance costs that extend development cycles and compress returns on legacy product lines. Academic medical centers demonstrate lowest price sensitivity due to carved-out reimbursement for donor-site morbidity reduction, while ambulatory surgery centers negotiate aggressively on synthetic graft procurement.
Supply Chain Analysis
Upstream medical-grade silicone production clusters in South Korea, Japan, and coastal China, with porous polyethylene resin synthesis concentrated in Germany and the United States. Electron beam melting equipment for patient-specific fabrication draws from Baden-Württemberg precision manufacturing clusters, while decellularized matrix biologics hinge on North American tissue processing facilities. Single-source vulnerability in silicone purification exposes implant manufacturers to tariff friction and geopolitical disruption. Distribution runs through hospital materials management committees for permanent alloplasts and direct surgeon purchasing for hyaluronic acid fillers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nose reconstruction sits in early-cycle expansion as computer-assisted surgical planning penetrates academic centers and medical tourism infrastructure matures in Seoul. Digital workflow adoption represents the primary penetration tailwind compressing operative time and revision rates.
For Market Incumbents: Build regulatory data moats through extended post-market surveillance studies that satisfy FDA's tightened silicone equivalence standards. Incorporate 3D printing service bureaus through exclusive partnerships to virtualize graft templating workflows. Invest in ISO 13485 certification harmonization across FDA, Health Canada, and TGA pathways to reduce audit duplication. Channel control through integrated digital surgery platforms defends against orthopedic conglomerates extending planning tools into craniomaxillofacial applications. For New Entrants and Emerging Players: Mid-market otolaryngology clinics in secondary US cities represent the most penetrable entry point, as telemedicine pre-consultation dissolves geographic barriers to specialist access. Bioresorbable scaffold development for European markets circumvents permanent implant classification and associated clinical evidence burdens. Non-surgical maintenance protocols using hyaluronic acid fillers offer recurring revenue attachment with lower capital requirements than surgical hardware manufacturing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aesthetic clinic chains operating filler touch-up programs that create patient lifetime value beyond primary surgical cases. Long-term viability favors platform-centric models bundling hardware with software subscriptions over commodity implant manufacturers facing input volatility. Acquisition targets should demonstrate MFDS fast-track designation progress or established validation facilities in Seoul. Monitor craniofacial fellowship graduation rates as an inflection indicator for surgeon supply constraints that bottleneck procedure volume growth.| Strategic Initiative | Industry Significance |
|---|---|
| Patient-Specific Implant Fabrication Partnership | Electron beam melting integration with surgical planning platforms captures margin previously retained by operating room time. |
| Bioresorbable Scaffold Development | European manufacturers accelerate resorbable matrices to circumvent EU MDR permanent implant classification entirely. |
| Telemedicine Pre-Consultation Platform | Remote 3D imaging and graft visualization opens access to patients lacking specialist proximity in secondary markets. |
| ISO 13485 Certification Harmonization | Convergence across FDA, Health Canada, and TGA pathways reduces duplicate audit burdens for multi-market entrants. |
| Non-Surgical Maintenance Program Launch | Hyaluronic acid filler touch-up protocols create recurring revenue attachment among younger patient cohorts. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with craniofacial surgeons, otolaryngologists, hospital purchasing committee members, biomedical engineers, and medical tourism intermediaries. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, MFDS approval databases, hospital procurement contracts, and GPO pricing disclosures. Bottom-up procedure volume estimates were triangulated against top-down manufacturer revenue allocations across the analysis window.
Calibration against historical implant shipment data and surgical planning software adoption curves anchored the analytical framework. Segmentation dimensions modeled include procedure type, material category, application context, and end-user concentration across the projection horizon. CAGRs were derived from regression analysis of procedural volume trends and pricing trajectory assumptions. Forecast inputs incorporated craniofacial fellowship pipeline data and medical tourism flow statistics from Seoul's Gangnam district.
Practitioners should monitor regulatory guidance revisions and biocompatibility standard updates for early signals of forecast deviation. Cross-checking against hospital implant procurement database trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Parathyroid Disease Treatment Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
Urea Cycle Disorders Treatment Market
Medical Treatment
Hyperkalemia Treatment Market
Medical Treatment
Hemorrhoids Treatment Market
Medical Treatment
Andersen Tawil Syndrome Treatment Market
Medical Treatment
Dengue Fever Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Liver Fluke Treatment Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Acute Migraine Treatment Market
Medical Treatment
North America Nerve Repair and Regeneration Market
Medical Treatment
Global Hyperhidrosis Treatment Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market