
 Brazilian Hemorrhagic Fever (Bzhf) Treatment Market | 2026-2036
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market Outlook
Domestic biopharmaceutical manufacturing capacity in Brazil is restructuring around pandemic preparedness mandates and reduced import dependency for critical antiviral stockpiles. F. Hoffmann-La Roche Ltd anchors its position through sustained investment in diagnostic-therapeutic integration for hemorrhagic fever protocols. Pfizer Inc leverages its established hospital channel relationships to secure procurement contracts within Brazil's Unified Health System. Teva Pharmaceutical Industries Ltd competes on cost positioning for generic antiviral formulations used in supportive care regimens.
Brazilian Hemorrhagic Fever treatment encompasses pharmacological and supportive interventions targeting arenavirus-induced vascular leakage and coagulopathy, typically administered through intravenous infusion under intensive monitoring with hemodynamic stabilization parameters. The primary purpose is to reduce mortality through early antiviral administration, fluid management, and correction of hematological abnormalities in confirmed cases. Monoclonal antibodies command premium positioning due to manufacturing complexity and limited supplier base, while antiviral drugs represent the volume backbone of hospital formularies. Emergency departments drive episodic demand spikes during outbreak periods, contrasting with the steady replenishment patterns seen in research laboratories maintaining pre-positioned therapeutic inventories.
ANVISA governs clinical trial authorization and post-market surveillance for antiviral therapies, while Brazil's Ministry of Health coordinates national stockpiling directives through the Strategic Inputs Secretariat under emergency preparedness frameworks. These regulatory layers create dual compliance requirements that favor manufacturers with established local quality documentation and cold-chain logistics certification. Stakeholders must monitor ANVISA's evolving guidance on accelerated approval for emerging infectious disease therapeutics to anticipate competitive entry windows and procurement list revisions.
Market Dynamics
ANVISA's accelerated review pathways for orphan and emerging disease therapeutics are compressing product registration timelines and redrawing competitive entry sequences for antiviral manufacturers serving Brazil's public health system.
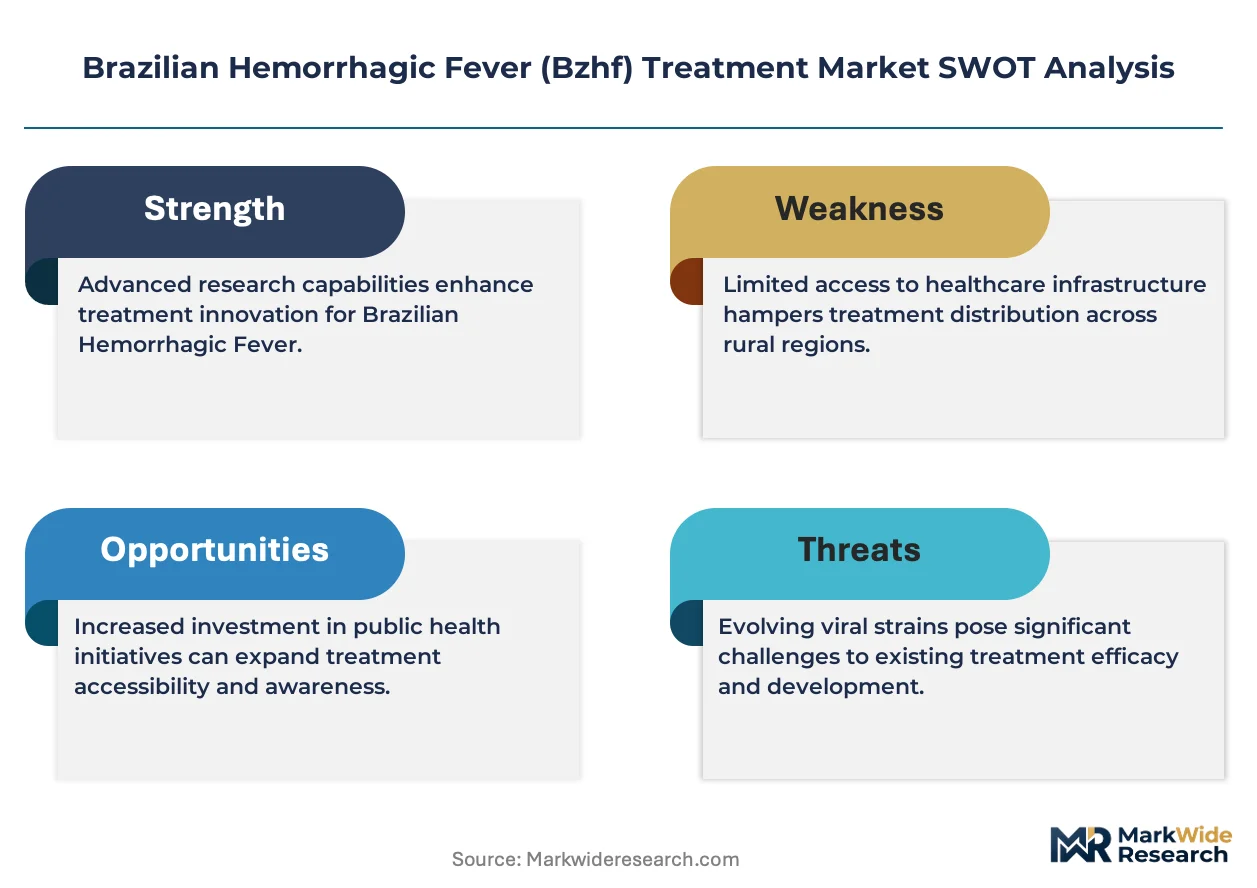
Growth Catalysts
- Emergency preparedness mandates:Brazil's Ministry of Health stockpiling directives through the Strategic Inputs Secretariat are institutionalizing recurring procurement volumes for hemorrhagic fever therapeutics.
- Diagnostic-therapeutic integration:Hospital networks in São Paulo state's metropolitan health corridor are consolidating infectious disease response capabilities around rapid pathogen identification protocols.
- Reduced import dependency policies:Domestic biopharmaceutical manufacturing capacity restructuring is creating captive supply incentives for critical antiviral stockpiles.
Market Restraints
- Cold-chain infrastructure gaps:Monoclonal antibody therapies requiring continuous temperature-controlled logistics face distribution limitations outside Brazil's southeastern hospital clusters.
- Regulatory dual compliance burden:ANVISA clinical trial authorization layered with Ministry of Health stockpiling certification creates documentation friction for foreign manufacturers.
- Input concentration risk:Active pharmaceutical ingredient sourcing for antiviral formulations remains concentrated among Asian suppliers, exposing formulators to supply volatility.
Strategic Opportunities
- Underpenetrated northern corridors:Amazon basin health networks lack specialized infectious disease centers, creating whitespace for mobile treatment unit deployments.
- Research laboratory pre-positioning:Steady replenishment patterns in biosafety level-4 facilities contrast with episodic hospital demand, offering predictable contract structures.
- Generic antiviral substitution window:Patent expirations on legacy ribavirin formulations are opening procurement list revisions for cost-positioned alternatives.
Industry Challenges
- Hemodynamic monitoring specialist scarcity:Intensive care units require trained personnel for fluid management protocol execution during acute arenavirus cases.
- Legacy system integration friction:Hospital pharmacy information systems in Brazil's Unified Health System lack interoperability with cold-chain tracking platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazilian Hemorrhagic Fever (Bzhf) Treatment Market |
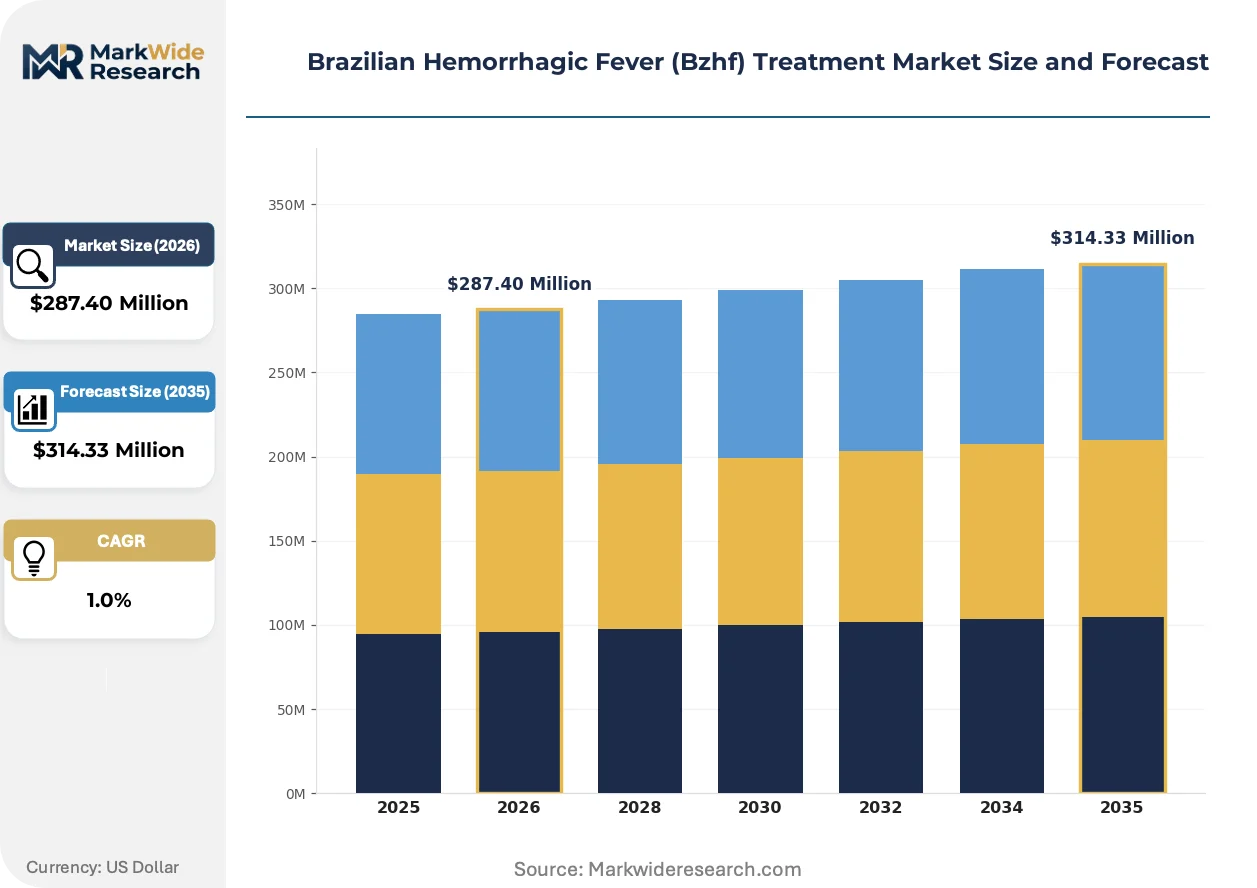
| Market Size in 2026 | $287.40 Million |
| Market Size in 2035 | $314.33 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Antiviral Drugs, Supportive Care, Vaccines End User: Hospitals, Clinics, Research Laboratories, Emergency Departments Administration Route: Intravenous, Intramuscular, Oral, Subcutaneous Distribution Channel: Direct Sales, Distributors, Online Pharmacies, Government Procurement |
| Companies Covered | Novartis AG, F. Hoffmann-La Roche Ltd, Pfizer Inc, Abbott, Teva Pharmaceutical Industries Ltd, Cipla Inc, Glenmark Pharmaceuticals Ltd, Dr Reddy's Laboratories Ltd, Zydus Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market Strategic Shifts
Point-of-care diagnostic platforms are compressing the treatment initiation window for hemorrhagic fever cases, reshaping how antiviral therapies align with hospital emergency department workflows and stockpiling strategies.
Portable nucleic acid amplification systems are decentralizing pathogen confirmation from centralized reference laboratories to emergency department settings. São Paulo metropolitan hospitals are deploying these platforms within infectious disease triage protocols. This capability compression is decentralizing treatment decisions to frontline clinicians and reducing reliance on external laboratory turnaround times.
ANVISA's orphan drug designation framework is streamlining post-market surveillance requirements for emerging infectious disease therapeutics. Manufacturers with established local quality documentation are securing conditional approvals with reduced Phase III data packages. Hemorrhagic fever monoclonal antibodies are benefiting most from this regulatory compression, as sponsors leverage Brazil's public health emergency provisions.
Hospital formularies are unbundling antiviral procurement from bundled infectious disease service contracts. São Paulo state procurement agencies are negotiating direct therapeutic acquisitions rather than full-service vendor relationships. This purchasing pattern shift is most visible in specialized infectious disease centers seeking transparent unit economics for stockpile rotation.
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market Segmentation
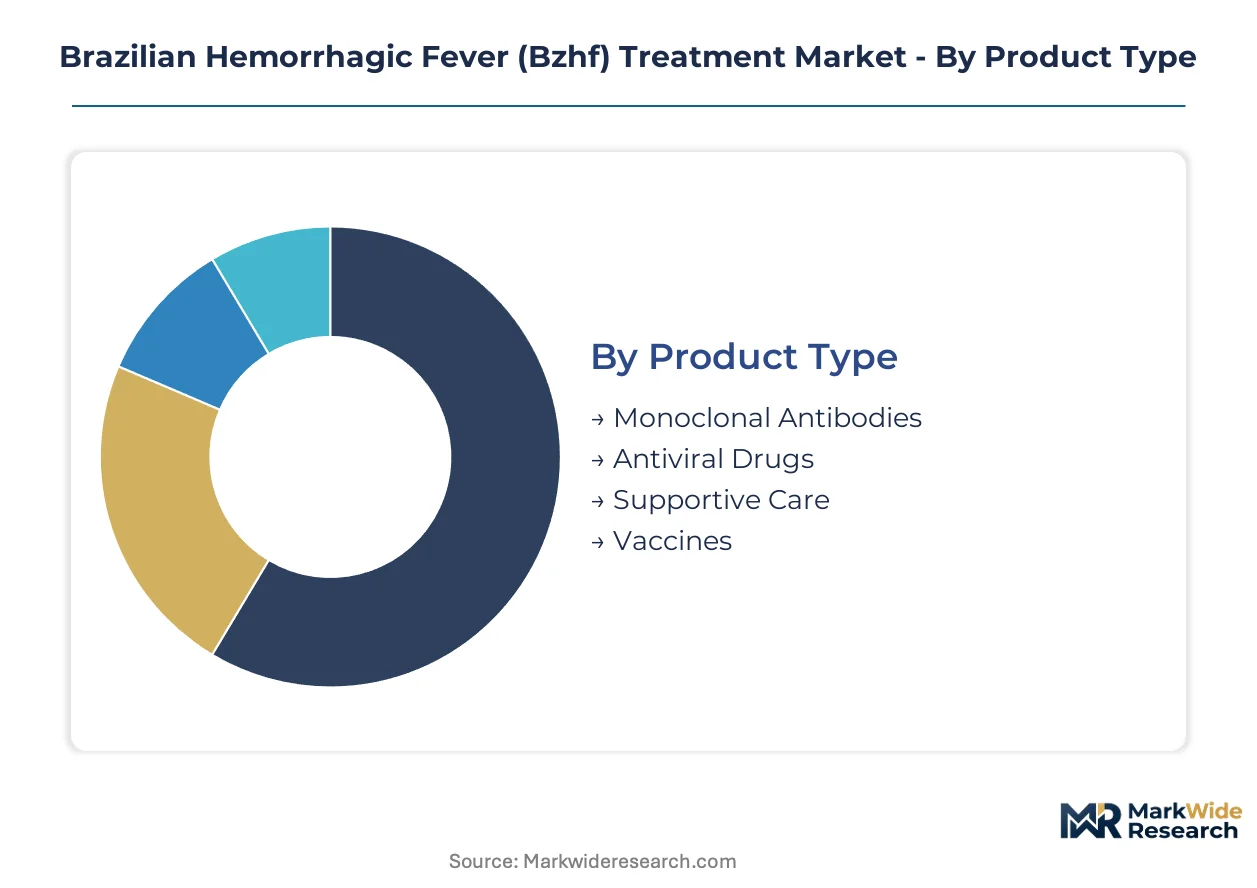
Segmentation in the Brazilian Hemorrhagic Fever treatment market reveals how procurement priorities diverge between emergency response infrastructure and research continuity requirements. ANVISA's regulatory pathways and Ministry of Health stockpiling directives create distinct demand profiles across product categories and end-use settings.
Product Type:
Replacement cycles for hemorrhagic fever therapeutics accelerate where cold-chain infrastructure upgrades and manufacturing technology shifts reduce shelf-life limitations for biological products.
- Monoclonal Antibodies:These engineered immunoglobulins target specific arenavirus epitopes to neutralize viral load. Demand concentrates in São Paulo state's metropolitan health corridor, where specialized infectious disease centers maintain dedicated infusion capacity and hemodynamic monitoring protocols.
- Antiviral Drugs:Ribavirin and investigational nucleoside analogs disrupt viral RNA replication through competitive inhibition. São Paulo procurement agencies negotiate direct acquisitions for hospital formularies as patent expirations on legacy formulations open substitution windows.
- Supportive Care:Intravenous fluids, electrolyte solutions, and coagulation factor concentrates manage vascular leakage and hemorrhagic complications. Teva Pharmaceutical Industries Ltd competes on cost positioning for generic formulations in this category.
- Vaccines:Prophylactic and post-exposure immunization candidates remain predominantly investigational, with research laboratories in Brazil's biosafety level-4 network driving pre-positioned inventory demand.
Antiviral drugs sit at the top of the volume ranking, with monoclonal antibodies climbing the fastest as ANVISA's accelerated review pathways compress registration timelines for biological therapeutics.
End User:
Customer-type concentration reflects Brazil's Unified Health System hierarchy, where federal stockpiling mandates cascade through state-level procurement to facility-level consumption patterns.
- Hospitals:Tertiary care centers administer intravenous antiviral protocols under intensive monitoring. F. Hoffmann-La Roche Ltd anchors its position through diagnostic-therapeutic integration investments in these facilities.
- Emergency Departments:Frontline triage units drive episodic demand spikes during outbreak periods, deploying point-of-care nucleic acid amplification systems to compress treatment initiation windows.
- Research Laboratories:Biosafety level-4 facilities maintain steady replenishment patterns for pre-positioned therapeutic inventories, offering predictable contract structures distinct from hospital procurement volatility.
- Clinics:Primary and secondary care settings provide initial case identification and referral, with limited direct therapeutic administration due to intensive monitoring requirements.
Hospitals capture the dominant procurement volume, while research laboratories demonstrate the most stable contract renewal profiles across the analysis window.
Administration Route:
Margin structures diverge sharply between infusion-based biological therapies and oral formulations, with cold-chain requirements and specialist supervision needs driving total cost of administration.
- Intravenous:Continuous infusion delivery enables precise dosing control for antiviral and monoclonal antibody therapies. São Paulo metropolitan hospitals consolidate procurement around this route for confirmed arenavirus cases.
- Oral:Ribavirin capsules support outpatient or early-stage management where hospital admission remains unnecessary. Distribution concentrates through government procurement channels for strategic stockpile rotation.
- Intramuscular:Vaccine candidates and certain immunoglobulin preparations utilize this route, with administration typically limited to research protocols and specialized infectious disease centers.
- Subcutaneous:Emerging monoclonal antibody formulations seek to displace intravenous protocols through reduced infusion center dependency, though cold-chain infrastructure gaps outside southeastern Brazil constrain adoption.
Intravenous administration maintains volume leadership, with subcutaneous alternatives gaining share fastest where pharmaceutical sponsors target reduced healthcare system burden.
Distribution Channel:
Supply concentration in government procurement reflects Brazil's public health system structure, with direct sales relationships and distributor networks competing for residual private and research segment access.
- Government Procurement:Ministry of Health stockpiling directives through the Strategic Inputs Secretariat institutionalize recurring procurement volumes. Pfizer Inc leverages established hospital channel relationships to secure contracts within this framework.
- Distributors:Regional pharmaceutical wholesalers bridge cold-chain logistics gaps for monoclonal antibody therapies, though coverage remains concentrated in Brazil's southeastern hospital clusters.
- Direct Sales:Manufacturers with established local quality documentation and ANVISA certification engage specialized infectious disease centers for unbundled therapeutic acquisitions.
- Online Pharmacies:Limited relevance for hemorrhagic fever therapeutics due to prescription requirements, cold-chain constraints, and emergency administration protocols.
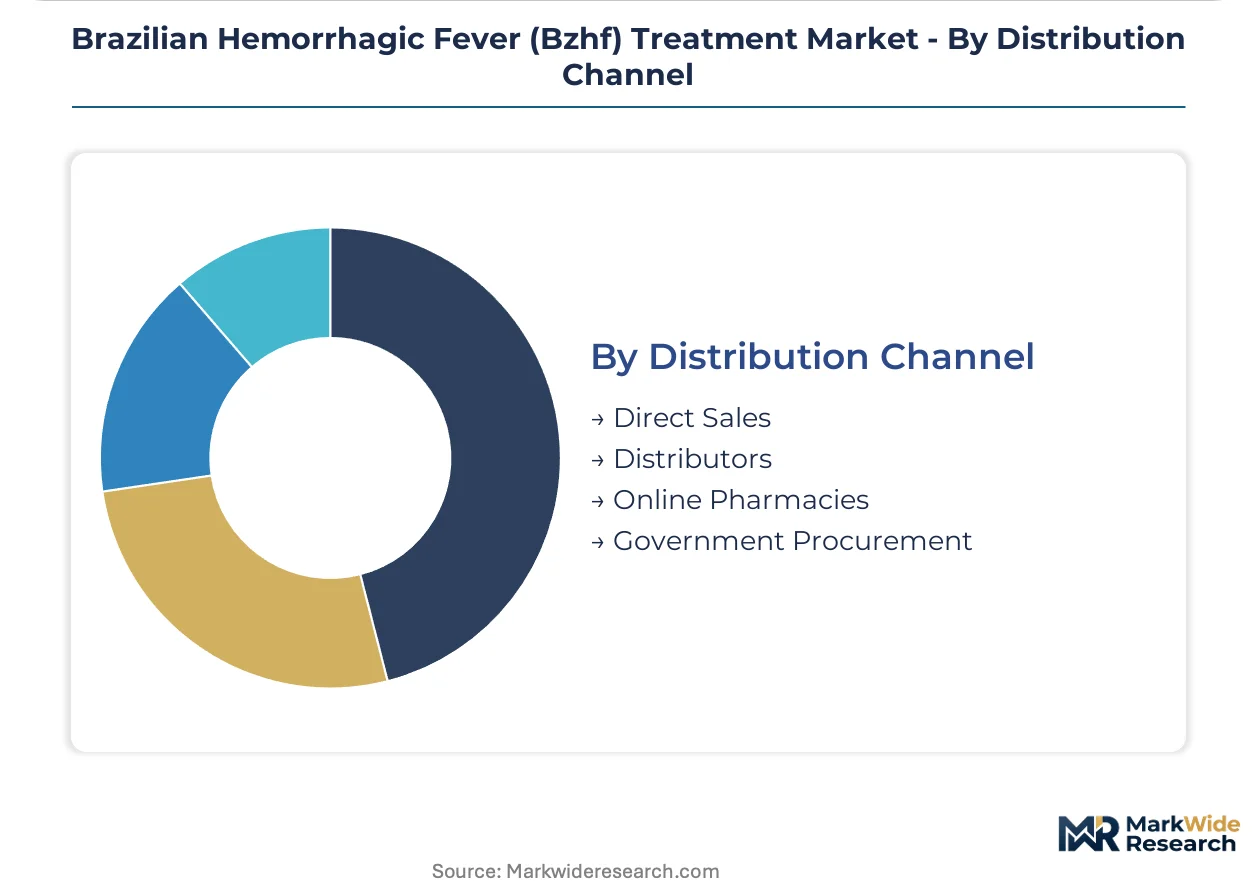
Government procurement dominates volume flow, with direct sales channels expanding most quickly as hospital formularies unbundle antiviral procurement from bundled service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for hemorrhagic fever therapeutics migrates toward jurisdictions where ANVISA-equivalent regulatory frameworks offer accelerated pathways without compromising cold-chain integrity standards. Brazil's cost-of-compliance advantage relative to North American or European certification timelines attracts regional production investment.
São Paulo
The metropolitan health corridor concentrates specialized infectious disease centers and diagnostic-therapeutic integration investments. ANVISA's São Paulo regional office processes the majority of antiviral clinical trial authorizations. The state procurement agency negotiates direct therapeutic acquisitions for hospital formularies in the capital and Campinas cluster.
Minas Gerais
Belo Horizonte anchors southeastern Brazil's secondary hub for infectious disease response infrastructure. The state's pharmaceutical manufacturing tax incentives support generic antiviral formulation facilities. Contagem and Betim industrial parks host cold-chain logistics providers serving the regional hospital network.
Rio de Janeiro
Federal research institutions drive pre-positioned therapeutic inventory demand for biosafety level-4 protocols. The Oswaldo Cruz Foundation coordinates national reference laboratory functions with ANVISA on post-market surveillance. Niterói and Duque de Caxias pharmaceutical distributors bridge southeastern supply gaps.
Rio Grande do Sul
Porto Alegre's hospital network maintains hemodynamic monitoring capacity for intensive antiviral administration. The state's proximity to Mercosur trade corridors facilitates cross-border API sourcing. Caxias do Sul hosts regional pharmaceutical packaging operations for government stockpile rotation.
Amazonas
Manaus represents the most significant underpenetrated corridor for mobile treatment unit deployment. The state's isolated health networks face cold-chain infrastructure gaps for monoclonal antibody distribution. ANVISA's northern regional office struggles with inspection capacity relative to the geographic dispersion of riverine communities.
Brazilian Hemorrhagic Fever (Bzhf) Treatment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biosimilar and generic substitution windows opened by patent expirations. The market structures around three archetypes: integrated diagnostic-therapeutic providers, cost-positioned generic formulators, and research-focused biological specialists. Consolidation pressures concentrate among hospital channel incumbents defending procurement relationships. Geographic expansion and technology licensing represent the dominant competitive moves as foreign manufacturers seek ANVISA certification efficiency.
Among Swiss-headquartered integrated healthcare conglomerates, F. Hoffmann-La Roche Ltd exemplifies the diagnostic-therapeutic bundling archetype. Pfizer Inc represents established hospital channel relationships within Brazil's Unified Health System. Teva Pharmaceutical Industries Ltd occupies the cost-positioned generic formulation tier for supportive care regimens.
| Leading Market Players |
|---|
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc |
| Abbott |
| Teva Pharmaceutical Industries Ltd |
| Cipla Inc |
| Glenmark Pharmaceuticals Ltd |
| Dr Reddy's Laboratories Ltd |
| Zydus Group |
| Others |
Value Chain & Pricing Dynamics
Hemodynamic monitoring specialists in São Paulo state's metropolitan health corridor anchor labor-cost differentials that widen pricing-tier spreads between premium monoclonal antibody therapies and generic antiviral formulations. ANVISA certification requirements for cold-chain handlers further stratify service premiums across Brazil's southeastern hospital clusters versus northern corridors.
Pricing Analysis
Distributor margins for monoclonal antibody therapies absorb cold-chain logistics certification costs and specialist infusion supervision requirements. Three-tier pricing structure across premium biologics, standard antivirals, and economy supportive care reflects ANVISA registration tier and volume scale. Pricing pressure stems from patent expirations on legacy ribavirin formulations opening substitution windows. Public hospital procurement through Brazil's Unified Health System demonstrates highest price sensitivity, while research laboratories maintaining biosafety level-4 pre-positioned inventories show lowest sensitivity due to continuity mandates.
Supply Chain Analysis
Workforce availability for sterile manufacturing and cold-chain logistics concentrates in São Paulo, Minas Gerais, and Rio de Janeiro industrial corridors. Active pharmaceutical ingredient sourcing draws from India and China for ribavirin precursors, with European suppliers dominating monoclonal antibody cell-line inputs. Single-source vulnerability in Asian API concentration exposes formulators to supply volatility. Distribution runs through government procurement channels anchored by the Strategic Inputs Secretariat, with regional pharmaceutical wholesalers bridging gaps for biological therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazilian Hemorrhagic Fever treatment functions as a geographic-arbitrage play where ANVISA's accelerated review timelines compress competitive entry costs relative to FDA or EMA pathways. Manufacturers capturing certification efficiency gain first-mover positioning in South American public health procurement.
For Market Incumbents: Acquire cold-chain logistics assets in northern Brazil to preempt mobile treatment unit deployment opportunities. Defend hospital channel relationships through diagnostic-therapeutic integration investments that lock in formulary positioning against emerging generic substitution threats. Anchor capacity in Minas Gerais pharmaceutical manufacturing zones to capture state tax incentives and reduce import dependency exposure. For New Entrants and Emerging Players: Enter via biosimilar monoclonal antibody development targeting ANVISA's orphan drug designation pathway. The Amazonas mobile treatment corridor offers lowest competitive density among underpenetrated regions. Partner with established regional distributors possessing existing Ministry of Health contracts to bypass direct procurement certification barriers. For Investors and Strategic Acquirers: Integrated diagnostic-therapeutic providers are the most active acquirer in this space, consolidating point-of-care platform capabilities with antiviral therapeutic portfolios. Five-to-ten year viability hinges on pandemic preparedness mandate durability and ANVISA regulatory compression sustainability. Monitor ANVISA guidance revisions on emerging infectious disease therapeutic approval as the primary inflection signal for competitive entry window expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Orphan Drug Designation Pathway | Compresses registration timelines for hemorrhagic fever monoclonal antibodies versus standard biological licensure. |
| Diagnostic-Therapeutic Integration Investment | Roche anchors São Paulo hospital relationships through combined point-of-care platform and antiviral protocol bundling. |
| Generic Antiviral Substitution Window | Teva and Dr Reddy's exploit patent expirations on legacy ribavirin to capture Ministry of Health procurement list revisions. |
| Mobile Treatment Unit Deployment | Addresses cold-chain infrastructure gaps in Amazonas riverine communities beyond southeastern hospital cluster reach. |
| Research Laboratory Pre-Positioning Contracts | Oswaldo Cruz Foundation and biosafety level-4 facilities offer predictable replenishment patterns distinct from episodic hospital demand. |
Study Parameters
Direct dialogue with infectious disease specialists, hospital procurement managers, ANVISA regulatory affairs leads, and pharmaceutical distribution executives grounded qualitative insights. Secondary validation drew from ANVISA clinical trial authorization databases, Ministry of Health Strategic Inputs Secretariat procurement records, ClinicalTrials.gov hemorrhagic fever protocol registrations, and Oswaldo Cruz Foundation research publication archives. Bottom-up therapeutic demand modeling and top-down public health expenditure analysis were triangulated against manufacturer capacity disclosures.
Segmented outputs across product type, end user, administration route, and distribution channel were generated through the projection horizon. CAGRs were derived from historical procurement velocity and pandemic preparedness mandate institutionalization trajectories. Forecast inputs incorporated ANVISA regulatory pathway evolution, cold-chain infrastructure investment flows, and biosafety level-4 facility expansion plans.
The model holds under stable ANVISA accelerated review commitment and continued Ministry of Health stockpiling directive continuity; deviation in federal public health budget allocation or regulatory pathway rollback would shift volume trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Systemic Inflammatory Response Syndrome Treatment Market
Medical Treatment
Systemic Mastocytosis Treatment Market
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Thyroid Deficiency Treatment Market
Medical Treatment
Cleft Lip Surgery Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Pompe Disease Treatment Market
Medical Treatment
Non-Invasive Surgery Market
Medical Treatment
Hyperbaric Oxygen Therapy (HBOT) Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Mesenteric Penniculitis Treatment Market