
 Thymus Cancer Treatment Market | 2026-2036
Thymus Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Thymus Cancer Treatment Market Analytics
Modular care bundles that combine surgery with adjuvant systemic therapy is repositioning how hospital purchasers evaluate total cost of care. Bristol-Myers Squibb Company leverages its immuno-oncology portfolio to anchor presence in thoracic malignancy protocols. Merck & Co., Inc. competes through broad clinical trial networks spanning rare epithelial tumors. AstraZeneca plc specializes in targeted therapy development for molecularly defined thymic carcinoma subsets.
Thymus cancer treatment encompasses multimodal interventions for neoplasms arising from thymic epithelial tissue, with platinum-based chemotherapy regimens serving as systemic backbone for advanced thymoma and thymic carcinoma cases. The primary purpose centers on achieving complete resection where anatomically feasible while managing autoimmune paraneoplastic syndromes such as myasthenia gravis. Surgery dominates as the curative-intent modality for localized disease, while targeted therapy represents the fastest-expanding segment driven by genomic profiling of refractory thymic carcinomas. Immunotherapy commands premium pricing within the drug class dimension though reimbursement remains contingent on demonstrated progression-free survival in small patient populations.
FDA orphan drug incentives and EMA rare disease frameworks shape clinical development economics by granting market exclusivity and protocol assistance for thymoma indications. NMPA accelerated review pathways in China are opening parallel registration strategies for multinational sponsors with thoracic oncology pipelines. Stakeholders must monitor biomarker-driven trial designs that could redefine patient stratification ahead of regulatory submissions.
Market Dynamics
FDA orphan drug incentives and EMA rare disease frameworks are compressing clinical development timelines for thymoma therapies, while academic medical centers consolidate multidisciplinary care into standardized bundles that reshape hospital purchasing criteria.
Growth Catalysts
- Orphan Drug Exclusivity:FDA grants seven-year market exclusivity for thymoma indications, reducing competitive risk for sponsors investing in small-population trials. This accelerates portfolio commitments from thoracic oncology developers.
- Genomic Profiling Adoption:Next-generation sequencing platforms identify actionable mutations in refractory thymic carcinomas, expanding addressable populations for targeted therapy candidates. Molecular stratification now guides patient selection for Phase II enrollment.
- Japan Referral Network Density:Concentrated mediastinal tumor expertise at National Cancer Center Hospital and Keio University Hospital generates standardized surgical volumes that attract adjuvant therapy trials. This clinical trial density shortens recruitment timelines.
Market Restraints
- Platinum Supply Concentration:South African and Russian mining operations control carboplatin and cisplatin precursor supply, exposing chemotherapy backbone regimens to geopolitical disruption and price volatility.
- Histopathological Complexity:WHO classification revisions for thymic epithelial tumors create diagnostic heterogeneity that complicates cross-trial comparability and regulatory endpoint harmonization.
- Myasthenia Gravis Management Burden:Autoimmune paraneoplastic syndrome requires specialized neurology co-management that fragments care coordination and extends hospital length-of-stay metrics.
Strategic Opportunities
- China NMPA Accelerated Pathways:Conditional approval frameworks for rare diseases enable parallel registration strategies that compress time-to-market for multinational sponsors with thoracic pipelines.
- Biomarker-Driven Trial Design:Integration of PD-L1 expression and TMB scoring with adaptive randomization protocols could redefine progression-free survival endpoints ahead of FDA submission.
- Telemedicine Prehabilitation:Remote patient monitoring platforms for myasthenia gravis symptom tracking reduce perioperative respiratory complications and expand eligible surgical populations.
Industry Challenges
- Thoracic Surgeon Training Pipeline:Fellowship positions in mediastinal oncology remain limited relative to disease incidence, constraining programmatic expansion at community hospital systems.
- Companion Diagnostic Synchronization:Parallel validation of tissue-based biomarker assays with therapeutic candidates creates regulatory interdependency risks that delay label expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thymus Cancer Treatment Market |
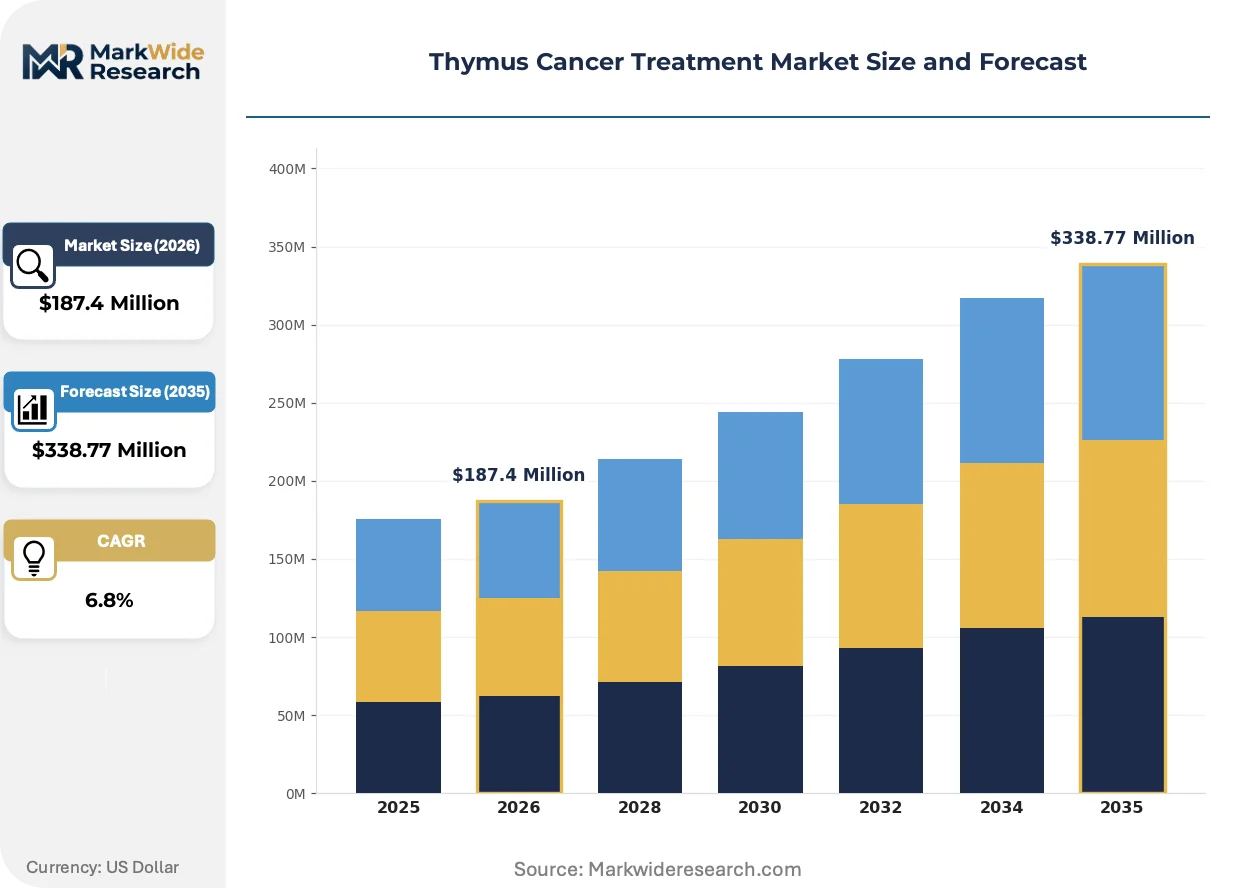
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Surgery, Radiation Therapy, Chemotherapy, Targeted Therapy Drug Class: Immunotherapy, Alkylating Agents, Antimetabolites, Tyrosine Kinase Inhibitors Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Ambulatory Surgery Centers, Research Laboratories |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., Novartis AG, Takeda Pharmaceutical Company Limited, Eli Lilly and Company, Amgen Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd., AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thymus Cancer Treatment Market Evolving Landscape
Multimodal care protocols are converging genomic stratification with surgical quality metrics, creating new competitive dimensions beyond drug efficacy alone. Three developments are compressing traditional development and delivery models.
Next-generation sequencing panels for thymic carcinoma are converging with real-world evidence platforms to identify off-label response patterns in refractory populations. Community oncology practices in Germany and Japan are adopting these tools to qualify patients for academic center trials. This convergence is compressing the interval between molecular identification and trial enrollment from months to weeks.
EMA's updated orphan drug guidelines now mandate pediatric investigation plans for thymoma therapies, extending development obligations to adolescent populations previously excluded from adult trials. Sponsors must now design age-appropriate formulations and dosing schedules that parallel adult protocols. Small biotechnology developers without pediatric capabilities are partnering with contract research organizations to meet these obligations.
Hospital purchasers are unbundling surgical episode payments from adjuvant therapy reimbursement, creating separate contracting negotiations for systemic drug procurement. Academic medical centers in the United States are consolidating these decisions into pharmacy and therapeutics committees with oncology-specific substructures. This unbundling is most visible at National Cancer Institute-designated centers where value-based oncology frameworks have achieved contractual scale.
Thymus Cancer Treatment Market Segmentation
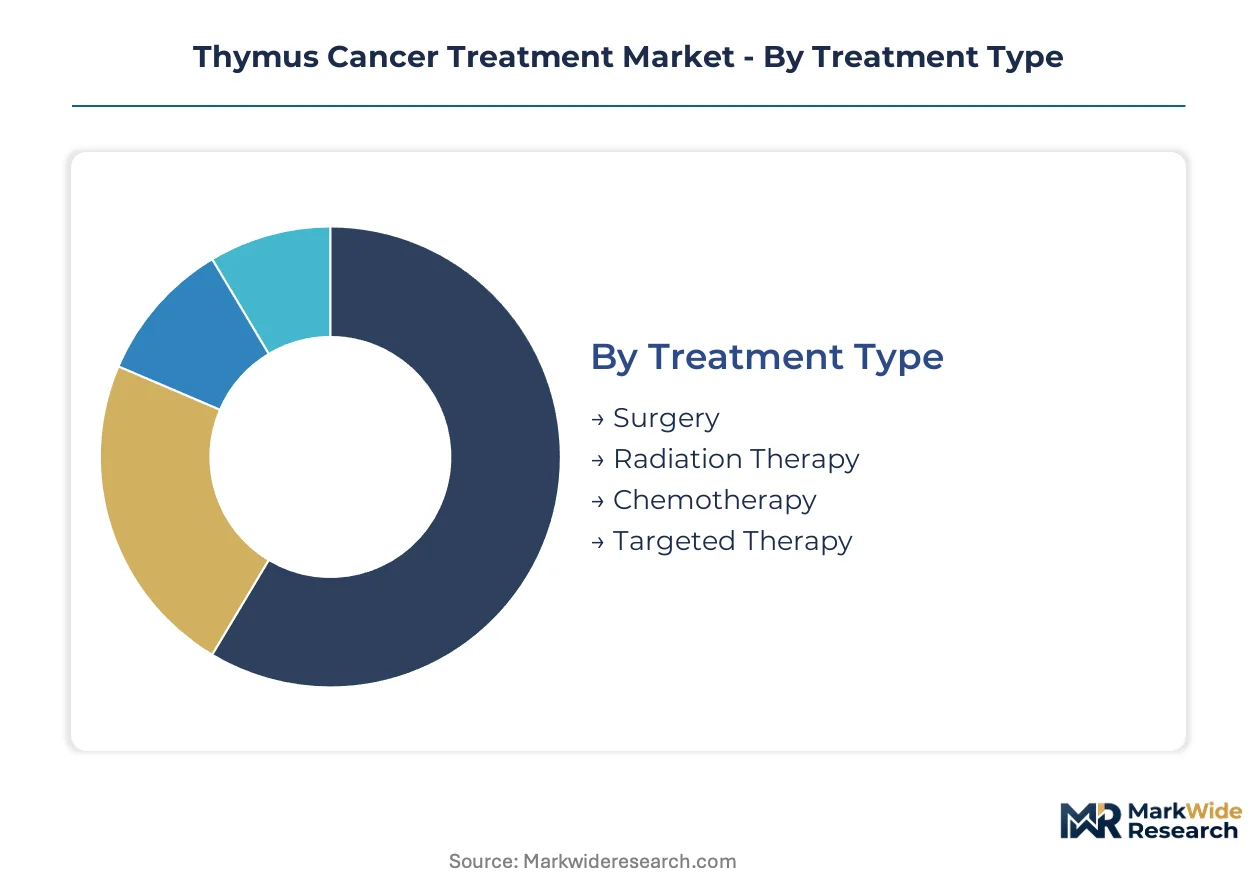
Thymus cancer treatment purchasing splits across curative-intent modalities, systemic drug classes, and care delivery settings. Hospital pharmacy committees evaluate total episode costs while academic centers prioritize genomic stratification capabilities. Understanding these decision hierarchies clarifies where manufacturers must anchor contracting and clinical evidence strategies.
Treatment Type:
Curative potential and resectability status drive hospital procurement prioritization, with complete resection feasibility determining first-line modality selection.
- Surgery:Anatomical resection of thymic epithelial tumors with negative margins remains the foundation for Masaoka-Koga Stage I-III disease. Demand clusters at National Cancer Institute-designated centers in the United States and Japan's National Cancer Center Hospital network, where robotic-assisted approaches reduce median length-of-stay.
- Targeted Therapy:Molecularly guided inhibition of actionable mutations in refractory thymic carcinoma represents the steepest expansion trajectory. Genomic profiling adoption at German comprehensive cancer centers and Keio University Hospital accelerates patient identification for KIT, EGFR, and PIK3CA-directed regimens.
- Radiation Therapy:Adjuvant and definitive photon or proton beam delivery for unresectable or margin-positive cases. Postoperative protocols at MD Anderson Cancer Center and Memorial Sloan Kettering Cancer Center establish dosing standards.
- Chemotherapy:Platinum-doublet regimens serve as systemic backbone for metastatic thymoma and first-line thymic carcinoma. Carboplatin-paclitaxel and cisplatin-doxorubicin combinations dominate adjuvant and neoadjuvant protocols.
Volume sits with Surgery; growth tilts toward Targeted Therapy.
Drug Class:
Pricing power and reimbursement complexity separate premium immuno-oncology agents from commoditized cytotoxic backbones, with PD-1/PD-L1 inhibitors commanding distinct contracting negotiations.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 and PD-L1 pathways command premium positioning contingent on progression-free survival data in small thymoma cohorts. Bristol-Myers Squibb's nivolumab and Merck's pembrolizumab anchor thoracic malignancy protocols at academic medical centers with specialized neurology co-management for myasthenia gravis.
- Tyrosine Kinase Inhibitors:Oral small-molecule inhibition of receptor tyrosine kinases enables outpatient administration for molecularly selected patients. Sunitinib and sorafenib demonstrate activity in KIT-mutant thymic carcinoma at centers with integrated molecular tumor boards.
- Alkylating Agents:Cyclophosphamide and ifosfamide remain components of salvage regimens for platinum-refractory disease. Compounding pharmacy capabilities constrain site-of-care flexibility.
- Antimetabolites:Pemetrexed and gemcitabine provide non-platinum alternatives for patients with renal dysfunction or neuropathy. Generic availability compresses margin structures.
Procurement volume concentrates in Immunotherapy; pipeline investment flows toward Tyrosine Kinase Inhibitors.
Administration Route:
Site-of-care economics and patient convenience preferences are shifting infusion-dependent regimens toward oral alternatives where bioequivalence permits.
- Intravenous:Infusion-based delivery of cytotoxic chemotherapy and monoclonal antibodies requires specialized oncology nursing and pharmacy infrastructure. Hospital outpatient departments capture revenue from carboplatin, cisplatin, and checkpoint inhibitor administration.
- Oral:Self-administered tyrosine kinase inhibitors and hormonal agents reduce treatment burden for stable disease maintenance. Adherence monitoring platforms at German cancer centers support remote management.
- Subcutaneous:Limited current application in thymoma protocols; investigational for checkpoint inhibitor formulations.
- Intramuscular:Minimal role in standard thymic epithelial tumor management; reserved for supportive care agents.
Infusion capacity dominates current utilization; oral formulations gain share in maintenance settings.
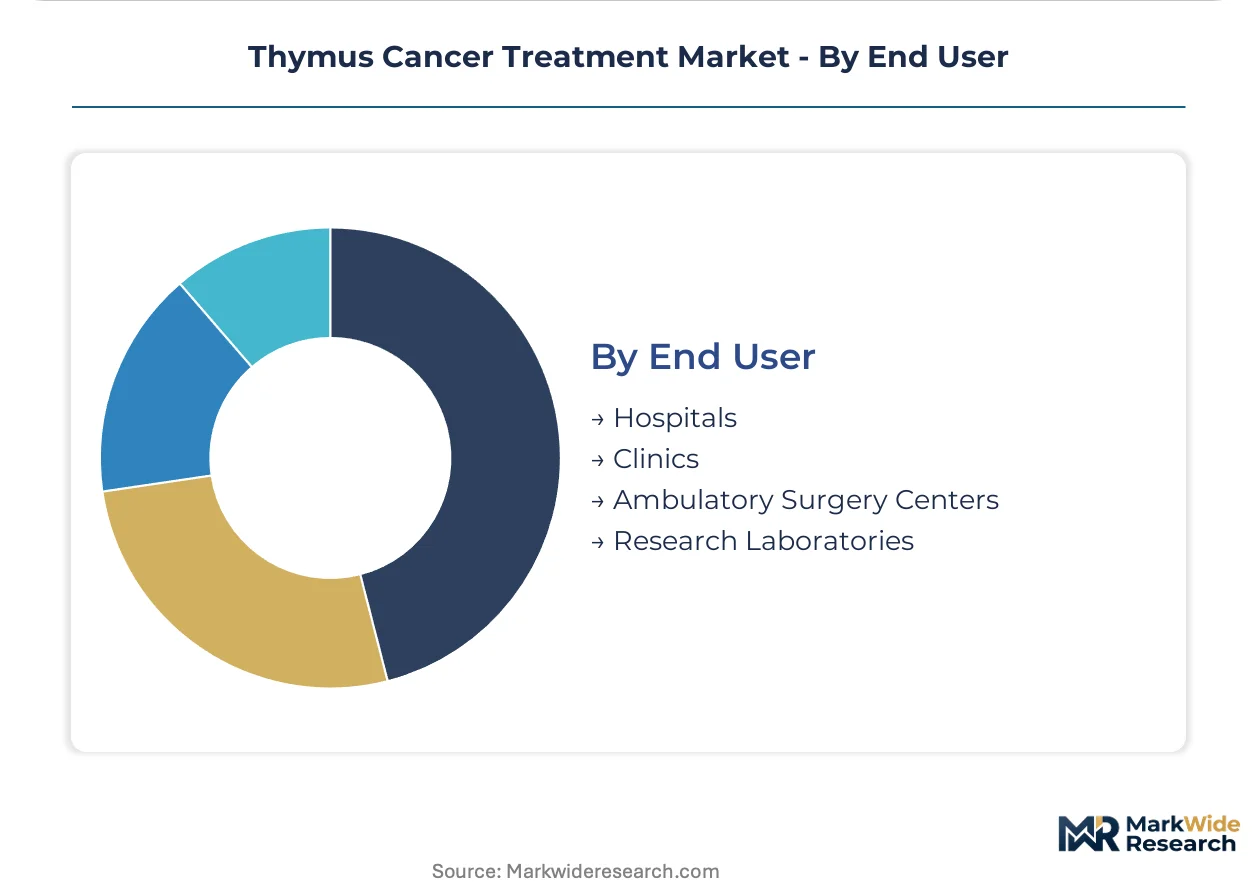
End User:
Care complexity and reimbursement rates concentrate high-value procedures at tertiary institutions, with community sites handling stable disease surveillance.
- Hospitals:Academic medical centers with multidisciplinary thoracic oncology programs perform complete resections and administer novel systemic therapies. NCI-designated cancer centers in the United States and Japan's cancer hospital network generate surgical volumes that attract adjuvant therapy trials.
- Research Laboratories:Companion diagnostic development and biomarker validation create specialized demand for tissue-based assay services. Contract research organizations partner with sponsors to meet EMA pediatric investigation plan obligations.
- Clinics:Community oncology practices in Germany participate in molecular profiling networks to qualify patients for academic center trials. Surveillance imaging and stable disease monitoring occur in lower-acuity settings.
- Ambulatory Surgery Centers:Limited role given anesthesia complexity and myasthenia gravis co-management requirements for thymoma resection.
Revenue concentrates at Hospitals; Research Laboratories expand fastest with biomarker-driven trial proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan drug tax credits in the United States and Japan's Sakigake designation system concentrate clinical development investment in these jurisdictions. FDA and PMDA incentives compress trial timelines for rare thoracic malignancies. Multidisciplinary referral networks at academic medical centers in Germany and China complete the geographic footprint.
United States
NCI-designated cancer centers generate surgical volumes that attract adjuvant therapy trials for thymoma. FDA orphan drug exclusivity grants seven-year market protection, reducing competitive risk for sponsors investing in small-population studies. Memorial Sloan Kettering Cancer Center and MD Anderson Cancer Center establish dosing standards for postoperative radiation protocols.
Japan
National Cancer Center Hospital and Keio University Hospital concentrate mediastinal tumor expertise that shortens patient recruitment timelines. PMDA's Sakigake designation accelerates priority review for thoracic oncology pipelines. Tokyo's clinical trial density enables rapid enrollment for genomic stratification studies in refractory thymic carcinoma.
Germany
Comprehensive cancer centers adopt next-generation sequencing panels to qualify patients for molecularly targeted trials. EMA orphan drug frameworks provide protocol assistance and market exclusivity for rare disease developers. Heidelberg and Munich academic networks anchor adjuvant therapy research for thymic epithelial tumors.
China
NMPA conditional approval pathways for rare diseases enable parallel registration strategies that compress time-to-market. National Cancer Center Hospital in Beijing generates standardized surgical volumes for multimodal protocol development. Shanghai's thoracic surgery programs integrate telemedicine platforms for perioperative myasthenia gravis management.
Thymus Cancer Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the thymus cancer treatment landscape. The market structure tilts toward consolidation among immuno-oncology developers with broad thoracic malignancy portfolios. Three archetypes dominate: checkpoint inhibitor specialists, targeted therapy developers with genomic stratification capabilities, and platinum-based chemotherapy suppliers with established hospital contracts. Competitive moves center on biomarker-driven trial design and multidisciplinary care bundle partnerships with academic medical centers.
Within the checkpoint inhibitor tier, Bristol-Myers Squibb Company and Merck & Co., Inc. anchor thoracic oncology protocols at academic institutions with specialized neurology co-management. AstraZeneca plc occupies a position among targeted therapy developers pursuing molecularly defined thymic carcinoma subsets. These three companies exemplify the strategic emphasis on genomic profiling integration and rare disease regulatory incentives that now determine competitive positioning in this indication.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| Novartis AG |
| Takeda Pharmaceutical Company Limited |
| Eli Lilly and Company |
| Amgen Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd. |
| AstraZeneca plc |
| Others |
Value Network & Pricing Analysis
Hospital pharmacy committee consolidation into oncology-specific substructures is compressing contracting timelines for immuno-oncology agents and forcing manufacturers toward value-based pricing frameworks that bundle surgical episode costs with adjuvant therapy reimbursement.
Pricing Analysis
Short lead-time premiums for platinum-based chemotherapy precursors command 15-25% markups over contract offtake pricing when South African or Russian supply disruptions compress spot availability. Three-tier pricing structure across originator biologics, biosimilars, and generic cytotoxics separates Bristol-Myers Squibb's nivolumab from pembrolizumab competitors and commoditized carboplatin vials. Pricing pressure stems from Medicare Part B reimbursement compression and 340B program expansion at NCI-designated centers. Community oncology practices exhibit highest price sensitivity; academic medical centers with dedicated thoracic surgery programs prioritize genomic stratification capabilities over per-vial cost.
Supply Chain Analysis
Single-source vulnerability sits with South African platinum group metal refineries and Russian palladium mining operations that feed carboplatin and cisplatin precursor synthesis. Active pharmaceutical ingredient production for alkylating agents and antimetabolites concentrates in India and China, while sterile fill-finish capacity for checkpoint inhibitors clusters in the United States, Ireland, and Singapore. Logistics chokepoint exposure runs through cold-chain distribution networks for temperature-sensitive biologics requiring -70°C storage. Hospital outpatient departments and specialty pharmacy distributors anchor downstream delivery, with limited ambulatory surgery center penetration due to myasthenia gravis co-management complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive control over companion diagnostic development to synchronize biomarker assay validation with therapeutic submission timelines.
For Market Incumbents: Extend genomic profiling platform partnerships to lock in patient identification workflows at German comprehensive cancer centers and Japan's National Cancer Center Hospital network. Deepen backward integration into tissue-based assay services to mitigate regulatory interdependency risks that delay label expansions. Counter emerging pure-play diagnostic developers by embedding CDx development within thoracic oncology trial protocols. For New Entrants and Emerging Players: Telemedicine prehabilitation platforms for myasthenia gravis symptom monitoring represent the most penetrable white-space entry point, enabling remote patient qualification for surgical eligibility expansion. Target community oncology practices in Germany participating in molecular profiling networks to qualify patients for academic center trials. Pursue hospital-at-home contracting models that reduce perioperative respiratory complications and length-of-stay metrics. For Investors and Strategic Acquirers: Re-rating potential sits with focused biomarker-driven trial design specialists given EMA's mandate for pediatric investigation plans extending development obligations to adolescent populations. Long-term viability across the analysis window favors developers with parallel registration strategies in China NMPA accelerated pathways and FDA orphan drug frameworks. Watch FDA breakthrough therapy designation grants for thymic carcinoma indications as the signal for inflection in competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Synchronization | Parallel validation of PD-L1 expression assays with pembrolizumab candidates compresses regulatory review timelines at FDA. |
| Pediatric Investigation Plan Compliance | EMA-mandated adolescent population inclusion forces partnership with contract research organizations lacking pediatric capabilities. |
| China NMPA Parallel Registration | Conditional approval frameworks for rare diseases enable multinational sponsors to compress time-to-market for thoracic pipelines. |
| Telemedicine Prehabilitation Deployment | Remote myasthenia gravis monitoring platforms at Shanghai thoracic surgery programs expand eligible surgical populations. |
| Multidisciplinary Care Bundle Integration | Academic medical center consolidation of surgical episode payments with adjuvant therapy reimbursement reshapes hospital purchasing criteria. |
Research Methodology
Multi-period observation of FDA orphan drug designation grants, EMA protocol assistance approvals, and PMDA Sakigake designations anchored the trend analysis, supplemented by interviews with thoracic oncology drug development executives, regulatory affairs leads at rare disease specialists, hospital pharmacy and therapeutics committee members, and payer access specialists. Secondary validation drew from FDA filings in the orphan drug database, EMA submissions for rare disease frameworks, ClinicalTrials.gov thoracic malignancy protocols, and formulary databases at NCI-designated cancer centers. Bottom-up patient population estimates triangulated against top-down pharmaceutical revenue attribution across treatment modalities.
Segment-weighting approaches modeled treatment type, drug class, administration route, and end-user facility tier dimensions across the projection horizon. CAGRs were derived from elasticity-adjusted volume projections and pricing scenario analysis. Forecast inputs incorporated platinum supply chain disruption probabilities, genomic profiling adoption curves at German and Japanese comprehensive cancer centers, and myasthenia gravis co-management cost trajectories.
The model holds under stable orphan drug incentive frameworks and continued academic medical center consolidation; deviation in platinum supply geopolitics or WHO histopathological classification revisions would shift addressable population definitions and trial endpoint harmonization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Lysosomal Storage Disease Treatment Market
Medical Treatment
Polycystic Ovary Syndrome (PCOS) Treatment Market
Medical Treatment
Hypercalcemia Treatment Market
Medical Treatment
Dementia and Alzheimers Disease Treatment Market
Medical Treatment
Allergy Treatment Market
Medical Treatment
Scoliosis Management Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Filariasis Treatment Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Sepsis Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Menopause Treatment Market