
 Isovaleric Acidemia Treatment Market | 2026-2036
Isovaleric Acidemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Isovaleric Acidemia Treatment Market Foresight
Single-source reliance on academic medical centers for gene therapy vectors is hardening into multi-source biomanufacturing partnerships. Amgen leverages its established biologics infrastructure to anchor production capacity for rare metabolic indications. Replimune Group Inc. specializes in oncolytic virus platforms that it adapts toward inborn errors of metabolism, competing on vector engineering expertise.
Isovaleric acidemia treatment encompasses dietary management protocols, pharmacological interventions, and emerging genetic therapies designed to correct or compensate for isovaleryl-CoA dehydrogenase deficiency, with leucine-restricted diets and glycine supplementation forming the biochemical foundation of current care. Metabolic drugs occupy the largest current revenue pool due to established reimbursement pathways, while gene therapies represent the fastest-advancing segment as viral vector manufacturing matures. Hospitals dominate end-user demand through acute crisis management protocols, though homecare delivery is expanding as oral dietary supplements gain formulation stability.
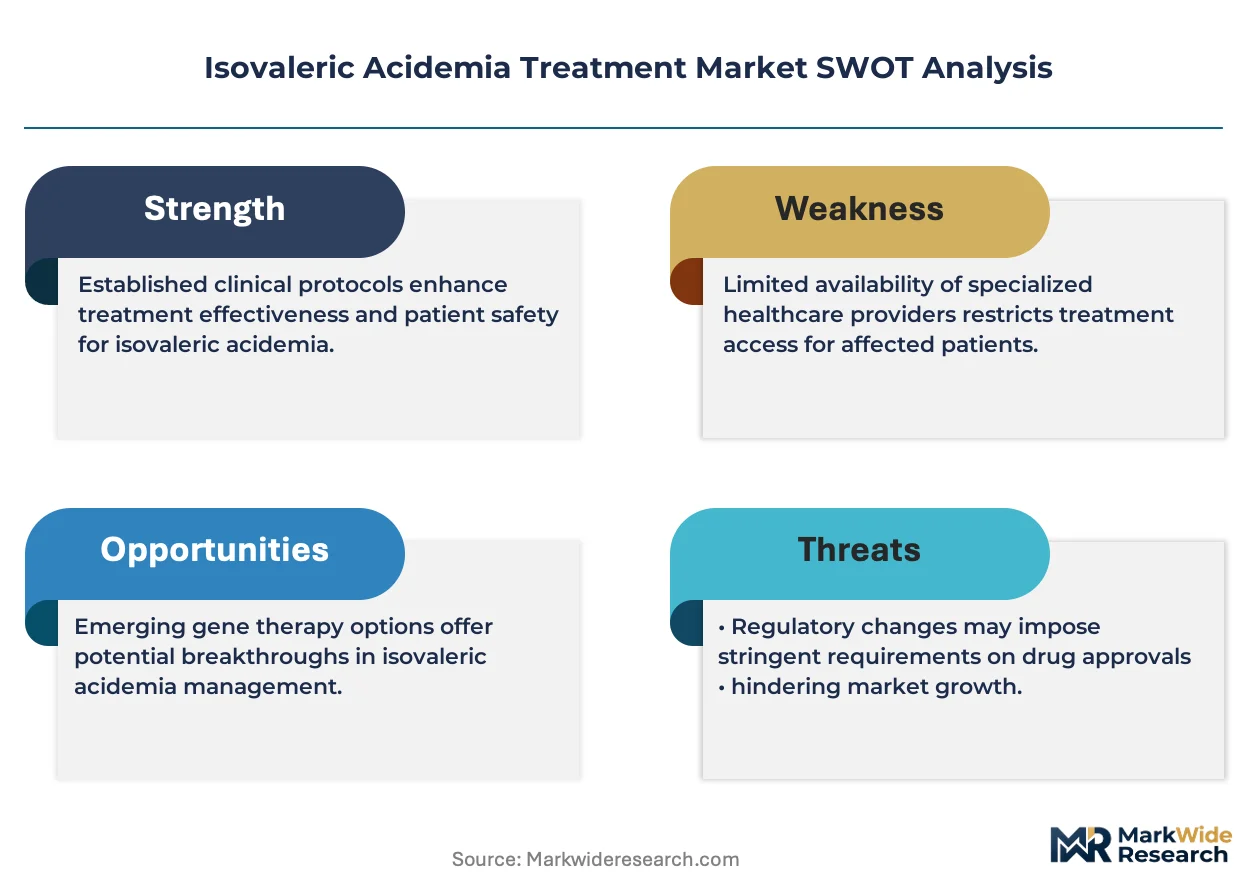
FDA orphan drug designation and EMA rare disease incentives shape clinical trial economics and market exclusivity terms for developers in this space. The EU F-Gas Regulation constrains certain cold-chain distribution methods, forcing adaptation in biologic transport protocols. Stakeholders must monitor vector manufacturing scale-up readiness and newborn screening expansion policies to time capacity investments against addressable patient identification rates.
Market Dynamics
Newborn screening program expansions and viral vector manufacturing maturation are compressing diagnosis-to-treatment timelines while reshaping competitive entry barriers for developers targeting this ultra-rare metabolic disorder.
Growth Catalysts
- FDA Orphan Drug Designation:The incentive framework accelerates clinical trial economics and extends market exclusivity terms for developers pursuing enzyme replacement and gene therapy candidates.
- Pediatric Metabolic Clinic Networks:Academic medical centers are consolidating care protocols and creating standardized referral pathways that streamline patient identification and therapy initiation.
- Leucine-Restricted Diet Formulations:Advances in medical food stability and palatability are extending homecare delivery options and reducing hospital dependency for chronic management.
Market Restraints
- EU F-Gas Regulation Constraints:Cold-chain distribution requirements for biologic therapies face adaptation costs as certain refrigerant methods phase out under environmental compliance timelines.
- Vector Manufacturing Bottlenecks:Academic medical centers retain concentrated control over gene therapy vector supply, creating single-source vulnerability for commercial-scale production.
- Reimbursement Pathway Fragmentation:Payer categorization inconsistencies across Medicaid, commercial, and rare disease funds create administrative friction for metabolic drug access.
Strategic Opportunities
- EMA Rare Disease Framework Alignment:Developers can leverage centralized European procedures and conditional marketing authorizations to compress regulatory timelines relative to standard biologics pathways.
- Homecare Channel Expansion:Oral glycine supplementation and stabilized medical food formulations enable direct-to-patient distribution models that bypass traditional hospital pharmacy procurement.
- Gene Therapy Manufacturing Partnerships:Multi-source biomanufacturing agreements with established biologics infrastructure operators reduce vector supply concentration risk.
Industry Challenges
- Patient Identification Latency:Newborn screening mandates vary by state and country, creating geographic gaps in early diagnosis that delay treatment initiation and clinical trial enrollment.
- Specialized Metabolic Genetics Expertise Scarcity:Clinical geneticists and biochemical geneticists with inborn error of metabolism specialization remain concentrated at tertiary academic centers, limiting care access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isovaleric Acidemia Treatment Market |
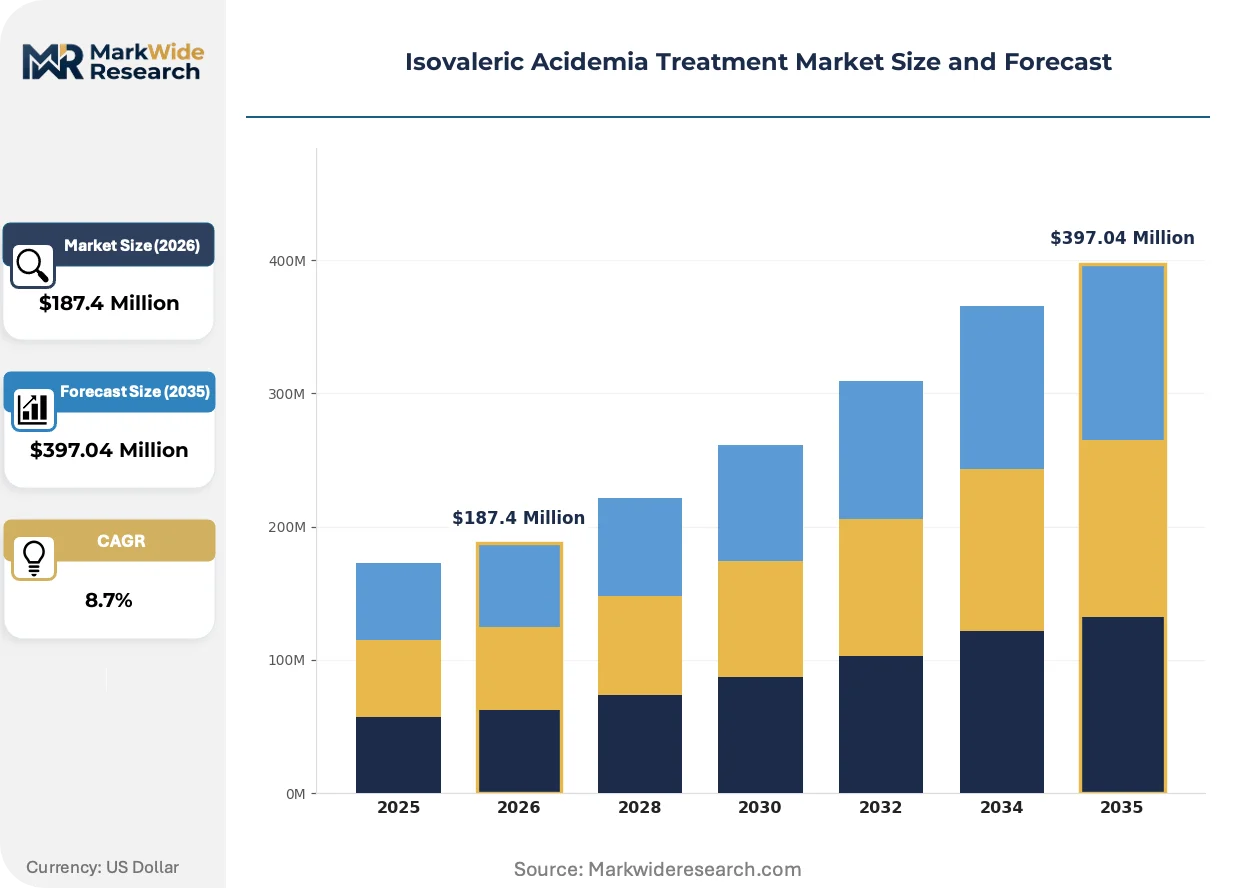
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Enzyme Therapies, Gene Therapies, Metabolic Drugs Delivery Mode: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Homecare, Specialty Clinics, Research Institutions Application: Symptomatic Treatment, Preventative Care, Emergency Intervention, Long-term Management |
| Companies Covered | Oncolys BioPharma, Lokon Pharma, Amgen, TILT Biotherapeutics, Vyriad, Replimune Group Inc., Targovax, VCNBiosciences, Transgene SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isovaleric Acidemia Treatment Market Shifts & Advancements
Gene therapy vector engineering and dietary formulation science are converging to expand therapeutic modalities beyond chronic management toward potential disease modification, while regulatory frameworks adapt to accommodate ultra-rare disease evidence standards.
Adeno-associated virus vector platforms are overtaking earlier generation delivery systems in clinical development pipelines for isovaleric acidemia. Pediatric metabolic specialists at academic medical centers are prioritizing these candidates for compassionate use protocols and early access programs. This shift is compressing development timelines for gene therapy candidates while elevating manufacturing scale-up readiness as a primary competitive differentiator.
EMA's rare disease framework and FDA's orphan drug incentives are harmonizing evidentiary standards for ultra-small patient populations. Developers now navigate accelerated assessment pathways that accept surrogate endpoints and single-arm trial designs. Gene therapy segments face the steepest adaptation requirements as regulators scrutinize long-term durability data and vector immunogenicity profiles.
Hospital-centric procurement of acute crisis interventions is fragmenting toward distributed homecare models for chronic management. Parents and caregivers of pediatric patients are driving demand for oral formulation stability and remote monitoring capabilities that reduce emergency department dependency. This behavioral shift concentrates in the United States where newborn screening mandates create the largest diagnosed patient cohorts and payer infrastructure supports medical food reimbursement.
Isovaleric Acidemia Treatment Market Segmentation
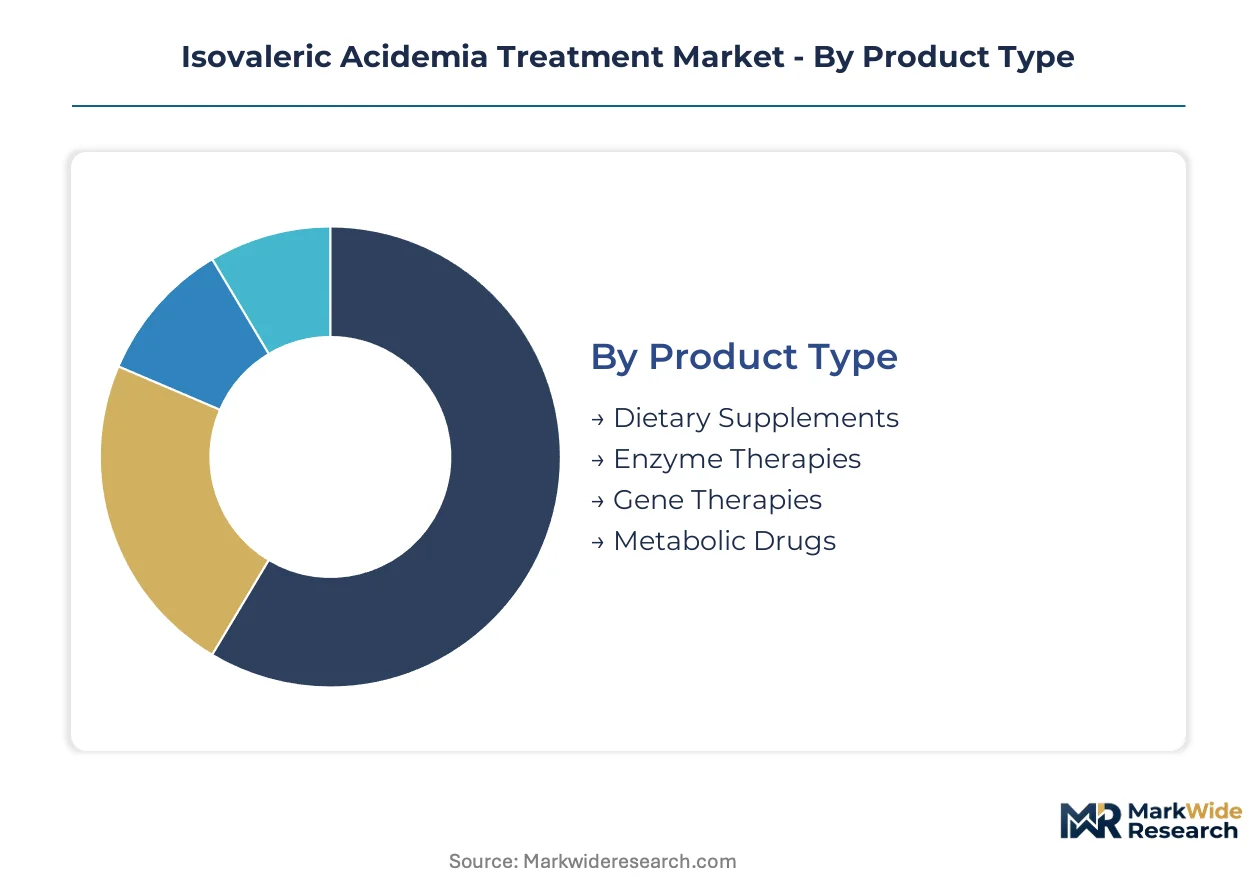
Treatment modality selection in isovaleric acidemia hinges on disease severity, patient age, and reimbursement infrastructure. Segmentation reveals how acute crisis interventions differ fundamentally from chronic management protocols in both procurement channels and clinical decision-making.
Product Type:
Cost tier separates chronic maintenance therapies from capital-intensive disease-modifying candidates.
- Metabolic Drugs:Glycine supplementation and carnitine formulations constitute the biochemical backbone of chronic management. Demand concentrates in the United States where Medicaid and commercial payers maintain established reimbursement codes for inborn errors of metabolism. FDA orphan drug incentives reinforce manufacturer commitment to this segment despite ultra-rare prevalence.
- Gene Therapies:Adeno-associated virus vector platforms deliver functional IVD gene copies to hepatocytes. Pediatric metabolic specialists at academic medical centers in Massachusetts, Pennsylvania, and California prioritize these candidates for compassionate use protocols. Manufacturing scale-up readiness determines which developers secure limited patient slots.
- Dietary Supplements:Leucine-restricted medical foods and specialized infant formulas support metabolic control.
- Enzyme Therapies:Recombinant enzyme replacement candidates remain in early clinical development.
Volume sits with Metabolic Drugs; growth tilts toward Gene Therapies.
Delivery Mode:
Application context dictates route selection, with acute decompensation requiring parenteral rescue and chronic maintenance favoring oral compliance.
- Oral:Glycine powders and leucine-restricted medical foods enable home-based chronic management. Parents and caregivers in the United States drive demand for palatable formulations that reduce emergency department dependency. Formulation stability improvements expand direct-to-patient distribution options.
- Intravenous:L-carnitine and glucose infusions reverse acute metabolic crises during hospital admission. Demand concentrates at tertiary pediatric centers with dedicated metabolic genetics units. Reimbursement pathway fragmentation across Medicaid and commercial plans creates administrative friction for access.
- Injectable:Subcutaneous enzyme preparations are under investigation.
- Transdermal:Novel delivery mechanisms remain preclinical.
Patient preference favors Oral; clinical necessity preserves Intravenous.
End User:
Customer type determines procurement complexity, with hospital pharmacy committees imposing distinct evaluation criteria from homecare distributors.
- Hospitals:Acute crisis management protocols require immediate availability of IV carnitine and metabolic emergency kits. Pediatric metabolic specialists at academic medical centers standardize care pathways that streamline therapy initiation. Specialized biochemical genetics expertise scarcity limits expansion beyond tertiary referral networks.
- Homecare:Oral glycine supplementation and stabilized medical food formulations bypass traditional hospital procurement. Direct-to-patient distribution models gain traction where payer infrastructure supports medical food reimbursement. Remote monitoring capabilities reduce emergency department utilization.
- Specialty Clinics:Consolidated metabolic genetics practices coordinate chronic care.
- Research Institutions:Gene therapy clinical trial sites concentrate vector manufacturing partnerships.
Revenue concentrates at Hospitals; channel expansion favors Homecare.
Application:
Maturity gradient separates established symptomatic protocols from emerging preventative strategies.
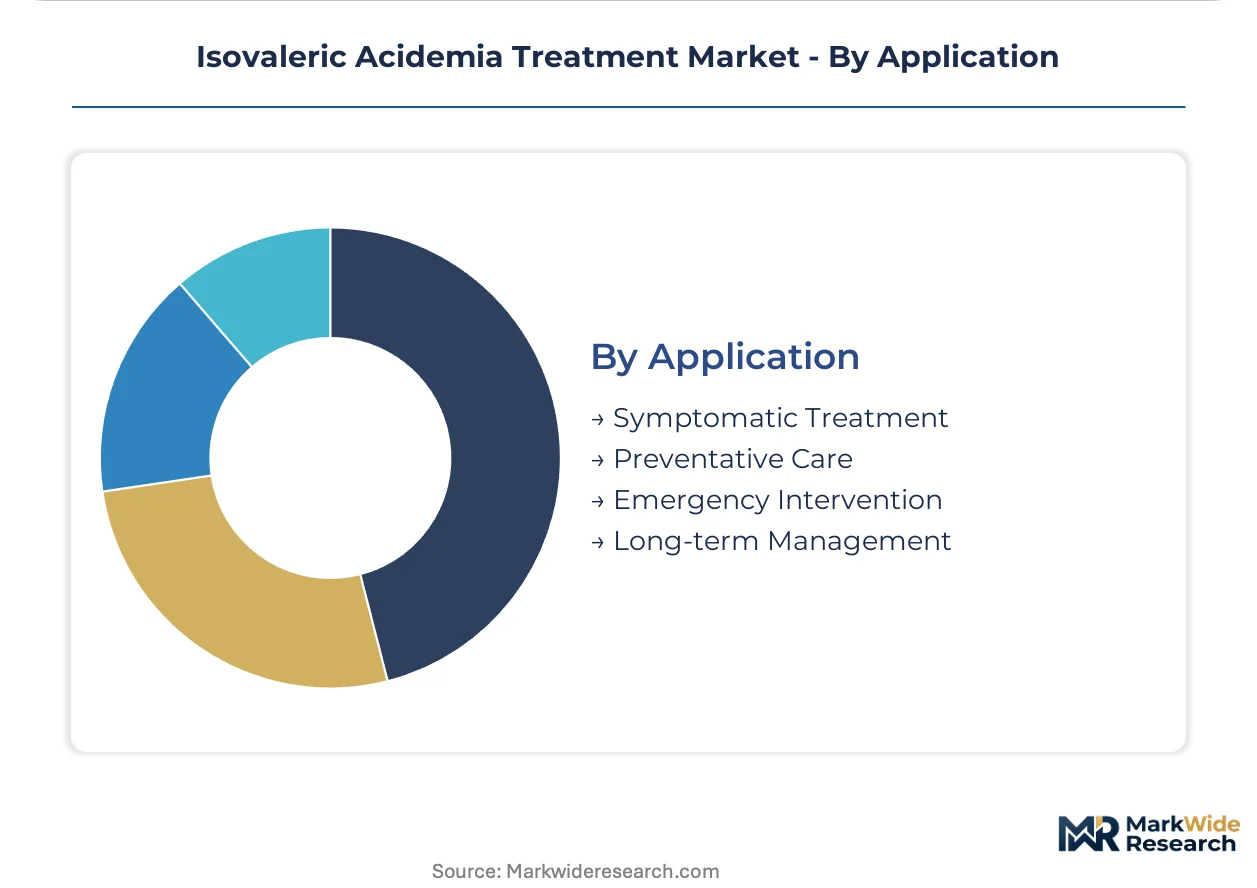
- Long-term Management:Chronic leucine restriction and glycine supplementation prevent cumulative neurological damage. Newborn screening program expansions compress diagnosis-to-treatment timelines, enlarging the addressable patient cohort for maintenance therapies. State-level mandate variations create geographic gaps in early identification.
- Emergency Intervention:Acute decompensation protocols reverse metabolic acidosis and prevent cerebral edema. Hospital-based pediatric intensive care units maintain ready access to IV glucose, carnitine, and anion gap monitoring. Caregiver education gaps delay appropriate escalation.
- Symptomatic Treatment:Addresses acute manifestations during metabolic crises.
- Preventative Care:Gene therapy candidates aim to eliminate crisis risk entirely.
Investment flows toward Preventative Care; clinical volume remains with Long-term Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnosed patient concentrations cluster in jurisdictions with comprehensive newborn screening mandates and established pediatric metabolic genetics infrastructure. The United States maintains the largest addressable cohort through state-level screening expansion. Germany and Japan anchor European and Asian demand through specialized academic medical networks.
United States
State-level newborn screening mandates in Massachusetts, Pennsylvania, and California generate the world's largest diagnosed pediatric cohort. FDA orphan drug designation accelerates clinical trial economics and extends market exclusivity for enzyme replacement candidates. Boston Children's Hospital and Children's Hospital of Philadelphia anchor gene therapy vector manufacturing partnerships.
Germany
EMA centralized procedures and conditional marketing authorizations compress regulatory timelines for metabolic drug developers. The EU F-Gas Regulation constrains cold-chain distribution methods, forcing biologic transport protocol adaptations. Heidelberg and Munich academic medical centers concentrate biochemical genetics expertise and compassionate use program administration.
Japan
PMDA's Sakigake designation system prioritizes review of rare disease gene therapies with surrogate endpoint acceptance. METI funding programs support domestic vector manufacturing capacity expansion. Tokyo and Osaka pediatric metabolic clinics standardize care pathways for leucine-restricted diet management.
United Kingdom
NHS England's specialized commissioning framework consolidates funding for ultra-rare metabolic conditions at designated centers. MHRA post-Brexit regulatory autonomy enables accelerated access schemes for gene therapy candidates. Manchester and London academic hospitals coordinate national newborn screening quality assurance.
Canada
Provincial newborn screening program variations create geographic diagnosis gaps, with Ontario and Quebec maintaining the most comprehensive panels. Health Canada's orphan drug framework parallels FDA incentives for rare metabolic indications. Toronto's Hospital for Sick Children anchors national biochemical genetics referral networks.
Isovaleric Acidemia Treatment Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers secure vector manufacturing capacity and academic medical center access. The market exhibits tiered concentration with established biologics infrastructure operators anchoring production scale-up, while specialized viral vector engineering firms compete on platform adaptation expertise. Two archetypes predominate: diversified biologics manufacturers with rare disease metabolic portfolios, and oncolytic virus platform specialists pivoting toward inborn errors of metabolism. Capacity expansion and multi-source biomanufacturing agreements constitute the primary competitive moves.
Among established biopharmaceutical operators, Amgen occupies a position representing diversified biologics infrastructure leveraged for rare metabolic indications. Replimune Group Inc. exemplifies the viral vector engineering specialist archetype, with its platform adaptation capabilities competing on delivery system innovation. Within the gene therapy manufacturing tier, Transgene SA anchors European vector production expertise.
| Leading Market Players |
|---|
| Oncolys BioPharma |
| Lokon Pharma |
| Amgen |
| TILT Biotherapeutics |
| Vyriad |
| Replimune Group Inc. |
| Targovax |
| VCNBiosciences |
| Transgene SA |
| Others |
Supply & Pricing Matrix
Captive vector manufacturing partnerships anchor both supply security and pricing power for gene therapy developers targeting this ultra-rare metabolic disorder. Amgen's backward integration into biologics infrastructure and academic medical center alliances insulate production capacity from third-party volatility while supporting premium positioning for disease-modifying candidates.
Pricing Analysis
Warranty and service bundling separates gene therapy candidates from chronic management protocols. Three-tier pricing structure across premium gene therapies, standard metabolic drugs, and economy dietary supplements reflects reimbursement pathway maturity. FDA orphan drug exclusivity supports premium tiers in the United States where Medicaid and commercial payers maintain established codes. Price differentiation hinges on clinical evidence durability and manufacturing scale-up readiness. Cost compression in oral medical food tiers intensifies as formulation stability expands direct-to-patient distribution. Homecare channels exhibit highest price sensitivity; hospital procurement committees show lowest sensitivity for acute crisis interventions.
Supply Chain Analysis
Single-source vulnerability sits with academic medical centers in Massachusetts, Pennsylvania, and California that retain concentrated viral vector production expertise. Manufacturing draws from plasmid DNA suppliers in the United States, cell culture media producers in Germany, and specialized cryogenic logistics operators in Japan. Raw material dependencies include recombinant enzymes, synthetic amino acid formulations, and AAV serotype-specific packaging cell lines. Tariff exposure on European-sourced bioreactor components elevates cost structures for domestic scale-up. Distribution runs through hospital pharmacy committees for acute interventions and direct-to-patient channels for chronic maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy vector platforms are displacing chronic dietary management as the dominant therapeutic modality, compressing development timelines while elevating manufacturing readiness as the critical success determinant.
For Market Incumbents: Deploy multi-source biomanufacturing agreements to neutralize vector supply concentration risk. Amgen anchors production capacity through established biologics infrastructure while Replimune Group Inc. competes on platform engineering specialization. Capacity addition in Germany and Japan reduces single-geography exposure. Certification investment in EMA centralized procedures accelerates European market access against emerging viral vector specialists.
For New Entrants and Emerging Players: Capture homecare distribution white space where oral glycine supplementation and stabilized medical food formulations bypass hospital procurement. The United States presents the most penetrable geography given newborn screening mandate expansion and Medicaid reimbursement infrastructure. Direct-to-patient models with remote monitoring capabilities address caregiver demand for reduced emergency department dependency.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-specialist acquisitions by diversified biopharmaceutical operators seeking rare disease metabolic portfolios. Long-term viability rests on vector manufacturing scale-up execution rather than clinical trial advancement alone. Manufacturing readiness signals from academic medical center partnerships indicate inflection points for valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Multi-source biomanufacturing agreements with Amgen reduce vector supply concentration vulnerability. |
| EMA Centralized Procedure Alignment | Conditional marketing authorizations compress regulatory timelines relative to standard biologics pathways. |
| Homecare Channel Expansion | Direct-to-patient distribution models bypass hospital pharmacy procurement for oral chronic therapies. |
| Newborn Screening Policy Advocacy | State-level mandate expansion enlarges addressable patient cohorts for maintenance therapies. |
| Vector Engineering Platform Adaptation | Replimune Group Inc.'s oncolytic expertise transfers to inborn error of metabolism delivery systems. |
Research Methodology
FDA orphan drug filings, EMA centralized procedure submissions, and ClinicalTrials.gov records formed the secondary backbone for pipeline and regulatory tracking. Primary interviews with pediatric metabolic specialists, gene therapy manufacturing executives, hospital formulary directors, and rare disease payer access specialists validated development timelines and reimbursement assumptions. Bottom-up patient cohort modeling triangulated against top-down market sizing from metabolic drug transaction data.
Bottom-up volume estimates anchored forecast construction, with top-down regulatory pathway analysis cross-validating commercial timing assumptions. Segmentation dimensions included treatment modality, delivery route, end-user channel, and regional regulatory cluster. CAGRs derived from patient identification rate projections and therapy adoption curves across the analysis window. Gene therapy manufacturing readiness scores and newborn screening expansion policies served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to vector immunogenicity profiles and durability data emergence. Assumptions reflect current FDA and EMA evidentiary standards for ultra-rare disease indications, with revision triggers including regulatory guidance shifts on surrogate endpoint acceptance. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Necrotizing Skin Infections Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Scalp Care Treatment Market
Medical Treatment
Global Autoimmune Treatment Market
Medical Treatment
Adenomyosis Treatment Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Global Medication Management Market
Medical Treatment
Peri-Implantitis Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
Hereditary Amyloidosis Treatment Market
Medical Treatment
ALAD Porphyria Treatment Market