
 Japan Pharmaceutical Market | 2026-2036
Japan Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Pharmaceutical Market Outlook
Biologics manufacturing is fragmenting across cell-line platforms, single-use bioreactors, and continuous processing technologies. Takeda Pharmaceutical Company Limited anchors Japan's plasma-derived and rare disease portfolio through backward integration into blood fractionation. Chugai Pharmaceutical Co. Ltd leverages Roche's global antibody engineering network while sustaining domestic oncology leadership. Daiichi Sankyo Company Ltd differentiates through antibody-drug conjugate pipelines and in-house payload-linker chemistry.
Japan pharmaceuticals encompass chemically synthesized small molecules, recombinant proteins, vaccines, and nucleic acid therapeutics formulated to meet pharmacopeial purity standards and stability profiles for parenteral or oral administration. These products treat acute and chronic diseases under prescribed or self-care protocols. Prescription medicines and biologics command the deepest margin pools as hospitals absorb high-cost oncology and immunology therapies. Generic drugs face sustained price erosion under Japan's biennial reimbursement cuts while online pharmacies gain structural share from regulatory easing of remote dispensing rules.
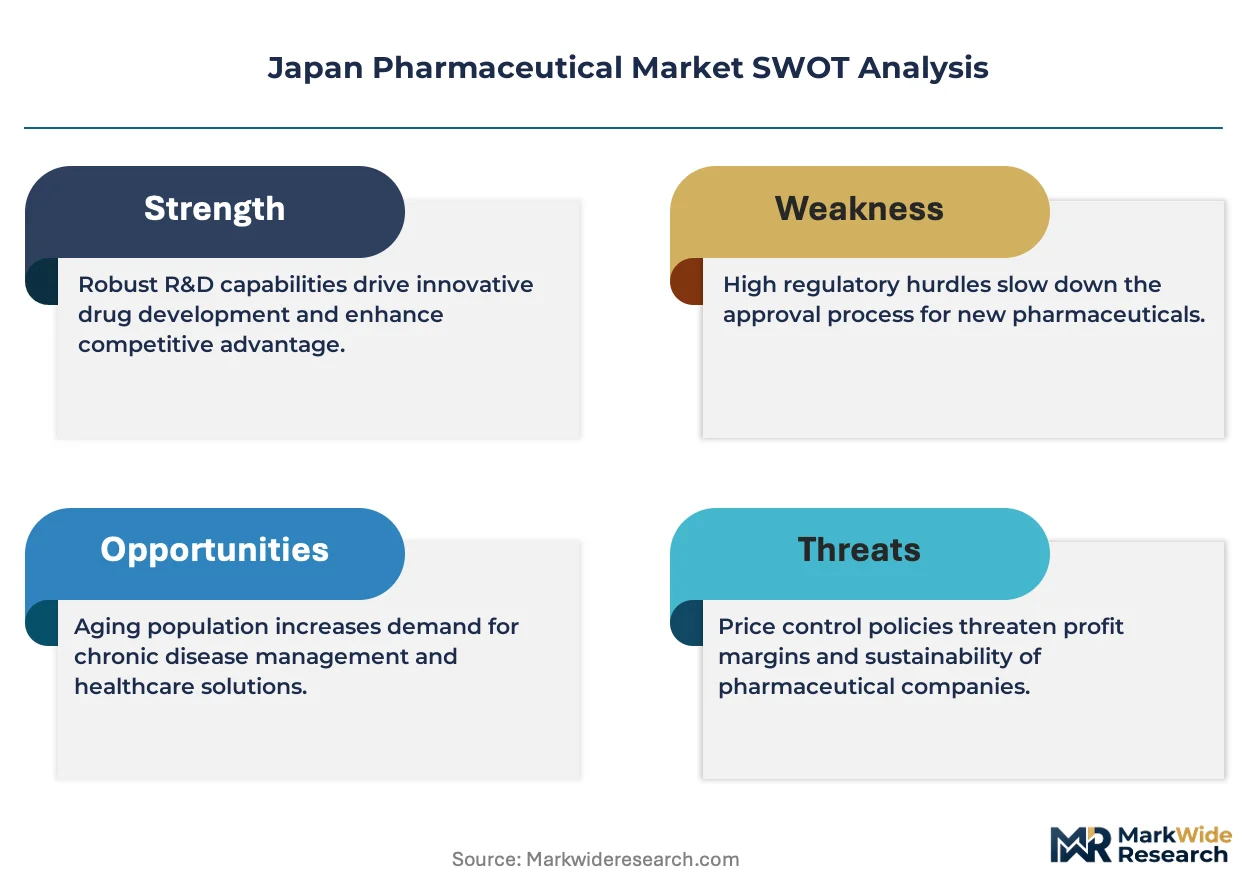
PMDA enforces ICH-aligned quality standards and post-market surveillance through the GQP and GVP frameworks. METI coordinates industrial policy under the Bio-Strategy to secure domestic vaccine and biologics supply chains. Stakeholders must monitor how Japan's NHI price revision cycle and PMDA consultation pathway timelines reshape investment thresholds for novel modalities.
Market Dynamics
PMDA's Sakigake designation system compresses approval timelines for first-in-class therapies, while METI's Bio-Strategy redirects domestic manufacturing capacity toward mRNA and cell-therapy platforms. Biennial NHI price revisions force portfolio restructuring toward high-value biologics.
Growth Catalysts
- Sakigake Accelerated Pathway:PMDA grants priority review and pre-application consultation to innovative drugs addressing unmet medical needs. Oncology and rare disease developers leverage this to compress time-to-market by 12-18 months versus standard review.
- Plasma Collection Infrastructure:Domestic blood fractionation capacity expansion under METI industrial policy secures supply chains for immunoglobulin and albumin products. Takeda's backward integration into plasma sourcing anchors this vertical.
- Greater Tokyo Specialist Concentration:University hospitals in the metropolitan corridor cluster advanced oncology and immunology expertise. Patient referral networks concentrate demand for high-complexity biologics within this geography.
Market Restraints
- Biennial NHI Price Cuts:Japan's Ministry of Health, Labour and Welfare mandates mandatory price reductions on all reimbursed products every two years. Generic manufacturers face margin compression exceeding 50% over a product's lifecycle.
- Active Pharmaceutical Ingredient Dependence:Over 80% of small-molecule APIs originate from Chinese and Indian suppliers. Geopolitical friction or export restrictions threaten continuous production of chronic disease therapies.
- Clinical Trial Site Scarcity:Limited investigator-initiated trial infrastructure and competing demands from global sponsors constrain patient recruitment. Oncology trials face particular bottlenecks in first-line settings.
Strategic Opportunities
- Kansai Biomedical Corridor:Osaka and Kyoto prefectures host underutilized manufacturing parks with JIS-compliant infrastructure. Prefectural governments offer tax incentives for cell-therapy and gene-therapy facility investments.
- Remote Dispensing Regulatory Easing:Revised pharmaceutical laws permit online pharmacies to dispense chronic disease medications without physical storefronts. Digital health platforms capture share from traditional drugstore chains.
- Antibody-Drug Conjugate Convergence:Payload-linker chemistry expertise combines with monoclonal antibody production capabilities. Domestic ADC pipelines target HER2, TROP2, and novel tumor-associated antigens with differentiated cytotoxic payloads.
Industry Challenges
- Bioprocess Engineering Talent Gap:Continuous manufacturing and single-use bioreactor operations require specialized skill sets. Japanese universities produce insufficient graduates with combined biochemical engineering and GMP compliance training.
- Legacy ERP Integration Friction:Established manufacturers operate on decades-old manufacturing execution systems. Cloud-based batch record systems face implementation delays due to validation complexity under PMDA GQP requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Pharmaceutical Market |
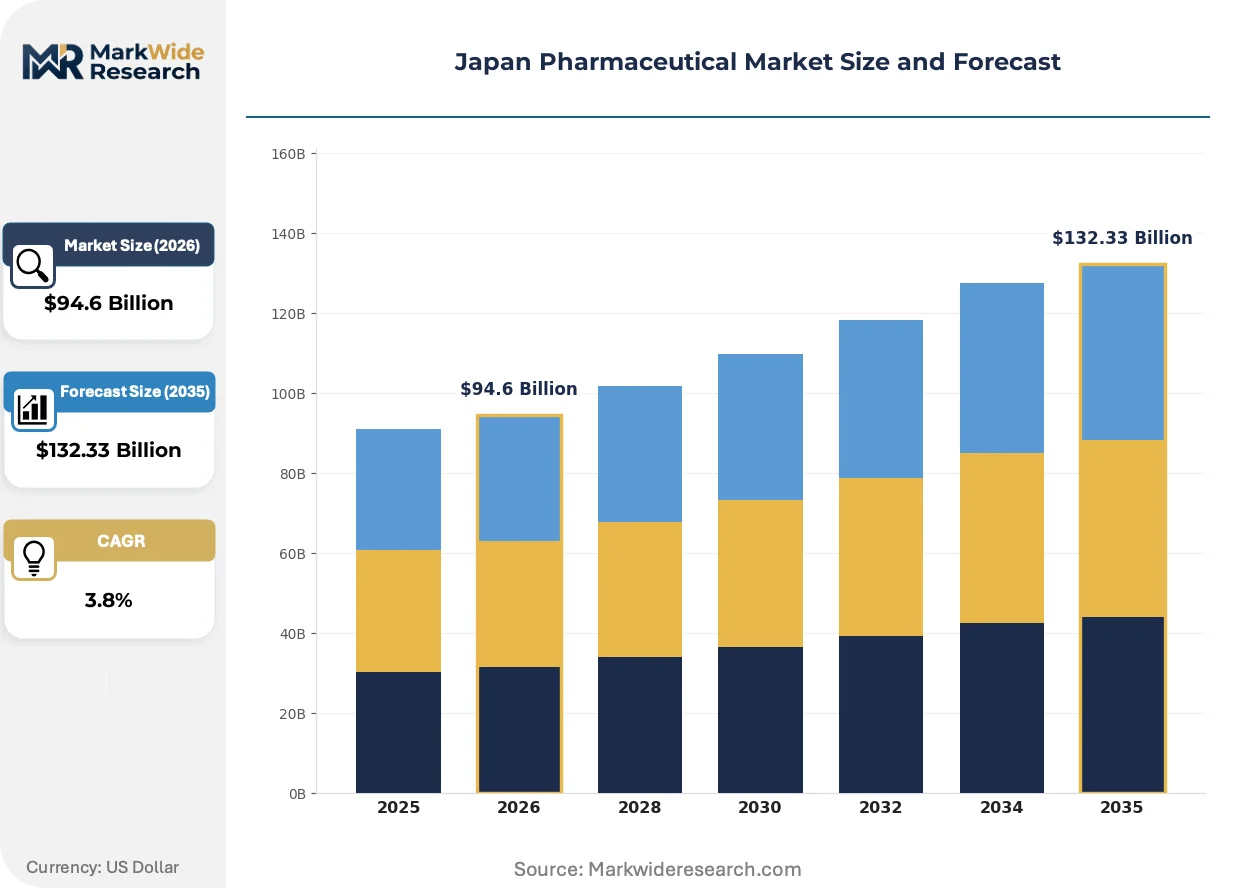
| Market Size in 2026 | $94.6 Billion |
| Market Size in 2035 | $132.33 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generic Drugs, Over-the-Counter, Biologics, Prescription Medicines Therapy Area: Cardiology, Oncology, Neurology, Infectious Diseases Distribution Channel: Retail Pharmacies, Hospitals, Online Pharmacies, Wholesalers Customer Type: Healthcare Professionals, Patients, Insurers, Pharmacy Chains |
| Companies Covered | Otsuka Holdings Co Ltd, Chugai Pharmaceutical Co. Ltd, Takeda Pharmaceutical Company Limited, Sumitomo Pharma Co., Ltd., Kyowa Kirin Co., Ltd., Astellas Pharma Inc, Eisai Co Ltd, Shionogi & Co., Ltd., Daiichi Sankyo Company Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Pharmaceutical Market Strategic Shifts
Digital twin technology is virtualizing process development workflows, compressing tech transfer timelines from clinical to commercial scale. Regulatory science harmonization and patient-centric trial design reshape how therapies reach Japanese patients.
Digital twin platforms replicate bioreactor performance, purification cascades, and fill-finish operations in silico before physical validation runs. Takeda and Chugai deploy these systems for scale-up prediction and deviation root-cause analysis. This capability is virtualizing traditional pilot-plant requirements, allowing direct progression from bench to commercial manufacturing with reduced material waste and accelerated timeline compression.
PMDA's implementation of ICH E6(R2) guidelines mandates risk-based monitoring and centralized data oversight for all new drug applications. Contract research organizations restructure site management models toward remote source data verification. Oncology sponsors face the steepest compliance burden as adaptive trial designs require real-time safety database integration and protocol amendment agility.
Hospital pharmacy committees increasingly consolidate purchasing decisions through regional formulary networks. Chugai and Daiichi Sankyo field specialized key account managers who negotiate directly with these consolidated buyers, displacing traditional wholesaler-mediated relationships. This concentration is most pronounced in the Greater Tokyo corridor where university hospital alliances synchronize procurement for high-cost immunology and oncology biologics.
Japan Pharmaceutical Market Segmentation
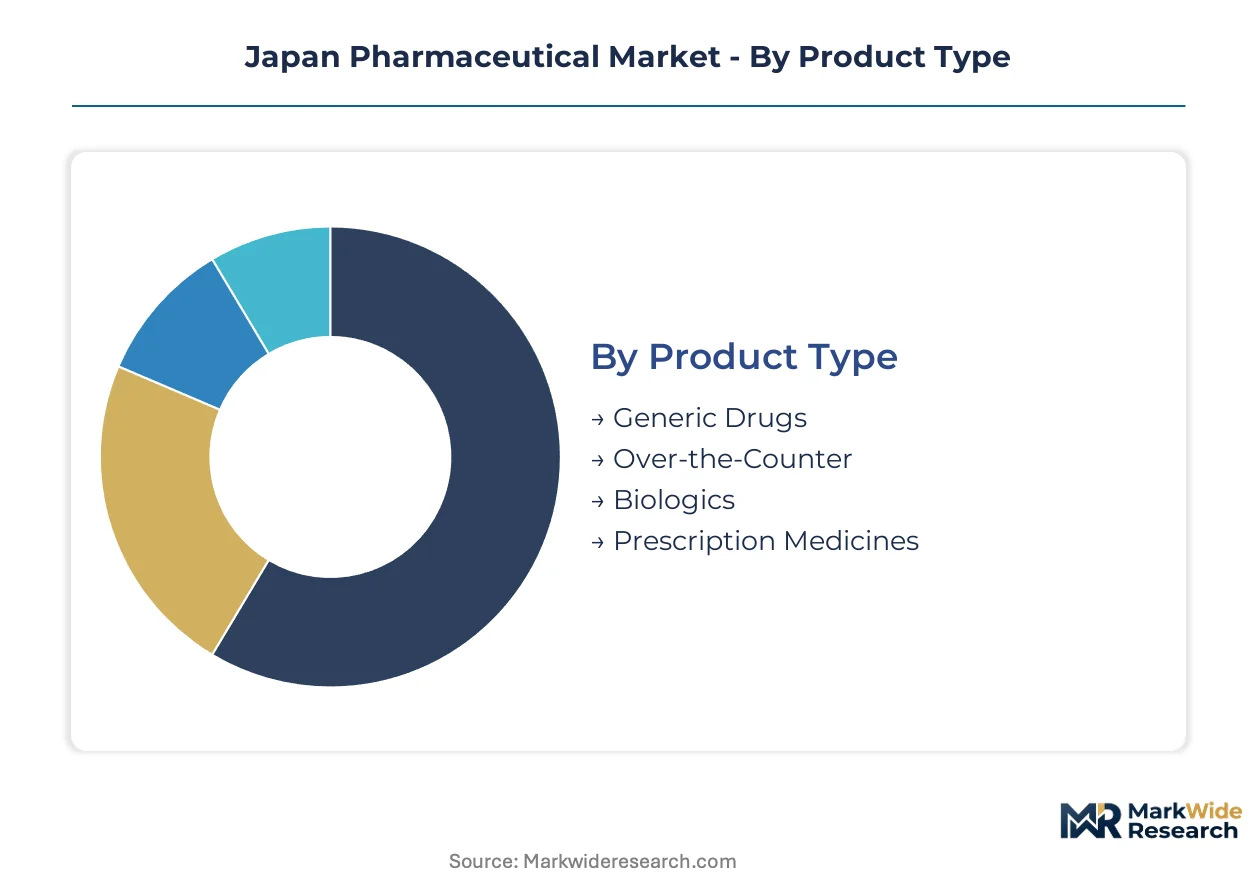
Japan's pharmaceutical segmentation reveals divergent margin profiles and regulatory exposure across product categories. Cycle times vary dramatically between biologics with decade-long development horizons and generics facing biennial price compression.
Product Type:
Biologics command extended development cycles measured in years while generic portfolios turn over rapidly under NHI price revision pressure.
- Biologics:Recombinant proteins, monoclonal antibodies, and plasma-derived therapeutics manufactured through cell culture or blood fractionation. Demand clusters in Greater Tokyo university hospitals where oncology and immunology specialists administer high-complexity therapies under PMDA Sakigake accelerated pathways.
- Prescription Medicines:Chemically synthesized small molecules and nucleic acid therapeutics meeting JIS pharmacopeial standards for purity and stability. Chronic disease formulations for cardiology and diabetes concentrate prescription volume in metropolitan corridor clinics with established specialist referral networks.
- Generic Drugs:Bioequivalent small-molecule copies subject to biennial NHI price cuts exceeding 50% over product lifecycles. Manufacturers compete on production scale and API sourcing efficiency rather than innovation.
- Over-the-Counter:Self-care formulations for analgesics, gastrointestinal, and dermatological conditions distributed through drugstore chains and convenience retail. Regulatory burden remains lighter than prescription categories under PMDA GQP frameworks.
Prescription medicines dominate installed base. Biologics are where expansion concentrates.
Therapy Area:
Oncology and cardiology represent opposite ends of the cost spectrum, with cancer biologics capturing premium reimbursement against commoditized cardiovascular generics.
- Oncology:Antibody-drug conjugates, immune checkpoint inhibitors, and targeted small molecules addressing HER2, TROP2, and novel tumor-associated antigens. University hospitals in Osaka and Tokyo prefectures anchor clinical trial recruitment and commercial adoption under PMDA priority review.
- Cardiology:Statins, anticoagulants, and antihypertensives facing intense generic competition and price erosion. Chronic disease management protocols drive volume through hospital outpatient departments and retail pharmacy chains.
- Neurology:Therapeutics for Alzheimer's disease, Parkinson's disease, and multiple sclerosis requiring specialized diagnostic infrastructure. Patient access concentrates in tertiary referral centers with neuroimaging capabilities.
- Infectious Diseases:Antivirals, antibiotics, and vaccines including mRNA platforms prioritized under METI Bio-Strategy domestic supply chain initiatives. Pandemic preparedness programs sustain procurement commitments beyond commercial market dynamics.
Cardiology commands largest prescription volume. Oncology claims steepest expansion trajectory.
Distribution Channel:
Hospital procurement exhibits longest decision cycles through pharmacy committee formulary reviews, while online pharmacies respond instantly to regulatory easing.
- Hospitals:Institutional purchasing through regional formulary networks consolidating decisions across university hospital alliances. Greater Tokyo corridor buyers negotiate directly with manufacturers for high-cost biologics, displacing traditional wholesaler mediation.
- Retail Pharmacies:Community-based dispensing for chronic disease maintenance therapies and acute condition treatments. Chains compete on location density and pharmacist consultation services under NHI reimbursement frameworks.
- Online Pharmacies:Digital platforms capturing share from regulatory revisions permitting remote dispensing without physical storefronts. Chronic disease medication refills migrate fastest to this channel among urban patient populations.
- Wholesalers:Logistics intermediaries facing margin compression as hospital consolidation and direct manufacturer negotiations erode traditional intermediary roles. Inventory management and cold-chain capabilities remain critical for biologics distribution.
Hospitals dominate biologics procurement. Online pharmacies are where structural share gains concentrate.
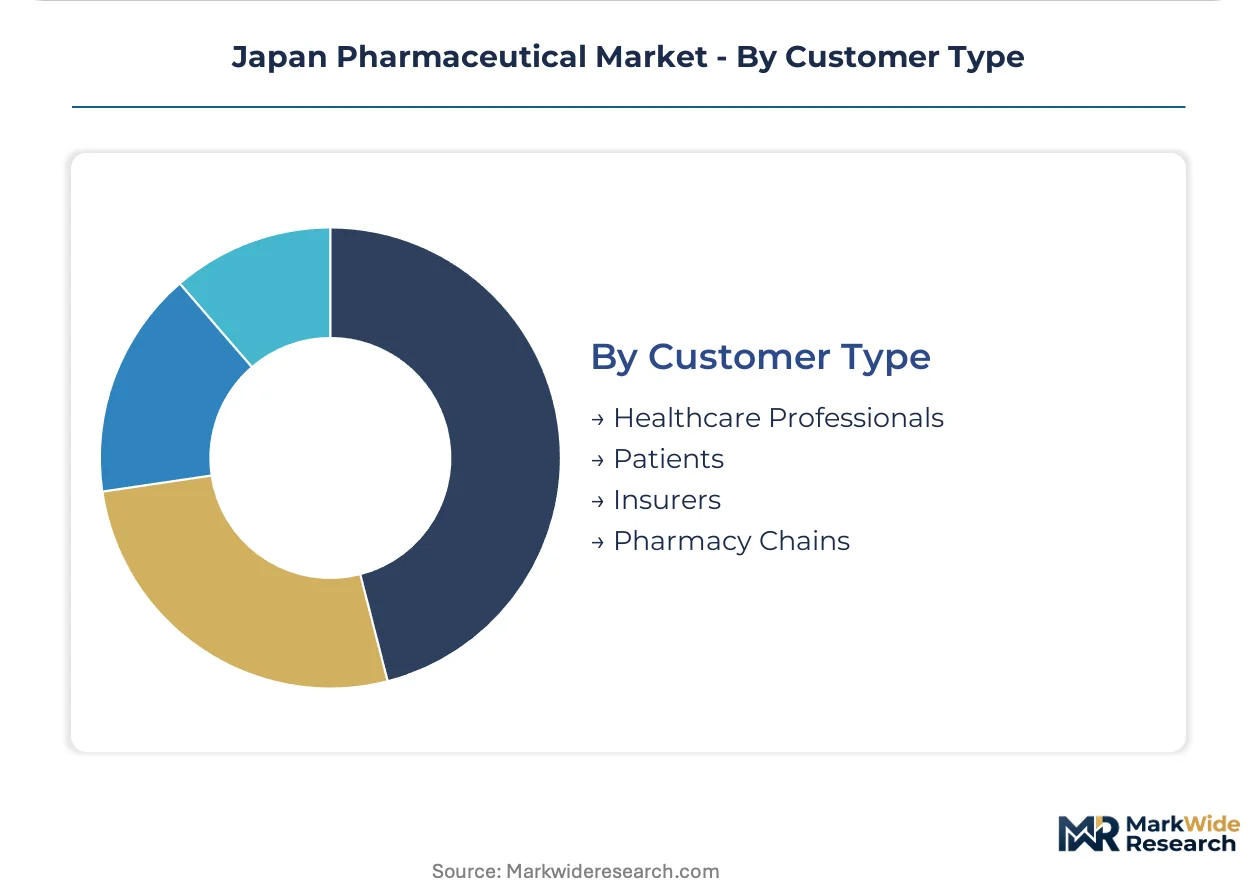
Customer Type:
Insurers and pharmacy chains operate on opposing incentive structures, with NHI payers driving cost containment against retail buyers seeking margin expansion.
- Healthcare Professionals:Prescribing physicians in university hospitals and specialist clinics determining therapy selection through clinical evidence and formulary compliance. Oncology and immunology specialists hold disproportionate influence over high-value biologics adoption.
- Insurers:NHI payers and supplemental health insurers applying cost-effectiveness thresholds and biennial price revision mandates. Reimbursement decisions cascade through Ministry of Health, Labour and Welfare policy implementation.
- Pharmacy Chains:Consolidated retail buyers negotiating generic procurement and over-the-counter assortment. Scale operators invest in central fill facilities and digital prescription management platforms.
- Patients:End consumers with limited direct price exposure under NHI coverage, though co-payment structures influence adherence and brand preference in self-pay categories.
Healthcare professionals dominate therapy selection authority. Pharmacy chains are where purchasing consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's pharmaceutical trade balance tilts toward import dependency for active pharmaceutical ingredients while finished dosage exports concentrate in biologics and specialty therapeutics. Metropolitan corridors anchor domestic demand absorption. Prefectural industrial policies reshape manufacturing geography.
Kanto/Tokyo
Greater Tokyo's university hospital alliances drive biologics procurement consolidation under regional formulary networks. METI's Bio-Strategy directs mRNA manufacturing investments toward Kanto-based facilities. The Keihin industrial corridor hosts Takeda's plasma fractionation and Chugai's antibody production campuses.
Kansai/Osaka
Osaka Prefecture's underutilized JIS-compliant manufacturing parks attract cell-therapy facility investments through tax incentive programs. PMDA Sakigake designation recipients cluster clinical trial recruitment in Kyoto and Osaka tertiary centers. The Kansai Biomedical Corridor positions for gene-therapy production scale-up.
Chubu/Nagoya
Nagoya's automotive-industrial supplier base diversifies into pharmaceutical packaging and precision molding for parenteral devices. Prefectural economic development agencies broker land-use conversions for bioprocess equipment manufacturing. Toyota Tsusho affiliates supply cold-chain logistics infrastructure.
Kyushu
Fukuoka's bio-cluster initiative incubates regenerative medicine startups through proximity to Kyushu University stem cell research institutes. Prefectural governments underwrite GMP facility construction for allogeneic cell-therapy production. Clinical trial site density remains below Kanto levels.
Hokkaido
Sapporo's medical university hospitals anchor neurology and infectious disease therapeutic demand in northern Japan. Limited plasma collection infrastructure constrains immunoglobulin supply chain localization. Prefectural biotech promotion programs target marine-derived compound screening.
Japan Pharmaceutical Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated biologics manufacturers and specialized oncology innovators. Three archetypes dominate: plasma-derived therapeutics specialists, antibody-drug conjugate developers, and rare disease portfolio builders. Competitive moves center on backward integration into blood fractionation and payload-linker chemistry capability acquisition.
Among Japan-based pharmaceutical groups, Takeda Pharmaceutical Company Limited, Chugai Pharmaceutical Co. Ltd, and Daiichi Sankyo Company Ltd occupy distinct strategic positions. Takeda exemplifies the plasma-integrated archetype through captive supply chain control. Chugai represents oncology-focused biologics development leveraging multinational antibody engineering networks. Daiichi Sankyo anchors the antibody-drug conjugate specialization tier through in-house cytotoxic payload production.
| Leading Market Players |
|---|
| Otsuka Holdings Co Ltd |
| Chugai Pharmaceutical Co. Ltd |
| Takeda Pharmaceutical Company Limited |
| Sumitomo Pharma Co., Ltd. |
| Kyowa Kirin Co., Ltd. |
| Astellas Pharma Inc |
| Eisai Co Ltd |
| Shionogi & Co., Ltd. |
| Daiichi Sankyo Company Ltd |
| Others |
Value Chain & Pricing Dynamics
API sourcing concentration across Chinese and Indian suppliers determines both margin compression trajectories and inventory positioning strategies for Japanese manufacturers. Biennial NHI price revisions amplify cost pass-through constraints while forcing portfolio migration toward biologics with captive production.
Pricing Analysis
Hospital pharmacy committees anchor pricing negotiations through regional formulary networks in the Greater Tokyo corridor. Three-tier pricing structure across premium biologics, standard prescription medicines, and economy generics separates reimbursement tiers by innovation status and unmet medical need. Price differentiation hinges on PMDA Sakigake designation and plasma-derived versus recombinant manufacturing origin. Cost compression in generic portfolios intensifies because biennial NHI cuts exceed therapeutic category inflation. Pharmacy chains exhibit highest price sensitivity for chronic disease maintenance therapies, while university hospital specialists prioritize clinical efficacy over acquisition cost for oncology biologics.
Supply Chain Analysis
Export control restrictions on dual-use bioprocessing equipment limit technology transfer into domestic manufacturing facilities. Active pharmaceutical ingredient supply draws from China, India, and Switzerland for small-molecule inputs, while cell culture media and single-use bioreactor components rest on German, American, and Japanese suppliers. Single-source vulnerability concentrates in plasma collection infrastructure where Takeda's backward integration anchors domestic immunoglobulin security. Distribution runs through regional wholesaler networks for retail pharmacy channels and direct manufacturer negotiations for hospital formulary procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialist care fragmentation across Japan's prefectural hospital networks creates niche entry points for targeted therapeutic developers. Demand-side decentralization from Tokyo-centric procurement toward Osaka and Fukuoka bioclusters rewards regional manufacturing investments.
For Market Incumbents: Harden formulary lock-in through specialized key account management targeting consolidated Greater Tokyo university hospital alliances. Deepen plasma collection infrastructure under METI Bio-Strategy industrial policy to secure rare disease portfolio margins against API import volatility. Bioprocess engineering talent scarcity threatens continuous manufacturing scale-up timelines. For New Entrants and Emerging Players: Cell-therapy manufacturing capacity in Osaka Prefecture's JIS-compliant industrial parks represents the most penetrable entry point for gene-therapy developers seeking tax-incentivized facility investments. Remote dispensing platform partnerships with digital health operators capture chronic disease medication refill migration from traditional drugstore chains. Prefectural economic development agencies broker land-use conversions and regulatory navigation support. For Investors and Strategic Acquirers: PMDA Sakigake designation pathway expansion reshapes the acquisition landscape toward early-stage oncology and rare disease pipelines with accelerated approval potential. Five-to-ten year viability concentrates on antibody-drug conjugate payload-linker chemistry capabilities and mRNA platform manufacturing assets. PMDA consultation queue depth signals inflection timing for novel modality investment thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Infrastructure Expansion | METI Bio-Strategy funding secures domestic immunoglobulin supply chains against geopolitical API disruption. |
| Digital Twin Process Development | Takeda and Chugai deployments compress tech transfer timelines from clinical to commercial manufacturing scale. |
| Antibody-Drug Conjugate Pipeline Advancement | Daiichi Sankyo's in-house cytotoxic payload production differentiates HER2 and TROP2 targeting programs. |
| Remote Dispensing Platform Integration | Regulatory easing permits online pharmacies to capture chronic disease refill volume without physical storefront investment. |
| Kansai Biomedical Corridor Manufacturing Scale-Up | Osaka and Kyoto tax incentives attract cell-therapy and gene-therapy facility investments from global sponsors. |
Study Parameters
The analysis maps biologics, prescription medicines, generics, and over-the-counter segments, each validated through drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Primary interview findings triangulate against PMDA submission databases, ClinicalTrials.gov recruitment records, NHI reimbursement bulletins, and METI industrial policy filings. Bottom-up patient-flow modeling and top-down therapeutic category spend analysis cross-validate market sizing.
Assumption sets held domestic plasma collection growth and PMDA Sakigake approval velocity constant while varying API import dependency and biennial NHI price revision severity across the projection horizon. Segmentation dimensions include therapy area, product type, distribution channel, and regional regulatory cluster. CAGRs derive from patient population epidemiology, treatment penetration curves, and reimbursement trajectory modeling. Forecast inputs incorporate bioprocess capacity expansion timelines and clinical trial site density by prefecture.
Macroeconomic conditions sit as an overlay; deviation in yen exchange rates, energy input costs, or cross-border pharmaceutical trade policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway efficiency and manufacturing localization incentives. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Anti-Neoplastic Agents Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Opioid Analgesics Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Ciclopirox Olamine Market
Pharmaceuticals
Global Cyclosporine Market