
 Hyperammonemia Treatment Market | 2026-2036
Hyperammonemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperammonemia Treatment Market Foresight
Hospital procurement consolidation is expanding across academic medical centers and specialized metabolic clinics, concentrating purchasing power among fewer buyers. Recordati Rare Diseases leverages its orphan disease infrastructure to sustain European market access. Swedish Orphan Biovitrum anchors Nordic distribution networks for enzyme replacement therapies. Ultragenyx Pharmaceutical competes through gene therapy platforms targeting urea cycle defects.
Hyperammonemia treatment encompasses pharmacological and nutritional interventions that reduce blood ammonia levels through alternative nitrogen clearance pathways, including phenylbutyrate derivatives and L-carnitine formulations that shuttle excess nitrogen for renal excretion. These therapies prevent neurological damage in patients with urea cycle disorders, organic acidemias, and acute liver failure. Pharmaceuticals dominates current revenue generation through established ammonia scavengers with decades of clinical validation. Intravenous delivery commands critical-care premium pricing during acute hyperammonemic crises, while oral formulations serve maintenance protocols in genetic disorders. Homecare Settings represents the fastest-expanding channel as stable patients transition from hospital-based infusion to self-administered oral regimens.
FDA orphan drug incentives and EMA's priority medicines scheme shape development economics for ultra-rare indications with limited addressable populations. The EU AI Act introduces algorithmic scrutiny for diagnostic tools that stratify patients by predicted treatment response. Reimbursement authorities in Germany through KBA and France via ANSM increasingly demand real-world evidence packages beyond traditional randomized trials. Stakeholders must monitor evolving health technology assessment criteria that differentiate clinical value from incremental innovation.
Market Dynamics
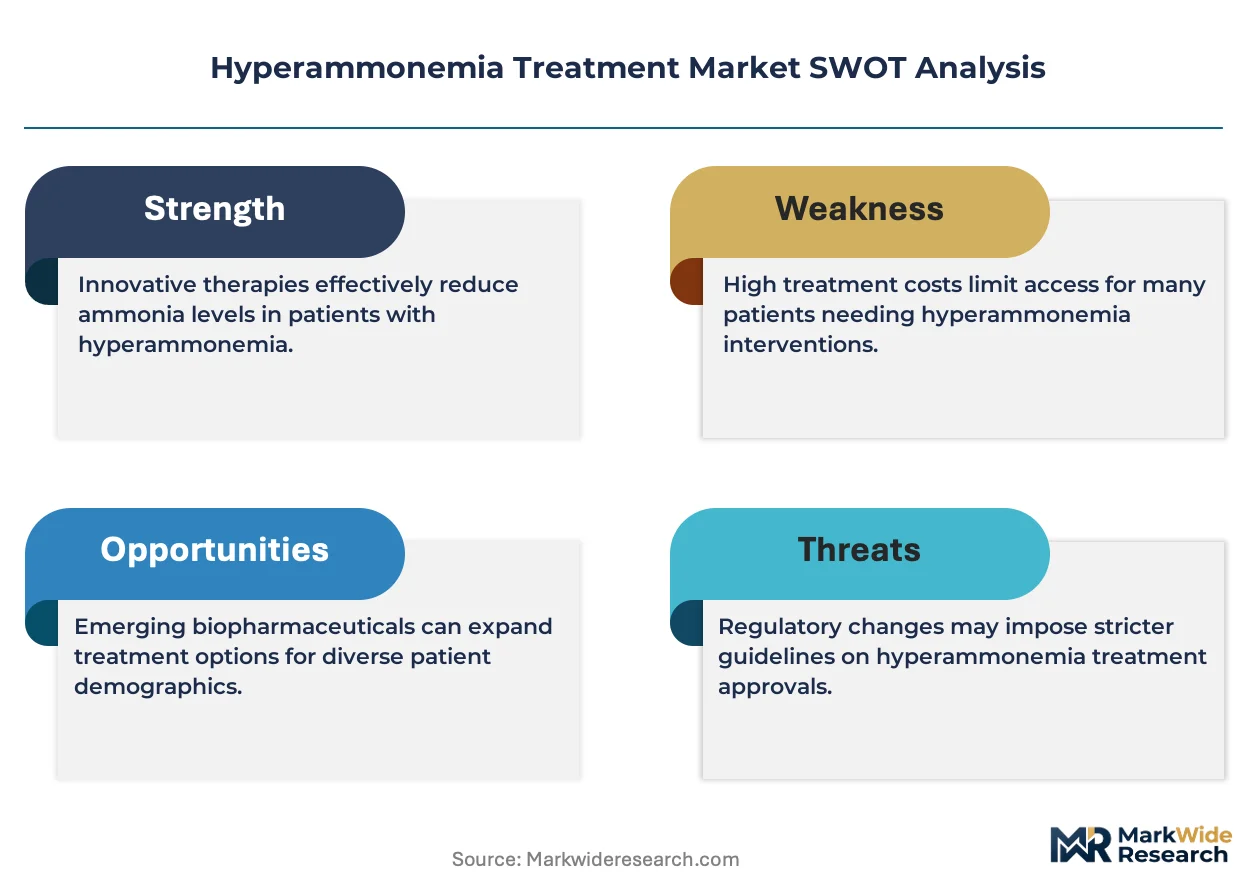
Hospital procurement consolidation among academic medical centers is concentrating purchasing power and reshaping contract negotiations for ammonia-scavenging therapies. This structural shift favors suppliers with integrated rare disease infrastructure and long-term outcome data.
Growth Catalysts
- FDA orphan drug designation:The framework accelerates development timelines for novel nitrogen clearance therapies targeting urea cycle disorders.
- Homecare transition protocols:Stable patients shifting from hospital infusion to self-administered oral regimens expand addressable treatment days.
- Metabolic center clustering:Specialized clinics in the United States drive standardized diagnostic and therapeutic protocol adoption.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for phenylbutyrate derivatives concentrates among limited contract manufacturers.
- Reimbursement complexity:Germany's KBA and France's ANSM demand real-world evidence packages beyond traditional randomized trials.
- Gene therapy substitution threat:Single-administration curative approaches for urea cycle defects threaten chronic maintenance therapy volumes.
Strategic Opportunities
- Diagnostic algorithm integration:The EU AI Act creates pathways for AI-stratified patient selection tools predicting treatment response.
- Homecare channel expansion:Remote monitoring technologies enable stable patients to transition from clinic-based to residential administration.
- Emerging metabolic indications:Organic acidemias and acute liver failure represent underpenetrated therapeutic applications beyond inherited urea cycle disorders.
Industry Challenges
- Specialized metabolic clinician scarcity:The limited pipeline of fellowship-trained biochemical geneticists constrains diagnostic and treatment capacity expansion.
- Multinational trial complexity:Harmonizing protocols across FDA, EMA, and PMDA requirements extends development timelines for ultra-rare indications.
- Legacy system integration:Electronic health record interoperability between hospital metabolic units and homecare monitoring platforms creates data fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperammonemia Treatment Market |
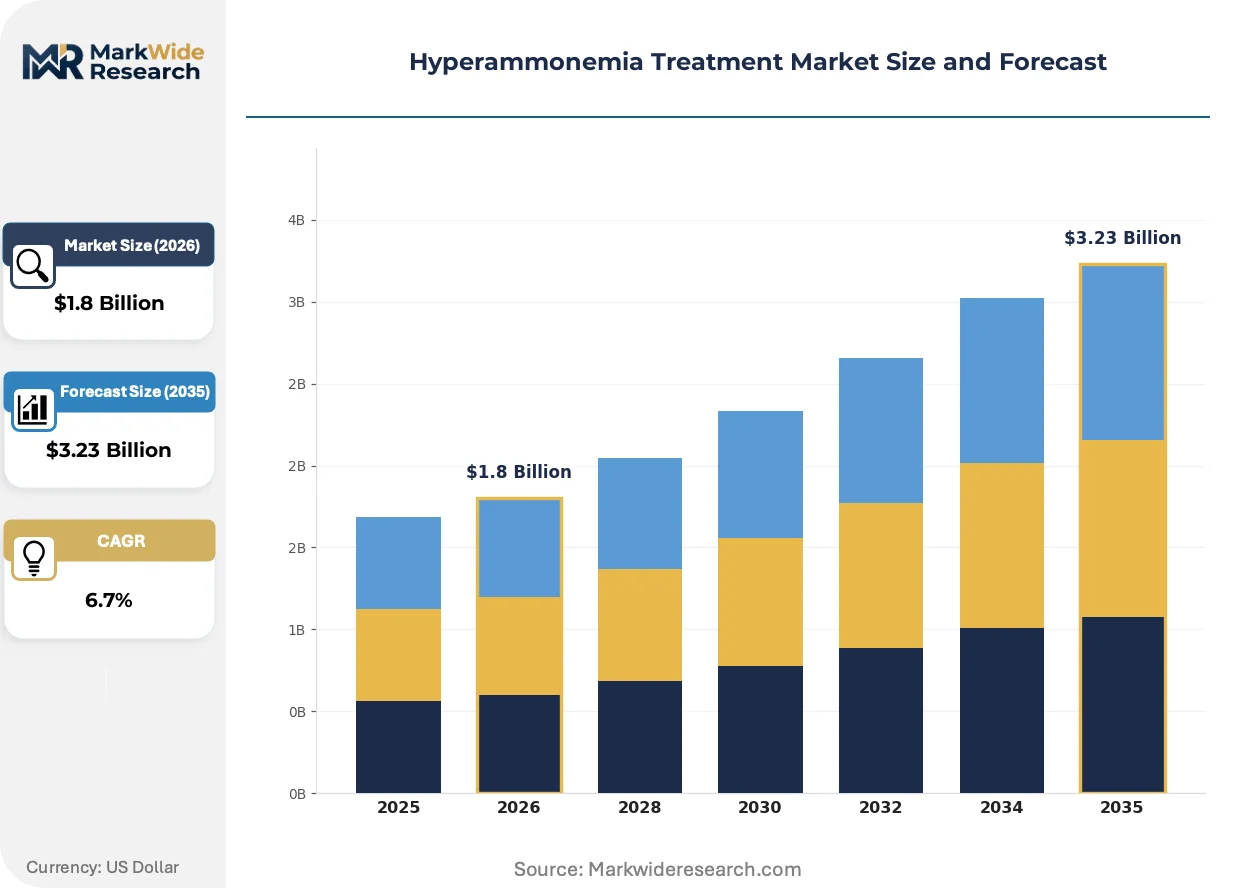
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Pharmaceuticals, Medical Devices, Nutritional Products Therapy Area: Genetic Disorders, Liver Disorders, Metabolic Disorders, Acute Conditions Delivery Mode: Intravenous, Oral, Inhalation, Subcutaneous End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers |
| Companies Covered | Bausch Health Companies, Recordati Rare Diseases, Acer Therapeutics, Swedish Orphan Biovitrum, Takeda Pharmaceuticals, Ultragenyx Pharmaceutical, Aeglea BioTherapeutics, Pfizer, Lucane Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperammonemia Treatment Market Shifts & Advancements
Gene therapy platforms are converging with established enzyme replacement infrastructure, creating hybrid treatment paradigms that challenge chronic pharmacological management. This technological intersection is reshaping competitive positioning across rare disease portfolios.
RNA interference therapeutics targeting urea cycle enzyme deficiencies are converging with existing ammonia-scavenging protocols. Academic medical centers in the United States are piloting combination regimens that pair gene silencing with nitrogen shuttle therapies. This convergence is compressing the addressable market for maintenance-only pharmaceutical approaches.
The EU AI Act introduces mandatory algorithmic scrutiny for diagnostic tools that stratify hyperammonemia patients by predicted treatment response. Industrial consequence includes elevated compliance costs for AI-enabled patient selection platforms. Metabolic centers in Germany and France are responding by establishing dedicated regulatory affairs functions for digital health integration.
Academic medical centers are unbundling after-sales clinical support from product procurement, contracting separately for nursing education and patient adherence monitoring. Hospital pharmacy directors are displacing traditional bundled contracts with modular service purchasing. This pattern is most visible in the United States, where specialized metabolic centers negotiate distinct agreements for drug supply versus care coordination.
Hyperammonemia Treatment Market Segmentation
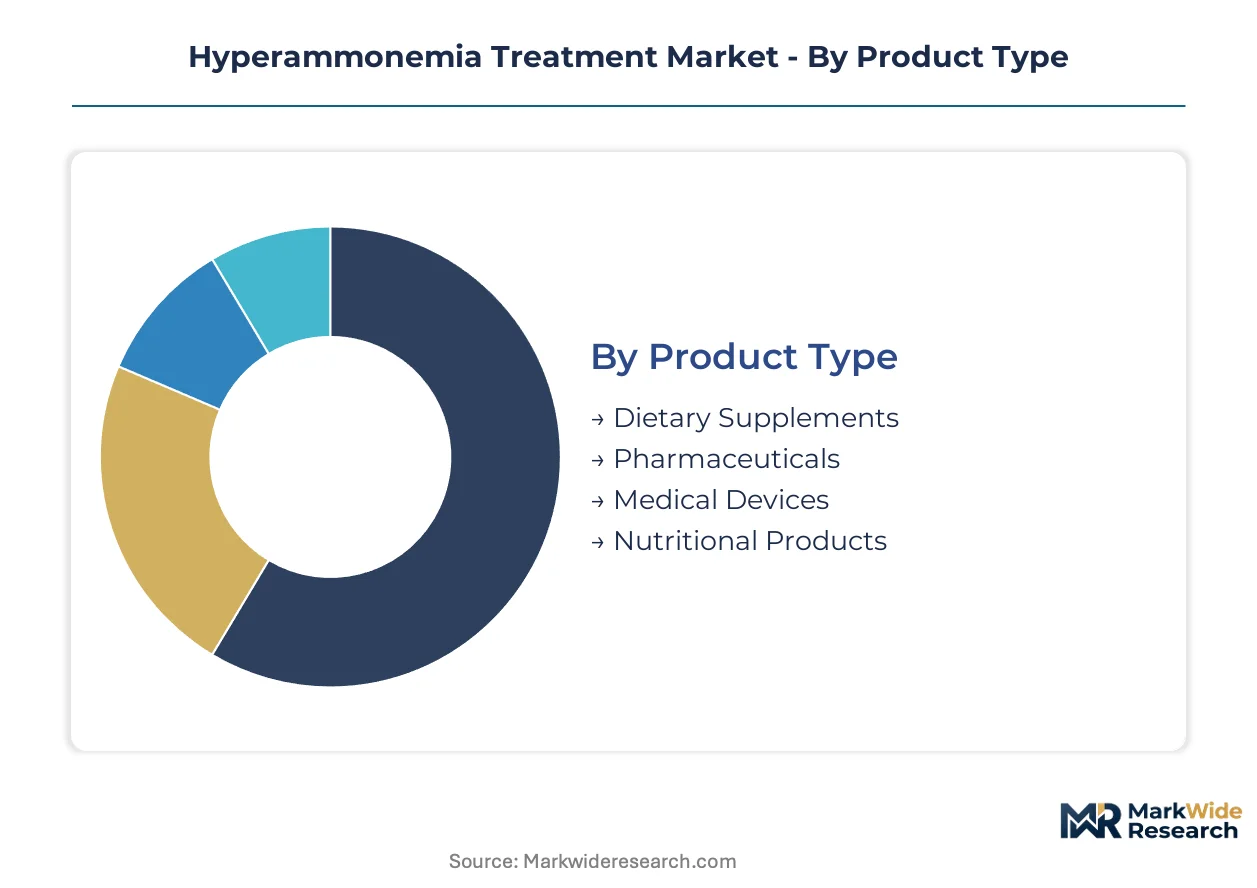
Hyperammonemia treatment segmentation reflects distinct clinical workflows across acute crisis management and chronic maintenance protocols. Product form, delivery route, and care setting each impose unique regulatory, reimbursement, and supply chain requirements that shape vendor strategy.
Product Type:
Hospital pharmacy directors differentiate procurement by clinical validation depth and reimbursement coding complexity.
- Pharmaceuticals:Ammonia-scavenging agents such as phenylbutyrate derivatives and glycerol phenylbutyrate formulations dominate hospital formularies. United States metabolic centers drive protocol standardization for urea cycle disorders, with FDA orphan drug exclusivity securing premium pricing windows.
- Nutritional Products:Disease-specific amino acid formulations and protein-restricted medical foods support long-term nitrogen management. German metabolic clinics through KBA reimbursement pathways concentrate demand for EFSA-compliant formulations.
- Dietary Supplements:L-carnitine and arginine-based over-the-counter preparations serve adjunctive roles in maintenance regimens.
- Medical Devices:Point-of-care ammonia analyzers and remote monitoring peripherals enable homecare transition protocols.
Pharmaceuticals leads volumes today; medical devices is gaining share fastest.
Therapy Area:
Addressable population size and treatment duration separate revenue pools across indication categories.
- Genetic Disorders:Urea cycle disorders and organic acidemias require lifelong ammonia management with established phenylbutyrate protocols. United States specialized metabolic centers anchor diagnostic and therapeutic standardization.
- Acute Conditions:Acute liver failure and Reye syndrome episodes demand rapid nitrogen clearance through intravenous scavengers. Hospital critical care units in France via ANSM emergency use pathways concentrate episodic demand.
- Metabolic Disorders:Secondary hyperammonemia from catabolic stress or drug toxicity responds to shorter intervention cycles.
- Liver Disorders:Cirrhosis-associated hepatic encephalopathy represents a volume opportunity with distinct reimbursement coding.
Genetic disorders commands the highest per-patient lifetime value; acute conditions delivers the steepest expansion trajectory.
Delivery Mode:
Route selection determines care setting economics and patient autonomy levels.
- Intravenous:Sodium phenylacetate and sodium benzoate infusions manage hyperammonemic crises requiring intensive monitoring. United States academic medical centers negotiate bundled critical-care contracts incorporating nursing supervision.
- Oral:Glycerol phenylbutyrate suspensions and sodium phenylbutyrate tablets enable outpatient maintenance. Homecare Settings in Germany through KBA ambulatory reimbursement codes drive volume migration from infusion centers.
- Subcutaneous:Emerging depot formulations aim to bridge hospital and residential administration gaps.
- Inhalation:Investigational ammonia-binding aerosols target pulmonary nitrogen clearance with limited current penetration.
Intravenous anchors hospital revenue today; oral formulations are climbing the fastest as homecare protocols mature.
End User:
Procurement sophistication and outcome accountability vary sharply across institutional and residential settings.
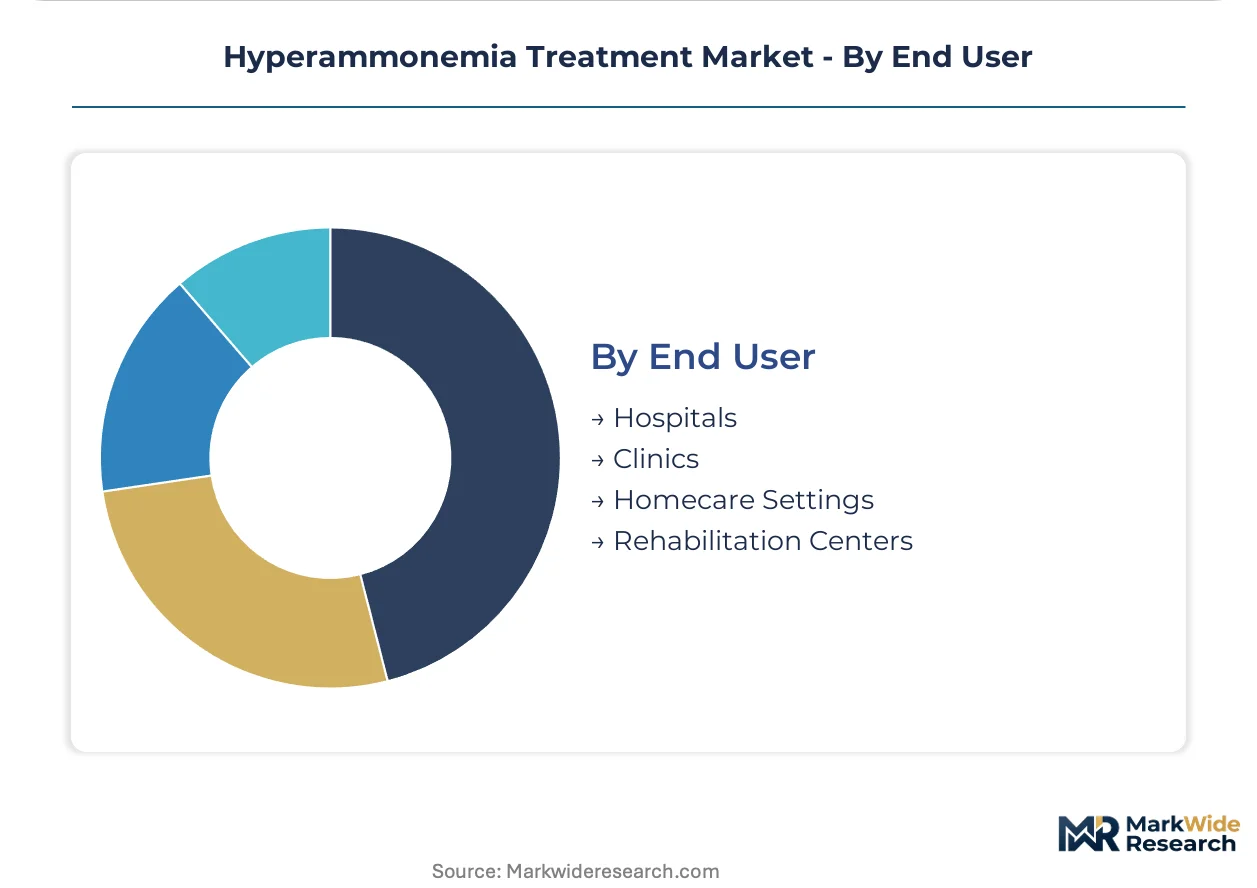
- Hospitals:Academic medical centers and tertiary metabolic units concentrate high-acuity case volume with integrated pharmacy and laboratory infrastructure. United States children's hospitals anchor regional referral networks for urea cycle disorder management.
- Homecare Settings:Self-administered oral regimens supported by remote monitoring reduce total cost of ownership for stable patients. French metabolic centers through ANSM telehealth frameworks pilot nursing oversight at distance.
- Clinics:Outpatient metabolic specialists manage dose titration and adherence monitoring between hospital episodes.
- Rehabilitation Centers:Post-acute facilities handle recovery phases following resolved hyperammonemic crises.
Hospitals retains the dominant share today; homecare settings is expanding most quickly as remote monitoring technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States metabolic centers deploy orphan drug infrastructure that Germany's KBA reimbursement pathways cannot yet match, though both concentrate specialized clinician networks. France and Japan anchor complementary demand poles through distinct regulatory accelerants.
United States
Academic medical centers in Boston and Philadelphia anchor regional referral networks for urea cycle disorder management. FDA orphan drug designation compresses development timelines for novel nitrogen clearance therapies. Children's Hospital of Philadelphia and Massachusetts General Hospital concentrate diagnostic capacity and drive protocol standardization across the Northeast corridor.
Germany
KBA reimbursement pathways concentrate demand for EFSA-compliant amino acid formulations among metabolic clinics in Munich and Heidelberg. The country's national pharmaceutical regulator mandates real-world evidence packages beyond traditional randomized trials. Berlin-Brandenburg clusters coordinate nursing education and patient adherence monitoring through modular service purchasing.
France
ANSM emergency use pathways concentrate episodic demand for intravenous scavengers in Paris and Lyon critical care units. The national pharmaceutical regulator pilots telehealth frameworks enabling nursing oversight at distance for homecare transitions. Île-de-France metabolic centers unbundle after-sales clinical support from product procurement.
Japan
PMDA requirements for multinational trial harmonization extend development timelines for ultra-rare indications. Tokyo and Osaka academic medical centers pilot combination regimens pairing gene silencing with nitrogen shuttle therapies. The Kanto region anchors biochemical geneticist training pipelines that constrain diagnostic capacity expansion.
United Kingdom
London and Cambridge metabolic units negotiate distinct agreements for drug supply versus care coordination. The country's national pharmaceutical regulator aligns with EMA priority medicines schemes for ultra-rare indications. Southeast England concentrates specialized pharmacy and laboratory infrastructure for high-acuity case volume.
Hyperammonemia Treatment Market Competitive Landscape
United States producers anchor the gene therapy tier; European specialists hold established ammonia-scavenging infrastructure. The vendor base separates across three strategic tiers: orphan disease incumbents with decades of clinical validation, gene therapy platforms targeting curative approaches, and emerging RNA interference specialists. Consolidation pressures favor suppliers with integrated rare disease infrastructure and long-term outcome data. Competitive moves concentrate on diagnostic algorithm integration and homecare channel expansion through remote monitoring technologies.
Within the orphan disease incumbent tier, Recordati Rare Diseases and Swedish Orphan Biovitrum occupy positions sustained by European market access infrastructure and Nordic distribution networks respectively. Ultragenyx Pharmaceutical exemplifies the gene therapy platform archetype targeting urea cycle defects. These three entities represent the competitive spectrum from established pharmaceutical maintenance therapies to single-administration curative approaches that threaten chronic therapy volumes.
| Leading Market Players |
|---|
| Bausch Health Companies |
| Recordati Rare Diseases |
| Acer Therapeutics |
| Swedish Orphan Biovitrum |
| Takeda Pharmaceuticals |
| Ultragenyx Pharmaceutical |
| Aeglea BioTherapeutics |
| Pfizer |
| Lucane Pharma |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up ammonia-scavenging specialists have consolidated API manufacturing capacity across contract manufacturers in India and China, tightening supply discipline while extracting procurement leverage from hospital pharmacy directors in the United States and Germany. This ownership concentration feeds directly into pricing power for phenylbutyrate derivatives, where three-tier pricing structure across premium intravenous formulations, standard oral maintenance regimens, and economy-tier dietary supplements reflects both input cost stratification and reimbursement coding complexity.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for phenylbutyrate API while contract-based long-term offtake agreements dominate procurement between European metabolic centers and established suppliers. Price differentiation hinges on FDA orphan drug exclusivity tiers and after-sales clinical support bundling, with premium intravenous formulations commanding the widest margins. Cost compression in oral maintenance segments is intensifying because of homecare transition protocols and self-administration adoption. Hospital procurement managers in France exhibit highest price sensitivity due to ANSM reimbursement scrutiny, while United States academic medical centers prioritize clinical validation depth over unit economics.
Supply Chain Analysis
Direct-to-hospital channels handle high-acuity intravenous demand while specialty pharmacy distributors manage oral maintenance fulfillment for homecare transitions. API manufacturing concentrates in India, China, and selected European contract facilities, with sodium phenylacetate and glycerol phenylbutyrate precursors drawing from concentrated petrochemical feedstock suppliers. Single-source vulnerability pervades the phenylbutyrate derivative supply base, where limited qualified manufacturers create chokepoints for European and North American formulators. Distribution runs through hospital pharmacy direct purchasing for critical-care units and metabolic center consignment arrangements for chronic maintenance patients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperammonemia treatment markets reward geographic arbitrage between United States orphan drug pricing premiums and European real-world evidence reimbursement pathways, with FDA designation timelines offering faster monetization than KBA or ANSM negotiation cycles.
For Market Incumbents: Acquire gene therapy platform capabilities to counter substitution threats from single-administration curative approaches for urea cycle disorders. Consolidate diagnostic algorithm assets that predict treatment response under EU AI Act compliance frameworks, securing patient stratification tools before reimbursement authorities mandate algorithmic transparency. Capacity expansion in Nordic distribution networks reinforces Swedish Orphan Biovitrum's geographic moat against Ultragenyx Pharmaceutical's gene therapy encroachment. For New Entrants and Emerging Players: Enter via organic acidemia indications, where phenylbutyrate protocol penetration lags urea cycle disorder standardization and hospital pharmacy directors seek expanded therapeutic options. Target French and German homecare transition protocols as the most penetrable channel, leveraging ANSM telehealth pilots and KBA ambulatory reimbursement codes to bypass entrenched hospital procurement relationships. Position around remote monitoring technology integration as the primary go-to-market differentiator against legacy bundled service contracts. For Investors and Strategic Acquirers: Rare disease pharmaceutical specialists are the most active acquirer in this space, consolidating ammonia-scavenging infrastructure ahead of gene therapy platform maturation. The viable acquisition window spans medium-term horizons where chronic maintenance therapy volumes remain defensible against curative substitution. Target firms with integrated European market access infrastructure and long-term outcome databases that satisfy KBA and ANSM real-world evidence demands. Watch FDA gene therapy approval velocity as the critical inflection signal for chronic pharmaceutical maintenance revenue erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA designation compresses development timelines for novel nitrogen clearance therapies targeting urea cycle disorders. |
| Diagnostic Algorithm Integration | EU AI Act compliance creates defensible positioning for patient stratification tools predicting ammonia-scavenging response. |
| Homecare Channel Expansion | Remote monitoring technologies enable stable patients to transition from hospital infusion to self-administered oral regimens. |
| Gene Therapy Platform Acquisition | Single-administration curative approaches threaten chronic maintenance volumes, demanding hybrid portfolio construction. |
| Real-World Evidence Infrastructure | KBA and ANSM reimbursement pathways increasingly demand outcome databases beyond traditional randomized trial designs. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, and ClinicalTrials.gov records; and bottom-up prescription volume triangulation against top-down metabolic center capacity estimates — were reconciled to construct segment-level demand models. Conversations with formulary directors at United States academic medical centers and payer access specialists in Germany supplied pricing and reimbursement pathway intelligence. Cross-referencing hospital procurement databases with GPO contracts anchored volume assumptions.
Data-stream reconciliation applied analytical frameworks across the projection horizon, modeling treatment line, dosage form, administration route, and regional regulatory cluster dimensions. CAGRs were derived from patient population epidemiology, protocol adoption curves, and pricing trajectory assumptions. Forecast inputs incorporated metabolic center clustering patterns in the United States, KBA reimbursement evolution in Germany, and gene therapy pipeline progression timelines.
The model holds under stable orphan drug incentive frameworks and continued metabolic center consolidation; deviation in FDA gene therapy approval velocity or EMA priority medicines scheme restructuring would shift chronic maintenance therapy volume assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Familial Hypercholesterolemia Treatment Market
Medical Treatment
Chagas Disease Treatment Market
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Tendonitis Treatment Market
Medical Treatment
Gunshot Injuries Treatment Market
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Intensity Modulated Radiation Therapy Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Global Nano Therapy Market
Medical Treatment
Hypogonadism Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Global Rotator Cuff Treatment Market