
 Th17 Driven Disease Treatment Market | 2026-2036
Th17 Driven Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Th17 Driven Disease Treatment Market Analytics
Modular combination regimens pairing monoclonal antibodies with small-molecule immunomodulators is consolidating prescriber preference around flexible, step-up protocols. AbbVie leverages its dermatology and gastroenterology infrastructure to anchor IL-23 inhibitor penetration across academic medical centers. Eli Lilly & Co. competes through manufacturing scale that sustains cost-of-goods advantages on subcutaneous delivery platforms. MoonLake Immunotherapeutics differentiates via Nanobody engineering that extends half-life and enables quarterly dosing intervals.
Th17 driven disease treatment encompasses therapeutic interventions targeting the interleukin-17 signaling axis and related T-helper-17 cell pathways, typically employing biologics engineered to neutralize IL-17A, IL-17F, or their receptor complexes with picomolar binding affinity and sustained tissue penetration. These therapies primarily interrupt autoimmune and inflammatory pathologies by blocking cytokine-mediated neutrophil recruitment and epithelial activation. Monoclonal antibodies occupy the largest revenue pool due to established efficacy in psoriasis and psoriatic arthritis, while biologics represent the fastest-expanding category as bispecific formats and extended-half-life constructs enter Phase III programs. Small molecules are gaining traction in oral maintenance settings where patient self-administration and storage simplicity reduce healthcare system burden.
FDA breakthrough therapy designation and EMA PRIME eligibility are compressing development timelines for novel IL-17 pathway modulators, while FDA biosimilar guidance and EMA comparability standards are intensifying pricing pressure on originator molecules nearing exclusivity expiry. The EU MDR and FDA cGMP requirements for multi-product biologics facilities are raising capital barriers for new manufacturing entrants. Stakeholders must monitor emerging JAK-STAT and TYK2 inhibitor clinical readouts that could displace first-line biologic positioning in dermatological conditions and inflammatory bowel disease.
Market Dynamics
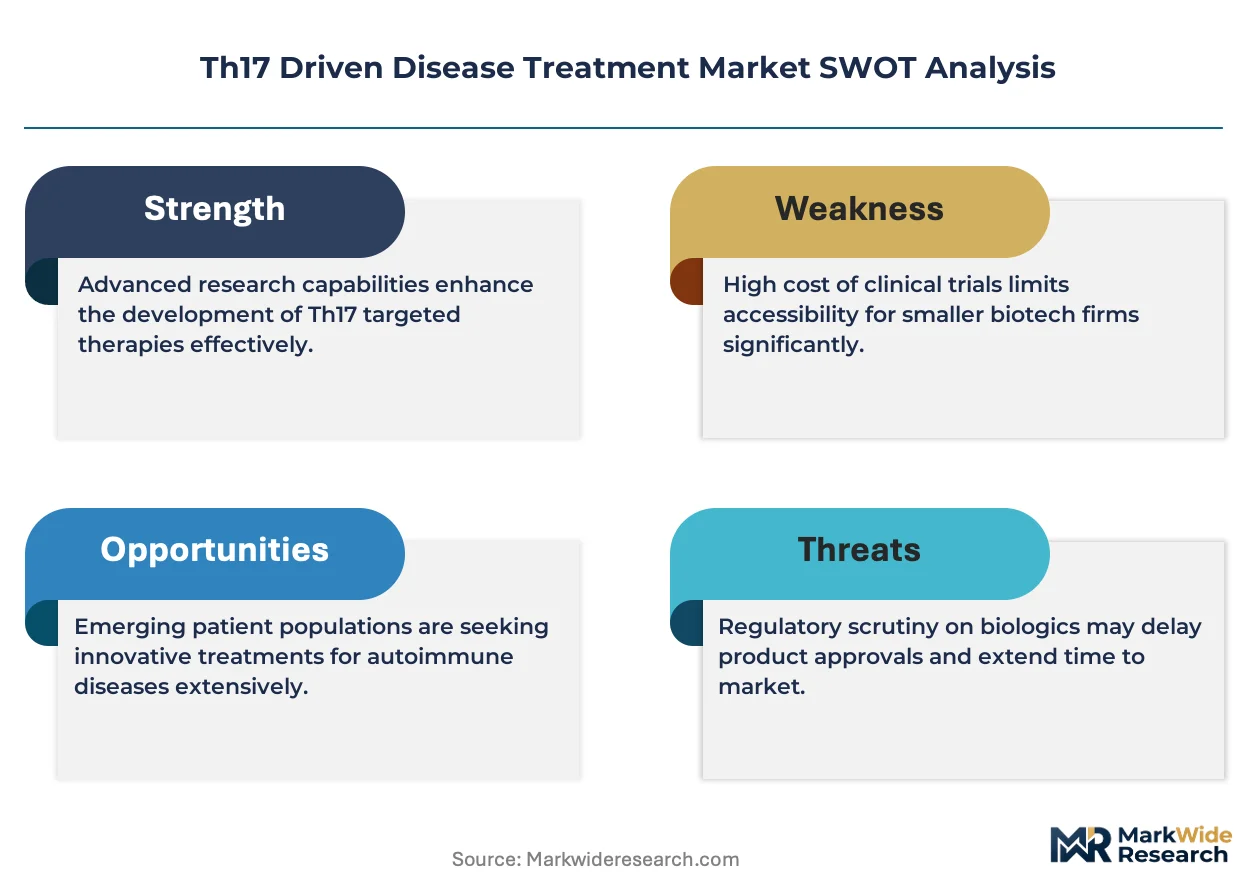
FDA breakthrough therapy designation and EMA PRIME eligibility are compressing development timelines for novel IL-17 pathway modulators, while biosimilar guidance intensifies pricing pressure on originator molecules approaching exclusivity expiry.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy and EMA PRIME designation frameworks compress Phase II-to-approval intervals for IL-23 and IL-17 inhibitors, enabling earlier commercialization of extended-half-life biologics.
- Specialist Prescriber Density:Concentration of dermatology and rheumatology specialists in the United States, Germany, and Japan creates receptive environments for premium biologic adoption and step-up protocol implementation.
- Quarterly Dosing Engineering:Nanobody and Fc-fusion technologies that extend half-life reduce infusion center burden and align with payer preference for lower administration frequency.
Market Restraints
- Manufacturing Capital Barriers:FDA cGMP and EU MDR requirements for multi-product biologics facilities demand substantial upfront investment, constraining new entrant capacity expansion.
- Biosimilar Price Compression:FDA biosimilar guidance and EMA comparability standards for IL-17 inhibitors erode originator pricing power as reference products approach exclusivity loss.
- JAK-STAT Substitution Threat:Oral TYK2 and JAK inhibitors for psoriasis and inflammatory bowel disease threaten to displace first-line biologic positioning in maintenance settings.
Strategic Opportunities
- Underpenetrated Gastroenterology:Crohn's disease and ulcerative colitis indications for IL-23 inhibitors remain underdeveloped relative to dermatology, offering expansion white space.
- Oral Small-Molecule Maintenance:Self-administered oral immunomodulators address patient preference for storage simplicity and reduced healthcare system touchpoints in stable disease phases.
- Bundled Outcomes Contracts:Hospital procurement is intensifying around risk-sharing agreements that tie reimbursement to measurable clinical endpoints in autoimmune populations.
Industry Challenges
- Bioprocess Talent Scarcity:Cell culture and downstream purification expertise for high-titer monoclonal antibody production concentrates at established contract manufacturers, limiting in-house buildout options.
- Multi-Indication Trial Complexity:Simultaneous pursuit of psoriasis, psoriatic arthritis, and axial spondyloarthritis approvals strains clinical operations and regulatory submission bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Th17 Driven Disease Treatment Market |
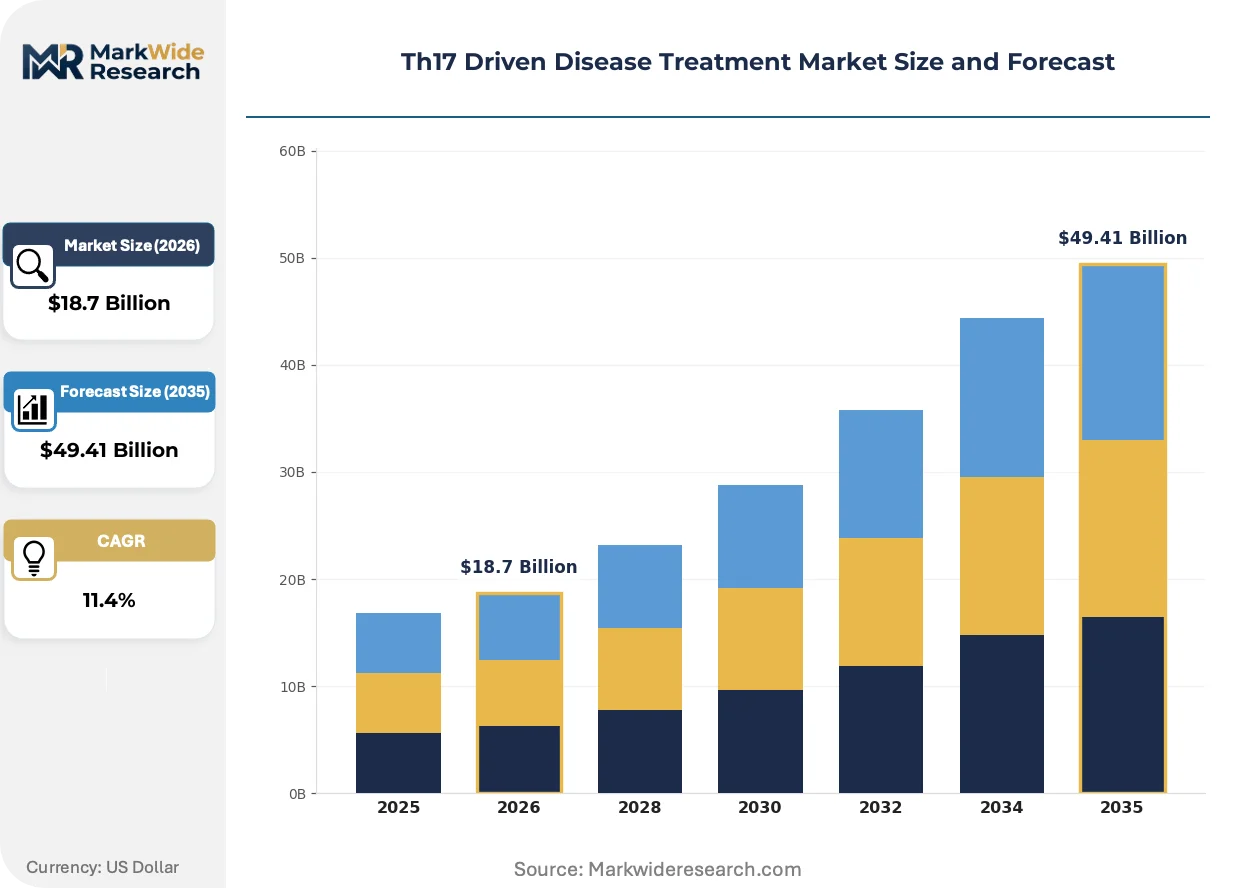
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Small Molecules, Biologics, Vaccines Therapy Area: Autoimmune Disorders, Allergic Reactions, Inflammatory Diseases, Dermatological Conditions End User: Hospitals, Clinics, Research Laboratories, Homecare Settings Administration Route: Subcutaneous, Intravenous, Oral, Topical |
| Companies Covered | AbbVie, Alexion Pharmaceuticals, Novartis Pharma AG, UCB SA, Eli Lilly & Co., MoonLake Immunotherapeutics, AstraZeneca, Amgen, LEO Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Th17 Driven Disease Treatment Market Evolving Landscape
Bispecific antibody engineering and extended-half-life constructs are reshaping competitive positioning in Th17 pathway modulation, while procurement models evolve toward outcomes-based hospital contracting.
Half-life extension technologies are unifying dosing convenience with manufacturing efficiency. Nanobody-Fc fusion and albumin-binding domain engineering enable quarterly subcutaneous administration. Academic medical centers and integrated delivery networks are prioritizing these formats to reduce infusion chair utilization. This unifying architecture compresses the competitive advantage window for monthly-dosing originators.
EMA MDR and FDA cGMP harmonization is elevating quality system requirements for multi-product biologics facilities. Manufacturers must demonstrate enhanced process analytical technology and continuous manufacturing readiness. European and North American production sites face the steepest compliance investment curves as they retrofit legacy stainless-steel trains.
Specialist prescribing behavior is fragmenting across step-up versus top-down initiation protocols. United States dermatology practices increasingly favor biologic-first approaches for moderate-to-severe psoriasis, displacing conventional systemic small-molecule sequencing. This pattern concentrates in metropolitan markets with high payer reimbursement clarity and prior authorization automation.
Th17 Driven Disease Treatment Market Segmentation
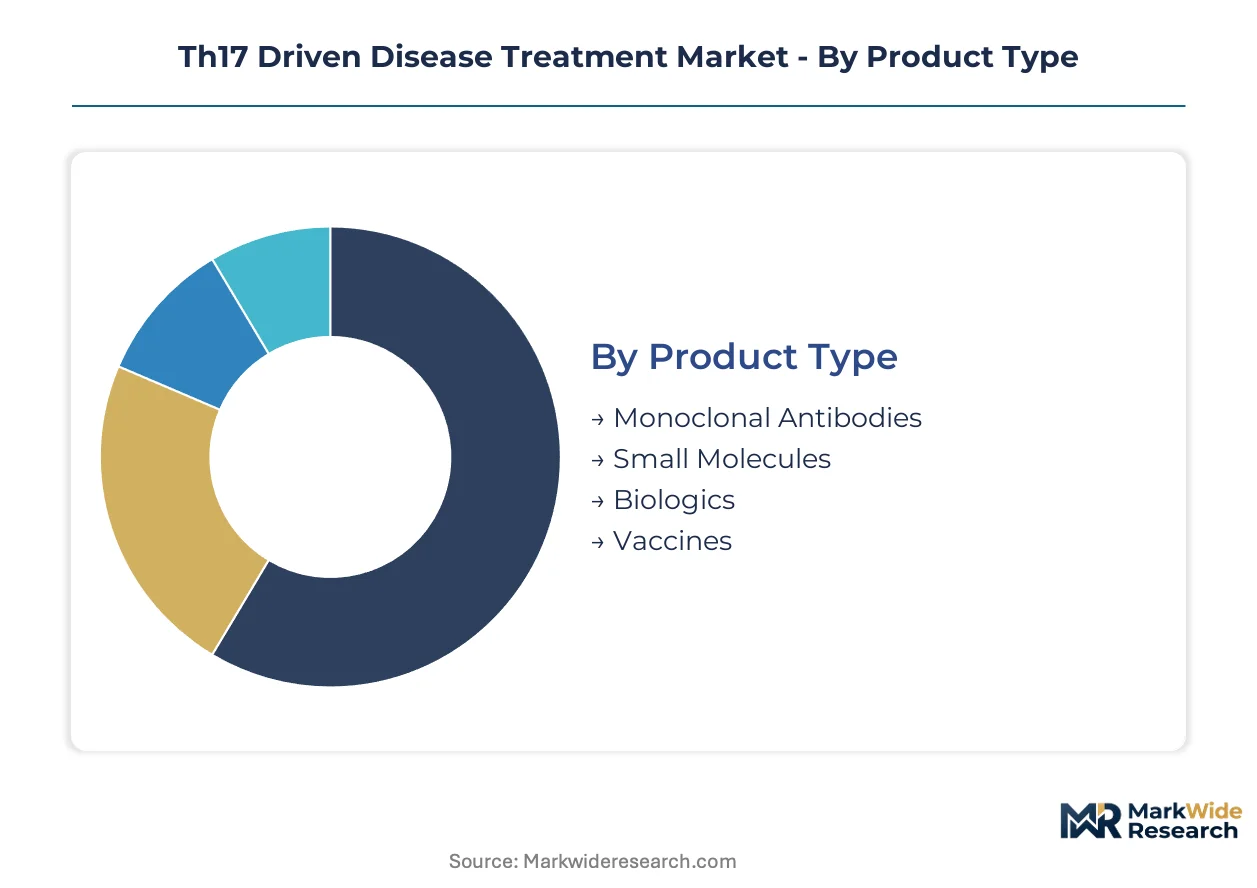
Th17 pathway modulation requires precise therapeutic matching across molecular formats, disease states, and care settings. Segmentation reveals where biologic engineering investments concentrate versus where oral alternatives disrupt established protocols.
Product Type:
Engineering complexity and manufacturing scale separate the revenue pools across molecular formats.
- Monoclonal Antibodies:Engineered IgG1 and IgG4 frameworks with Fc-silencing mutations deliver picomolar IL-17A and IL-23 neutralization. Demand clusters in United States academic medical centers where prior authorization automation supports premium biologic reimbursement. These formats anchor step-up therapy protocols for moderate-to-severe psoriasis.
- Biologics:Extended-half-life constructs including Nanobody-Fc fusions and albumin-binding domain fusions enable quarterly subcutaneous dosing. Germany's integrated care networks prioritize these formats to reduce infusion center utilization and align with DRG efficiency targets. This category is gaining share fastest as manufacturing titers improve.
- Small Molecules:Oral JAK-STAT and TYK2 inhibitors address patient preference for self-administration without cold-chain storage.
- Vaccines:Tolerogenic peptide constructs remain investigational, targeting disease modification rather than symptom suppression.
Mature deployment sits with Monoclonal Antibodies. Newer deployment is concentrated in Biologics.
Therapy Area:
Clinical evidence density and prescriber specialization determine which indications command development resources.
- Dermatological Conditions:Psoriasis and hidradenitis suppurativa deliver the most mature clinical data packages for IL-17 pathway inhibitors. Japan's dermatology specialist density supports rapid uptake of novel biologics with differentiated dosing schedules. FDA breakthrough therapy designations have compressed approval timelines for extended-half-life entrants in this category.
- Inflammatory Diseases:Crohn's disease and ulcerative colitis represent expansion white space where IL-23 inhibitors challenge anti-TNF primacy. United States gastroenterology practices in metropolitan markets are shifting toward biologic-first protocols for fistulizing disease. EMA PRIME eligibility has accelerated European development programs in this segment.
- Autoimmune Disorders:Psoriatic arthritis and axial spondyloarthritis require joint-specific endpoints that complicate trial design.
- Allergic Reactions:Th17 modulation remains investigational for severe asthma and allergic bronchopulmonary aspergillosis.
Revenue concentration favors Dermatological Conditions. Pipeline momentum is shifting toward Inflammatory Diseases.
End User:
Procurement sophistication and reimbursement mechanics fragment demand across care settings.
- Hospitals:Integrated delivery networks in the United States negotiate bundled outcomes contracts tying biologic reimbursement to PASI-75 and ACR-20 response rates. These institutions concentrate infusion capacity and specialist prescriber density for complex autoimmune populations. EMA MDR compliance requirements favor established hospital pharmacy operations with validated cold-chain infrastructure.
- Clinics:Dermatology and rheumatology group practices in Germany leverage disease-specific quality contracts with statutory health insurers. These settings prioritize subcutaneous formulations that reduce nursing burden and enable same-day initiation. FDA cGMP requirements for multi-product biologics facilities raise barriers for new manufacturing entrants serving this channel.
- Homecare Settings:Self-administration of prefilled syringes and autoinjectors addresses patient mobility constraints.
- Research Laboratories:Academic centers conduct investigator-sponsored trials for novel Th17 pathway modulators.
Volume leadership belongs to Hospitals. Growth acceleration is occurring in Clinics.
Administration Route:
Patient preference and healthcare system efficiency drive route selection in maintenance therapy.
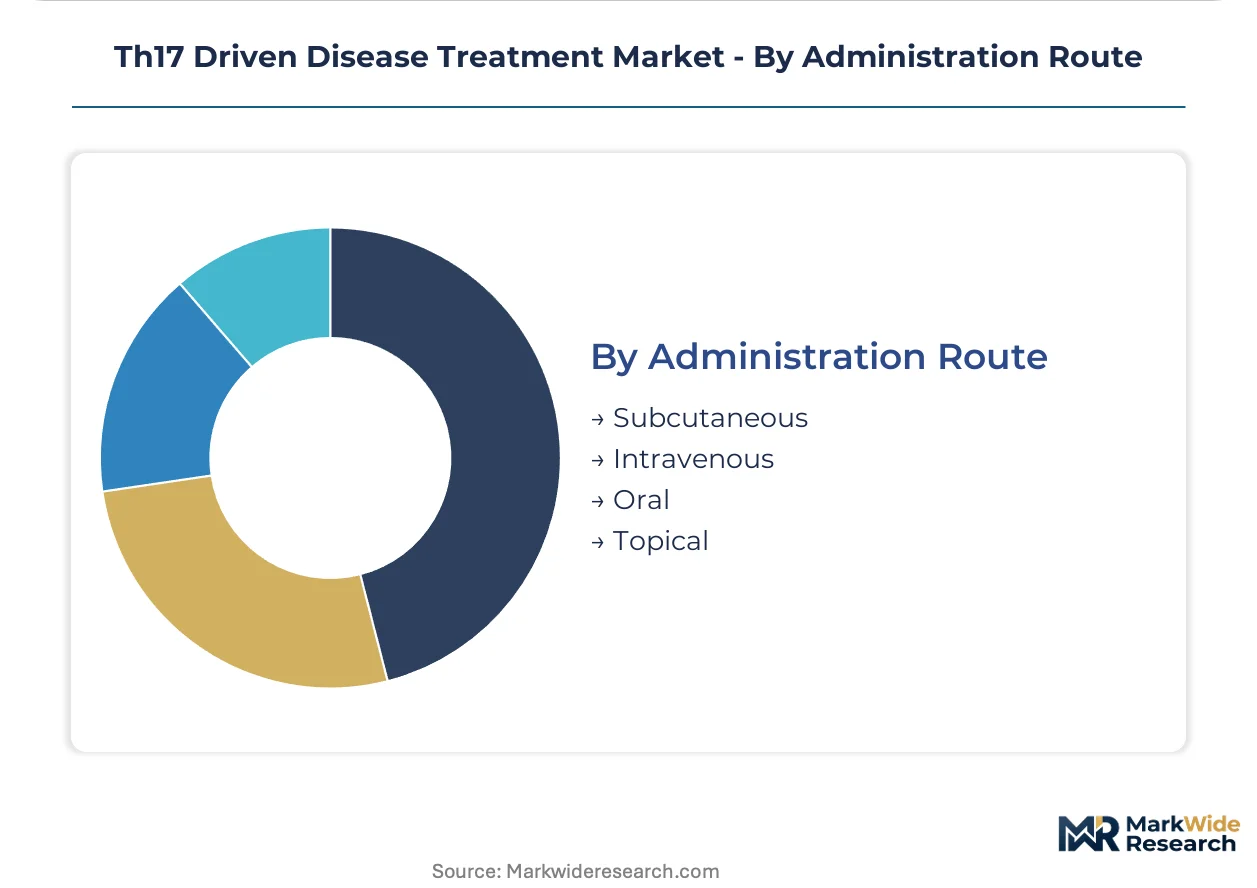
- Subcutaneous:Prefilled syringes and autoinjectors enable self-administration without infusion center dependency. United States pharmacy benefit managers favor these formats for their reduced medical benefit spend and lower prior authorization friction. MoonLake Immunotherapeutics and competitors engineer half-life extension to sustain quarterly dosing intervals that align with patient convenience.
- Intravenous:Infusion center delivery maintains relevance for induction dosing and patients with needle phobia or adherence concerns. Japan's hospital-centric reimbursement system preserves IV volume for biologic initiations despite subcutaneous alternatives. EMA and FDA cGMP requirements for multi-product facilities concentrate IV manufacturing at established contract manufacturers.
- Oral:Small-molecule immunomodulators address storage simplicity and travel flexibility for stable maintenance patients.
- Topical:Localized delivery remains limited to mild disease or combination approaches in dermatology.
Established preference centers on Subcutaneous. Emerging substitution pressure targets Intravenous from Oral alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical special economic zones in Massachusetts and North Carolina concentrate Th17 pathway drug development through FDA breakthrough therapy designations and state-level R&D tax credits that offset clinical trial costs.
United States
Academic medical centers in Boston and the Research Triangle Park anchor IL-23 inhibitor adoption through integrated delivery networks negotiating bundled outcomes contracts. FDA accelerated approval pathways compress Phase II-to-commercialization timelines for extended-half-life biologics. The Massachusetts biopharmaceutical cluster sustains manufacturing capacity expansion for multi-product monoclonal antibody facilities serving hospital pharmacy operations.
Germany
Integrated care networks prioritize quarterly-dosing biologics to align with DRG efficiency targets and reduce infusion center utilization. EMA PRIME eligibility accelerates European development programs for novel IL-17 pathway modulators. The Rhine-Main biotech corridor concentrates contract manufacturing organization capacity for high-titer monoclonal antibody production serving statutory health insurer quality contracts.
Japan
Hospital-centric reimbursement preserves intravenous biologic initiations despite subcutaneous alternatives, while dermatology specialist density supports rapid uptake of novel dosing schedules. PMDA Sakigake designation expedites regulatory review for first-in-class Th17 pathway inhibitors. The Kanto region's metropolitan hospital networks concentrate prescriber training programs for biologic-first psoriasis protocols.
United Kingdom
NICE technology appraisals shape IL-17 inhibitor access through cost-effectiveness thresholds that favor extended-half-life formats reducing administration frequency. NHS England's specialist commissioning frameworks concentrate biologic prescribing in tertiary dermatology centers. The Golden Triangle research cluster sustains investigator-sponsored trials for tolerogenic peptide constructs targeting disease modification.
Switzerland
Swissmedic's streamlined review procedures attract European headquarters for biologics developers seeking concurrent EMA submission strategies. The Basel biopharmaceutical hub concentrates nanobody engineering expertise for half-life extension technologies enabling quarterly dosing. Cantonal economic promotion agencies offer R&D tax incentives that offset bioprocess development costs for novel Fc-fusion constructs.
Th17 Driven Disease Treatment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Th17 pathway modulation space, creating a tiered structure where scale advantages in manufacturing confront agility in clinical trial design. Large-cap pharmaceutical companies leverage dermatology and gastroenterology infrastructure to anchor IL-23 inhibitor penetration across academic medical centers. Mid-cap biologics developers concentrate on half-life extension engineering and nanobody-Fc fusion formats. Competitive moves center on strategic partnerships for manufacturing capacity access and geographic licensing arrangements for hospital procurement channels.
Among the diversified pharmaceutical tier, AbbVie exemplifies infrastructure-led positioning across immunology franchises, while Eli Lilly & Co. anchors scale-driven manufacturing advantages on subcutaneous delivery platforms. MoonLake Immunotherapeutics represents the focused specialist archetype, occupying a position defined by nanobody engineering capabilities that enable differentiated dosing intervals. These three entities collectively illustrate the competitive spectrum from integrated conglomerate to pure-play biologics developer, with each archetype pursuing distinct prescriber access strategies through hospital formulary positioning and payer contracting mechanics.
| Leading Market Players |
|---|
| AbbVie |
| Alexion Pharmaceuticals |
| Novartis Pharma AG |
| UCB SA |
| Eli Lilly & Co. |
| MoonLake Immunotherapeutics |
| AstraZeneca |
| Amgen |
| LEO Pharma |
| Others |
Value Network & Pricing Analysis
Hospital procurement consolidation around bundled outcomes contracts for biologic therapies is forcing manufacturers to absorb administration cost risk while maintaining cold-chain integrity across multi-product facilities. This demand-side pressure compresses margins on originator molecules approaching exclusivity expiry while rewarding extended-half-life formats that reduce infusion center utilization.
Pricing Analysis
Short lead-time premiums for quarterly-dosing biologics command pricing advantages over monthly alternatives in United States integrated delivery networks. Three-tier pricing structure across originator, biosimilar, and next-generation extended-half-life constructs segments buyer access. Cost compression in the biosimilar tier is intensifying because FDA comparability guidance accelerates entry. Statutory health insurers in Germany exhibit highest price sensitivity, while Japan's hospital-centric reimbursement system preserves originator premiums.
Supply Chain Analysis
Reverse logistics for temperature-controlled biologics—returns of expired vials, cold-chain equipment refurbishment, and patient autoinjector recollection—adds complexity to multi-product facility operations. Manufacturing concentrates in the United States, Germany, and Switzerland where FDA cGMP and EU MDR compliance infrastructure is pre-established. Cell culture media, single-use bioreactor bags, and Fc-fusion protein engineering expertise anchor raw material dependencies. Single-source vulnerability for high-titer monoclonal antibody production strains capacity expansion timelines. Distribution runs through hospital pharmacy operations and specialty distributors with validated cold-chain credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA MDR and FDA cGMP harmonization for multi-product biologics facilities erects a cost-of-compliance barrier that advantages incumbent manufacturers with existing quality infrastructure. This regulatory moat protects compliant players from new entrant capacity buildout.
For Market Incumbents: To counter biosimilar price erosion on IL-17 inhibitors nearing exclusivity loss, deepen backward integration into high-titer cell culture capacity and anchor hospital formulary positioning through outcomes-based contracting. Prioritize manufacturing investment in Massachusetts and North Carolina biopharmaceutical clusters where state R&D tax credits offset clinical trial costs. For New Entrants and Emerging Players: Launch via specialty distributor partnerships targeting Crohn's disease and ulcerative colitis indications where IL-23 inhibitor clinical data remains underdeveloped relative to dermatology. Germany's integrated care networks offer the most penetrable geography for quarterly-dosing biologics aligned with DRG efficiency targets. Position around nanobody engineering differentiation to bypass originator patent thickets. For Investors and Strategic Acquirers: The window for entry favors mid-cap biologics developers with validated half-life extension platforms and Phase III-ready gastroenterology pipelines. Long-term viability hinges on manufacturing scale sufficient to serve hospital procurement consolidation. Watch FDA breakthrough therapy designation velocity for IL-23 inhibitors in inflammatory bowel disease as inflection signal for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | High-titer monoclonal antibody capacity in FDA-cGMP facilities secures hospital formulary access. |
| Regulatory Approval Pathway | EMA PRIME eligibility compresses Phase II-to-approval intervals for novel IL-17 modulators. |
| Pipeline Diversification | Crohn's disease and ulcerative colitis indications expand addressable market beyond dermatology. |
| Licensing Agreement | Geographic licensing for hospital procurement channels accelerates prescriber access in Japan. |
| Clinical Trial Advancement | Extended-half-life construct readouts in axial spondyloarthritis validate quarterly dosing superiority. |
Research Methodology
Independent corroboration across formulary directors at United States academic medical centers, regulatory affairs leads at EMA-submitted biologics developers, and hospital procurement managers in German integrated care networks underwrites the qualitative findings. Secondary validation draws from FDA breakthrough therapy designations, EMA PRIME eligibility records, ClinicalTrials.gov protocol filings, and CMS Medicare Part B reimbursement data. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure triangulation anchor market sizing.
Rate-of-change decomposition across the analysis window separates volume expansion from price trajectory and mix-shift effects. Segmentation dimensions include molecular format, therapy area, administration route, and regional regulatory cluster. CAGRs derive from indication-specific patient prevalence, treatment penetration curves, and dosing interval assumptions. Forecast inputs incorporate biosimilar entry timing and JAK-STAT substitution elasticity in maintenance settings.
Regulatory approval delays, biosimilar launch acceleration, and TYK2 inhibitor clinical success in inflammatory bowel disease are the dominant revision risks. Practitioners should monitor FDA advisory committee outcomes for novel IL-23 inhibitors and EMA MDR inspection findings at multi-product facilities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Regenerative Medicine
Next Generation Immunotherapies Market
Regenerative Medicine
Asia Pacific Platelet Rich Plasma Market
Regenerative Medicine
Degenerative Disc Disease Treatment Market
Regenerative Medicine
Cartilage Degeneration Market
Regenerative Medicine
Bone Regeneration Market
Regenerative Medicine
Platelet Rich Plasma Market
Regenerative Medicine
North America Scar Treatment Market
Regenerative Medicine
North America Regenerative Medicines Market
Regenerative Medicine
Autologous Matrix Induced Chondrogenesis Market
Regenerative Medicine
Epidermal Cell Sheets Market
Regenerative Medicine
Europe Longevity and Anti-Senescence Therapy Market
Regenerative Medicine
Soft Tissue Repair Market
Regenerative Medicine
Cytokine Storm Therapy Market
Regenerative Medicine
Global Vaginal Rejuvenation Market
Regenerative Medicine
Hyper Personalized Medicine Market
Regenerative Medicine
Global Orthopedic Regenerative Surgical Products Market