
 Depyrogenation Oven Market | 2026-2036
Depyrogenation Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Depyrogenation Oven Market Analytics
The EU Green Deal and its pharmaceutical sector decarbonization targets is expanding the addressable market for energy-efficient depyrogenation equipment across European manufacturing sites. Lytzen leverages its Scandinavian engineering heritage to sustain premium positioning in validated batch systems for sterile fill-finish lines. Despatch anchors North American supply through its thermal processing specialization, while Fedegari Group competes on integrated washer-sterilizer-depyrogenation workflows that reduce floor space and utility consumption.
A depyrogenation oven is a thermal processing unit that destroys pyrogens—principally bacterial endotoxins—through sustained dry-heat exposure typically at temperatures exceeding 250 degrees Celsius, with validated dwell times ensuring a three-log or greater endotoxin reduction. Batch ovens retain the largest installed base due to their validation simplicity and flexibility across vial, ampoule, and syringe formats, though continuous ovens are gaining share in high-volume parenteral facilities where throughput optimization drives capital planning. Dry heat technology dominates regulatory submissions and pharmacopeial compliance, while microwave and infrared variants occupy niche positions where rapid cycle development or reduced thermal exposure benefits heat-sensitive elastomeric closures.
The FDA enforces pyrogen control through 21 CFR Part 211 current good manufacturing practice requirements, while the EMA coordinates endotoxin testing harmonization through the European Pharmacopoeia. In Japan, PMDA aligns with ICH Q5A-Q5D guidelines to ensure viral and pyrogen safety in biologics manufacturing. Contract manufacturing organizations must navigate divergent national inspection frameworks when qualifying multi-site depyrogenation protocols. Stakeholders should monitor evolving pharmacopeial chapters on alternative depyrogenation technologies and pre-emptively validate equipment platforms against anticipated regulatory revisions.
Market Dynamics
FDA container closure integrity guidance and EMA endotoxin testing harmonization are tightening validation protocols across parenteral manufacturing, forcing equipment upgrades and extending qualification timelines for thermal processing infrastructure.
Growth Catalysts
- EMA endotoxin testing harmonization:European Pharmacopoeia chapter revisions mandate validated three-log endotoxin reduction, accelerating replacement cycles for non-compliant batch ovens in Germany and Switzerland.
- Biologics manufacturing clusters:mRNA vaccine facilities in Massachusetts and North Carolina require continuous depyrogenation tunnels to match fill-finish line speeds, expanding addressable equipment demand.
- Dry-heat technology dominance:Pharmacopeial compliance advantages over microwave and infrared alternatives sustain regulatory submission preference in parenteral drug applications.
Market Restraints
- Stainless steel and HEPA filter cost volatility:Input material price swings compress OEM margins and extend quotation validity periods for validated equipment contracts.
- Validation service concentration in Germany and Switzerland:Limited qualified thermal mapping specialists create bottlenecks for multi-site CMO qualification schedules.
- Continuous oven technical limitations:Format inflexibility across vial diameter ranges restricts adoption in multiproduct facilities serving fragmented biologics pipelines.
Strategic Opportunities
- EU Green Deal pharmaceutical decarbonization targets:Energy efficiency mandates create replacement demand for legacy convection ovens across Belgian and Dutch manufacturing sites.
- Cell therapy aseptic processing:Autologous manufacturing scale-out requires compact batch systems with rapid format changeover for patient-specific production runs.
- Integrated washer-sterilizer-depyrogenation workflows:Floor space and utility consumption reductions attract greenfield facility investment in Singapore and South Korea.
Industry Challenges
- Thermal validation engineer scarcity:Specialized IQ/OQ/PQ documentation expertise shortages delay site acceptance testing and revenue recognition for equipment suppliers.
- Legacy SCADA integration complexity:Proprietary communication protocols in installed base ovens obstruct unified manufacturing execution system connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Depyrogenation Oven Market |
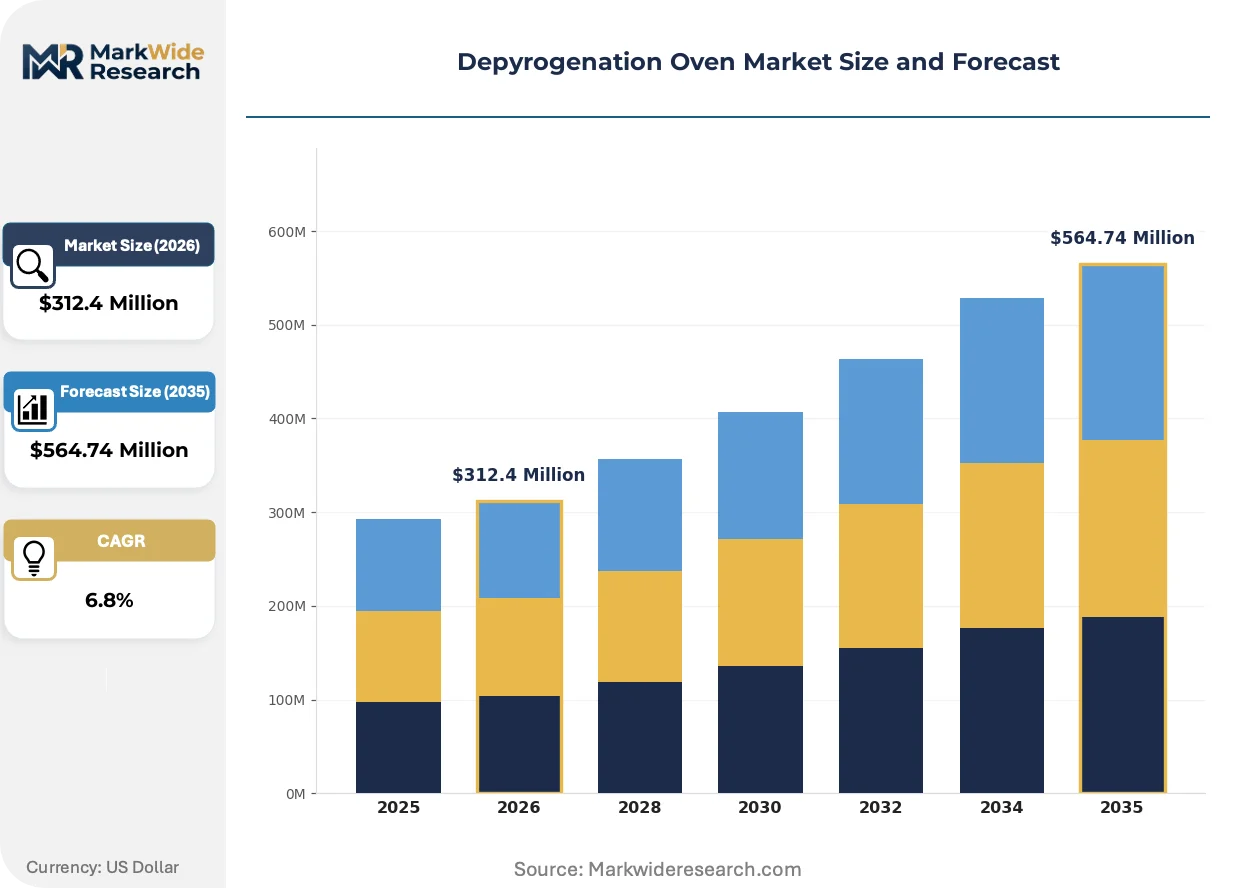
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Ovens, Continuous Ovens, Hybrid Ovens, Conveyor Ovens Technology: Dry Heat, Radiant Heat, Microwave, Infrared End User: Pharmaceutical Companies, Biotechnology Firms, Research Laboratories, Contract Manufacturing Organizations Application: Sterilization, Pyrogen Removal, Sample Preparation, Quality Control |
| Companies Covered | Lytzen, Avantor, Despatch, Fedegari Group, Telstar, Stericox, Biometrix Corporation, Gruenberg, Romaco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Depyrogenation Oven Market Evolving Landscape
Dry-heat depyrogenation equipment is undergoing architectural transformation as regulatory pressure intensifies and biologics manufacturing scales toward continuous processing paradigms.
Continuous tunnel oven technology is modularizing around interchangeable heating zone configurations that accommodate varying vial formats without mechanical changeover. High-volume parenteral facilities in New Jersey and Illinois are adopting these systems to synchronize with isolator-integrated fill-finish lines. The technology is compressing per-unit thermal processing costs while reducing validation burden for format switches.
EU Green Deal pharmaceutical sector decarbonization targets are mandating heat recovery systems and reduced nitrogen consumption in thermal sterilization equipment. German and Danish manufacturing sites face binding energy efficiency disclosures under CSRD-aligned reporting frameworks. Batch oven suppliers are responding with regenerative burner designs and predictive maintenance algorithms that cut utility intensity.
Buyer concentration among contract manufacturing organizations is compressing equipment procurement cycles and unbundling after-sales service contracts. Large CMOs in Massachusetts and North Carolina now demand outcome-based performance guarantees covering endotoxin reduction validation rather than discrete hardware purchases. This shift pressures OEM margin structures while favoring suppliers with captive validation service capabilities.
Depyrogenation Oven Market Segmentation
Depyrogenation oven procurement decisions diverge sharply across user profiles, with pharmaceutical manufacturers prioritizing validated batch systems for regulatory submission while CMOs optimize for format flexibility. Equipment specification cascades through technology choice, thermal uniformity requirements, and integration complexity with existing fill-finish infrastructure.
Product Type:
FDA 21 CFR Part 211 compliance burdens fall heaviest on batch configurations requiring documented IQ/OQ/PQ protocols, while continuous systems face lighter validation loads but demand higher capital commitment.
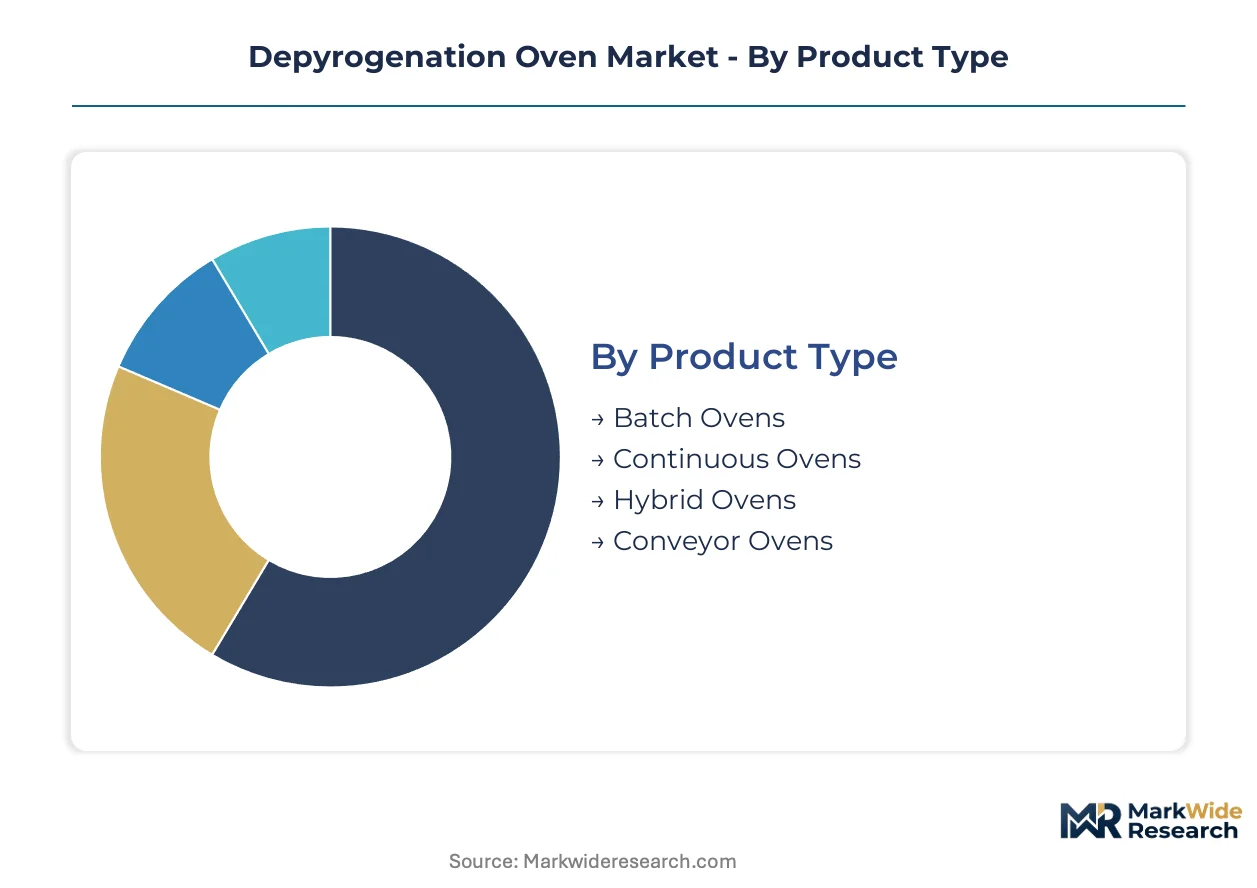
- Batch Ovens:These units process discrete loads of vials, ampoules, or syringes through programmable temperature profiles with validated dwell times exceeding 250°C. Pharmaceutical companies in Germany and Switzerland specify these systems for multi-product facilities where format changeover frequency exceeds 50 cycles annually. The EMA's endotoxin testing harmonization mandates three-log reduction documentation that batch architecture simplifies through isolated chamber validation.
- Continuous Ovens:Tunnel configurations synchronize with high-speed fill-finish lines through modular heating zones and conveyor throughput matching isolator cycle times. mRNA vaccine manufacturing clusters in Massachusetts and North Carolina deploy these systems where single-format production runs exceed 10 million units monthly. PMDA alignment with ICH guidelines in Japan restricts adoption to facilities with dedicated product lines due to revalidation costs for format switches.
- Hybrid Ovens:Dual-mode systems combine batch flexibility with continuous throughput options through interchangeable chamber configurations.
- Conveyor Ovens:Belt-driven thermal processing units serve intermediate volume requirements in research-scale manufacturing environments.
Batch Ovens sits at the top of the volume ranking, with Continuous Ovens climbing the fastest.
Technology:
Capital deployment patterns reveal a cost-tier stratification, with dry-heat platforms commanding premium pricing against emerging alternatives that sacrifice pharmacopeial acceptance for operational speed.
- Dry Heat:Convection and forced-air systems dominate regulatory submissions through pharmacopeial recognition in USP, EP, and JP chapters. The technology's three-log endotoxin reduction validation protocols are established across FDA, EMA, and PMDA inspection frameworks. Biologics manufacturers in the United States, Germany, and Japan specify dry-heat as the default for parenteral drug applications where regulatory risk tolerance approaches zero.
- Radiant Heat:Electric element configurations reduce nitrogen consumption and align with EU Green Deal pharmaceutical decarbonization targets for Belgian and Dutch manufacturing sites. Heat recovery integration and regenerative burner designs cut utility intensity by 15-25% versus conventional convection, attracting replacement demand from legacy equipment installed before CSRD-aligned reporting mandates.
- Microwave:Rapid cycle development benefits niche applications involving heat-sensitive elastomeric closures.
- Infrared:Targeted wavelength heating reduces thermal exposure duration for specialized container formats.
Dry Heat captures the dominant revenue share, with Radiant Heat gaining share fastest on sustainability tailwinds.
End User:
Customer-type concentration shapes margin structures, with large CMOs extracting outcome-based performance guarantees while research laboratories accept standard hardware procurement terms.
- Pharmaceutical Companies:Integrated manufacturers in the United States and Germany deploy validated batch systems across sterile fill-finish lines with captive validation engineering teams. These buyers specify equipment with 20-year service life projections and demand thermal mapping documentation that satisfies multi-site FDA and EMA inspection schedules.
- Contract Manufacturing Organizations:CMOs in Massachusetts and North Carolina now unbundle after-sales service contracts and negotiate endotoxin reduction validation guarantees rather than discrete hardware purchases. Procurement cycles compress as buyer concentration intensifies, pressuring OEM margins while favoring suppliers with captive IQ/OQ/PQ documentation capabilities.
- Biotechnology Firms:Emerging biologics developers prioritize compact batch systems with rapid format changeover for pipeline flexibility.
- Research Laboratories:Academic and government facilities specify lower-throughput units with simplified validation protocols for non-commercial production.
Pharmaceutical Companies sit at the top of the volume ranking, with Contract Manufacturing Organizations climbing the fastest.
Application:
Maturity gradients separate established sterilization protocols from emerging quality control automation where validation frameworks remain under development.
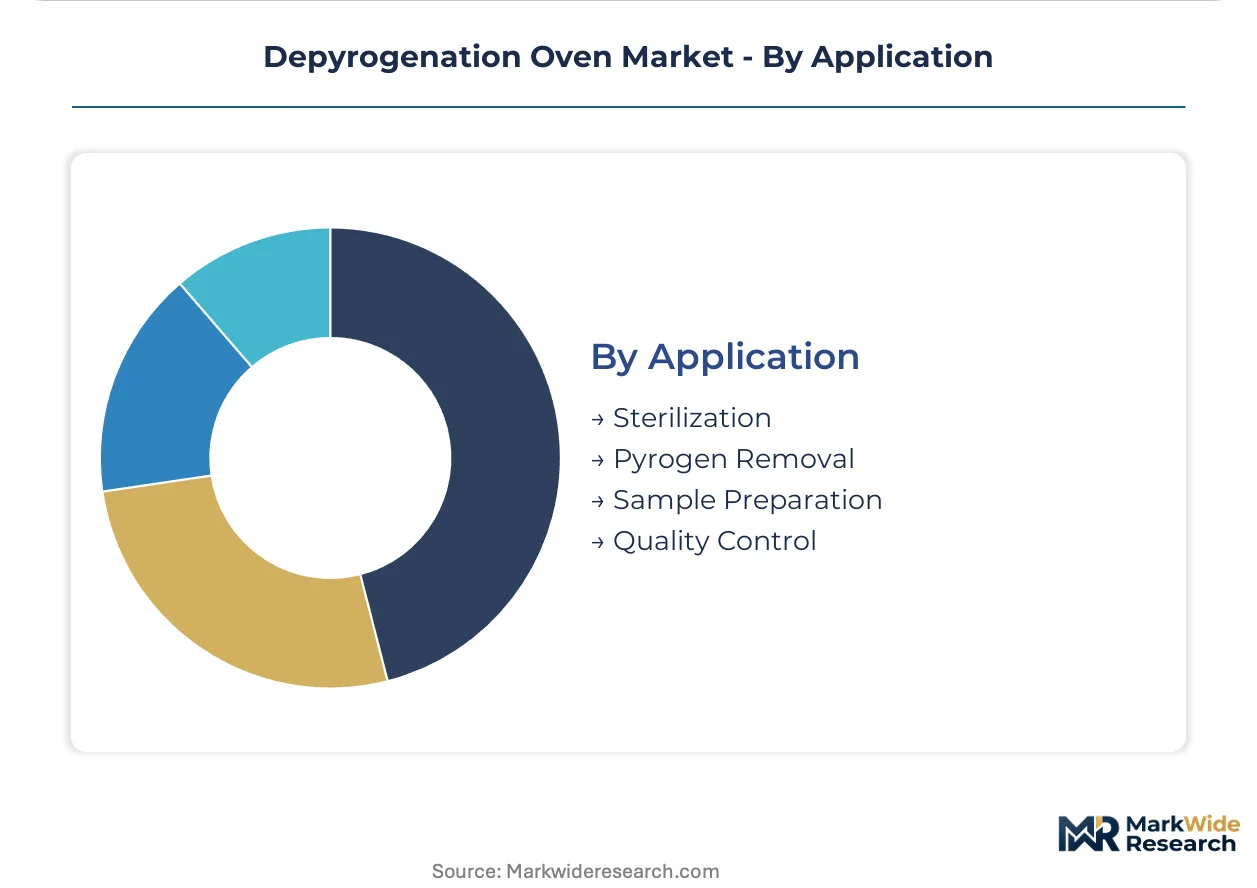
- Sterilization:Terminal sterilization of parenteral containers represents the foundational application with established pharmacopeial methods and inspection precedents across FDA, EMA, and PMDA jurisdictions. The application commands the largest installed base and replacement cycle predictability.
- Pyrogen Removal:Endotoxin inactivation through validated dry-heat exposure drives equipment specification for vial, ampoule, and syringe processing. Demand concentrates in biologics manufacturing where bacterial endotoxin limits are most stringent.
- Sample Preparation:Pre-analytical thermal processing supports laboratory workflows with reduced validation requirements.
- Quality Control:Automated endotoxin testing integration is emerging as equipment suppliers embed LAL-compatible sampling protocols.
Sterilization sits at the top of the volume ranking, with Quality Control climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dry-heat depyrogenation technology originated in mid-20th century European pharmaceutical manufacturing, with German and Swiss engineering firms establishing the foundational validation protocols now codified across pharmacopeial standards worldwide.
United States
mRNA vaccine manufacturing clusters in Massachusetts and North Carolina drive continuous tunnel oven demand to match high-speed fill-finish line throughputs. FDA container closure integrity guidance tightens validation requirements for pyrogen control in parenteral drug applications. The New Jersey and Illinois corridor anchors high-volume parenteral facilities adopting modular heating zone configurations.
Germany
EMA endotoxin testing harmonization through European Pharmacopoeia revisions accelerates replacement cycles for legacy batch ovens in Baden-Württemberg and Bavaria. EU Green Deal pharmaceutical decarbonization targets mandate heat recovery systems and CSRD-aligned energy efficiency disclosures. The Rhine-Main manufacturing belt concentrates validated equipment engineering and thermal mapping specialist services.
Switzerland
Swissmedic inspection frameworks enforce stringent IQ/OQ/PQ documentation standards for sterile fill-finish operations in Basel and Zurich biologics clusters. Limited qualified thermal validation engineers create qualification bottlenecks for multi-site contract manufacturing protocols. The country's precision engineering heritage sustains premium positioning in batch system architecture.
Japan
PMDA alignment with ICH Q5A-Q5D guidelines ensures viral and pyrogen safety in biologics manufacturing across Kanto and Kansai regions. Continuous oven adoption remains restricted to dedicated product lines due to revalidation costs for format switches. Osaka and Tokyo pharmaceutical corridors prioritize dry-heat pharmacopeial compliance over emerging microwave alternatives.
Singapore
Greenfield biologics manufacturing investment in Tuas Biomedical Park attracts integrated washer-sterilizer-depyrogenation workflows reducing floor space and utility consumption. The national pharmaceutical regulator enforces alignment with FDA and EMA inspection precedents for export-oriented production. South Korean and Japanese contract manufacturers co-locate sterile processing infrastructure in the city-state's advanced manufacturing zones.
Depyrogenation Oven Market Competitive Landscape
Capital-heavy thermal processing specialists compete with asset-light validation service integrators across the depyrogenation equipment landscape. The vendor base stratifies between Scandinavian engineering heritage firms, North American thermal processing specialists, and Italian integrated workflow providers. Three archetypes dominate: validated batch system architects, continuous tunnel modularizers, and turnkey sterilization workflow integrators. Competitive moves concentrate on captive validation engineering capabilities and outcome-based performance contracting rather than discrete hardware sales.
Within the premium engineering tier, Lytzen anchors Scandinavian heritage positioning in validated batch systems for sterile fill-finish lines. Despatch occupies the North American supply anchor position through thermal processing specialization. Fedegari Group exemplifies the integrated workflow archetype, competing on unified washer-sterilizer-depyrogenation configurations that compress facility footprint and utility intensity for greenfield investments.
| Leading Market Players |
|---|
| Lytzen |
| Avantor |
| Despatch |
| Fedegari Group |
| Telstar |
| Stericox |
| Biometrix Corporation |
| Gruenberg |
| Romaco |
| Others |
Value Network & Pricing Analysis
Captive validation engineering capabilities anchor both supply position and pricing power in the depyrogenation oven market, as OEMs with in-house IQ/OQ/PQ documentation teams command premium positioning against hardware-only competitors. This vertical integration into thermal mapping and protocol development insulates margins while compressing quotation cycles for large pharmaceutical buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated batch systems with full pharmacopeial documentation from continuous tunnels with modular heating zones and research-scale units with simplified protocols. Price differentiation centers on certification grade—FDA 21 CFR Part 211 tier versus EMA endotoxin testing harmonization tier—and volume scale for multi-site CMO procurement. Cost compression in the standard tier is intensifying because stainless steel and HEPA filter input volatility extends quotation validity periods. Research laboratories exhibit highest price sensitivity; integrated biologics manufacturers with captive validation teams show lowest.
Supply Chain Analysis
Domestic-content mandates in the EU Green Deal pharmaceutical decarbonization framework are reshaping sourcing for regenerative burner components and heat recovery systems. Supply concentrates in Germany, Switzerland, and the United States for precision thermal processing hardware. Raw material dependencies rest on 316L stainless steel, HEPA filtration media, and nitrogen supply systems. Single-source vulnerability runs through qualified thermal mapping specialist services concentrated in the Rhine-Main belt. Distribution runs through direct OEM sales for validated equipment and regional service integrators for aftermarket thermal validation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EMA endotoxin testing harmonization and FDA container closure integrity guidance continuously tighten equipment replacement cycles and extend qualification timelines.
For Market Incumbents: Cement captive validation engineering capabilities through targeted hiring in Germany and Switzerland where thermal mapping specialist scarcity creates bottlenecks. Deepen backward integration into HEPA filtration media supply to offset stainless steel cost volatility. Defend against modular continuous tunnel entrants by embedding predictive maintenance algorithms that cut utility intensity for EU Green Deal compliance. For New Entrants and Emerging Players: Direct-to-CMO digital sales channels bypass incumbent field service networks and compress procurement cycles for outcome-based performance contracts. Target cell therapy aseptic processing in Massachusetts and North Carolina where autologous manufacturing scale-out demands compact batch systems with rapid format changeover. Lead with energy efficiency guarantees aligned to CSRD-aligned reporting frameworks rather than hardware specifications. For Investors and Strategic Acquirers: Roll-up economics work for regional validation service specialists because thermal mapping engineer scarcity and multi-site CMO qualification complexity create durable margin pools. Five-to-ten year viability hinges on pharmacopeial chapter expansion into alternative depyrogenation technologies. Watch for PMDA alignment with ICH guideline revisions as signal for Japanese replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Validation Service Capability Buildout | In-house IQ/OQ/PQ teams capture CMO outcome-based contracts and compress revenue recognition cycles. |
| Heat Recovery System Integration | Regenerative burner designs satisfy EU Green Deal pharmaceutical decarbonization mandates in Belgium and the Netherlands. |
| Modular Continuous Tunnel Development | Interchangeable heating zone configurations reduce revalidation burden for format switches in high-volume parenteral facilities. |
| Thermal Mapping Specialist Acquisition | Captive validation engineering eliminates qualification bottlenecks for multi-site CMO protocols in Switzerland. |
| Isolator-Integrated Workflow Partnership | Synchronized conveyor throughput matching fill-finish line speeds anchors New Jersey and Illinois corridor demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sterile fill-finish line engineers, thermal validation specialists, CMO procurement directors, and regulatory affairs leads with secondary validation against FDA 21 CFR Part 211 guidance documents, European Pharmacopoeia chapter revisions, PMDA ICH alignment notifications, and EPC contractor equipment procurement databases. Bottom-up equipment shipment tracking and top-down pharmaceutical capital expenditure analysis triangulated market sizing.
Historical reference periods anchored volume and value projections across the modeling period, with analytical frameworks segmenting by product architecture, thermal technology type, end-user procurement archetype, and regional regulatory cluster. CAGRs derived from replacement cycle analysis, greenfield facility investment pipelines, and pharmacopeial compliance deadline schedules. Forecast inputs incorporated stainless steel price indices, HEPA filtration media supply lead times, and thermal validation engineer availability metrics.
The model assumes a particular technology adoption path; alternative pathways for microwave and infrared depyrogenation would alter the outlook if pharmacopeial recognition accelerates. Forecasts reflect assumptions around EMA endotoxin testing harmonization implementation timelines, EU Green Deal enforcement intensity, and CMO buyer concentration trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Continuous Manufacturing Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Flexible Manufacturing Systems for Pharmaceutical Industry Market
Pharmaceutical Equipment
US Pharmaceutical Isolators Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
Inhalation CDMO Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmacy Automation Systems Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market