
 Marburg Virus Disease Therapeutics Market | 2026-2036
Marburg Virus Disease Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Marburg Virus Disease Therapeutics Market Foresight
Modular platform technologies for rapid therapeutic deployment is restructuring procurement patterns among biodefense agencies and outbreak-response coalitions. Regeneron Pharmaceuticals leverages its VelociSuite antibody discovery engine to compress development timelines for filovirus candidates. Emergent BioSolutions anchors government contracting relationships through its established manufacturing infrastructure for medical countermeasures. Moderna competes with mRNA platform flexibility that enables swift sequence adaptation against emerging Marburg variants.
Marburg Virus Disease therapeutics comprise pharmaceutical interventions targeting the filovirus responsible for severe hemorrhagic fever, including monoclonal antibodies engineered for glycoprotein neutralization and vaccines utilizing viral vectors or nucleic acid platforms to elicit protective immune responses. These products serve national stockpile programs, outbreak containment operations, and clinical management of confirmed infections in high-containment settings. Vaccines command the largest development pipeline investment due to prophylactic demand from at-risk healthcare workers and military personnel. Monoclonal Antibodies capture premium positioning as post-exposure therapeutics where rapid viral load reduction determines survival outcomes. RNA Interference remains nascent but attracts capital for its theoretical capacity to silence viral replication machinery across genetically diverse strains.
The FDA's Animal Rule governs efficacy requirements for Marburg therapeutics, permitting licensure based on animal model survival data when human challenge trials are ethically impermissible. BARDA funding mechanisms and the Strategic National Stockpile procurement framework shape demand concentration and manufacturing scale requirements for suppliers. The WHO R&D Blueprint and African regulatory harmonization initiatives will determine market access velocity for candidates targeting endemic regions. Stakeholders must monitor epidemic frequency trends and platform technology transfer agreements to calibrate capacity investments against unpredictable outbreak-driven procurement surges.
Market Dynamics
BARDA procurement cycles and the FDA's Animal Rule pathway are compressing development timelines while concentrating supplier relationships around platform-technology holders with proven manufacturing scale.
Growth Catalysts
- Strategic National Stockpile mandates:The United States maintains forward-deployed countermeasure reserves requiring sustained replenishment contracts. This creates predictable offtake for qualified suppliers.
- VelociSuite antibody discovery engines:Modular platform technologies enable sequence-to-candidate compression from months to weeks. Biodefense agencies prioritize suppliers with demonstrated rapid-response capabilities.
- WHO R&D Blueprint prioritization:Marburg's designation as a priority pathogen accelerates regulatory harmonization across African endemic regions. This streamlines clinical trial site activation and eventual market access.
Market Restraints
- High-containment manufacturing scarcity:Biosafety Level 4 production capacity concentrates among a handful of government-contracted facilities. Facility qualification timelines extend 24-36 months.
- Filovirus animal model limitations:Non-human primate studies cost substantially more than standard preclinical programs. This restricts candidate progression to well-capitalized developers.
- Substitution by platform redundancy:Multi-pathogen vaccine platforms threaten single-agent Marburg candidates. Investors favor flexible technologies over dedicated filovirus programs.
Strategic Opportunities
- Uganda-Rwanda border surveillance integration:Cross-border outbreak detection networks create demand for rapid-deployment stockpiles. Pre-positioned therapeutics reduce response latency.
- EMA's PRIME designation pathway:Accelerated assessment for public health emergencies reduces time-to-authorization. European procurement diversification follows successful designations.
- mRNA-LNP formulation convergence:Combining nucleic acid platforms with established lipid delivery systems enables rapid strain adaptation. This addresses viral genetic drift concerns.
Industry Challenges
- BSL-4 operational talent scarcity:Qualified personnel for high-containment manufacturing and clinical management remain limited. Training pipelines require 18-24 month development cycles.
- EMA-FDA divergence on surrogate endpoints:Differing evidentiary standards for Animal Rule-equivalent pathways create duplicate study requirements. This extends registration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marburg Virus Disease Therapeutics Market |
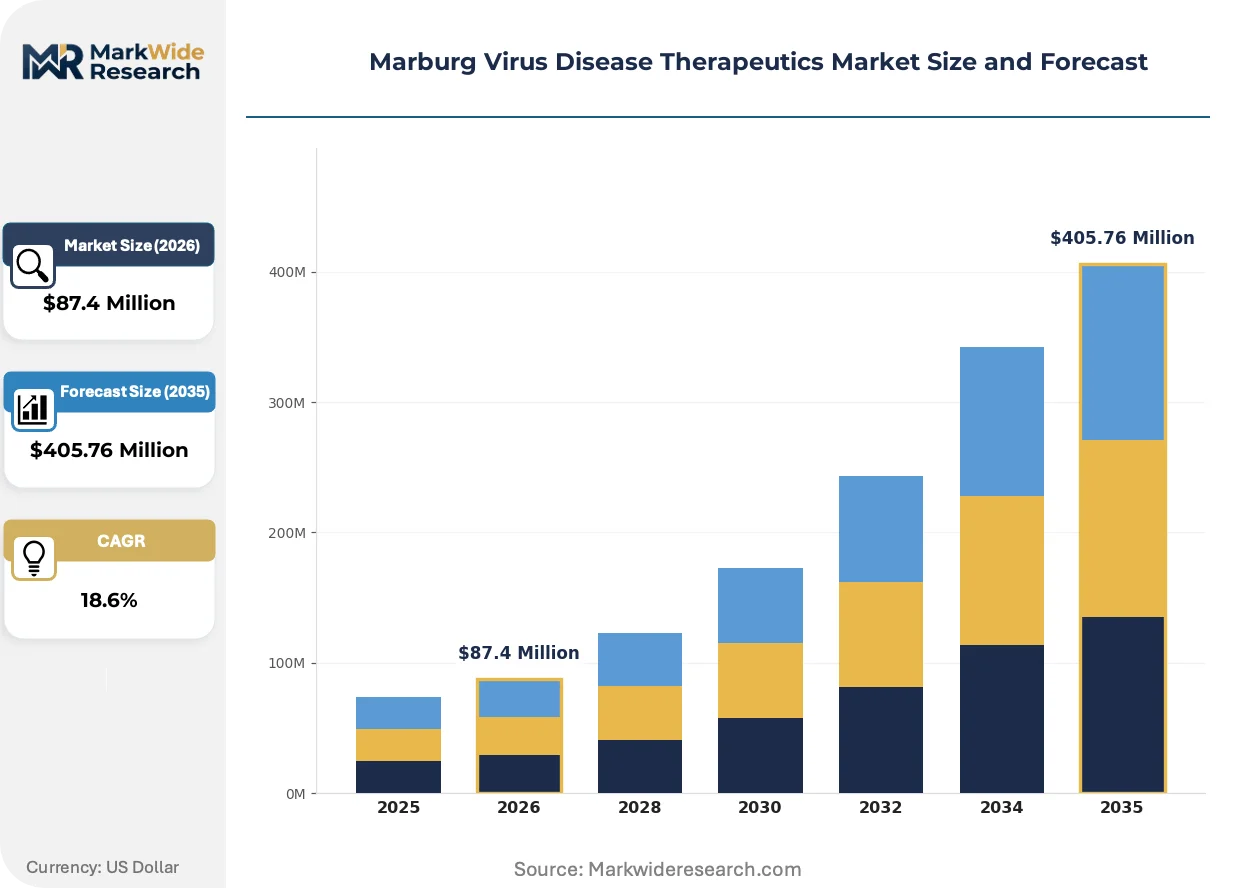
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $405.76 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Small Molecules, RNA Interference Therapy Area: Treatment, Immunotherapy, Prophylaxis, Supportive Care Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation End User: Hospitals, Research Institutions, Clinics, Home Care |
| Companies Covered | Regeneron Pharmaceuticals, Inc., Emergent BioSolutions Inc., Moderna, Inc., Janssen Pharmaceuticals, Gilead Sciences, Inc., Bavarian Nordic, BioCryst Pharmaceuticals, Integrated Biotherapeutics, Mapp Biopharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marburg Virus Disease Therapeutics Market Shifts & Advancements
Platform standardization is compressing the gap between pathogen emergence and therapeutic availability, while regulatory frameworks adapt to accommodate evidence generation without human challenge studies.
Multivalent filovirus vaccines are unifying Marburg and Ebola glycoprotein targets within single immunization regimens. BARDA and the Strategic National Stockpile favor candidates reducing stockpile complexity. This is unifying procurement specifications around cross-protective candidates rather than single-pathogen products.
EMA's PRIME scheme for public health emergencies is accelerating assessment timelines for Marburg therapeutics. Sponsors receive enhanced regulatory dialogue and accelerated review commitments. African endemic countries are responding by aligning national registration requirements with EMA determinations.
Stockpile rotation contracts are displacing traditional purchase-and-hold arrangements. BARDA now requires vendors to manage shelf-life extension through real-time stability data. European and African procurement authorities are adopting similar lifecycle-management terms.
Marburg Virus Disease Therapeutics Market Segmentation
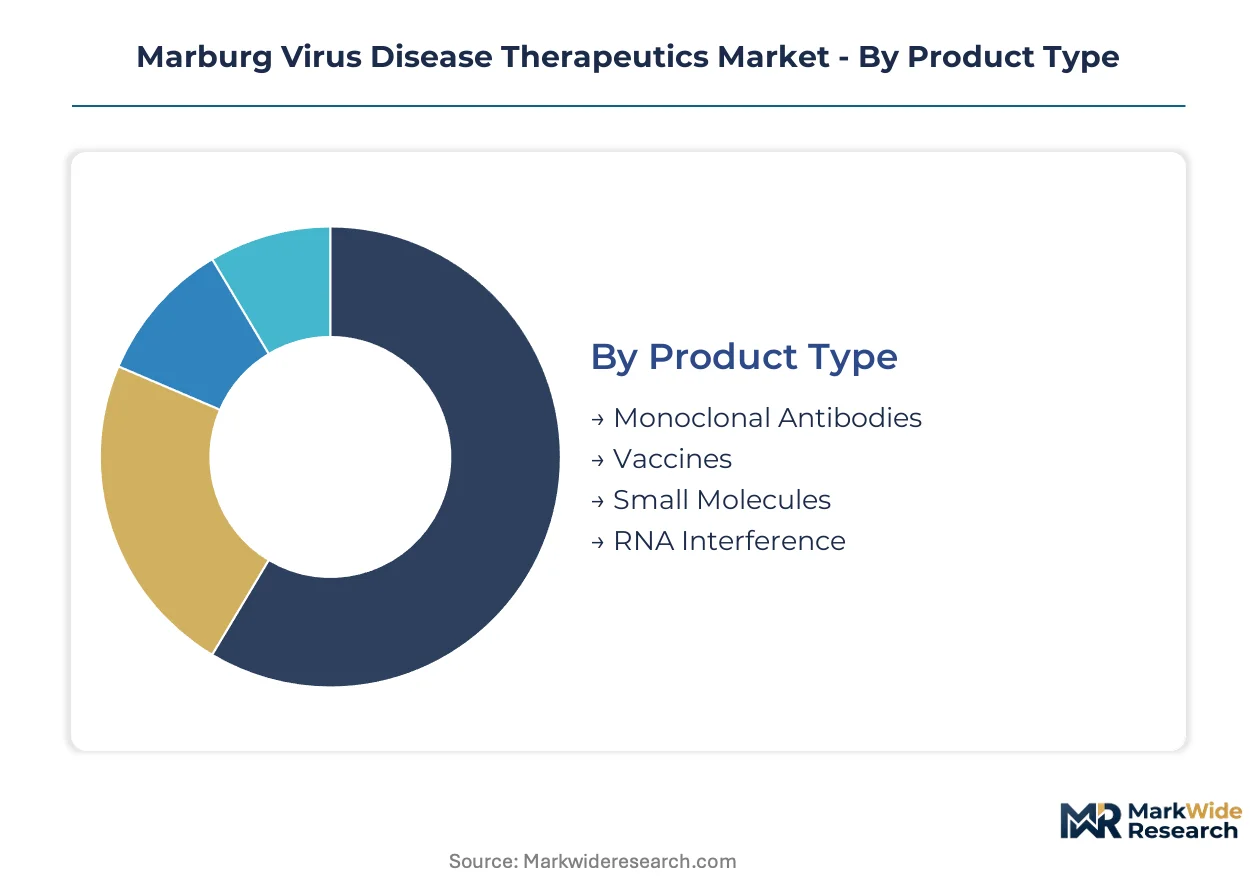
Segmentation in Marburg therapeutics reveals divergent capital requirements and risk profiles across product modalities. BARDA procurement patterns favor segments with demonstrated manufacturing scalability and regulatory precedent under the Animal Rule pathway.
Product Type:
Vaccines demand the heaviest upfront investment due to BSL-4 manufacturing infrastructure and non-human primate efficacy studies. Monoclonal antibodies require substantial but more contained capital outlays for cell line development and single-use bioreactor deployment.
- Monoclonal Antibodies:Engineered immunoglobulins targeting viral glycoproteins for post-exposure viral neutralization. Demand concentrates in the United States Strategic National Stockpile, where rapid-deployment requirements prioritize candidates with proven stability profiles and established cold-chain logistics.
- Vaccines:Viral vector and nucleic acid platforms inducing protective immunity against Marburg glycoproteins. Investment flows toward multivalent filovirus candidates that unify Marburg and Ebola targets, reducing stockpile complexity for biodefense agencies.
- Small Molecules:Oral antiviral compounds targeting viral polymerase or entry mechanisms.
- RNA Interference:Therapeutic oligonucleotides designed to silence viral replication machinery through sequence-specific gene silencing.
Vaccines absorb the bulk of installed capacity; RNA Interference is expanding most quickly as platform technologies mature.
Therapy Area:
Prophylaxis commands premium pricing and predictable offtake from military and healthcare worker immunization programs. Treatment segments face sporadic demand tied to outbreak frequency, compressing revenue visibility.
- Prophylaxis:Preventive interventions administered prior to exposure risk, including pre-deployment vaccination for laboratory personnel and outbreak response teams. Procurement runs through the United States Department of Defense and BARDA stockpile mandates.
- Treatment:Curative interventions targeting active infection to reduce viral load and improve survival outcomes. Demand surges correlate with confirmed outbreak declarations in Uganda, Rwanda, and other endemic regions.
- Immunotherapy:Immune-modulating approaches enhancing host defense responses.
- Supportive Care:Adjunctive interventions managing hemorrhagic fever complications.
Prophylaxis anchors manufacturer revenue stability; Treatment exhibits the steepest expansion trajectory during active outbreak periods.
Delivery Mode:
Intravenous administration dominates clinical-grade therapeutics requiring precise dosing in high-containment settings. Subcutaneous formulations attract development investment for field-deployable prophylaxis.
- Intravenous:Direct vascular administration enabling rapid systemic distribution of monoclonal antibodies and antiviral compounds. Hospital-based end users in the United States and European outbreak response networks specify IV stability as a procurement requirement.
- Subcutaneous:Tissue-layer injection suitable for self-administered prophylaxis in remote settings. Development priorities align with African endemic region deployment needs and military field-use specifications.
- Oral:Enteric delivery of small-molecule antivirals.
- Inhalation:Pulmonary administration for localized antiviral deposition.
Intravenous delivery retains the largest share of qualified manufacturing capacity; Subcutaneous routes are gaining share fastest for stockpile diversification.
End User:
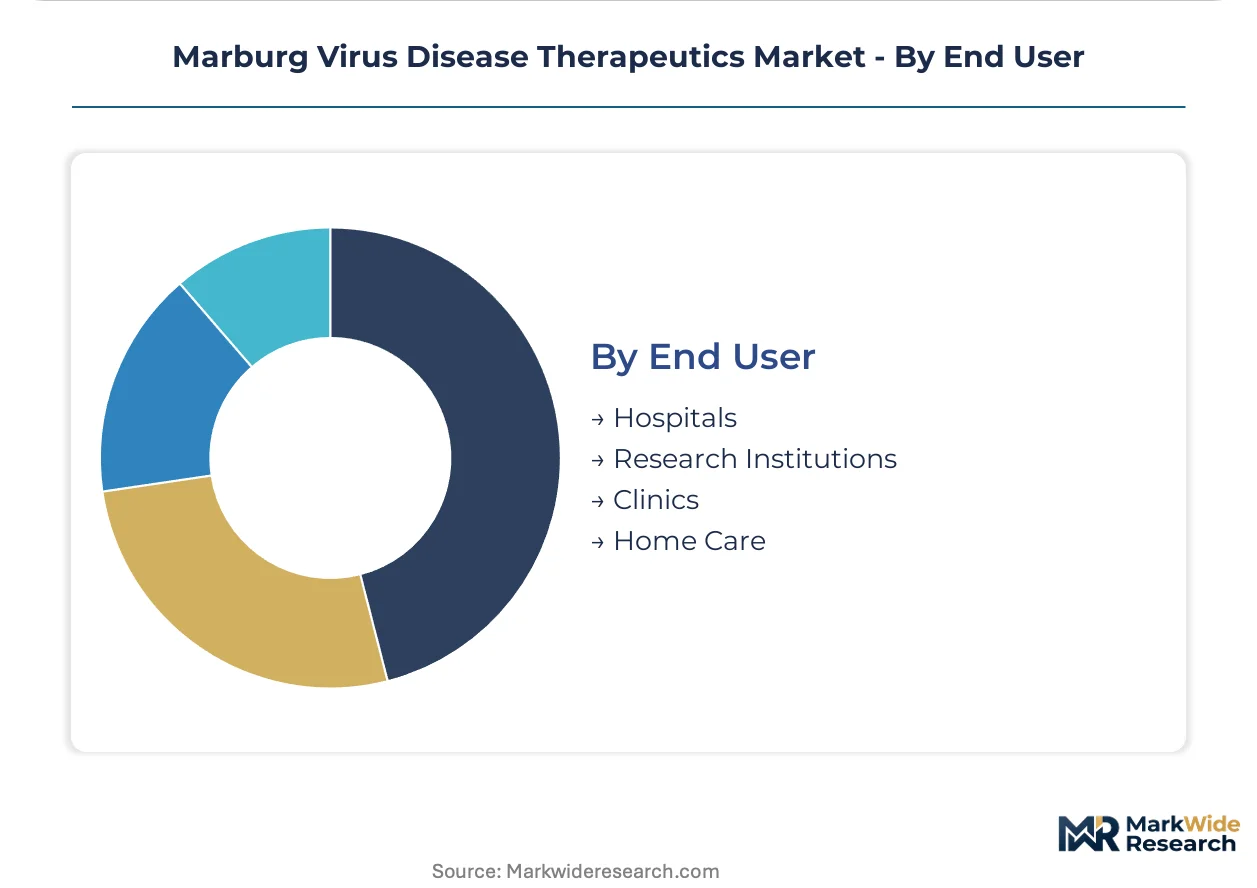
Hospitals concentrate demand for treatment-grade therapeutics requiring specialized containment infrastructure. Research institutions drive early-phase clinical trial volume and platform technology validation.
- Hospitals:Acute care facilities managing confirmed Marburg infections in BSL-4 isolation units. The United States hospital network coordinates with the Strategic National Stockpile for therapeutic access during domestic containment scenarios.
- Research Institutions:Academic and government laboratories conducting preclinical studies and early-phase clinical trials. Funding flows from the National Institutes of Health and BARDA support non-human primate study requirements.
- Clinics:Outpatient facilities in endemic regions.
- Home Care:Self-administered prophylaxis for at-risk personnel.
Hospitals dominate current procurement volume; Research Institutions are climbing the fastest as pipeline candidates advance through Animal Rule pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of Marburg therapeutics concentrates in BSL-4 manufacturing facilities across the United States and Western Europe, while consumption demand clusters around endemic African regions and strategic stockpile programs in North America. This geographic mismatch shapes logistics networks and regulatory harmonization priorities.
United States
BARDA contracts and Strategic National Stockpile mandates drive the majority of global procurement volume for monoclonal antibodies and vaccine candidates. The FDA's Animal Rule pathway governs licensure standards for all Marburg countermeasures entering federal stockpiles. Maryland's biotech corridor near Fort Detrick anchors multiple government-contracted manufacturing facilities with active BSL-4 capacity.
Germany
EMA's PRIME designation for public health emergencies accelerates assessment timelines for Marburg therapeutics targeting European stockpile diversification. The Paul-Ehrlich-Institut coordinates with African regulators through WHO R&D Blueprint harmonization initiatives. Marburg itself hosts specialized virology research infrastructure supporting filovirus therapeutic development.
Uganda
Outbreak response demand surges concentrate in the country's western districts bordering the DRC, where cross-border surveillance networks trigger rapid-deployment stockpile requests. The national pharmaceutical regulator aligns registration requirements with EMA determinations to streamline trial site activation. Kampala's infectious disease research cluster coordinates clinical management protocols for confirmed infections.
Rwanda
Border surveillance integration with Uganda creates demand for pre-positioned therapeutics reducing response latency during cross-border outbreak scenarios. The Rwanda Food and Drugs Authority participates in African regulatory harmonization initiatives targeting streamlined market access. Kigali's emerging biotech infrastructure supports regional distribution hub development for emergency countermeasures.
Switzerland
Swissmedic's engagement with EMA-FDA convergence efforts addresses surrogate endpoint standardization challenges for Animal Rule-equivalent pathways. Geneva-based international health organizations coordinate outbreak response financing mechanisms. Basel's pharmaceutical manufacturing cluster provides specialized containment infrastructure for European stockpile contributions.
Marburg Virus Disease Therapeutics Market Competitive Landscape
The competitive structure tilts toward platform-technology holders with established government contracting relationships and proven BSL-4 manufacturing scale. Supplier concentration remains high due to biosafety containment requirements and non-human primate study costs that restrict candidate progression to well-capitalized developers. Three archetypes dominate: modular platform specialists, government-contracted manufacturers, and nucleic acid platform competitors. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms position for BARDA procurement cycles.
Among platform-technology specialists, Regeneron Pharmaceuticals, Emergent BioSolutions, and Moderna occupy distinct positions within the supplier hierarchy. Regeneron exemplifies the antibody discovery engine archetype with capabilities for sequence-to-candidate compression. Emergent BioSolutions anchors the government-contracted manufacturing tier through established relationships with biodefense procurement programs. Moderna represents nucleic acid platform flexibility enabling rapid sequence adaptation against emerging viral variants. Each firm sits within a differentiated competitive space defined by manufacturing infrastructure, regulatory precedent, and platform modularity.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals, Inc. |
| Emergent BioSolutions Inc. |
| Moderna, Inc. |
| Janssen Pharmaceuticals |
| Gilead Sciences, Inc. |
| Bavarian Nordic |
| BioCryst Pharmaceuticals |
| Integrated Biotherapeutics |
| Mapp Biopharmaceutical |
| Others |
Supply & Pricing Matrix
Bifurcation between Animal Rule-qualified premium therapeutics and pre-qualified development candidates manifests in contract structures and manufacturing access tiers. BARDA stockpile procurement commands premium pricing for FDA-cleared countermeasures with established BSL-4 production records, while developmental candidates face cost compression from platform redundancy and substitution risk.
Pricing Analysis
Margin tightening in pre-qualified candidate tiers reflects non-human primate study cost burdens and extended facility qualification timelines. Contract-based long-term offtake dominates BARDA and Strategic National Stockpile procurement, with pricing differentiation anchored in FDA licensure status and demonstrated cold-chain stability. Cost-down pressure accelerates on single-pathogen programs as multivalent filovirus candidates capture procurement preference. Military and healthcare worker prophylaxis segments exhibit lowest price sensitivity; research institutions and early-stage developers face acute budget constraints.
Supply Chain Analysis
Direct-to-government channels handle biodefense agency demand through sole-source and limited-competition awards. Manufacturing concentrates in the United States, Germany, and Switzerland where BSL-4 infrastructure and regulatory precedent cluster. Raw material dependencies center on non-human primate supply chains, specialized cell culture media, and lipid nanoparticle formulation components. Single-source vulnerability in qualified BSL-4 facility capacity creates supply risk. Distribution runs through federal stockpile depots and pre-positioned regional hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Animal Rule pathway erects a formidable cost-of-compliance barrier, requiring non-human primate efficacy data and BSL-4 manufacturing validation that eliminates undercapitalized entrants.
For Market Incumbents: Lock in government contracting relationships through multi-year stockpile rotation agreements before platform redundancy erodes single-pathogen premiums. Expand BSL-4 capacity in Maryland's Fort Detrick corridor to capture BARDA procurement cycle timing. Defend against mRNA platform substitution by accelerating multivalent filovirus combination programs. For New Entrants and Emerging Players: Biodefense subcontractor partnerships offer the most penetrable entry vector for developers lacking direct BARDA relationships. Target Uganda-Rwanda border surveillance integration programs where rapid-deployment stockpile demand outpaces qualified supplier capacity. Pursue EMA PRIME designation as a regulatory credibility shortcut for European procurement diversification. For Investors and Strategic Acquirers: Re-rating potential sits with platform-technology holders possessing VelociSuite-equivalent antibody discovery engines given WHO R&D Blueprint prioritization acceleration. Five-to-ten year viability hinges on epidemic frequency trends and manufacturing scale sustainability. Monitor African regulatory harmonization implementation velocity as inflection signal for endemic region market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Animal Rule Licensure Pathway | FDA clearance under this pathway enables BARDA stockpile eligibility and premium contract terms. |
| BSL-4 Manufacturing Scale-Up | Facility qualification in Maryland or Marburg anchors government contracting relationships and supply security. |
| Multivalent Filovirus Pipeline Expansion | Combining Marburg and Ebola targets reduces stockpile complexity and captures procurement preference. |
| African Regulatory Harmonization Engagement | WHO R&D Blueprint alignment streamlines trial site activation in Uganda and Rwanda outbreak corridors. |
| Platform Technology Licensing Agreement | VelociSuite or mRNA-LNP partnerships compress development timelines for emerging variant response. |
Research Methodology
Independent corroboration across biodefense procurement officers, BSL-4 facility operations directors, and regulatory affairs specialists at filovirus therapeutic developers underwrites the qualitative findings. Primary interviews with BARDA program managers, Strategic National Stockpile logistics coordinators, and African infectious disease research institute leadership combined with secondary validation from FDA Animal Rule guidance documents, EMA PRIME designation records, and WHO R&D Blueprint priority pathogen listings. Bottom-up therapeutic pipeline assessment and top-down government contracting budget analysis provided triangulation.
Rate-of-change decomposition across product type, therapy area, delivery mode, and end user segmentation dimensions structured the analytical framework over the projection horizon. CAGRs derived from epidemic frequency scenario modeling, stockpile replenishment cycle analysis, and platform technology adoption curves. Non-human primate study cost trajectories and BSL-4 facility capacity expansion timelines served as industry-specific forecast inputs.
Caveats apply where epidemic declaration timing, regulatory pathway divergence between FDA and EMA, and platform technology obsolescence could materially shift the outlook. Forecasts reflect documented assumptions regarding BARDA funding continuity and African regulatory harmonization progress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Cancer Vaccines Market
Pharmaceuticals
Global Aromatase Inhibitors Drug Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Norway Pharmaceutical Market
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Minocycline Hydrochloride Market
Pharmaceuticals
Global DPT Vaccine Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Cryptococcosis Therapeutics Market