
 Pharmaceutical Glass Vials and Ampoules Market | 2026-2036
Pharmaceutical Glass Vials and Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Glass Vials and Ampoules Market Analytics
Germany is narrowing the supply gap for borosilicate glass tubing through expanded melting capacity near Mainz and Mitterteich. Gerresheimer AG leverages backward integration into tubular glass production to secure feedstock for its vial finishing lines. Schott AG anchors European supply of FIOLAX clear and amber glass, the dominant pharmaceutical tubing grade worldwide. Stevanato Group differentiates through integrated capabilities spanning glass primary packaging, inspection systems, and containment device assembly.
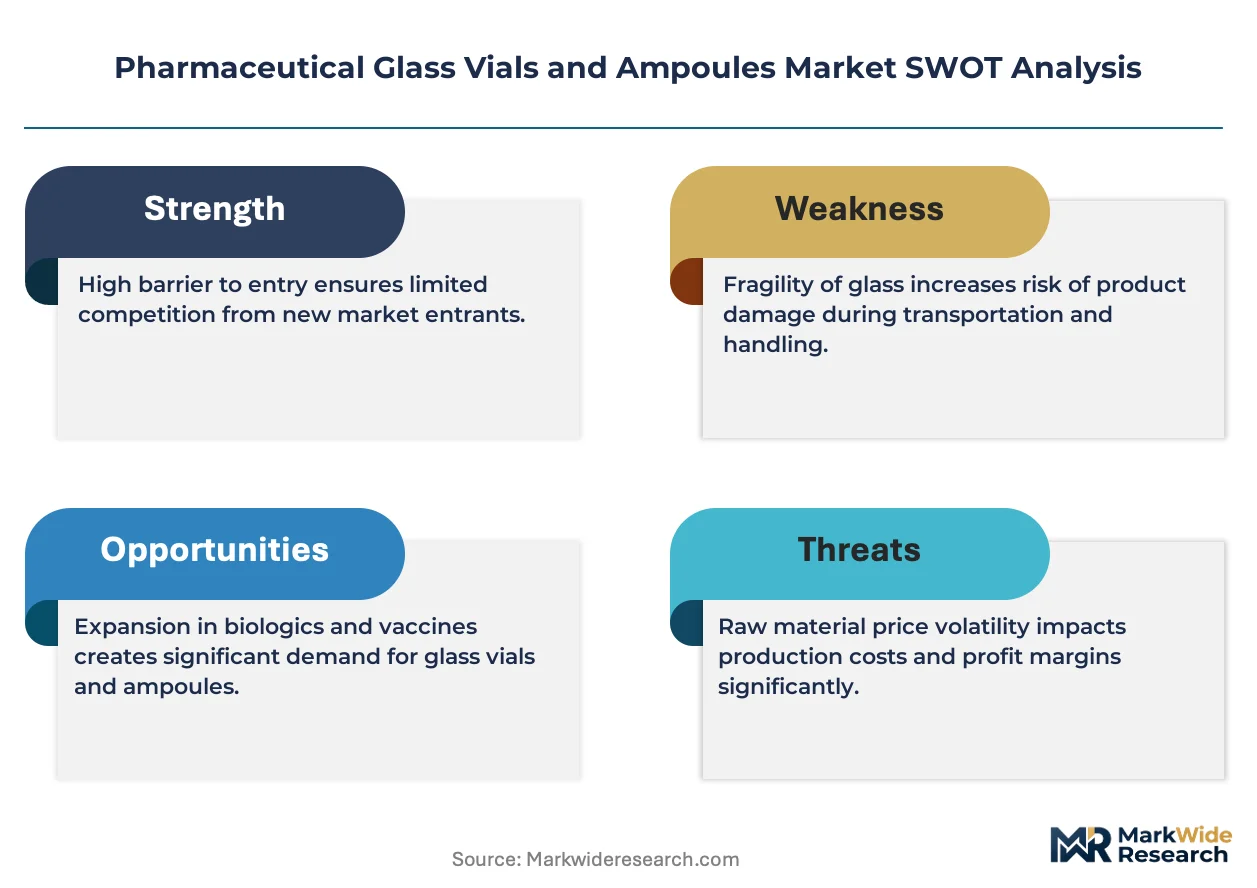
Pharmaceutical glass vials and ampoules are rigid containers fabricated from borosilicate or soda-lime glass, typically meeting hydrolytic resistance Class I or II per pharmacopeial standards, designed to maintain sterility, chemical inertness, and dimensional precision for parenteral drug storage. Vials dominate volume demand across injectable and vaccine applications, where multi-dose formats and lyophilization compatibility command premium positioning. Type I borosilicate glass captures the highest-margin segment due to its superior chemical durability for biologics and sensitive formulations, while Type III soda-lime glass retains cost-driven volume in generic small-molecule injectables. Ampoules face structural pressure from prefillable syringes and cartridges in vaccine delivery, though they persist in emerging-market hospital settings where single-use break-open formats reduce contamination risk.
FDA enforces container closure system integrity under USP <1207> for sterile product packaging, while EMA's MDR elevates traceability and extractables testing burdens for glass suppliers accessing European markets. India's CDSCO mandates BIS certification for imported glass primary packaging, creating compliance friction for multinational suppliers serving domestic generic injectable manufacturers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP glass classifications, as divergence in hydrolytic test methods continues to fragment qualification protocols and inflate regulatory submission costs for multi-region product registrations.
Market Dynamics
Europe's MDR and F-Gas Regulation are compressing supplier margins while accelerating consolidation among glass manufacturers capable of certifying hydrolytic resistance Class I at scale.
Growth Catalysts
- Biologics expansion:Parenteral biologics require Type I borosilicate glass for protein stability, pulling demand from CDMOs and originators alike. FDA's USP <1207> container closure integrity requirements tighten specification windows for these applications.
- EMA traceability mandates:MDR Article 27 unique device identification rules force serialization investments that favor suppliers with integrated inspection and track-and-trace capabilities.
- Lyophilization compatibility:Freeze-dried vaccines and antibody-drug conjugates need specialized vial geometries, creating premium positioning for manufacturers with dedicated mold tooling.
Market Restraints
- Borosilicate feedstock concentration:Tubular glass melting capacity clusters in Germany and limited alternative suppliers expose finishers to input bottlenecks during demand spikes.
- Prefillable syringe substitution:Cartridge and syringe formats displace ampoules in vaccine delivery, eroding volume in hospital segments previously dependent on break-open glass.
- Extractables testing burden:EMA's elevated elemental impurity screening under ICH Q3D extends qualification timelines and inflates R&D costs for new glass formulations.
Strategic Opportunities
- India CDSCO compliance services:BIS certification requirements for imported primary packaging create advisory revenue streams for testing laboratories and regulatory consultants.
- Ready-to-use (RTU) vial formats:Sterilized, pre-washed, and pre-capped vials reduce fill-finish line complexity for biotech firms lacking in-house depyrogenation tunnels.
- EU Green Deal alignment:Electric melting furnace retrofits qualify glass manufacturers for carbon border adjustment mechanism exemptions and green procurement preferences.
Industry Challenges
- Pharmacopeial harmonization friction:Divergent USP, EP, and JP hydrolytic test methods force redundant qualification studies, fragmenting multi-region submission strategies.
- Specialized mold engineering scarcity:Lyophilization vial and nested container designs require precision glass-forming expertise concentrated among aging toolmaking workforces in Germany and Italy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Glass Vials and Ampoules Market |
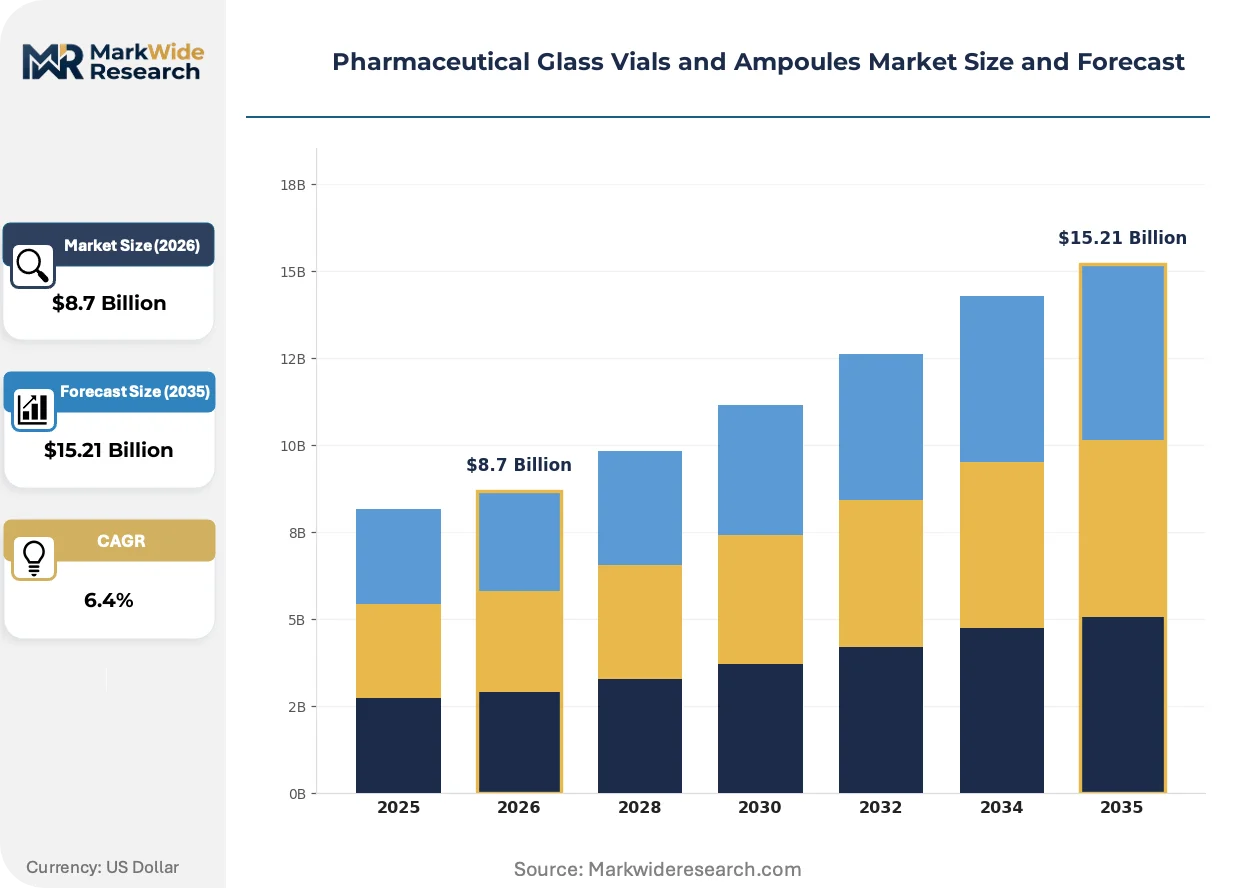
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Cartridges, Syringes Material: Type I Glass, Type II Glass, Type III Glass, Plastic Application: Injectables, Vaccines, Biotechnology Drugs, Diagnostics End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturers, Hospitals |
| Companies Covered | Gerresheimer AG, Schott AG, Stevanato Group, SGD Pharma, Nipro Corporation, West Pharmaceutical Services, Ardagh Group, Bormioli Pharma, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Glass Vials and Ampoules Market Evolving Landscape
Container closure systems are evolving from commodity supply to integrated drug-device platforms, with functionality, sustainability credentials, and regulatory pre-certification becoming primary purchase criteria alongside unit cost.
Copolymer-coated borosilicate glass is hybridizing chemical inertness with mechanical durability. Biologics manufacturers adopting these containers reduce protein adsorption and glass delamination risks during shelf life. The technology is compressing traditional uncoated glass margins in high-value injectable segments while opening formulation possibilities for sensitive monoclonal antibodies previously requiring polymer alternatives.
EMA's F-Gas Regulation is forcing refrigerant transitions in pharmaceutical cold chains. Glass primary packaging must now demonstrate thermal shock resistance across wider temperature excursions as logistics operators phase down hydrofluorocarbon-based cooling systems. Vaccine distributors in Northern Europe are qualifying alternative insulation configurations that expose vials to more aggressive freeze-thaw cycles.
Biotech procurement teams are consolidating supplier panels around end-to-end containment platforms. Single-source contracts spanning glass primary packaging, elastomeric closures, and delivery devices are displacing multi-vendor assembly models. This concentration is most visible among mid-cap biotech firms in Massachusetts and North Carolina seeking to streamline FDA submission documentation.
Pharmaceutical Glass Vials and Ampoules Market Segmentation
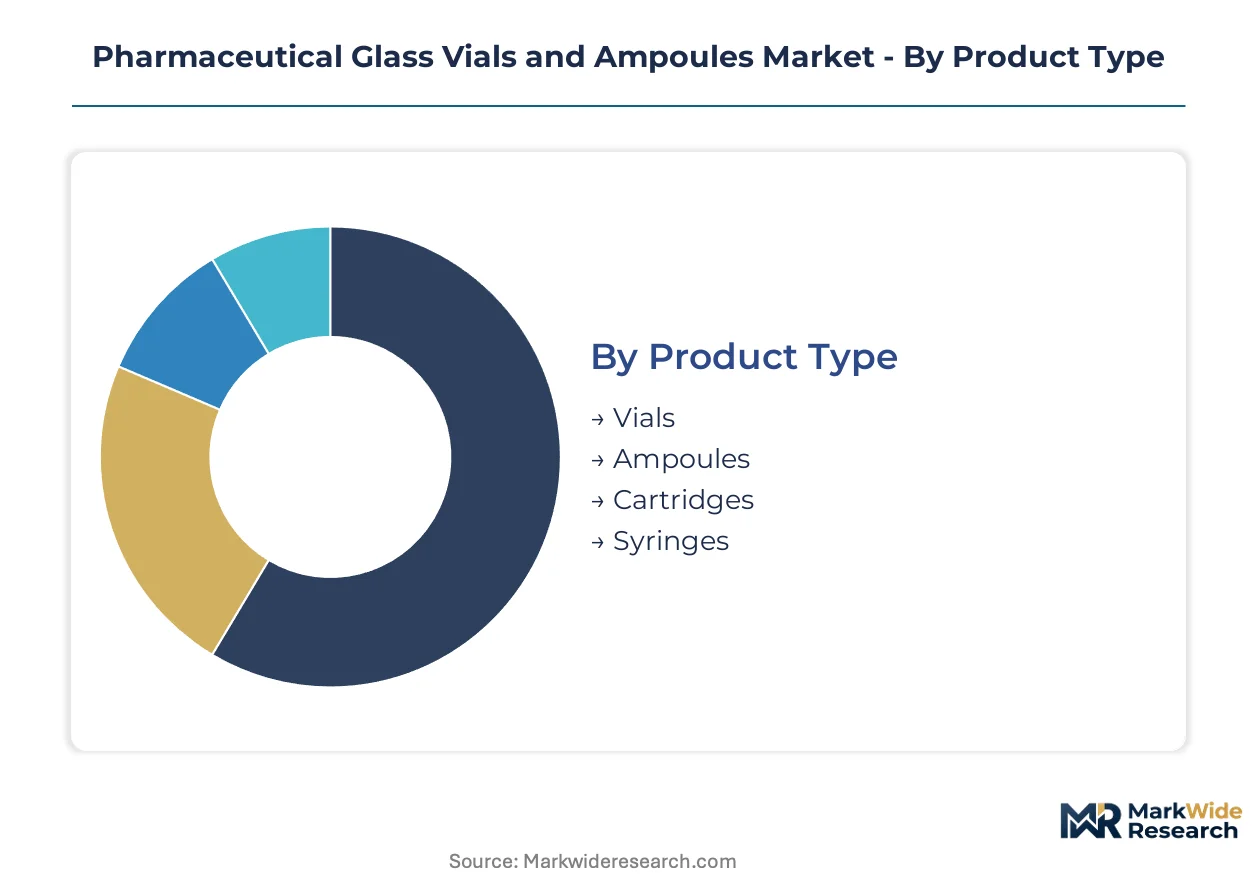
Pharmaceutical glass packaging segments diverge sharply in procurement cadence and margin structure. Cycle times for Type I borosilicate vials stretch across multi-year qualification protocols, while generic ampoules turn on quarterly price negotiations.
Product Type:
Vials rotate through inventory fastest in high-volume injectable fill-finish operations, while cartridges and prefillable syringes lock in longer conversion timelines due to device assembly complexity.
- Vials:Multi-dose and single-dose formats fabricated from tubular or molded glass dominate parenteral drug containment. Demand clusters in vaccine and biologics fill-finish lines across Germany and India, where lyophilization-compatible geometries command dedicated mold tooling investments.
- Ampoules:Break-open single-use containers in clear or amber glass persist in hospital settings requiring immediate sterility assurance. Volume concentrates in emerging-market injectable markets, though prefillable syringes are displacing share in European vaccine distribution.
- Cartridges:Cylindrical glass reservoirs engineered for pen-injector and auto-injector integration. Penetration climbs in diabetes and growth hormone therapies where patient self-administration protocols dominate.
- Syringes:Prefillable glass-barrel systems combining primary containment with delivery functionality. Adoption accelerates in biotech manufacturing clusters seeking to eliminate fill-finish line contamination risks.
Vials anchor the volume base while syringes gain share at the steepest rate.
Material:
Cost tiers separate pharmacopeial-grade borosilicate from commodity soda-lime alternatives, with coating technologies creating a premium overlay above base glass specifications.
- Type I Glass:Borosilicate composition delivering hydrolytic resistance Class I per USP and EP standards. Biologics manufacturers in Massachusetts and North Carolina mandate this grade for protein stability, pulling supply from Schott's FIOLAX and Gerresheimer's tubular melting operations.
- Type II Glass:Surface-treated soda-lime glass achieving intermediate chemical durability through sulfur or ammonium sulfate processing. Generic injectable producers in India leverage this grade for cost-sensitive small-molecule formulations under CDSCO oversight.
- Type III Glass:Untreated soda-lime glass meeting Class III hydrolytic standards for non-aqueous or dry powder applications. Oral and topical pharmaceutical packaging in cost-optimized supply chains retains this specification.
- Plastic:Cyclic olefin polymer and copolymer alternatives displacing glass in protein formulations prone to delamination or adsorption. Cyclic olefin polymer vials from Daikyo and West are penetrating monoclonal antibody portfolios.
Type III glass anchors the volume base while Type I glass climbs the fastest in revenue contribution.
Application:
Volume scale inversely correlates with qualification burden, as diagnostic reagents turn rapidly while biotechnology drugs lock in multi-year container closure system validation cycles.
- Injectables:Sterile solutions and suspensions administered parenterally, spanning antibiotics to complex biologics. Multi-dose vial demand in hospital pharmacy compounding drives replenishment velocity in North American distribution.
- Vaccines:Immunological formulations requiring cold chain stability across lyophilized and liquid presentations. Glass delamination risk in aluminum-adjuvanted products has intensified USP <1660> evaluation protocols.
- Biotechnology Drugs:Recombinant proteins, monoclonal antibodies, and gene therapies demanding inert contact surfaces. EMA's MDR traceability mandates are extending serialization investments across this segment's supplier base.
- Diagnostics:Reagent containment for in-vitro and molecular testing platforms. PCR and immunoassay kit manufacturers in South Korea and Singapore drive rapid-turn procurement of standard borosilicate vials.
Injectables anchor the volume base while biotechnology drugs expand most quickly in value terms.
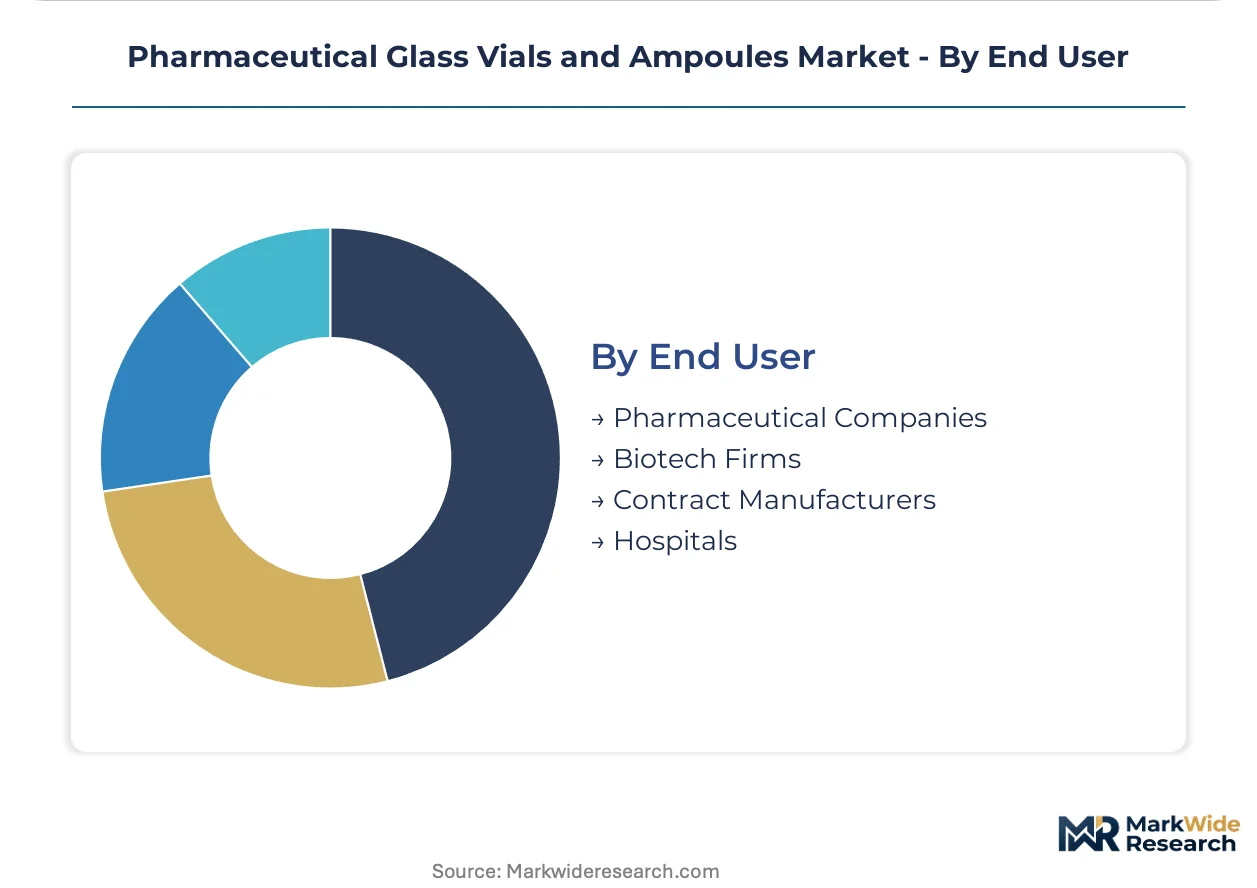
End User:
Procurement sophistication stratifies sharply, with biotech firms consolidating supplier panels while hospitals fragment purchasing across distributor catalogs.
- Pharmaceutical Companies:Originators and generic manufacturers operating captive fill-finish capacity or outsourced operations. Large-cap firms in Germany and Switzerland are qualifying ready-to-use vial formats to compress line changeover times.
- Biotech Firms:Mid-cap and emerging developers lacking in-house manufacturing infrastructure. Massachusetts and North Carolina clusters are driving single-source containment platform contracts spanning glass, elastomer, and device assembly.
- Contract Manufacturers:CDMOs and CMOs serving multiple sponsor programs with flexible batch sizing. These operators prioritize format standardization to minimize mold changeover downtime across client portfolios.
- Hospitals:Acute care and clinic settings sourcing break-open ampoules and multi-dose vials through group purchasing organizations. Procurement in India's public health system flows through centralized tender mechanisms under Ministry of Health oversight.
Pharmaceutical companies anchor the volume base while biotech firms are consolidating supplier relationships at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass melting capacity clusters heavily in Germany, while finishers in India and North America depend on imported tubular feedstock. Regulatory divergence between FDA, EMA, and CDSCO compliance protocols fragments multi-region qualification strategies. Demand for Type I borosilicate containers concentrates in biotech manufacturing corridors across Massachusetts, Bavaria, and Karnataka.
Germany
Injectable fill-finish operations at Boehringer Ingelheim and Merck KGaA drive vial consumption across the Rhine-Main and Upper Bavaria regions. EMA's MDR traceability mandates force serialization investments at every packaging node. Gerresheimer and Schott anchor melting operations near Mainz and Mitterteich, supplying FIOLAX tubing across European finishers.
United States
Biotech clusters in Massachusetts and North Carolina consolidate supplier panels around single-source containment platforms. FDA enforces USP <1207> container closure integrity requirements that extend qualification timelines for new glass formulations. West Pharmaceutical Services and Corning maintain finishing and coating operations serving parenteral drug manufacturers in the Northeast and Research Triangle.
India
Domestic generic injectable producers in Gujarat and Maharashtra source Type II and Type III glass for cost-sensitive antibiotic formulations. CDSCO mandates BIS certification for all imported primary packaging, creating compliance friction for multinational suppliers. Hyderabad and Ahmedabad host expanding fill-finish capacity serving export markets to Africa and Southeast Asia.
China
NMPA oversight of pharmaceutical packaging materials intensifies as domestic biologics manufacturing scales in Suzhou and Shanghai. Local borosilicate tubing producers in Shandong and Jiangsu challenge imported feedstock dominance in mid-tier applications. Yangtze River Delta clusters attract joint ventures between global glass suppliers and state-owned distributors.
Japan
PMDA pharmacopeial alignment with USP and EP standards streamlines multi-region submissions for domestic innovators. Osaka and Tokyo pharmaceutical corridors demand premium Type I glass for monoclonal antibody portfolios. Nipro Corporation maintains vertical manufacturing control from tubing melt through finished vial conversion.
Pharmaceutical Glass Vials and Ampoules Market Competitive Landscape
Backward-integrated melters and specialized finishers split the market along feedstock security lines. German and Japanese players control tubular glass melting capacity, while Italian and Indian competitors concentrate on conversion and value-added processing. Three archetypes dominate: captive tubing producers, independent finishers dependent on merchant supply, and integrated containment platform vendors spanning glass, elastomer, and device assembly. Capacity expansion in electric melting furnaces and strategic partnerships for ready-to-use formats represent the dominant competitive vectors.
Among German-based manufacturers, Gerresheimer AG and Schott AG exemplify the captive-feedstock archetype through in-house borosilicate melting operations. Stevanato Group occupies a position spanning glass conversion, inspection systems, and containment device integration. These three anchors demonstrate how European suppliers leverage regulatory proximity to EMA headquarters for faster MDR compliance certification cycles.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Schott AG |
| Stevanato Group |
| SGD Pharma |
| Nipro Corporation |
| West Pharmaceutical Services |
| Ardagh Group |
| Bormioli Pharma |
| Corning Incorporated |
| Others |
Value Network & Pricing Analysis
Melting capacity utilization above 85% at German borosilicate facilities tightens tubular glass feedstock availability, compressing margins for independent finishers while amplifying pricing power among backward-integrated suppliers. EMA's MDR compliance costs and F-Gas Regulation investments layer fixed-cost burdens that concentrate in Type I glass quotations.
Pricing Analysis
EMA's MDR dictates the pricing tier structure across European pharmaceutical glass procurement, with hydrolytic resistance Class I certification commanding premium positioning over Class II surface-treated alternatives. Three-tier pricing structure across premium, standard, and economy levels separates ready-to-use vial formats from bulk unprocessed containers and commodity ampoules. Cost compression in generic injectable segments is intensifying because Indian CDSCO BIS certification requirements for imported packaging inflate landed costs for multinational suppliers. Biotech firms in Massachusetts and North Carolina exhibit lowest price sensitivity, prioritizing container closure system integrity and serialization readiness over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and India dominates supply chain risk calculus for pharmaceutical glass finishers dependent on imported FIOLAX tubing. Borosilicate melting capacity clusters in Germany, China, and Japan, while conversion operations draw from merchant feedstock in Italy, India, and the United States. Raw material dependencies rest on quartz sand purity, boron oxide supply, and rare earth elements for amber glass coloration. Single-source vulnerability concentrates at Schott's Mitterteich and Mainz facilities, which anchor European tubular glass supply. Distribution runs through direct mill relationships for large-volume biopharma accounts and medical distributor networks for hospital break-open ampoule procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical glass packaging is evolving toward integrated containment platforms where regulatory compliance services and ready-to-use sterilization layers expand faster than commodity vial hardware. Recurring-revenue attach rates climb highest among suppliers bundling serialization, extractables testing, and cold-chain qualification support.
For Market Incumbents: Entrench feedstock security through electric melting furnace retrofits qualifying for EU carbon border adjustment exemptions. Lock in multi-year offtake agreements with Massachusetts and North Carolina biotech clusters before CDMO consolidation accelerates. Preempt prefillable syringe substitution by embedding glass barrel production within auto-injector platform partnerships. For New Entrants and Emerging Players: Mid-market generic injectable producers in Gujarat and Maharashtra represent the most penetrable entry point, as CDSCO BIS certification friction deters established European suppliers from aggressive pricing. Target cost-optimized Type II glass formulations for antibiotic portfolios where hydrolytic resistance requirements relax. Lead with regulatory advisory services bundling BIS documentation and elemental impurity screening to differentiate from commodity traders. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among inspection system and track-and-trace technology providers serving EMA MDR Article 27 compliance mandates. Long-term viability over the next decade hinges on electric melting scale and green procurement qualification. Target finishers with captive borosilicate supply or exclusive mold engineering relationships in Germany and Italy. Watch for inflection when NMPA accelerates domestic substitution mandates in China's Yangtze River Delta biologics corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tubular Melting | Gerresheimer's Mainz capacity expansion secures feedstock independence from Schott's FIOLAX monopoly. |
| Ready-to-Use Vial Format Launch | Pre-sterilized nested containers reduce fill-finish line capital burden for emerging biotech firms lacking depyrogenation tunnels. |
| Electric Melting Furnace Retrofit | Carbon border adjustment mechanism exemptions under EU Green Deal qualify German suppliers for premium procurement pools. |
| Regulatory Compliance Service Bundling | CDSCO BIS certification advisory creates sticky revenue streams alongside commodity glass shipments to Indian generic manufacturers. |
| Copolymer-Coated Glass Scale-Up | SGD Pharma and Stevanato coating investments target monoclonal antibody portfolios vulnerable to protein adsorption and delamination. |
Research Methodology
Initial hypotheses were tested against primary input from fill-finish operations directors, regulatory affairs leads at glass suppliers, hospital pharmacy procurement managers, and CDSCO compliance consultants, then refined against secondary validation from FDA USP <1207> guidance documents, EMA MDR implementation reports, BIS certification registries, and pharmacopeial harmonization working group proceedings. Bottom-up demand modeling across vial, ampoule, cartridge, and syringe formats triangulated with top-down borosilicate melting capacity assessments.
Demand-supply-balance dynamics anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, material grade, application, and end-user procurement sophistication. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends across lyophilization-compatible and standard geometries. Industry-specific inputs incorporated EMA F-Gas Regulation refrigerant transition timelines and CDSCO import certification processing durations.
Practitioners should monitor NMPA domestic substitution acceleration, Indian PLI scheme extensions for pharmaceutical packaging, and EU carbon border adjustment mechanism implementation schedules for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
US and Europe Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Malaysia Pharmacy Automation Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Cryogenic Ampoules Market
Pharmaceutical Equipment
Middle East and Africa Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market