
 Pharmaceutical CDMO Market | 2026-2036
Pharmaceutical CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical CDMO Market Analytics
Swiss-based large-molecule producers is repositioning capacity toward continuous bioprocessing platforms. Lonza leverages its Visp campus to anchor cell-and-gene therapy manufacturing scale. Thermo Fisher Scientific sustains geographic dominance through its Patheon network across North American and European regulatory jurisdictions. Samsung Biologics competes on single-use bioreactor throughput at its Songdo complex.
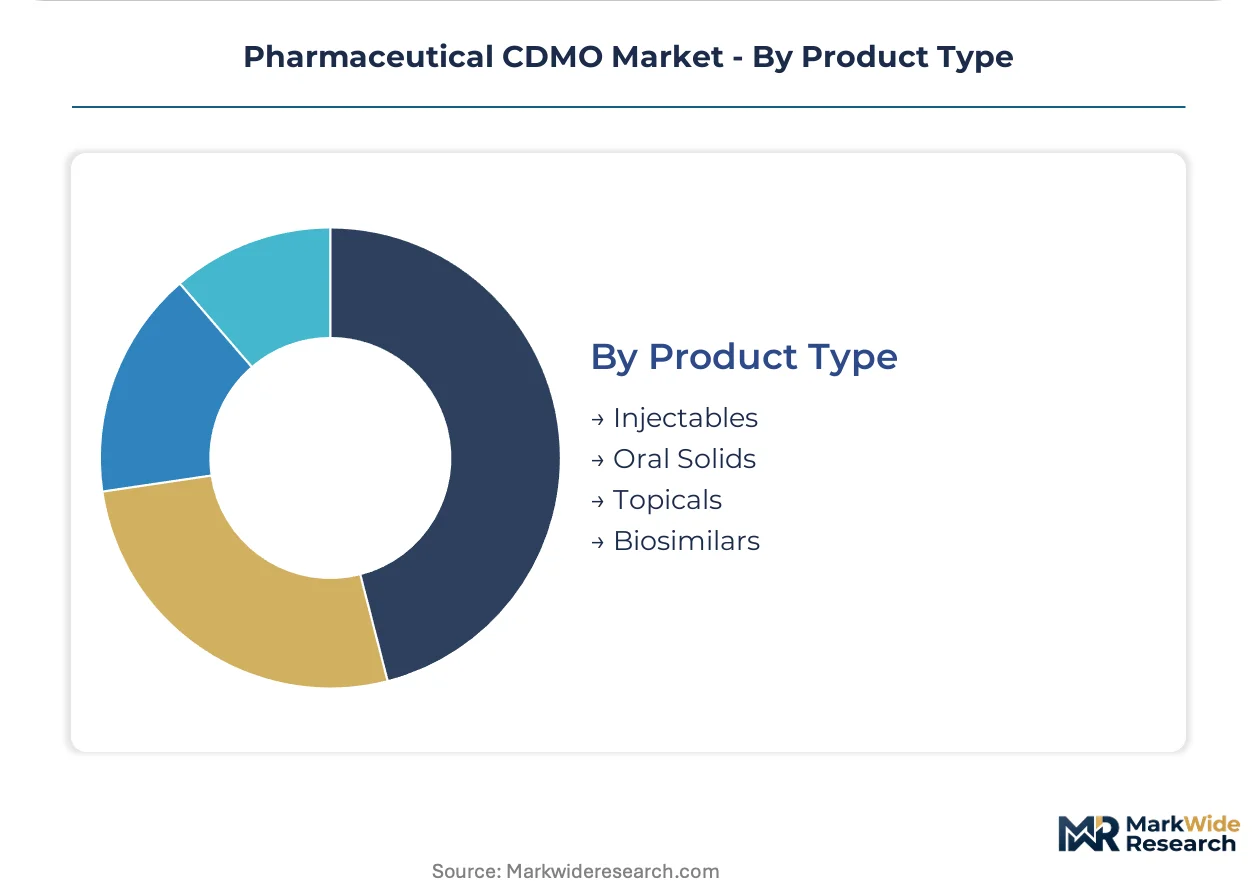
Pharmaceutical contract development and manufacturing organizations provide outsourced services spanning active pharmaceutical ingredient synthesis, finished dose formulation, packaging, and analytical testing, typically operating under GMP conditions with batch sizes ranging from kilogram-scale clinical supplies to multi-ton commercial production. These entities enable sponsor companies to convert fixed capital expenditures into variable costs while accessing specialized technologies. API Manufacturing dominates value capture due to high technical barriers and regulatory filing complexity, while Drug Delivery represents the fastest-expanding service tier as complex biologics require novel administration formats. Among product categories, Injectables command premium pricing because of aseptic processing requirements, whereas Biosimilars concentrate volume growth as patent cliffs accelerate.
FDA, EMA, and WHO standards govern facility inspections, data integrity protocols, and cross-border batch release procedures, directly determining which CDMOs qualify for blockbuster molecule supply chains. China's NMPA and India's CDSCO now align with ICH Q7 and Q10 frameworks, expanding the addressable supplier base for Western sponsors. Stakeholders must monitor regulatory divergence between jurisdictions as a determinant of network redundancy strategies and qualification timelines.
Market Dynamics
Biopharma sponsors now compress development timelines through integrated CDMO partnerships that span cell-line development to commercial fill-finish, converting fixed facility investments into variable operational expenditures while accessing specialized bioprocessing platforms unavailable in-house.
Growth Catalysts
- Patent cliff acceleration:Blockbuster biologics losing exclusivity force originators to outsource manufacturing to preserve margins, while biosimilar developers rely on CDMOs for rapid scale-up without captive infrastructure.
- FDA's Quality Management System Regulation:The updated QMSR framework mandates enhanced data integrity and risk-based validation, driving sponsor companies toward CDMOs with pre-qualified quality systems and established inspection histories.
- Continuous bioprocessing adoption:Perfusion cell culture and integrated continuous manufacturing reduce facility footprints and cost-of-goods, attracting investment from CDMOs seeking differentiation in monoclonal antibody production.
Market Restraints
- Single-use consumables cost volatility:Resin and film supply concentrates among limited polymer suppliers, exposing CDMO margins to petrochemical feedstock fluctuations and logistics bottlenecks.
- Swiss and South Korean capacity concentration:High-value biologics manufacturing clusters in Visp and Songdo create geographic single points of failure, amplifying disruption risks from regional energy constraints or trade policy shifts.
- EMA Annex 1 revision compliance:The 2022 update to sterile manufacturing guidelines requires extensive facility modifications for contamination control strategy implementation, extending qualification timelines and capital lock-up.
Strategic Opportunities
- India's CDSCO alignment with ICH Q7:Regulatory convergence enables Western sponsors to qualify Indian API and formulation CDMOs for commercial supply, expanding the addressable supplier base beyond traditional North American and European sources.
- Cell-and-gene therapy manufacturing:Viral vector production and allogeneic cell processing demand novel cleanroom configurations and specialized workforce competencies, creating first-mover advantages for CDMOs building dedicated capacity.
- EU Green Deal pharmaceutical emissions targets:Sustainability mandates favor CDMOs with renewable energy procurement, solvent recovery systems, and carbon footprint transparency, enabling premium positioning in European sponsor procurement.
Industry Challenges
- Bioprocessing engineer scarcity:Cell culture optimization and scale-up troubleshooting require hybrid skill sets combining biochemical engineering with GMP operations, constraining capacity expansion at specialized facilities.
- Multi-product facility changeover complexity:Campaign switching between monoclonal antibodies, antibody-drug conjugates, and mRNA products demands extensive cleaning validation and regulatory filing updates, compressing utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical CDMO Market |
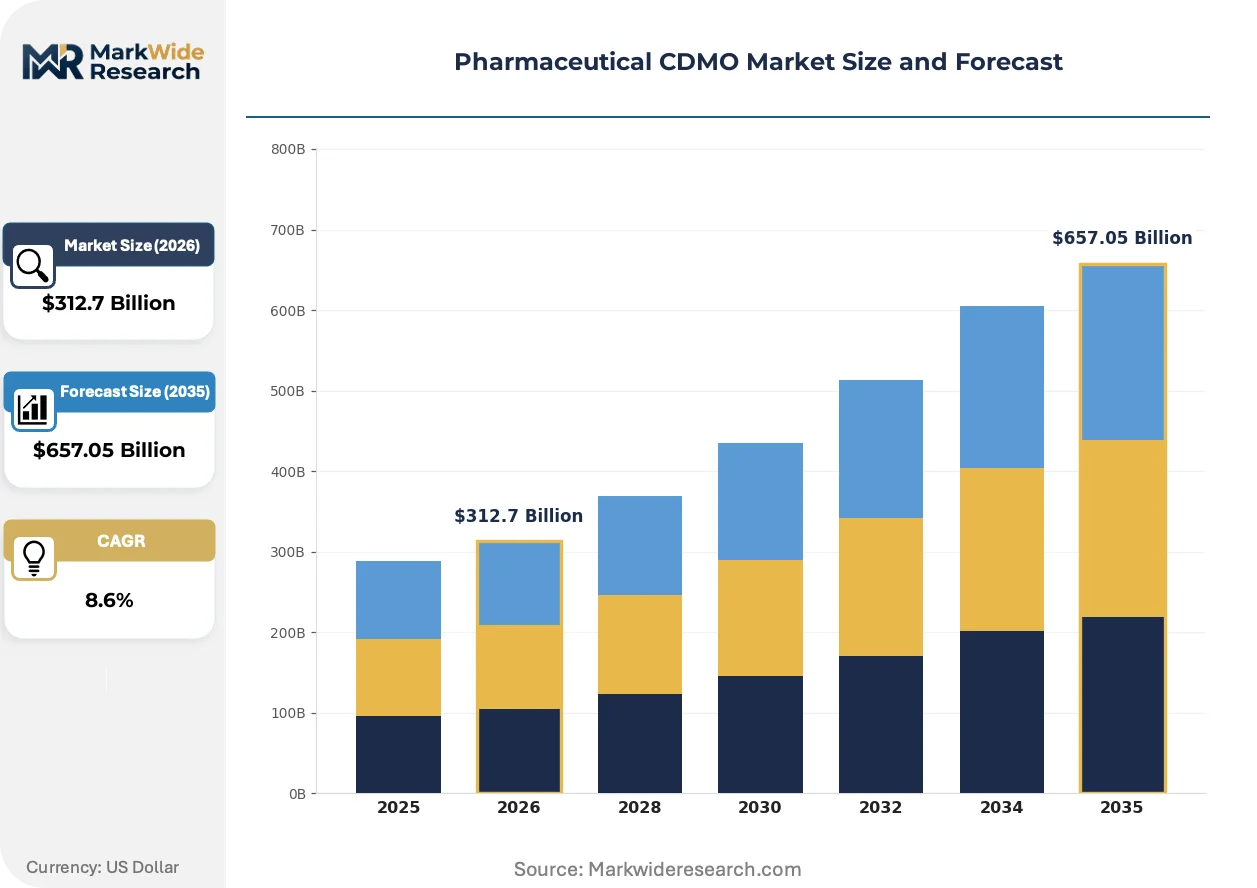
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $657.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: API Manufacturing, Formulation Development, Packaging Solutions, Drug Delivery End User: Biopharma Companies, Generic Manufacturers, Specialty Pharma, Startups Technology: Biotechnology, Chemical Synthesis, Robotics, Quality Control Product Type: Injectables, Oral Solids, Topicals, Biosimilars |
| Companies Covered | Lonza, Thermo Fisher Scientific, Catalent, Samsung Biologics, Recipharm, WuXi AppTec, Piramal Pharma Solutions, Siegfried Holding, CordenPharma International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical CDMO Market Evolving Landscape
Digital manufacturing architectures and modular facility designs are compressing traditional biologics production economics, while regulatory convergence across FDA, EMA, and NMPA frameworks reshapes qualification strategies for multi-jurisdictional supply networks.
Single-use bioreactor systems with integrated process analytical technology (PAT) sensors are automating real-time titer monitoring and feedback control. Mid-cap biotech sponsors adopting these platforms achieve faster process characterization and reduced deviation rates. This automation is compressing traditional tech transfer timelines from twelve to six months for late-phase programs.
EMA's Annex 1 revision on sterile manufacturing now mandates comprehensive contamination control strategies with barrier technology deployment. European fill-finish CDMOs are retrofitting isolator lines and restricted access barrier systems to meet the 2023 implementation deadline. Injectable biologics manufacturers in Germany and Switzerland face the steepest compliance investments due to legacy open processing infrastructure.
Sponsor procurement teams now unbundle development and commercial manufacturing awards, selecting specialized CDMOs for each phase rather than single-source partnerships. This fragmentation accelerates competitive bidding cycles and forces CDMOs to demonstrate distinct capabilities in either speed-to-IND or cost-of-goods optimization. The pattern is most pronounced among US-based biotechs with venture-backed funding structures prioritizing milestone-based capital efficiency.
Pharmaceutical CDMO Market Segmentation
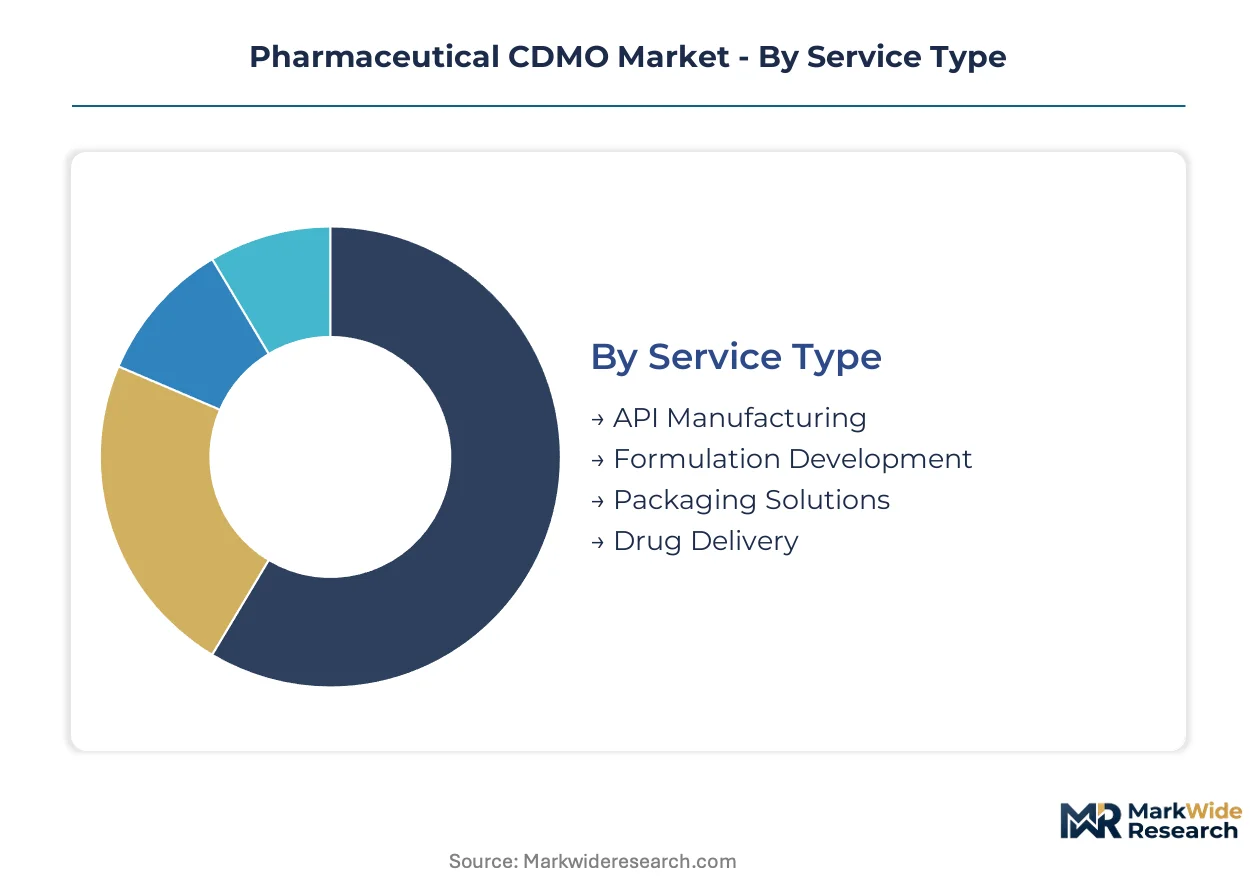
CDMO procurement decisions hinge on matching sponsor pipeline characteristics with vendor capability profiles across service breadth, technology platforms, and regulatory track records. Segment boundaries blur as integrated providers bundle API production with fill-finish services to capture lifetime contract value.
Service Type:
Buyers prioritize technical barriers and regulatory filing complexity when selecting service tiers, with high-chemistry-risk segments commanding premium pricing and longer qualification cycles.
- API Manufacturing:Active pharmaceutical ingredient synthesis demands multi-step organic chemistry expertise, crystallization optimization, and impurity profiling under ICH Q7 guidelines. Demand concentrates among US and Swiss sponsors seeking high-potency compound handling and controlled substance scheduling capabilities, constrained by limited qualified facilities for cytotoxic or highly potent APIs.
- Drug Delivery:Novel administration formats—lipid nanoparticles, sustained-release depots, and complex parenteral formulations—address bioavailability challenges for biologics. Korean and German sponsors drive investment here, motivated by patent extension strategies and differentiation requirements for biosimilar competition.
- Formulation Development:Preclinical-to-Phase I dosage form optimization accelerates IND timelines through salt screening, polymorph selection, and excipient compatibility studies.
- Packaging Solutions:Serialization compliance, cold-chain distribution formats, and patient-centric design support commercial launch readiness.
API Manufacturing leads on scale; Drug Delivery leads on momentum.
End User:
Capital intensity and pipeline risk tolerance determine sponsor outsourcing depth, with venture-backed entities favoring variable-cost structures over captive infrastructure.
- Biopharma Companies:Large-molecule developers outsource cell-line construction, bioreactor scale-up, and aseptic processing to access perfusion technologies unavailable in-house. US and Swiss innovators dominate contract awards, prioritizing CDMOs with FDA and Swissmedic inspection histories for blockbuster molecule supply security.
- Startups:Early-stage biotechs rely on fee-for-service models to preserve runway, selecting CDMOs offering integrated CMC packages from cell banking to clinical supply. Capital efficiency demands compress vendor selection timelines and favor partners with platform technologies applicable across multiple pipeline assets.
- Generic Manufacturers:Cost-of-goods optimization drives API and formulation sourcing from India and Eastern European CDMOs with established DMF portfolios.
- Specialty Pharma:Niche therapeutic focus—orphan diseases, oncology, rare genetic disorders—requires specialized handling capabilities and smaller batch flexibility.
Biopharma Companies anchor contract value; Startups expand most quickly.
Technology:
Platform selection dictates facility capital requirements, workforce specialization, and regulatory pathway complexity for sponsor qualification.
- Biotechnology:Mammalian cell culture, microbial fermentation, and viral vector production enable monoclonal antibodies, recombinant proteins, and gene therapies. Thermo Fisher's Patheon network and Samsung Biologics' Songdo complex exemplify scale leadership, with single-use bioreactor trains reaching kiloliter capacities for commercial supply.
- Chemical Synthesis:Small-molecule API production leverages flow chemistry and continuous processing to reduce solvent volumes and improve reaction control.
- Robotics:Automated sampling, in-line monitoring, and closed-system processing reduce contamination risk and labor dependency in aseptic operations.
- Quality Control:Analytical method development, stability testing, and release assays ensure batch consistency across jurisdictions.
Biotechnology commands the steepest expansion trajectory; Chemical Synthesis retains volume dominance.
Product Type:
Administration route determines aseptic processing requirements, cold-chain infrastructure, and pricing power in sponsor negotiations.
- Injectables:Parenteral biologics demand isolator-based fill-finish, terminal sterilization or aseptic processing, and EMA Annex 1 compliance for contamination control. German and Swiss facilities face the steepest retrofit investments for barrier technology deployment, while Korean CDMOs build greenfield capacity to capture biosimilar volume.
- Biosimilars:Follow-on biologics accelerate post-patent-cliff, requiring analytical biosimilarity packages and immunogenicity risk assessment. Indian and South Korean manufacturers concentrate capacity here, exploiting cost structures and abbreviated regulatory pathways to displace originator market share.
- Oral Solids:Tablets and capsules remain the dominant dosage form for small molecules, with high-speed packaging lines and modified-release technologies differentiating providers.
- Topicals:Transdermal patches, creams, and ophthalmic preparations require specialized manufacturing suites for semi-solid processing and sterility assurance.
Injectables lead on margin capture; Biosimilars gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics redirect capital toward jurisdictions where compliance costs align with sponsor risk tolerance. Swiss and South Korean facilities command premium positioning for high-value biologics, while Indian and Chinese producers capture API volume through aligned ICH frameworks.
United States
FDA's Quality Management System Regulation drives sponsor migration toward CDMOs with pre-qualified inspection histories. The updated QMSR framework mandates enhanced data integrity protocols. Greater Boston and San Francisco Bay Area clusters concentrate cell-and-gene therapy development partnerships.
Switzerland
Swissmedic alignment with FDA and EMA standards attracts blockbuster molecule supply contracts. The Visp industrial corridor anchors Lonza's large-molecule capacity expansion. Continuous bioprocessing investments reshape competitive positioning for monoclonal antibody production.
South Korea
MFDS regulatory convergence enables Western sponsor qualification for commercial supply. Samsung Biologics' Songdo complex exemplifies single-use bioreactor scale leadership. Biosimilar developers exploit cost structures and abbreviated pathways to displace originator market share.
India
CDSCO alignment with ICH Q7 and Q10 frameworks expands the addressable supplier base for Western sponsors. Hyderabad and Ahmedabad clusters concentrate API and formulation manufacturing capacity. Generic manufacturers drive cost-of-goods optimization through established DMF portfolios.
Germany
EMA Annex 1 revision compliance mandates extensive facility modifications for contamination control. Frankfurt-Rhine-Main and Bavarian pharmaceutical corridors face steepest retrofit investments for isolator line deployment. EU Green Deal emissions targets favor CDMOs with renewable energy procurement.
Pharmaceutical CDMO Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cell-and-gene therapy specialization and continuous manufacturing platforms. The vendor base stratifies across integrated multinational networks, regional specialists, and platform-technology providers. Three archetypes dominate: scale-driven biologics manufacturers, chemistry-focused API specialists, and modality-agnostic development partners. Capacity expansion and strategic technology licensing constitute the primary competitive vectors.
Within the integrated multinational tier, Lonza and Thermo Fisher Scientific exemplify archetype leadership through geographic network breadth. Samsung Biologics occupies a position at the scale-driven end of biologics manufacturing. These entities represent the competitive spectrum from Swiss-based large-molecule platforms to Korean single-use throughput capacity.
| Leading Market Players |
|---|
| Lonza |
| Thermo Fisher Scientific |
| Catalent |
| Samsung Biologics |
| Recipharm |
| WuXi AppTec |
| Piramal Pharma Solutions |
| Siegfried Holding |
| CordenPharma International |
| Others |
Value Network & Pricing Analysis
Venture-backed biotech sponsors concentrate procurement authority among small molecule and biologics developers seeking variable-cost structures, compressing CDMO pricing toward project-based fee-for-service models with milestone-triggered payment terms.
Pricing Analysis
Direct-to-sponsor contracting eliminates distributor markups, though large pharmaceutical procurement teams extract volume-based discounts reaching standard-economy tier separation. Price differentiation hinges on FDA inspection history and EMA Annex 1 compliance certification, with pre-qualified facilities commanding premiums. Cost compression in clinical-phase services intensifies as sponsor cash runway constraints tighten vendor selection. Generic manufacturers exhibit highest price sensitivity; cell-and-gene therapy developers prioritize speed over unit economics.
Supply Chain Analysis
GMP certification and regulatory qualification gates filter supplier eligibility, with only FDA- and EMA-inspected facilities qualifying for blockbuster molecule supply chains. Manufacturing concentrates in Switzerland, South Korea, and India for distinct service tiers. Resin and single-use film dependencies draw from limited polymer suppliers, exposing margins to petrochemical feedstock volatility. Single-source vulnerability concentrates in Swiss large-molecule campuses and Korean bioreactor complexes. Distribution runs through sponsor-directed logistics with cold-chain custody requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
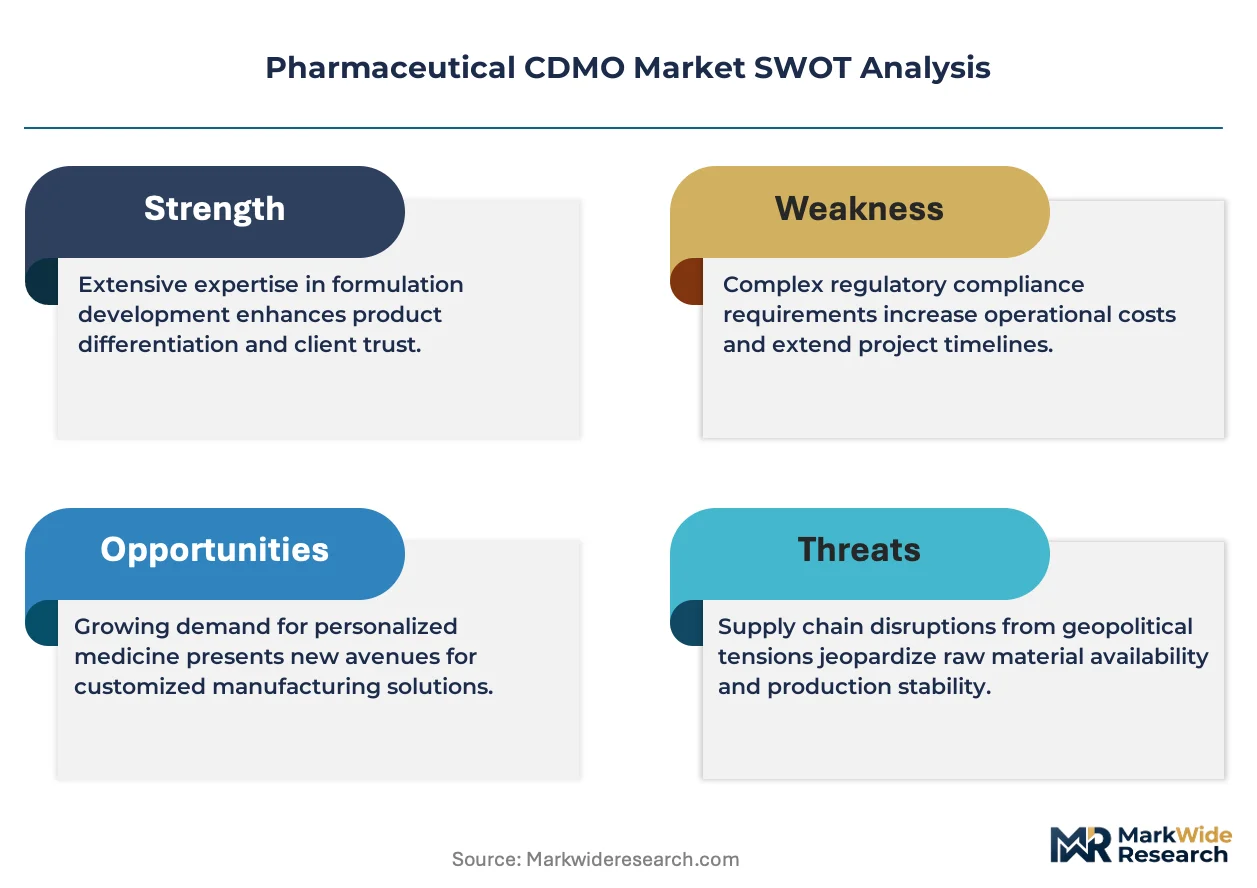
This market functions as a regulatory compounder, with FDA's Quality Management System Regulation and EMA Annex 1 revision driving sponsor migration toward pre-qualified CDMO networks.
For Market Incumbents: Hedge geographic concentration risk by diversifying capacity across multiple regulatory jurisdictions beyond Swiss and Korean strongholds. Samsung Biologics and Lonza face emerging competition from Indian CDMOs with CDSCO-aligned quality systems; backward integration into single-use consumables manufacturing reduces resin cost volatility exposure. For New Entrants and Emerging Players: Capture white-space in cell-and-gene therapy viral vector production, where qualified cleanroom capacity scarcity outstrips sponsor demand. India's regulatory convergence with ICH frameworks offers the most penetrable geography for API and formulation services. Position through platform technology licensing to accelerate sponsor qualification timelines. For Investors and Strategic Acquirers: Large biopharma companies with pipeline concentration in biologics are the most active acquirer in this space, seeking captive manufacturing security. Long-term viability favors CDMOs with demonstrated FDA and EMA inspection histories plus continuous bioprocessing capabilities. Monitor MFDS and CDSCO inspection reciprocity agreements as inflection indicators for geographic supply base expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Qualification Investment | FDA QMSR and EMA Annex 1 compliance pre-qualifies facilities for blockbuster supply chains. |
| Continuous Bioprocessing Scale-Up | Perfusion cell culture platforms reduce cost-of-goods for monoclonal antibody sponsors. |
| Cell-and-Gene Therapy Capacity Buildout | Viral vector cleanroom suites address manufacturing bottlenecks in gene therapy pipelines. |
| Geographic Diversification | Indian and Chinese regulatory alignment expands qualified supplier bases beyond Western sources. |
| Backward Integration into Consumables | In-house resin and film production buffers margin exposure to petrochemical volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biopharma development executives, regulatory affairs leads, CDMO operations directors, and sponsor procurement managers with secondary validation against FDA filings, EMA inspection databases, ClinicalTrials.gov protocols, and CDSCO registration records. Bottom-up capacity modeling and top-down demand estimation triangulated market sizing.
Segment-weighting distributed value across service type, technology platform, product category, and end-user archetype dimensions. CAGRs derived from regression analysis of historical outsourcing penetration rates and sponsor pipeline forecasts, with inputs including biologics patent cliff timing and regulatory inspection queue lengths across the projection horizon.
Underlying measurement precision varies by segment; API manufacturing and established biologics carry tighter precision than emerging cell-and-gene therapy modalities. Forecasts reflect assumptions about regulatory convergence pace and sponsor outsourcing depth preferences. A model refresh is warranted upon material change in FDA-EMA inspection reciprocity or ICH framework adoption by major supply jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
North America Unit Dose Manufacturing Market
Pharmaceutical Equipment
Tablet Press Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Anti-Counterfeiting Technologies Market
Pharmaceutical Equipment
Global Pharmaceutical Cartridges Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Isolator Market
Pharmaceutical Equipment
Global Fill Finish Manufacturing Market
Pharmaceutical Equipment
China Pharmaceutical Warehousing Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market