
 Radiosynthesis Equipment Market | 2026-2036
Radiosynthesis Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Radiosynthesis Equipment Market Analytics
Pharmaceutical-grade synthesis capability is rotating toward the center of procurement decisions as radiopharmaceutical manufacturers seek equipment that meets FDA cGMP and EMA GMP Annex 1 standards for sterile production. Siemens Healthineers leverages its integrated cyclotron-synthesizer platforms to dominate hospital-based installations across North America. GE Healthcare anchors its position through long-term service contracts and single-source tracer supply agreements. Trasis competes on modular, compact synthesizer architectures that reduce cleanroom footprint requirements for emerging radiopharma facilities.
Radiosynthesis equipment encompasses automated systems that produce positron-emitting radiopharmaceuticals through controlled chemical reactions, typically operating within temperature ranges of 80°C to 180°C and requiring lead-shielded hot cells to manage radioactivity levels up to several hundred curies. These systems serve the commercial and clinical purpose of manufacturing diagnostic tracers for PET imaging and therapeutic isotopes for targeted radionuclide therapy. Synthesizers command the largest product-type position due to their centrality in fluorodeoxyglucose and novel tracer production workflows. Continuous-flow technology leads growth among technology segments because it enables higher reproducibility and reduced operator radiation exposure compared with conventional batch processing. Pharmaceutical companies represent the fastest-expanding end-user category as they internalize radiopharmaceutical manufacturing rather than outsourcing to contract production organizations.
FDA cGMP regulations for PET drugs, EMA's GMP guidelines for radiopharmaceuticals, and ISO 13485 quality management standards collectively shape equipment validation requirements, installation qualification protocols, and market access barriers for non-compliant manufacturers. The NRC and its agreement-state counterparts enforce personnel training and radiation safety mandates that directly influence synthesizer design specifications and operational software features. Stakeholders must monitor evolving regulatory harmonization between FDA and EMA regarding automated synthesis validation to anticipate compliance-driven replacement cycles and new product qualification pathways.
Market Dynamics
Continuous-flow microreactor technology is fragmenting the installed base of batch-mode synthesizers as radiopharmaceutical manufacturers prioritize reproducibility and operator safety over legacy platform familiarity.
Growth Catalysts
- FDA cGMP for PET Drugs:The 2009 final rule and subsequent guidance documents mandate validated manufacturing processes that favor automated, closed-system synthesizers over manual production methods in commercial settings.
- Targeted radionuclide therapy expansion:Lutetium-177 and actinium-225 therapeutic isotope programs are driving dual-purpose equipment procurement that serves both diagnostic and production workflows.
- China cyclotron installation surge:Provincial hospital network expansions and radiopharmaceutical manufacturing investments are accelerating demand for integrated synthesis platforms in tier-one and tier-two cities.
Market Restraints
- High-purity precursor supply concentration:German and Belgian chemical suppliers dominate fluorine-18 precursor manufacturing, creating single-source vulnerability for non-integrated producers.
- Lead-shielded hot cell lead time volatility:Specialized radiation shielding fabrication capacity constraints extend equipment delivery timelines by 8-14 months during demand surges.
- Cyclotron-to-synthesizer interface standardization gaps:Proprietary communication protocols between accelerator targets and synthesis modules limit multi-vendor system integration.
Strategic Opportunities
- India CDMO market penetration:Contract development and manufacturing organizations in Mumbai and Hyderabad are building radiopharmaceutical capabilities that require GMP-qualified synthesis equipment.
- Alpha-emitter theranostics convergence:Combined diagnostic-therapeutic tracer pipelines are creating demand for multi-radionuclide capable synthesizers with rapid isotope switching functionality.
- EMA GMP Annex 1 sterile manufacturing alignment:The 2022 revision's emphasis on barrier isolation technology creates replacement demand for legacy hot cell installations across European production facilities.
Industry Challenges
- Qualified radiochemist talent scarcity:The intersection of synthetic organic chemistry expertise and radiation safety certification requirements limits operational scaling for new production facilities.
- IQ/OQ/PQ validation timeline compression:Equipment qualification protocols for FDA-regulated PET drug manufacturing extend facility startup schedules and defer revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiosynthesis Equipment Market |
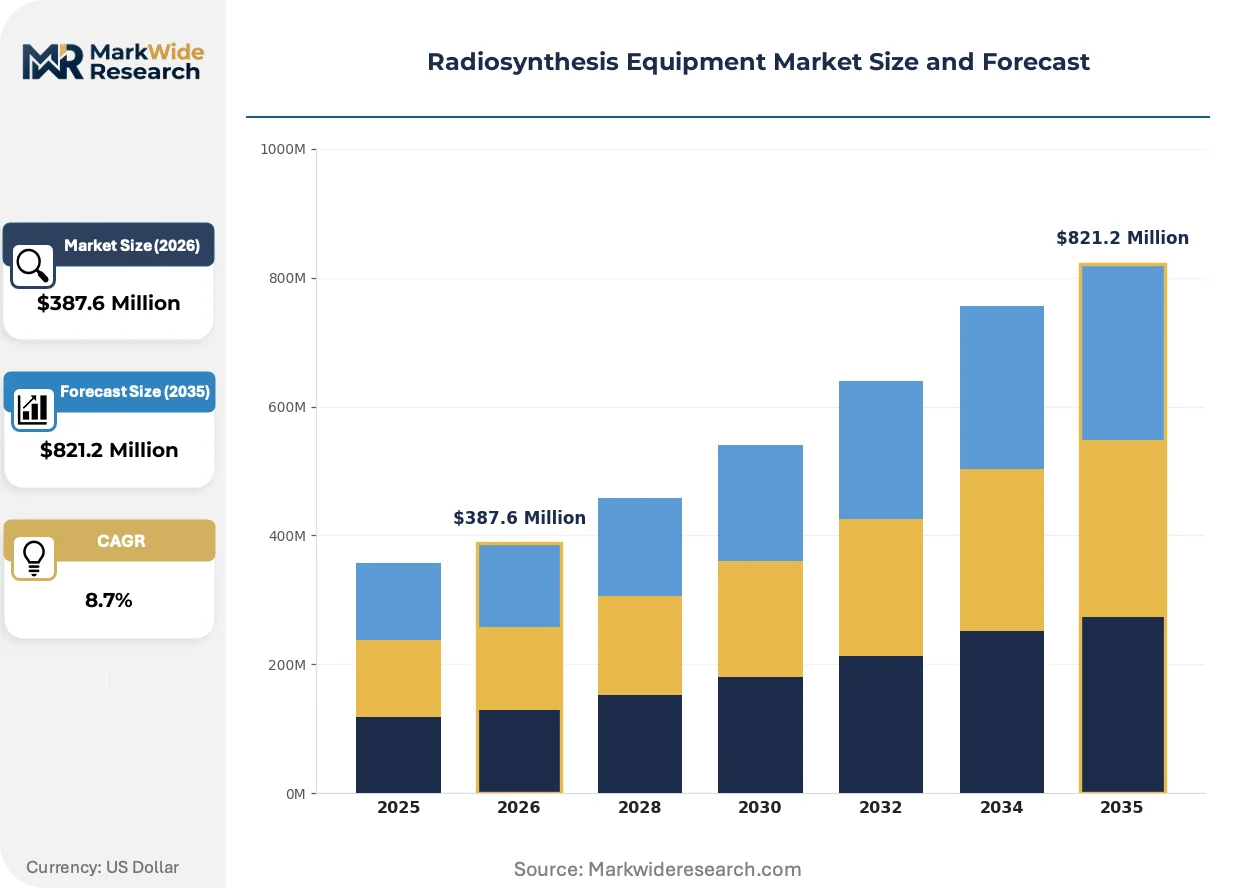
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactors, Radiochemical Generators, Synthesizers, Analyzers Application: Nuclear Medicine, Research Laboratories, Pharmaceutical Production, Clinical Diagnostics End User: Hospitals, Diagnostic Centers, Academic Institutions, Pharmaceutical Companies Technology: Liquid Phase, Solid Phase, Continuous Flow, Batch Processing |
| Companies Covered | Siemens Healthineers, GE Healthcare, IBA Radiopharma Solutions, Eckert & Ziegler, Sofie Biosciences, Trasis, Sumitomo Heavy Industries, Synthra GmbH, Comecer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiosynthesis Equipment Market Evolving Landscape
Digital integration and closed-system automation are converging to reshape equipment specifications as buyers prioritize data integrity and personnel exposure minimization over incremental throughput gains.
Microfluidic continuous-flow synthesis platforms are fragmenting the conventional batch reactor paradigm by enabling real-time reaction monitoring and automated parameter adjustment. Academic medical centers and emerging radiopharma startups are adopting these systems at accelerating rates despite higher initial capital requirements. The technology is fragmenting vendor competitive positions by rewarding software and sensor integration capabilities over mechanical engineering heritage.
EMA's 2022 GMP Annex 1 revision for sterile medicinal products is mandating isolator-based containment for aseptic processing operations. Radiopharmaceutical manufacturers must retrofit or replace open-front hot cells with restricted access barrier systems to maintain compliance. German and French production facilities are responding fastest due to stringent national inspectorate interpretations of barrier technology requirements.
Hospital-based nuclear medicine departments are consolidating tracer procurement through long-term single-source supply agreements rather than capital equipment acquisition. Equipment vendors are pivoting toward managed service and per-dose pricing models that transfer operational risk from clinical users. This pattern is most pronounced in United States integrated delivery networks where capital budget constraints favor operational expenditure structures.
Radiosynthesis Equipment Market Segmentation
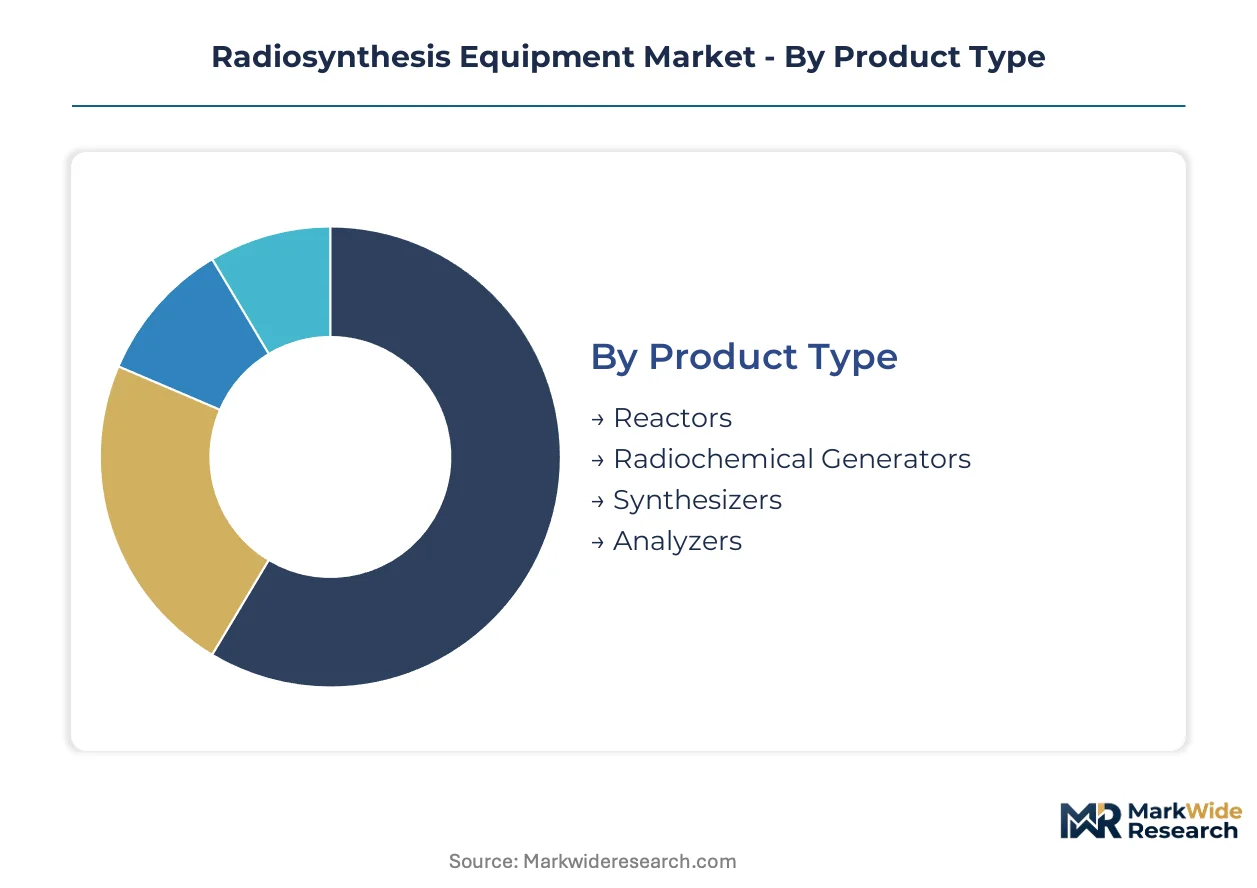
Radiosynthesis equipment procurement varies sharply by operational context, with FDA cGMP compliance requirements and cyclotron integration needs dictating specification choices. Segmentation reveals where capital concentrates versus where emerging demand is reshaping vendor priorities.
Product Type:
Continuous-flow microreactor platforms are displacing legacy batch-mode equipment in commercial settings, though installed base inertia protects incumbent categories in hospital environments.
- Synthesizers:Automated closed-system platforms execute fluorodeoxyglucose and novel tracer production within lead-shielded hot cells at 80°C to 180°C operating ranges. Hospital-based nuclear medicine departments in the United States and Germany drive replacement demand as FDA cGMP and EMA GMP Annex 1 standards tighten validation requirements for commercial tracer supply.
- Reactors:Vessel-based systems handle larger-volume therapeutic isotope production including lutetium-177 and actinium-225 programs. Pharmaceutical companies building internal radiopharmaceutical capabilities favor reactor platforms for batch flexibility across diagnostic and therapeutic workflows.
- Radiochemical Generators:Technetium-99m and gallium-68 generators serve decentralized clinical sites lacking cyclotron infrastructure.
- Analyzers:Quality control systems verify radiochemical purity, specific activity, and sterility for release testing.
Synthesizers anchor the volume base while continuous-flow reactor configurations gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive pharmaceutical production from research-scale installations, with nuclear medicine departments occupying the middle ground where managed service models are displacing equipment ownership.
- Nuclear Medicine:Clinical PET imaging departments require validated tracer production for oncology, neurology, and cardiology applications. United States integrated delivery networks increasingly outsource to single-source suppliers rather than acquiring capital equipment directly.
- Pharmaceutical Production:Commercial radiopharmaceutical manufacturing demands GMP-qualified systems with full IQ/OQ/PQ documentation and isolator-based containment. EMA's GMP Annex 1 revision is accelerating replacement of open-front hot cells with restricted access barrier systems across German and French facilities.
- Research Laboratories:Academic medical centers prioritize microfluidic continuous-flow platforms for reaction optimization and novel tracer development despite higher capital requirements.
- Clinical Diagnostics:Reference laboratories and regional imaging centers rely on simplified synthesis modules for high-throughput FDG production.
Pharmaceutical production commands the premium pricing tier while research laboratories expand most quickly as academic startups commercialize novel tracer platforms.
End User:
Customer type determines procurement modality, with pharmaceutical companies favoring capital purchase and qualification protocols while hospitals migrate toward operational expenditure structures.
- Pharmaceutical Companies:Internalization of radiopharmaceutical manufacturing is accelerating demand for multi-radionuclide capable systems with rapid isotope switching. These buyers prioritize GMP compliance documentation and long-term vendor service partnerships over initial capital cost.
- Hospitals:Nuclear medicine departments balance tracer autonomy against capital budget constraints, with tier-one cities in China showing strongest cyclotron-synthesizer installation growth alongside provincial network expansions.
- Academic Institutions:Research-focused buyers adopt microfluidic platforms for reaction mechanism studies and tracer validation before commercial transfer.
- Diagnostic Centers:Independent imaging facilities favor compact, single-tracer synthesizers with minimal cleanroom footprint and simplified operator training requirements.
Hospitals retain the largest installed base while pharmaceutical companies are climbing the fastest as vertical integration into radiopharmaceutical supply reshapes procurement patterns.
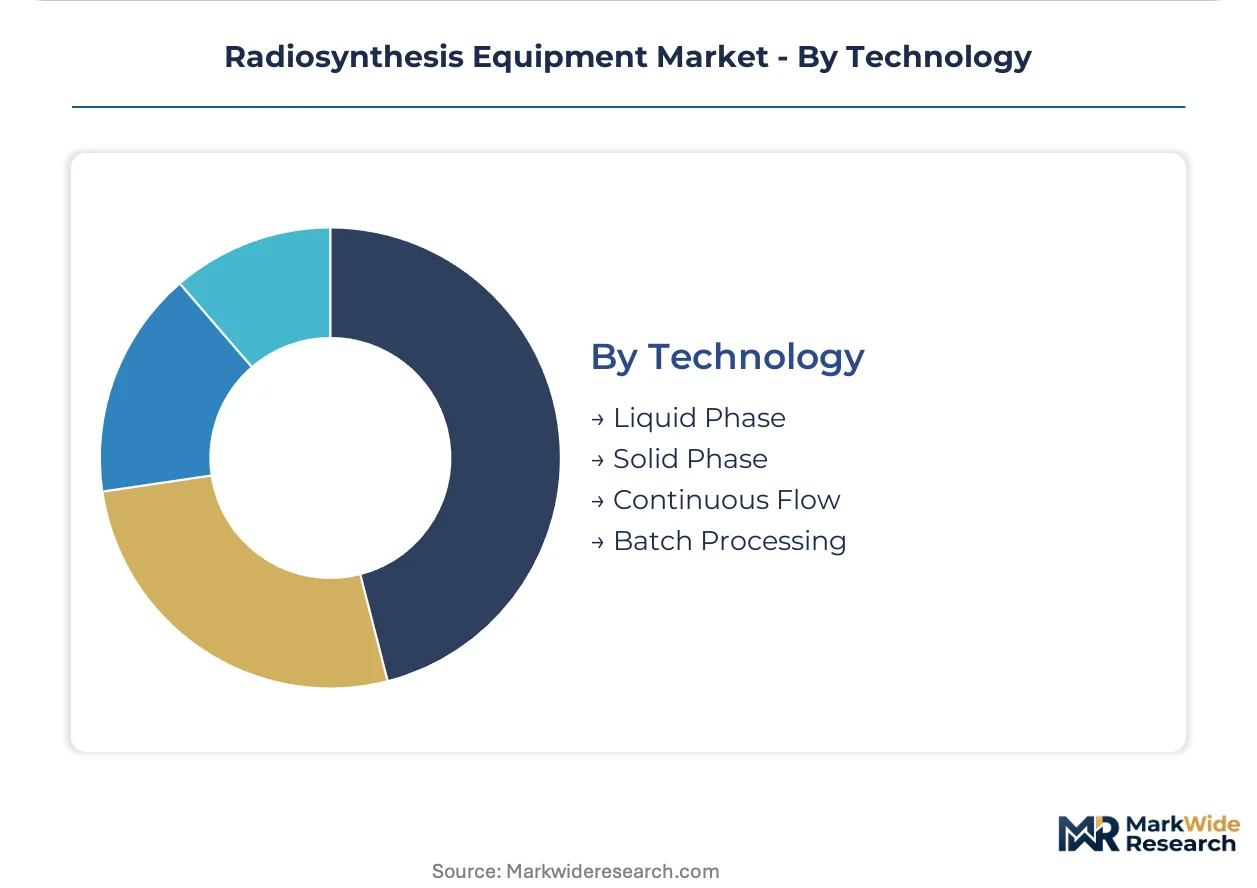
Technology:
Maturity gradients separate established batch processing from emerging continuous-flow architectures, with adoption pace constrained by qualified radiochemist availability and validation timeline compression.
- Continuous Flow:Microreactor platforms enable real-time reaction monitoring, automated parameter adjustment, and reduced operator radiation exposure. Academic medical centers and emerging radiopharma startups adopt these systems despite higher initial capital requirements and steeper learning curves.
- Batch Processing:Conventional reactor vessels dominate existing installations due to operator familiarity and established validation protocols. Legacy platform persistence is strongest in hospital settings where personnel training budgets limit technology transition.
- Liquid Phase:Homogeneous reaction conditions support broad substrate scope for fluorine-18 and carbon-11 chemistry.
- Solid Phase:Supported reagent approaches simplify purification and enable multi-step syntheses for complex tracer architectures.
Batch processing retains volume leadership while continuous flow platforms are expanding most quickly as reproducibility and safety specifications tighten across commercial production environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for fluorine-18 precursors and lead-shielded hot cells shapes regional equipment procurement patterns, with net importers facing extended delivery timelines during supply surges. Export-oriented radiopharmaceutical manufacturers in Germany and Belgium supply critical precursors to North American and Asian synthesis facilities.
United States
Hospital-based nuclear medicine departments and pharmaceutical manufacturers drive cyclotron-synthesizer installations, with integrated delivery networks consolidating tracer procurement through single-source agreements. FDA cGMP requirements for PET drug products mandate validated manufacturing processes that favor automated closed-system platforms. Boston and Houston anchor radiopharmaceutical production clusters where academic medical centers commercialize novel tracer platforms.
Germany
EMA GMP Annex 1 compliance pressures are accelerating replacement of open-front hot cells with restricted access barrier systems across commercial production facilities. The national pharmaceutical regulator enforces stringent interpretations of isolator-based containment requirements. Munich and Berlin concentration radiopharma manufacturing investments where contract production organizations expand GMP-qualified synthesis capacity.
China
Provincial hospital network expansions in tier-one and tier-two cities are accelerating demand for integrated synthesis platforms as cyclotron installation rates surge. NMPA regulatory harmonization with international standards is elevating equipment qualification requirements for domestic manufacturers. Shanghai and Beijing radiopharmaceutical clusters are internalizing production capabilities previously outsourced to foreign suppliers.
India
Contract development and manufacturing organizations in Mumbai and Hyderabad are building radiopharmaceutical capabilities that require GMP-qualified synthesis equipment and qualified radiochemist workforces. CDSCO regulatory frameworks for radiopharmaceutical manufacturing are tightening validation documentation requirements. Western and Southern industrial corridors are attracting equipment vendors establishing localized service and qualification support infrastructure.
France
ANSM inspectorate interpretations of EMA GMP Annex 1 barrier technology requirements are driving faster compliance adoption than neighboring jurisdictions. Academic medical centers in Paris and Lyon prioritize microfluidic continuous-flow platforms for research-scale tracer development before technology transfer to commercial partners. The national nuclear medicine infrastructure supports dual-purpose diagnostic and therapeutic isotope production workflows.
Radiosynthesis Equipment Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates that leverage integrated cyclotron-synthesizer platforms and long-term service contracts to anchor hospital-based installations. The vendor base spans three strategic tiers: full-platform integrators with cyclotron-to-dose capabilities, modular synthesizer specialists reducing cleanroom footprints, and regional equipment fabricators serving emerging markets. Competitive dynamics center on GMP compliance documentation depth and qualification protocol support rather than pure equipment specifications. Dominant moves include backward integration into precursor supply and managed service model expansion.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify full-platform positioning through integrated hardware-service ecosystems. Trasis occupies a specialist tier with compact modular architectures targeting emerging radiopharma facilities. IBA Radiopharma Solutions and Eckert & Ziegler sit within the accelerator-to-synthesis integration segment. Synthra GmbH and Comecer Group represent European fabrication capabilities serving regional compliance requirements. Sofie Biosciences and Sumitomo Heavy Industries anchor geographic diversification strategies across North American and Asian demand centers.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| IBA Radiopharma Solutions |
| Eckert & Ziegler |
| Sofie Biosciences |
| Trasis |
| Sumitomo Heavy Industries |
| Synthra GmbH |
| Comecer Group |
| Others |
Value Network & Pricing Analysis
FDA cGMP qualification requirements for PET drug manufacturing gate both supplier certification and price tiering simultaneously, forcing buyers to pay premiums for validated equipment documentation while constraining vendor pools to those with established regulatory track records. This dual filtration concentrates pricing power among incumbent manufacturers who have amortized qualification costs across multi-year service contracts.
Pricing Analysis
Pharmaceutical companies anchor pricing structures through capital purchase models with bundled IQ/OQ/PQ validation packages, while hospital-based buyers shift toward per-dose operational expenditure frameworks. Price differentiation rests on GMP documentation depth and cyclotron integration complexity, with fully validated systems commanding substantial premiums over research-grade configurations. Cost compression in hospital segments intensifies as integrated delivery networks consolidate procurement through single-source tracer agreements. Academic institutions exhibit highest price sensitivity due to constrained capital budgets, whereas commercial radiopharma manufacturers prioritize compliance assurance over initial capital outlay.
Supply Chain Analysis
Germany and Belgium anchor fluorine-18 precursor manufacturing, with specialized chemical suppliers feeding synthesis facilities across North America and Asia. Lead-shielded hot cell fabrication draws from concentrated radiation shielding foundries in France and the United States, creating extended delivery timelines during demand surges. Single-source vulnerability in high-purity precursor supply exposes non-integrated producers to supply interruptions. Distribution runs through direct vendor-to-manufacturer relationships for GMP-qualified systems, with regional service partnerships supporting aftermarket qualification support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiosynthesis equipment sits in early-cycle expansion as therapeutic radionuclide programs accelerate dual-purpose platform procurement beyond traditional diagnostic imaging boundaries.
For Market Incumbents: Fortify service contract penetration through backward integration into precursor supply, locking in customer switching costs before modular competitors reduce cleanroom footprint advantages. Expand qualification protocol support teams in China and India where regulatory harmonization is elevating documentation requirements. Prioritize rapid isotope switching capabilities to capture lutetium-177 and actinium-225 therapeutic production workflows. For New Entrants and Emerging Players: Post-sales validation support gaps in emerging radiopharma facilities present white-space entry points where incumbents under-serve with standardized documentation packages. Target tier-two Chinese cities and Indian CDMO corridors where cyclotron installation rates outpace established vendor service capacity. Lead with microfluidic continuous-flow architectures that reduce qualified radiochemist training burdens as a differentiated go-to-market angle. For Investors and Strategic Acquirers: EMA GMP Annex 1 barrier technology mandates reshape the acquisition landscape by accelerating replacement demand for legacy hot cell installations across European production facilities. Five-to-ten year viability favors vendors with software-integrated sensor platforms over mechanical engineering heritage. Acquire specialists with isolator-based containment expertise. Watch FDA-EMA regulatory harmonization progress on automated synthesis validation as the signal for compliance-driven replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Based Containment Retrofit | EMA GMP Annex 1 compliance mandates barrier technology replacement across German and French production facilities. |
| Continuous-Flow Microreactor Launch | Real-time reaction monitoring capabilities fragment batch-mode incumbent positions in academic and startup segments. |
| Precursor Supply Backward Integration | Captive fluorine-18 chemistry production secures margins against German and Belgian supplier concentration. |
| Per-Dose Managed Service Expansion | Operational expenditure models align with United States integrated delivery network capital budget constraints. |
| Multi-Radionuclide Platform Development | Rapid isotope switching functionality captures therapeutic isotope program demand from pharmaceutical internalization. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radiopharmaceutical manufacturing executives, nuclear medicine department directors, GMP qualification specialists, and cyclotron facility managers. Secondary validation drew from FDA PET drug guidance documents, EMA GMP Annex 1 revisions, NRC radiation safety regulations, and ISO 13485 quality management standards. Bottom-up equipment installation tracking and top-down radiopharmaceutical production capacity estimates were triangulated to anchor market sizing.
Across the analysis window, forecasts model equipment demand by product type, application tier, end-user category, and technology architecture, with specific attention to cyclotron-to-synthesizer integration complexity and regulatory qualification pathway differentiation. CAGRs were derived from segment-level growth trajectory analysis weighted by installed base replacement cycles and net new facility commissioning patterns. Forecast inputs incorporate radiochemist workforce expansion rates and precursor supply capacity constraints.
Forecasts assume regulatory continuity in FDA cGMP, EMA GMP Annex 1, and NMPA harmonization pathways; material policy shifts would require re-modeling. Specific risks that could revise projections include qualified radiochemist talent scarcity prolonging facility startup timelines, lead-shielded hot cell fabrication bottlenecks extending equipment delivery, and cyclotron-to-synthesizer interface standardization failures limiting multi-vendor system integration. Recalibration cycles align with material shifts in regulatory harmonization progress and therapeutic radionuclide program advancement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Prefilled Formalin Vials Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Pharmaceutical Sterilization Equipment Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Europe Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market