
 Ophthalmic Loupes Market | 2026-2036
Ophthalmic Loupes Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Loupes Market Intelligence
High-definition prismatic optics is collapsing the price-performance barrier between entry-level Galilean systems and premium surgical loupes. ZEISS leverages its Jena-based optical engineering heritage to sustain manufacturing precision at scale. Designs for Vision, Inc. anchors the North American custom-fit segment through direct clinician relationships. Orascoptic competes aggressively on LED-integrated headlight configurations for dental crossover applications.
Ophthalmic loupes are binocular magnification instruments employing Galilean or prismatic optical architectures, typically offering 2.5x to 6.0x magnification with working distances of 340-550 mm and declination angles up to 40 degrees, engineered to reduce musculoskeletal strain during prolonged microsurgical procedures. The Galilean category remains the volume leader due to lower weight and cost, while prismatic designs capture disproportionate margin pools among vitreoretinal surgeons demanding wider fields of view. Custom-fit configurations command premium positioning as they require pupillary distance and working-distance calibration, whereas clip-on variants expand addressable demand among residents and trainees in academic medical centers.
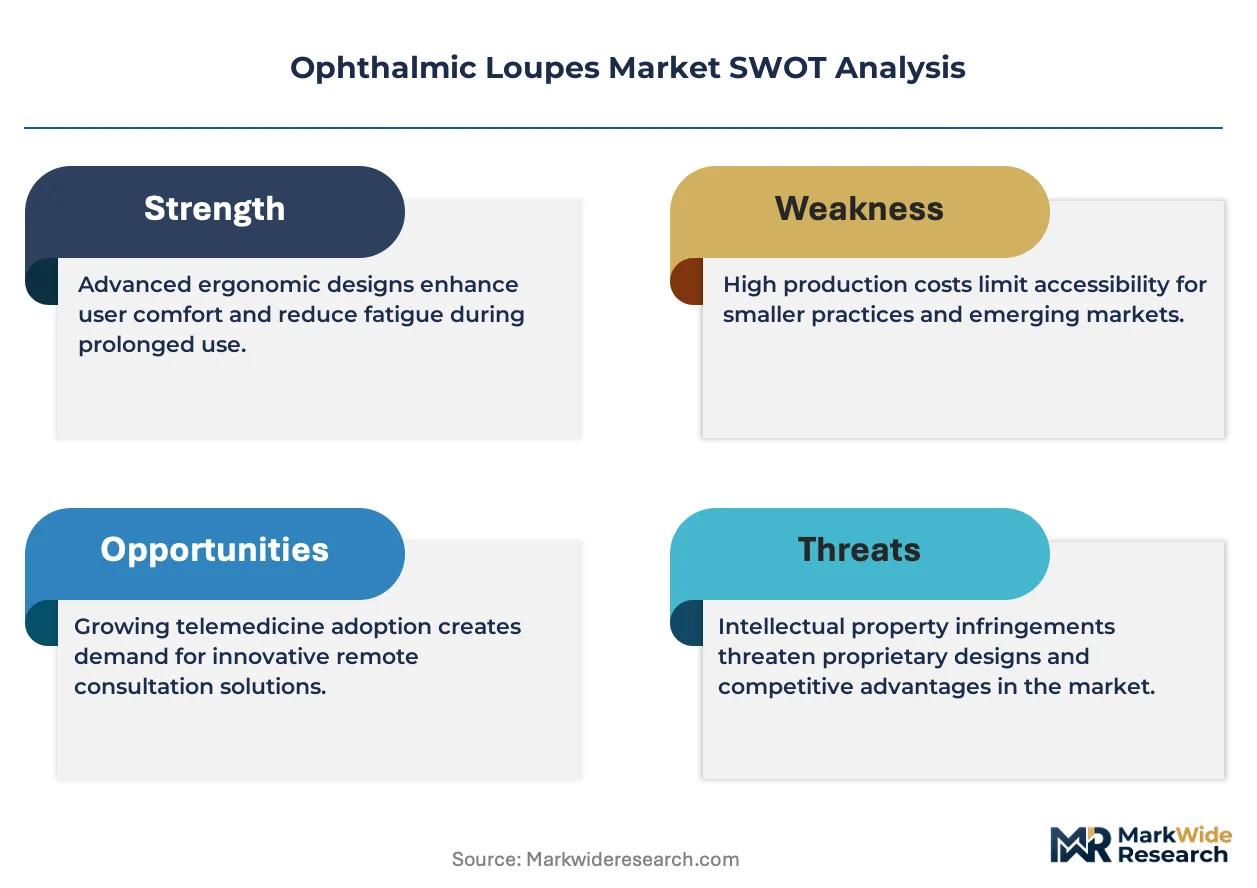
FDA 510(k) clearance requirements for prescription medical devices govern commercial entry in the United States, while the EU Medical Device Regulation mandates notified-body conformity assessment for CE marking across European markets. ISO 10993 biocompatibility testing and IEC 60601-1 electrical safety standards further constrain design freedom for LED-integrated systems. Stakeholders must monitor evolving reimbursement codes for presbyopia-correcting intraocular procedures, as these directly influence capital equipment budgets for magnification upgrades in ophthalmology practices.
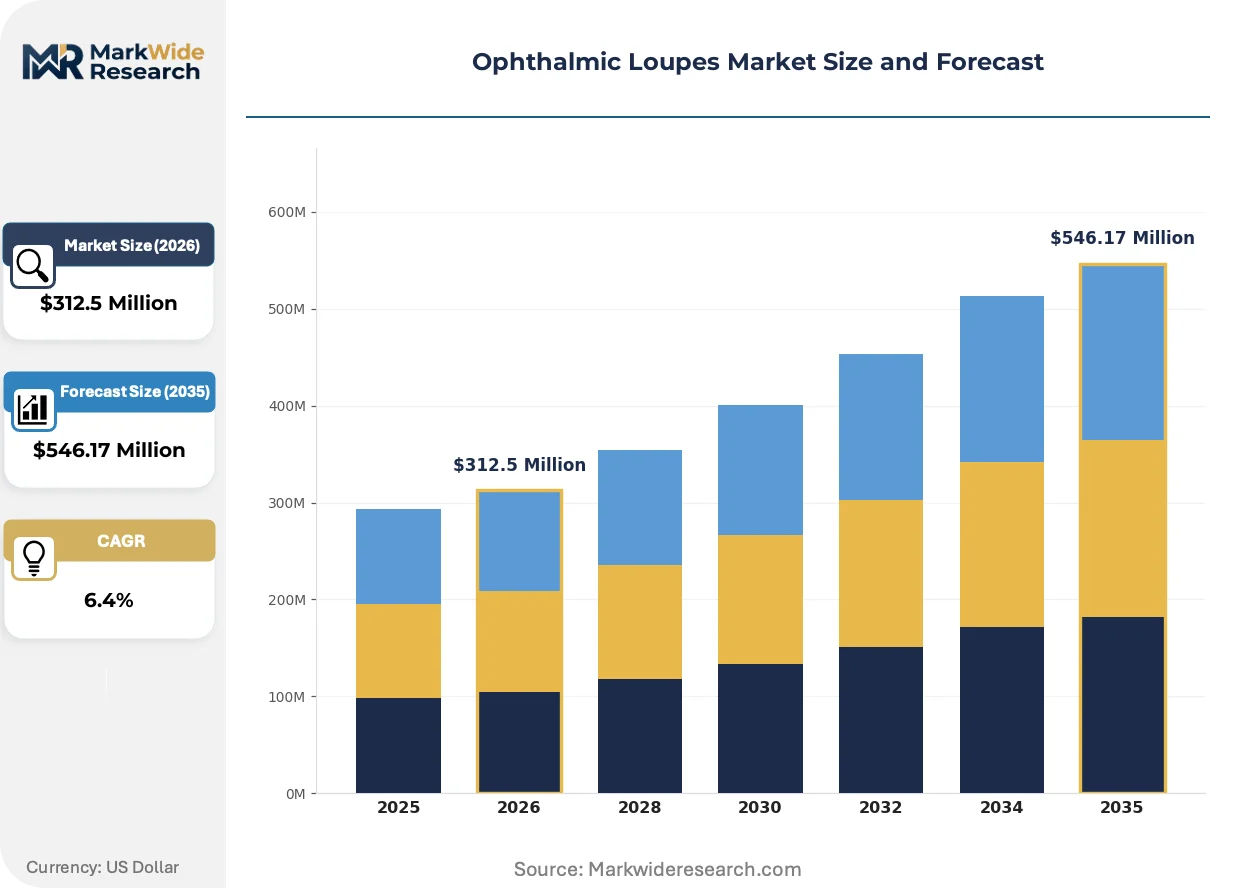
Market Dynamics
High-definition prismatic optics is collapsing the price-performance barrier between entry-level Galilean systems and premium surgical loupes, forcing incumbent manufacturers to recalibrate product positioning across magnification tiers.
Growth Catalysts
- Cataract surgery volume:Ambulatory surgical centers in Germany and the United States are expanding dedicated ophthalmology suites, creating pull-through demand for precision magnification equipment.
- FDA 510(k) pathway clarity:Updated medical device classification for magnification optics has streamlined premarket notification requirements, reducing time-to-market for prismatic loupe innovations.
- Precision optics clustering:Manufacturing capabilities concentrate around Jena and Oberkochen in Germany, enabling just-in-time supply chains for custom-fit configurations.
Market Restraints
- Optical glass supply concentration:Schott AG and Hoya Corporation control specialty glass substrate supply for high-index prismatic lenses, creating input cost volatility.
- Custom-fit calibration overhead:Pupillary distance and working-distance measurement protocols require trained optometric technicians, limiting scalable deployment.
- EU MDR conformity assessment:Notified-body bottlenecks for CE marking under the Medical Device Regulation extend commercialization timelines by 12-18 months.
Strategic Opportunities
- India ophthalmology expansion:CDSCO regulatory harmonization and private hospital chain growth in Mumbai and Delhi create underpenetrated demand for clip-on resident training loupes.
- LED-integrated convergence:Surgical headlight systems combining coaxial illumination with magnification optics are capturing dental crossover applications.
- Academic medical center leasing:Subscription-based equipment access models are replacing capital purchase cycles for residency programs in the United States.
Industry Challenges
- Optical engineer scarcity:Precision lens design expertise concentrates among aging specialists in German and Japanese manufacturing clusters, constraining R&D expansion.
- ISO 10993 biocompatibility testing:Frame material certification for prolonged skin contact adds 6-9 months to product development cycles.
- Legacy inventory obsolescence:Rapid prismatic adoption is stranding Galilean loupe inventories at distributor level, forcing write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Loupes Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Galilean, Prismatic, High-Quality, LED Lighting End User: Ophthalmologists, Dentists, Surgeons, Veterinary Professionals Application: Medical Surgery, Routine Checkups, Dental Procedures, Veterinary Exams Design Type: Custom-Fit, Adjustable, Clip-On, Binocular |
| Companies Covered | SurgiTel, Orascoptic, Designs for Vision, Inc., ZEISS, Keeler, SheerVision Loupes & Headlights, Rudolf Riester GmbH, Univet S.r.l., NEITZ INSTRUMENTS Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Loupes Market Strategic Shifts & Innovations
Optical architectures, regulatory frameworks, and procurement models are simultaneously evolving, compressing traditional product lifecycles and redrawing competitive boundaries across magnification tiers.
Prismatic optical systems employing high-index glass and advanced coatings are decomposing the historical segmentation between economy Galilean loupes and premium surgical configurations. Vitreoretinal surgeons in academic medical centers are adopting these systems at accelerating rates. The technology is decomposing margin pools that previously stratified cleanly across magnification tiers, forcing manufacturers to defend positioning through service bundling rather than optical performance alone.
REACH restrictions on hazardous substances in electrical equipment are constraining LED-integrated headlight material choices for European market entry. Manufacturers must reformulate solder compositions and housing plastics to maintain CE marking compliance. German and French notified bodies are applying heightened scrutiny to optical devices with active electronic components, delaying certification timelines for hybrid illumination-magnification systems.
Residency program purchasing committees are consolidating vendor relationships around single-source agreements with comprehensive maintenance coverage. Academic medical center procurement departments in the United States are displacing individual surgeon preference with standardized equipment pools. This concentration is most visible in the Northeast corridor, where hospital network consolidation has reduced active loupe suppliers from six to two preferred vendors across affiliated ophthalmology departments.
Ophthalmic Loupes Market Segmentation
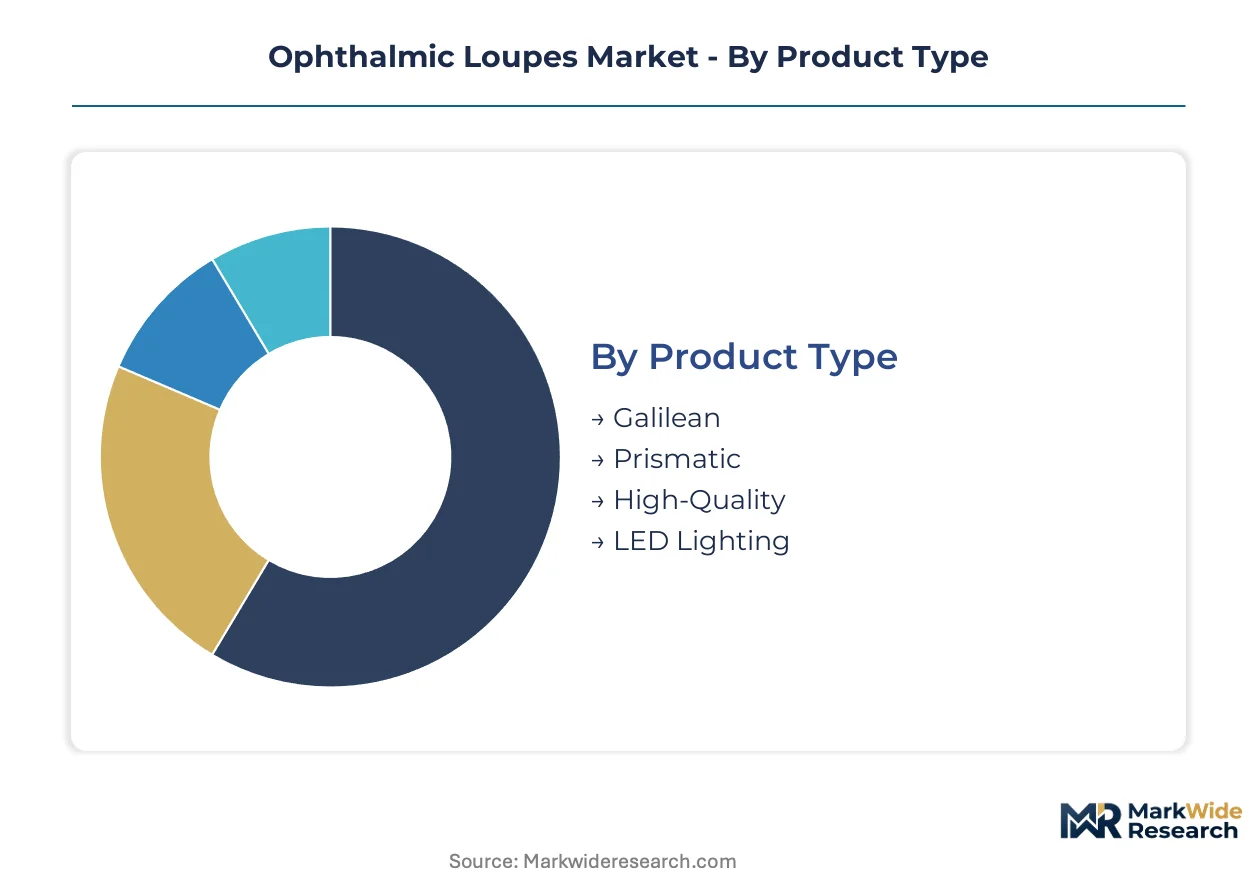
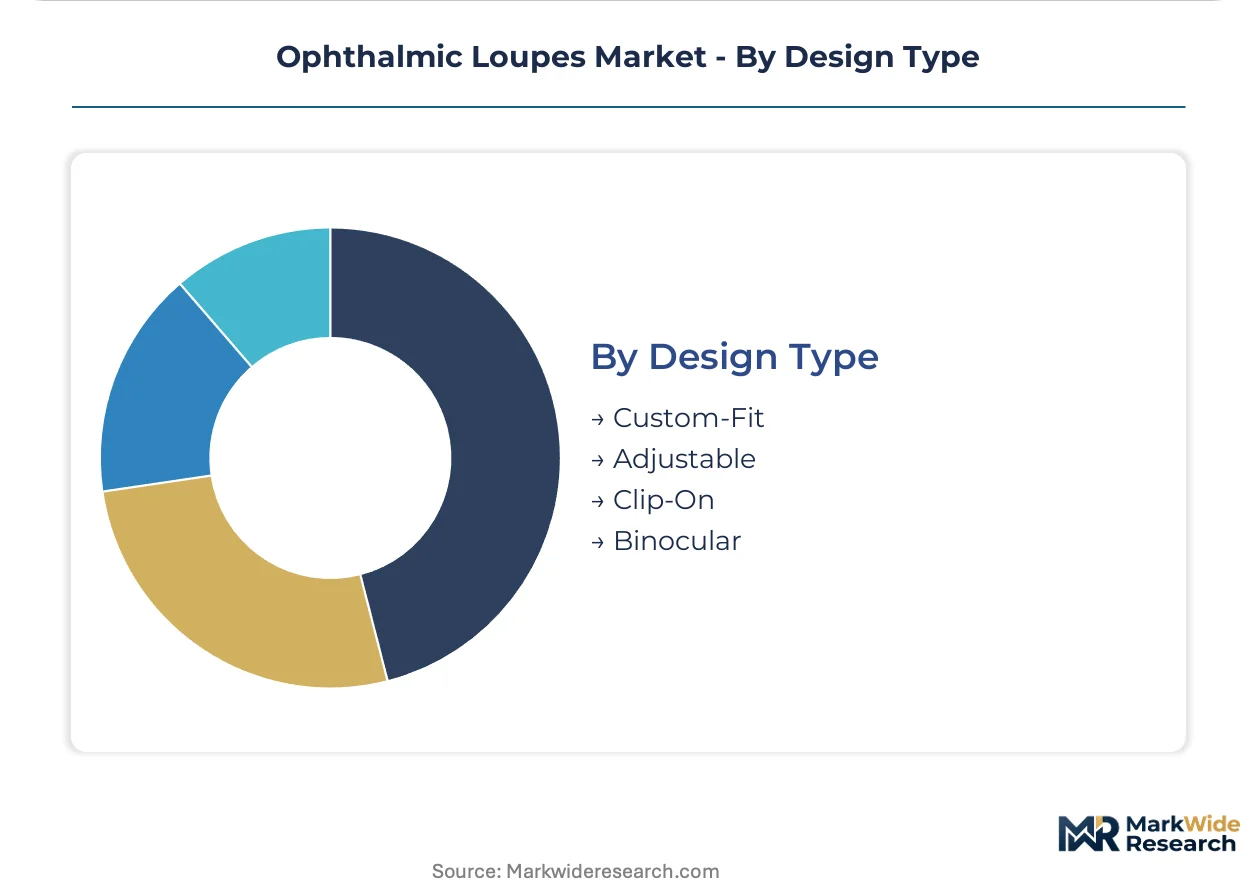
Channel strategy for ophthalmic loupes diverges sharply by product architecture and end-user sophistication. Custom-fit prismatic systems flow through direct manufacturer relationships with academic medical centers, while clip-on Galilean variants distribute through dental supply houses and veterinary equipment catalogs.
Product Type:
Galilean configurations dominate volume through distributor networks serving price-sensitive residents and trainees, whereas prismatic platforms command direct sales channels targeting vitreoretinal specialists.
- Galilean:Lightweight two-lens optical systems employing convex objective and concave eyepiece elements deliver 2.5x to 3.5x magnification with minimal chromatic aberration. Demand concentrates in German university hospitals where resident training programs prioritize cost containment over field-of-view performance. The segment faces margin compression as prismatic technology cascades downward.
- Prismatic:Multi-lens Schmidt-Pechan or Abbe-König architectures achieve 4.0x to 6.0x magnification with wider stereoscopic fields through total internal reflection. Vitreoretinal surgery suites in Oberkochen-region medical centers drive adoption, attracted by reduced eye strain during macular membrane peeling procedures. FDA 510(k) pathway streamlining accelerates commercialization timelines for new prismatic entrants.
- High-Quality:Premium-grade optical glass from Schott AG and Hoya Corporation substrates with anti-reflective multicoating.
- LED Lighting:Coaxial illumination modules integrated into loupe frames, subject to IEC 60601-1 electrical safety compliance.
By volume, Galilean leads. By growth pace, prismatic systems are climbing the fastest as surgical precision demands intensify.
End User:
Cost tier differentiation separates hospital-based ophthalmologists from private-practice dentists, with procurement authority residing in distinct organizational layers.
- Ophthalmologists:Cataract and retinal surgeons in ambulatory surgical centers represent the core revenue base, with purchasing committees evaluating optical resolution specifications against capital equipment budgets. German precision manufacturing clusters supply this segment through just-in-time calibration services.
- Dentists:Oral surgery and endodontic practitioners in North American group practices drive LED-integrated configuration demand. Crossover applications from dental to ophthalmic markets create channel conflict as manufacturers defend specialty positioning.
- Surgeons:Plastic and microvascular specialists requiring intermediate magnification for tissue approximation.
- Veterinary Professionals:Equine ophthalmology and small-animal surgical practices in academic veterinary hospitals.
By installed base, ophthalmologists dominate. By expansion trajectory, veterinary applications are gaining share fastest as specialty animal care monetization improves.
Application:
Volume concentration in routine clinical workflows contrasts with margin capture in complex surgical interventions, reshaping manufacturer R&D allocation.
- Medical Surgery:Vitreoretinal and cataract procedures demand highest optical performance, with working distances calibrated to surgeon anthropometry. Academic medical centers in the United States consolidate vendor relationships around single-source agreements covering maintenance and recalibration.
- Routine Checkups:Slit-lamp examination support applications in general ophthalmology practices emphasize lightweight wearability over magnification extremes. Indian private hospital chains in Mumbai and Delhi generate underpenetrated demand for basic clip-on configurations.
- Dental Procedures:Endodontic and periodontal interventions requiring 2.5x to 4.0x magnification with integrated illumination.
- Veterinary Exams:Diagnostic and minor surgical applications in companion animal practices.
By procedure count, routine checkups lead. By revenue per unit, medical surgery commands premium positioning.
Design Type:
Supply concentration in German optics clusters favors custom-fit manufacturing, while Asian contract producers enable clip-on scalability.
- Custom-Fit:Pupillary distance and working-distance measurement protocols require trained optometric technicians for individualized frame fabrication. Jena-based engineering heritage sustains manufacturing precision at scale for this segment. EU MDR notified-body bottlenecks extend CE marking timelines by 12-18 months.
- Adjustable:Modular interpupillary and declination angle mechanisms accommodate multiple users in shared equipment pools. Residency programs in the United States Northeast corridor favor this category for standardized equipment pools replacing individual surgeon preference.
- Clip-On:Universal mounting systems attaching to prescription eyewear, expanding addressable demand among trainees.
- Binocular:Traditional through-the-lens configurations maintaining market presence in established practices.
By unit economics, custom-fit commands highest margins. By addressable expansion, clip-on variants show steepest volume trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics manufacturers export prismatic loupe systems to ambulatory surgical centers across the United States and academic medical centers in Japan. This trade corridor channels high-index glass substrates from Schott AG through Jena-based engineering clusters toward international buyers demanding calibrated magnification equipment.
United States
Ambulatory surgical centers in Texas and Florida are expanding dedicated ophthalmology suites for cataract procedures. FDA 510(k) clearance requirements govern commercial entry for magnification optics classified as prescription medical devices. The Northeast corridor exhibits hospital network consolidation that has reduced active loupe suppliers from six to two preferred vendors across affiliated ophthalmology departments.
Germany
Precision optics manufacturing clusters around Jena and Oberkochen sustain just-in-time supply chains for custom-fit configurations. EU Medical Device Regulation mandates notified-body conformity assessment for CE marking, extending commercialization timelines by 12-18 months for hybrid illumination-magnification systems. Bavarian engineering heritage anchors manufacturing precision at scale for vitreoretinal surgery applications.
Japan
Vitreoretinal specialists in Tokyo and Osaka academic medical centers drive adoption of high-definition prismatic systems for macular membrane peeling procedures. PMDA marketing approval requirements align with international harmonization frameworks for optical medical devices. Nagoya-based precision instrument manufacturers supply calibrated working-distance configurations to domestic surgeons.
India
Private hospital chains in Mumbai and Delhi generate underpenetrated demand for clip-on resident training loupes as ophthalmology residency programs expand. CDSCO regulatory harmonization with international standards streamlines import pathways for magnification equipment. Maharashtra-based distributors are displacing individual surgeon preference with standardized equipment pools for training institutions.
United Kingdom
NHS procurement frameworks for ophthalmology equipment emphasize maintenance coverage and recalibration service bundling. MHRA conformity assessment procedures apply heightened scrutiny to LED-integrated systems with active electronic components. London and Southeast England academic medical centers consolidate vendor relationships around single-source agreements covering precision magnification upgrades.
Ophthalmic Loupes Market Key Industry Players
Listed leaders compete with private specialists across optical engineering heritage and direct clinician relationship depth. The vendor base stratifies into three tiers: heritage optics conglomerates with captive glass supply, mid-scale custom-fit specialists, and volume distributors serving resident training markets. Strategic differentiation concentrates on LED-integrated convergence for dental crossover applications and subscription-based leasing models for academic medical center procurement departments. Capacity expansion in German precision clusters and technology licensing agreements for prismatic architectures represent dominant competitive moves.
Among heritage German optics manufacturers, ZEISS and Rudolf Riester GmbH exemplify engineering-led positioning anchored in Jena-based manufacturing traditions. Designs for Vision, Inc. occupies a representative position within the North American custom-fit segment through direct clinician relationships. Orascoptic sits within the LED-integrated configuration tier, competing aggressively on headlight-magnification convergence for dental-to-ophthalmic crossover demand.
| Leading Market Players |
|---|
| SurgiTel |
| Orascoptic |
| Designs for Vision, Inc. |
| ZEISS |
| Keeler |
| SheerVision Loupes & Headlights |
| Rudolf Riester GmbH |
| Univet S.r.l. |
| NEITZ INSTRUMENTS Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Jena-based precision optics facilities creates scale economies that compress unit costs for prismatic loupe manufacturers while establishing price floors for custom-fit configurations. German engineering heritage sustains premium positioning as Schott AG glass substrates flow through Oberkochen-region calibration centers toward ambulatory surgical centers.
Pricing Analysis
Next-generation prismatic architectures command substantial premiums over legacy Galilean systems, while entry-level clip-on variants undercut both tiers for resident training markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by optical resolution certification and after-sales calibration bundling. Cost compression in the Galilean tier intensifies because prismatic technology cascades downward, stranding distributor inventories. Residents and trainees in Indian academic medical centers exhibit highest price sensitivity, whereas vitreoretinal surgeons in Japanese academic centers demonstrate lowest sensitivity due to capital equipment budget insulation.
Supply Chain Analysis
Germany and Japan anchor precision lens fabrication and optomechanical assembly for ophthalmic magnification equipment. High-index prismatic glass from Schott AG and Hoya Corporation, precision-machined aluminum frames, and IEC 60601-1-compliant LED modules constitute critical input dependencies. Single-source vulnerability concentrates in specialty optical glass substrates, where Schott AG and Hoya Corporation control manufacturing. Distribution runs through direct manufacturer relationships with academic medical centers for custom-fit systems, while dental supply houses and veterinary equipment catalogs handle clip-on Galilean variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration and recalibration service contracts are expanding faster than hardware unit sales as academic medical centers consolidate vendor relationships around comprehensive maintenance coverage. This service-attach dynamic transforms capital equipment vendors into recurring-revenue platforms.
For Market Incumbents: Consolidate manufacturing precision advantages through captive calibration technician networks in German optics clusters, defending against prismatic technology commoditization. Deepen backward integration into optical glass substrate supply to mitigate Schott AG and Hoya Corporation pricing power. Channel control through exclusive academic medical center service contracts represents the critical defensive lever. For New Entrants and Emerging Players: LED-integrated headlight maintenance gaps in North American dental crossover applications offer white-space entry points where heritage manufacturers under-serve rapid-turn repair demands. Indian private hospital chains in Mumbai and Delhi present the most penetrable geography for clip-on resident training configurations. A subscription-based equipment access model targeting United States residency programs bypasses capital purchase committee friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among custom-fit prismatic specialists with embedded calibration service contracts. Long-term viability across the analysis window favors manufacturers with Jena-based engineering heritage and FDA 510(k) clearance track records. The signal to watch is academic medical center procurement committee consolidation velocity in the Northeast corridor.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR notified-body relationships accelerate commercialization timelines for prismatic innovations. |
| Hospital System Partnership | Single-source agreements with academic medical centers displace fragmented supplier relationships. |
| Software Companion Development | Digital pupillary distance measurement tools reduce custom-fit calibration overhead and technician dependency. |
| Backward Integration into Optical Glass | Captive supply of Schott AG-equivalent substrates mitigates input cost volatility. |
| Reimbursement Strategy Alignment | Presbyopia-correcting intraocular procedure codes directly influence magnification upgrade budgets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vitreoretinal surgeons, ophthalmology purchasing committee chairs, biomedical engineers, GPO contracts managers, and precision optics manufacturing executives. Secondary validation drew from FDA 510(k) filings, EU MDR notified-body registers, hospital procurement databases, and CMS Medicare reimbursement code updates. Bottom-up unit demand modeling and top-down market sizing triangulated across these sources.
Across the analysis window, forecasts reflect segment-level modeling by optical architecture, end-user specialty, application procedure type, and design configuration. CAGRs were derived from procedure volume trajectories, capital equipment replacement cycles, and technology substitution elasticities. PMDA marketing approval timelines and CDSCO regulatory harmonization progress served as geography-specific forecast modifiers.
Forecasts assume regulatory continuity in FDA 510(k) and EU MDR regimes; material policy shifts would require re-modeling. Optical engineer scarcity in German manufacturing clusters and REACH restriction evolution on LED-integrated systems constitute primary revision triggers. Recalibration cycles align with material shifts in reimbursement code structures and academic medical center consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Aphakia Market
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Exophthalmos Treatment Market
Ophthalmology
Global Therapeutic Lenses Market
Ophthalmology
Ischemic Optic Neuropathy Treatment Market
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Ophthalmic Ultrasound Systems Market
Ophthalmology
Vitrectomy Machines Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Ophthalmology Diagnostics and Surgical Devices Market
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Global Vitreous Tamponades Market
Ophthalmology
Personalized LASIK Surgery Market
Ophthalmology
Ocular Hypertension Treatment Market