
 Urinary Tract Infection (UTI) Market | 2026-2036
Urinary Tract Infection (UTI) Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Tract Infection (UTI) Market Insights
Hospital procurement of UTI diagnostic and therapeutic solutions is broadening as ambulatory networks fragment purchasing authority across specialty clinics and home care channels. Pfizer leverages its manufacturing scale to sustain antibiotic supply contracts with integrated delivery networks. Cipla anchors generic fluoroquinolone distribution across emerging markets where cost sensitivity shapes formulary decisions. Shionogi & Co. differentiates through its R&D intensity in novel antimicrobial mechanisms against resistant uropathogens.
A urinary tract infection denotes microbial colonization of the urethra, bladder, ureters, or kidneys, typically caused by uropathogenic Escherichia coli and diagnosed through urine culture or rapid nucleic acid amplification assays with turnaround thresholds under twenty-four hours for uncomplicated cases. The primary commercial purpose spans therapeutic eradication of pathogens, symptomatic pain management, and preventive probiotic colonization to reduce recurrence frequency. Antibiotics occupy the largest value pool among product types due to established reimbursement and recurrent prescribing patterns, while diagnostic kits represent the fastest-expanding segment as CLIA-waived platforms enable pharmacy-based screening. The home care end user category is gaining structural importance as telehealth prescribing workflows legitimize remote test-to-treatment pathways.
The FDA governs UTI diagnostic kit premarket notification through 510(k) clearance and antimicrobial drug approval via stringent efficacy endpoints against resistant organisms, while the EMA's centralized procedure shapes access across European member states and the WHO publishes treatment guidelines that influence national essential medicine lists. These frameworks elevate compliance costs for novel entrants but protect incumbent positions for companies with established regulatory dossiers. Stakeholders must monitor evolving antimicrobial stewardship mandates that restrict empirical prescribing and redirect investment toward rapid diagnostics and non-antibiotic prophylaxis modalities.
Market Dynamics
Point-of-care diagnostic platforms are fragmenting purchasing authority away from centralized hospital laboratories toward retail pharmacies and direct-to-consumer channels, compressing traditional supply relationships while expanding addressable test volumes.
Growth Catalysts
- CLIA-waived platform expansion:Pharmacy chains across the United States deploy waived molecular diagnostic instruments, enabling same-day prescription workflows without laboratory infrastructure.
- Antimicrobial stewardship mandates:Hospital systems under Joint Commission accreditation requirements now mandate rapid susceptibility testing before empirical antibiotic administration.
- Telehealth test-to-treatment protocols:Remote consultation platforms integrate home collection kits with electronic prescribing, creating closed-loop care pathways for uncomplicated cases.
Market Restraints
- Active pharmaceutical ingredient concentration:Generic fluoroquinolone production depends on intermediate supply from concentrated Asian manufacturing clusters, exposing formulary managers to input volatility.
- FDA 510(k) antimicrobial device criteria:Stringent resistant-organism performance endpoints extend premarket review timelines for novel susceptibility testing platforms.
- Probiotic colonization substitutes:Lactobacillus-based preventive regimens displace recurring antibiotic prescriptions in postmenopausal patient populations with high recurrence rates.
Strategic Opportunities
- Indian retail pharmacy networks:Unorganized diagnostic access in tier-two and tier-three cities creates whitespace for kiosk-based rapid screening deployment.
- CRISPR-based detection convergence:Gene-editing diagnostic platforms paired with smartphone-readable lateral flow formats enable ultra-low-cost pathogen identification at resource-limited sites.
- German statutory health insurance digitization:Digital Health Applications (DiGA) fast-track reimbursement creates regulatory tailwind for app-integrated home monitoring systems.
Industry Challenges
- Clinical microbiology workforce scarcity:Laboratory technologist training programs fail to replenish retirement-driven attrition, constraining culture-based confirmation capacity.
- Legacy health record interoperability:Point-of-care device data formats lack standardized integration with Epic and Cerner dominant electronic medical record architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Tract Infection (UTI) Market |
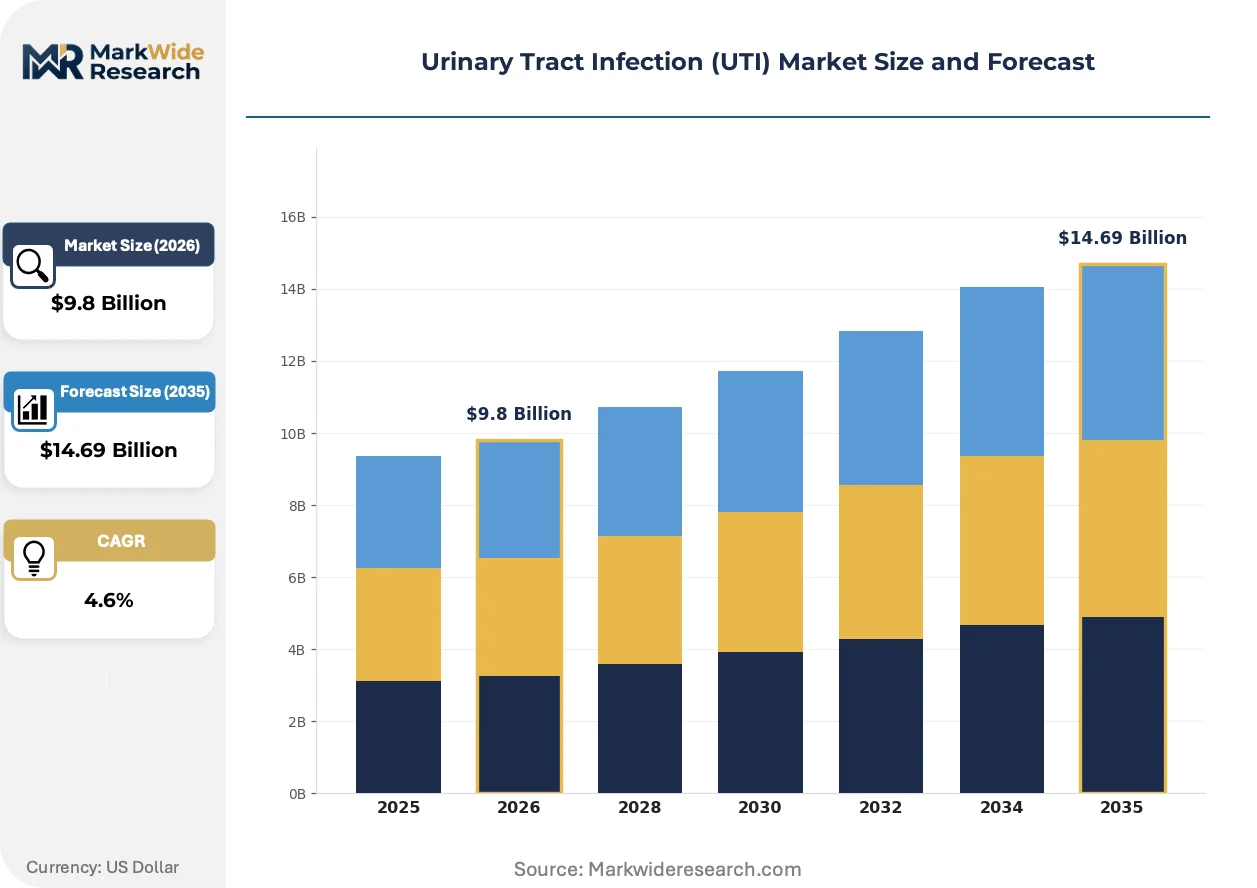
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Pain Relievers, Diagnostic Kits, Probiotics End User: Hospitals, Clinics, Home Care, Diagnostic Laboratories Delivery Mode: Oral, Intravenous, Topical, Intra-urethral Application: Acute UTI, Recurrent UTI, Asymptomatic Bacteriuria, Others |
| Companies Covered | Pfizer, GlaxoSmithKline, Bayer AG, AstraZeneca, Novartis, Cipla, Shionogi & Co., Merck Sharp and Dohme, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Tract Infection (UTI) Market Trends and Innovations
Molecular detection methods and connected health infrastructure are compressing diagnostic turnaround times while shifting site-of-care decisions away from traditional laboratory hierarchies toward distributed access models.
Multiplex nucleic acid amplification technology is integrating bacterial identification with resistance marker detection into single-cartridge formats. Urgent care networks and retail clinic operators adopt these platforms at accelerating replacement cycles for legacy culture-based workflows. The technology is integrating antibiotic stewardship compliance directly into initial patient encounters, reducing empirical broad-spectrum prescribing.
The FDA's streamlined 510(k) pathway for antimicrobial susceptibility devices accelerates premarket clearance for platforms demonstrating substantial equivalence to predicate instruments. This regulatory architecture compresses commercialization timelines for diagnostic developers while elevating post-market surveillance obligations. European manufacturers pursuing CE marking under MDR face parallel clinical evidence requirements that delay synchronized transatlantic launches.
Home-based specimen collection and remote result interpretation are displacing clinic-dependent diagnostic workflows. Direct-to-consumer kit providers partner with telehealth platforms to complete prescription fulfillment without physical consultation. This behavioral shift concentrates demand growth in United States metropolitan corridors with established same-delivery pharmacy infrastructure and permissive asynchronous prescribing regulations.
Urinary Tract Infection (UTI) Market Segmentation
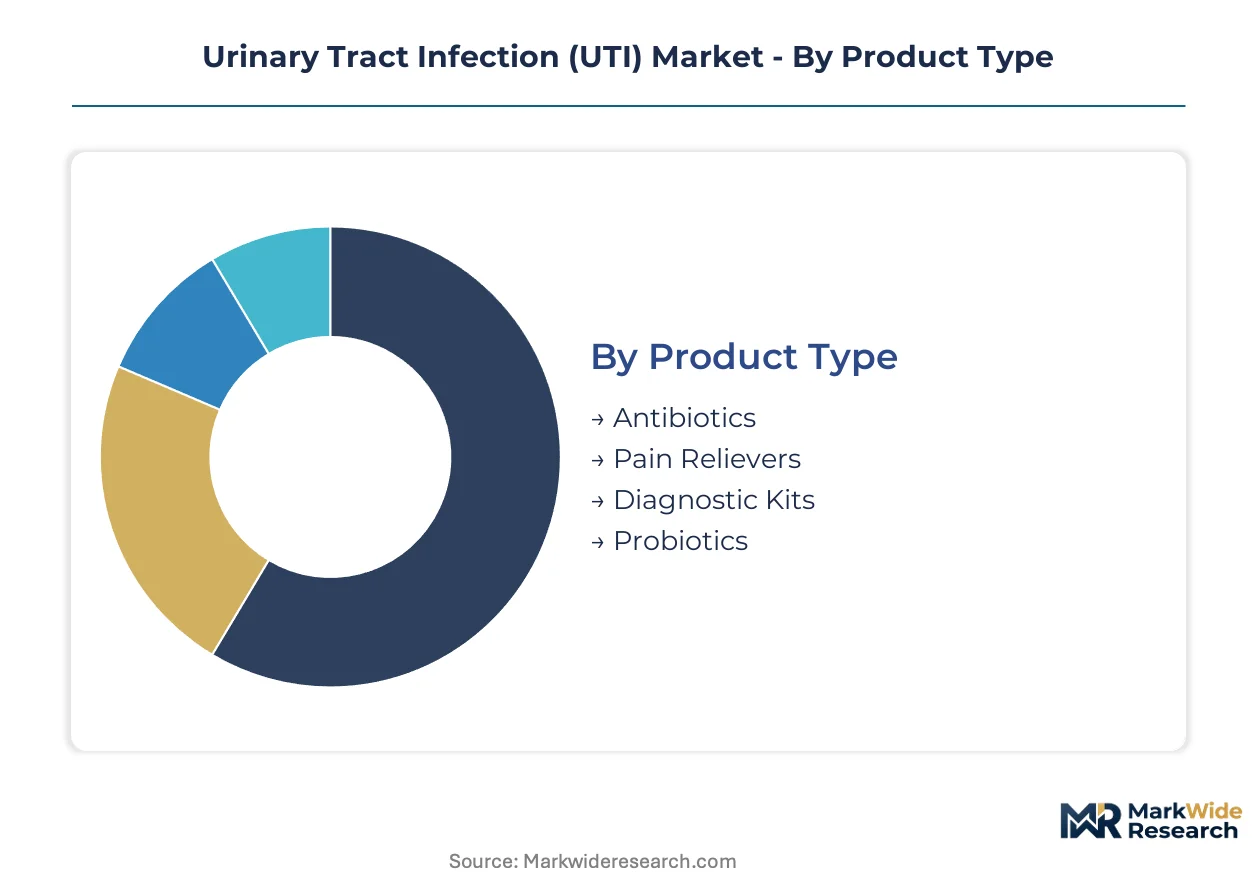
UTI market segmentation reveals divergent margin structures across therapeutic and diagnostic categories. Product type splits between commoditized antibiotics and premium-priced molecular diagnostics, while end-user fragmentation channels volume through institutional procurement versus decentralized home care pathways.
Product Type:
Antibiotics command volume dominance through recurrent prescribing patterns, while diagnostic kits capture premium expansion from point-of-care decentralization.
- Antibiotics:Beta-lactams, fluoroquinolones, and nitrofurantoin formulations constitute first-line eradication therapy. Hospital formularies in the United States concentrate procurement through integrated delivery networks facing Joint Commission stewardship mandates.
- Diagnostic Kits:Nucleic acid amplification assays and CLIA-waived lateral flow platforms enable sub-one-hour pathogen identification. Pharmacy chains deploy these instruments to bypass centralized laboratory bottlenecks, accelerating same-day prescription workflows.
- Pain Relievers:Phenazopyridine and NSAID adjuncts address symptomatic dysuria without antimicrobial activity.
- Probiotics:Lactobacillus rhamnosus and reuteri strains colonize urogenital mucosa to suppress uropathogenic E. coli adherence.
Today's leader: Antibiotics. Tomorrow's challenger: Diagnostic Kits.
End User:
Institutional procurement concentrates in hospital systems, while home care channels fragment purchasing authority toward direct-to-consumer platforms.
- Hospitals:Inpatient and emergency departments manage complicated pyelonephritis and catheter-associated infections requiring IV antibiotic administration.
- Home Care:Telehealth-integrated test-to-treatment protocols legitimize remote specimen collection and asynchronous prescribing. United States metropolitan corridors with same-day pharmacy delivery infrastructure channel disproportionate volume growth.
- Clinics:Urgent care networks adopt multiplex molecular platforms to reduce empirical broad-spectrum prescribing.
- Diagnostic Laboratories:Centralized reference labs perform culture-based confirmation and antimicrobial susceptibility testing for stewardship compliance.
Institutional channels anchor current revenue. Home care infrastructure is climbing the fastest.
Delivery Mode:
Oral administration dominates uncomplicated cases, while intravenous routes retain premium positioning for hospitalized patients.
- Oral:Tablet and suspension formulations of fosfomycin, nitrofurantoin, and trimethoprim-sulfamethoxazole enable outpatient completion of therapy without infusion infrastructure.
- Intravenous:Ceftriaxone and piperacillin-tazobactam administration requires hospital or infusion center capacity for complicated infections.
- Topical:Estrogen creams address atrophic vaginitis predisposing to recurrent infection in postmenopausal populations.
- Intra-urethral:Instilled antimicrobial and silver-containing solutions target catheter-associated biofilm colonization.
Oral routes defend volume leadership. Intravenous maintains margin concentration in institutional settings.
Application:
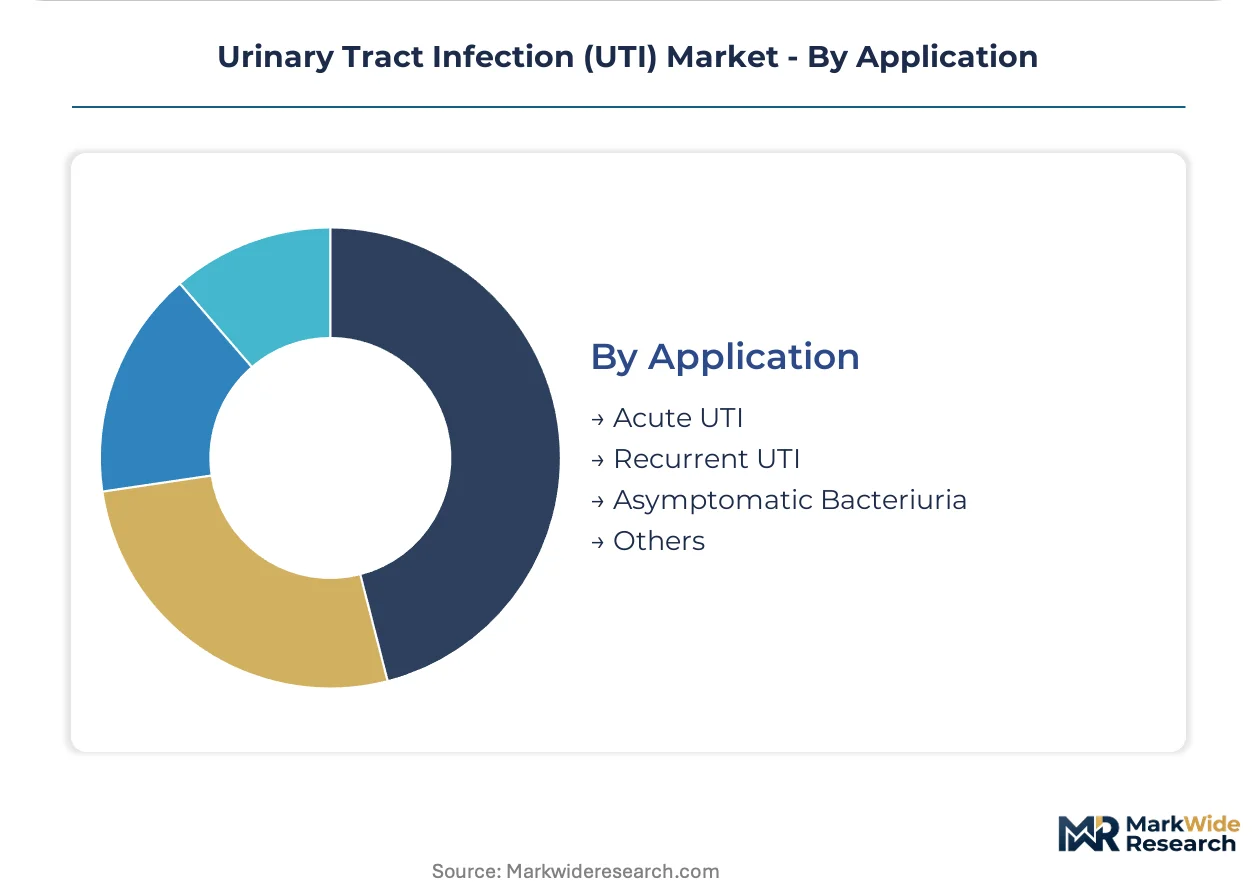
Acute uncomplicated infections drive prescription frequency, while recurrent UTI management commands premium investment in prophylaxis and diagnostics.
- Acute UTI:Single-episode cystitis in premenopausal women generates the highest prescription volume through retail pharmacy channels.
- Recurrent UTI:Three or more episodes within twelve months triggers specialist referral, extended prophylactic antibiotic courses, and urologic workup. Postmenopausal and spinal cord injury populations exhibit elevated recurrence rates.
- Asymptomatic Bacteriuria:Screening in pregnancy and preoperative settings detects colonization requiring treatment to prevent pyelonephritis or procedural sepsis.
- Others:Catheter-associated UTI and complicated infections with functional or anatomical abnormalities require tailored antimicrobial selection.
Acute cases anchor prescription economics. Recurrent UTI management shows steepest expansion trajectory from preventive diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States channels higher diagnostic kit volumes through retail pharmacy networks than Germany, where hospital-based laboratory confirmation retains stronger institutional preference.
United States
Ambulatory care networks and telehealth prescribing workflows drive home-based UTI testing adoption. The FDA's streamlined 510(k) pathway accelerates antimicrobial susceptibility device clearances. Pharmacy chains in metropolitan corridors deploy CLIA-waived molecular platforms for same-day test-to-treatment completion.
Germany
Statutory health insurance digitization through DiGA fast-track reimbursement creates regulatory tailwind for app-integrated home monitoring systems. The EMA's centralized procedure shapes diagnostic kit access across member states. Berlin-Brandenburg clusters host digital health startups converging on remote UTI management platforms.
India
Unorganized diagnostic access in tier-two and tier-three cities creates whitespace for kiosk-based rapid screening deployment. CDSCO governs medical device registration and antimicrobial drug manufacturing standards. Maharashtra and Gujarat pharmaceutical manufacturing belts anchor generic fluoroquinolone production for domestic and export markets.
Japan
PMDA maintains stringent efficacy endpoints for novel antimicrobial mechanisms against resistant uropathogens. Tokyo-Osaka pharmaceutical corridors concentrate R&D investment in non-antibiotic prophylaxis modalities. PMDA's Sakigake designation accelerates priority review for breakthrough diagnostic platforms.
United Kingdom
NHS antimicrobial stewardship programs mandate rapid susceptibility testing before empirical antibiotic administration. MHRA post-Brexit regulatory autonomy diverges from EMA centralized procedures for certain device categories. London-Southeast biotech clusters develop multiplex nucleic acid amplification technologies for point-of-care deployment.
Urinary Tract Infection (UTI) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across antibiotic manufacturing and diagnostic platform development. The market structure tiers between scale-driven pharmaceutical majors and agile diagnostic innovators. Strategic archetypes include integrated delivery network contractors, generic API specialists, and rapid point-of-care technology developers. Competitive moves concentrate on M&A for antimicrobial resistance capabilities and strategic partnerships for CLIA-waived platform distribution.
Within the diversified pharmaceutical tier, Pfizer and GlaxoSmithKline occupy positions anchored by manufacturing scale and hospital supply contract breadth. Bayer AG exemplifies the European conglomerate archetype with historical urology therapeutic presence. Cipla represents emerging market generic specialists competing on cost-sensitive formulary access. Shionogi & Co. sits within the R&D-intensive innovation tier focused on novel mechanisms against resistant organisms.
| Leading Market Players |
|---|
| Pfizer |
| GlaxoSmithKline |
| Bayer AG |
| AstraZeneca |
| Novartis |
| Cipla |
| Shionogi & Co. |
| Merck Sharp and Dohme |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Clinical microbiology technologist concentration in the United States Northeast and Germany creates labor-cost differentials that widen pricing-tier spreads between automated molecular diagnostics and culture-based confirmation workflows.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for generic fluoroquinolone APIs. Three-tier pricing structure across premium, standard, and economy levels separates branded extended-spectrum antibiotics from hospital-contracted generics and unbranded commodity tablets. Cost compression in the economy tier is intensifying because of intermediate supply volatility from concentrated Asian manufacturing clusters. Hospital procurement committees exhibit lowest price sensitivity due to Joint Commission stewardship mandates, while retail pharmacy chains in emerging markets demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with intermediate API manufacturing clusters in Zhejiang and Jiangsu provinces. Active pharmaceutical ingredient production draws from concentrated chemical synthesis corridors in China, India, and Italy. Raw material dependencies include fluoroquinolone intermediates, nitrofurantoin precursors, and specialized diagnostic reagents. Tariff exposure on Chinese-sourced inputs presents structural risk to European and North American formularies. Distribution runs through integrated delivery networks in the United States, statutory health insurance channels in Germany, and fragmented retail pharmacy networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UTI market functions as a regulatory compounder where FDA's streamlined 510(k) pathway for antimicrobial susceptibility devices accelerates product entry and reshapes competitive timelines.
For Market Incumbents: To counter point-of-care diagnostic fragmentation, Pfizer and GlaxoSmithKline should deepen backward integration into generic API supply through captive production of fluoroquinolone intermediates. Incumbents must also secure CLIA-waived platform distribution partnerships with pharmacy chains to defend institutional channel erosion.
For New Entrants and Emerging Players: Capture whitespace in Indian tier-two and tier-three cities through kiosk-based rapid screening deployment. The most penetrable segment is home-based specimen collection integrated with telehealth prescribing workflows. A direct-to-consumer go-to-market angle paired with same-day pharmacy delivery partnerships enables asynchronous test-to-treatment completion without legacy laboratory infrastructure.
For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates are the most active acquirer in this space, targeting novel antimicrobial mechanism developers to fill resistance-gap pipelines. Over the medium-term horizon, acquisition focus should center on CRISPR-based diagnostic platforms with smartphone-readable output formats. The signal to watch is PMDA Sakigake designation awards for breakthrough susceptibility testing technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Platform Deployment | Pharmacy chains bypass centralized laboratories using FDA-cleared molecular instruments for same-day prescribing. |
| Antimicrobial Stewardship Compliance | Hospital systems satisfy Joint Commission mandates through rapid susceptibility testing before empirical antibiotic administration. |
| Telehealth Integration Partnership | Direct-to-consumer kit providers close test-to-treatment loops with asynchronous prescribing platforms. |
| Generic API Backward Integration | Manufacturing scale secures fluoroquinolone intermediate supply against concentrated Asian production volatility. |
| Novel Mechanism R&D Investment | Shionogi and peers target resistant uropathogens through non-traditional antimicrobial approaches beyond beta-lactams. |
Research Methodology
Bottom-up hospital and home care demand modeling reconciled against top-down API production and diagnostic kit manufacturing tracking forms the analytical core. Primary interviews with hospital procurement managers, formulary directors, regulatory affairs leads, and CLIA-waived platform engineers combined with secondary validation from FDA 510(k) filings, EMA centralized procedure submissions, hospital procurement databases, and GPO contract repositories. Triangulation across stakeholder perspectives and documentary sources ensures segment-level consistency.
Input-output matrices map product type volumes through end-user channels across the projection horizon. Segmentation dimensions modeled include antibiotics versus diagnostics versus probiotics, institutional versus home care delivery, and oral versus intravenous administration routes. CAGRs derive from patient episode frequency projections, reimbursement trajectory assumptions, and point-of-care adoption curves. Forecast inputs incorporate antimicrobial stewardship mandate penetration rates and telehealth prescribing regulatory permissiveness by state and country.
Regulatory timeline delays, resistant organism outbreak patterns, and probiotic substitution acceleration are the dominant revision risks. Forecasts reflect documented assumptions about CLIA-waiver expansion pace and integrated delivery network consolidation trends. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Disposable Ureteroscope Market
Urology
Urinary Tract Infection Testing Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Prostate Cancer Treatment Market
Urology
Urology Ultrasound Market
Urology
Varicocele Treatment Market
Urology
Suprapubic Catheters Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Urology Robotic Surgery Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Asia-Pacific Bladder Disorders Market