
 Harmonic Scalpel Market | 2026-2036
Harmonic Scalpel Market Size, Share, and Industry Trends Forecast 2026-2036
Harmonic Scalpel Market Outlook
Ultrasonic energy delivery is tilting harmonic scalpel architectures toward integrated generator-handpiece platforms that consolidate dissection and coagulation. Johnson & Johnson (Ethicon) leverages its broad surgical stapling ecosystem to bundle harmonic devices with complementary instruments. Stryker Corporation anchors its position through dedicated R&D spending on advanced energy platforms. Medtronic plc competes across multiple surgical specialties with a diversified energy device portfolio.
A harmonic scalpel is an electrosurgical instrument that transmits ultrasonic vibrations at frequencies typically between 55 kHz and 60 kHz to simultaneously cut tissue and coagulate blood vessels through protein denaturation. The technology minimizes thermal spread beyond the active blade tip, preserving adjacent anatomical structures during precision dissection. Ultrasonic Scalpel systems command the largest revenue share within product type segmentation due to their established presence in open and laparoscopic procedures. Hospitals represent the dominant end user channel, though Ambulatory Services are gaining traction as same-day surgical volumes expand. Piezoelectric Technology variants are emerging as a faster-growing technology subset, offering enhanced frequency control and reduced generator footprint.
FDA 510(k) clearance pathways govern harmonic scalpel market access in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence requirements for electrosurgical equipment in Europe. Japan's PMDA maintains rigorous electrical safety and biocompatibility standards that shape product design cycles for manufacturers targeting that market. Stakeholders must monitor evolving reimbursement codes for ultrasonic dissection procedures across national health systems to anticipate volume shifts and pricing pressures.
Market Dynamics
Ultrasonic dissection platforms are consolidating generator-handpiece architectures as hospitals demand single-vendor ecosystems that reduce OR setup complexity and standardize training protocols across surgical departments.
Growth Catalysts
- Laparoscopic procedure expansion:Minimally invasive surgery volumes in Germany's academic medical centers are pulling ultrasonic scalpel utilization into general, gynecologic, and colorectal specialties.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for electrosurgical devices accelerates product iterations and competitive entry in the United States.
- Piezoelectric frequency control:Enhanced signal precision enables smaller generator footprints that fit ambulatory surgery center space constraints.
Market Restraints
- Single-use consumable cost structure:Per-procedure blade and sheath expenses strain hospital procurement budgets compared to reusable electrosurgical alternatives.
- EU MDR clinical evidence requirements:Stricter biocompatibility and electrical safety documentation timelines delay product launches across European markets.
- Monopolar electrosurgery substitution:Lower capital requirements and established surgeon familiarity preserve competitive pressure in price-sensitive segments.
Strategic Opportunities
- Ambulatory surgery center channel development:Same-day discharge protocols in the United States create demand for compact, portable ultrasonic systems with simplified interfaces.
- Japan PMDA electrical safety standards:Compliance with rigorous biocompatibility frameworks opens premium positioning for manufacturers demonstrating superior thermal spread control.
- AI-assisted tissue recognition convergence:Integration of real-time impedance feedback with ultrasonic energy delivery enables autonomous vessel sealing optimization.
Industry Challenges
- OR staff training standardization:Ultrasonic dissection technique differs substantially from electrosurgery, requiring dedicated competency programs that extend deployment timelines.
- EU MDR technical documentation:Clinical evaluation report preparation for electrosurgical equipment consumes 18-24 months of regulatory resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Harmonic Scalpel Market |
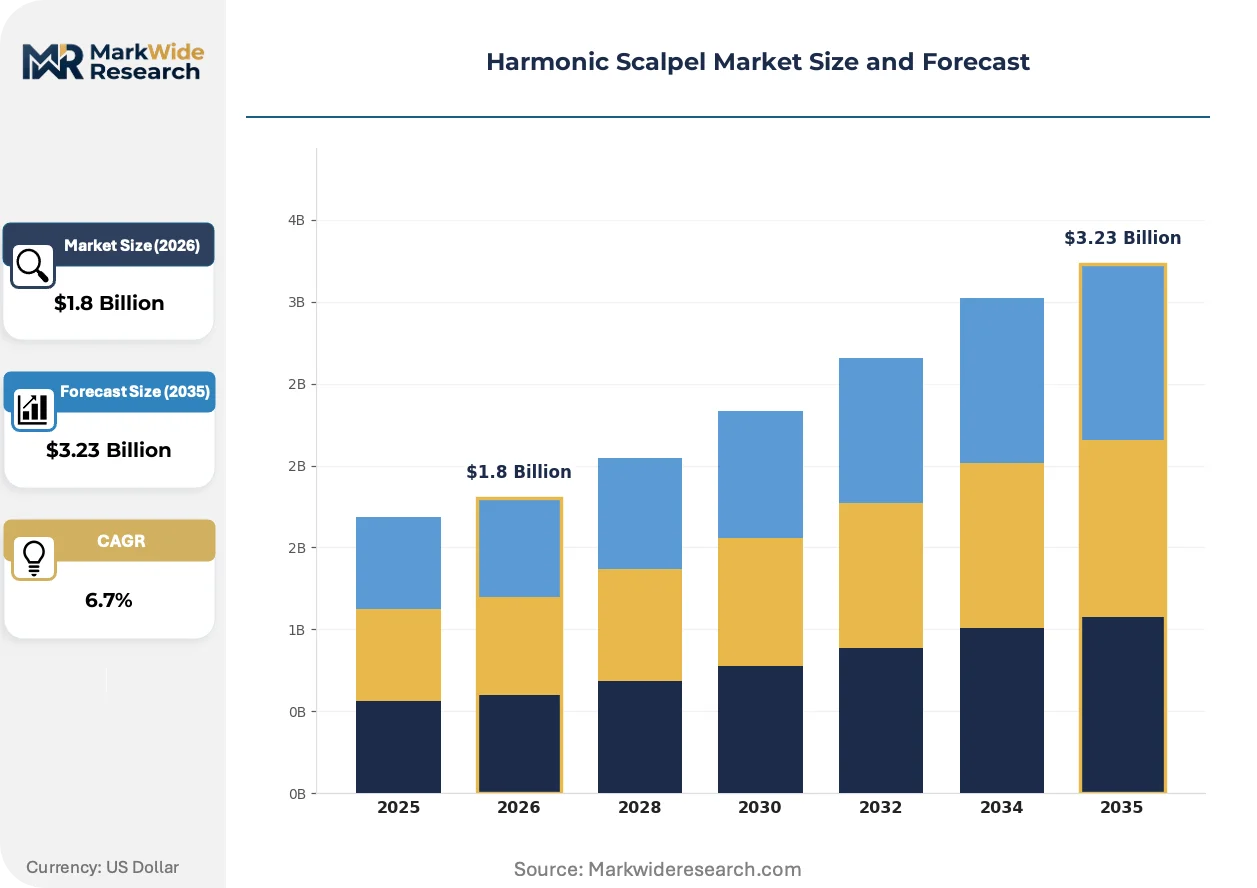
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Scalpel, Energy Device, Surgical Handpiece, Tissue Harmonics End User: Hospitals, Surgical Centers, Ambulatory Services, Specialty Clinics Application: General Surgery, Gynecological Surgery, Urological Surgery, Surgical Oncology Technology: Ultrasound Technology, Piezoelectric Technology, Vaporization Technology, RF Technology |
| Companies Covered | Stryker Corporation, Integra LifeSciences, Johnson & Johnson (Ethicon), Wuhan BBT Medical Tech, Axon Medical Solutions Private Ltd, Medtronic plc, BOWA-electronic GmbH & Co. KG, Beijing Sonicmed Medical, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Harmonic Scalpel Market Strategic Shifts
Harmonic scalpel architectures are pivoting toward intelligent energy delivery that adapts to tissue impedance in real time, compressing the gap between dissection precision and hemostatic reliability.
Advanced generator-handpiece communication protocols are digitizing surgical workflows through embedded sensors that transmit blade temperature, tissue impedance, and activation duration to centralized OR data systems. Academic medical centers in Germany are piloting these connected platforms to standardize technique across training programs. The technology is digitizing compliance documentation by automatically logging procedure parameters for quality assurance and reimbursement validation.
EU MDR implementation is tightening clinical evidence requirements for electrosurgical devices, forcing manufacturers to generate prospective safety data rather than relying on predicate equivalence. This regulatory shift extends product development cycles and elevates documentation costs. High-complexity ultrasonic systems targeting multi-specialty use face the steepest compliance burden, with some firms narrowing indications to accelerate approval.
Hospital procurement departments are consolidating vendor relationships through single-source agreements that bundle harmonic devices with complementary stapling and sealing instruments. This purchasing model squeezes standalone ultrasonic suppliers and rewards integrated surgical platform vendors. The United States exhibits the most pronounced concentration, with IDNs leveraging volume commitments to extract price concessions and dedicated service support.
Harmonic Scalpel Market Segmentation
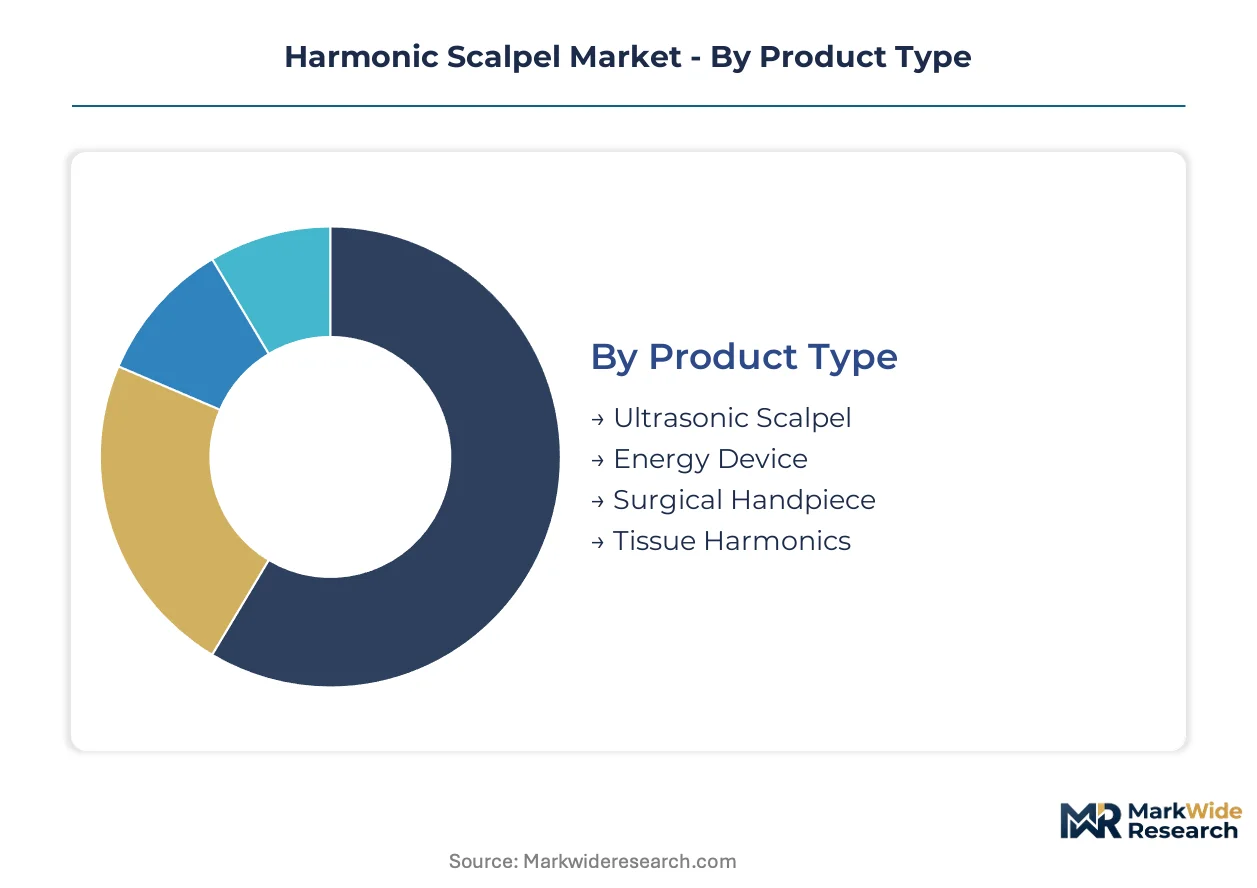
Harmonic scalpel procurement patterns diverge sharply across clinical settings, with generator-handpiece compatibility and per-procedure consumable economics driving vendor selection. Segmentation reveals how ultrasonic dissection platforms penetrate distinct surgical workflows through tailored energy delivery specifications and regulatory compliance profiles.
Product Type:
After-sales service intensity varies dramatically across product categories, with integrated generator-handpiece systems demanding dedicated field engineering support while disposable components require just-in-time logistics rather than technical intervention.
- Ultrasonic Scalpel:These systems combine piezoelectric transducers with titanium alloy blades vibrating at 55-60 kHz to achieve simultaneous cutting and coagulation through protein denaturation. Demand concentrates in Germany's academic medical centers where laparoscopic procedure volumes necessitate precision thermal control for complex dissections adjacent to critical structures.
- Energy Device:Standalone generator units power multiple handpiece configurations through standardized connection protocols, enabling hospitals to standardize across surgical specialties. Procurement in United States integrated delivery networks prioritizes single-vendor ecosystems that bundle energy platforms with complementary stapling instruments to reduce OR setup complexity.
- Surgical Handpiece:Ergonomic instrument designs accommodate varying grip preferences across open and laparoscopic access techniques.
- Tissue Harmonics:Specialized configurations optimize frequency modulation for delicate parenchymal dissection in hepatobiliary procedures.
Ultrasonic Scalpel holds the largest share; momentum sits with Energy Device as hospitals consolidate vendor relationships.
End User:
Capital deployment cycles and consumable replenishment rhythms create distinct service models across customer types, with high-volume institutions negotiating enterprise pricing against ambulatory facilities prioritizing equipment footprint.
- Hospitals:These institutions command the dominant procurement channel through centralized sterile processing departments and dedicated biomedical engineering staff capable of maintaining complex generator platforms. United States hospital systems leverage volume commitments across multiple campuses to extract price concessions and dedicated technical support from manufacturers.
- Surgical Centers:Freestanding facilities optimize equipment utilization across high-throughput specialty schedules, favoring rapid-cooling handpiece designs that accommodate compressed turnover times. Germany's dense cluster of specialized surgical hospitals drives concentrated demand for multi-specialty ultrasonic platforms.
- Ambulatory Services:Same-day discharge protocols create demand for portable systems with simplified interfaces.
- Specialty Clinics:Focused practices prioritize single-procedure efficiency over platform versatility.
Hospitals hold the largest share; momentum sits with Ambulatory Services as procedure migration accelerates.
Application:
Procedure complexity and tissue vascularity determine energy platform specifications, with high-bleed-risk specialties demanding advanced coagulation algorithms while standardized operations accommodate simpler device configurations.
- General Surgery:Cholecystectomy, appendectomy, and hernia repair procedures constitute the foundational utilization base for ultrasonic dissection across hospital systems. United States general surgery departments are expanding adoption as training programs standardize ultrasonic technique alongside traditional electrosurgery competency.
- Gynecological Surgery:Hysterectomy and myomectomy procedures leverage harmonic technology for precise uterine vessel sealing with minimal thermal spread to adjacent ureteral and bowel structures. Germany's academic medical centers are pulling utilization into this specialty through minimally invasive fellowship programs.
- Urological Surgery:Prostatectomy and nephrectomy applications demand extended blade lengths for deep pelvic dissection.
- Surgical Oncology:Oncologic margins require precise tissue plane identification with controlled thermal damage zones.
General Surgery holds the largest share; momentum sits with Gynecological Surgery as minimally invasive volumes expand.
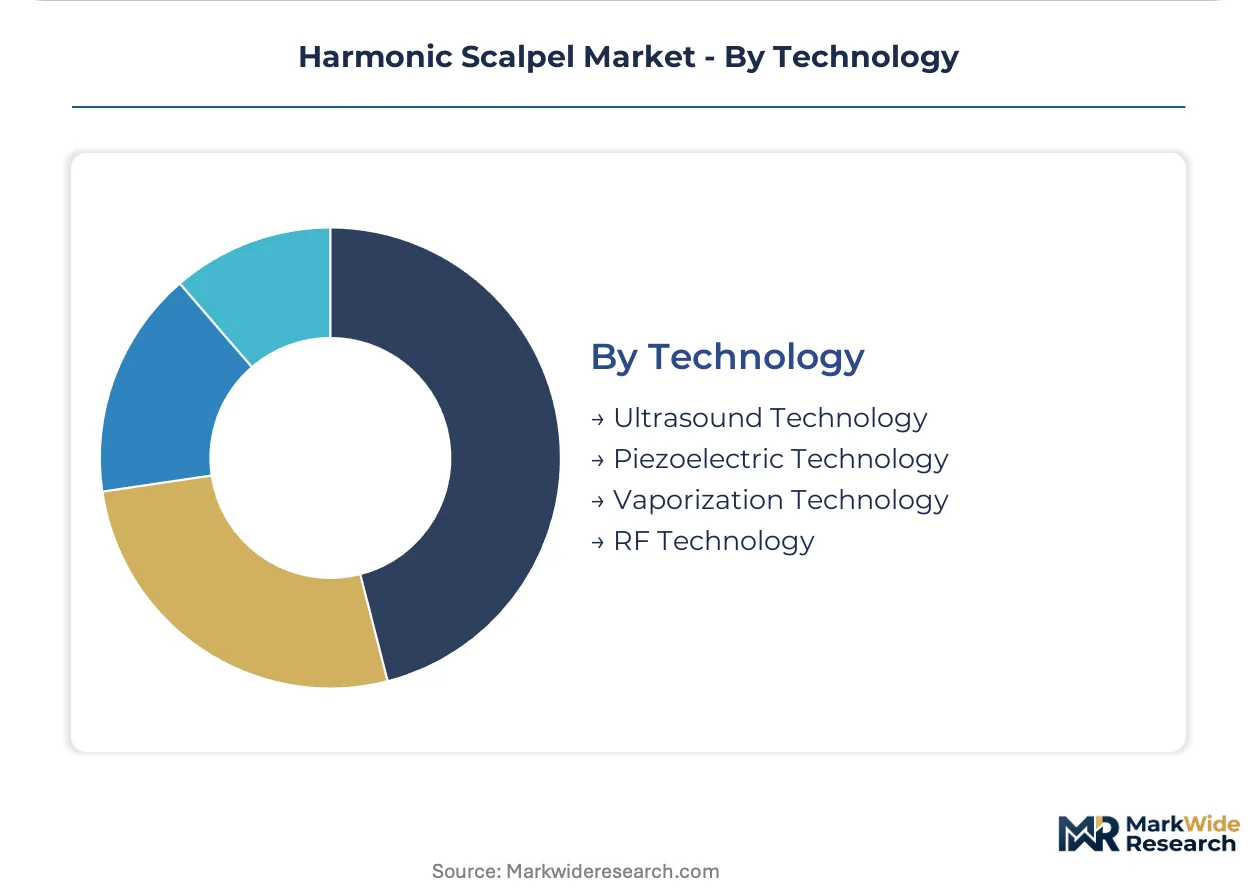
Technology:
Signal processing sophistication and generator miniaturization potential differentiate technology categories, with frequency control precision determining suitability for compact ambulatory configurations versus high-power open surgery platforms.
- Ultrasound Technology:Conventional piezoelectric systems operating at fixed frequencies between 55-60 kHz dominate installed bases through proven reliability and broad tissue applicability. United States hospitals maintain substantial investments in these platforms, constraining rapid technology transitions despite emerging alternatives.
- Piezoelectric Technology:Advanced ceramic transducer designs enable real-time frequency modulation based on tissue impedance feedback, compressing dissection-coagulation transition times. Germany's research hospitals are piloting these systems to standardize technique across training programs through embedded performance analytics.
- Vaporization Technology:Cavitation-based tissue removal offers alternative dissection mechanics for specific parenchymal applications.
- RF Technology:Radiofrequency energy integration provides hybrid coagulation options for surgeons transitioning from traditional electrosurgery.
Ultrasound Technology holds the largest share; momentum sits with Piezoelectric Technology as frequency control capabilities advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export ultrasonic dissection platforms to United States hospital systems, establishing a dominant trade corridor in advanced energy surgical devices.
United States
Integrated delivery networks consolidate procurement through single-vendor agreements spanning harmonic devices and complementary stapling instruments. FDA 510(k) premarket notification pathways streamline clearance timelines for electrosurgical equipment iterations. Academic medical centers in Boston and the Research Triangle anchor adoption pilots for AI-assisted tissue recognition modules.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia drive laparoscopic procedure volumes across general, gynecologic, and colorectal specialties. EU MDR clinical evidence requirements impose stricter biocompatibility documentation timelines for electrosurgical device launches. The Munich-Stuttgart corridor concentrates R&D activity for piezoelectric frequency control systems.
Japan
PMDA electrical safety and biocompatibility standards shape product design cycles for manufacturers targeting premium hospital segments. METI industrial policy supports domestic production of advanced ceramic transducer components. Tokyo-Osaka metropolitan hospitals pilot connected generator platforms with embedded performance analytics.
China
NMPA medical device registration pathways govern market access for imported ultrasonic dissection systems. The Yangtze River Delta manufacturing base supplies piezoelectric components to global OEMs. Beijing and Shanghai tertiary hospitals expand minimally invasive surgery training programs standardizing harmonic technique.
India
CDSCO medical device rules classify ultrasonic scalpels as Class C products requiring import license compliance for multinational suppliers. Maharashtra and Karnataka host the densest clusters of corporate hospital chains expanding laparoscopic surgery capacity. Delhi-NCR medical device distributors build service networks for generator-handpiece maintenance.
Harmonic Scalpel Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: integrated surgical platform conglomerates, standalone energy device specialists, and regional component fabricators. Consolidation pressures intensify as hospital procurement departments demand bundled instrument ecosystems. Dominant competitive moves include strategic partnerships for distribution reach and technology licensing for frequency control IP.
Among diversified medical technology conglomerates, Johnson & Johnson (Ethicon) and Stryker Corporation occupy positions exemplifying integrated platform strategies, while Medtronic plc anchors the multi-specialty energy device tier. Wuhan BBT Medical Tech and Beijing Sonicmed Medical represent Chinese fabricators building regional scale. BOWA-electronic GmbH & Co. KG exemplifies German precision engineering specialization in electrosurgical components.
| Leading Market Players |
|---|
| Stryker Corporation |
| Integra LifeSciences |
| Johnson & Johnson (Ethicon) |
| Wuhan BBT Medical Tech |
| Axon Medical Solutions Private Ltd |
| Medtronic plc |
| BOWA-electronic GmbH & Co. KG |
| Beijing Sonicmed Medical |
| Olympus Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in piezoelectric ceramic transducer fabrication across the Yangtze River Delta is tightening supply availability for ultrasonic generator manufacturers, compressing margins and forcing procurement departments toward multi-year offtake commitments to secure component allocation.
Pricing Analysis
Cost-plus contracts with titanium alloy indexation dominate procurement agreements between generator OEMs and blade fabricators. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) clearance status and bundled after-sales service intensity. Pricing pressure stems from single-use consumable cost scrutiny in United States hospital procurement committees. Ambulatory surgery centers exhibit highest price sensitivity, while German academic medical centers prioritize thermal spread performance over per-procedure economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard practice among Chinese component suppliers serving global OEMs. Manufacturing concentration spans China for piezoelectric ceramics, Germany for precision titanium blade fabrication, and Japan for advanced generator electronics. Supply chain risk centers on single-source vulnerability for high-purity lead zirconate titanate feedstock. Distribution runs through hospital GPO contracts in the United States and specialized surgical instrument distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The harmonic scalpel market is entering a cyclical recovery phase as deferred laparoscopic procedure volumes from prior years normalize through hospital backlogs, with Germany's academic medical centers leading utilization restoration.
For Market Incumbents: Insulate installed base relationships through backward integration into piezoelectric transducer production, securing captive supply of critical frequency-control components. Deepen service attachment rates by embedding performance analytics that automate compliance documentation for EU MDR clinical evidence requirements. Counter monopolar electrosurgery substitution threats with bundled stapling instrument agreements that raise switching costs.
For New Entrants and Emerging Players: Establish a beachhead in ambulatory surgery center channels by developing compact generator-handpiece platforms with sub-15-minute sterilization cycles. Target United States same-day discharge protocols where incumbent footprint remains underdeveloped. Pursue white-label manufacturing partnerships with Chinese component fabricators to compress capital requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform vendors with multi-specialty energy device portfolios and hospital GPO contract penetration. Long-term viability favors manufacturers with demonstrated EU MDR technical documentation capabilities and Japan PMDA electrical safety clearance. Monitor laparoscopic procedure volume reporting from German academic medical centers as the earliest inflection signal for ultrasonic dissection demand recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined premarket notification accelerates competitive entry for electrosurgical device iterations in United States. |
| EU MDR Clinical Evidence Investment | Prospective safety data generation enables premium positioning against predicate-equivalence competitors in Europe. |
| Hospital System Partnership Development | Single-vendor ecosystem agreements with IDNs reduce OR setup complexity and standardize training protocols. |
| AI-Assisted Tissue Recognition Integration | Real-time impedance feedback convergence enables autonomous vessel sealing optimization across laparoscopic specialties. |
| Piezoelectric Frequency Control Licensing | Advanced ceramic transducer IP acquisition compresses generator miniaturization timelines for ambulatory configurations. |
Study Parameters
Initial hypotheses were tested against primary input from hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and regulatory affairs leads at electrosurgical device manufacturers, then refined through secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement spend analytics, and piezoelectric component trade flow records. Bottom-up demand modeling triangulated with top-down market sizing across generator installations and per-procedure consumable throughput.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation by product type, end user channel, application specialty, and technology variant informing volume projections. CAGRs were derived from installed base expansion rates multiplied by utilization intensity assumptions, incorporating laparoscopic procedure migration patterns and same-day discharge protocol adoption as harmonic scalpel-specific forecast inputs.
Sensitivities concentrate around EU MDR implementation timelines, Japan PMDA electrical safety standard revisions, and ambulatory surgery center reimbursement code changes. Forecasts reflect documented assumptions regarding procedure volume normalization and vendor consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Disposable Spinal Instruments Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
Cardiac Surgery Instruments Market
Surgical Instruments
Absorbable PGA Surgical Sutures Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Equine Surgical Equipment Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market
Surgical Instruments
Global Plastic Surgery Instruments Market
Surgical Instruments
Laparoscopic Power Morcellators Market
Surgical Instruments
Cryosurgery Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market