
 Europe Urology Devices Market | 2026-2036
Europe Urology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Urology Devices Market Foresight
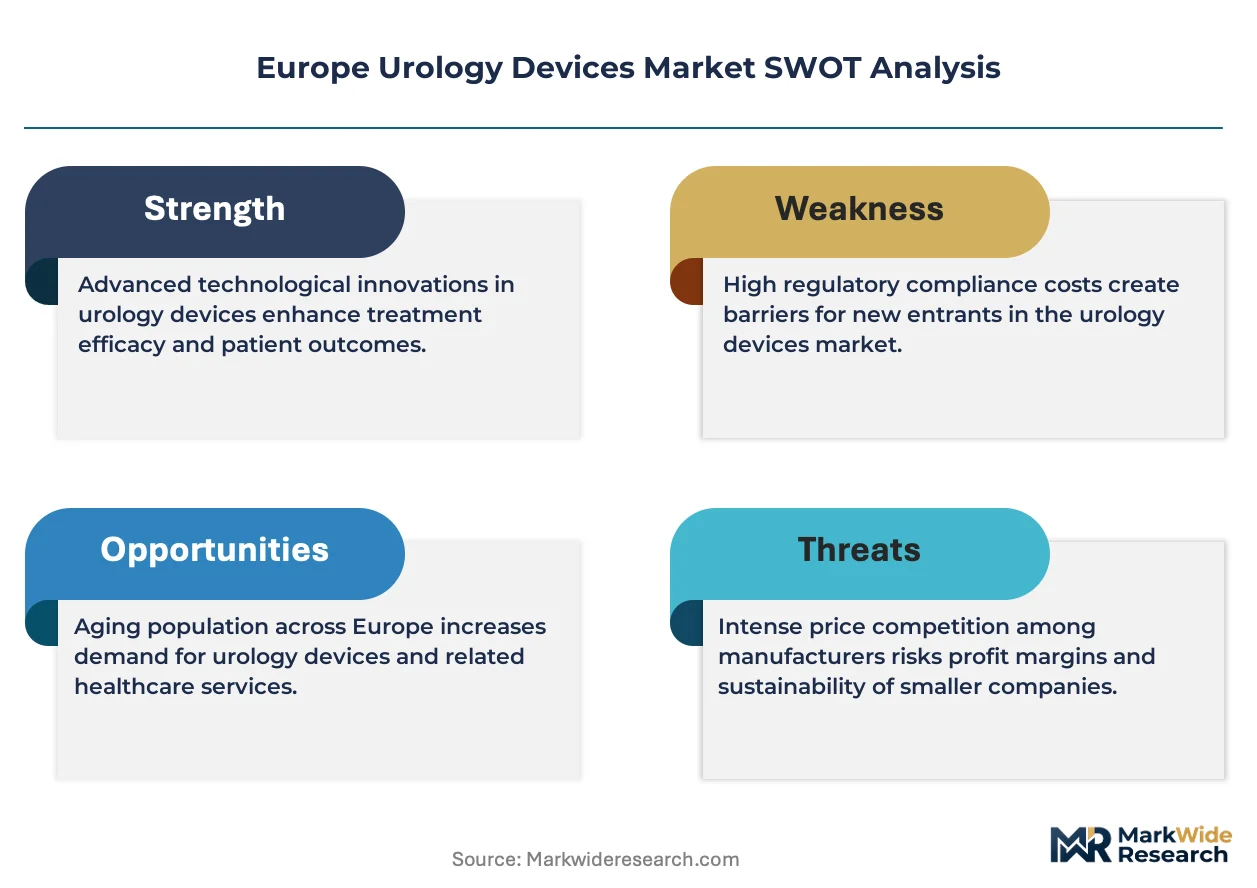
Modularization of endoscope-tower configurations is restructuring purchasing decisions across European hospital systems. KARL STORZ SE & Co. KG dominates rigid endoscope manufacturing from its Tuttlingen base. Richard Wolf GmbH anchors specialized lithotripsy system production for stone management workflows. B. Braun Melsungen AG leverages integrated catheter and drainage portfolios to compete across acute and chronic care settings.
Europe urology devices encompass instruments, endoscopes, catheters, imaging systems, and surgical tools designed for diagnosing and treating disorders of the urinary tract and male reproductive system, typically manufactured from medical-grade polymers, stainless alloys, or fiber-optic assemblies with sterilization compatibility and biocompatibility per ISO 10993. These devices serve urologists, general surgeons, and oncologists in hospitals, ambulatory surgical centers, and specialty clinics for procedures ranging from diagnostic cystoscopy to tumor resection and stone fragmentation. Endoscopes command premium positioning due to capital intensity and replacement cycles tied to optical technology refresh. Catheters represent the highest-volume segment with margin pressure from standardization and group purchasing consolidation. Surgical instruments for benign prostatic hyperplasia and prostate cancer applications concentrate specialized R&D investment as robotic and laser platforms displace conventional resection.
The EU Medical Device Regulation and EMA oversight shape clinical trial obligations and post-market surveillance for implantable and active urological devices, extending time-to-market for novel technologies. REACH compliance and RoHS substance restrictions influence material selection in catheter and endoscope manufacturing, particularly for phthalate-free alternatives and recyclable packaging. France's ANSM and Germany's BfArM enforce national vigilance reporting that affects product liability exposure and recall protocols across the single market. Stakeholders must monitor reimbursement divergence between statutory health insurance systems as technology assessment bodies in Berlin and Paris apply divergent cost-effectiveness thresholds to innovative urological interventions.
Market Dynamics
EU MDR clinical evidence requirements are compressing time-to-market for implantable urological devices while ambulatory surgical centers in Germany and France accelerate procurement of minimally invasive stone management systems.
Growth Catalysts
- Minimally invasive lithotripsy adoption:Ambulatory surgical centers across Germany and France are expanding capital deployment for integrated stone management workflows that reduce inpatient bed utilization.
- REACH phthalate restrictions:Regulatory pressure for phthalate-free catheter materials is stimulating polymer innovation and creating first-mover advantages for compliant manufacturers.
- Hospital procurement consolidation:Germany's centralized hospital procurement networks are standardizing endoscope-tower specifications, driving volume commitments from multi-site health systems.
Market Restraints
- Optical component supply concentration:Fiber-optic assemblies for rigid endoscopes depend on specialized suppliers concentrated in southern Germany, creating vulnerability to component shortages.
- MDR clinical trial cost inflation:Extended post-market surveillance obligations under EU MDR are raising capital requirements for novel implantable urological device commercialization.
- Catheter margin compression:Standardization through group purchasing organizations is squeezing pricing power in high-volume disposable segments.
Strategic Opportunities
- Robotic-laser platform convergence:Integration of robotic positioning with thulium fiber laser technology creates differentiated positioning for benign prostatic hyperplasia procedures.
- France regional health agency frameworks:ARS regional purchasing structures present entry points for specialized urology device vendors targeting specific administrative regions.
- Single-use endoscope substitution:Cross-contamination risk mitigation priorities in outpatient settings are opening adoption pathways for disposable cystoscopy platforms.
Industry Challenges
- Optical engineer talent scarcity:Specialized expertise in rigid endoscope design remains concentrated among aging workforces in Tuttlingen-area manufacturing clusters.
- Legacy system integration friction:New digital imaging platforms face interoperability barriers with installed base tower configurations in mature European hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Urology Devices Market |
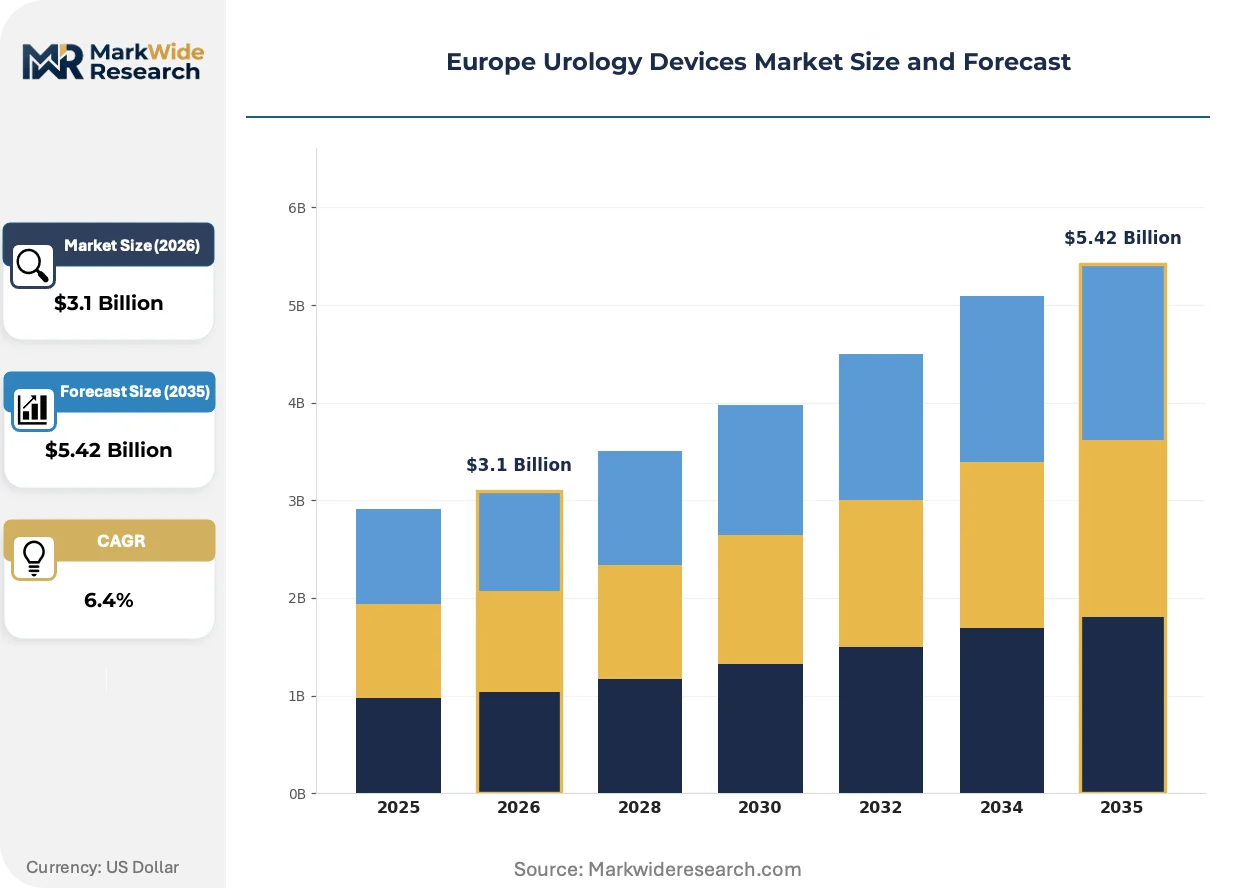
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Endoscopes, Catheters, Surgical Instruments, Imaging Systems Application: Kidney Stones, Prostate Cancer, Urinary Incontinence, Benign Prostatic Hyperplasia Delivery Mode: Hospital, Ambulatory Surgical Center, Home Care, Specialty Clinics End User: Urologists, General Surgeons, Oncologists, Healthcare Facilities |
| Companies Covered | B. Braun Melsungen AG, Richard Wolf GmbH, Boston Scientific Corporation, Medtronic PLC, KARL STORZ SE & Co. KG, Coloplast A/S, Olympus Corporation, Stryker Corporation, Fresenius Medical Care AG & Co. KGaA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Urology Devices Market Shifts & Advancements
Digital imaging integration and single-use platform proliferation are restructuring capital allocation patterns across European urology device procurement.
Thulium fiber laser technology is electrifying benign prostatic hyperplasia treatment workflows by enabling precise tissue vaporization with reduced thermal spread. German university hospitals are piloting these systems at accelerated replacement cycles compared to conventional holmium platforms. The technology is electrifying competitive positioning for vendors able to bundle laser sources with integrated resectoscope systems.
EU MDR Article 61 clinical evidence requirements are extending notified body review timelines for implantable urological devices by mandating prospective data collection. Manufacturers are restructuring regulatory affairs functions to manage parallel submissions across multiple member state competent authorities. Active implantable segments including sacral neuromodulation systems face the most pronounced compliance burden recalibration.
Hospital procurement departments are consolidating cystoscopy service contracts under single-source agreements that bundle capital equipment, maintenance, and disposable supply. Traditional distributor networks are losing access as direct manufacturer relationships with procurement consortia displace intermediaries. This pattern is most visible in Germany's university hospital procurement networks and France's AP-HP central purchasing structure.
Europe Urology Devices Market Segmentation
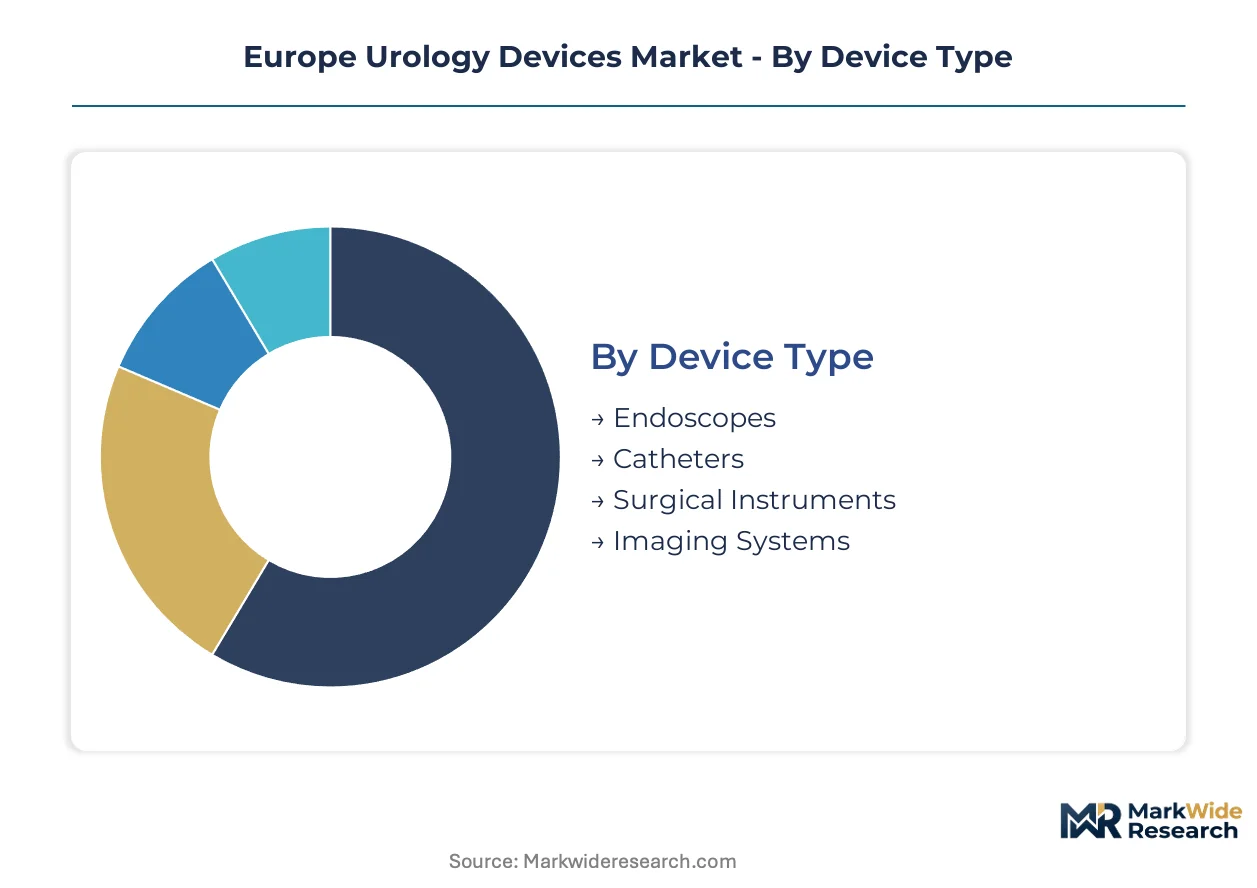
Procurement patterns across European urology diverge sharply by clinical setting and reimbursement pathway. Device specifications must align with divergent capital cycles in German university hospitals versus French ambulatory networks.
Device Type:
Capital intensity and replacement frequency drive purchasing committee priorities across European health systems.
- Endoscopes:Rigid and flexible fiber-optic assemblies with sterilization compatibility per ISO 10993. German hospital procurement networks concentrate demand for tower-integrated configurations with digital imaging interfaces.
- Catheters:Medical-grade polymer drainage and access devices manufactured in high-volume extrusion facilities. REACH phthalate restrictions are forcing material transitions toward TPE alternatives in French and German supply contracts.
- Surgical Instruments:Resectoscopes, forceps, and lithotripters for stone and tissue procedures. Standardization through group purchasing organizations compresses margin recovery in disposable instrument kits.
- Imaging Systems:C-arm fluoroscopy and ultrasound platforms for intraoperative guidance. Capital allocation cycles extend replacement timelines beyond seven years in most European public hospital systems.
Volume sits with catheters; growth tilts toward endoscopes.
Application:
Procedure reimbursement rates and clinical outcome data shape technology adoption velocity across member states.
- Kidney Stones:Lithotripsy and ureteroscopic extraction workflows dominate ambulatory surgical center investment in Germany and France. Minimally invasive stone management reduces inpatient bed utilization and aligns with DRG optimization priorities.
- Prostate Cancer:Robotic-assisted radical prostatectomy and focal therapy platforms command premium positioning. EU MDR clinical evidence requirements extend notified body review timelines for novel ablation technologies.
- Urinary Incontinence:Sling systems and artificial urinary sphincters for stress incontinence correction. Sacral neuromodulation implantables face heightened post-market surveillance obligations under MDR Article 61.
- Benign Prostatic Hyperplasia:Thulium fiber laser vaporization and waterjet ablation systems displace conventional transurethral resection. German university hospitals pilot accelerated replacement cycles for integrated laser-resectoscope platforms.
Prostate cancer commands premium pricing; kidney stone procedures expand most quickly.
Delivery Mode:
Reimbursement pathway differentiation creates divergent device specification requirements across care settings.
- Hospital:Integrated capital equipment and disposable supply contracts dominate procurement in Germany's university hospital networks and France's AP-HP structure. Single-source agreements bundle endoscope towers, maintenance, and consumables.
- Ambulatory Surgical Center:German and French outpatient facilities accelerate deployment of compact lithotripsy systems with reduced footprint. Cross-contamination risk mitigation priorities open adoption pathways for single-use cystoscopy platforms.
- Home Care:Intermittent catheterization supplies and drainage bag systems for chronic urinary management. Standardization through regional health agency frameworks in France constrains supplier selection.
- Specialty Clinics:Diagnostic cystoscopy and urodynamic assessment equipment for private urology practices. Equipment leasing structures predominate given capital constraints outside hospital procurement networks.
Hospitals anchor installed base; ambulatory surgical centers climb the fastest.
End User:
Specialization depth and procedure volume determine device feature prioritization and purchasing authority.
- Urologists:Subspecialty-trained practitioners in stone, oncology, or functional urology drive specification for advanced endoscopic and laser platforms. Direct manufacturer relationships displace traditional distributor networks in high-volume accounts.
- General Surgeons:Emergency stone extraction and catheter placement procedures in smaller hospitals. Standardized instrument kits with reduced configuration options dominate purchasing.
- Oncologists:Multidisciplinary tumor board participation influences prostate cancer staging and treatment device selection. Integration with radiology and pathology workflows shapes imaging platform requirements.
- Healthcare Facilities:Central procurement departments consolidate specifications across clinical specialties. Germany's centralized hospital procurement networks standardize endoscope-tower configurations through multi-site volume commitments.
Healthcare facilities control purchasing authority; urologists drive technology specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates urology device manufacturing capacity while France and the United Kingdom absorb the majority of regional consumption. Tuttlingen anchors optical instrument production. Procurement centralization in German hospital networks and French regional health agencies shapes cross-border trade patterns.
Germany
University hospital procurement networks drive demand for integrated endoscope-tower configurations with digital imaging interfaces. BfArM enforces national vigilance reporting that affects product liability exposure and recall protocols. Tuttlingen manufacturing clusters house specialized rigid endoscope production facilities facing optical engineer talent scarcity.
France
ARS regional purchasing structures present entry points for specialized vendors targeting specific administrative regions with lithotripsy systems. ANSM vigilance requirements parallel BfArM standards while applying divergent cost-effectiveness thresholds to innovative interventions. Paris-based AP-HP central purchasing structure bundles capital equipment and disposable supply contracts.
United Kingdom
NHS procurement frameworks standardize catheter specifications through national tenders that compress supplier margins. MHRA post-Brexit regulatory divergence creates parallel compliance pathways for implantable devices. London teaching hospitals pilot robotic-laser platform convergence for benign prostatic hyperplasia procedures.
Italy
Regional health authority fragmentation slows centralized procurement adoption compared to northern European counterparts. AIFA reimbursement assessments influence technology adoption velocity for novel ablation platforms. Lombardy hospital networks concentrate demand for minimally invasive stone management workflows.
Netherlands
Academic medical center consortia standardize endoscope specifications across multi-site agreements that displace traditional distributor networks. Health and Youth Care Inspectorate oversight aligns with EU MDR implementation timelines. Randstad procurement clusters concentrate purchasing authority for imaging system replacements.
Europe Urology Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology vectors in European urology devices. Consolidation characterizes capital equipment segments where tower-integrated systems require substantial R&D investment, while catheter manufacturing exhibits fragmentation among polymer extrusion specialists. Three archetypes dominate: diversified medical technology conglomerates with broad surgical portfolios, specialized endoscope manufacturers anchored in German industrial clusters, and disposable catheter suppliers competing on material compliance and volume scale. M&A activity concentrates on laser platform capabilities and single-use endoscope technologies, while strategic partnerships between equipment vendors and procurement consortia displace traditional distribution channels.
Among diversified medical technology conglomerates, Medtronic PLC and Boston Scientific Corporation occupy positions spanning implantable and capital equipment segments. KARL STORZ SE & Co. KG exemplifies the specialized optical instrument archetype rooted in German manufacturing heritage. B. Braun Melsungen AG represents integrated catheter and surgical instrument positioning across acute and chronic care settings.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Richard Wolf GmbH |
| Boston Scientific Corporation |
| Medtronic PLC |
| KARL STORZ SE & Co. KG |
| Coloplast A/S |
| Olympus Corporation |
| Stryker Corporation |
| Fresenius Medical Care AG & Co. KGaA |
| Others |
Supply & Pricing Matrix
Germany's centralized hospital procurement networks are consolidating endoscope-tower specifications into multi-site volume commitments, forcing manufacturers to absorb cost-down pressure through standardized configurations while sacrificing customization premiums. This procurement concentration compresses supplier margins across rigid endoscope and integrated imaging system categories.
Pricing Analysis
Margin tightening in catheter manufacturing reflects REACH phthalate compliance costs and group purchasing organization standardization across French and German supply contracts. Three-tier pricing structure across premium digital endoscopes, standard fiber-optic configurations, and economy single-use platforms separates vendors by optical technology generation and after-sales service bundling. Cost-down pressure on disposable instrument kits accelerates because ambulatory surgical centers prioritize compact lithotripsy systems with reduced capital footprints. Healthcare facilities control purchasing authority and exhibit highest price sensitivity; subspecialty urologists driving laser platform specification show lowest sensitivity to capital equipment premiums.
Supply Chain Analysis
Refurbishment flows for rigid endoscope optical assemblies concentrate in Tuttlingen-area service facilities, extending asset lifecycles and displacing new unit demand in German hospital networks. Manufacturing draws from specialized fiber-optic suppliers in southern Germany, polymer extrusion facilities in Ireland and the Netherlands, and precision stainless alloy forgers in Italy. Single-source vulnerability in optical component supply creates exposure to component shortages from aging engineering workforces. Distribution runs through direct manufacturer relationships with procurement consortia, displacing traditional distributor networks in university hospital and AP-HP central purchasing structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evidence requirements are compressing time-to-market for implantable urological devices, forcing capital-constrained players toward exit or acquisition while rewarding diversified conglomerates with regulatory affairs scale.
For Market Incumbents: Lock in ambulatory surgical center procurement relationships through single-source agreements bundling capital equipment, maintenance, and disposable supply before new entrants establish laser platform footholds. Deepen backward integration into polymer extrusion for phthalate-free catheter materials to capture REACH compliance premiums and defend margin position against group purchasing organization consolidation. For New Entrants and Emerging Players: The gap between premium robotic-laser platforms and economy single-use cystoscopy systems offers entry points for compact lithotripsy vendors targeting French ARS regional purchasing structures. Target German university hospital pilot programs for thulium fiber laser vaporization systems, where accelerated replacement cycles create technology substitution windows. Pursue direct procurement consortia relationships rather than distributor channel builds to bypass entrenched intermediary networks. For Investors and Strategic Acquirers: The window for entry favors specialized endoscope manufacturers with optical engineering capabilities in Tuttlingen-area clusters, where talent scarcity creates defensive moats. Acquire targets demonstrating EU MDR notified body relationships and parallel submission experience across BfArM and ANSM jurisdictions. Monitor MDR Article 61 post-market surveillance compliance cost inflation as early signal for distressed asset availability among implantable device specialists.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body relationships compress time-to-market for novel implantable urological technologies. |
| Hospital System Partnership | Direct procurement consortia relationships with Germany's university hospital networks displace distributor intermediaries. |
| Software Companion Development | Digital imaging integration with existing tower configurations reduces legacy system replacement friction. |
| Reimbursement Strategy | Alignment with France's HAS and Germany's IQWiG cost-effectiveness thresholds accelerates regional adoption velocity. |
| Backward Integration | In-house polymer extrusion for phthalate-free catheter materials captures REACH compliance premiums and supply security. |
Research Methodology
Document review covered EU MDR implementation guidance, BfArM vigilance reports, ANSM market surveillance data, and hospital procurement database records, complemented by interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and urology department heads. Secondary validation drew from notified body technical documentation, REACH compliance filings, and trade association production statistics. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to reconcile volume projections.
Segmentation outputs across device type, application, delivery mode, and end user dimensions were generated through the projection horizon, with CAGRs derived from historical replacement cycle analysis and procurement pipeline visibility. Thulium fiber laser adoption curves, ambulatory surgical center capital deployment rates, and MDR transition timeline impacts served as industry-specific forecast inputs.
Inputs from hospital procurement databases and notified body submission trackers were available through the study window; gaps in real-time ambulatory surgical center equipment deployment data introduce uncertainty bands around outpatient segment growth trajectories. Forecasts reflect assumptions regarding MDR implementation consistency across member state competent authorities and REACH phthalate restriction enforcement timelines. Practitioners should monitor BfArM and ANSM vigilance reporting patterns for early signals of implantable device recall activity that could reshape competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
LAMEA Transrectal Ultrasound Market
Urology
Global Bladder Cancer Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Cystectomy Market
Urology
Ureterorenoscopes Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Genitourinary Cancers Treatment Market
Urology
Uropathy Treatment Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Global Prostate Health Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Disposable Ureteroscope Market
Urology
Ureteral Obstruction Market
Urology
Urinary Bag Market