
 Virus Filtration Market | 2026-2036
Virus Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Virus Filtration Market Analysis
Germany's Rhine-Main biotech corridor is rewriting regional supply dynamics for viral clearance solutions. Merck KGaA leverages its integrated filtration portfolio to anchor European bioprocessing demand. Danaher Corporation sustains competitive pressure through broad life sciences instrumentation reach. Sartorius AG specializes in single-use filtration systems that dominate contract manufacturing workflows.
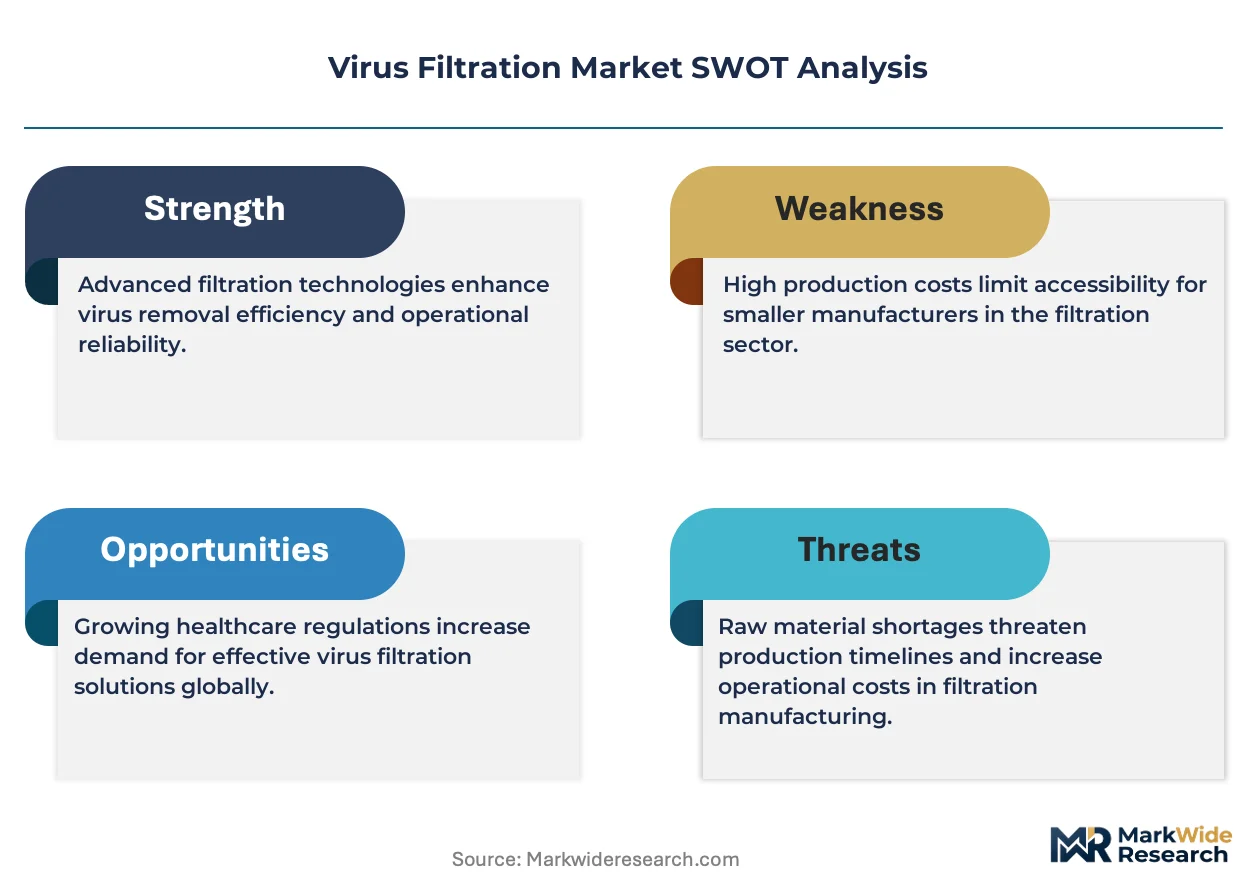
Virus filtration encompasses membrane-based and adsorptive technologies designed to remove or retain viral particles down to 20 nanometers, employing polyethersulfone or regenerated cellulose matrices in dead-end or tangential-flow configurations. The primary purpose centers on ensuring viral safety in parenteral biologics, plasma derivatives, and vaccine manufacturing streams. Filters and membranes command the largest product share due to recurring replacement cycles in validated bioprocesses, while nanofiltration technology captures the fastest expansion trajectory as gene therapy vectors and mRNA platforms demand finer retention capabilities. Biopharmaceuticals application generates the dominant value pool, though water treatment and medical device reprocessing segments are widening addressable scope.
FDA guidance on viral safety evaluation and the EU MDR framework collectively mandate demonstrable log reduction values and filter integrity testing protocols, directly shaping product development roadmaps and qualification timelines. ISO 13485 quality management standards and WHO TRS 941 viral safety recommendations further harmonize international compliance expectations for manufacturers and end users. Stakeholders must monitor evolving regulatory divergence between FDA process validation requirements and EMA's evolving stance on continuous manufacturing viral clearance claims.
Market Dynamics
Gene therapy manufacturing is forcing step-change improvements in nanofiltration retention capabilities, as adeno-associated virus vectors and lipid nanoparticles demand pore size precision below 20 nanometers that legacy membrane chemistries cannot reliably deliver.
Growth Catalysts
- FDA viral safety guidance:Updated process validation requirements for biotechnology products mandate demonstrable log reduction values, compelling biopharmaceutical manufacturers to upgrade filtration trains and validate new membrane formats.
- Single-use adoption:Contract development and manufacturing organizations are standardizing disposable filtration systems to reduce cross-contamination risk and accelerate batch turnaround in multi-product facilities.
- Rhine-Main biotech cluster:Concentrated capacity expansion by German contract manufacturers is pulling regional supply of high-performance polyethersulfone membranes and integrity testing instrumentation.
Market Restraints
- Regenerated cellulose supply concentration:Raw material production for this preferred hydrophilic membrane matrix clusters among a limited set of European chemical suppliers, exposing filter manufacturers to input volatility.
- EU MDR reprocessing validation:Medical device filtration systems face extended qualification timelines under the Medical Device Regulation framework, delaying commercialization of multi-use hospital filtration equipment.
- Tangential-flow system cost structure:Capital equipment and consumable requirements for continuous processing configurations price out smaller plasma fractionators and emerging market vaccine producers.
Strategic Opportunities
- mRNA platform expansion:Lipid nanoparticle manufacturing for self-amplifying RNA vaccines creates demand for novel charged membrane surfaces that selectively retain viral contaminants without nucleic acid product loss.
- Continuous manufacturing regulatory pathway:EMA's evolving stance on integrated viral clearance claims offers first-mover advantage to suppliers with validated inline nanofiltration skids for perfusion bioreactor operations.
- Water treatment vector control:Municipal and industrial water systems are adopting virus-retentive membranes for enteric pathogen management, extending addressable scope beyond pharmaceutical applications.
Industry Challenges
- Filter integrity testing skill gap:Diffusion and bubble-point test execution requires specialized operators; contract manufacturing workforce shortages delay validation protocols and release timelines.
- Legacy stainless steel integration:Hybrid facilities struggle to retrofit single-use filtration manifolds into existing cleanroom infrastructure designed for reusable hardware and steam-in-place sterilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virus Filtration Market |
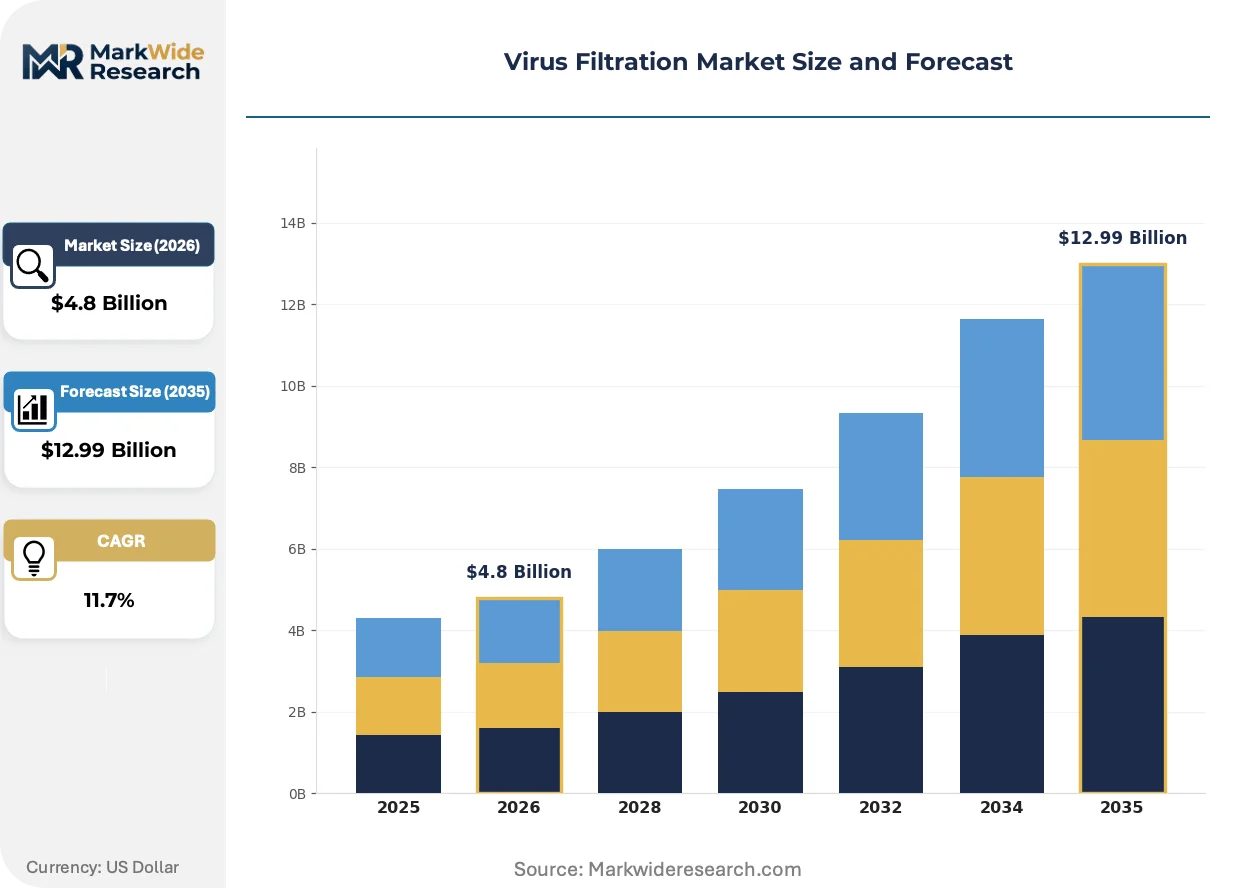
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filters, Membranes, Adsorbents, Consumables Application: Biopharmaceuticals, Water Treatment, Medical Devices, Food & Beverages End User: Pharmaceutical Companies, Research Laboratories, Hospitals, Contract Manufacturers Technology: Ultrafiltration, Microfiltration, Nanofiltration, Cross-flow Filtration |
| Companies Covered | Merck KGaA, Danaher Corporation, Sartorius AG, Thermo Fisher Scientific, Asahi Kasei Medical, GE Healthcare, Charles River Laboratories, Lonza Group, Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virus Filtration Market Emerging Trajectories
Membrane surface chemistry and process analytical technology are converging to enable real-time viral clearance verification, eliminating the batch-release bottlenecks that constrain continuous bioprocessing adoption.
Multimodal membrane technology is hybridizing charged and size-exclusion mechanisms into single-layer formats. Gene therapy vector manufacturers are adopting these surfaces to achieve simultaneous DNA, host cell protein, and viral impurity clearance. This convergence is compressing the number of downstream unit operations required for recombinant adeno-associated virus production.
EMA's draft guideline on viral safety for advanced therapy medicinal products is tightening documentation requirements for filtration train validation. Biopharmaceutical sponsors must now demonstrate robustness across worst-case feed stream conditions. European contract manufacturers are responding by investing in automated integrity testing platforms with electronic batch record integration.
Biopharmaceutical procurement teams are consolidating filtration spend under preferred supplier agreements with technical service bundling. Large molecule developers are displacing transactional catalog purchasing with multi-year framework contracts covering membrane supply, validation support, and on-site technical training. This concentration is most visible among North American monoclonal antibody producers with established CDMO partnerships.
Virus Filtration Market Segmentation
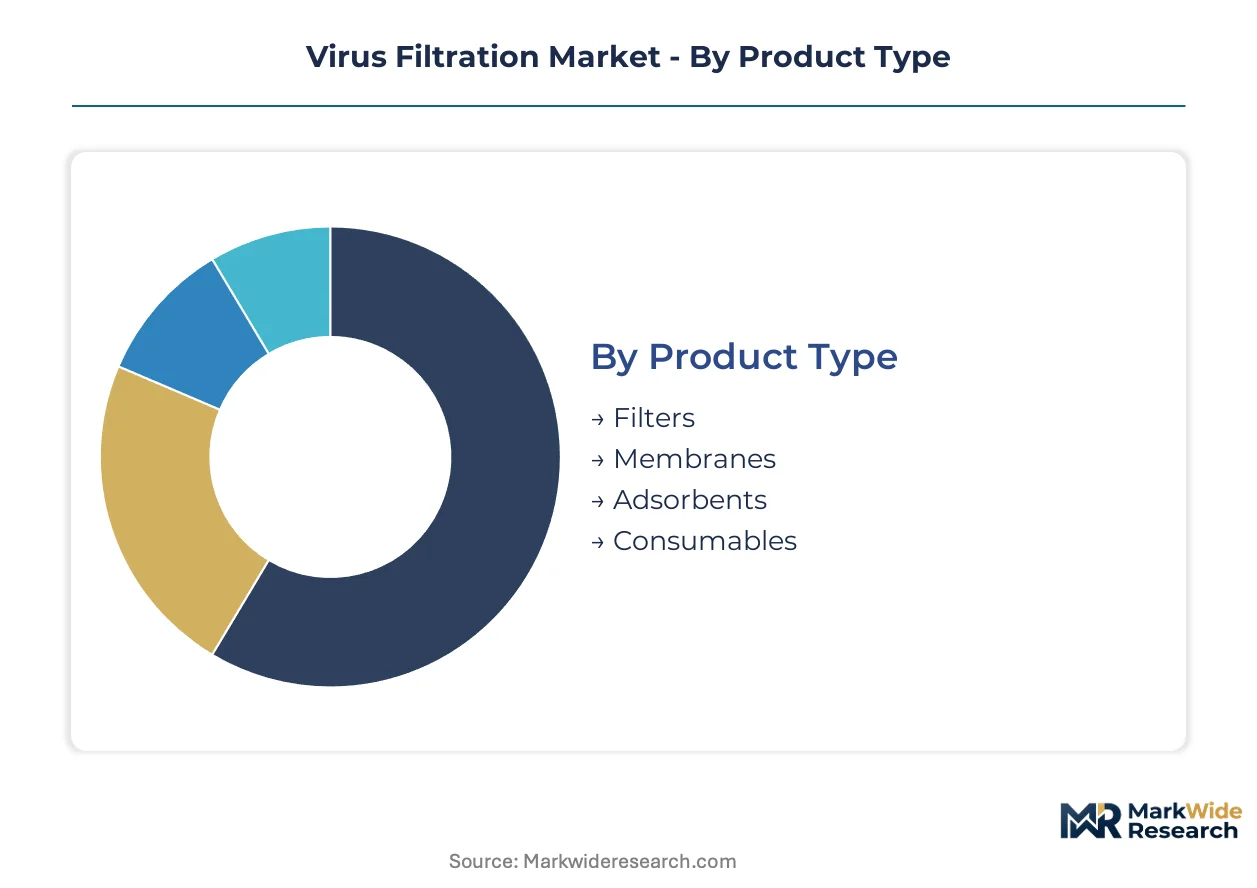
Virus filtration segmentation reveals divergent service intensity across product categories. Validation support, membrane replacement scheduling, and integrity testing calibration create sticky supplier relationships that lock in recurring revenue streams.
Product Type:
After-sales service intensity varies sharply across product categories, with validation protocols and replacement cycles driving supplier stickiness.
- Filters:Cartridge and capsule formats in polyethersulfone or polyvinylidene fluoride housings deliver dead-end retention for batch bioprocessing. Demand concentrates among monoclonal antibody producers in Massachusetts and Bavaria, where FDA and EU MDR compliance mandates drive quarterly replacement cycles and on-site technical support contracts.
- Membranes:Flat-sheet and hollow-fiber configurations in regenerated cellulose or polyethersulfone matrices form the retentive barrier in tangential-flow systems. Germany's Rhine-Main CDMO cluster pulls regional supply of high-performance formats requiring membrane integrity testing instrumentation and operator training bundles.
- Adsorbents:Charged surface media for selective viral capture in mixed-mode clearance trains.
- Consumables:Single-use tubing, connectors, and buffer solutions for disposable filtration manifolds.
By volume, Filters leads. By growth pace, Membranes is ahead.
Application:
Cost tier stratification separates validated pharmaceutical-grade systems from industrial and medical device segments with lighter compliance burdens.
- Biopharmaceuticals:Viral clearance for monoclonal antibodies, plasma derivatives, and recombinant proteins demands demonstrable log reduction values under FDA process validation guidance. Massachusetts and North Carolina biotech corridors anchor procurement concentration for multi-year framework contracts bundling membrane supply with validation support.
- Water Treatment:Municipal and industrial systems deploy virus-retentive membranes for enteric pathogen management. European utilities under EU Drinking Water Directive pressure are adopting nanofiltration for adenovirus and norovirus control in surface water reuse schemes.
- Medical Devices:Reprocessing filtration for endoscopes and surgical instruments faces extended EU MDR qualification timelines.
- Food & Beverages:Beverage clarification and dairy pathogen control using microfiltration skids.
By installed base, Biopharmaceuticals dominates. By expansion trajectory, Water Treatment is climbing fastest.
End User:
Customer type determines procurement sophistication, with large pharmaceutical developers displacing transactional purchasing through technical service bundling.
- Pharmaceutical Companies:In-house bioprocessing operations for commercial monoclonal antibody and plasma fractionation facilities. North American large molecule developers are consolidating filtration spend under preferred supplier agreements covering membrane supply, validation protocols, and on-site training.
- Contract Manufacturers:CDMOs standardize disposable filtration systems to reduce cross-contamination risk and accelerate batch turnaround in multi-product facilities. Germany's Rhine-Main cluster is expanding capacity with single-use manifold adoption.
- Research Laboratories:Process development and early-stage viral clearance studies using bench-scale filtration skids.
- Hospitals:Point-of-use water filtration and medical device reprocessing systems.
By procurement volume, Pharmaceutical Companies lead. By adoption velocity, Contract Manufacturers is gaining share fastest.
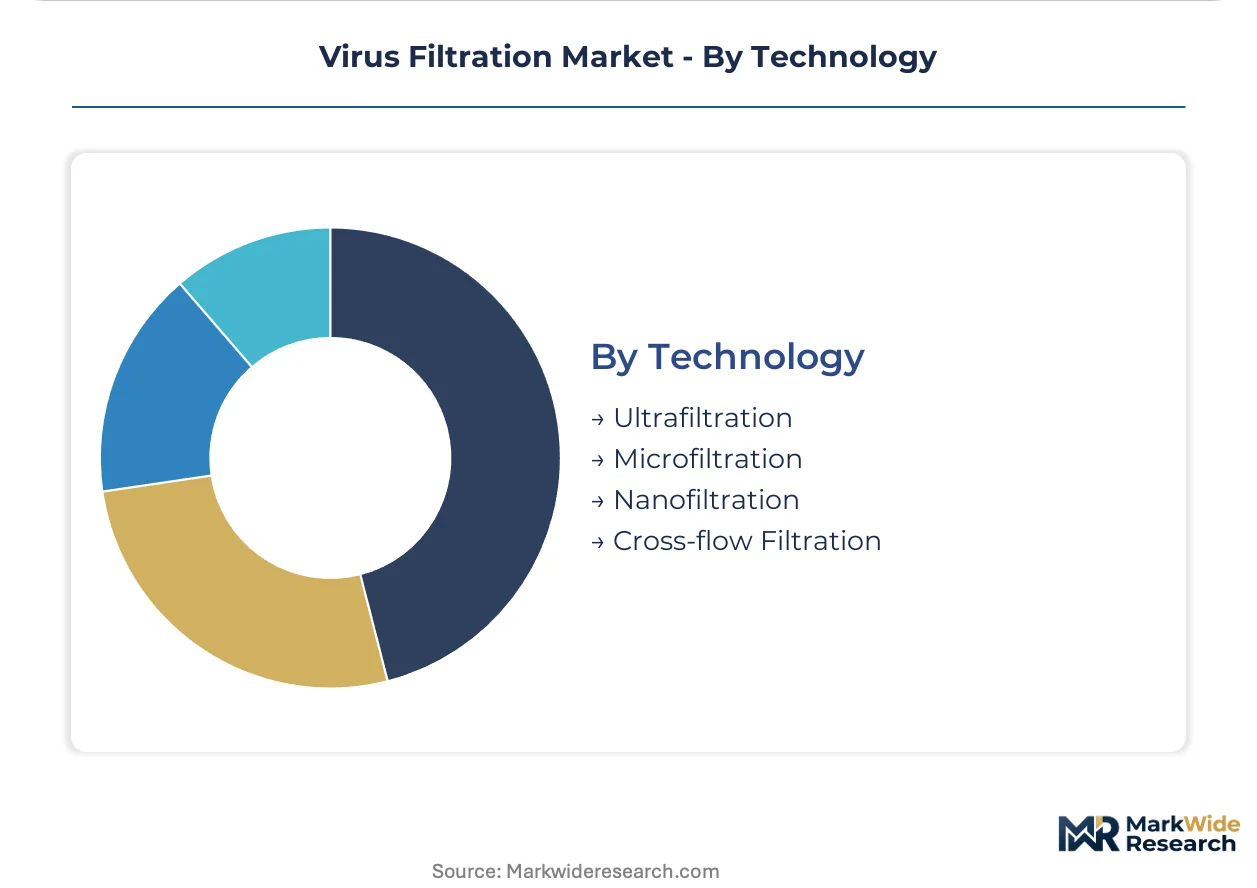
Technology:
Retention precision requirements separate mature microfiltration from nanofiltration's steepest capability demands.
- Nanofiltration:Pore size precision below 20 nanometers retains viral particles while permitting protein or nucleic acid passage. Gene therapy vector manufacturers in Pennsylvania and Maryland are adopting these systems for adeno-associated virus and lipid nanoparticle processing where legacy chemistries fail.
- Ultrafiltration:Molecular weight cut-off-based separation for protein concentration and buffer exchange upstream of viral clearance. Massachusetts bioprocessing facilities deploy these in tandem with nanofiltration for integrated downstream trains.
- Microfiltration:Larger pore removal of bacteria and cellular debris as pretreatment.
- Cross-flow Filtration:Tangential-flow configurations for continuous processing and reduced membrane fouling.
By deployment scale, Ultrafiltration leads. By capability investment, Nanofiltration is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyethersulfone membrane manufacturing clusters in Germany and Switzerland supply filtration trains across the European biopharmaceutical corridor. FDA process validation mandates in the United States and EMA viral safety guidelines in Europe shape divergent qualification timelines for filter suppliers.
United States
Massachusetts and North Carolina biotech corridors drive demand for single-use nanofiltration systems in monoclonal antibody manufacturing. FDA updated guidance on viral safety evaluation for biotechnology products mandates demonstrable log reduction values and integrity testing protocols. Greater Boston contract manufacturers are expanding capacity with disposable manifold adoption to accelerate batch turnaround.
Germany
The Rhine-Main biotech cluster anchors European demand for high-performance tangential-flow filtration systems in viral clearance operations. EU MDR framework for medical device reprocessing tightens filtration performance standards and extends qualification timelines. Hesse-based contract development organizations are scaling polyethersulfone membrane consumption for multi-product bioprocessing facilities.
Switzerland
Swissmedic oversight of advanced therapy medicinal products drives precision requirements for gene therapy vector filtration below 20 nanometers. The country's pharmaceutical regulator harmonizes viral clearance documentation with EMA draft guidelines on worst-case feed stream validation. Basel-area bioprocessing facilities are investing in automated integrity testing platforms with electronic batch record integration.
Japan
PMDA viral safety standards for plasma derivatives and recombinant proteins sustain demand for regenerated cellulose membrane formats. METI industrial policy supports domestic filtration technology development to reduce import dependence for critical bioprocessing materials. Kanto region biomanufacturers are adopting nanofiltration skids for continuous processing in perfusion bioreactor operations.
China
NMPA biologics approval pathways for biosimilars and gene therapies expand addressable scope for viral clearance solutions. The national pharmaceutical regulator aligns viral safety evaluation with WHO TRS 941 recommendations for international market access. Yangtze River Delta contract manufacturers are building single-use filtration capacity to serve domestic and export monoclonal antibody production.
Virus Filtration Market Vendor Landscape
Integrated filtration portfolio providers and specialized single-use system suppliers split the market into distinct competitive spheres. Concentration remains moderate with established life sciences conglomerates holding membrane chemistry advantages while mid-scale specialists capture contract manufacturing workflow standardization. Two strategic archetypes dominate: diversified healthcare conglomerates leveraging broad instrumentation reach, and focused bioprocessing specialists anchoring regional supply clusters. Competitive moves center on multi-year framework contracts bundling technical services and preferred supplier agreements consolidating procurement spend.
Among diversified healthcare conglomerates, Merck KGaA and Danaher Corporation exemplify the integrated portfolio archetype through their life sciences and diagnostics divisions. Sartorius AG occupies a specialist position within the German Rhine-Main bioprocessing corridor, representing the focused single-use filtration system provider model. These three entities anchor the competitive structure by demonstrating how geographic proximity to major biomanufacturing clusters shapes supplier positioning and customer relationship intensity.
| Leading Market Players |
|---|
| Merck KGaA |
| Danaher Corporation |
| Sartorius AG |
| Thermo Fisher Scientific |
| Asahi Kasei Medical |
| GE Healthcare |
| Charles River Laboratories |
| Lonza Group |
| Pall Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in regenerated cellulose membrane production across German chemical suppliers is tightening supplier pricing power while forcing biopharmaceutical buyers into multi-year offtake commitments. This utilization squeeze propagates through the value chain, elevating input costs for polyethersulfone filter manufacturers and compressing margins for smaller plasma fractionators unable to secure volume-backed contracts.
Pricing Analysis
FDA process validation guidance dictates the pricing tier structure across the virus filtration market, separating premium-grade membranes with complete validation documentation from standard formats with abbreviated qualification support. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and after-sales service bundling. Cost compression in standard-tier cartridge formats is intensifying because contract manufacturers are consolidating procurement spend under framework agreements. Emerging market vaccine producers exhibit the highest price sensitivity, while gene therapy developers in Pennsylvania and Maryland demonstrate the lowest due to vector purity requirements.
Supply Chain Analysis
Contract manufacturing concentration among Germany's Rhine-Main CDMO cluster and Massachusetts-based bioprocessors anchors regional demand pull for high-performance filtration systems. Supply chains draw from polyethersulfone resin production in Germany, regenerated cellulose matrix manufacturing in Switzerland, and hollow-fiber spinning operations in Japan. Single-source vulnerability in European chemical suppliers for hydrophilic membrane matrices exposes filter manufacturers to input volatility. Distribution runs through direct technical service relationships with large pharmaceutical developers and group purchasing organizations serving hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virus filtration is approaching a platform-economics inflection as automated integrity testing platforms with electronic batch record integration create interoperability standards that lock in supplier ecosystems. This shift favors incumbents with validated inline skids and disadvantages point-solution providers lacking continuous manufacturing regulatory alignment.
For Market Incumbents: Pre-empt emerging entrant challenges by deepening backward integration into regenerated cellulose matrix production to secure input supply against European chemical supplier concentration. Anchor capacity expansion in the Rhine-Main corridor to capture CDMO workflow standardization, while investing in multimodal membrane R&D to defend against substitute technologies for gene therapy vector clearance.
For New Entrants and Emerging Players: Establish a beachhead in water treatment vector control applications where regulatory compliance burdens remain lighter than pharmaceutical-grade requirements. Target European utilities under EU Drinking Water Directive pressure with nanofiltration skids for enteric pathogen management. Lead with outcome-based service models that bundle membrane supply with integrity testing calibration to differentiate from transactional catalog competitors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among membrane manufacturers with validation support contracts and scheduled replacement programs. Long-term viability centers on suppliers with demonstrated regulatory navigation across FDA and EMA frameworks. Acquisition candidates should demonstrate automated integrity testing platform deployment. Monitor EMA draft guideline finalization on advanced therapy medicinal products as the signal for continuous manufacturing viral clearance claim inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Integrity Testing Platform Deployment | Electronic batch record integration accelerates CDMO validation timelines and locks in preferred supplier status. |
| Multimodal Membrane R&D Investment | Hybrid charged-size-exclusion surfaces compress downstream unit operations for adeno-associated virus production. |
| Backward Integration into Regenerated Cellulose | In-house matrix production mitigates European chemical supplier concentration risk. |
| Water Treatment Vector Control Expansion | Municipal nanofiltration adoption for enteric pathogen management extends addressable scope beyond biopharmaceuticals. |
| Continuous Manufacturing Regulatory Alignment | EMA evolving stance on integrated viral clearance claims offers first-mover advantage for perfusion bioreactor operations. |
Methodological Framework
The analysis maps membrane-based filtration, adsorptive technologies, integrity testing instrumentation, and validation services, each validated through bioprocess engineers, regulatory affairs specialists, CDMO procurement directors, and filtration system operators. Primary interviews with these stakeholders combined with secondary validation from FDA guidance documents, EMA submissions, ISO 13485 certification records, and WHO TRS 941 technical reports. Bottom-up membrane consumption modeling and top-down biopharmaceutical capital expenditure triangulation anchored volume estimates.
Assumptions held fixed include regulatory framework stability across FDA and EMA jurisdictions, while membrane chemistry innovation rates and contract manufacturing capacity expansion trajectories were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, application, end user, and technology, with additional stratification by regional regulatory cluster. CAGRs were derived from installed base growth and replacement cycle analysis, incorporating gene therapy manufacturing expansion and mRNA platform adoption as industry-specific demand drivers.
Sensitivities concentrate around EMA guideline finalization timelines, raw material supply disruptions from European chemical suppliers, and workforce availability for filter integrity testing execution. Forecasts reflect these assumptions with explicit scenario boundaries. Quarterly review of CDMO capacity announcements, regulatory submission trends, and membrane chemistry patent filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Ear Infection Treatment Market
Infection Control
Disinfection Cupboard Market
Infection Control
Ultraviolet Disinfection Equipment Market
Infection Control
North America Hand Sanitizer Market
Infection Control
Intra-Amniotic Infection Treatment Market
Infection Control
Infection Prevention Market
Infection Control
Global Wall Mounted Ozone Disinfection Machine Market
Infection Control
Denture Disinfectants Market
Infection Control
Biological and Chemical Indicators Market
Infection Control
Antiseptic Bathing Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Salivary Gland Infection Market
Infection Control
Global Disease Control and Prevention Vaccine Market
Infection Control
Disinfection Equipment Market
Infection Control
Sterilization Tunnel Market
Infection Control
Middle East and Africa Hand Sanitizer Market