
 Obstructive Uropathy Treatment Market | 2026-2036
Obstructive Uropathy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Obstructive Uropathy Treatment Market Analytics
Buyer concentration among hospital systems is shifting as ambulatory surgical centers capture a growing share of ureteroscopy and laser lithotripsy procedures. Boston Scientific Corporation leverages its integrated urology portfolio to sustain catheter and stent placements across integrated delivery networks. Cook Medical anchors its position through specialized urological access devices that dominate interventional radiology suites. Coloplast A/S differentiates via hydrophilic-coated intermittent catheters that command premium positioning in home care channels.
Obstructive uropathy treatment encompasses the mechanical, pharmacological, and surgical interventions used to relieve urinary tract obstruction caused by stones, tumors, strictures, or prostatic enlargement, typically involving catheterization, endoscopic instrumentation, or energy-based fragmentation with procedural success measured by restored urine flow and preserved renal function. The primary purpose is to prevent hydronephrosis, recurrent infection, and progressive renal impairment across acute and chronic clinical presentations. Stents and catheters represent the mature volume base where manufacturing scale determines margin capture, while lasers sustain the fastest procedural growth as thulium and holmium platforms displace older electrohydraulic systems in stone fragmentation. Ureteroscopes occupy concentrated margin pools at the premium end, where single-use digital platforms are reshaping capital-versus-consumable economics across hospital and ambulatory settings.
The FDA's 510(k) clearance pathway for urological devices shapes product iteration cycles and competitive entry timelines in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements that filter market access for stent and laser manufacturers seeking CE marking. OSHA bloodborne pathogen standards and Joint Commission surgical safety protocols directly influence single-use instrument adoption and reprocessing economics across hospital end users. Stakeholders must monitor how CMS reimbursement adjustments for outpatient urological procedures redirect site-of-care decisions between hospitals and ambulatory surgical centers.
Market Dynamics
Single-use digital ureteroscopes are compressing reprocessing economics and redistributing capital budgets from hospitals to ambulatory surgical centers, forcing incumbent manufacturers to restructure their revenue models around consumable placement rather than durable equipment sales.
Growth Catalysts
- CMS outpatient reimbursement expansion:Medicare payment adjustments for ambulatory surgical centers accelerate site-of-care migration for ureteroscopy and laser lithotripsy procedures in the United States.
- Holmium laser platforms:Energy-based stone fragmentation systems displace electrohydraulic lithotripsy in hospital operating suites due to superior stone-free rates and reduced retropulsion.
- Aging urological patient pools:Benign prostatic hyperplasia and nephrolithiasis prevalence rises among populations over 65 in Japan, Germany, and the United States, expanding procedural addressable markets.
Market Restraints
- Nitinol raw material concentration:Superelastic alloy supply for ureteral stents concentrates among limited specialty metal processors, creating input cost volatility and qualification bottlenecks.
- EU MDR clinical evidence requirements:Enhanced post-market surveillance and notified body capacity constraints extend CE marking timelines for stent and catheter manufacturers seeking European market access.
- Reusable flexible ureteroscope durability:Repair frequency and maintenance costs for conventional scopes sustain resistance to full single-use conversion among cost-constrained hospital systems.
Strategic Opportunities
- Home intermittent catheterization:Hydrophilic-coated single-use catheters penetrate post-discharge care channels as payors favor reduced urinary tract infection readmission costs.
- Thulium fiber laser adoption:Lower energy threshold and improved fiber durability converge with holmium platform familiarity to expand laser lithotripsy into smaller ambulatory settings.
- India urology infrastructure buildout:Government hospital procurement programs and private chain expansion create catheter and stent volume growth outside mature Western markets.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization study backlogs delay new coating formulations and material substitutions for stent manufacturers.
- Single-use scope waste management:OSHA bloodborne pathogen disposal protocols and EPA medical waste regulations impose operational complexity on ambulatory surgical centers adopting disposable platforms.
- Interoperability with imaging archives:Digital ureteroscope video output standards fragment across DICOM-compliant and proprietary formats, complicating integration with hospital PACS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Obstructive Uropathy Treatment Market |
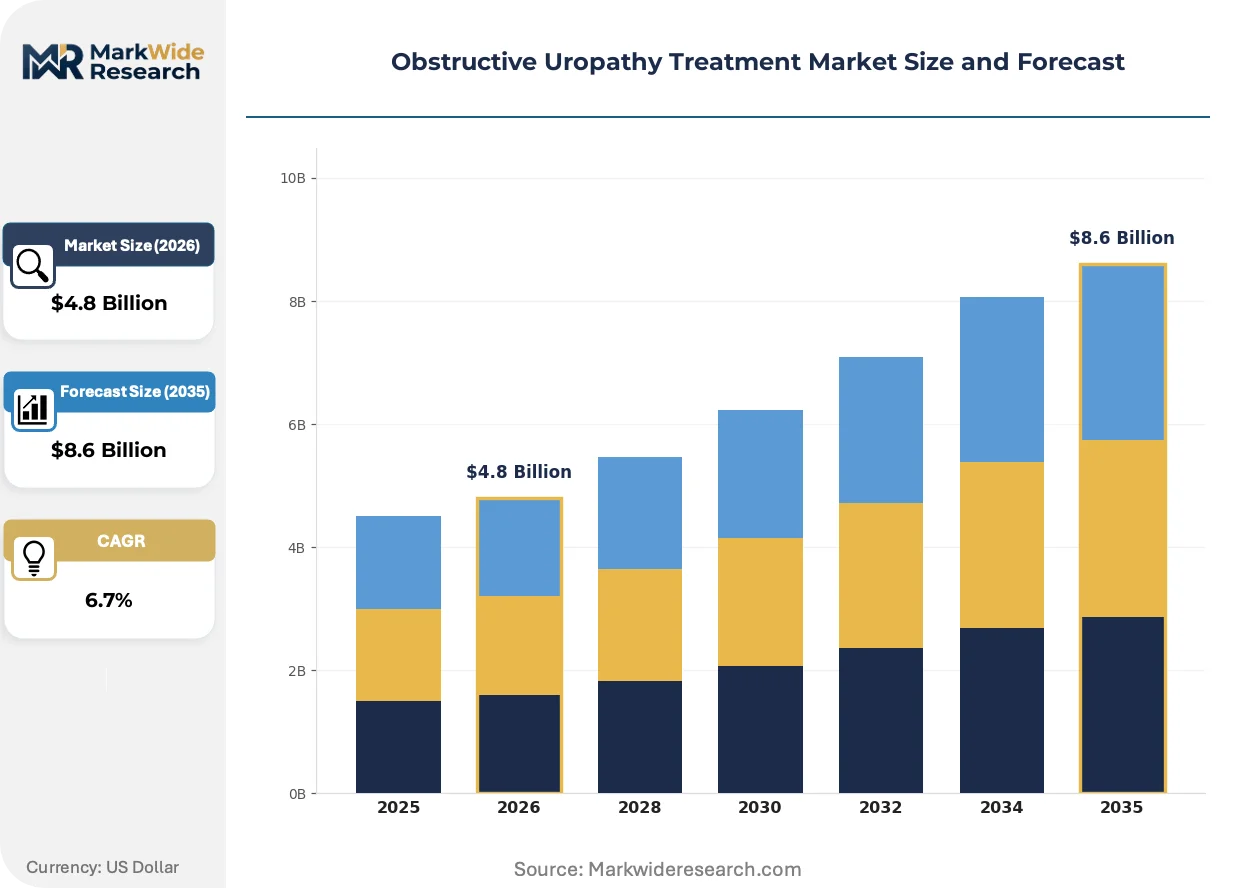
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Catheters, Ureteroscopes, Lasers Indication: Kidney Stones, Tumors, Benign Prostatic Hyperplasia, Strictures End User: Hospitals, Outpatient Clinics, Ambulatory Surgical Centers, Home Care Delivery Mode: Injectable, Oral, Intravenous, Other |
| Companies Covered | Boston Scientific Corporation, Cook Medical, Coloplast A/S, Teleflex Incorporated, B. Braun Melsungen AG, Olympus Corporation, Becton, Dickinson & Co., Merit Medical Systems, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Obstructive Uropathy Treatment Market Evolving Landscape
Disposable instrumentation, enhanced laser energy delivery, and reimbursement-driven site-of-care migration are restructuring capital deployment and procurement patterns across urological intervention markets.
Digital single-use ureteroscopes is integrating high-definition imaging chips with single-patient-use sheaths, eliminating cross-contamination risk and repair logistics. Ambulatory surgical centers in the United States adopt these platforms faster than hospital systems due to lower capital barriers and simplified inventory management. The technology is integrating procedural volume into outpatient settings that previously required hospital-based operating rooms.
EU Medical Device Regulation imposes systematic clinical follow-up requirements for implantable urological devices, compelling manufacturers to maintain post-market surveillance registries. Notified body capacity constraints in Germany and the Netherlands extend certification cycles by twelve to eighteen months for stent and catheter product lines. Mid-tier manufacturers without established European authorized representatives face accelerated market exit or acquisition pressure.
Buyer consolidation among integrated delivery networks concentrates catheter and stent purchasing decisions into centralized procurement committees. Group purchasing organizations in the United States negotiate multi-year sole-source agreements that displace fragmented hospital-level contracting. This concentration is most visible in the southeastern and midwestern United States, where Catholic health systems and for-profit chains dominate regional urological service line planning.
Obstructive Uropathy Treatment Market Segmentation
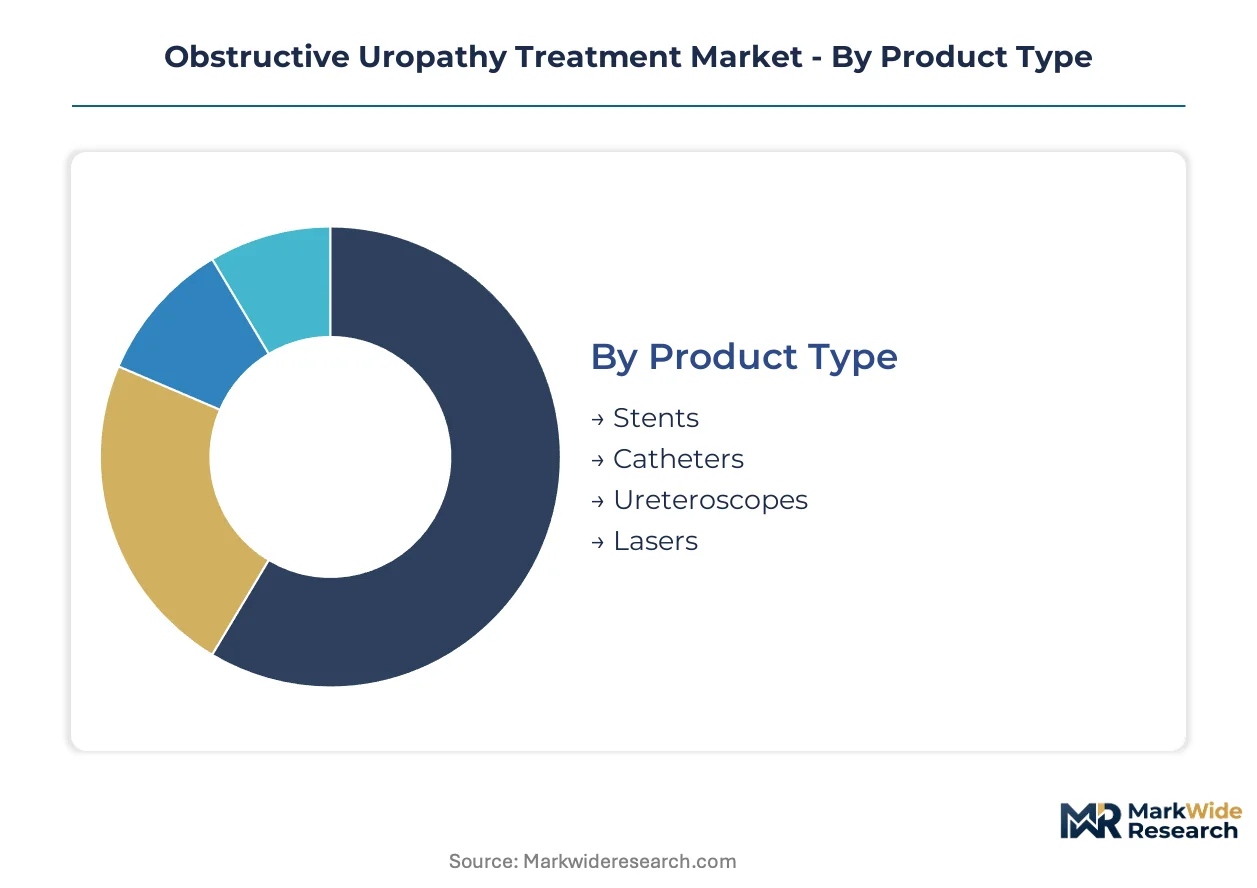
Obstructive uropathy treatment segments along procedural intensity, care setting economics, and device durability requirements. Each axis carries distinct margin profiles and regulatory pathways that shape manufacturer portfolio decisions.
Product Type:
Material composition and reusability specifications define procurement economics across the four device categories.
- Stents:Nitinol superelastic alloys form the structural backbone of double-J and mesh designs, with hydrophilic coatings reducing tissue encrustation during indwelling periods. Demand concentrates in hospital interventional suites across the United States and Germany, where CMS and statutory health insurance reimbursement favor scheduled exchange protocols.
- Catheters:Hydrophilic-coated intermittent and indwelling designs dominate post-operative and chronic obstruction management. Home care channels in Japan and the United States absorb expanding volumes as payors prioritize urinary tract infection reduction over acute readmission costs.
- Ureteroscopes:Single-use digital platforms with integrated high-definition imaging chips eliminate cross-contamination risk and repair logistics for ambulatory surgical centers.
- Lasers:Holmium and thulium fiber systems deliver energy-based stone fragmentation with superior stone-free rates compared to legacy electrohydraulic platforms.
Mature deployment sits with stents and catheters. Newer deployment is concentrated in single-use ureteroscopes.
Indication:
Pathology severity determines acuity tier and reimbursement intensity for intervention selection.
- Kidney Stones:Nephrolithiasis drives the highest procedural volume through ureteroscopy and laser lithotripsy, with recurrence patterns creating repeat intervention demand. Ambulatory surgical centers in the United States capture growing share as CMS outpatient reimbursement expands.
- Benign Prostatic Hyperplasia:Aging male populations across Japan, Germany, and the United States sustain catheter and pharmaceutical intervention growth, with minimally invasive surgical alternatives displacing transurethral resection in earlier disease stages.
- Tumors:Malignant obstruction requires urgent stenting or nephrostomy drainage, with interventional radiology suites managing complex cases.
- Strictures:Iatrogenic and idiopathic ureteral narrowing demands graduated dilation protocols and temporary stenting.
Stone disease commands the highest procedure frequency. Tumor-related obstruction carries the most acute intervention requirements.
End User:
Capital availability and reimbursement differentials redistribute volume across care settings.
- Hospitals:Integrated delivery networks maintain dominance for complex multi-stage procedures and emergency obstruction management, with centralized procurement committees consolidating catheter and stent purchasing decisions.
- Ambulatory Surgical Centers:Lower capital barriers and simplified inventory management accelerate single-use ureteroscope adoption, with CMS outpatient reimbursement adjustments redirecting ureteroscopy volume from hospital operating rooms.
- Outpatient Clinics:Urology specialty practices manage stable chronic obstruction through scheduled catheter exchange and monitoring.
- Home Care:Post-discharge intermittent catheterization programs expand across the United States and Western Europe as hydrophilic-coated single-use designs reduce infection readmission costs.
Hospital systems retain complex case concentration. Ambulatory surgical centers are climbing the fastest in procedural volume capture.
Delivery Mode:
Pharmacological adjuncts to mechanical intervention vary by obstruction etiology and acuity.
- Injectable:Alpha-blockers and corticosteroids administered peri-procedurally reduce ureteral edema and facilitate stone passage.
- Oral:Medical expulsive therapy with tamsulosin supports distal ureteral stone management in outpatient settings.
- Intravenous:Antibiotic prophylaxis and analgesia support acute obstruction management in emergency departments.
- Other:Topical and intravesical installations address select stricture and prostatic indications.
Oral medical expulsive therapy dominates chronic management. Injectable peri-procedural adjuncts concentrate in surgical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals and ambulatory surgical centers absorb the largest procedural volumes for obstructive uropathy interventions, with reimbursement pathways for minimally invasive urology procedures concentrating demand in integrated delivery networks across the Southeast and Midwest.
United States
CMS outpatient reimbursement expansion redirects ureteroscopy volume from hospital operating rooms to ambulatory surgical centers, with FDA 510(k) clearance pathways shaping product iteration cycles for stent and laser manufacturers. OSHA bloodborne pathogen standards accelerate single-use instrument adoption in southeastern Catholic health systems and for-profit chains.
Germany
Statutory health insurance reimbursement favors scheduled stent exchange protocols in hospital interventional suites, while aging populations over 65 expand benign prostatic hyperplasia intervention demand. EU Medical Device Regulation imposes enhanced clinical evidence requirements that extend CE marking timelines for catheter manufacturers seeking market access.
Japan
Metropolitan Tokyo and Osaka medical centers manage rising nephrolithiasis prevalence among elderly males, with PMDA regulatory frameworks governing urological device approvals. Home care channels absorb expanding hydrophilic-coated intermittent catheter volumes as payors prioritize urinary tract infection reduction.
India
Government hospital procurement programs and private urology chain expansion in Maharashtra and Karnataka create catheter and stent volume growth outside mature Western markets. CDSCO medical device regulations establish quality benchmarks for domestic and imported urological access devices.
United Kingdom
NHS integrated care systems consolidate purchasing decisions for urological interventions, with London and Southeast England academic medical centers maintaining complex case concentration. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment pathways for stent and laser system manufacturers.
Obstructive Uropathy Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue single-use digital platforms and home care channel penetration. The market structure consolidates around diversified medical technology conglomerates with integrated urology portfolios, while specialized access device manufacturers anchor interventional radiology supply chains. Three archetypes dominate: diversified conglomerates with full urology suites, specialized stent and catheter manufacturers with coating expertise, and capital equipment suppliers pivoting toward consumable revenue models. Competitive moves concentrate on strategic partnerships with ambulatory surgical center chains and portfolio diversification into disposable instrumentation.
Within the diversified conglomerate tier, Boston Scientific Corporation and Stryker Corporation exemplify integrated portfolio strategies spanning catheters, stents, and energy-based systems. Cook Medical occupies a position among specialized access device fabricators, anchoring interventional radiology suite supply relationships through concentrated manufacturing expertise. Olympus Corporation represents the capital-to-consumable pivot archetype, leveraging endoscopic platform familiarity to reposition toward single-use digital ureteroscope placement economics.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Medical |
| Coloplast A/S |
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| Olympus Corporation |
| Becton, Dickinson & Co. |
| Merit Medical Systems |
| Stryker Corporation |
| Others |
Value Network & Pricing Analysis
Single-use digital ureteroscope manufacturing simultaneously compresses production scale requirements and fragments supplier bases, as chip-on-tip imaging assemblies displace traditional fiber-optic bundles and redistribute component sourcing from German precision optics houses to Asian semiconductor packaging facilities. This technology transition concentrates margin capture among nitinol processors and CMOS sensor integrators while ambulatory surgical center procurement committees exploit the shift to renegotiate per-procedure consumable economics.
Pricing Analysis
Volume concentrates in stents and catheters where manufacturing scale determines margin capture, while premium pools cluster around single-use ureteroscopes and laser platforms where technology differentiation commands pricing power. Three-tier pricing structure across premium hydrophilic-coated, standard polymer, and economy uncoated tiers reflects ISO 10993 biocompatibility certification levels and coating durability specifications. Pricing pressure stems from group purchasing organization consolidation in southeastern United States hospital systems, where sole-source agreements compress supplier margins. Ambulatory surgical centers exhibit highest price sensitivity due to per-procedure reimbursement caps, while integrated delivery networks prioritize total cost-of-ownership metrics over unit pricing.
Supply Chain Analysis
ISO 13485 quality management certification and FDA 510(k) premarket notification requirements gate supplier entry for nitinol alloy processors and hydrophilic coating formulators, creating qualification backlogs that extend procurement timelines. Manufacturing concentrates in United States, Germany, and Japan for precision stent fabrication, while China and South Korea dominate CMOS image sensor and laser fiber production. Raw material dependencies center on nickel-titanium superelastic alloys, medical-grade polymers, and rare-earth laser gain media. Single-source vulnerability concentrates in nitinol wire drawing capacity, where limited qualified suppliers create input bottlenecks. Distribution runs through specialized medical device distributors and direct hospital contracting channels, with group purchasing organizations consolidating downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over nitinol raw material processing and hydrophilic coating formulation determines margin defense against emerging single-use platform competitors.
For Market Incumbents: Lock in nitinol alloy supply through long-term offtake agreements with certified wire processors, insulating against raw material volatility that threatens stent margin structures. Secure exclusive coating formulation partnerships with ISO 10993-qualified polymer suppliers to defend premium catheter positioning against standard-tier competitors. Prioritize backward integration into laser fiber manufacturing to capture energy-delivery margin pools currently flowing to third-party component vendors. For New Entrants and Emerging Players: Enter via single-use digital ureteroscope platforms targeting ambulatory surgical center chains in the United States, where lower capital barriers and CMS reimbursement expansion create rapid volume accumulation opportunities. Exploit white-space in India government hospital procurement programs, where CDSCO quality benchmarks favor cost-optimized stent and catheter designs over premium Western imports. Deploy direct-to-facility sales models bypassing traditional distributor markups, leveraging simplified inventory management as the primary value proposition. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical technology conglomerates seeking urology portfolio completeness, with valuation premia attaching to hydrophilic coating intellectual property and nitinol processing qualifications. Target mid-tier manufacturers with established European authorized representative networks, as EU MDR compliance costs accelerate market exit pressure. Watch FDA 510(k) clearance velocity for single-use ureteroscope entrants as the inflection signal indicating ambulatory surgical center adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates product iteration cycles for stent and laser manufacturers targeting United States hospital systems. |
| CE Marking Pathway | European market access hinges on MDR clinical evidence requirements that filter mid-tier manufacturer participation. |
| Hospital System Partnership | Integrated delivery network sole-source agreements consolidate catheter and stent purchasing into multi-year contracts. |
| Backward Integration into Nitinol | Captive alloy processing insulates margin structures against specialty metal processor concentration and price volatility. |
| Reimbursement Strategy | CMS outpatient payment adjustments redirect ureteroscopy volume toward ambulatory surgical center placements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving urology department heads, hospital purchasing committee members, biomedical engineers, GPO contracts managers, and ambulatory surgical center administrators. FDA 510(k) premarket notification databases, EU MDR notified body certificates, CMS Medicare reimbursement schedules, and import-export manifests provided procedural volume and device flow validation. Bottom-up stent and catheter shipment analysis triangulated against top-down reimbursement claim patterns.
Segmentation-level modeling addressed product type durability specifications, indication acuity tiers, end-user capital availability differentials, and delivery mode pharmacological adjuncts across the projection horizon. CAGRs derived from procedural volume elasticity to aging demographic penetration, technology substitution curves for single-use versus reusable platforms, and reimbursement policy shift scenarios. Forecast inputs incorporated nitinol raw material price trajectories, notified body capacity constraints, and ambulatory surgical center construction pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR implementation delays or nitinol supply disruptions. Model outputs reflect assumptions regarding CMS reimbursement stability, laser platform technology adoption curves, and coating formulation regulatory acceptance. A model refresh is warranted upon material change in FDA premarket review timelines or group purchasing organization consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Europe Urology Devices Market
Urology
Global Prostate Health Market
Urology
Varicocele Treatment Market
Urology
India Urology Device Market
Urology
Urinary Tract Infection Testing Market
Urology
Pyelonephritis Treatment Market
Urology
Europe Bladder Disorders Market
Urology
North America Bladder Disorders Market
Urology
Uropathy Treatment Market
Urology
Continence Care Market
Urology
Urology Devices Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Male Urinary Incontinence Market
Urology
Urinary Incontinence Market
Urology
Ureteral Obstruction Market
Urology
Global Bladder Cancer Market