
 Acute Pyelonephritis Treatment Market | 2026-2036
Acute Pyelonephritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Pyelonephritis Treatment Market Analytics
Hospital procurement channels for parenteral antibiotics is reshaping competitive dynamics in acute pyelonephritis care. Pfizer Inc. leverages its manufacturing scale to dominate intravenous cephalosporin supply chains across major health systems. Merck & Co., Inc. anchors its position through sustained R&D investment in carbapenem-class therapies for multidrug-resistant cases. Cipla Inc. competes aggressively on cost-engineered oral generics, extending its reach into outpatient transition protocols.
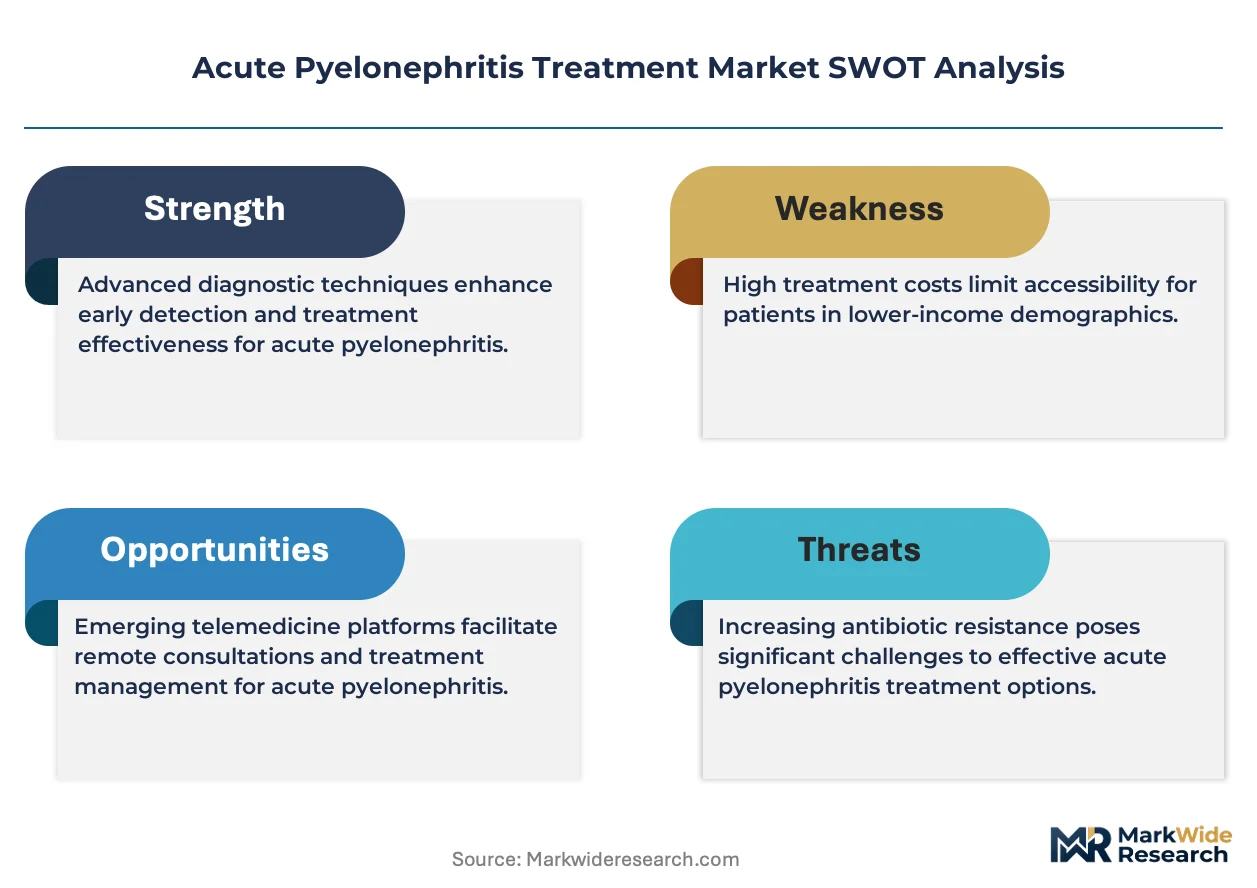
Acute pyelonephritis treatment encompasses the pharmacological and supportive management of sudden kidney parenchyma infection, typically requiring empiric antibiotic regimens targeting Enterobacteriaceae with minimum inhibitory concentration breakpoints guided by CLSI standards. The primary purpose centers on rapid bacteriuria clearance, fever resolution, and prevention of renal abscess or sepsis progression. Antibiotic therapy commands the largest value pool given empiric IV-to-oral step-down protocols, while intravenous fluids maintains steady procedural attachment to inpatient admission bundles. Oral delivery mode is gaining structural share as outpatient stewardship programs expand appropriate early discharge criteria.
FDA antimicrobial stewardship mandates and EMA pharmacovigilance frameworks jointly elevate the evidentiary bar for new antibiotic approvals, compressing development timelines for resistant-pathogen indications. Hospital reimbursement tied to CMS Hospital-Acquired Condition Reduction Program penalties directly shapes formulary decisions for first-line pyelonephritis agents. Stakeholders must monitor resistance surveillance data from CDC NHSN and adapt pipeline priorities toward pathogens exceeding current susceptibility breakpoints.
Market Dynamics
Antimicrobial stewardship mandates from FDA and EMA are compressing empiric prescribing windows, forcing formulary committees to prioritize narrow-spectrum agents with rapid susceptibility turnaround. This regulatory pressure is restructuring hospital procurement protocols and reshaping competitive positioning among antibiotic developers.
Growth Catalysts
- Rising Multidrug-Resistant Enterobacteriaceae Prevalence:Escalating resistance rates in E. coli and Klebsiella species are compelling health systems to stock broader-spectrum reserve antibiotics. Tertiary care centers in the United States are expanding infectious disease consult services to manage complex cases.
- CMS Hospital-Acquired Condition Reduction Program:Financial penalties tied to preventable complications are accelerating investment in rapid diagnostic platforms. Hospitals are integrating PCR-based pathogen identification into emergency department workflows.
- Outpatient Parenteral Antimicrobial Therapy (OPAT) Infrastructure:Home infusion capabilities are expanding step-down care capacity. Skilled nursing facilities and home health agencies are building antibiotic administration competencies.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Penicillin and cephalosporin precursor manufacturing concentrates in China and India, creating supply vulnerability. Geopolitical disruptions or export restrictions threaten production continuity.
- Carbapenem Production Cost Volatility:Complex synthesis routes and sterile manufacturing requirements elevate fixed costs. Energy-intensive fermentation processes expose margins to electricity price fluctuations.
- Antibiotic Development Pipeline Attrition:Limited commercial returns relative to oncology and immunology compress R&D investment. Venture capital has retrenched from early-stage antibacterial discovery.
Strategic Opportunities
- Oral Bioavailability Enhancement:Prodrug formulations and permeability-modifying excipients are enabling IV-to-oral conversion for broader-spectrum agents. This convergence of formulation science and pharmacokinetic modeling reduces hospital length of stay.
- India Outpatient Transition Protocols:Underpenetrated ambulatory care infrastructure presents white space for oral fluoroquinolone and beta-lactam distribution. Pharmacy chains are building chronic disease management capabilities that extend to infection follow-up.
- AI-Guided Empiric Therapy Selection:Machine learning algorithms trained on local antibiograms are personalizing initial antibiotic choice. Health systems with robust electronic health record data are piloting decision support integration.
Industry Challenges
- Microbiology Laboratory Staffing Shortages:Specialized technologists capable of performing susceptibility testing and quality assurance are in scarce supply. Training pipelines have not kept pace with retirement attrition.
- Legacy EHR Interoperability Barriers:Antibiotic stewardship software requires seamless data exchange between pharmacy, laboratory, and clinical documentation systems. Fragmented vendor landscapes impede unified dashboard deployment.
- Pharmacovigilance Signal Detection Complexity:Rare adverse event reporting for new antibiotics demands sophisticated epidemiological surveillance. Smaller patient exposure bases complicate safety profile characterization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Pyelonephritis Treatment Market |
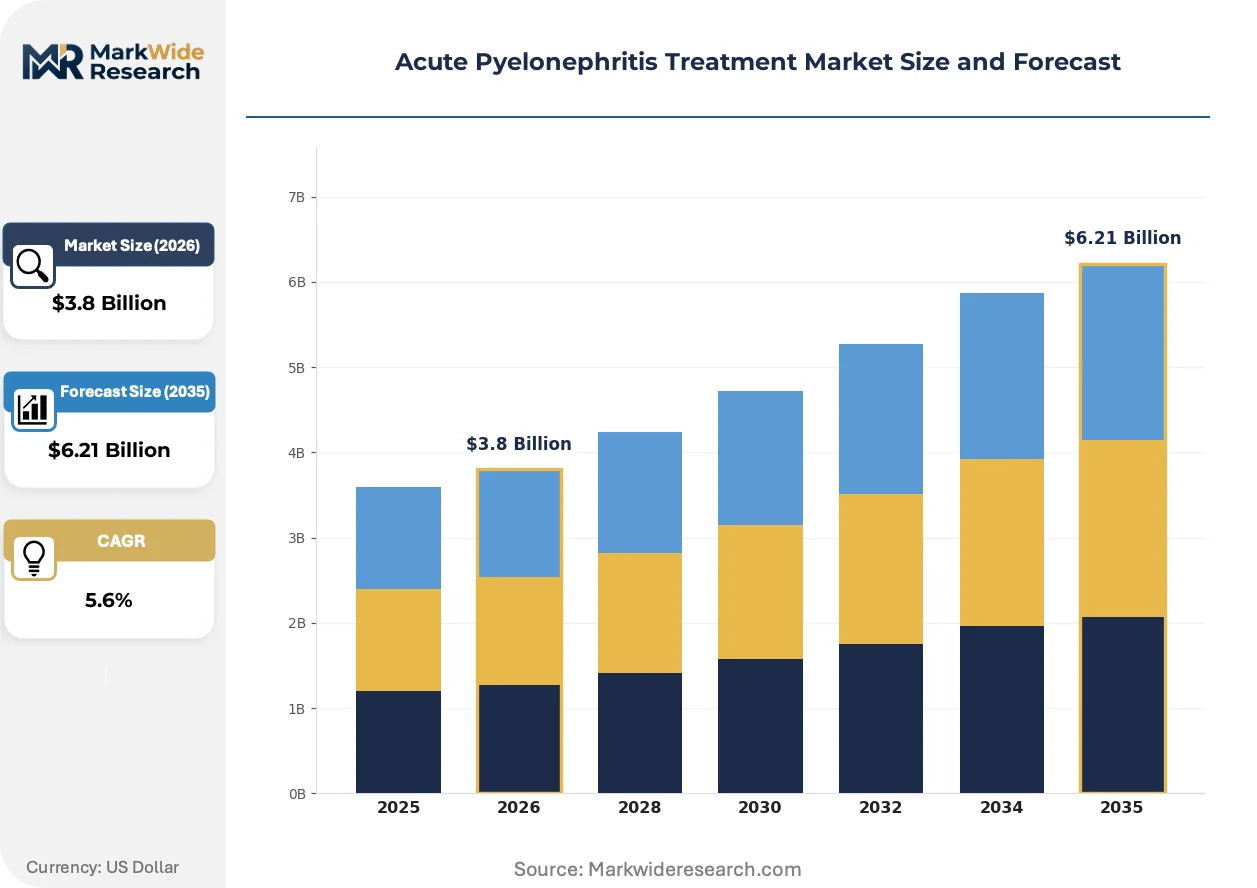
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antipyretics, Pain Relievers, Intravenous Fluids Delivery Mode: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Clinics, Home Care, Pharmaceutical Companies Treatment Approach: Symptomatic Management, Antibiotic Therapy, Inpatient Treatment, Outpatient Care |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Melinta Therapeutics, LLC., Spero Therapeutics, VenatoRx Pharmaceuticals, Inc., Johnson & Johnson Services, Inc., Cipla Inc., Wockhardt, Entasis Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Pyelonephritis Treatment Market Evolving Landscape
Diagnostic-guided de-escalation protocols are compressing the empiric-to-targeted therapy transition window, while novel delivery mechanisms and digital surveillance tools are restructuring how acute infections are managed across care settings.
Pharmacokinetic-pharmacodynamic modeling software is hybridizing traditional dosing protocols with real-time renal function monitoring. Large academic medical centers are deploying these platforms to optimize beta-lactam exposure in critically ill patients with fluctuating creatinine clearance. This technology is enabling precision dosing that reduces toxicity while maintaining bacterial kill rates.
FDA's Project Facilitate and EMA's PRIME designation are accelerating development pathways for qualified infectious disease products. These frameworks compress Phase 3 trial timelines for agents targeting resistant pathogens with limited treatment options. Developers are prioritizing carbapenem-resistant Enterobacteriaceae indications to secure priority review vouchers and enhanced market exclusivity.
Hospital formulary committees are consolidating antibiotic purchasing through group purchasing organizations and regional collaborative networks. This concentration is displacing individual hospital contracting autonomy with standardized preferred drug lists. The United States exhibits the most pronounced shift, as integrated delivery networks leverage volume to extract price concessions from manufacturers.
Acute Pyelonephritis Treatment Market Segmentation
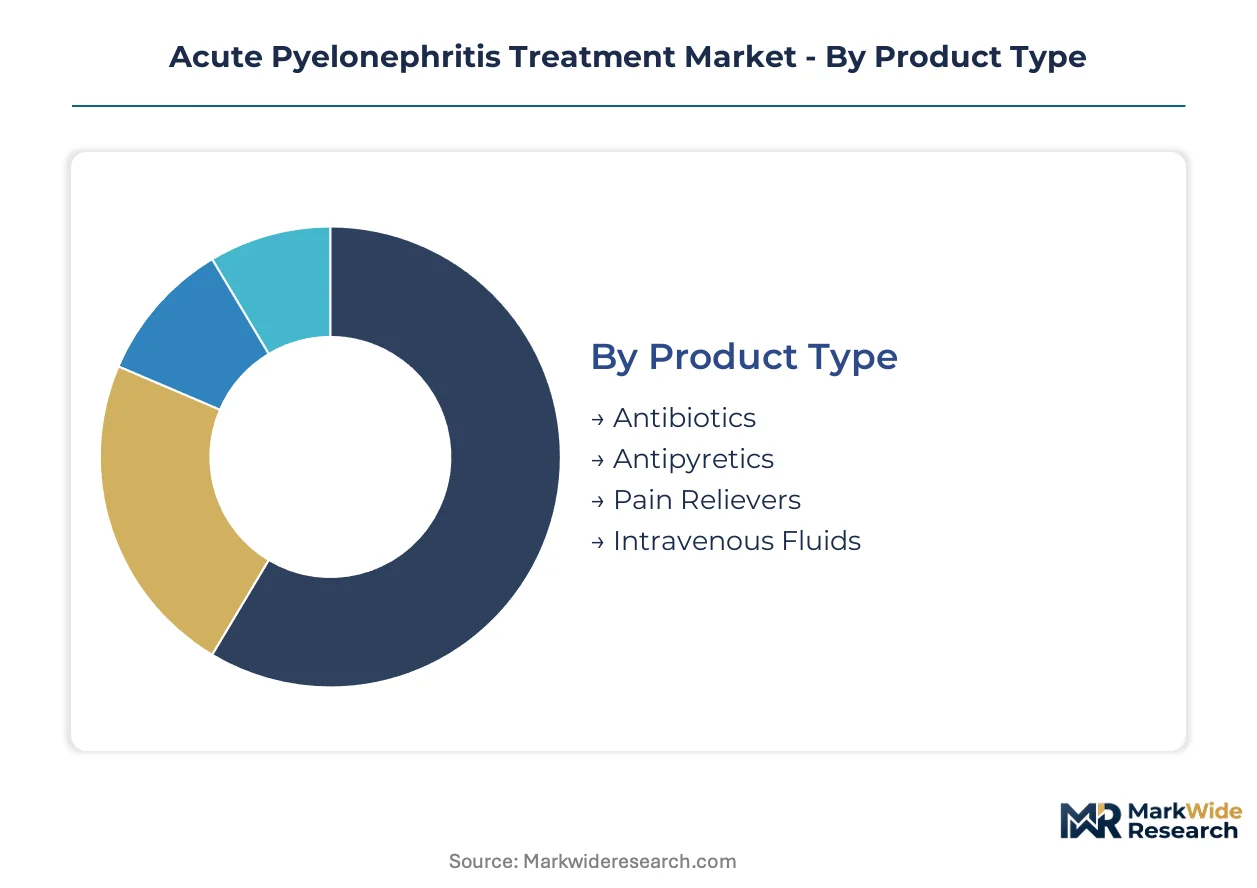
Segmentation in acute pyelonephritis treatment reveals how clinical protocols, reimbursement structures, and resistance patterns allocate value across therapeutic modalities. Each dimension captures distinct procurement rhythms and margin profiles that shape manufacturer strategy.
Product Type:
Antibiotics turn over fastest due to stewardship-mandated formulary rotations, while intravenous fluids maintain the most stable demand cycles tied to admission bundles.
- Antibiotics:Beta-lactams, fluoroquinolones, and carbapenems constitute the therapeutic backbone with empiric-to-targeted step-down protocols. Tertiary care centers in the United States are expanding carbapenem stockpiles as extended-spectrum beta-lactamase prevalence climbs.
- Antipyretics:Acetaminophen and NSAID formulations manage fever burden during acute infection phases. Outpatient transition protocols in India are driving demand for fixed-dose combination packs paired with oral antibiotics.
- Pain Relievers:Opioid-sparing analgesic strategies favor NSAID-first approaches in emergency department pathways.
- Intravenous Fluids:Crystalloid resuscitation bundles attach to sepsis protocol compliance with minimal substitution risk.
Antibiotics anchors the volume base while intravenous fluids gains share at the steepest rate as observation-unit admission criteria expand.
Delivery Mode:
Cost tiering separates high-complexity parenteral administration from commodity oral dispensing, with reimbursement differentials widening between inpatient and ambulatory channels.
- Oral:Bioavailable agents enable early discharge and outpatient parenteral antimicrobial therapy step-down. Pharmacy chains in the United States are building home delivery infrastructure for post-discharge antibiotic adherence.
- Intravenous:Hospital-based infusion requires sterile compounding capabilities and nursing supervision. Academic medical centers are deploying pharmacokinetic-guided dosing platforms to optimize beta-lactam exposure in critically ill patients.
- Subcutaneous:Limited application for selected long-acting agents in stable transition patients.
- Topical:Negligible role in kidney parenchyma infection given tissue penetration requirements.
Intravenous dominates value capture while oral climbs the fastest as CMS readmission penalties accelerate discharge velocity.
End User:
Customer concentration patterns concentrate procurement leverage in integrated delivery networks while fragmenting purchasing across independent practice settings.
- Hospitals:Inpatient admission bundles capture the majority of acute pyelonephritis spend through emergency department-to-ward pathways. Group purchasing organizations in the United States are consolidating antibiotic contracts across member health systems.
- Clinics:Urgent care and primary care settings manage uncomplicated cases with oral-first protocols. Federally qualified health centers are expanding point-of-care urine PCR capabilities to reduce unnecessary broad-spectrum prescribing.
- Home Care:Skilled nursing and home infusion agencies administer OPAT regimens with nursing supervision.
- Pharmaceutical Companies:Contract manufacturing and clinical trial supply represent niche demand.
Hospitals anchors the volume base while home care gains share at the steepest rate as infusion infrastructure decentralizes.
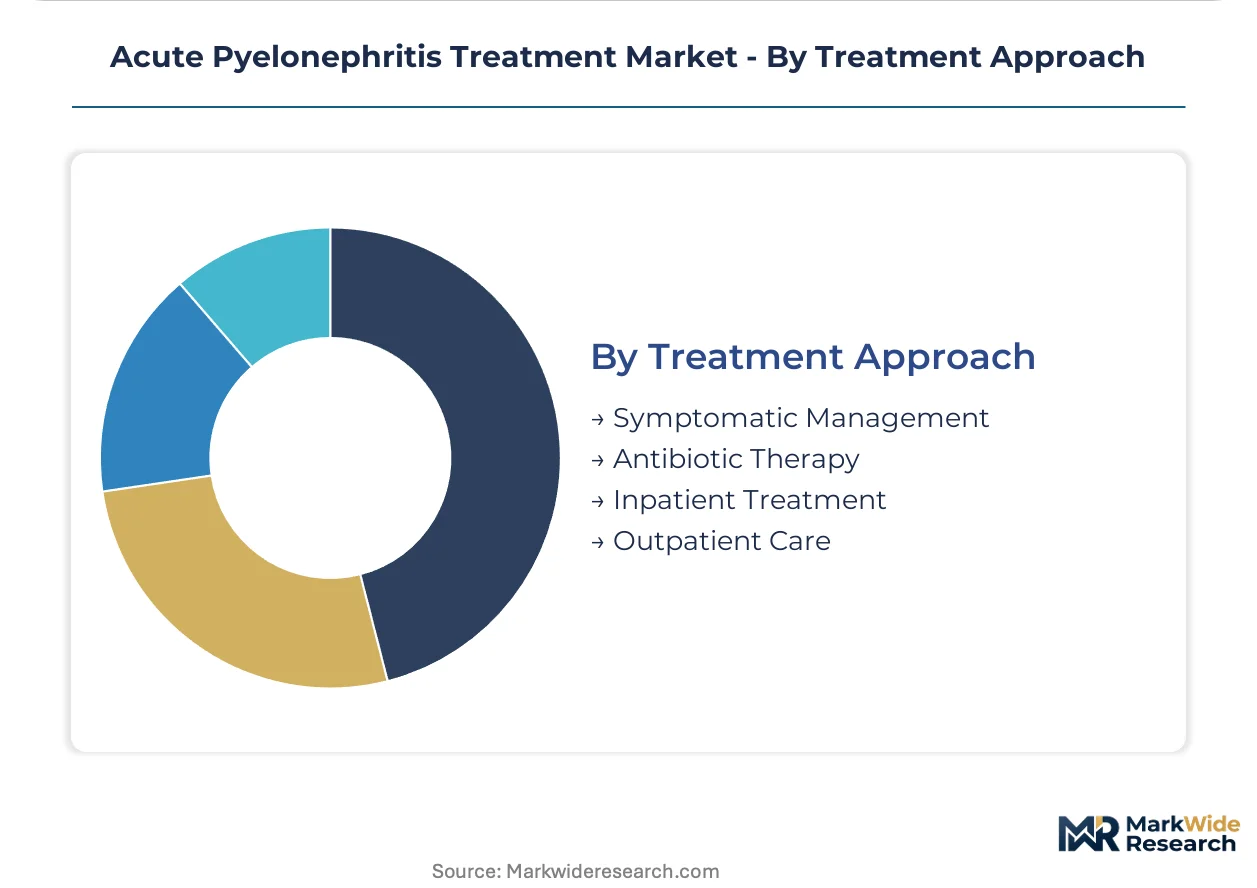
Treatment Approach:
Maturity differentiation separates established antibiotic protocols from emerging diagnostic-guided de-escalation workflows reshaping clinical pathways.
- Antibiotic Therapy:Empiric selection followed by susceptibility-guided refinement constitutes the core intervention. FDA antimicrobial stewardship mandates are compressing broad-spectrum exposure windows in United States hospitals.
- Inpatient Treatment:Admission criteria center on sepsis risk stratification and oral intolerance. Tertiary care centers are deploying rapid molecular diagnostics to accelerate appropriate admission versus discharge decisions.
- Symptomatic Management:Hydration, antipyresis, and analgesia support antibiotic efficacy without standalone curative effect.
- Outpatient Care:Observation protocols and early discharge criteria expand ambulatory capacity. India's pharmacy-led chronic disease networks are piloting infection follow-up services.
Antibiotic therapy anchors the volume base while outpatient care gains share at the steepest rate as risk stratification tools improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites Europe's distribution primacy for temperature-sensitive parenteral antibiotics. This logistics backbone enables rapid deployment of reserve carbapenems to tertiary centers managing resistant Enterobacteriaceae outbreaks.
United States
Tertiary care centers in Boston, New York, and Houston are expanding infectious disease consult services for multidrug-resistant pyelonephritis cases. FDA antimicrobial stewardship mandates through the National Action Plan for Combating Antibiotic-Resistant Bacteria compress empiric prescribing windows. The Research Triangle Park cluster in North Carolina anchors pharmacovigilance operations for several antibiotic developers.
Germany
EMA pharmacovigilance frameworks elevate evidentiary requirements for new antibiotic approvals, reshaping formulary decisions across university hospitals. The Paul-Ehrlich-Institut in Langen coordinates resistance surveillance that informs national treatment guidelines. Baden-Württemberg's pharmaceutical manufacturing corridor maintains cephalosporin precursor production capabilities.
India
Pharmacy chains in Mumbai and Delhi are building chronic disease management capabilities that extend to infection follow-up services. CDSCO's tightened manufacturing inspection protocols align domestic production with WHO prequalification standards. The Hyderabad-Visakhapatnam corridor concentrates active pharmaceutical ingredient synthesis for beta-lactam antibiotics.
China
NMPA's priority review pathways for anti-infective drugs accelerate market entry for novel agents targeting carbapenem-resistant pathogens. The Yangtze River Delta pharmaceutical cluster in Shanghai and Suzhou dominates penicillin and cephalosporin precursor manufacturing. Beijing's infectious disease hospitals are piloting rapid molecular diagnostic platforms for emergency department triage.
Japan
PMDA's Sakigake designation system fast-tracks antibiotics addressing unmet medical needs in resistant gram-negative infections. The Kansai region's Osaka-Kobe pharmaceutical hub maintains fermentation-based antibiotic production infrastructure. Tokyo's academic medical centers deploy pharmacokinetic-guided dosing platforms for critically ill patients with renal impairment.
Acute Pyelonephritis Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The acute pyelonephritis treatment market consolidates around three strategic archetypes: multinational pharmaceutical conglomerates with manufacturing scale, mid-cap antibiotic specialists pursuing resistant-pathogen indications, and cost-engineered generic manufacturers. Competitive dynamics center on formulary positioning through group purchasing organization contracts and rapid diagnostic co-development partnerships.
Among the multinational tier, Pfizer Inc. and Merck & Co., Inc. exemplify platform-scale antibiotic developers with integrated hospital supply chain access. Cipla Inc. occupies a distinct position as a geography-anchored generic specialist with cost-optimized oral formulation capabilities. These three entities represent the dominant competitive archetypes: scale-driven platform integration, R&D-intensive resistance-focused development, and emerging market cost leadership.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Melinta Therapeutics, LLC. |
| Spero Therapeutics |
| VenatoRx Pharmaceuticals, Inc. |
| Johnson & Johnson Services, Inc. |
| Cipla Inc. |
| Wockhardt |
| Entasis Therapeutics |
| Others |
Value Network & Pricing Analysis
The Port of Rotterdam's pharmaceutical cold chain infrastructure anchors cost dynamics for temperature-sensitive parenteral antibiotics, with freight premiums widening price spreads between reserve carbapenems and standard cephalosporins as group purchasing organizations leverage volume concentration against manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates originator carbapenems from licensed generics and unbranded oral fluoroquinolones. Price differentiation hinges on FDA Q1/Q2 certification status and contract scale with integrated delivery networks. Pricing pressure stems from CMS Hospital-Acquired Condition penalty exposure compressing formulary budgets. Federally qualified health centers exhibit highest price sensitivity; tertiary academic centers prioritize resistance coverage over acquisition cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply risk calculus for beta-lactam precursor flows. Active pharmaceutical ingredient synthesis concentrates in the Yangtze River Delta, Hyderabad-Visakhapatnam corridor, and Baden-Württemberg manufacturing cluster. Penicillin and cephalosporin fermentation feeds from Chinese fermentation capacity; carbapenem synthesis rests on Indian intermediate chemistry. Single-source vulnerability in sterile injectable finishing threatens reserve antibiotic availability. Distribution runs through regional hospital distribution centers and specialty pharmacy networks for outpatient parenteral antimicrobial therapy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acute pyelonephritis treatment operates as a defensive-moat market where FDA antimicrobial stewardship mandates create regulatory entrenchment, elevating switching costs for hospital formulary committees and protecting incumbent positions against generic displacement.
For Market Incumbents: Pre-empt formulary displacement by securing rapid diagnostic co-development partnerships with molecular platform vendors before mid-cap specialists capture stewardship software integration. Anchor manufacturing scale through backward integration into cephalosporin precursor supply. Lock in group purchasing organization preferred status with resistance surveillance data subscriptions that embed clinical decision support.
For New Entrants and Emerging Players: Pursue oral bioavailability enhancement for carbapenem-class agents as the most penetrable white space, targeting India outpatient transition protocols where pharmacy chains build chronic disease management infrastructure. Secure CDSCO manufacturing inspections early to align with WHO prequalification standards. Lead with cost-engineered generics paired with adherence packaging for skilled nursing facility discharge channels.
For Investors and Strategic Acquirers: AI-guided empiric therapy selection platform developers represent the priority acquisition archetype, with machine learning algorithms trained on local antibiograms commanding premium valuations from health systems seeking stewardship automation. Watch for inflection when hospital reimbursement shifts toward outcome-based infection management contracts. Long-term viability favors developers with carbapenem-resistant Enterobacteriaceae priority review vouchers and FDA Project Facilitate engagement.
| Strategic Initiative | Industry Significance |
|---|---|
| Rapid Diagnostic Co-Development Partnership | Integrates PCR-based pathogen identification with antibiotic stewardship software to compress empiric prescribing windows. |
| Oral Bioavailability Enhancement Program | Enables IV-to-oral conversion for broader-spectrum agents, reducing hospital length of stay under CMS penalties. |
| CDSCO Manufacturing Inspection Alignment | Positions Indian production facilities for WHO prequalification and export market access. |
| AI-Guided Empiric Therapy Platform | Deploys machine learning on local antibiograms to personalize initial antibiotic selection in emergency departments. |
| Carbapenem-Resistant Pathogen Priority Voucher | Secures FDA expedited review and enhanced market exclusivity for qualified infectious disease products. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Interviews with infectious disease clinicians, formulary directors, group purchasing organization contract managers, and regulatory affairs specialists informed demand-side dynamics. Bottom-up prescription volume modeling triangulated against top-down manufacturer revenue attribution across antibiotic therapy, intravenous fluids, and diagnostic platform segments.
Forecast inputs incorporate resistance surveillance data from CDC NHSN and Paul-Ehrlich-Institut, antimicrobial stewardship mandate implementation timelines, and CMS penalty exposure trajectories. Segmentation dimensions span product type, delivery mode, end user, and treatment approach with regional regulatory cluster overlays. CAGRs derive from iterative convergence of epidemiological trend projection, pricing elasticity assumptions, and formulary rotation velocity across the analysis window.
Sensitivities concentrate around carbapenem production cost volatility, microbiology laboratory staffing shortages delaying susceptibility testing, and geopolitical disruption to active pharmaceutical ingredient flows. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Self-Intermittent Catheters Market
Urology
Botulinum Toxin in Urology Market
Urology
Suprapubic Catheters Market
Urology
Urology Ultrasound Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Global Bladder Scanner Market
Urology
Renal Cyst Treatment Market
Urology
Global Bladder Cancer Market
Urology
Uraemia Treatment Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Global Hydronephrosis Market
Urology
Urinary Retention Therapeutics Market
Urology
Ureter Cancer Treatment Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market