
 Pelvic Cancer Induced Hemorrhegic Cystitis Market | 2026-2036
Pelvic Cancer Induced Hemorrhegic Cystitis Market Size, Share, and Industry Trends Forecast 2026-2036
Pelvic Cancer Induced Hemorrhegic Cystitis Market Analytics
Multi-source procurement of active pharmaceutical ingredients is expanding as formulators seek supply resilience against single-source dependencies. Johnson & Johnson Services, Inc. leverages its hospital channel dominance to secure preferred vendor status in cancer treatment centers. Astellas Pharma Inc. anchors its position through deep specialization in uro-oncology therapeutic portfolios. Bayer AG competes on manufacturing scale for intravesical formulation capacity across North American and European markets.
Pelvic cancer induced hemorrhagic cystitis denotes severe bladder mucosal inflammation with bleeding, triggered by radiation or chemotherapy damage to the urinary epithelium, typically managed through intravesical instillations of formalin, alum, or hyaluronic acid formulations. The condition demands continuous monitoring of hematuria grade, clot retention risk, and renal function parameters to guide intervention intensity. Medications occupy the largest margin pool among product types due to recurring prescription cycles and patent-protected biologics, while surgical solutions represent the fastest-growing segment as minimally invasive cystoscopic techniques displace open procedures. Hospitals dominate end-user demand through captive patient flows and integrated pharmacy formularies, though outpatient clinics are gaining share through same-day intravesical therapy protocols.
The FDA's Breakthrough Therapy designation and EMA's PRIME eligibility framework are reshaping clinical trial requirements for hemorrhagic cystitis therapeutics, compressing development timelines while intensifying post-market surveillance obligations. ISO 13485 quality management standards govern device-manufacturer compliance for cystoscopic delivery systems, creating certification barriers for new entrants. Stakeholders must monitor how real-world evidence requirements from these regulators alter payer negotiation leverage for novel supportive care agents.
Market Dynamics
The FDA's orphan drug designation pathway is compressing development timelines for novel bladder-protective agents, while Medicare reimbursement expansion is pulling tertiary hospital oncology departments toward intravesical therapy protocols. This regulatory-commercial alignment is restructuring competitive entry barriers and treatment site economics simultaneously.
Growth Catalysts
- EMA PRIME Eligibility:The European Medicines Agency's priority medicines framework accelerates regulatory review for hemorrhagic cystitis therapeutics, compressing time-to-market for developers targeting radiation-induced bladder injury.
- Tertiary Hospital Expansion:Oncology departments in academic medical centers are building dedicated uro-oncology infusion suites, creating captive demand channels for formalin and hyaluronic acid formulations.
- Hyaluronic Acid Formulation Advances:Novel cross-linked polymer technologies are extending dwell times in bladder mucosa, reducing instillation frequency and improving patient compliance metrics.
Market Restraints
- Single-Source API Dependencies:Active pharmaceutical ingredient supply for alum solutions concentrates among Chinese manufacturers, exposing formulators to geopolitical trade friction and shipping volatility.
- ISO 13485 Certification Barriers:Cystoscopic delivery system manufacturers face 18-24 month quality management audits, freezing new entrants from device market participation.
- Substitute Procedure Competition:Hyperbaric oxygen therapy for radiation cystitis is capturing refractory cases through Medicare Part B reimbursement, diverting patients from pharmaceutical management.
Strategic Opportunities
- Outpatient Clinic Protocols:Same-day intravesical therapy centers in the United States are bypassing hospital pharmacy formularies, opening direct purchasing relationships with specialty distributors.
- Real-World Evidence Requirements:Post-market surveillance obligations under FDA Breakthrough Therapy designation are creating demand for digital health monitoring platforms that track hematuria grade and clot retention events.
- Biologics Patent Windows:Patent-protected recombinant growth factor formulations command premium pricing through recurring prescription cycles in oncology supportive care.
Industry Challenges
- Uro-Oncology Specialist Scarcity:Fellowship-trained cystoscopists capable of managing grade IV hemorrhagic cystitis are concentrated in metropolitan academic centers, limiting protocol rollout to community hospitals.
- Legacy EHR Integration:Bladder instillation documentation workflows require custom API development with Epic and Cerner systems, extending implementation timelines for digital therapeutics vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pelvic Cancer Induced Hemorrhegic Cystitis Market |
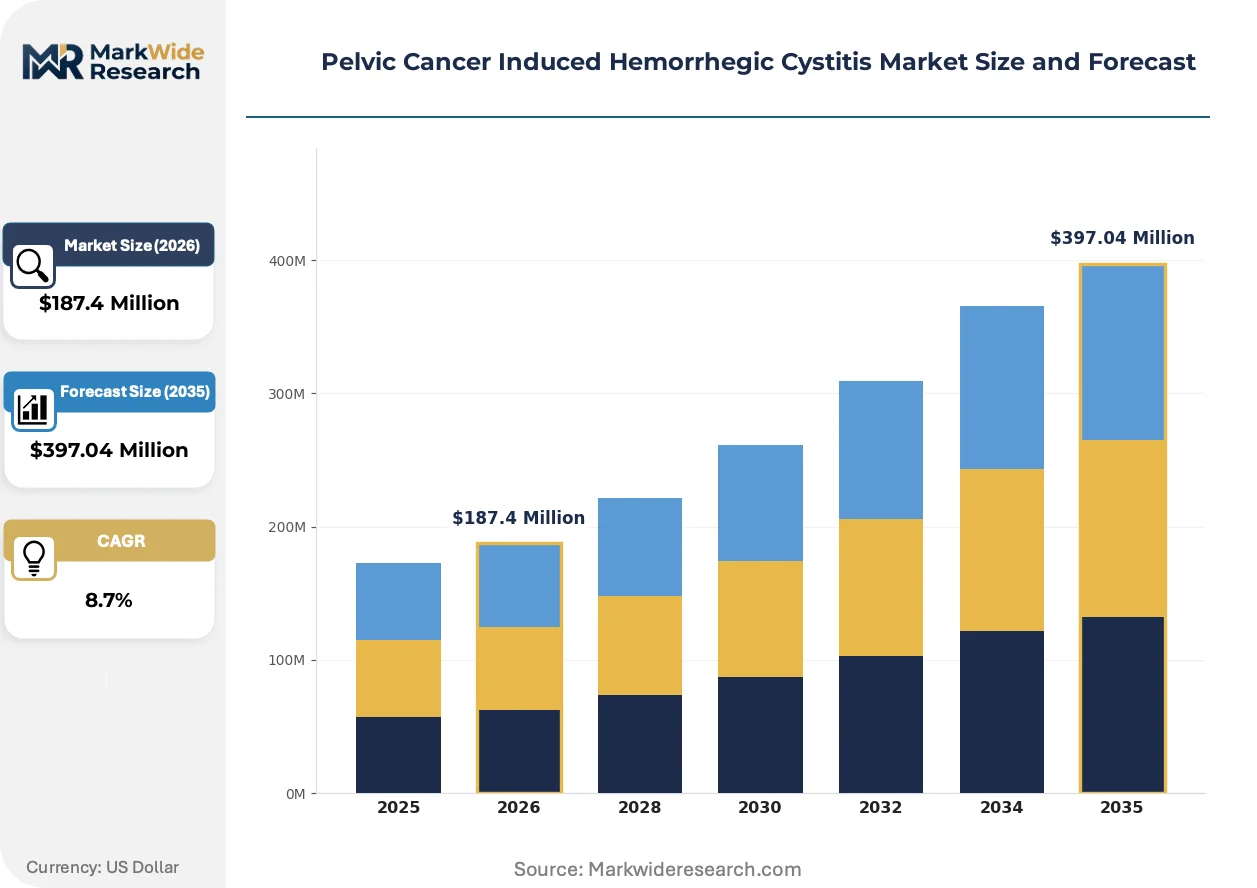
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Therapies, Surgical Solutions, Supportive Care End User: Hospitals, Cancer Treatment Centers, Outpatient Clinics, Home Care Delivery Mode: Intravenous, Oral, Subcutaneous, Topical Application: Palliative Care, Symptomatic Treatment, Preventive Therapy, Emergency Intervention |
| Companies Covered | Johnson & Johnson Services, Inc., Astellas Pharma Inc., Sanofi, Bayer AG, AstraZeneca, Merck & Co., Inc., Pfizer Inc., Lipella Pharmaceuticals Inc., Urigen Pharmaceuticals Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pelvic Cancer Induced Hemorrhegic Cystitis Market Evolving Landscape
Digital health integration and minimally invasive delivery systems are restructuring how clinicians monitor and intervene in radiation-induced bladder injury. These shifts are compressing treatment cycles while expanding site-of-care flexibility.
Smart cystoscopic irrigation systems with embedded pressure sensors and automated clot evacuation are decentralizing acute hemorrhagic cystitis management from operating rooms to procedure suites. Ambulatory surgery centers in Florida and Texas are piloting these platforms to reduce inpatient admission rates. The technology is decentralizing capital equipment requirements and enabling same-day discharge protocols previously restricted to tertiary facilities.
EMA's Medical Device Regulation (MDR) reclassification of high-risk urological delivery systems is forcing manufacturers to submit clinical evidence packages for legacy catheter designs. European notified bodies are extending review timelines for cystoscopic devices, delaying market access for novel instillation technologies. German and French urology clinics are responding by consolidating purchases through group purchasing organizations to amortize compliance costs across hospital networks.
Hospital procurement departments are unbundling device and pharmaceutical contracts, separating cystoscope purchases from hyaluronic acid formulation supply agreements. This pattern disrupts bundled vendor relationships that previously locked oncology departments into single-source formularies. The shift is most visible in United States cancer centers participating in the 340B drug pricing program, where pharmacy benefit managers are negotiating direct manufacturer contracts for intravesical agents.
Pelvic Cancer Induced Hemorrhegic Cystitis Market Segmentation
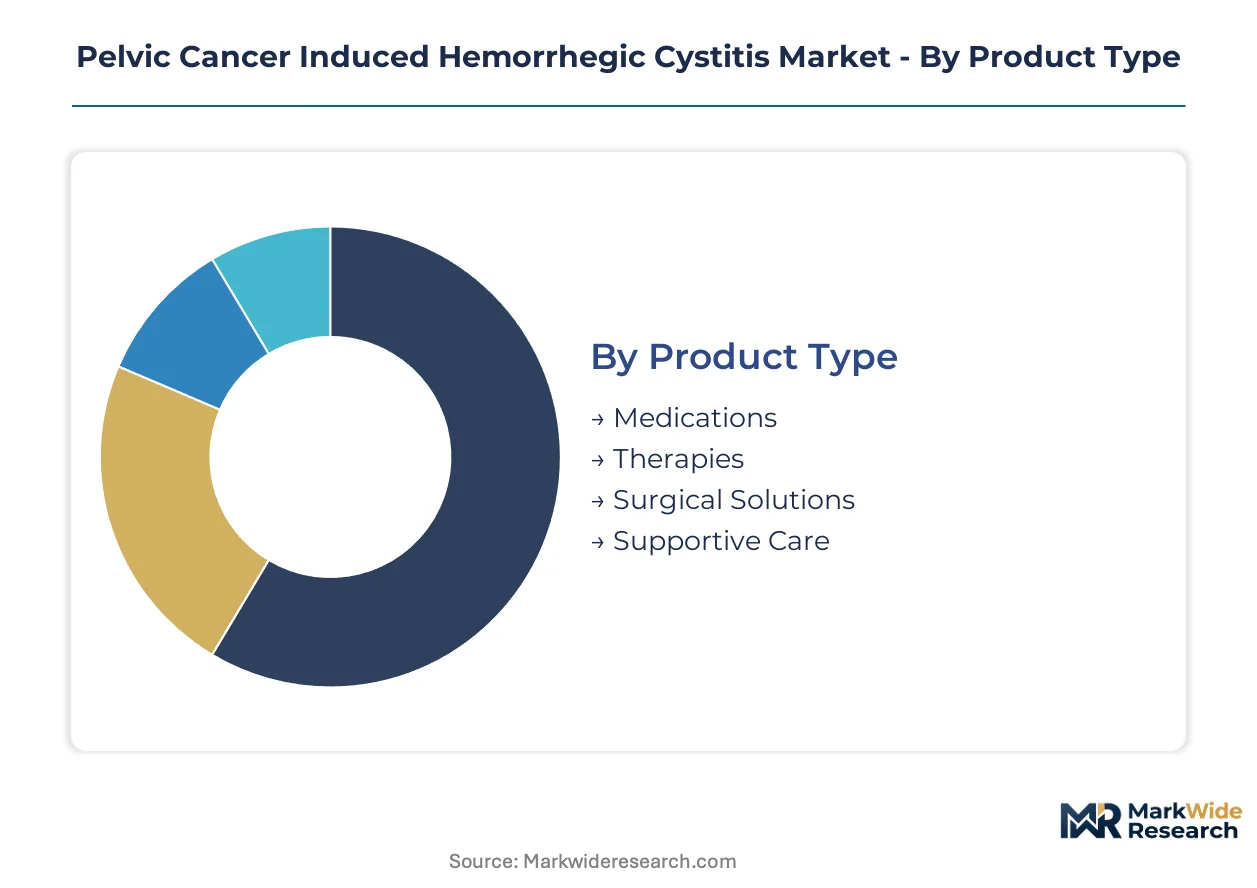
Pelvic cancer induced hemorrhagic cystitis demands precise segment targeting due to divergent regulatory pathways across product types and delivery modes. Manufacturers must align certification strategies with end-user procurement patterns to secure formulary placement.
Product Type:
FDA Breakthrough Therapy designation and EMA PRIME eligibility apply unevenly across this category, with biologics facing steeper clinical evidence requirements than chemical instillations.
- Medications:Intravesical formulations including formalin, alum, and hyaluronic acid solutions require sterile manufacturing under cGMP standards. Demand concentrates in United States tertiary hospitals where Medicare reimbursement for supportive cancer care has broadened access. Patent-protected biologics command recurring prescription cycles.
- Therapies:Hyperbaric oxygen and bladder irrigation protocols fall under device-drug combination rules in some jurisdictions. German and French urology clinics are consolidating purchases through group purchasing organizations to amortize compliance costs.
- Surgical Solutions:Minimally invasive cystoscopic techniques displace open procedures.
- Supportive Care:Blood transfusion adjuncts and clot management products.
Medications sit at the top of the volume ranking, with surgical solutions climbing the fastest.
End User:
Procurement authority and reimbursement mechanisms vary sharply across this category, dictating pricing flexibility and contract structure.
- Hospitals:Academic medical centers with dedicated uro-oncology infusion suites dominate high-complexity cases. These institutions leverage 340B drug pricing program participation to negotiate direct manufacturer contracts for intravesical agents.
- Cancer Treatment Centers:Specialized facilities integrate bladder-protective protocols into radiation oncology workflows. Florida and Texas ambulatory surgery centers pilot smart cystoscopic systems to reduce inpatient admissions.
- Outpatient Clinics:Same-day intravesical therapy centers bypass hospital pharmacy formularies.
- Home Care:Limited to oral supportive medications and monitoring devices.
Hospitals capture the largest revenue share, though outpatient clinics are expanding most quickly.
Delivery Mode:
Route selection determines device classification burden and site-of-care economics for manufacturers.
- Intravenous:Systemic agents for severe hemorrhagic complications require infusion center infrastructure. United States cancer centers favor this route for grade III-IV hematuria requiring hospital-based monitoring.
- Oral:Supportive medications including analgesics and bladder wall stabilizers. Home care demand is concentrating in Medicare Advantage networks with expanded supportive care benefits.
- Subcutaneous:Growth factor formulations for mucosal healing.
- Topical:Limited to external genitourinary applications.
Intravenous administration leads by value, with oral delivery gaining share fastest through home-based protocols.
Application:
Clinical urgency and evidence requirements shape development investment and regulatory strategy across use cases.
- Palliative Care:Comfort-focused management for terminal pelvic cancer patients emphasizes clot retention prevention and pain control. Hospice partnerships in United States metropolitan areas drive demand for simplified instillation protocols.
- Symptomatic Treatment:Active hematuria management with formalin or hyaluronic acid instillations. Tertiary hospital oncology departments are expanding adoption as intravesical therapy protocols standardize.
- Preventive Therapy:Pre-radiation bladder conditioning regimens.
- Emergency Intervention:Acute clot evacuation and continuous bladder irrigation.
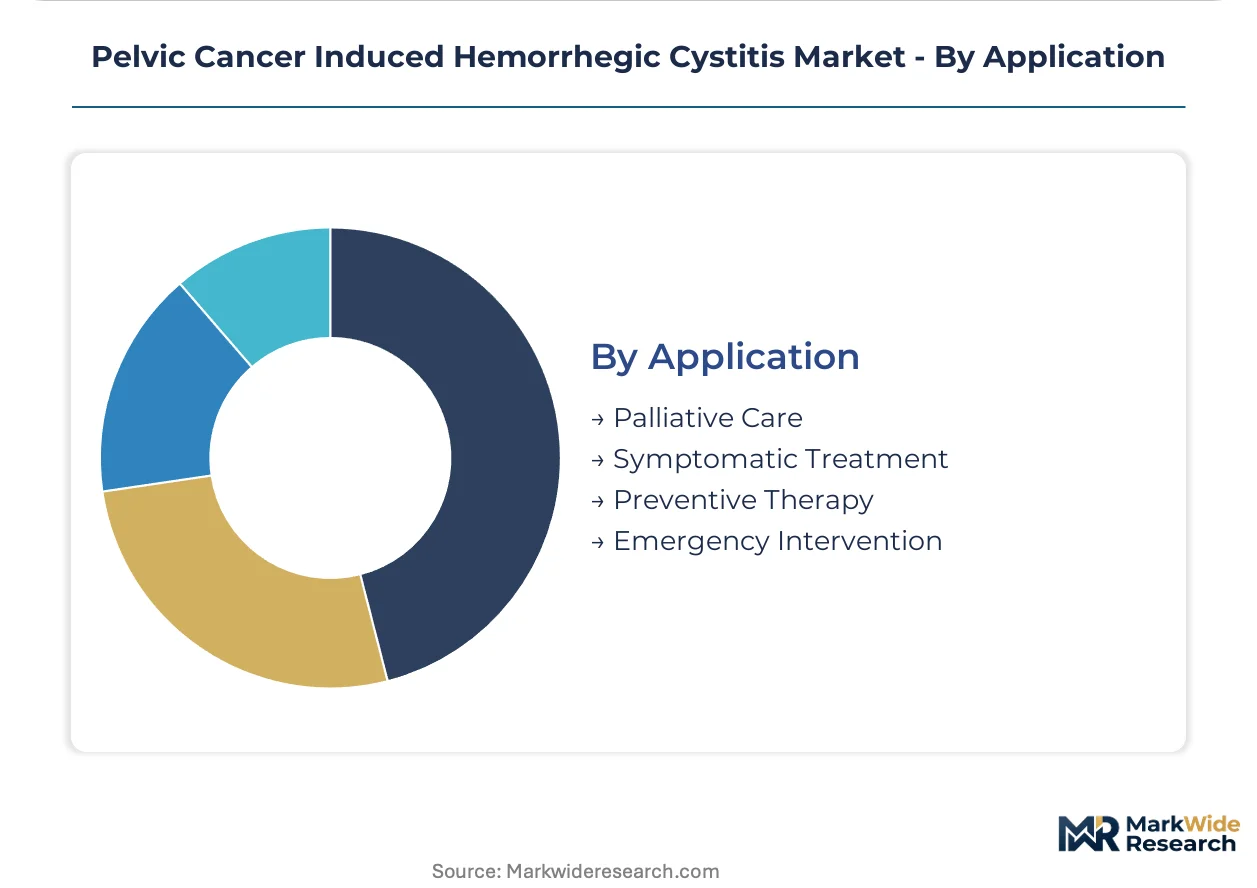
Symptomatic treatment holds the highest procedure volume, with preventive therapy showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tertiary hospital oncology departments in the United States anchor demand for intravesical hemorrhagic cystitis therapies, with Medicare reimbursement expansion pulling treatment protocols toward academic medical centers. FDA orphan drug designations and EMA PRIME eligibility frameworks are compressing development timelines across North America and Europe, while supply chain dependencies on Chinese API manufacturers create geographic risk concentrations.
United States
Academic medical centers in Boston, Houston, and New York Metro are building dedicated uro-oncology infusion suites for formalin and hyaluronic acid protocols. Medicare Part B reimbursement for hyperbaric oxygen therapy is diverting refractory radiation cystitis cases from pharmaceutical management. The 340B drug pricing program enables direct manufacturer contracting at cancer centers in Florida and Texas.
Germany
EMA Medical Device Regulation reclassification is forcing cystoscopic device manufacturers to submit clinical evidence packages for legacy catheter designs. Notified bodies in Berlin and Munich are extending review timelines, delaying market access for novel instillation technologies. German urology clinics are consolidating purchases through group purchasing organizations to amortize compliance costs across hospital networks.
France
ANSM oversight of intravesical biologics is tightening post-market surveillance requirements for recombinant growth factor formulations. Paris and Lyon cancer centers are standardizing hyaluronic acid instillation protocols for radiation-induced bladder injury. French procurement departments are unbundling device and pharmaceutical contracts, disrupting previous single-source vendor relationships.
Japan
PMDA accelerated review pathways for supportive cancer care agents are attracting development investment from domestic uro-oncology specialists. Tokyo and Osaka tertiary hospitals are expanding adoption of smart cystoscopic irrigation systems with embedded pressure sensors. Japanese manufacturers are seeking ISO 13485 certification for automated clot evacuation platforms targeting ambulatory surgery centers.
United Kingdom
NICE technology appraisals for hemorrhagic cystitis therapeutics are creating evidence-generation requirements that favor large-scale randomized trials. London and Manchester oncology departments are piloting same-day intravesical therapy protocols to reduce inpatient admission rates. UK procurement frameworks are separating cystoscope purchases from formulation supply agreements.
Pelvic Cancer Induced Hemorrhegic Cystitis Market Competitive Landscape
Global majors compete with regional champions across regulatory certification and hospital channel access, producing a tiered structure where scale-driven pharmaceutical conglomerates share space with uro-oncology specialists. The vendor base organizes around three archetypes: diversified healthcare conglomerates with hospital supply dominance, mid-cap pharmaceutical firms with deep therapeutic specialization, and emerging biotech developers targeting orphan indications. Competitive moves concentrate on strategic partnerships for cystoscopic device-drug combinations and backward integration into active pharmaceutical ingredient supply.
Within the diversified healthcare tier, Johnson & Johnson Services, Inc. and Bayer AG occupy positions anchored by hospital channel infrastructure and manufacturing scale for intravesical formulations. Astellas Pharma Inc. exemplifies the uro-oncology specialist archetype, with its portfolio concentration reflecting deep therapeutic focus rather than horizontal diversification. Lipella Pharmaceuticals Inc. and Urigen Pharmaceuticals Inc. represent the emerging developer segment, sitting within the orphan drug designation pathway where accelerated regulatory timelines offset limited commercial infrastructure.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Astellas Pharma Inc. |
| Sanofi |
| Bayer AG |
| AstraZeneca |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Lipella Pharmaceuticals Inc. |
| Urigen Pharmaceuticals Inc. |
| Others |
Value Network & Pricing Analysis
Alum and hyaluronic acid raw material indices cascade through Chinese API manufacturing into three-tier pricing structures across premium, standard, and economy levels at United States cancer centers. Contract formulators pass commodity volatility into hospital procurement negotiations, with 340B program participants extracting steeper discounts than non-participating institutions.
Pricing Analysis
Input-cost pass-through from alum sulfate and cross-linked hyaluronic acid polymers stratifies pricing across patent-protected biologics, branded formulations, and commodity chemical instillations. Price differentiation hinges on FDA Breakthrough Therapy designation tier and ISO 13485 certification status of companion delivery devices. Cost compression in standard-tier formalin solutions is intensifying because Medicare Part B reimbursement for hyperbaric oxygen therapy diverts refractory cases. Outpatient clinics exhibit highest price sensitivity due to direct purchasing without 340B leverage, while tertiary academic medical centers absorb premium pricing for orphan-designated agents.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturers of alum active pharmaceutical ingredients and German notified bodies for cystoscopic device CE marking under EMA Medical Device Regulation. Raw material dependencies center on alum sulfate from Shandong province, medical-grade hyaluronic acid from Japanese fermentation facilities, and silicone catheter components from Malaysian processors. Tariff exposure on Chinese chemical imports threatens margin stability for United States formulators lacking backward integration. Distribution runs through specialty pharmaceutical distributors serving hospital pharmacy formularies, with ambulatory surgery centers increasingly negotiating direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as oncology departments shift procurement toward hyaluronic acid formulations with extended mucosal dwell times and superior compliance metrics over commodity alternatives.
For Market Incumbents: Lock in cystoscopic device-drug combination exclusivity through ISO 13485 certification investments and hospital GPO contract consolidation. Defend against hyperbaric oxygen therapy substitution by embedding smart irrigation sensors into proprietary instillation protocols. Prioritize captive supply of cross-linked polymer raw materials to insulate margin structures from Chinese API volatility.
For New Entrants and Emerging Players: FDA orphan drug designation in the United States opens a window for biologics developers to compress regulatory timelines while premium pricing persists. Target ambulatory surgery centers in Florida and Texas with same-day therapy protocols that bypass entrenched hospital formularies. Lead with digital health monitoring platforms that satisfy post-market surveillance obligations under Breakthrough Therapy designation.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap uro-oncology specialists possessing deep therapeutic focus rather than diversified pharmaceutical conglomerates. Five-to-ten-year viability favors developers with patent-protected recombinant growth factor pipelines and established hospital channel relationships. Monitor EMA PRIME eligibility announcements as inflection indicators for European market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA pathway compresses development timelines for novel bladder-protective biologics. |
| ISO 13485 Certification Investment | Quality management audits enable cystoscopic device market participation in Europe. |
| Hospital GPO Contract Consolidation | Group purchasing relationships lock in formulary placement against emerging competitors. |
| Digital Health Platform Development | Real-world evidence tracking satisfies post-market surveillance for Breakthrough Therapy agents. |
| Backward Integration into API Supply | In-house polymer production insulates margin structures from Chinese alum volatility. |
Research Methodology
Direct dialogue with uro-oncology specialists, hospital formulary directors, cystoscopic device manufacturers, and specialty pharmaceutical distributors grounded qualitative insights. Secondary validation drew from FDA orphan drug designation filings, EMA PRIME eligibility decisions, ClinicalTrials.gov hemorrhagic cystitis protocols, and CMS Medicare reimbursement databases. Bottom-up prescription volume modeling and top-down hospital procurement expenditure analysis enabled triangulation across the analysis window.
Top-down macroeconomic framing anchored regional demand projections, while bottom-up patient flow analysis through tertiary hospital oncology departments refined segment-level outputs. Modeled dimensions spanned product type, end-user site of care, delivery mode, and application severity, with regulatory pathway clustering as an additional pharmaceutical-specific layer. CAGRs were derived from trajectory fitting across historical Medicare claims data and projected orphan drug approval timelines, incorporating hyaluronic acid formulation adoption curves and hyperbaric oxygen therapy diversion rates as industry-specific inputs.
Revisions become necessary when EMA Medical Device Regulation enforcement intensifies, Chinese API export restrictions materialize, or Medicare reimbursement for hyperbaric oxygen therapy expands substantially. Forecasts reflect documented assumptions about regulatory pathway timelines, hospital procurement centralization, and specialty distributor consolidation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Nocturia Market
Urology
Prostate Cancer Treatment Market
Urology
Global Prostate Cancer Market
Urology
US Urology Devices Market
Urology
Penile Cancer Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Ureteral Obstruction Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Genitourinary Cancers Treatment Market
Urology
Urology Surgery Supplies Market
Urology
Urinary Tract Infection Testing Market
Urology
Europe Bladder Disorders Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Urology Laser Fibers Market
Urology
Ureter Cancer Treatment Market