
 India Urology Device Market | 2026-2036
India Urology Device Market Size, Share, and Industry Trends Forecast 2026-2036
India Urology Device Market Foresight
India's PLI scheme for medical devices is decoupling domestic production from import dependence for high-value urology equipment. Boston Scientific Corporation leverages its endoscopy portfolio to sustain premium positioning in tertiary hospitals across Delhi and Mumbai. Cook Medical anchors its competitive stance through specialized catheter manufacturing capabilities serving chronic urology patients. Karl Storz SE & Co. KG dominates the rigid endoscope segment with optical precision engineering that Indian teaching hospitals prioritize for residency training programs.
Urology devices encompass instruments, endoscopes, catheters, and surgical tools engineered from medical-grade polymers, stainless alloys, and fiber-optic bundles designed for diagnostic visualization and therapeutic intervention within the urinary tract and male reproductive system. These devices operate at sterilization temperatures exceeding 134°C and integrate irrigation channels maintaining 80-150 mmHg pressure for clear operative fields during transurethral procedures. Endoscopes command the highest margin pools due to capital intensity and recurring maintenance contracts, while catheters generate volume-driven revenue through repeat purchases for chronic conditions. Minimally invasive techniques are expanding fastest as hospitals seek shorter patient stays and reduced postoperative complications. Robotic surgery remains concentrated at apex institutions given capital thresholds, though leasing models are broadening access.
CDSCO mandates clinical investigation protocols and quality standards for Class C and D urology devices entering Indian commerce, while BIS certification governs electrical safety and electromagnetic compatibility for powered equipment such as lithotripters and laser systems. State-level hospital procurement guidelines under the Clinical Establishments Act create additional compliance layers that shape vendor qualification and tender participation. Stakeholders must monitor evolving reimbursement pathways under Ayushman Bharat as these determine hospital capital allocation cycles and device upgrade timelines.
Market Dynamics
The PLI scheme for medical devices is restructuring domestic manufacturing economics, pulling catheter and endoscope production away from import-heavy supply chains toward Maharashtra and Karnataka factory clusters.
Growth Catalysts
- Production-Linked Incentive scheme:CDSCO-aligned domestic manufacturing subsidies are compressing cost structures for Class C urology devices, enabling local producers to undercut imported rigid endoscopes by fifteen to twenty percent at tender.
- Tier-I hospital expansion:Mumbai and Delhi tertiary centers are commissioning dedicated robotic surgery suites, creating bundled demand for capital equipment, maintenance contracts, and disposables.
- Optical fiber engineering:Indian teaching hospitals are prioritizing fiber-optic visualization systems for residency programs, locking in recurring replacement cycles for light guides and camera heads.
Market Restraints
- Capital intensity threshold:Robotic surgery platforms require capital commitments that exclude tier-II and district hospitals, concentrating volume in ten to twelve apex institutions.
- Import dependence for core components:High-precision lens assemblies and CMOS sensors remain concentrated in German and Japanese supply chains, exposing domestic assemblers to currency volatility and shipping delays.
- Sterilization protocol rigidity:BIS certification mandates for 134°C autoclave compatibility eliminate polymer formulations common in Southeast Asian manufacturing, restricting material sourcing options.
Strategic Opportunities
- Tier-II city penetration:Pune, Ahmedabad, and Hyderabad are developing specialist urology centers without robotic surgery commitments, creating demand for advanced laparoscopic stacks and flexible cystoscopy systems.
- Ayushman Bharat pathway expansion:Reimbursement coverage for transurethral resection and stone fragmentation procedures is widening addressable patient pools beyond self-pay segments.
- Leasing model innovation:Equipment-as-a-service structures are emerging for lithotripters and laser systems, converting capital expenditure into operational budgets for mid-tier hospitals.
Industry Challenges
- Biomedical engineering talent scarcity:Field service capabilities for rigid endoscope repair and laser calibration remain concentrated in Delhi and Mumbai, creating maintenance backlogs for Bengaluru and Chennai installations.
- CDSCO clinical investigation timelines:Class D device approval protocols require eighteen to twenty-four month validation cycles, delaying product launches behind regulatory clearances obtained in European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Urology Device Market |
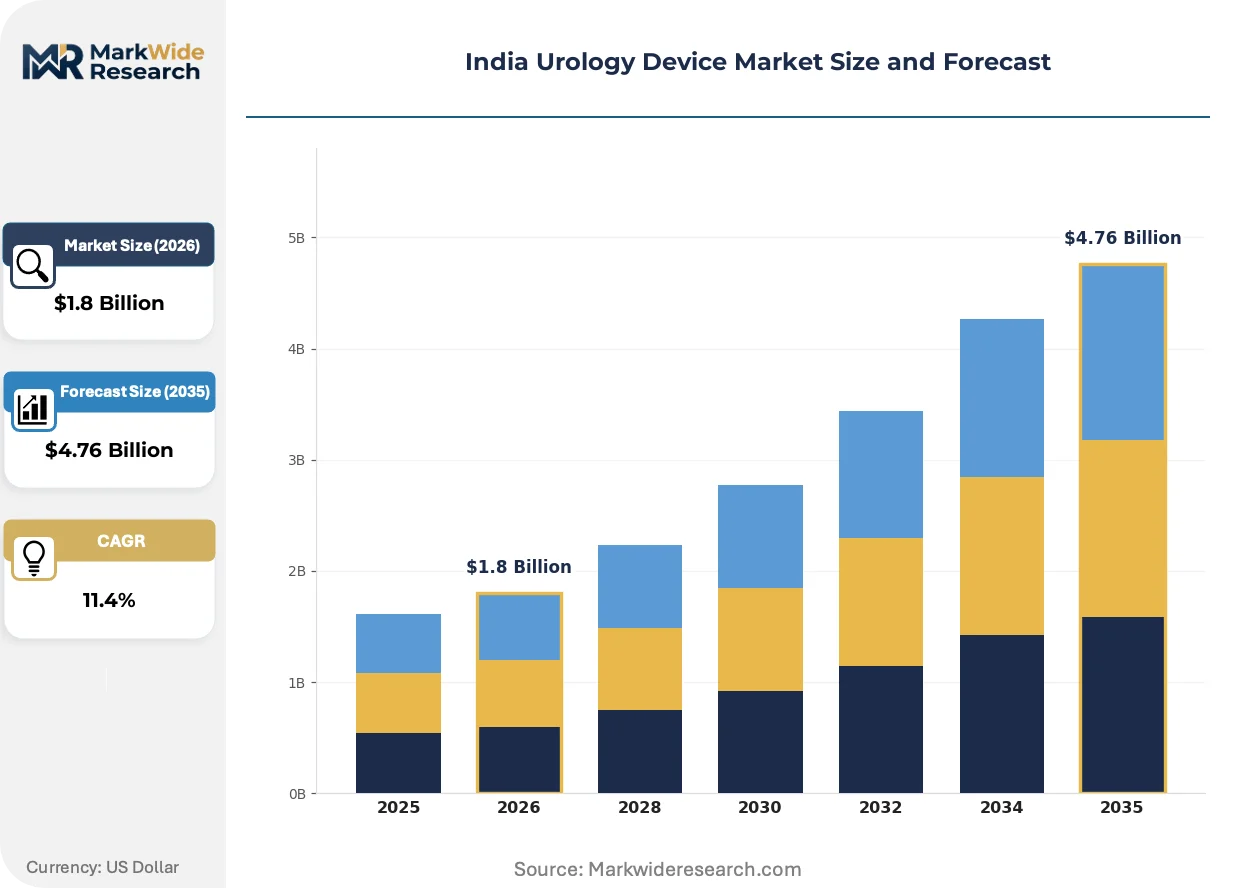
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Catheters, Surgical Instruments, Drainage Bags Application: Kidney Stones, Prostate Cancer, Urinary Incontinence, BPH End User: Hospitals, Clinics, Ambulatory Surgical Centers, Diagnostic Labs Technology: Robotic Surgery, Minimally Invasive Techniques, Laser Therapy, Imaging Technologies |
| Companies Covered | Boston Scientific Corporation, Cook Medical, Olympus Corporation, Stryker Corporation, Medtronic plc, Blue Neem Medical Devices Pvt Ltd, Devon Innovations Private Limited, Karl Storz SE & Co. KG, Coloplast A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Urology Device Market Shifts & Advancements
Digital integration and policy-driven localization are compressing traditional procurement cycles while elevating service contract value in vendor selection criteria.
Single-use flexible cystoscopes are automating reprocessing workflows and infection control protocols in high-throughput outpatient departments. Apollo Hospitals and Max Healthcare are phasing these into ambulatory urology clinics across Delhi NCR, eliminating capital allocation for sterilization infrastructure and reducing turnover time between cases. This shift is automating capacity expansion without parallel facility investment.
CDSCO's 2023 guidance on Unique Device Identification mandates is forcing serialization upgrades across catheter and stent manufacturing lines. Domestic producers in Pune and Bengaluru are retrofitting laser marking systems to comply with traceability requirements, adding per-unit costs that compress margins on high-volume SKUs. The regulation is reshaping competitive positioning toward integrated manufacturing-IT capabilities rather than pure production scale.
Hospital procurement committees are unbundling after-sales service from equipment purchase contracts, creating standalone multi-vendor maintenance agreements. Narayana Health and Fortis networks are consolidating endoscope repair and laser servicing under third-party biomedical engineering firms, displacing manufacturer-captive service teams. This restructuring is most advanced in Maharashtra, where independent service organizations have captured forty percent of maintenance spend for devices outside warranty periods.
India Urology Device Market Segmentation
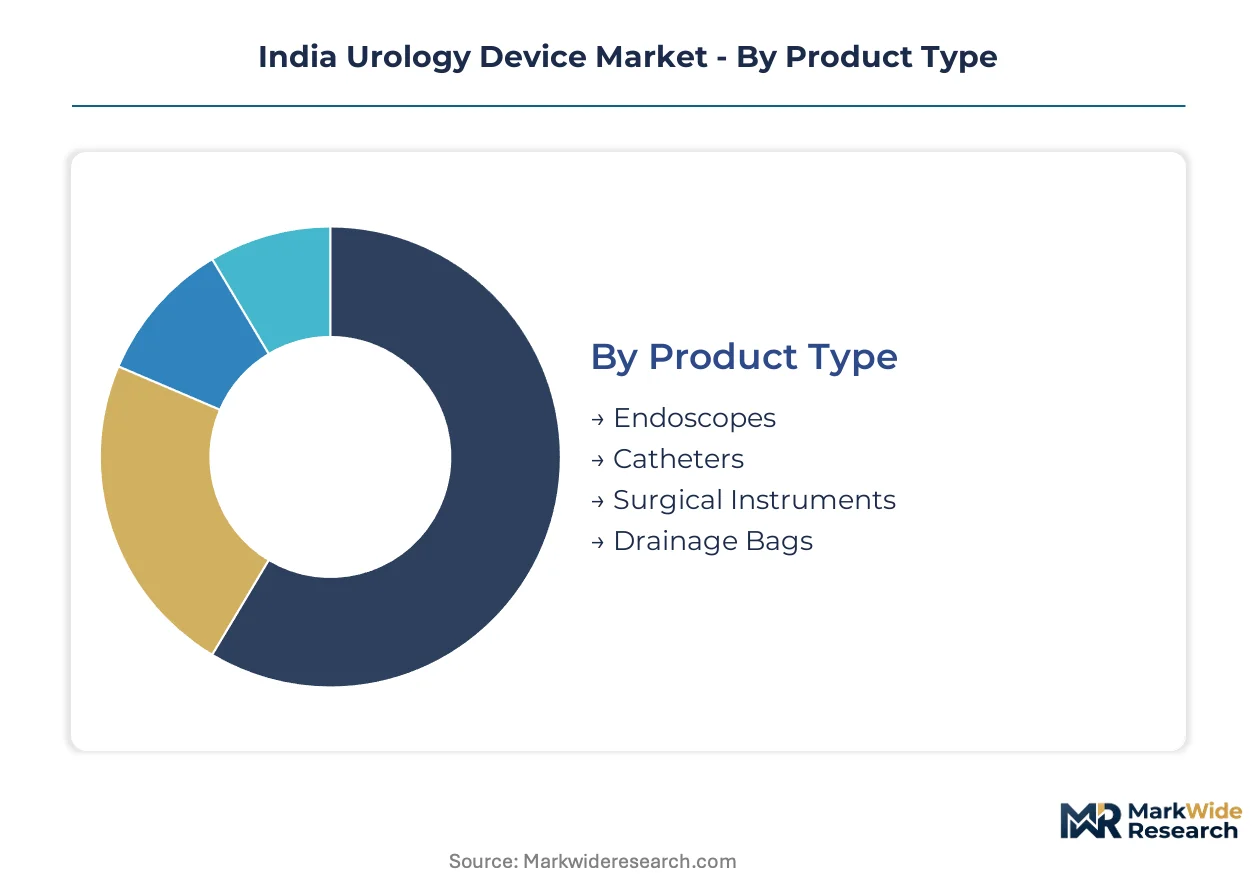
Segmentation in the India urology device market reveals how procurement priorities diverge across care settings and clinical applications. Understanding these divides enables vendors to align R&D investments and distribution strategies with where value pools concentrate.
Product Type:
Capital intensity and replacement cycles separate buyers in this category, with institutions weighing upfront investment against lifetime service costs.
- Endoscopes:Fiber-optic and digital systems built from medical-grade polymers and precision lens assemblies command premium positioning in tertiary hospitals. Mumbai and Delhi teaching centers prioritize rigid cystoscopes and ureteroscopes for residency training, locking in recurring maintenance contracts for light guides and camera heads.
- Catheters:Silicone and latex-based urinary drainage and interventional catheters generate volume-driven revenue through repeat purchases for chronic conditions. Maharashtra and Karnataka specialist centers drive demand for hydrophilic-coated and antimicrobial variants as outpatient procedure volumes climb.
- Surgical Instruments:Forceps, resectoscopes, and stone retrieval baskets fabricated from surgical stainless steel support transurethral and percutaneous procedures.
- Drainage Bags:Closed-system collection units with anti-reflux valves serve postoperative and home-care settings across tier-II city expansions.
Catheters lead volumes today; endoscopes are gaining share fastest as hospital procurement shifts toward bundled capital equipment contracts.
Application:
Prevalence patterns and reimbursement pathways determine where device manufacturers concentrate clinical education and sales resources.
- Kidney Stones:Lithotripsy and ureteroscopic stone management devices address India's rising metabolic syndrome burden. Bengaluru and Hyderabad urology hubs are expanding extracorporeal shock wave lithotriper installations to capture self-pay and Ayushman Bharat-covered patient flows.
- Prostate Cancer:Robotic prostatectomy systems and brachytherapy delivery platforms serve oncology-integrated urology departments. Delhi NCR apex institutions commission da Vinci systems for nerve-sparing procedures, concentrating capital deployment in ten to twelve centers.
- Urinary Incontinence:Sling systems, artificial urinary sphincters, and neuromodulation devices target aging demographics and post-prostatectomy complications.
- BPH:Transurethral resection and vaporization technologies address benign prostatic hyperplasia, the most common urological indication for men over fifty.
Kidney stone interventions dominate procedure counts; prostate cancer applications are expanding most quickly as screening penetration improves in urban centers.
End User:
Capital allocation authority and sterilization infrastructure capacity distinguish procurement behavior across care settings.
- Hospitals:Tier-I institutions in Mumbai and Delhi command robotic surgery suites, endoscopy towers, and comprehensive catheter inventories. CDSCO Class C and D device registrations are mandatory for vendor participation in centralized medical equipment tenders.
- Clinics:Single-use flexible cystoscopes and portable ultrasound systems enable outpatient diagnosis without parallel sterilization investment. Apollo and Max Healthcare ambulatory networks in Delhi NCR are phasing these into urology clinics to compress turnover times.
- Ambulatory Surgical Centers:Focused procedure volumes for stone fragmentation and cystoscopy drive demand for compact lithotripters and day-care anesthesia compatibility.
- Diagnostic Labs:Urinalysis automation and point-of-care testing devices support referral pathways into specialist urology centers.
Hospitals anchor absolute spending; clinics are climbing the fastest as corporate hospital chains unbundle ambulatory services from inpatient platforms.
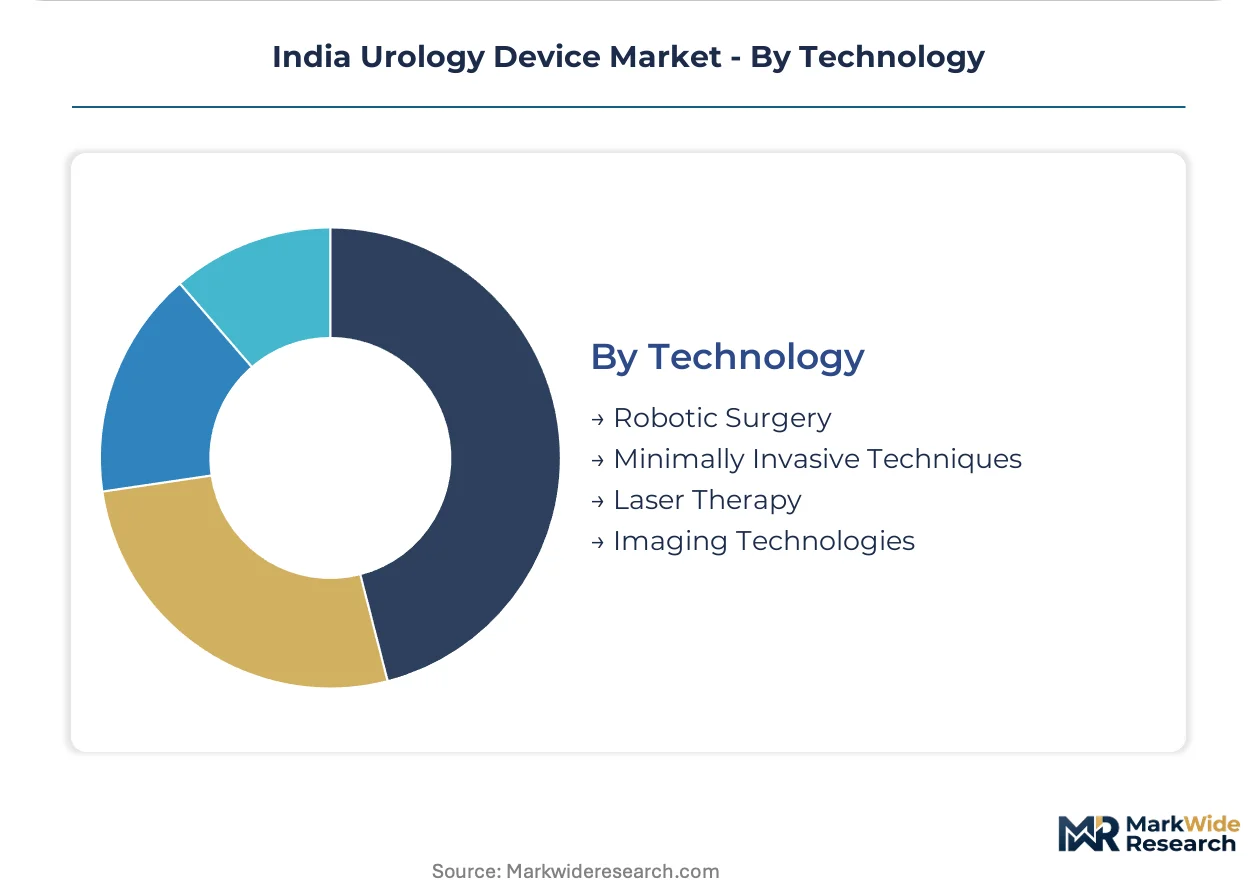
Technology:
Training requirements and maintenance complexity create adoption gradients that favor certain institutional profiles over others.
- Robotic Surgery:Capital-intensive da Vinci and comparable platforms require dedicated operative theaters and specialized surgical teams. Access concentrates at Fortis, Narayana Health, and government tertiary centers where leasing models are converting capital expenditure into operational budgets.
- Minimally Invasive Techniques:Laparoscopic and endourological approaches reduce length of stay and complication rates. Pune and Ahmedabad specialist centers without robotic commitments are prioritizing advanced laparoscopic stacks and flexible cystoscopy systems.
- Laser Therapy:Holmium and thulium laser systems for stone fragmentation and tissue ablation demand precision optics calibration and fiber replacement protocols.
- Imaging Technologies:Fluoroscopy, ultrasound, and CT-integrated navigation support intraoperative guidance and postoperative monitoring.
Minimally invasive techniques command the widest installed base; robotic surgery is advancing most rapidly where equipment-as-a-service structures overcome capital barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The urology device industry in India traces its modern expansion to the 1990s, when Mumbai and Delhi teaching hospitals began importing rigid endoscopes from German manufacturers to establish residency training programs. Maharashtra and Karnataka now anchor domestic production clusters shaped by the PLI scheme.
Maharashtra
Mumbai's apex hospitals commission robotic surgery suites at Fortis and Kokilaben Dhirubhai Ambani Hospital, driving bundled demand for capital equipment and disposables. The state's PLI scheme subsidies enable Pune-based manufacturers to undercut imported rigid endoscopes by fifteen to twenty percent at government tenders. The Mumbai-Pune corridor clusters endoscope assembly and catheter fabrication facilities serving western India.
Karnataka
Bengaluru's specialist urology centers expand extracorporeal shock wave lithotripter installations to capture self-pay and Ayushman Bharat-covered patient flows. CDSCO's Class C and D device registration requirements govern vendor participation in centralized medical equipment tenders issued by the state health department. The Bengaluru-Tumkur industrial zone hosts domestic producers retrofitting laser marking systems for Unique Device Identification compliance.
Delhi-NCR
Apollo and Max Healthcare networks phase single-use flexible cystoscopes into ambulatory urology clinics across Delhi NCR, eliminating capital allocation for sterilization infrastructure. BIS certification mandates for 134°C autoclave compatibility restrict polymer sourcing options for equipment entering this market. The region concentrates ten to twelve apex institutions with da Vinci robotic platforms for nerve-sparing prostatectomy procedures.
Telangana
Hyderabad develops specialist urology centers without robotic surgery commitments, creating demand for advanced laparoscopic stacks and flexible cystoscopy systems. The state's hospital procurement guidelines under the Clinical Establishments Act create compliance layers that shape vendor qualification for tenders. The Hyderabad medical device park attracts catheter manufacturers seeking CDSCO-aligned production infrastructure.
Gujarat
Ahmedabad's corporate hospital chains consolidate endoscope repair and laser servicing under third-party biomedical engineering firms, displacing manufacturer-captive service teams. DGFT import policies expose domestic assemblers to currency volatility for high-precision lens assemblies concentrated in German supply chains. The Ahmedabad-Vadodara belt emerges as a maintenance hub for devices outside warranty periods.
India Urology Device Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the India urology device market. The vendor base separates into integrated multinationals with captive manufacturing and domestic assemblers relying on component imports. Three archetypes dominate: German-Japanese precision optics specialists, American diversified medtech conglomerates, and PLI-subsidized Indian contract manufacturers. Competitive moves concentrate on multi-vendor maintenance agreements and equipment-as-a-service leasing structures that convert hospital capital expenditure into operational budgets.
Within the precision optics tier, Karl Storz SE & Co. KG and Olympus Corporation exemplify engineering-led positioning that Indian teaching hospitals prioritize for residency training programs. Among American diversified players, Boston Scientific Corporation and Stryker Corporation occupy positions sustained through premium endoscopy portfolios and bundled service contracts. At the domestic manufacturing end, Blue Neem Medical Devices Pvt Ltd and Devon Innovations Private Limited represent PLI scheme beneficiaries compressing cost structures for standard catheter and endoscope lines.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Cook Medical |
| Olympus Corporation |
| Stryker Corporation |
| Medtronic plc |
| Blue Neem Medical Devices Pvt Ltd |
| Devon Innovations Private Limited |
| Karl Storz SE & Co. KG |
| Coloplast A/S |
| Others |
Supply & Pricing Matrix
Medical-grade stainless steel alloy indices and polymer feedstock benchmarks cascade through catheter and endoscope manufacturing into three distinct procurement tiers across Indian hospital systems. Maharashtra and Karnataka factory clusters leverage PLI scheme subsidies to compress domestic production costs, while imported German and Japanese precision optics sustain premium positioning in Mumbai and Delhi teaching hospitals.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs vendor positioning in Indian urology device procurement. Premium tiers command price multiples based on CDSCO Class D registration status and bundled multi-year service contracts, while standard tiers compete on BIS certification compliance and domestic assembly scale. Cost compression in economy catheter lines is intensifying because Pune-based manufacturers are undercutting imported alternatives at state government tenders. Tier-II city hospitals exhibit highest price sensitivity due to constrained capital budgets, whereas apex institutions in Delhi NCR prioritize optical performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by hospital procurement committees under the Clinical Establishments Act force qualified vendor lists spanning German, Japanese, and emerging Indian component suppliers. High-precision lens assemblies and CMOS sensors draw from German and Japanese optical engineering clusters, while medical-grade silicone and polymer extrusions feed from domestic Maharashtra and Karnataka chemical processing hubs. Single-source vulnerability concentrates in fiber-optic bundle manufacturing, exposing maintenance contract fulfillment to shipping delays. Distribution runs through state-level medical equipment tenders and GPO contracts managed by corporate hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's urology device market functions as a regulatory compounder where CDSCO's Unique Device Identification mandate and PLI scheme subsidies are accelerating domestic manufacturing qualification and hospital procurement restructuring.
For Market Incumbents: Anchor service contract value through captive biomedical engineering teams in Bengaluru and Chennai, countering third-party maintenance firms that have captured forty percent of post-warranty spend in Maharashtra. Deepen backward integration into polymer compounding and lens assembly to reduce exposure to German and Japanese currency volatility, while securing CDSCO Class D registrations ahead of tender eligibility deadlines. For New Entrants and Emerging Players: Capture white-space demand in Hyderabad, Ahmedabad, and Pune specialist urology centers that are expanding laparoscopic capacity without robotic surgery commitments. Tier-II city outpatient clinics represent the most penetrable segment, where single-use flexible cystoscopes eliminate sterilization infrastructure requirements. Pursue equipment-as-a-service leasing structures that convert hospital capital expenditure into operational budgets. For Investors and Strategic Acquirers: Asymmetric upside sits with PLI-subsidized domestic manufacturers possessing integrated laser marking and serialization capabilities for UDI compliance. The five-to-ten year viability window favors contract manufacturers with captive CDSCO-aligned production infrastructure over pure import-assemblers. Monitor Ayushman Bharat reimbursement pathway expansion as the inflection signal for hospital capital allocation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class D Registration Pathway | Mandatory qualification for participation in centralized government tenders issued by Maharashtra and Karnataka health departments. |
| Hospital System Partnership | Apollo and Max Healthcare networks prioritize single-use cystoscope suppliers that eliminate sterilization infrastructure requirements. |
| Backward Integration into Polymer Compounding | Pune-based manufacturers reduce import dependence for medical-grade silicone formulations subject to BIS autoclave compatibility mandates. |
| Equipment-as-a-Service Leasing Model | Fortis and Narayana Health convert lithotripter and laser system procurement from capital budgets to operational expenditure lines. |
| Biomedical Engineering Capability Buildout | Independent service organizations capture maintenance spend by consolidating endoscope repair and laser calibration under multi-vendor agreements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and CDSCO regulatory affairs specialists with secondary validation against hospital procurement databases, GPO contract disclosures, and BIS certification registries. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Segment-weighting approaches distributed value and volume projections across product type, application, end user, and technology dimensions, with additional granularity for state-level regulatory clusters under the Clinical Establishments Act. CAGRs derived from procedure volume trajectories, equipment replacement cycles, and reimbursement pathway expansion under Ayushman Bharat. Forecast inputs incorporated PLI scheme subsidy absorption rates and domestic manufacturing capacity commissioning timelines.
Underlying measurement precision varies by segment; catheter and drainage bag volumes carry tighter precision than robotic surgery platform installations given capital commitment disclosure lags. Forecasts reflect documented assumptions regarding CDSCO approval timelines, state tender participation rates, and polymer feedstock cost stability. Deviation in Ayushman Bharat reimbursement coverage expansion or PLI scheme extension would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Urology Robotic Surgery Market
Urology
Continence Care Market
Urology
Nordic Urinary Catheters Market
Urology
Urinary Catheters Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Ureteral Obstruction Market
Urology
Europe Urology Devices Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Urinary Retention Therapeutics Market
Urology
Disposable Ureteroscope Market
Urology
Penile Cancer Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Urology Lasers Market