
 Prostatic Arterial Embolization (PAE) Market | 2026-2036
Prostatic Arterial Embolization (PAE) Market Size, Share, and Industry Trends Forecast 2026-2036
Prostatic Arterial Embolization (PAE) Market Analytics
Aftermarket service revenue for imaging systems and embolic delivery platforms is rewriting profit dynamics across the PAE supply chain. Merit Medical Systems leverages its integrated catheter and embolic agent portfolios to sustain recurring instrument sales. Siemens Healthineers anchors the high-end imaging segment with angiography systems purpose-built for pelvic arterial mapping. Boston Scientific competes through specialized microcatheter designs that navigate tortuous prostatic vasculature with reduced fluoroscopy time.
Prostatic arterial embolization is a minimally invasive interventional radiology procedure involving selective catheterization of prostatic arteries and injection of embolic agents—typically polyvinyl alcohol particles or calibrated microspheres 100–300 μm in diameter—to induce ischemic volume reduction of enlarged prostate tissue. The technique serves patients with lower urinary tract symptoms from benign prostatic hyperplasia who seek alternatives to surgical resection or long-term pharmacotherapy. Embolic agents command the deepest margin pools due to single-use consumption per procedure and limited generic substitution, while minimally invasive delivery modes are expanding fastest as ambulatory surgical centers build same-day discharge capabilities. Imaging systems represent the most mature segment, with replacement cycles extending as software upgrades defer capital purchases.
FDA 510(k) clearance requirements for embolic agents and delivery catheters shape product development timelines and clinical evidence burdens for manufacturers seeking US market access. EMA medical device regulation and ISO 13485 quality management standards govern European commercialization, with notified body conformity assessments adding certification layers for embolic particle characterization. CMS national coverage determinations and local coverage article updates directly influence hospital procurement decisions and physician practice revenue. Stakeholders must monitor evolving payer evidence requirements for symptom improvement durability beyond twelve months.
Market Dynamics
CMS reimbursement pathway clarifications are compressing the decision timeline for hospital procurement committees evaluating PAE program investments, while ambulatory surgical centers race to capture same-day discharge volumes before academic medical centers consolidate market position.
Growth Catalysts
- IR Training Infrastructure:Germany's interventional radiology fellowship pipelines and prostate-focused clinical pathways generate higher procedural throughput than peer European markets, creating a template for capacity expansion.
- Outpatient Migration:Ambulatory surgical centers in the United States are building dedicated pelvic angiography suites to capture Medicare reimbursement for same-day PAE procedures.
- Embolic Agent Innovation:Calibrated microsphere formulations with 100–300 μm diameter precision are reducing non-target embolization rates and expanding treatable patient anatomy.
Market Restraints
- Capital Equipment Concentration:Angiography system supply chains concentrate among three dominant imaging OEMs, creating procurement bottlenecks for mid-tier hospitals.
- Reimbursement Latency:Private payor prior authorization requirements in the United States impose 30-90 day delays that compress physician practice cash flow.
- Technical Anatomical Limitations:Tortuous prostatic arterial origins in 15-20% of patients prevent selective catheterization, forcing conversion to pharmacotherapy or surgical alternatives.
Strategic Opportunities
- Underpenetrated Asia-Pacific:Japan's aging male population and PMDA regulatory clarity create a procedural volume expansion corridor exceeding European growth rates.
- Technology Convergence:Fusion of cone-beam CT with digital subtraction angiography is collapsing procedural time and radiation exposure in high-volume centers.
- Channel Innovation:Direct-to-physician embolic agent distribution platforms are bypassing traditional hospital purchasing committees in outpatient settings.
Industry Challenges
- Interventional Radiology Workforce Gap:Prostatic arterial catheterization demands sub-millimeter wire manipulation skills that fewer than 8% of practicing interventional radiologists perform regularly.
- CMS Evidence Requirements:National coverage determinations mandate 12-month durability data that most existing trials fail to capture, freezing market access for new embolic formulations.
- Integration Complexity:PAE workflow integration with existing urology practice management systems requires custom HL7 interface development that stretches IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prostatic Arterial Embolization (PAE) Market |
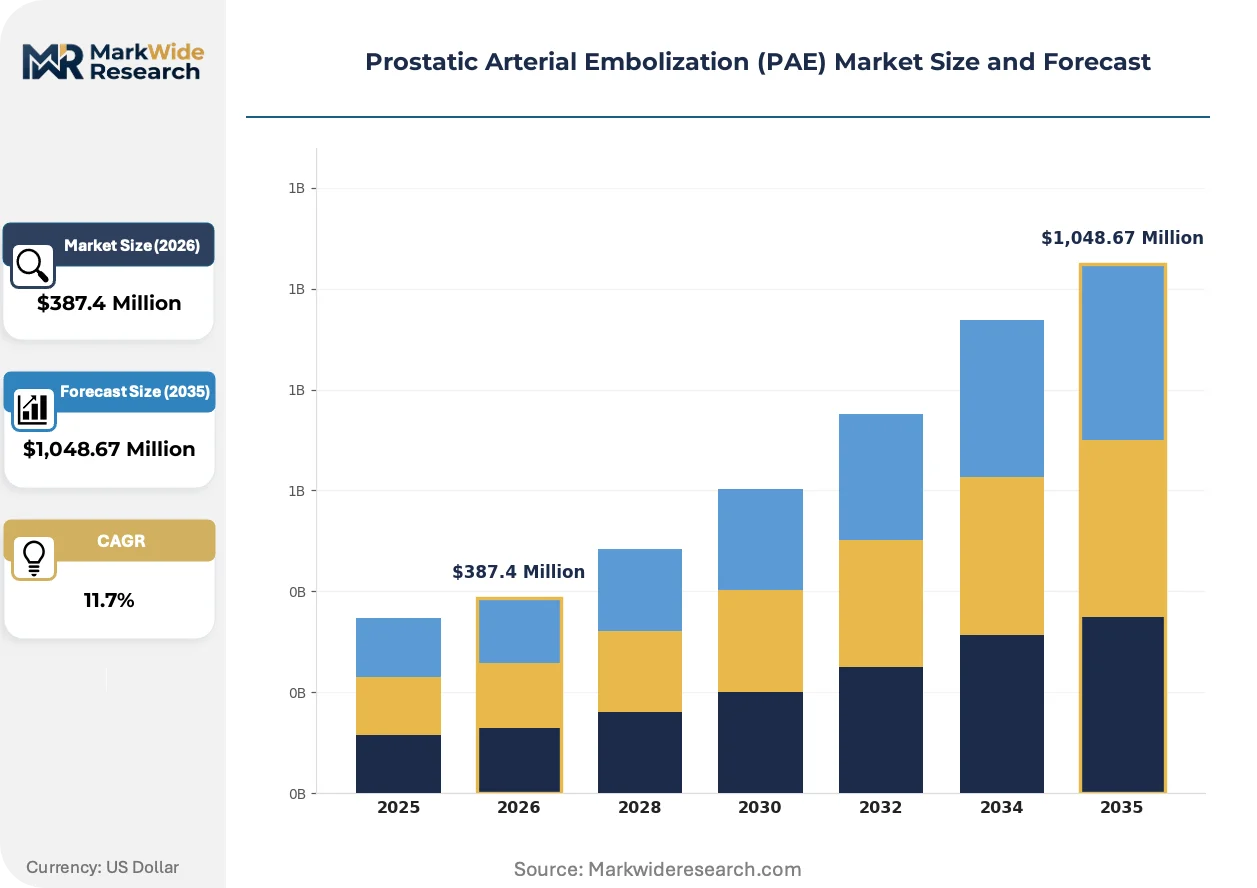
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $1,048.67 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embolic Agents, Catheters, Guide Wires, Imaging Systems Application: Benign Prostatic Hyperplasia, Oncological Procedures, Diagnostic Imaging, Interventional Radiology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Delivery Mode: Invasive, Minimally Invasive, Outpatient, Inpatient |
| Companies Covered | Merit Medical Systems, Boston Scientific, Mentice, Siemens Healthineers, Terumo, General Electric, Embolx, QXMedical, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prostatic Arterial Embolization (PAE) Market Evolving Landscape
Real-time imaging guidance and embolic delivery precision are compressing the gap between diagnostic angiography and therapeutic outcome, while reimbursement policy and procurement behavior reshape where procedures occur.
Calibrated microsphere embolic agents with narrow size distribution are collapsing the distinction between diagnostic pelvic angiography and definitive PAE therapy. Academic medical centers in Germany and the United States are adopting these formulations for same-day discharge protocols. The technology is collapsing average procedure time from 90 minutes to under 45 minutes in high-volume practices.
EMA Medical Device Regulation (MDR) conformity assessment requirements for embolic particle characterization are extending certification timelines by 12-18 months for manufacturers without established notified body relationships. European hospitals are delaying procurement decisions until MDR-compliant inventory reaches distribution channels. The regulatory friction is most acute for mid-tier embolic agent suppliers lacking legacy CE mark grandfathering.
Urology department purchasing committees are unbundling after-sales service contracts from capital equipment procurement, forcing imaging OEMs to compete on hardware margin alone. Ambulatory surgical centers in the United States are driving this behavior through direct ownership models that exclude traditional hospital service agreements. The shift is most visible in Texas and Florida markets where physician-owned specialty facilities concentrate.
Prostatic Arterial Embolization (PAE) Market Segmentation
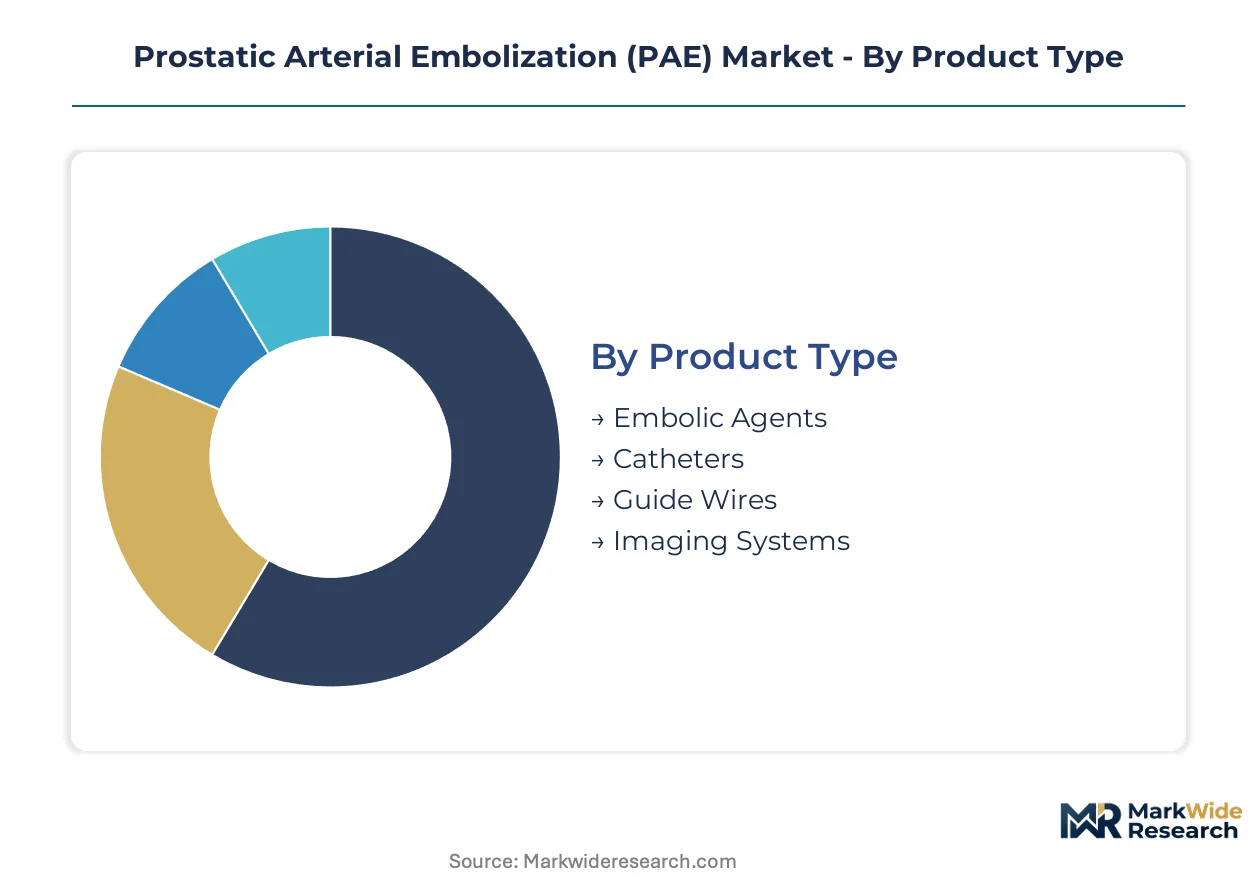
PAE market segmentation reveals distinct margin profiles across consumables versus capital equipment, with embolic agents generating recurring revenue streams while imaging systems anchor long-term procurement cycles. Understanding these segment dynamics illuminates where supply chain power concentrates and where clinical adoption accelerates.
Product Type:
Cost tier differentiation separates single-use consumables from durable capital platforms, with procurement committees evaluating lifetime cost of ownership against per-procedure economics.
- Embolic Agents:Polyvinyl alcohol particles and calibrated microspheres 100–300 μm in diameter constitute the procedure's therapeutic core, with narrow size distribution formulations commanding premium positioning. Demand concentrates in Germany and the United States where same-day discharge protocols prioritize embolic precision over cost minimization. Single-use consumption per procedure sustains recurring revenue pools that resist generic substitution pressure.
- Catheters:Specialized microcatheter designs navigate tortuous prostatic vasculature with reduced fluoroscopy exposure, integrating hydrophilic coatings and distal tip flexibility specifications. Merit Medical Systems and Boston Scientific compete through proprietary lumen geometries that collapse procedural time in high-volume interventional radiology practices. German academic medical centers drive specification requirements through prostate-focused clinical pathway standardization.
- Guide Wires:Sub-millimeter diameter wires with torque-responsive cores enable selective prostatic arterial catheterization in anatomically challenging cases.
- Imaging Systems:Angiography platforms with pelvic arterial mapping software represent the most mature segment, with replacement cycles extending as software upgrades defer capital purchases.
Embolic agents hold installed capacity. Catheters are rotating up the share rankings.
Application:
Clinical indication breadth spans symptomatic relief through oncological intervention, with reimbursement pathways diverging sharply between established BPH coverage and emerging cancer applications.
- Benign Prostatic Hyperplasia:Lower urinary tract symptom management drives the preponderance of procedural volume, with CMS national coverage determinations and private payor prior authorization frameworks shaping access. The United States and Germany concentrate demand where outpatient migration and interventional radiology training infrastructure align. Symptom improvement durability requirements beyond twelve months increasingly influence payer evidence demands.
- Oncological Procedures:Prostate cancer applications remain investigational, with clinical trials exploring embolization for localized disease and palliative symptom control. Japan's PMDA regulatory clarity and aging male population create procedural volume expansion potential exceeding European growth benchmarks. Reimbursement latency constrains near-term commercial penetration relative to BPH indications.
- Diagnostic Imaging:Pelvic angiography for treatment planning and follow-up assessment supports procedural workflow integration.
- Interventional Radiology:Training program expansion and fellowship pipeline development in Germany generate higher procedural throughput than peer European markets.
BPH anchors current revenue. Oncological procedures are gaining share fastest.
End User:
Facility type determines reimbursement capture, capital deployment requirements, and integration complexity with existing urology practice management systems.
- Hospitals:Academic medical centers anchor complex case referrals and training program development, with urology department purchasing committees unbundling after-sales service contracts from capital equipment procurement. Texas and Florida markets exhibit pronounced physician-owned specialty facility concentration that pressures traditional hospital service agreement structures. HL7 interface development requirements stretch IT budgets for PAE workflow integration.
- Ambulatory Surgical Centers:Same-day discharge capabilities align with Medicare reimbursement pathways, driving dedicated pelvic angiography suite construction. Direct-to-physician embolic agent distribution platforms bypass traditional hospital purchasing committees in outpatient settings. Prior authorization delays impose 30-90 day cash flow compression that favors established high-volume operators.
- Specialty Clinics:Urology-focused practices integrate PAE as an outpatient alternative to transurethral resection.
- Research Institutions:Clinical trial infrastructure supports embolic formulation innovation and long-term durability data collection for CMS evidence requirements.
Hospitals hold installed capacity. Ambulatory surgical centers are rotating up the share rankings.
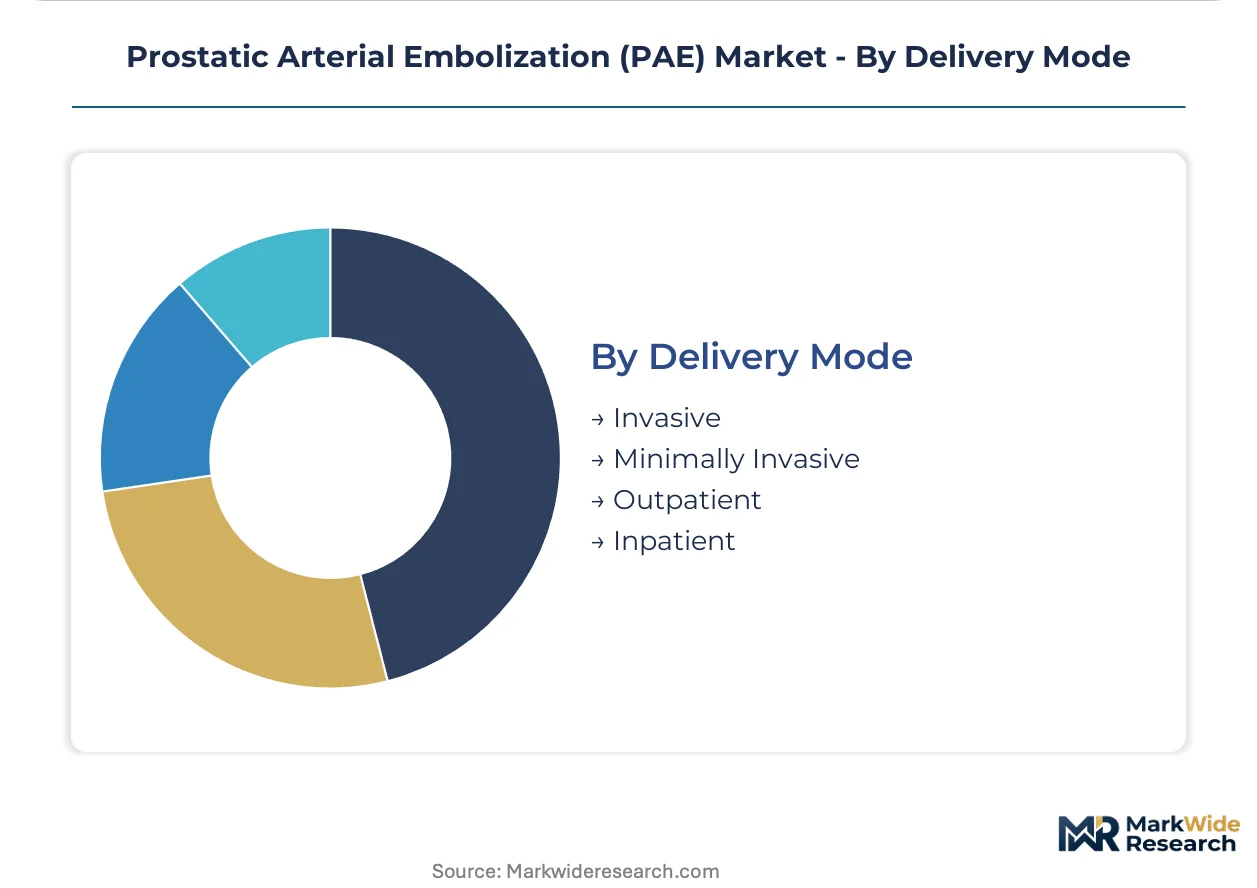
Delivery Mode:
Care setting migration from inpatient to outpatient channels rewrites procurement behavior and reimbursement economics across the PAE supply chain.
- Minimally Invasive:Same-day discharge protocols collapse average procedure time from 90 minutes to under 45 minutes in high-volume practices, with calibrated microsphere formulations enabling precision embolization. Ambulatory surgical centers in the United States race to capture Medicare reimbursement volumes before academic medical centers consolidate market position. Cone-beam CT fusion with digital subtraction angiography reduces radiation exposure and procedural time.
- Outpatient:Direct ownership models exclude traditional hospital service agreements, forcing imaging OEMs to compete on hardware margin alone. CMS reimbursement pathway clarifications compress decision timelines for facility investment committees. Channel innovation through direct-to-physician distribution platforms accelerates in Texas and Florida markets.
- Invasive:Conventional surgical alternatives persist for anatomically unfavorable cases where tortuous prostatic arterial origins prevent selective catheterization.
- Inpatient:Reserved for complex cases requiring overnight observation or conversion management.
Minimally invasive holds installed capacity. Outpatient delivery is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply chains for embolic agents and angiography systems concentrate among German interventional radiology training hubs and United States outpatient migration corridors. Manufacturers prioritize notified body relationships in Europe and FDA 510(k) pathway experience in North America. Clinical evidence generation follows distinct regulatory timelines across jurisdictions.
United States
CMS national coverage determinations and private payor prior authorization frameworks shape hospital procurement decisions. The FDA 510(k) clearance pathway governs embolic agent and microcatheter commercialization timelines. Texas and Florida markets exhibit pronounced ambulatory surgical center construction for same-day discharge protocols.
Germany
Interventional radiology fellowship pipelines generate higher procedural throughput than peer European markets. EMA Medical Device Regulation conformity assessments extend certification timelines for embolic particle characterization. Academic medical centers in Bavaria and North Rhine-Westphalia drive prostate-focused clinical pathway standardization.
Japan
Aging male demographics and lower urinary tract symptom prevalence expand addressable patient populations. PMDA regulatory clarity for minimally invasive prostate interventions accelerates clinical trial infrastructure investment. The Kanto region around Tokyo anchors high-volume interventional radiology practice development.
United Kingdom
NICE technology appraisal pathways influence NHS commissioning decisions for novel BPH interventions. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment requirements for embolic device suppliers. London and Southeast England concentrate urology department purchasing committee activity.
Australia
TGA medical device inclusion requirements shape embolic agent import and distribution economics. Medicare Benefits Schedule updates determine physician reimbursement for outpatient pelvic angiography procedures. New South Wales and Victoria lead interventional radiology workforce training program expansion.
Prostatic Arterial Embolization (PAE) Market Competitive Landscape
Integrated imaging-embolic portfolios and specialized catheter engineering split the market between capital equipment anchoring and consumable precision plays. Three strategic archetypes dominate: diversified medtech conglomerates with angiography system installed bases, interventional radiology consumable specialists with recurring revenue models, and simulation-training hybrids addressing workforce skill gaps. Competitive moves concentrate on M&A for embolic formulation capabilities and strategic partnerships for cone-beam CT fusion technology licensing.
Within the diversified medtech tier, Siemens Healthineers and General Electric exemplify capital equipment anchoring through angiography platform installed bases. Merit Medical Systems and Boston Scientific occupy positions as interventional radiology consumable specialists, with the former representing integrated catheter-embolic portfolio breadth and the latter exemplifying microcatheter design precision for tortuous vasculature navigation.
| Leading Market Players |
|---|
| Merit Medical Systems |
| Boston Scientific |
| Mentice |
| Siemens Healthineers |
| Terumo |
| General Electric |
| Embolx |
| QXMedical |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
Undercapacity in German interventional radiology training pipelines drives both supplier premium capture and hospital procurement urgency, as academic medical centers compete for limited catheter and embolic agent inventory while ambulatory surgical centers bid up spot pricing for same-day discharge capacity.
Pricing Analysis
After-sales service contracts for angiography systems anchor lifetime value calculations, with imaging OEMs unbundling maintenance tiers to compete on hardware margin alone. Pricing stratifies across premium calibrated microspheres, standard polyvinyl alcohol particles, and economy uncalibrated formulations differentiated by size distribution precision and FDA 510(k) clearance status. Cost compression in the economy tier intensifies as mid-tier hospitals defer capital purchases and stretch consumable budgets. Ambulatory surgical centers exhibit highest price sensitivity due to direct ownership models, while academic medical centers prioritize embolic precision over cost minimization.
Supply Chain Analysis
Single-source vulnerability for 100–300 μm calibrated microspheres concentrates risk among German and United States manufacturing hubs, with EMA MDR conformity assessments extending lead times for European distribution. Polymer feedstocks for microsphere production draw from petrochemical complexes in Germany, Belgium, and the Netherlands, while nitinol wire for torque-responsive catheter cores sources from specialized metallurgical suppliers in the United States and Japan. Tariff exposure between the United States and China disrupts ancillary component sourcing for imaging system software modules. Distribution runs through direct-to-physician platforms in outpatient settings and GPO contracts in hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PAE market expansion represents high-growth disruption justified by CMS reimbursement pathway clarifications that collapsed hospital procurement decision timelines from years to months.
For Market Incumbents: Pre-empt workforce scarcity threats by embedding training simulators into catheter and embolic agent bundles, locking interventional radiology fellowship programs into proprietary ecosystems. Acquire cone-beam CT fusion technology licenses before imaging OEMs consolidate software integration capabilities. Backward integration into polymer microsphere manufacturing secures supply continuity against EMA MDR certification bottlenecks. For New Entrants and Emerging Players: Pursue Japan's PMDA-cleared oncological procedure segment where reimbursement latency has frozen incumbent investment and clinical trial infrastructure remains underdeveloped. Target physician-owned specialty facilities in Texas and Florida with direct distribution models that bypass hospital purchasing committees. Lead with calibrated microsphere formulations sized for cancer applications as the differentiated entry wedge. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across ambulatory surgical center delivery modes as equipment leasing and direct-to-physician distribution reduce fixed asset requirements. Five-to-ten year viability favors consumable-specialist acquisition targets with recurring revenue models and established notified body relationships for EMA MDR compliance. Watch CMS national coverage determination updates for symptom durability evidence requirements as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR conformity assessments for microsphere characterization extend certification timelines and freeze procurement decisions. |
| Hospital System Partnership | Urology department purchasing committees in Germany and the United States unbundle service contracts and demand hardware-only pricing. |
| Software Companion Development | Cone-beam CT fusion with digital subtraction angiography collapses procedural time and radiation exposure in high-volume centers. |
| Reimbursement Strategy | CMS national coverage determinations mandate twelve-month durability data that most existing trials fail to capture. |
| Geographic Expansion | Japan's PMDA regulatory clarity and aging male population create procedural volume expansion corridors exceeding European benchmarks. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with interventional radiologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers; and secondary validation against FDA 510(k) filings, EMA MDR submission databases, CMS national coverage determinations, and hospital procurement records. Bottom-up procedure volume estimates triangulated with top-down imaging system installed base calculations.
Forecast inputs incorporated procedure migration patterns across delivery modes, reimbursement pathway evolution, and interventional radiology workforce pipeline expansion. Segmentation dimensions modeled include product type, clinical indication, facility type, and delivery mode alongside regional regulatory cluster differentiation. CAGRs derived from logistic adoption curves fitted to historical procedural volume data and payer coverage expansion timelines.
Sensitivities concentrate around CMS durability evidence requirement revisions, EMA MDR certification timeline extensions, and interventional radiology fellowship graduation rates. Forecasts embed assumptions regarding outpatient migration velocity and ambulatory surgical center construction permitting. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Castrate Resistant Prostate Cancer Market
Urology
Urinary Bag Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Self-Intermittent Catheters Market
Urology
Global Bladder Cancer Market
Urology
Ureter Cancer Treatment Market
Urology
Uropathy Treatment Market
Urology
Urology Ultrasound Market
Urology
Nordic Urinary Catheters Market
Urology
Global Bladder Scanner Market
Urology
North America Transrectal Ultrasound Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
North America Bladder Disorders Market
Urology
Nocturia Market
Urology
Hematuria Treatment Market
Urology
Global Prostate Health Market