
 Nocturia Market | 2026-2036
Nocturia Market Size, Share, and Industry Trends Forecast 2026-2036
Nocturia Market Outlook
Urology-geriatrics cross-training capacity is collapsing across major health systems, creating bottlenecks in nocturia diagnosis and therapy initiation. Ferring Pharmaceuticals leverages its desmopressin franchise to sustain European hospital formulary presence. Astellas Pharma Inc. anchors Japanese urology channels with established nocturia portfolios. AbbVie Inc. competes through broader pelvic health R&D intensity that extends into adjacent lower urinary tract indications.
Nocturia describes the clinical condition of waking one or more times nightly to void, with each episode preceded and followed by sleep, typically quantified through bladder diary frequency-volume charts and nocturnal polyuria indices. The condition originates from nocturnal polyuria, diminished nocturnal bladder capacity, or mixed etiologies, requiring differentiated pharmacological or behavioral intervention. Prescription medications dominate value capture where antidiuretic and antimuscarinic therapies command reimbursement premiums, while over-the-counter solutions expand volume through pharmacy self-selection. Retail pharmacies remain the margin-rich core channel for chronic nocturia therapy fulfillment, though online platforms are gaining script conversion among mobility-limited geriatric patients and their caregivers.
The FDA regulates nocturia drug candidates through its Division of Urology, Obstetrics and Gynecology, while the EMA's Committee for Medicinal Products for Human Use shapes European approval standards for antidiuretic therapies. Japan's PMDA maintains distinct efficacy endpoints for nocturnal polyuria that influence regional trial design and label claims. Stakeholders must monitor how FDA guidance on digital therapeutics for bladder training intersects with CMS reimbursement decisions for connected care devices, as this convergence will determine whether technology-enabled behavioral interventions achieve parity with pharmaceutical coverage.
Market Dynamics
Urology-geriatrics cross-training capacity is collapsing across major health systems, creating bottlenecks in nocturia diagnosis and therapy initiation that pharmaceutical and device manufacturers must navigate through alternative channel strategies.
Growth Catalysts
- Japan's PMDA efficacy endpoints:Distinct regulatory pathways for nocturnal polyuria therapies accelerate regional trial completion and label differentiation for antidiuretic drug developers.
- Geriatric clinic expansion:Screening protocol adoption across German, Japanese, and American hospital networks pulls undiagnosed patients into formal treatment pathways.
- Digital therapeutics guidance:FDA Division of Urology positioning on connected bladder training devices creates reimbursement precedent for technology-enabled behavioral interventions.
Market Restraints
- Antidiuretic safety thresholds:FDA cardiovascular risk requirements for desmopressin analogues limit dose escalation and expand post-market surveillance obligations.
- Specialist concentration:Urologist-geriatrician co-location remains concentrated in Tokyo, Berlin, and Boston metropolitan clusters, constraining rural and secondary market access.
- Behavioral therapy substitution:Sleep hygiene and fluid restriction protocols compete with pharmacological solutions in primary care settings where reimbursement favors non-prescription approaches.
Strategic Opportunities
- Online pharmacy conversion:Mobility-limited geriatric patients and their caregivers are shifting script fulfillment from retail to digital platforms, opening direct-to-patient channel control.
- EMA antidiuretic harmonization:Committee for Medicinal Products for Human Use standardization efforts may streamline multi-country European hospital formulary access.
- CMS connected care decisions:Reimbursement parity between pharmaceutical and technology-enabled behavioral coverage would unlock Medicare Advantage plan contracting for integrated nocturia management.
Industry Challenges
- Bladder diary compliance:Patient adherence to frequency-volume chart documentation undermines diagnostic accuracy and therapy titration across all treatment modalities.
- Urology-geriatrics workforce pipeline:Fellowship program output fails to match screening protocol expansion, extending time-to-diagnosis in expanded access markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nocturia Market |
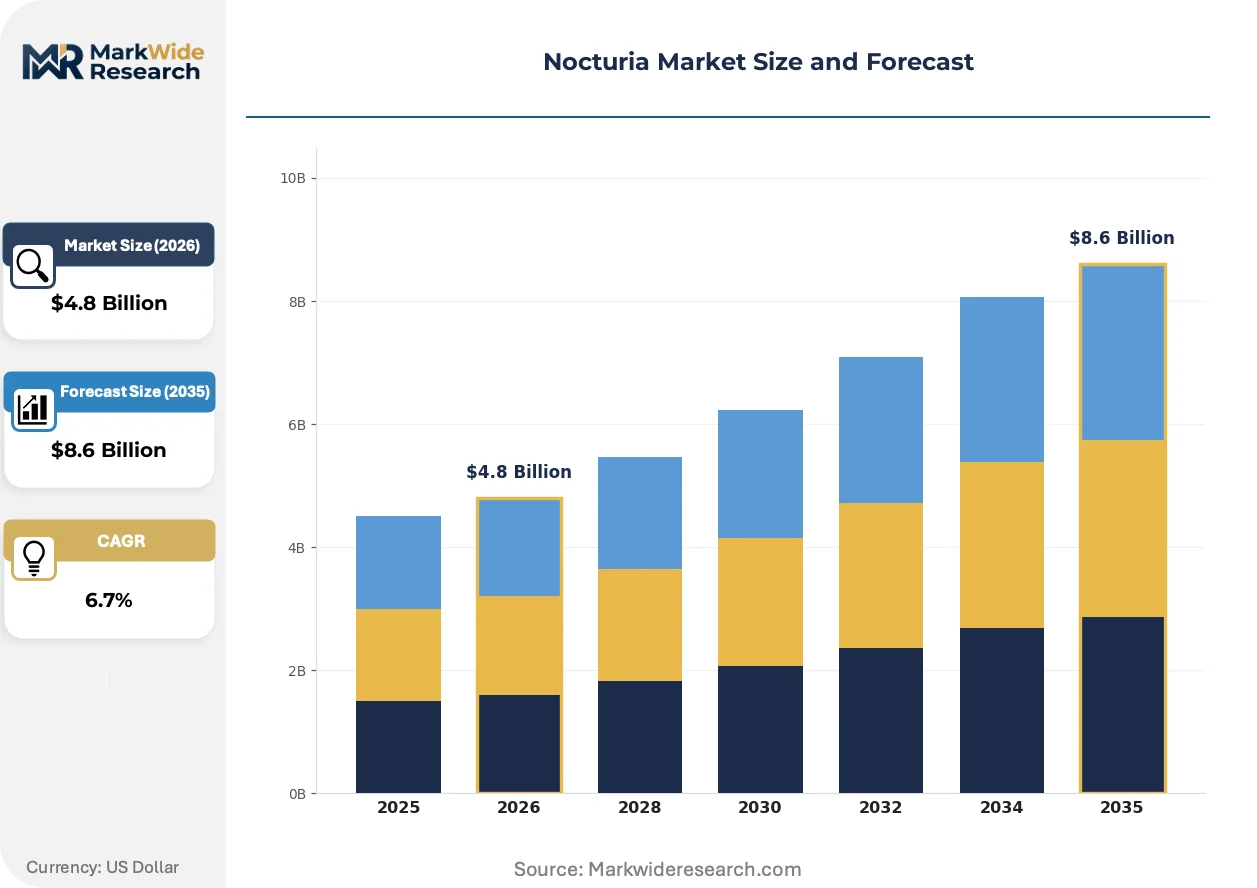
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Medications, Over-the-Counter Solutions, Lifestyle Aids, Dietary Supplements End User: Patients, Healthcare Providers, Caregivers, Pharmacists Therapy Area: Urology, Neurology, Geriatrics, Sleep Medicine Distribution Channel: Retail Pharmacies, Online Platforms, Hospitals, Clinics |
| Companies Covered | Ferring Pharmaceuticals, Astellas Pharma Inc., AbbVie Inc., Teva Pharmaceutical Industries Ltd., Avadel Pharmaceuticals plc, Glenmark Pharmaceuticals, Urigen Pharmaceuticals Inc., Vantia Therapeutics, Sumitomo Pharma Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nocturia Market Strategic Shifts
Connected diagnostic tools and algorithmic patient stratification are reconfiguring how nocturia etiology is identified and how therapy selection occurs across ambulatory and institutional settings.
Connected bladder monitoring hardware paired with machine learning classification is fragmenting the traditional diagnostic pathway. Urology departments in Japanese metropolitan hospital networks are piloting these systems for nocturnal polyuria index automation. The technology is fragmenting reliance on patient-reported bladder diaries and enabling real-time capacity measurement that reshapes antimuscarinic versus antidiuretic prescribing decisions.
EMA guidance evolution on pharmacogenomic stratification for antidiuretic therapies is tightening safety monitoring requirements. Drug developers must now incorporate CYP2C19 metabolizer status into European trial designs and labeling. German hospital pharmacists are responding by building pharmacogenomic testing into formulary review protocols for desmopressin-containing products.
Geriatric patients and their caregivers are consolidating prescription fulfillment through integrated pharmacy-benefit platforms that bundle nocturia therapies with chronic condition management. Retail pharmacy chains are losing script volume to these platforms in American Medicare Advantage markets. This consolidation is most visible in Florida and Arizona retirement corridors where mobility constraints and caregiver coordination needs concentrate.
Nocturia Market Segmentation
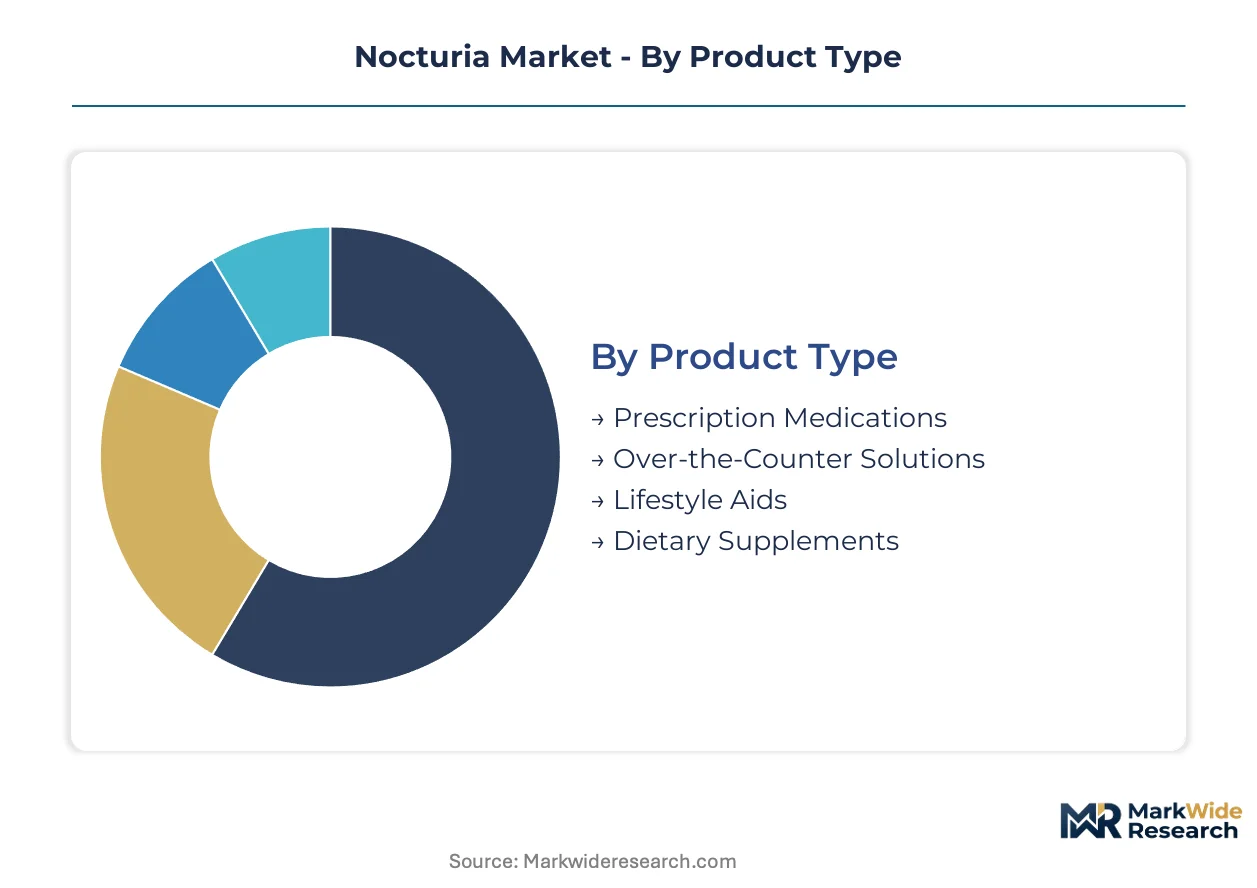
Nocturia treatment selection hinges on precise patient stratification across pharmacological, behavioral, and assistive modalities. Segmentation reveals where reimbursement premiums concentrate versus where volume expansion occurs through self-directed patient behavior.
Product Type:
Margin pools concentrate in prescription antidiuretic therapies where hospital formulary placement commands pricing leverage, while over-the-counter volume scales through pharmacy self-selection.
- Prescription Medications:Antidiuretic analogues and antimuscarinic agents require FDA Division of Urology approval pathways and carry cardiovascular safety monitoring obligations. German hospital networks and Japanese metropolitan urology departments drive demand concentration where geriatric screening protocols expand eligible patient pools.
- Over-the-Counter Solutions:Bladder training devices and absorbent products bypass prescription barriers. Mobility-limited patients in Florida and Arizona retirement corridors rotate fulfillment toward integrated pharmacy-benefit platforms that bundle these with chronic condition management.
- Lifestyle Aids:Bedside commodes and nocturnal lighting systems address functional limitations without clinical intervention. Caregiver procurement through durable medical equipment suppliers dominates channel flow.
- Dietary Supplements:Pumpkin seed extract and saw palmetto formulations compete on pharmacy shelf presence. Japanese consumers demonstrate highest trial rates for botanical nocturia therapies.
Prescription Medications holds installed capacity. Over-the-Counter Solutions is rotating up the share rankings.
End User:
Decision-making authority fragments across clinical prescribers, patient self-advocacy, and caregiver proxy purchasing.
- Patients:Geriatric individuals with nocturnal polyuria symptoms increasingly initiate dialogue with primary care physicians following direct-to-consumer bladder health education. Bladder diary compliance remains the primary adherence barrier across all therapeutic modalities.
- Healthcare Providers:Urologists and geriatricians in Tokyo, Berlin, and Boston metropolitan clusters concentrate diagnostic capacity. Cross-training bottlenecks extend time-to-therapy-initiation in secondary markets.
- Caregivers:Adult children and professional aides manage script fulfillment and device procurement for mobility-constrained elderly. Online platform conversion is highest among this proxy purchaser segment.
- Pharmacists:German hospital pharmacists integrate pharmacogenomic testing into desmopressin formulary reviews following EMA guidance evolution. Community pharmacists drive OTC substitution recommendations in primary care settings.
Healthcare Providers controls diagnostic gatekeeping. Caregivers is expanding most quickly as proxy purchasing consolidates.
Therapy Area:
Specialist concentration determines referral pathway efficiency and therapy selection protocol standardization.
- Urology:Departments in Japanese metropolitan hospital networks pilot connected bladder monitoring systems for nocturnal polyuria index automation. Machine learning classification is fragmenting traditional diary-dependent diagnostic workflows.
- Neurology:Multiple sclerosis and Parkinson's disease patients with neurogenic bladder dysfunction require differentiated antimuscarinic titration. Sleep disruption from nocturia compounds primary neurological symptom burden.
- Geriatrics:Screening protocol adoption across German, Japanese, and American hospital networks pulls undiagnosed patients into formal treatment pathways. Fellowship program output fails to match this expanded access demand.
- Sleep Medicine:Polysomnography integration identifies nocturia as a primary sleep architecture disruptor. Collaboration with urology remains institutionally variable.
Urology holds installed capacity. Geriatrics is climbing the fastest as screening protocols expand eligible populations.
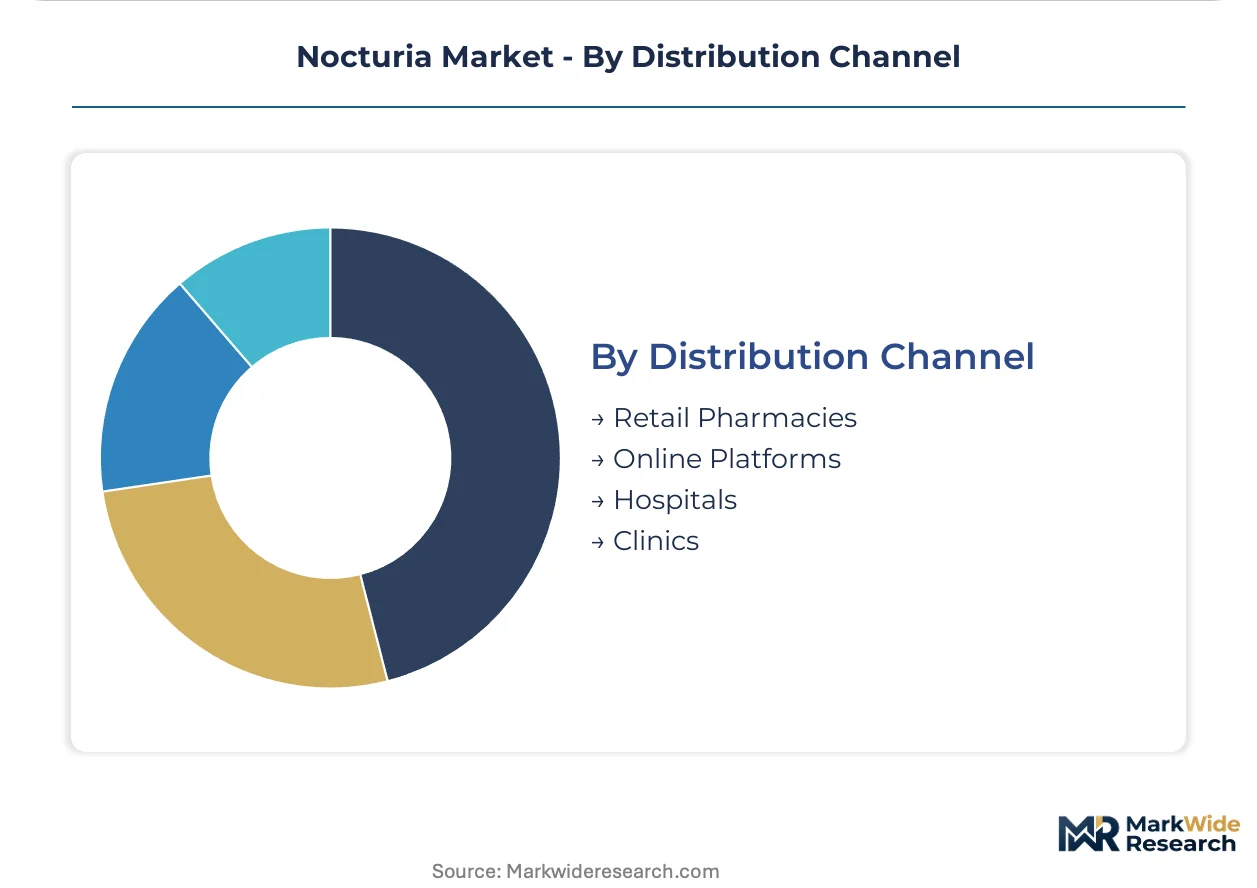
Distribution Channel:
Channel control determines patient capture efficiency and script fulfillment margin retention.
- Retail Pharmacies:Chains maintain margin-rich core positioning for chronic nocturia therapy fulfillment. Script volume erosion to digital platforms concentrates in Medicare Advantage markets.
- Online Platforms:Direct-to-patient channel control opens through mobility-limited geriatric patient and caregiver adoption. Fulfillment bundling with chronic condition management is consolidating prescription capture.
- Hospitals:Inpatient nocturia management during acute admissions creates formulary placement stickiness for discharge prescribing. Japanese metropolitan networks demonstrate deepest urology-geriatrics integration.
- Clinics:Geriatric clinic expansion across German, Japanese, and American networks drives screening-driven patient volume. Rural and secondary market access remains constrained by specialist concentration.
Retail Pharmacies holds installed capacity. Online Platforms is gaining share fastest among mobility-limited demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on nighttime polyuria diagnostics anchors United States market evolution, while PMDA efficacy endpoints and EMA harmonization efforts reshape parallel pathways in Japan and Europe. Regulatory divergence across these three jurisdictions fragments product registration strategies for device and drug developers.
United States
Medicare Advantage plan contracting drives demand concentration in Florida and Arizona retirement corridors where mobility-limited geriatric populations cluster. FDA Division of Urology oversight of digital therapeutics for bladder training intersects with CMS reimbursement decisions for connected care devices. Greater Boston maintains specialist concentration where urology-geriatrics co-location supports screening protocol adoption.
Japan
Metropolitan hospital networks in Tokyo and Osaka pilot connected bladder monitoring systems for nocturnal polyuria index automation. PMDA maintains distinct efficacy endpoints that accelerate regional trial completion for antidiuretic drug developers. Kanto region demonstrates deepest urology-geriatrics integration among Japanese hospital systems.
Germany
Geriatric clinic expansion across Berlin and Bavaria pulls undiagnosed patients into formal nocturia treatment pathways. EMA Committee for Medicinal Products for Human Use standardization efforts streamline multi-country European hospital formulary access. Hospital pharmacists in Baden-Württemberg integrate pharmacogenomic testing into desmopressin formulary reviews.
United Kingdom
NHS England screening protocol adoption in London and Southeast England concentrates diagnostic capacity among aging populations. MHRA alignment with EMA pharmacogenomic guidance tightens safety monitoring for antidiuretic therapies. Midlands region faces specialist bottlenecks as fellowship program output fails to match expanded access demand.
Switzerland
Swissmedic oversight of antidiuretic therapies supports hospital formulary placement for desmopressin-containing products. Cantonal health system integration in Zurich and Geneva enables cross-specialist referral pathways for nocturnal polyuria management. Basel pharmaceutical cluster proximity facilitates early-stage trial site activation for nocturia drug candidates.
Nocturia Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with prescription pharmaceutical developers commanding hospital formulary placement against over-the-counter and device challengers. The upper tier leverages desmopressin franchises and urology channel anchoring to sustain pricing leverage, while mid-tier players compete on pharmacy self-selection and digital platform conversion. Two archetypes dominate: antidiuretic specialists with established regulatory dossiers, and pelvic health generalists extending R&D intensity into adjacent lower urinary tract indications. Competitive moves concentrate on M&A for pharmacogenomic capabilities and strategic partnerships for connected care device reimbursement parity.
Within the antidiuretic specialist tier, Ferring Pharmaceuticals and Astellas Pharma Inc. exemplify geographic anchoring strategies—Ferring sustaining European hospital formulary presence, Astellas dominating Japanese urology channels. AbbVie Inc. occupies a position among pelvic health generalists where broader lower urinary tract R&D intensity extends competitive reach beyond nocturia-specific indications. These three entities represent distinct strategic postures: franchise defense through regulatory dossier depth, regional channel control through specialist co-location, and portfolio diversification through adjacent indication overlap.
| Leading Market Players |
|---|
| Ferring Pharmaceuticals |
| Astellas Pharma Inc. |
| AbbVie Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Avadel Pharmaceuticals plc |
| Glenmark Pharmaceuticals |
| Urigen Pharmaceuticals Inc. |
| Vantia Therapeutics |
| Sumitomo Pharma Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Desmopressin analogue substitution for antimuscarinic first-line therapy is simultaneously reshaping supply geography toward European API manufacturers and compressing pricing economics for hospital formulary placement across German and Japanese networks.
Pricing Analysis
Hospital procurement spreads between Tokyo metropolitan networks and Florida Medicare Advantage corridors reveal substantial geographic price differentiation for antidiuretic therapies. Three-tier pricing structure across premium desmopressin formulations, standard antimuscarinics, and economy generic alternatives dominates contract negotiations. Cost compression in the economy tier is intensifying because Japanese PMDA efficacy endpoints accelerate regional trial completion and expand eligible patient pools. Medicare Advantage plans demonstrate highest price sensitivity, while Japanese metropolitan urology departments maintain lowest sensitivity due to integrated screening protocol budgets.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp pharmaceutical corridors and container availability constraints across Asia-Europe trade lanes are elevating inbound logistics costs for active pharmaceutical ingredient shipments. API production concentrates in Switzerland, Germany, and India for desmopressin-containing products, while device components source from South Korea and Japan for connected bladder monitoring systems. Supply chain risk centers on single-source vulnerability for CYP2C19 pharmacogenomic testing kits required under evolving EMA guidance. Distribution runs through hospital pharmacy central procurement in German and Japanese networks, with retail pharmacy chains handling OTC and lifestyle aid fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as behavioral therapy protocols and digital therapeutics gain primary care reimbursement parity, threatening pharmacological volume capture.
For Market Incumbents: Secure hospital formulary placement through pharmacogenomic testing integration in German networks, addressing EMA safety monitoring evolution. Anchor Japanese urology channel control via connected device co-development partnerships with Tokyo metropolitan hospital networks. These moves counter behavioral therapy substitution and digital therapeutic reimbursement expansion.
For New Entrants and Emerging Players: Lead with online pharmacy platform partnerships targeting Florida and Arizona retirement corridor caregivers, where mobility constraints drive script fulfillment consolidation. Penetrate the OTC bladder training device segment where pharmacy self-selection bypasses prescription barriers. Deploy direct-to-patient education campaigns to capture undiagnosed geriatric populations before formal screening protocol exposure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed connected care device developers lacking Medicare Advantage reimbursement pathways. Five-to-ten year viability hinges on CMS coverage parity decisions for technology-enabled behavioral interventions. Watch FDA Division of Urology digital therapeutics guidance evolution as the critical inflection signal for portfolio reallocation between pharmaceutical and device exposures.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacogenomic Testing Integration | EMA Committee for Medicinal Products for Human Use guidance tightens safety monitoring for antidiuretic therapies in European hospital networks. |
| Connected Device Co-Development | Japanese metropolitan urology departments pilot machine learning classification systems for nocturnal polyuria index automation. |
| Online Pharmacy Platform Partnership | Mobility-limited geriatric patients in Florida and Arizona retirement corridors consolidate script fulfillment through digital channels. |
| Medicare Advantage Reimbursement Strategy | CMS connected care decisions determine technology-enabled behavioral intervention parity with pharmaceutical coverage. |
| Cross-Specialist Training Program Investment | Urology-geriatrics fellowship expansion addresses workforce pipeline failures constraining screening protocol adoption. |
Study Parameters
The analysis maps prescription antidiuretic therapies, over-the-counter solutions, connected diagnostic devices, and behavioral intervention protocols, each validated through formulary directors, urology department heads, geriatric clinic administrators, and Medicare Advantage plan contracting officers. Primary interview findings triangulate against FDA Division of Urology guidance documents, PMDA submission databases, EMA Committee for Medicinal Products for Human Use opinions, hospital procurement records, and CMS reimbursement determinations. Bottom-up patient volume modeling and top-down pharmaceutical revenue reconciliation ensure cross-validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework segments by product type, therapy area, end user decision authority, and distribution channel, with regional regulatory clusters as an additional dimension. CAGRs derive from patient population epidemiology, screening protocol adoption curves, and reimbursement pathway evolution. Forecast inputs incorporate PMDA efficacy endpoint completion rates and EMA pharmacogenomic guidance implementation timelines.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA oversight regimes; material policy shifts would require re-modeling. Antidiuretic cardiovascular safety threshold changes, CMS digital therapeutic coverage reversals, or specialist fellowship program expansion failures represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
India Urology Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Ureterorenoscopes Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Urethral Stricture Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Botulinum Toxin in Urology Market
Urology
Cystoscope Market
Urology
Urology Ultrasound Market
Urology
Uraemia Treatment Market
Urology
Primary Aldosteronism Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
Global Bladder Scanner Market
Urology
Europe Bladder Disorders Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Urology Surgery Supplies Market