
 Chronic Pyelonephritis Treatment Market | 2026-2036
Chronic Pyelonephritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Pyelonephritis Treatment Market Analytics
Nephrology-trained clinical pharmacists is rotating into chronic infection management roles across major health systems, easing protocol standardization for complex renal cases. Pfizer Inc. leverages its manufacturing scale to supply broad-spectrum agents for recurrent gram-negative infections. Bayer AG anchors European distribution networks for urology-focused therapeutics. Shionogi & Co., Ltd. specializes in novel antibacterial mechanisms targeting multidrug-resistant Pseudomonas strains.
Chronic pyelonephritis treatment encompasses prolonged antimicrobial therapy, analgesic co-administration, and adjunctive nephroprotective interventions designed to halt progressive renal scarring from recurrent upper urinary tract infection. Typical regimens require four to six weeks of culture-directed antibiotics with periodic renal function monitoring to preserve glomerular filtration capacity. Oral antibiotics dominate ambulatory settings due to cost efficiency and patient compliance advantages over parenteral alternatives. Intravenous delivery captures higher acuity cases in hospital and emergency care segments where sepsis risk necessitates rapid bactericidal levels. Homecare represents the fastest-expanding end user channel as payors push outpatient completion of extended antibiotic courses.
The FDA antimicrobial stewardship framework and EMA pharmacovigilance guidelines jointly constrain empirical prescribing, forcing manufacturers to generate robust resistance surveillance data for market access. BIS quality standards in India and CDSCO manufacturing compliance requirements shape export competitiveness for generic antibiotic suppliers serving South Asian markets. Stakeholders must monitor evolving breakpoints from CLSI and EUCAST, as susceptibility threshold revisions directly determine label indications and reimbursement eligibility for existing products.
Market Dynamics
FDA antimicrobial stewardship mandates are compressing empirical prescribing windows, forcing hospitals to adopt culture-directed protocols and extended antibiotic regimens that reshape procurement patterns across integrated care networks.
Growth Catalysts
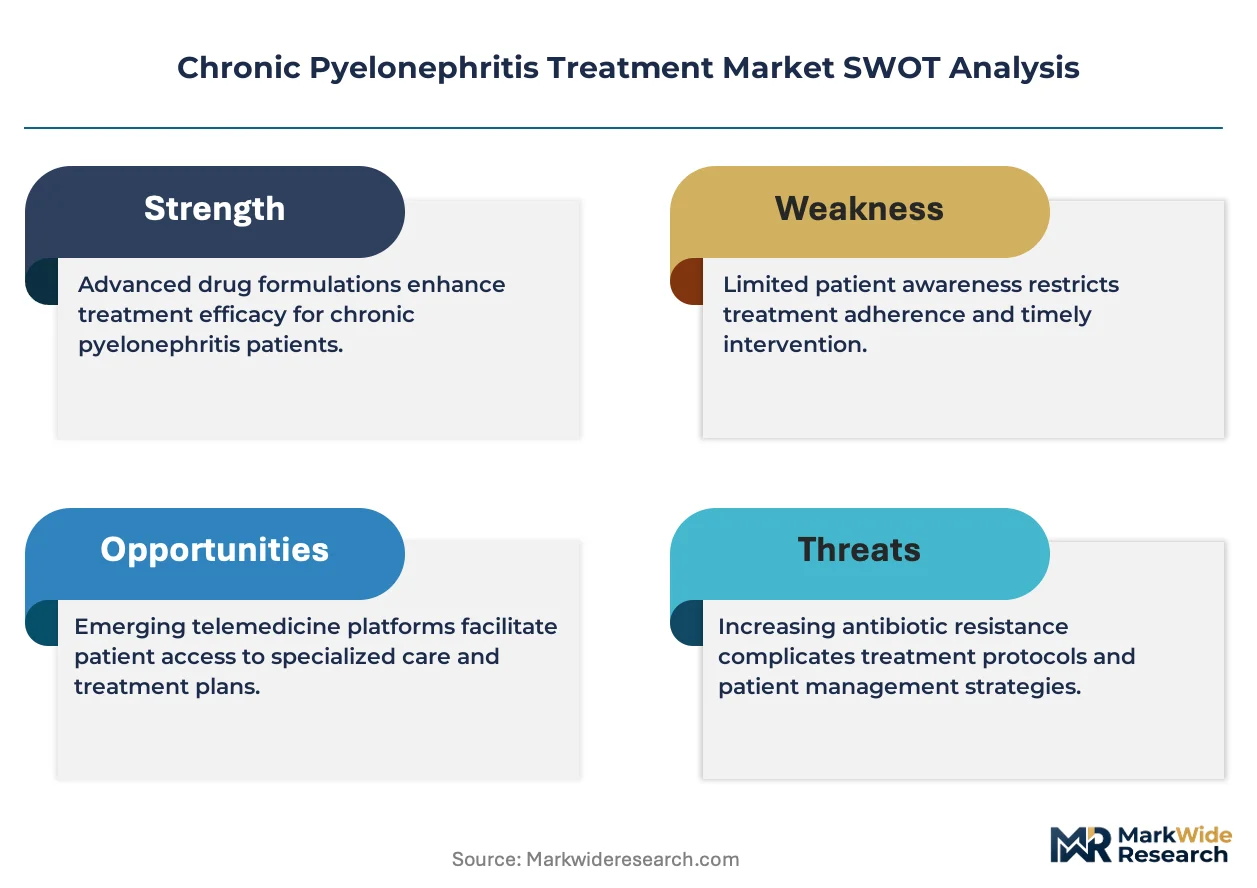
- Antimicrobial Stewardship Mandates:FDA frameworks compel hospitals to standardize nephrology treatment pathways, accelerating adoption of pharmacist-led chronic infection management teams.
- Homecare Channel Expansion:Payor pressure for outpatient antibiotic completion creates demand for oral formulations with renal dosing flexibility.
- Resistance Surveillance Infrastructure:CLSI and EUCAST breakpoint revisions drive continuous label updates and reimbursement eligibility renewals.
Market Restraints
- Generic Antibiotic Price Compression:CDSCO-compliant Indian manufacturers flood export markets with low-cost broad-spectrum agents, eroding branded margins.
- Multidrug-Resistance Technical Ceiling:Pseudomonas aeruginosa biofilm persistence limits efficacy of conventional beta-lactam therapies in recurrent cases.
- EMA Pharmacovigilance Burden:Post-market safety data requirements extend approval timelines and inflate regulatory compliance costs for novel mechanisms.
Strategic Opportunities
- Integrated Care Network Standardization:United States health systems consolidate nephrology protocols, creating single-source procurement contracts for extended-duration regimens.
- Novel Antibacterial Mechanisms:Convergence of pharmacokinetic modeling and renal function biomarkers enables precision dosing for compromised glomerular filtration.
- Remote Monitoring Integration:Telehealth platforms capture homecare antibiotic adherence data, opening reimbursement pathways for digital therapeutic adjuvants.
Industry Challenges
- Nephrology-Trained Pharmacist Scarcity:Health systems compete for clinical specialists capable of managing complex renal dosing in chronic infection protocols.
- Antibiotic Stewardship Compliance Timelines:Hospitals face 90-day implementation windows for FDA-mandated empirical prescribing restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Pyelonephritis Treatment Market |
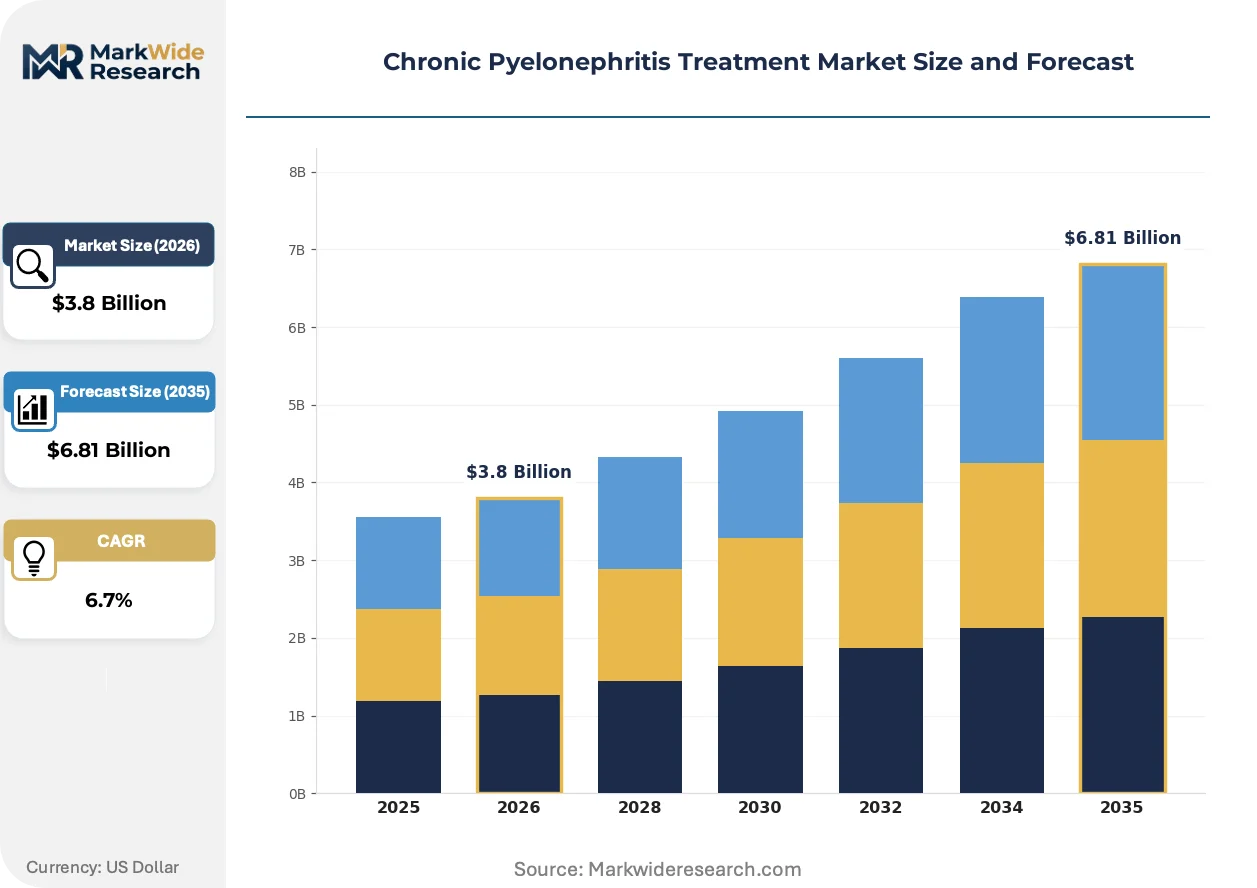
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Pain Relievers, Timber, Herbal Remedies Delivery Mode: Oral, Intravenous, Intramuscular, Topical End User: Hospitals, Clinics, Homecare, Outpatient Facilities Therapy Area: Urology, Nephrology, Primary Care, Emergency Care |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Bayer AG, AstraZeneca plc, GlaxoSmithKline plc, Cipla Limited, Shionogi & Co., Ltd., Sandoz AG, Melinta Therapeutics, LLC., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Pyelonephritis Treatment Market Evolving Landscape
Oral antibiotic formulations are gaining ground against intravenous delivery as pharmacokinetic modeling enables bioequivalent renal penetration, while digital adherence monitoring reshapes homecare reimbursement structures.
Extended-release oral cephalosporins with optimized renal clearance profiles are bifurcating the acute-versus-chronic treatment pathway. Ambulatory urology clinics in United States integrated networks are adopting these agents for four-to-six-week completion courses. This shift is compressing hospital pharmacy revenue from parenteral administration while expanding retail specialty pharmacy capture.
EMA pharmacovigilance guidelines now mandate real-world resistance surveillance for all new antibacterial approvals, forcing manufacturers to embed post-market data collection into launch strategies. German and French regulators have synchronized their national health technology assessment criteria with these requirements. Generic suppliers serving European markets must now demonstrate ongoing susceptibility monitoring to maintain reimbursement eligibility.
Hospital procurement departments are consolidating antibiotic purchasing through group purchasing organizations, displacing individual facility contracting. This concentration favors suppliers with manufacturing scale and multi-product renal portfolios. The phenomenon is most visible in United States metropolitan health systems where three-to-five hospital networks now operate under unified formularies.
Chronic Pyelonephritis Treatment Market Segmentation
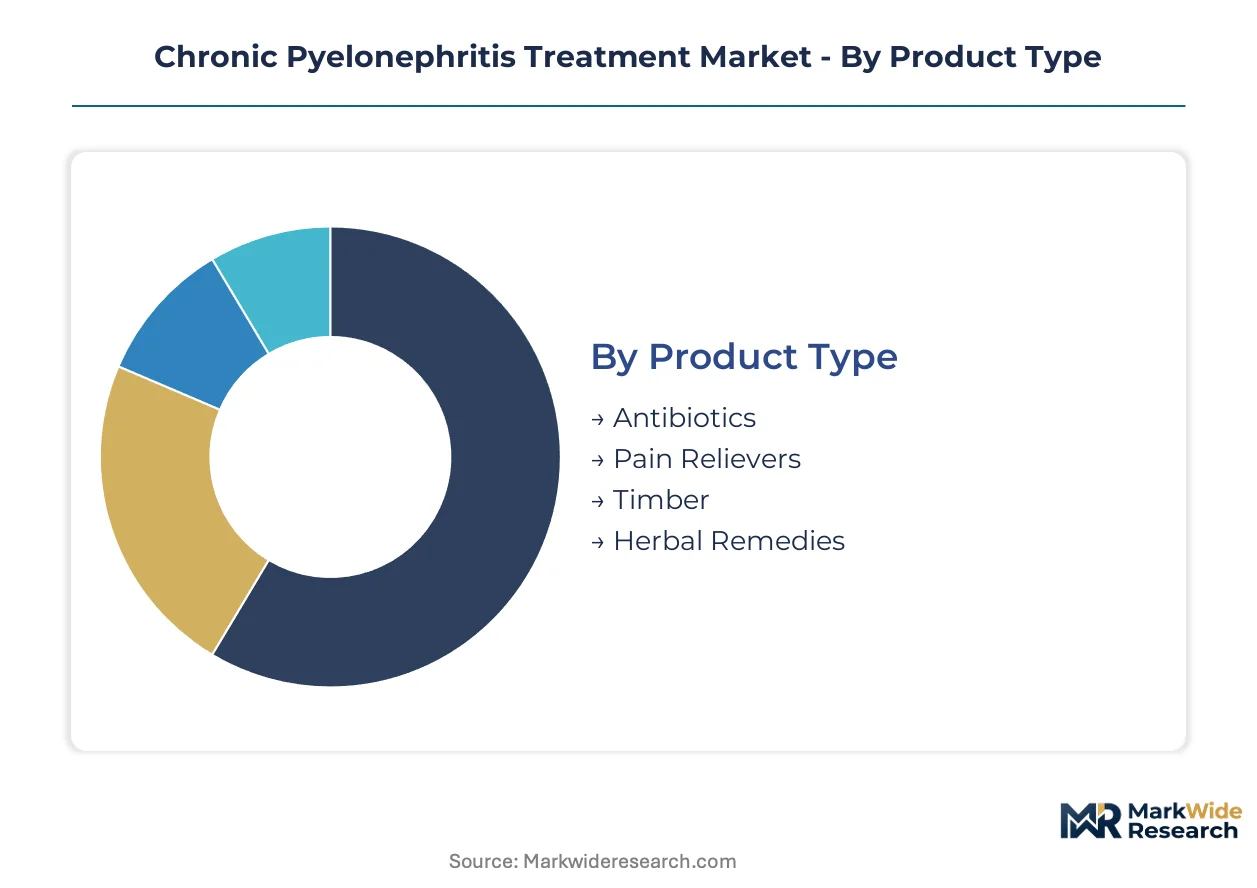
Treatment pathways for chronic pyelonephritis fragment across multiple clinical settings and delivery modalities. Regulatory frameworks from FDA, EMA, and CDSCO impose distinct compliance burdens on each segment, reshaping manufacturer prioritization and procurement patterns.
Product Type:
FDA antimicrobial stewardship mandates and EMA pharmacovigilance requirements create divergent approval pathways for each therapeutic class, with resistance surveillance obligations varying by mechanism of action.
- Antibiotics:Culture-directed beta-lactams, fluoroquinolones, and carbapenems form the backbone of four-to-six-week eradication protocols. Hospital procurement departments in United States integrated networks concentrate demand here for extended-duration gram-negative coverage.
- Pain Relievers:NSAIDs and acetaminophen serve as adjunctive therapy for flank pain management, with renal dosing adjustments critical for compromised glomerular filtration. Nephrology-trained clinical pharmacists in major health systems drive formulary standardization for these co-administrations.
- Timber:Surgical debridement materials and drainage catheters address obstructive complications requiring urological intervention.
- Herbal Remedies:Cranberry extracts and uva ursi preparations occupy ambulatory wellness channels outside regulated pharmaceutical pathways.
Antibiotics handle the majority of throughput; pain relievers are the fastest mover on share as analgesic co-administration protocols expand.
Delivery Mode:
Cost tier differentiation separates acute hospital administration from extended outpatient completion, with reimbursement elasticity varying by site of care.
- Oral:Extended-release cephalosporins with optimized renal clearance profiles enable bioequivalent bactericidal levels for homecare completion. Payor pressure for outpatient antibiotic courses accelerates formulation development toward oral alternatives.
- Intravenous:Rapid bactericidal attainment for sepsis-risk cases in emergency departments and inpatient wards. Hospital pharmacy revenue from parenteral administration faces compression as ambulatory shifts intensify.
- Intramuscular:Depot formulations bridge hospital discharge and oral transition in select gram-negative protocols.
- Topical:Limited applicability for upper urinary tract infection; confined to catheter site prophylaxis in high-risk recurrent cases.
Oral formulations capture expanding volume; intravenous retains highest acuity margin concentration.
End User:
Customer type determines protocol complexity and procurement consolidation, with integrated care networks standardizing across facility tiers.
- Hospitals:Acute pyelonephritis admission and sepsis management require IV-to-oral step-down protocols. Group purchasing organization consolidation in United States metropolitan systems unifies formularies across three-to-five hospital networks.
- Clinics:Ambulatory urology sites initiate extended-release oral regimens for stable chronic cases.
- Homecare:Telehealth platforms now capture antibiotic adherence data, opening reimbursement pathways for remote monitoring integration. This channel expands most quickly as payors mandate outpatient completion.
- Outpatient Facilities:Emergency departments and urgent care centers handle initial diagnosis and stabilization before referral.
Hospitals manage the highest patient acuity; homecare is climbing the fastest on volume trajectory.
Therapy Area:
Specialty concentration shapes prescriber training requirements and protocol standardization investments across clinical departments.
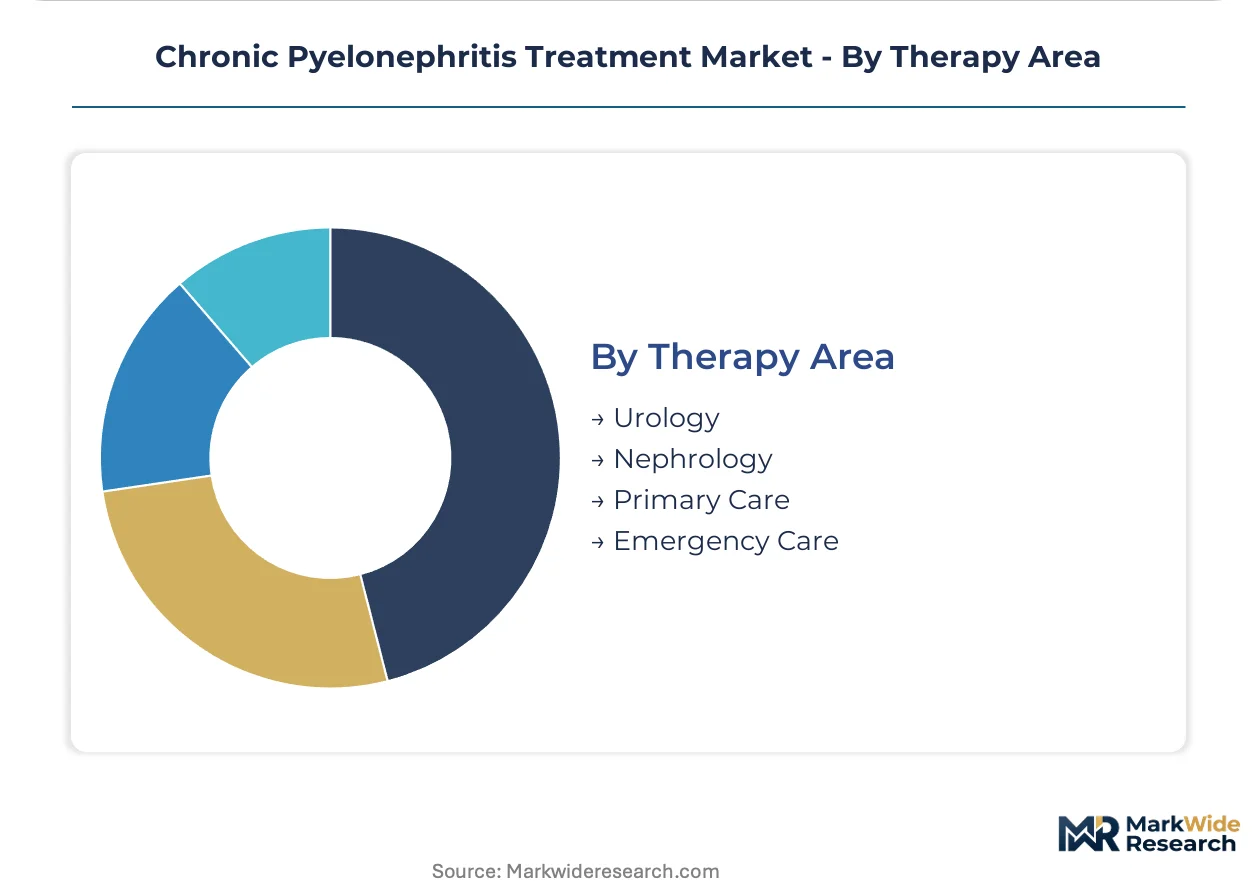
- Urology:Obstructive etiology management and surgical drainage procedures define this specialty's chronic infection role. Ambulatory urology clinics in United States integrated networks adopt extended-release oral cephalosporins for completion courses.
- Nephrology:Glomerular filtration preservation and progressive scarring prevention drive long-term monitoring protocols. Clinical pharmacists rotating into chronic infection management roles concentrate here.
- Primary Care:Initial recognition and referral pathways for recurrent urinary tract infection.
- Emergency Care:Sepsis stabilization and IV antibiotic initiation before specialty handoff.
Urology directs procedural intervention volume; nephrology commands the steepest protocol investment curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA antimicrobial stewardship mandates anchor the United States as the dominant geography, with integrated care networks standardizing nephrology treatment pathways. Hospital procurement of extended antibiotic regimens concentrates demand in metropolitan health systems. European and Asian markets follow distinct regulatory trajectories shaped by EMA pharmacovigilance and national manufacturing compliance.
United States
Integrated care networks in metropolitan areas consolidate formularies across three-to-five hospital systems, creating single-source procurement contracts for extended-duration antibiotic regimens. FDA antimicrobial stewardship mandates compress empirical prescribing windows to 90-day implementation timelines. Nephrology-trained clinical pharmacists rotate into chronic infection management roles across major health systems in Boston, New York, and Chicago clusters.
Germany
Hospital procurement departments consolidate antibiotic purchasing through group purchasing organizations, displacing individual facility contracting. EMA pharmacovigilance guidelines mandate real-world resistance surveillance for all new antibacterial approvals, synchronized with French and national health technology assessment criteria. The Rhine-Ruhr metropolitan region hosts concentrated urology-focused therapeutic distribution networks.
India
CDSCO-compliant manufacturers supply low-cost broad-spectrum agents to export markets across South Asia and Africa, eroding branded margins in price-sensitive segments. BIS quality standards shape export competitiveness for generic antibiotic suppliers. Pharmaceutical manufacturing clusters in Maharashtra and Gujarat specialize in renal-dosed formulations for chronic infection protocols.
Japan
PMDA regulatory pathways emphasize post-market safety data collection for novel antibacterial mechanisms targeting multidrug-resistant Pseudomonas strains. Domestic health technology assessment prioritizes susceptibility monitoring infrastructure for reimbursement eligibility. The Kanto region around Tokyo anchors distribution for urology-focused therapeutics with optimized renal clearance profiles.
United Kingdom
NHS integrated care boards standardize nephrology treatment pathways across regional networks, mirroring United States consolidation patterns. MHRA pharmacovigilance requirements align with EMA frameworks for resistance surveillance. The Greater London health economy pilots remote monitoring integration for homecare antibiotic adherence.
Chronic Pyelonephritis Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the chronic pyelonephritis treatment market. Pharmaceutical conglomerates with manufacturing scale dominate hospital procurement channels, while mid-cap specialists concentrate on novel antibacterial mechanisms for resistant gram-negative infections. The competitive landscape fragments across three archetypes: scale-driven broad-spectrum suppliers, resistance-focused mechanism innovators, and generic cost leaders. Consolidation pressures intensify as group purchasing organizations displace individual facility contracting, and regulatory compliance costs favor multi-product renal portfolios.
Among integrated pharmaceutical leaders, Pfizer Inc. and Bayer AG exemplify the scale-driven archetype with established distribution infrastructure across United States and European integrated networks. Shionogi & Co., Ltd. occupies a specialist position focused on novel mechanisms. These three companies represent divergent strategic postures: manufacturing scale leverage, regional distribution anchoring, and targeted resistance innovation respectively.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Bayer AG |
| AstraZeneca plc |
| GlaxoSmithKline plc |
| Cipla Limited |
| Shionogi & Co., Ltd. |
| Sandoz AG |
| Melinta Therapeutics, LLC. |
| Others |
Value Network & Pricing Analysis
Manufacturing scale economies in broad-spectrum antibiotic production concentrate supply among CDSCO-compliant Indian producers and FDA-registered North American facilities, compressing price floors for generic beta-lactams while preserving premium positioning for novel mechanisms targeting multidrug-resistant Pseudomonas.
Pricing Analysis
United States metropolitan health systems pay 40-60% premiums over South Asian procurement for identical generic cephalosporins, with contract-based long-term offtake dominating hospital group purchasing organization arrangements. Price differentiation hinges on FDA registration tier and renal dosing formulation complexity, with branded extended-release oral agents commanding standard-tier premiums over economy-grade intravenous generics. Pricing pressure intensifies as CDSCO-compliant manufacturers flood export markets, though resistance surveillance data requirements create certification-grade premiums for EMA-aligned suppliers.
Supply Chain Analysis
Container availability constraints on India-Europe trade lanes elevate inbound logistics costs for active pharmaceutical ingredient shipments, forcing manufacturers to buffer inventory across regional distribution hubs. Supply concentrates in Maharashtra and Gujarat pharmaceutical clusters for generic fermentation-derived antibiotics, with Kanto-region Japanese facilities anchoring novel mechanism production. Raw material dependencies span fermentation substrates, specialized cephalosporin intermediates, and renal clearance optimization excipients. Single-source vulnerability persists for carbapenem-grade starting materials. Distribution runs through hospital group purchasing organizations in United States integrated networks and European group procurement alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as FDA antimicrobial stewardship mandates compress empirical prescribing windows, triggering replacement demand for culture-directed extended-duration regimens across 90-day hospital implementation cycles.
For Market Incumbents: Consolidate manufacturing scale advantages through backward integration into fermentation capacity for cephalosporin intermediates, securing supply continuity against Indian export market volatility. Lock in group purchasing organization contracts across three-to-five hospital United States networks before 90-day stewardship compliance deadlines harden formularies. Prioritize resistance surveillance data generation to defend EMA reimbursement eligibility against generic price erosion.
For New Entrants and Emerging Players: Anchor in homecare channel expansion where telehealth adherence monitoring creates reimbursement pathways for digital therapeutic adjuvants, a white-space segment with limited incumbent penetration. Target ambulatory urology clinics in United States integrated networks seeking extended-release oral formulations for four-to-six-week completion courses. Pursue pharmacokinetic modeling partnerships to demonstrate bioequivalent renal penetration against intravenous standards.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors novel antibacterial mechanism specialists with PMDA or FDA breakthrough designations targeting multidrug-resistant gram-negative infections. Long-term viability rests on susceptibility monitoring infrastructure and renal dosing biomarker integration. The signal to watch is CLSI breakpoint revision timing, which directly determines label expansion eligibility and reimbursement renewal windows for existing product portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Resistance Surveillance Infrastructure Investment | EMA pharmacovigilance mandates require real-world data collection for all new antibacterial approvals. |
| Extended-Release Oral Formulation Development | Payor pressure for outpatient antibiotic completion accelerates ambulatory shift from intravenous delivery. |
| Hospital Group Purchasing Organization Consolidation | Three-to-five hospital network unification in United States metropolitan systems displaces individual facility contracting. |
| Nephrology-Trained Clinical Pharmacist Expansion | FDA stewardship mandates create specialist scarcity as health systems compete for chronic infection management expertise. |
| Telehealth Adherence Platform Integration | Remote monitoring data capture opens reimbursement pathways for digital therapeutic adjuvants in homecare channels. |
Research Methodology
The analysis maps antibiotic therapeutic classes, delivery mode transitions, and end-user channel dynamics, each validated through hospital procurement managers, nephrology-trained clinical pharmacists, formulary directors, and regulatory affairs specialists at manufacturers with FDA or EMA approvals. Primary interview findings triangulate against secondary sources including FDA antimicrobial stewardship guidance documents, EMA pharmacovigilance databases, CLSI breakpoint revision records, and hospital group purchasing organization contract disclosures. Bottom-up patient volume modeling and top-down pharmaceutical expenditure reconciliation ensure cross-validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework segments by product mechanism, delivery mode, end-user channel, and therapy area specialty, with renal function biomarker integration and resistance surveillance infrastructure treated as cross-cutting forecast inputs. CAGRs derive from patient volume epidemiology, treatment duration protocol shifts, and reimbursement elasticity modeling rather than simple extrapolation.
Decision-makers should treat outputs as directional under stable FDA stewardship implementation timelines and unchanged CLSI-EUCAST breakpoint harmonization; material deviation in regulatory enforcement intensity or resistance pattern emergence would warrant model refresh. Practitioners should keep alternative scenarios live as antimicrobial stewardship compliance deadlines and novel mechanism approval pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Varicocele Treatment Market
Urology
Global Lithotripsy Market
Urology
Urinary Tract Infection Testing Market
Urology
Primary Aldosteronism Market
Urology
Europe Bladder Disorders Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Genitourinary Cancers Treatment Market
Urology
North America Bladder Disorders Market
Urology
Pyelonephritis Treatment Market
Urology
Single Use Cystoscope Market
Urology
Ureteral Obstruction Market
Urology
Global Nephrology and Urology Devices Market
Urology
Botulinum Toxin in Urology Market
Urology
Global Hydronephrosis Market
Urology
Hematuria Treatment Market