
 Urology Laser Fibers Market | 2026-2036
Urology Laser Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Urology Laser Fibers Market Analytics
Thulium fiber laser technology is reshaping urological surgery by enabling precise tissue ablation at lower power thresholds with reduced thermal spread. Boston Scientific Corporation leverages its integrated urology portfolio to bundle fiber consumables with laser system placements. Olympus Corporation anchors its competitive position through deep specialization in rigid endoscopy channels that pair natively with proprietary fiber designs. Richard Wolf GmbH competes via its established presence in European hospital systems where surgeon training programs lock in fiber preferences.
Urology laser fibers are silica-glass waveguides with core diameters typically ranging from 200 to 1000 microns, engineered to transmit high-energy laser pulses from source to tissue target for lithotripsy and soft-tissue resection. Fiber lasers dominate the product landscape due to superior beam quality and compatibility with holmium and thulium wavelength platforms. Kidney stone management commands the largest application share as rising metabolic syndrome prevalence sustains procedural volumes across hospital and ambulatory settings. Ambulatory surgical centers represent the fastest-growing end-user channel as payers shift reimbursement toward lower-acuity sites.
FDA 510(k) premarket notification requirements govern fiber safety and efficacy claims in the United States, while EU MDR technical documentation demands expanded clinical evidence for reusable device reprocessing validations. ISO 10993 biocompatibility testing and IEC 60601-1 electrical safety standards shape design specifications for fibers marketed across OECD jurisdictions. Stakeholders must monitor how FDA guidance on reprocessing validation evolves alongside payer pressure for disposable-single-use economics.
Market Dynamics
Thulium fiber laser platforms are compressing thermal damage zones and expanding ambulatory eligibility for stone and soft-tissue procedures. This wavelength shift is redistributing fiber demand toward smaller-core disposable designs that pair with compact, lower-power generators.
Growth Catalysts
- Metabolic syndrome prevalence:Rising kidney stone incidence across North American and European populations sustains procedural volumes in hospital and outpatient settings.
- FDA 510(k) clearance streamlining:Expedited pathways for predicate-device laser fibers accelerate commercialization timelines for silica-based consumables in the United States.
- Holmium laser lithotripsy:Established reimbursement codes for stone fragmentation procedures lock in fiber utilization patterns across urology departments.
Market Restraints
- High-purity silica supply concentration:Specialty fiber preform manufacturing clusters in Germany and Japan, creating single-source vulnerability for core waveguide materials.
- EU MDR clinical evidence requirements:Expanded technical documentation for reusable fiber reprocessing validations extends time-to-market for European launches.
- Thulium solid-state laser substitution:Bulk crystal alternatives in development threaten fiber-laser platform dominance for certain ablation applications.
Strategic Opportunities
- Indian outpatient urology expansion:Private hospital chains in Mumbai and Delhi are investing in compact laser systems for same-day stone procedures.
- Single-use fiber economics:Payer pressure for infection control is opening ambulatory surgical center channels that bypass traditional hospital procurement.
- Thulium-holmium dual-wavelength convergence:Fiber designs compatible with both platforms capture switching flexibility premiums from capital-constrained buyers.
Industry Challenges
- Laser physics specialization shortage:Urology device companies compete for optical engineers capable of optimizing beam delivery through tapered fiber tips.
- ISO 10993 biocompatibility testing bottlenecks:Silica coating cytotoxicity studies create six-to-nine-month certification delays for new fiber formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urology Laser Fibers Market |
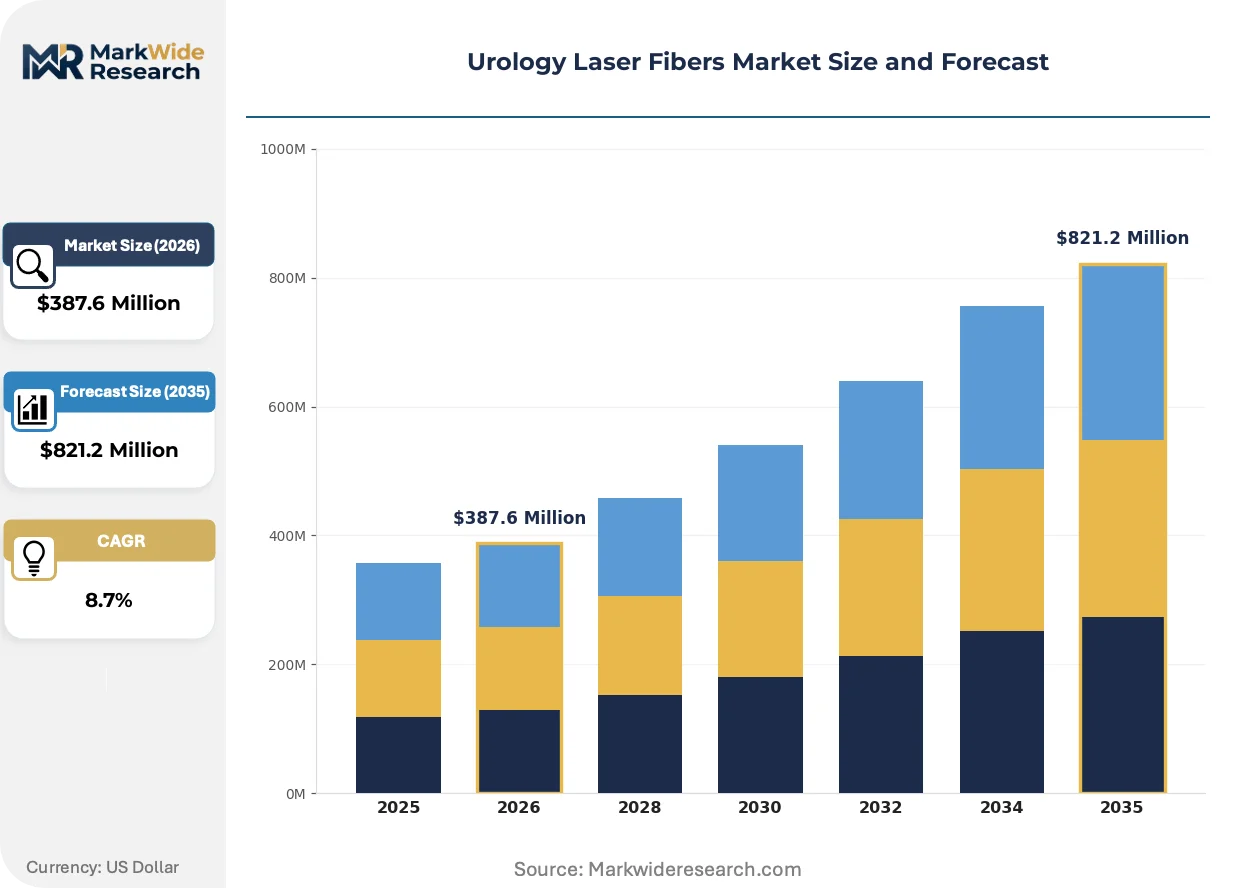
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Lasers, Solid State Lasers, Gas Lasers, Diode Lasers Application: Kidney Stone Management, Tumor Ablation, Prostate Surgery, Tissue Vaporization End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Distribution Channel: Direct Sales, Distributors, Online Sales, Medical Equipment Suppliers |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Richard Wolf GmbH, Cook Medical, Lumenis, biolitec AG, Allengers Medical Systems Limited, B. Braun Melsungen AG, OmniGuide Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urology Laser Fibers Market Evolving Landscape
Fiber architecture and wavelength platforms are converging to reduce thermal collateral damage while expanding procedure settings beyond traditional operating rooms.
Thulium fiber laser technology is hybridizing holmium and solid-state capabilities into single platforms that surgeons toggle between stone dusting and soft-tissue resection. Ambulatory surgical centers in the United States are adopting these dual-purpose systems at accelerated replacement cycles. This convergence is compressing demand for dedicated single-wavelength fiber inventories and favoring universal connector designs.
EU MDR technical documentation requirements are mandating expanded clinical evidence for reusable fiber reprocessing validations. Manufacturers must now submit sterilization cycle data and endotoxin testing protocols that exceed prior CE-marking thresholds. European hospital procurement committees are responding by tilting specifications toward single-use disposables that sidestep reprocessing liability.
Hospital group purchasing organizations are consolidating vendor contracts around bundled laser system and fiber consumable agreements. Independent urology practices and freestanding surgery centers are resisting these lock-in structures through direct distributor relationships and disposable-only procurement. This bifurcation is most pronounced in Texas, Florida, and Arizona where ambulatory site-of-service expansion is outpacing hospital outpatient department growth.
Urology Laser Fibers Market Segmentation
Laser fiber segmentation in urology tracks wavelength-platform evolution and site-of-service economics. Procurement patterns diverge sharply between consolidated hospital systems and independent ambulatory operators.
Product Type:
Cost tier differentiation separates capital-intensive platform investments from disposable consumable economics across laser modalities.
- Fiber Lasers:Silica-glass waveguides transmit holmium and thulium wavelengths with core diameters from 200 to 1000 microns. Hospital procurement committees in the United States favor these for compatibility with dual-wavelength generators that reduce capital redundancy.
- Solid State Lasers:Bulk crystal gain media produce high-peak-power pulses for stone fragmentation. Demand concentrates in European hospital systems where surgeon training programs established preference decades ago.
- Gas Lasers:CO2 and argon platforms serve niche soft-tissue applications with limited fiber-coupled configurations.
- Diode Lasers:Compact semiconductor sources enable office-based low-power procedures with simplified cooling requirements.
Fiber Lasers hold installed capacity. Solid State Lasers is rotating up the share rankings.
Application:
Procedure volume distribution follows metabolic disease prevalence and reimbursement site-of-service differentials.
- Kidney Stone Management:Lithotripsy procedures dominate procedural volumes as rising metabolic syndrome incidence sustains demand across hospital and outpatient channels. Ambulatory surgical centers in Texas and Florida are capturing migration from hospital outpatient departments through same-day stone dusting protocols.
- Prostate Surgery:Holmium laser enucleation and thulium vaporesection displace transurethral resection in academic medical centers. European urology departments in Germany and France lead adoption curves for laser-based benign prostatic hyperplasia treatment.
- Tumor Ablation:Precision thermal destruction targets upper tract urothelial carcinoma with reduced collateral damage.
- Tissue Vaporization:Surface ablation applications serve bladder lesion management with limited penetration depth.
Kidney Stone Management holds installed capacity. Prostate Surgery is rotating up the share rankings.
End User:
Customer type stratification reflects capital access, procurement autonomy, and infection control liability exposure.
- Hospitals:Integrated delivery networks leverage group purchasing organization contracts for bundled laser system and fiber agreements. These institutions maintain reprocessing infrastructure for reusable fiber portfolios.
- Ambulatory Surgical Centers:Freestanding facilities in Arizona and Georgia are expanding fastest as payers shift reimbursement toward lower-acuity sites. Single-use disposable fibers eliminate reprocessing validation burdens under FDA 510(k) requirements.
- Specialty Clinics:Urology-focused practices in suburban markets operate compact diode systems for office-based stone procedures.
- Research Institutions:Academic medical centers pilot next-generation thulium fiber platforms and validate new fiber tip geometries.
Hospitals hold installed capacity. Ambulatory Surgical Centers is expanding most quickly.
Distribution Channel:
Supply chain configuration determines pricing transparency and vendor lock-in intensity across customer segments.
- Direct Sales:Manufacturer field representatives negotiate enterprise contracts with IDN procurement committees. These relationships bundle capital equipment with multi-year fiber consumable commitments.
- Distributors:Independent medical device distributors serve mid-sized hospital systems and specialty clinics with localized inventory and technical support.
- Medical Equipment Suppliers:Regional suppliers stock standard fiber configurations for emergency replacement and small-volume accounts.
- Online Sales:E-commerce channels penetrate independent urology practices seeking price transparency on disposable fiber SKUs.
Direct Sales holds installed capacity. Distributors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fiber preform manufacturers export silica waveguide materials to laser system assemblers in the United States and Japan, creating a concentrated trade corridor that shapes procurement costs across OECD hospital systems.
United States
Hospital procurement consolidation through group purchasing organizations bundles fiber consumables with capital equipment placements. FDA 510(k) clearance pathways expedite commercialization for predicate-device laser fibers. The Texas-Florida corridor drives ambulatory surgical center expansion as payers shift stone procedure reimbursement toward freestanding sites.
Germany
European hospital systems maintain reusable fiber reprocessing infrastructure despite EU MDR clinical evidence requirements tightening sterilization validation standards. Richard Wolf GmbH anchors surgeon training programs that lock in fiber preferences across academic medical centers. The Baden-Württemberg precision optics cluster supplies specialty fiber preforms to global laser manufacturers.
Japan
Metabolic syndrome prevalence sustains kidney stone procedural volumes in aging demographics. PMDA regulatory frameworks align with IEC 60601-1 electrical safety standards for fiber-coupled laser systems. The Nagoya medical device manufacturing belt concentrates rigid endoscopy production that pairs with proprietary fiber designs.
India
Private hospital chains in Mumbai and Delhi invest in compact laser systems for same-day stone procedures. CDSCO medical device regulations are harmonizing with ISO 10993 biocompatibility testing protocols for silica-based fiber coatings. The Maharashtra-Gujarat industrial corridor hosts emerging domestic fiber assembly operations serving South Asian markets.
China
NMPA regulatory pathways for Class II laser fibers are streamlining domestic manufacturer market entry. Provincial hospital procurement in Jiangsu and Guangdong provinces favors cost-competitive fiber consumables for high-volume stone centers. The Yangtze River Delta medical device cluster integrates fiber drawing capabilities with laser system final assembly.
Urology Laser Fibers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement structures. The vendor base clusters around three strategic archetypes: integrated urology platform providers, rigid endoscopy specialists, and standalone fiber consumable suppliers. Consolidated hospital procurement favors bundled system-and-consumable contracts, while ambulatory bypass channels reward distributor-direct relationships. M&A activity concentrates on fiber tip geometry IP and dual-wavelength compatibility portfolios.
Within the integrated platform tier, Boston Scientific Corporation and Olympus Corporation exemplify archetypes that leverage capital equipment placements to secure multi-year fiber commitments. Richard Wolf GmbH occupies a position as the European hospital system anchor, while biolitec AG and Lumenis represent wavelength-specialist players competing on thulium-holmium convergence. OmniGuide Holdings, Inc. sits within the fiber-delivery technology niche, and B. Braun Melsungen AG anchors the German surgical consumables tradition. Cook Medical exemplifies the mid-scale diversified device manufacturer competing through GPO contract breadth.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Richard Wolf GmbH |
| Cook Medical |
| Lumenis |
| biolitec AG |
| Allengers Medical Systems Limited |
| B. Braun Melsungen AG |
| OmniGuide Holdings, Inc. |
| Others |
Value Network & Pricing Analysis
German specialty fiber preform manufacturers concentrate upstream supply of high-purity silica waveguide materials, anchoring margin pools with laser system assemblers in the United States and Japan who bundle consumables into long-term hospital contracts.
Pricing Analysis
Next-generation thulium fiber laser platforms command 40-60% premiums over legacy holmium systems, while prior-generation reusable fiber inventories face accelerated depreciation as ambulatory surgical centers shift toward single-use disposables. Three-tier pricing structure across premium, standard, and economy levels stratifies by core diameter precision and coating biocompatibility certification grade. Cost compression in standard-tier consumables is intensifying because Chinese domestic manufacturers are scaling fiber drawing capabilities. Independent urology practices exhibit highest price sensitivity, whereas consolidated hospital systems prioritize total-cost-of-ownership metrics including reprocessing liability.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk planning for silica preform imports, with alternative sourcing from Japanese specialty glass manufacturers offering partial mitigation. High-purity synthetic silica feedstock, precision fiber drawing towers, and ISO 10993-certified coating chemistries anchor production dependencies. Single-source vulnerability concentrates in Baden-Württemberg precision optics clusters where three family-owned preform suppliers control specialty waveguide formulations. Distribution runs through manufacturer-direct field representatives for integrated delivery networks, while independent distributors serve ambulatory bypass channels with localized inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical engineering talent capable of optimizing tapered fiber tip geometries for dual-wavelength platforms represents the critical capability gap constraining competitive positioning in this market.
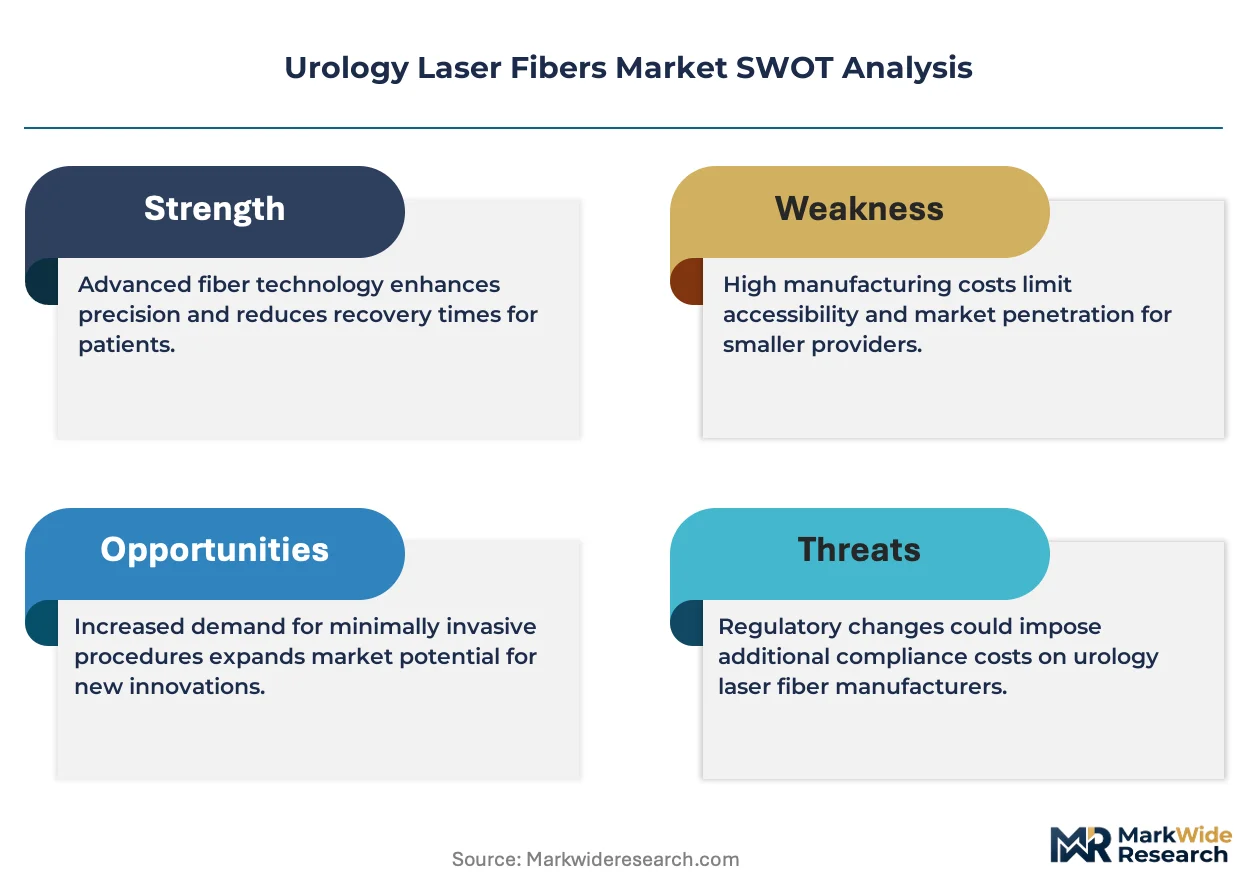
For Market Incumbents: Pre-empt thulium-holmium dual-wavelength convergence by acquiring fiber tip geometry IP portfolios from specialized academic spinouts before capital-constrained competitors lock in exclusive licensing. Backward integration into silica preform manufacturing in Germany or Japan reduces single-source exposure while securing supply continuity for GPO contract fulfillment. Channel control through exclusive surgeon training programs at academic medical centers remains the priority defensive lever against disposable-only ambulatory challengers. For New Entrants and Emerging Players: Mid-market ambulatory surgical centers in Texas, Florida, and Arizona represent the most penetrable entry point, bypassing consolidated hospital procurement through direct distributor relationships and single-use-only value propositions. Private hospital chains in Mumbai and Delhi offer secondary white-space expansion as CDSCO regulatory harmonization accelerates. A go-to-market angle anchored on thulium fiber laser compatibility without capital equipment bundling unlocks procurement autonomy at freestanding sites. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed urology platform specialists seeking fiber consumable verticality to complete integrated system offerings. The five-to-ten year viability window favors targets with proprietary dual-wavelength connector designs and validated EU MDR technical documentation. The signal to watch is FDA guidance evolution on reprocessing validation timelines, which would accelerate single-use adoption curves and revalue disposable-focused fiber portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Tip Geometry IP Acquisition | Dual-wavelength compatibility patents lock in switching premiums from capital-constrained hospital buyers. |
| EU MDR Technical Documentation Investment | Expanded sterilization validation data accelerates European market entry ahead of reprocessing liability shifts. |
| Ambulatory Surgical Center Direct Distribution | Bypassing GPO contracts captures fastest-growing end-user channel in Texas-Florida corridor. |
| Silica Preform Backward Integration | German or Japanese upstream control mitigates single-source supply risk for high-purity waveguide materials. |
| Surgeon Training Program Expansion | Academic medical center lock-in programs defend fiber preference against disposable-only competitors. |
Research Methodology
A spread of perspectives from urology department heads, hospital GPO contracts managers, biomedical engineers, and laser system field service technicians converged on the working assumptions. Primary interviews combined with secondary validation against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement contract repositories, and ISO 10993 biocompatibility testing records. Bottom-up fiber shipment estimates triangulated against top-down laser system installed base calculations.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include laser modality platform, procedural application, end-user facility type, and regional regulatory cluster. CAGRs derived from procedure volume trajectories weighted by reimbursement site-of-service differentials and capital equipment replacement cycles. Thulium fiber laser adoption curves and ambulatory surgical center expansion rates served as primary industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in payer reimbursement policies, hospital capital expenditure cycles, or specialty silica raw material pricing would shift the trajectory. Forecasts reflect documented assumptions on wavelength platform substitution rates and regulatory clearance timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Hematuria Treatment Market
Urology
India Urology Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Nordic Urinary Catheters Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Global Prostate Health Market
Urology
Transrectal Ultrasound Market
Urology
Global Lithotripsy Market
Urology
Urinary Incontinence Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Urinary Bag Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Urology Forceps Market
Urology
Prostate Cancer Treatment Market
Urology
Cystectomy Market