
 Nephrology and Urology Incontinence Devices Market | 2026-2036
Nephrology and Urology Incontinence Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nephrology and Urology Incontinence Devices Market Foresight
Hospital procurement consortiums is reshaping how nephrology and urology incontinence devices reach end users, consolidating purchasing power across integrated delivery networks. Coloplast leverages its direct-to-institution sales force to sustain premium positioning in advanced catheter systems. Hollister Incorporated anchors its competitive stance through specialized manufacturing of ostomy and continence products with strong clinician loyalty. B. Braun Melsungen AG competes on manufacturing scale, operating catheter production facilities that supply multiple European and Asian markets.
Nephrology and urology incontinence devices comprise engineered products for urinary management, including silicone and latex catheters with hydrophilic coatings, absorbent core structures with superabsorbent polymers, and implantable pulse generators for sacral neuromodulation. These devices serve to restore continence, protect skin integrity, and reduce catheter-associated urinary tract infections in acute and chronic care settings. Urinary catheters occupy the largest revenue pool due to indwelling and intermittent use across hospitals and long-term care, though neuromodulation devices represent the fastest-growing segment as rechargeable systems extend replacement intervals. Absorbent technology in disposable pads dominates unit volume, while sensor-based solutions are gaining structural traction in remote patient monitoring programs for home care settings.
The FDA regulates implantable neuromodulation devices under Class III premarket approval pathways, while the EPA oversees disposal standards for contaminated absorbent products in clinical environments. The EU Medical Device Regulation imposes stricter clinical evidence requirements on catheter coatings and biocompatibility testing, reshaping market access timelines for manufacturers without established notified body relationships. Stakeholders must monitor reimbursement negotiations for sacral nerve stimulation procedures and absorbent product categories across Medicare and private payers, as coverage determinations will dictate investment prioritization between commodity and technology-intensive segments.
Market Dynamics
Hospital procurement consortiums are consolidating purchasing power across integrated delivery networks, forcing manufacturers to restructure pricing and service models around volume commitments rather than individual institution relationships.
Growth Catalysts
- EU Medical Device Regulation (MDR):Stricter clinical evidence requirements on catheter coatings are accelerating biocompatibility investments, raising barriers for marginal competitors and protecting established manufacturers with notified body relationships.
- Home care migration:Patients discharged earlier from acute settings are driving demand for disposable external devices and sensor-based monitoring systems that reduce institutional dependency.
- Superabsorbent polymer advances:New core structures in disposable pads are extending wear time and reducing skin compromise events, expanding addressable populations in long-term care facilities.
Market Restraints
- Silicone feedstock volatility:Catheter manufacturers face margin pressure from petrochemical-derived silicone price swings, with limited short-term substitution options for hydrophilic-coated indwelling products.
- FDA Class III pathway friction:Implantable neuromodulation systems require extended premarket approval timelines, compressing commercialization windows and elevating clinical validation costs beyond mid-cap reach.
- Rechargeable battery substitution threat:Extended-interval neuromodulation systems are reducing replacement procedure volumes, constraining recurring revenue pools for service-dependent business models.
Strategic Opportunities
- Remote patient monitoring integration:Sensor-enabled pads and external collection devices are converging with telehealth platforms, creating subscription revenue streams in post-acute home settings.
- India's CDSCO pathway acceleration:Streamlined medical device registration for absorbent and catheter products is opening direct market access without historical distributor dependency.
- Medicare coverage expansion:Reimbursement clarity for sacral nerve stimulation procedures in ambulatory surgical centers is shifting procedure volume away from inpatient settings.
Industry Challenges
- Notified body capacity scarcity:EU MDR implementation has created certification bottlenecks, with extended audit queues delaying market access for coating and material innovations.
- Legacy EHR integration complexity:Sensor-based continence devices require interoperability with fragmented hospital information systems, elevating implementation costs and elongating sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nephrology and Urology Incontinence Devices Market |
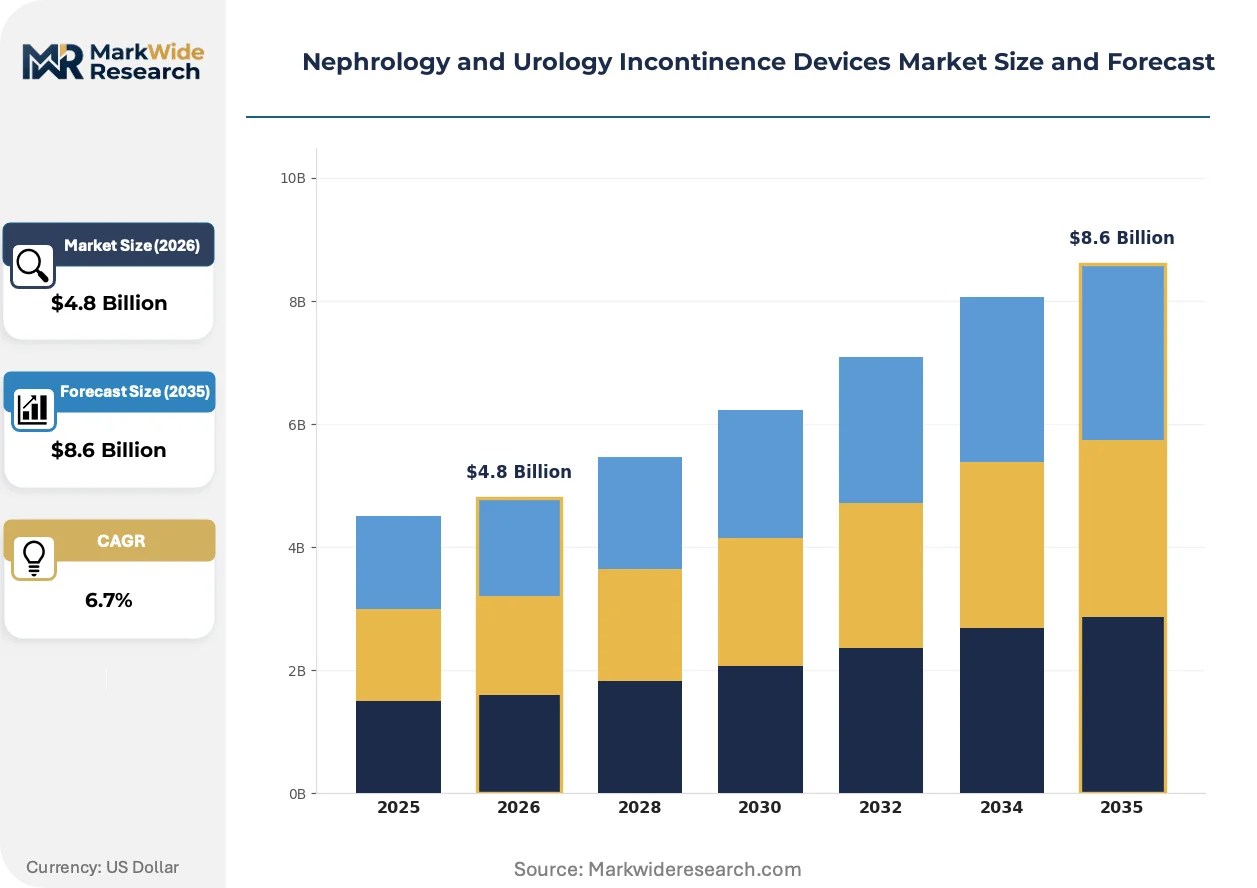
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urinary Catheters, External Devices, Disposable Pads, Neuromodulation Devices Technology: Absorbent Technology, Sensor-Based Solutions, Implantable Devices, Non-Invasive Techniques End User: Home Care Settings, Hospitals, Rehabilitation Centers, Long-Term Care Facilities Distribution Channel: Online Retail, Direct Sales, Medical Supply Stores, Pharmacy Chains |
| Companies Covered | Coloplast, Hollister Incorporated, ConvaTec Group, Boston Scientific Corporation, Medtronic, Teleflex, B. Braun Melsungen AG, Becton Dickinson, First Quality Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nephrology and Urology Incontinence Devices Market Shifts & Advancements
Active materials and connected diagnostics are redefining product value propositions, shifting competition from commodity manufacturing toward data-enabled care coordination and predictive intervention capabilities.
Rechargeable implantable pulse generators are hybridizing sacral neuromodulation therapy delivery. Urology clinics in Germany and the United States are prioritizing these systems for patients requiring long-term neuromodulation management. The technology is hybridizing procedure economics by compressing replacement intervals from three years toward ten-plus years, forcing manufacturers to develop service and monitoring revenue attachments.
The EU Medical Device Regulation imposes stricter clinical evidence requirements on catheter coatings and biocompatibility testing. Manufacturers without established notified body relationships face extended market access timelines and elevated documentation burdens. Catheter suppliers with pre-MDR certifications are accelerating portfolio rationalization to concentrate resources on highest-margin hydrophilic and antimicrobial-coated lines.
Integrated delivery networks are consolidating absorbent product procurement through centralized contracting offices. Group purchasing organizations are displacing individual hospital negotiations, extracting standardized pricing and compliance reporting across multi-facility systems. This concentration is most visible in United States metropolitan markets where health system mergers have created regional procurement monopolies controlling hundreds of acute and post-acute sites.
Nephrology and Urology Incontinence Devices Market Segmentation
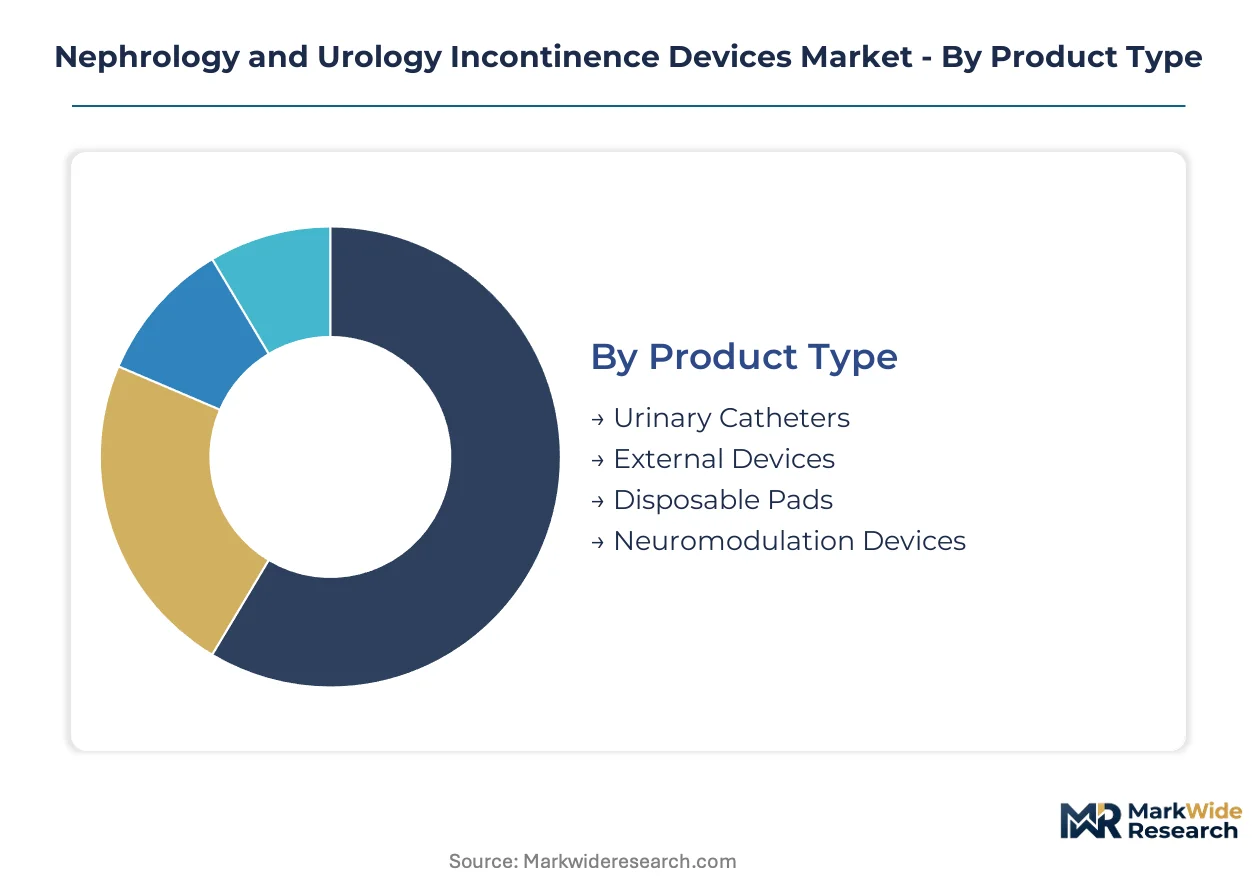
Device segmentation in nephrology and urology incontinence reflects divergent clinical requirements across acute intervention and chronic management. Procurement patterns fragment by reimbursement pathway, with institutional buyers prioritizing infection prevention metrics while home care patients optimize for discretion and wear duration.
Product Type:
Use-case spectrum spans indwelling intervention through non-invasive surface management, with material science and reimbursement tier determining commercial priority.
- Urinary Catheters:Silicone and latex constructs with hydrophilic coatings dominate institutional procurement for CAUTI prevention. United States hospital systems concentrate demand here, with reimbursement clarity supporting sustained volume through Medicare's inpatient prospective payment system.
- Neuromodulation Devices:Implantable pulse generators for sacral nerve stimulation deliver electrical modulation to restore continence. German and United States urology clinics are prioritizing rechargeable systems, with extended replacement intervals compressing procedure economics toward service-based revenue models.
- External Devices:Male external catheters and collection systems serve ambulatory patients seeking alternatives to indwelling placement. Home care migration in United States metropolitan markets is elevating demand for discreet, skin-friendly adhesives.
- Disposable Pads:Superabsorbent polymer core structures manage light to moderate incontinence without clinical intervention. Long-term care facilities across the United States represent the volume anchor, with skin integrity protection driving specification choices.
Established volume favors urinary catheters; emerging adoption favors neuromodulation devices.
Technology:
Cost tier stratification separates commodity absorption from capital-intensive implantable electronics, with sensor platforms occupying an intermediate development stage.
- Implantable Devices:Pulse generators and lead systems require Class III regulatory pathways and specialized surgical placement. FDA premarket approval timelines and EU MDR clinical evidence requirements are elevating barriers to competitive entry.
- Sensor-Based Solutions:Moisture detection and connectivity modules enable remote monitoring of continence events. United States telehealth platform integrations are gaining structural traction in post-acute home settings, though EHR interoperability complexity elongates sales cycles.
- Absorbent Technology:Superabsorbent polymers and acquisition distribution layers form the functional core of disposable pads. Manufacturing scale and raw material sourcing determine margin sustainability against private-label competition.
- Non-Invasive Techniques:Pelvic floor stimulation and biofeedback systems serve patients contraindicated for surgery or seeking behavioral alternatives. Rehabilitation centers in Germany and the United States represent the primary channel.
Capital intensity peaks with implantable devices; volume concentration rests with absorbent technology.
End User:
Customer type determines specification priority, with institutional buyers emphasizing infection metrics and individual patients optimizing for autonomy and discretion.
- Hospitals:Acute care settings drive catheter volume through surgical recovery and intensive care protocols. Integrated delivery network procurement consolidation in the United States is extracting standardized pricing across multi-facility systems.
- Home Care Settings:Discharged patients and community-dwelling elderly manage continence through disposable pads and external devices. United States reimbursement for durable medical equipment supports sustained demand, with sensor-enabled products gaining adoption in remote monitoring programs.
- Long-Term Care Facilities:Skilled nursing and assisted living environments balance staff efficiency with resident dignity. Skin integrity protection and odor control dominate product selection criteria.
- Rehabilitation Centers:Post-acute recovery settings employ neuromodulation trials and pelvic floor therapy. Ambulatory surgical center reimbursement expansion in the United States is shifting procedure volume from inpatient settings.
Institutional procurement anchors hospital volume; patient-directed selection is expanding fastest in home care settings.
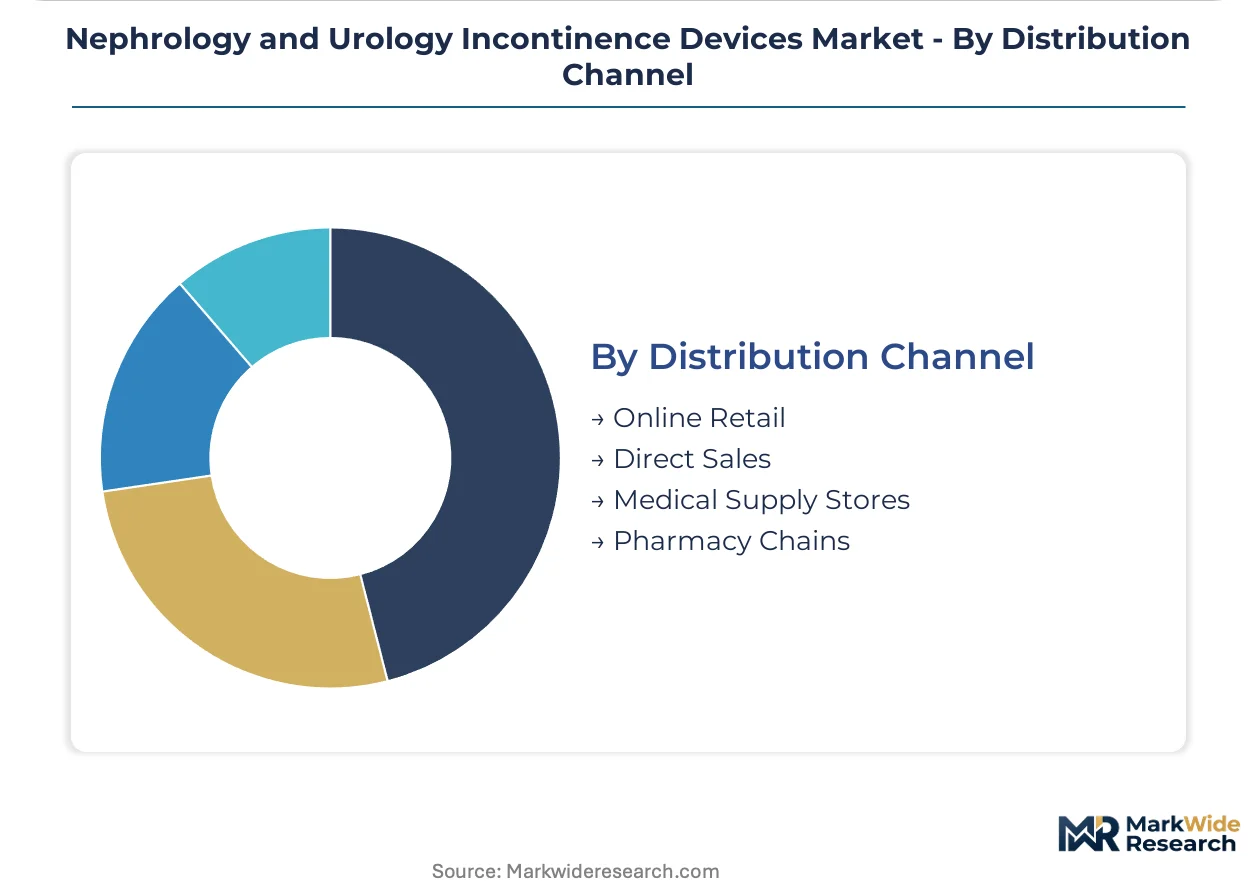
Distribution Channel:
Supply concentration varies by buyer sophistication, with direct sales forces serving complex institutional contracts and retail channels capturing individual consumers.
- Direct Sales:Manufacturer representatives negotiate enterprise contracts with integrated delivery networks and group purchasing organizations. Coloplast and Hollister field organizations sustain premium positioning through clinical relationships and service attachments.
- Medical Supply Stores:Durable medical equipment dealers serve home care patients with catheter and external device prescriptions. United States Medicare competitive bidding programs have compressed margins in this channel.
- Pharmacy Chains:Retail pharmacy shelf space captures disposable pad volume from convenience-oriented consumers. Private-label absorption is displacing branded share in mass-market positioning.
- Online Retail:E-commerce platforms enable discreet procurement of pads and external devices, with subscription models gaining traction for recurring replenishment. India's CDSCO pathway acceleration is enabling direct manufacturer access without historical distributor dependency.
Direct sales capture institutional value; online retail is climbing the fastest in patient-directed segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where Medicare reimbursement clarity and integrated delivery network consolidation sustain premium capture, while European markets face margin compression from EU MDR compliance costs and centralized procurement.
United States
Aging demographics and ambulatory surgical center reimbursement expansion drive neuromodulation procedure volume. FDA Class III premarket approval pathways for implantable pulse generators extend validation timelines. The Minneapolis medical device cluster anchors sacral nerve stimulation system development and clinical trial infrastructure.
Germany
Rechargeable implantable pulse generators command preference in urology clinics seeking extended replacement intervals. EU MDR notified body relationships determine catheter coating market access speed. The Baden-Württemberg region concentrates hydrophilic catheter manufacturing and biocompatibility testing facilities.
India
CDSCO pathway acceleration enables direct manufacturer market entry without historical distributor dependency. Streamlined medical device registration for absorbent and catheter products attracts foreign investment. Maharashtra's Mumbai-Pune pharmaceutical corridor hosts expanding contract manufacturing for disposable pads.
Japan
PMDA regulatory efficiency supports faster approval timelines for sensor-based continence monitoring systems. Super-aging demographics expand addressable populations for home care external devices. The Kansai region around Osaka maintains specialized manufacturing for skin-friendly adhesive technologies.
United Kingdom
NHS procurement consolidation extracts standardized pricing across catheter and pad categories through national framework agreements. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR implementation timelines. The East Midlands medical technology cluster focuses on absorbent core structure innovation.
Nephrology and Urology Incontinence Devices Market Competitive Landscape
Integrated multinationals and specialized continence-focused manufacturers split the market between scale-driven institutional contracting and clinical relationship premiums. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with neuromodulation portfolios, dedicated urology and ostomy specialists with direct sales forces, and regional catheter fabricators competing on manufacturing throughput. Dominant competitive moves include portfolio rationalization toward highest-margin hydrophilic and antimicrobial-coated lines, and backward integration into superabsorbent polymer sourcing.
Among diversified medical technology conglomerates, Boston Scientific Corporation and Medtronic occupy positions spanning implantable pulse generators and interventional urology systems. Coloplast exemplifies the specialized continence and ostomy archetype with direct-to-institution commercial infrastructure. B. Braun Melsungen AG anchors the European manufacturing-scale tier with multi-market catheter supply capabilities.
| Leading Market Players |
|---|
| Coloplast |
| Hollister Incorporated |
| ConvaTec Group |
| Boston Scientific Corporation |
| Medtronic |
| Teleflex |
| B. Braun Melsungen AG |
| Becton Dickinson |
| First Quality Enterprises |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp petrochemical corridor anchors silicone feedstock logistics for hydrophilic catheter coatings, with freight cost volatility transmitting directly to manufacturer margin structures and downstream tiered pricing across institutional and home care channels.
Pricing Analysis
Configured-to-order pricing for antimicrobial-coated catheters commands substantial premiums over standard hydrophilic lines, with differentiation resting on FDA 510(k) clearance tier and ISO 10993 biocompatibility certification depth. Three-tier pricing structure across premium, standard, and economy levels stratifies by coating sophistication and clinical validation burden. Pricing pressure stems from Medicare competitive bidding compression in durable medical equipment channels, with home care patients exhibiting highest price sensitivity and integrated delivery networks leveraging volume scale for concession extraction.
Supply Chain Analysis
Extended payment terms from German and Danish catheter manufacturers to superabsorbent polymer suppliers have become standard working capital instruments, with supply-chain finance facilities now underwriting raw material procurement cycles. Manufacturing concentrates in Germany, the United States, and Malaysia, with silicone elastomer and hydrophilic coating chemistry drawing from petrochemical and specialty chemical feedstocks respectively. Single-source vulnerability in hydrophilic polymer additives elevates risk exposure, while distribution runs through direct sales forces for institutional contracts and e-commerce platforms for patient-direct segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from rechargeable neuromodulation systems that compress replacement procedure economics and erode recurring revenue pools historically dependent on device turnover.
For Market Incumbents: Insulate service revenue streams by embedding remote monitoring capabilities into implantable pulse generator portfolios, countering the replacement-interval extension threat from rechargeable systems. Deepen backward integration into superabsorbent polymer sourcing to defend margin position against raw material volatility and private-label absorption competition. Prioritize notified body relationship investment under EU MDR to sustain coating innovation market access speed.
For New Entrants and Emerging Players: Mid-tier home care sensor platforms in United States metropolitan markets represent the most penetrable entry point, with EHR interoperability gaps creating white-space for purpose-built telehealth integrations. India's CDSCO accelerated registration pathway enables direct market access without legacy distributor dependency for absorbent and external device categories. Anchor go-to-market execution through subscription replenishment models that capture recurring patient lifetime value.
For Investors and Strategic Acquirers: Specialized coating technology developers with established FDA 510(k) and EU MDR biocompatibility dossiers offer the most defensible acquisition profile, given certification scarcity and extended validation timelines that protect incumbent positioning. Long-term viability hinges on portfolio exposure to neuromodulation service economics rather than transactional device replacement. Monitor Medicare coverage determination timelines for sacral nerve stimulation in ambulatory surgical centers as volume-shift inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Medicare coverage clarity for sacral nerve stimulation procedures dictates ambulatory surgical center volume allocation. |
| CE Marking Pathway | EU MDR notified body relationships determine catheter coating market access speed and clinical evidence burden. |
| Hospital System Partnership | Integrated delivery network procurement consolidation extracts standardized pricing across multi-facility contracting. |
| Software Companion Development | Sensor-enabled pad integration with telehealth platforms creates subscription revenue in post-acute home settings. |
| Backward Integration | In-house superabsorbent polymer production defends margin position against raw material price volatility. |
Research Methodology
A standing panel of urology clinic directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR notified body certification databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up demand modeling across catheter, neuromodulation, external device, and absorbent product categories triangulated with top-down market sizing from manufacturer revenue disclosures and trade flow analysis.
Scenario-bracketing framed volume projections across the analysis window, with segmentation by product type, technology tier, end user setting, and distribution channel anchoring the analytical structure. CAGRs derived from fitted growth curves applied to category-specific adoption rates, incorporating Medicare coverage expansion trajectories for neuromodulation procedures and EU MDR implementation timelines for coating innovations.
Practitioners should monitor FDA premarket approval backlog durations and EU notified body audit queue lengths for early signals of competitive access shifts. Forecasts reflect assumptions regarding reimbursement stability, regulatory pathway efficiency, and raw material supply continuity. Macroeconomic contraction, MDR certification bottlenecks, or rechargeable battery substitution acceleration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
India Urology Device Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Disposable Ureteroscope Market
Urology
Varicocele Treatment Market
Urology
Cystoscope Market
Urology
Voiding Cystourethrogram Market
Urology
Benign Prostatic Hyperplasia Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Urinary Incontinence Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Urinary Tract Infection (UTI) Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Transrectal Ultrasound Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Global Hydronephrosis Market