
 Global Urinary Tract Infections Therapeutics Market | 2026-2036
Global Urinary Tract Infections Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Urinary Tract Infections Therapeutics Market Intelligence
The divergence between novel, high-potency antibiotics for resistant strains and generic, first-line treatments for uncomplicated cases is rebalancing the market. Pfizer Inc. leverages its extensive R&D pipeline to develop therapies targeting resistant pathogens. In contrast, Bayer AG competes with a broad portfolio addressing various infection severities. Merck & Co., Inc. sustains its market presence through large-scale manufacturing and established distribution channels.
Urinary tract infections therapeutics comprise pharmacological agents designed to eradicate pathogenic bacteria, such as E. coli, from the urinary system. The efficacy of these drugs depends on bacterial susceptibility, often measured by minimum inhibitory concentration (MIC) values. While antibiotics constitute the primary product type, therapies for recurrent infections represent the fastest-growing therapy area due to rising antimicrobial resistance. Acute cystitis continues to command the largest treatment volume, primarily addressed by oral delivery modes.
Regulatory frameworks, including the FDA's Qualified Infectious Disease Product (QIDP) designation and the EMA's PRIME scheme, incentivize the development of new antibiotics. These programs offer expedited reviews and extended market exclusivity to combat antimicrobial resistance. For drug developers, the critical decision involves navigating these pathways to address unmet needs in treating complicated and recurrent UTIs while promoting antimicrobial stewardship to preserve the efficacy of new agents.
Market Dynamics
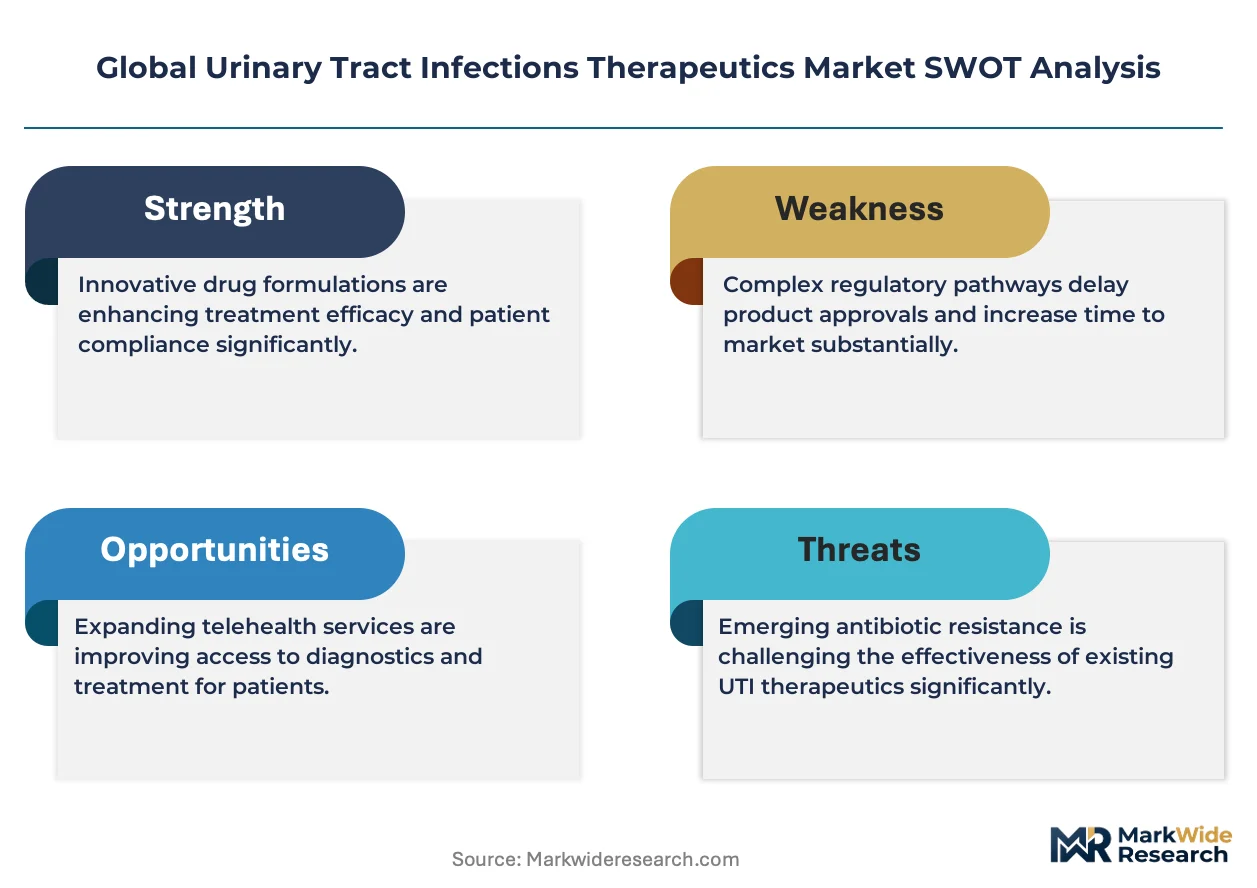
The central dynamic shaping the urinary tract infections therapeutics market is the escalating crisis of antimicrobial resistance. This pressure is creating a bifurcation between the development of high-value, novel agents for resistant pathogens and the commoditized, high-volume market for generic first-line treatments.
Growth Catalysts
- Regulatory Incentives:Frameworks like the FDA's Qualified Infectious Disease Product (QIDP) designation provide expedited review and extended market exclusivity, stimulating investment into new antibiotics for serious infections.
- Recurrent Infection Incidence:A rising prevalence of recurrent UTIs, particularly within aging populations and hospital-acquired infection settings, creates a persistent demand for more effective and long-term therapeutic strategies.
- Healthcare Expenditure:High diagnostic rates and robust healthcare spending in developed nations, especially the United States, support the reimbursement and uptake of both established and newly approved UTI therapeutics.
Market Restraints
- Generic Competition:The widespread availability of low-cost generic antibiotics, such as trimethoprim-sulfamethoxazole and nitrofurantoin, for uncomplicated cystitis limits pricing power and market penetration for newer, more expensive branded drugs.
- Slow Scientific Discovery:The pace of discovering new classes of antibiotics with novel mechanisms of action is slow, leading to a pipeline heavily reliant on modifying existing drug scaffolds, which may not overcome all resistance mechanisms.
- Clinical Trial Hurdles:The high cost and significant failure rate of clinical trials for infectious disease therapies, combined with difficulties in enrolling patients for specific resistant pathogens, deter investment from pharmaceutical companies.
Strategic Opportunities
- Non-Antibiotic Prophylaxis:There is a significant market opportunity for developing non-antibiotic preventative therapies, such as vaccines, cranberry proanthocyanidins, and microbiome modulators, to reduce the incidence of recurrent UTIs and antibiotic use.
- Personalized Medicine:Integrating rapid, point-of-care diagnostics that identify pathogens and their resistance profiles with treatment decisions offers an opportunity to optimize therapy, improve outcomes, and support antimicrobial stewardship.
- Emerging Market Expansion:Increasing healthcare access and a growing middle class in countries like Brazil and India present untapped opportunities for manufacturers of both generic and specialized UTI treatments.
Industry Challenges
- Antimicrobial Stewardship Implementation:A primary operational challenge is the effective, widespread implementation of antimicrobial stewardship programs in hospitals worldwide to ensure new, potent antibiotics are used judiciously and their efficacy is preserved.
- Patent Cliff Management:The finite patent life of successful antibiotics creates a challenging business model, as revenue can decline sharply upon generic entry, making long-term R&D investment difficult to justify.
- Complex Regulatory Harmonization:Navigating the distinct and rigorous approval processes of multiple major regulatory bodies, including the FDA, EMA, and Japan's PMDA, for a single drug is a time-consuming and resource-intensive challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Urinary Tract Infections Therapeutics Market |
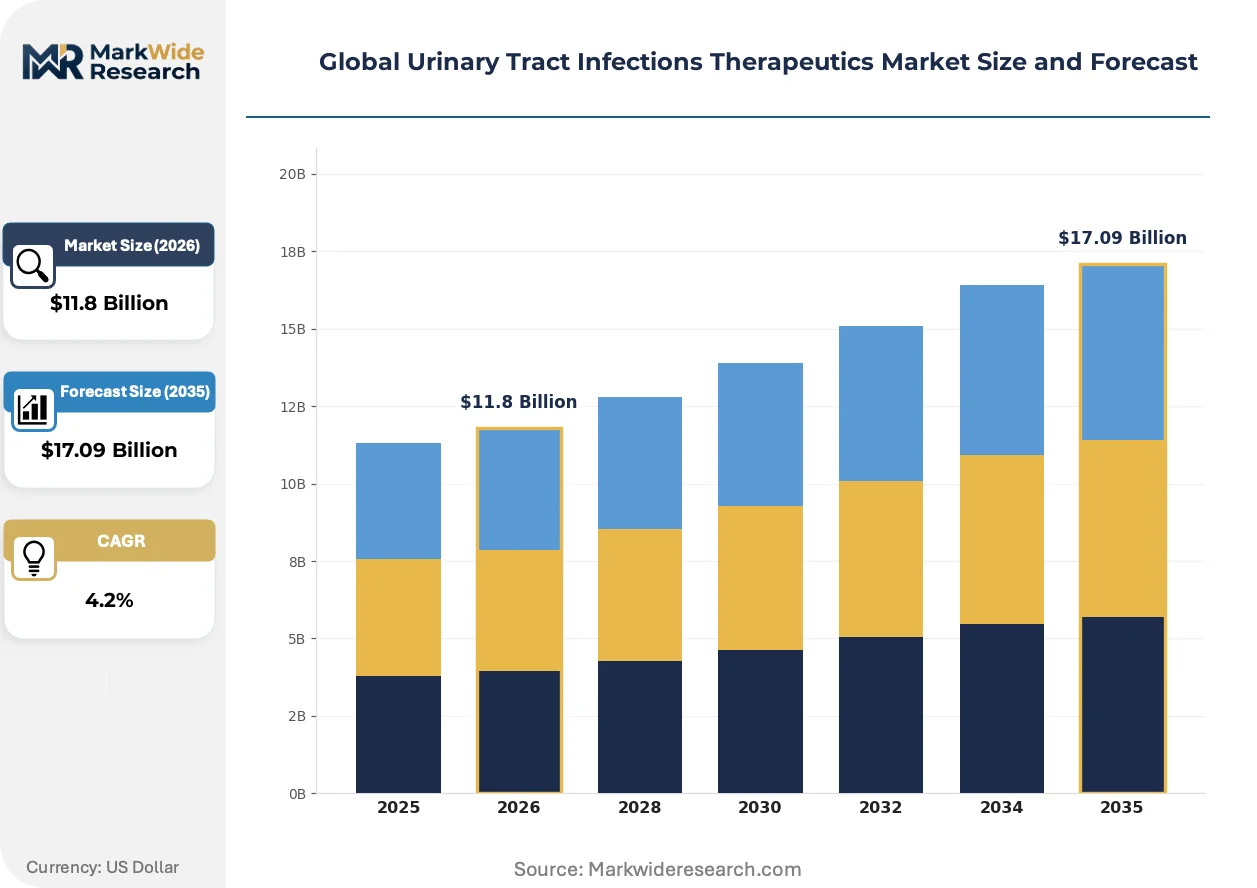
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.09 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antiseptics, Analgesics, Immunomodulators, Probiotics Therapy Area: Acute Cystitis, Recurrent Infections, Pyelonephritis, Asymptomatic Bacteriuria, Urethritis End User: Hospitals, Ambulatory Care Centers, Diagnostic Laboratories, Home Healthcare Services Delivery Mode: Oral, Intravenous, Topical, Intramuscular, Subcutaneous |
| Companies Covered | Bayer AG, Shionogi & Co., Ltd, Pfizer Inc, Melinta Therapeutics, Spero Therapeutics, Merck & Co., Inc, GlaxoSmithKline Plc, Wockhardt, AbbVie Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Urinary Tract Infections Therapeutics Market Strategic Shifts & Innovations
The fight against antimicrobial resistance is forcing a fundamental re-evaluation of treatment paradigms. This is catalyzing innovation in therapeutic modalities beyond traditional small-molecule antibiotics and prompting new commercial and regulatory models to sustain the development pipeline.
Bacteriophage therapy utilizes viruses that specifically infect and kill pathogenic bacteria as a therapeutic agent. Research institutions and specialized biotech firms are advancing its use in clinical settings to combat multidrug-resistant infections unresponsive to conventional antibiotics. This targeted approach is modularizing treatment by enabling the creation of personalized phage cocktails designed to eradicate a patient's specific strain of E. coli or other uropathogens.
Regulatory frameworks are adapting to stimulate development. The EMA's PRIority MEdicines (PRIME) scheme offers early and enhanced scientific and regulatory dialogue for drugs targeting significant unmet needs, such as those for complicated UTIs caused by resistant bacteria. This support primarily benefits smaller, research-focused companies, helping them navigate the complex European Union approval pathway and potentially accelerate patient access to critical new therapies.
A shift toward subscription-style payment models for novel antibiotics is gaining traction in policy discussions. This disrupts the traditional volume-based sales model by delinking a manufacturer's revenue from the quantity of drugs sold, instead paying a fixed annual fee for access. This trend, most visible in pilot programs within the United Kingdom's NHS, aims to encourage R&D for critical antimicrobials that must be used sparingly.
Global Urinary Tract Infections Therapeutics Market Segmentation
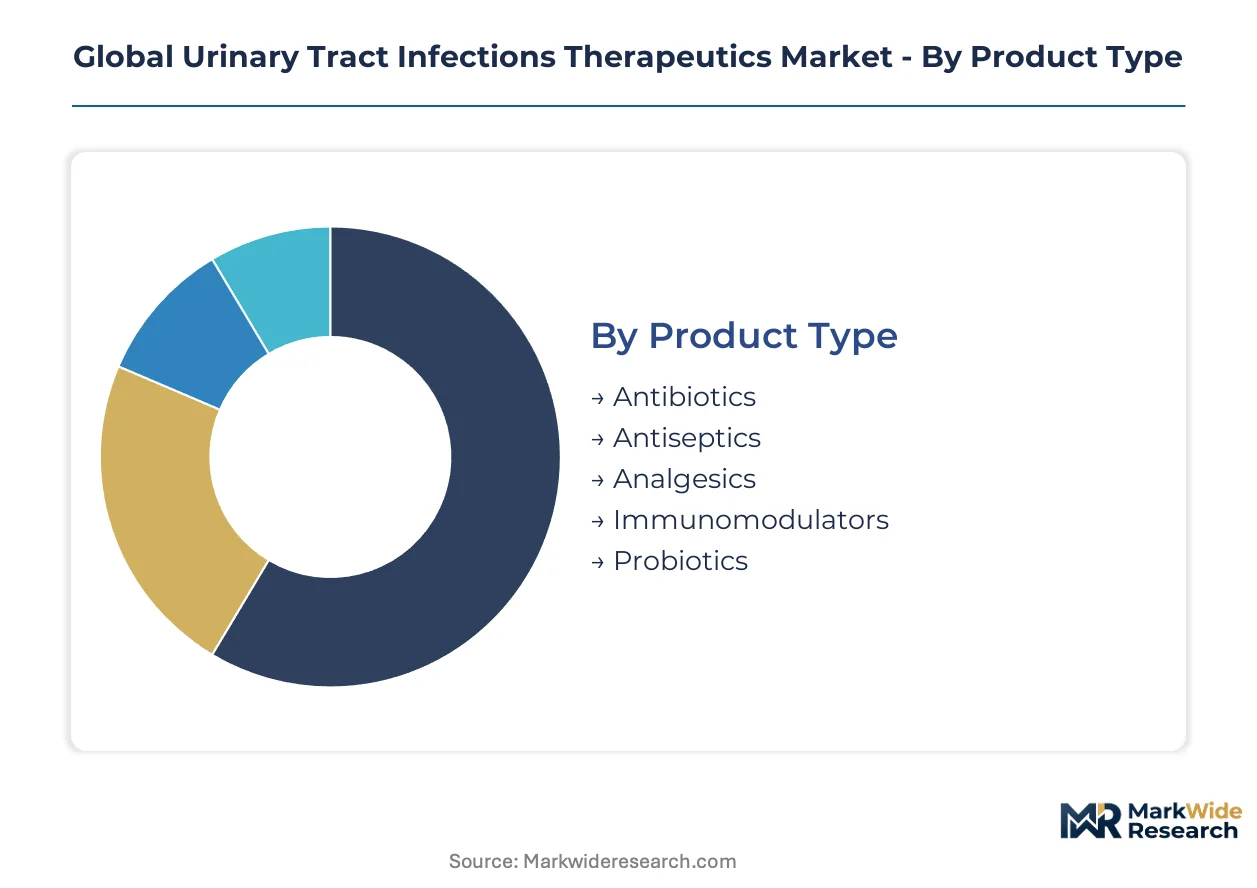
Understanding the distinct segments within the urinary tract infections therapeutics market is critical for strategic planning. This analysis dissects the market by product type, therapy area, end user, and delivery mode, revealing where innovation and demand are most concentrated. Each category highlights specific treatment approaches and patient demographics.
Product Type:
The market for urinary tract infection therapeutics is undergoing a re-evaluation of product types, driven by the need to upgrade efficacy against resistant strains and replace older, less potent options.
- Antibiotics:These pharmacological agents directly target and eradicate pathogenic bacteria causing UTIs, such as E. coli. Demand for novel antibiotics is concentrating in hospital settings across the United States, driven by the escalating challenge of multidrug-resistant infections.
- Antiseptics:Urinary antiseptics inhibit bacterial growth within the urinary tract, offering a prophylactic or adjunctive treatment option. Their use is prevalent in primary care clinics in Germany, supported by efforts to reduce reliance on broad-spectrum antibiotics.
- Analgesics:These medications alleviate pain and discomfort associated with UTIs, primarily managing symptoms rather than treating the infection itself. Their application is widespread in home healthcare services.
- Immunomodulators:These agents modulate the body's immune response to enhance defense against uropathogens. Research into immunomodulators focuses on preventing recurrent infections.
- Probiotics:Probiotics introduce beneficial microorganisms to restore microbial balance and prevent pathogen colonization in the genitourinary tract. Their use is expanding in preventative care.
Volume placements concentrate in Antibiotics; the faster expansion belongs to Probiotics.
Therapy Area:
The application of UTI therapeutics varies significantly by the specific clinical presentation, influencing treatment protocols and market dynamics.
- Recurrent Infections:These involve multiple UTI episodes within a defined period, necessitating long-term management strategies. Demand for advanced therapies for recurrent infections is rising in aging populations across Japan, driven by increased susceptibility and antibiotic resistance.
- Acute Cystitis:This common, uncomplicated bladder infection typically presents with sudden onset symptoms. Treatment volume for acute cystitis remains highest in community pharmacies throughout France, reflecting its high incidence and first-line oral antibiotic management.
- Pyelonephritis:This severe kidney infection requires more aggressive treatment, often involving intravenous antibiotics. Its management is a focus in specialized hospital departments.
- Asymptomatic Bacteriuria:This condition involves bacteria in the urine without symptoms, often managed conservatively except in specific patient groups. Screening and monitoring for this condition occur in prenatal clinics.
- Urethritis:Inflammation of the urethra, frequently caused by sexually transmitted infections, requires targeted antimicrobial therapy. Its treatment is concentrated in sexual health clinics.
Demand for Acute Cystitis drives significant volume, while Recurrent Infections exhibits strong growth potential.
End User:
The distribution and administration of UTI therapeutics are segmented by the healthcare facilities providing patient care, reflecting different levels of acuity and treatment settings.
- Hospitals:These institutions manage severe, complicated, and recurrent UTI cases, often requiring intravenous administration and advanced diagnostics. High healthcare expenditure in Canada supports the comprehensive management of complex UTI cases within hospital environments.
- Ambulatory Care Centers:These outpatient facilities handle uncomplicated UTIs and follow-up care, emphasizing oral therapies and rapid diagnostics. The efficiency of ambulatory care centers in Australia supports broad patient access for routine UTI treatment.
- Diagnostic Laboratories:These facilities perform pathogen identification and antimicrobial susceptibility testing, guiding treatment decisions. Their services are crucial for informing targeted therapy.
- Home Healthcare Services:These services provide care for patients recovering from UTIs, particularly for those requiring prolonged oral antibiotic courses or symptom management. Home healthcare supports patient comfort and reduces hospital readmissions.
The largest patient cohorts are managed within Hospitals, with Ambulatory Care Centers expanding their service delivery.
Delivery Mode:
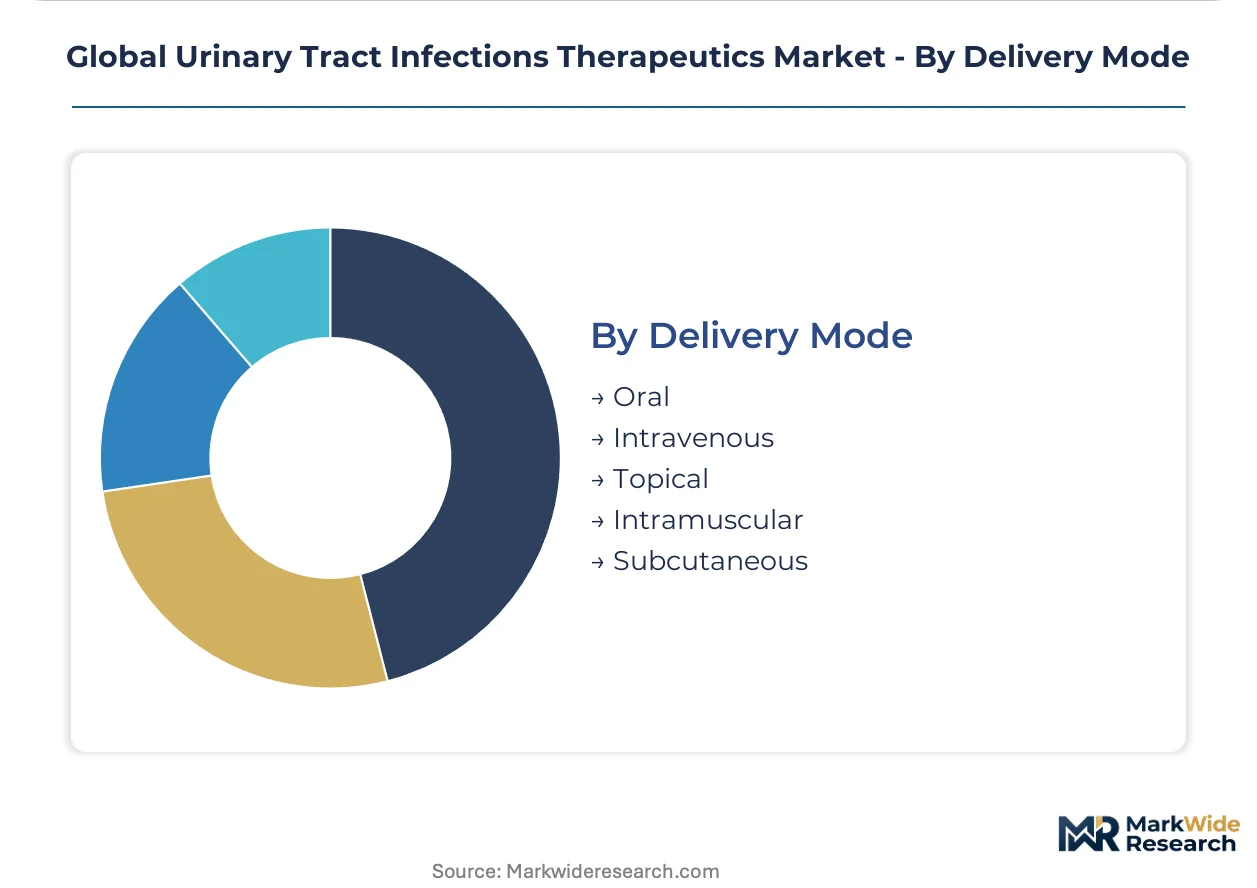
The method of drug administration influences patient compliance, onset of action, and suitability for different infection severities.
- Oral:This mode involves medications taken by mouth, suitable for uncomplicated UTIs and long-term prophylaxis. Oral delivery remains the primary choice for acute cystitis management in the United Kingdom due to its convenience and cost-effectiveness.
- Intravenous:This mode delivers drugs directly into the bloodstream, used for severe infections, hospitalized patients, or when oral absorption is compromised. Intravenous therapies are essential for treating pyelonephritis in critical care units across India.
- Topical:These applications are less common for UTIs but may be used for localized symptoms or external urethral inflammation. Topical treatments offer localized relief for some symptoms.
- Intramuscular:This involves injections into muscle tissue, offering an alternative to oral or intravenous routes for certain antibiotics. Intramuscular administration provides a sustained release of medication.
- Subcutaneous:This mode involves injections under the skin, often used for self-administration of certain medications. Subcutaneous delivery offers a less invasive alternative for some therapies.
Convenience and cost-effectiveness position Oral as the dominant method, though Intravenous addresses critical care needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's extensive biotech research cluster drives significant innovation in novel antimicrobial agents for urinary tract infections. High diagnostic rates and substantial healthcare expenditure across the United States support the uptake of both established and new UTI therapeutics. This concentration of R&D and market demand positions the region as a critical hub.
United States
High diagnostic rates and substantial healthcare expenditure across the United States fuel demand for advanced UTI treatments. The FDA's Qualified Infectious Disease Product (QIDP) designation incentivizes the development of new antibiotics. Boston's biotech corridor is a focal point for research into novel antimicrobial agents and targeted therapies.
Germany
Germany's robust healthcare system supports widespread use of urinary antiseptics in primary care clinics to reduce broad-spectrum antibiotic reliance. The EMA's PRIME scheme offers early scientific advice for drugs addressing unmet medical needs like complicated UTIs. Frankfurt's established pharmaceutical industry maintains strong manufacturing and distribution networks for therapeutics.
Japan
An aging population in Japan creates a persistent demand for advanced therapies to manage recurrent urinary tract infections. The Pharmaceuticals and Medical Devices Agency (PMDA) offers expedited review pathways for innovative drugs targeting serious conditions. Tokyo's prominent medical research centers focus on developing immunomodulators and non-antibiotic preventative strategies.
India
India's increasing healthcare access and expanding middle class drive demand for both generic and specialized UTI treatments. The Central Drugs Standard Control Organization (CDSCO) oversees drug approvals and manufacturing standards across the country. Hyderabad's pharmaceutical manufacturing hub is a significant producer of antibiotics and other essential therapeutics.
United Kingdom
The United Kingdom prioritizes convenient and cost-effective oral delivery for acute cystitis management. The National Health Service (NHS) is piloting subscription-style payment models for novel antibiotics to preserve their efficacy. London's health tech sector is integrating rapid diagnostics with treatment decisions for antimicrobial stewardship.
Global Urinary Tract Infections Therapeutics Market Key Industry Players
Premium-margin players sit above commodity-margin players across the spectrum of specialized versus high-volume treatments for urinary tract infections. The market exhibits a clear tiered structure, with innovators focusing on novel antibiotics for resistant strains and diversified pharmaceutical companies offering broad portfolios across various infection severities. Generic manufacturers primarily compete on cost-effectiveness for first-line therapies, serving a large patient base. Companies engage in significant R&D investment to discover new agents, actively pursue portfolio diversification, and form strategic partnerships to strengthen their market positions.
Within the diversified pharmaceutical archetype, Pfizer Inc. leverages its extensive research and development pipeline for advanced therapies. Bayer AG, a German pharmaceutical company, occupies a position with a broad portfolio addressing various infection severities. Merck & Co., Inc., a US-based entity, anchors its market presence through large-scale manufacturing and established distribution channels for essential medications. These entities exemplify the strategic balance between innovation for resistant pathogens and widespread availability of foundational treatments.
| Leading Market Players |
|---|
| Bayer AG |
| Shionogi & Co., Ltd |
| Pfizer Inc |
| Melinta Therapeutics |
| Spero Therapeutics |
| Merck & Co., Inc |
| GlaxoSmithKline Plc |
| Wockhardt |
| AbbVie Inc |
| Others |
Cost & Logistics Intelligence
Antimicrobial stewardship programs, a crucial public health mandate, gate the qualified supply of novel antibiotics by ensuring judicious use. This mandate also enables premium pricing for therapies targeting resistant pathogens.
Pricing Analysis
Clinical outcome improvement anchors pricing for advanced urinary tract infection therapeutics. A hybrid model combines value-based pricing for novel antibiotics targeting resistant pathogens with transactional per-unit pricing for generic first-line treatments. Efficacy against multidrug-resistant strains and regulatory designations like QIDP drive premium differentiation. Pricing pressure intensifies for generic antibiotics due to widespread availability, while hospitals show lower price sensitivity for critical novel agents.
Supply Chain Analysis
Logistics and specialized freight costs significantly impact the supply chain for urinary tract infection therapeutics. Geographic supply concentrates in India and China for Active Pharmaceutical Ingredients (APIs), with finished product manufacturing in Germany and the United States. The supply chain relies on complex chemical intermediates, and single-source vulnerability for novel APIs presents a structural risk. Distribution runs through a multi-tiered network involving wholesalers and hospital pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urinary tract infection therapeutics market is entering a technology-transition phase. Bacteriophage therapy represents a novel modality actively displacing reliance on traditional small-molecule antibiotics for multidrug-resistant infections.
For Market Incumbents: Hedge against the patent cliff of established antibiotics by diversifying into non-antibiotic prophylaxis. Invest in advanced R&D for novel antimicrobial agents, leveraging regulatory incentives like QIDP designation. Control distribution channels to maintain market share for first-line treatments amidst generic competition.
For New Entrants and Emerging Players: Enter via niche segments focused on non-antibiotic prophylaxis, such as microbiome modulators or vaccines for recurrent UTIs. Target personalized medicine approaches, integrating rapid diagnostics to optimize treatment for specific resistant pathogens. Develop bacteriophage therapies for multidrug-resistant infections, focusing on hospital-acquired settings where unmet needs are highest.
For Investors and Strategic Acquirers: Successful pilot programs for subscription-style antibiotic payment models are the leading indicator that novel funding mechanisms can sustain R&D. The market offers long-term viability for companies addressing the escalating antimicrobial resistance crisis. Identify acquisition targets with strong intellectual property in bacteriophage therapy or advanced immunomodulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel therapeutics targeting resistant UTI strains. |
| Regulatory Approval Pathway | Expedites access to critical new drugs through schemes like FDA QIDP. |
| Manufacturing Scale-Up | Ensures broad availability of both generic and specialized UTI treatments globally. |
| Strategic Partnership | Combines R&D expertise with established distribution networks for market reach. |
| Pipeline Diversification | Reduces reliance on traditional antibiotics by exploring non-antibiotic solutions. |
Research Approach
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for this analysis, supplemented by academic publications. Primary interviews with R&D executives, regulatory affairs specialists, and hospital procurement managers provided qualitative insights. This approach combined bottom-up data collection with top-down validation from industry experts.
Historical trendline analysis established foundational growth patterns across the analysis window. The forecast framework segmented the market by product type, therapy area, end user, delivery mode, and regional antimicrobial resistance rates. Compound annual growth rates were derived from a multi-variant regression model. Key inputs included evolving resistance patterns and aging population demographics.
Revisions become necessary when significant new antibiotic classes emerge or unforeseen regulatory shifts impact market access. Forecasts reflect assumptions regarding antimicrobial resistance evolution and healthcare policy. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Global Lithotripsy Market
Urology
Ureteral Obstruction Market
Urology
Single Use Cystoscope Market
Urology
Continence Care Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Global Prostate Cancer Market
Urology
Pyelonephritis Treatment Market
Urology
Urethral Stricture Market
Urology
Nocturia Market
Urology
Genitourinary Cancers Treatment Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Ureterorenoscopes Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Obstructive Uropathy Treatment Market
Urology
Hematuria Treatment Market
Urology
Global Prostate Health Market