
 Asia-Pacific Bladder Disorders Market | 2026-2036
Asia-Pacific Bladder Disorders Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bladder Disorders Market Outlook
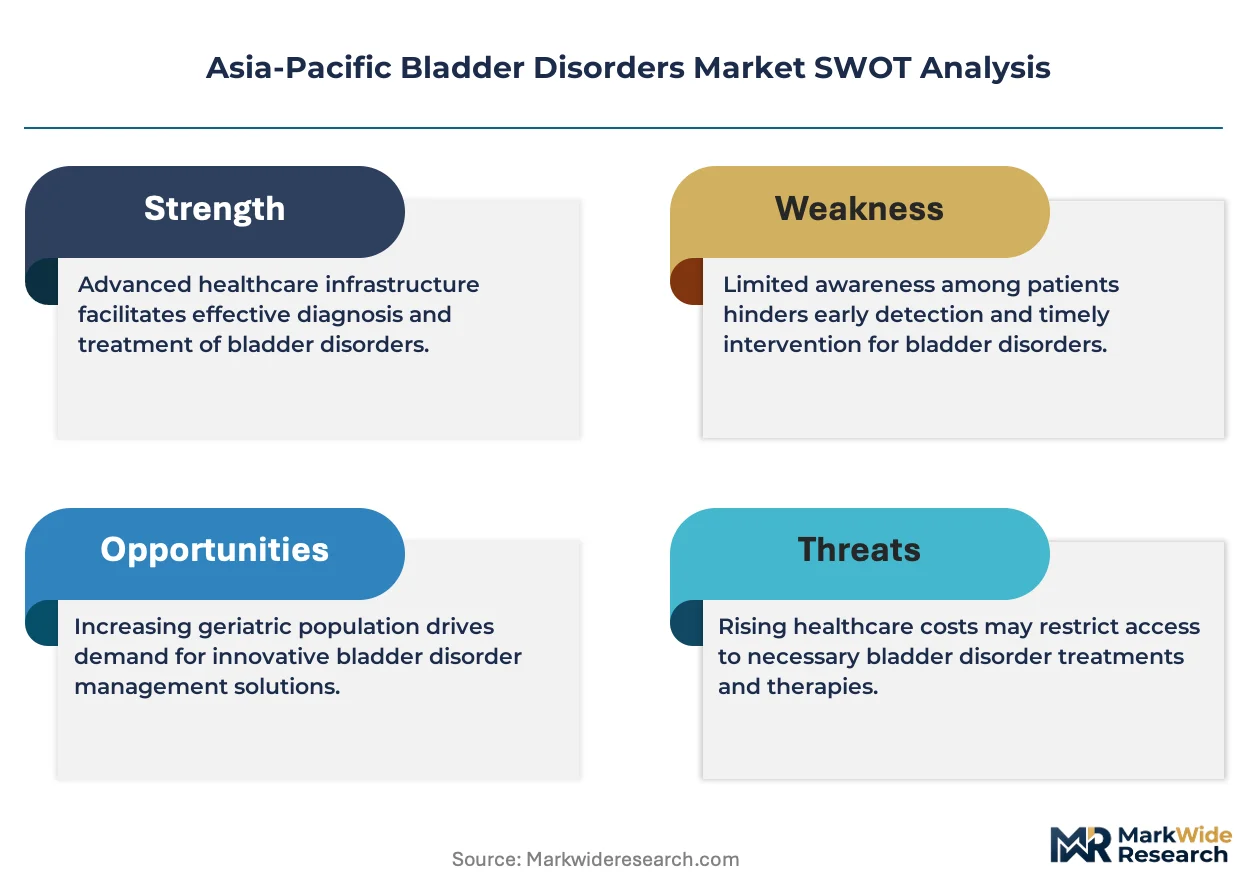
Hospital procurement networks across Southeast Asia are reshaping how bladder disorder therapies reach patients. Astellas Pharma leverages its established urology franchise to dominate specialty pharmacy channels in Japan and South Korea. Pfizer competes through primary care physician access programs that sustain volume in oral overactive bladder medications across Australia and India.
Bladder disorders encompass pathological conditions affecting urinary storage and voiding function, including overactive bladder syndrome characterized by detrusor overactivity with frequency and urgency symptoms, and bladder malignancies requiring transurethral resection and intravesical chemotherapy protocols. Medications targeting muscarinic receptors and beta-3 adrenergic agonists serve as first-line pharmacotherapy for urge incontinence, while surgical instruments enable minimally invasive tumor resection and urinary diversion procedures. The therapy area segment positions overactive bladder as the largest volume pool due to prevalence in aging populations, though bladder cancer commands premium pricing through intravesical delivery modes that concentrate margin in hospital settings.
Japan's PMDA, Australia's TGA, and India's CDSCO enforce divergent clinical evidence standards that fragment product registration timelines and shape regional launch sequencing for device-drug combinations. China's NMPA has tightened post-market surveillance for imported catheters and imaging systems, compelling manufacturers to localize quality management systems. Stakeholders must monitor how reimbursement harmonization between national health insurance schemes and private payers in Indonesia, Thailand, and Vietnam influences site-of-care shifts from hospitals to homecare settings.
Market Dynamics
Hospital procurement consolidation across Southeast Asia is compressing vendor margins while elevating technical compliance requirements for bladder disorder device suppliers. China's NMPA localization mandates and Japan's PMDA streamlined pathways for combination therapies are bifurcating market access strategies.
Growth Catalysts
- Japan's PMDA Sakigake designation:Accelerated review timelines for novel drug-device combinations are pulling multinational trials into Japanese sites earlier in development cycles.
- Homecare catheter demand:Australia's aged care infrastructure expansion and India's Ayushman Bharat home health extensions are creating pull-through for intermittent catheter supply chains.
- Transurethral laser lithotripsy:Ho:YAG and thulium fiber platforms are displacing pneumatic ballistic systems in tertiary hospital upgrade cycles across South Korea and Thailand.
Market Restraints
- Silicone raw material concentration:Three Japanese and Chinese chemical conglomerates control medical-grade silicone supply, exposing catheter and stent manufacturers to input cost volatility and allocation risk.
- NMPA quality system localization:Imported imaging and endoscopic devices face mandatory onshore quality management audits that extend registration timelines by 12-18 months.
- Oral beta-3 agonist substitution:Mirabegron and vibegron tablets are eroding intravesical botulinum toxin volumes in mild-to-moderate overactive bladder segments.
Strategic Opportunities
- Vietnam private hospital buildout:Vinmec and Hoan My chains are importing complete urology suites, creating first-mover advantages for integrated device suppliers.
- Tele-urodynamics:Remote pressure-flow monitoring convergence with 5G infrastructure is opening ambulatory diagnostic channels outside metropolitan hospital clusters.
- Indonesia's JKN-KIS reimbursement expansion:National health insurance coverage for overactive bladder pharmacotherapy is widening addressable patient pools beyond cash-pay segments.
Industry Challenges
- Interventional urologist training pipelines:Fellowship programs in advanced endourology remain concentrated in Tokyo, Seoul, and Melbourne, constraining procedure volume growth in secondary cities.
- Dual regulatory dossier requirements:Drug-device combination submissions must satisfy divergent PMDA, TGA, and CDSCO clinical evidence standards, fragmenting development resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bladder Disorders Market |
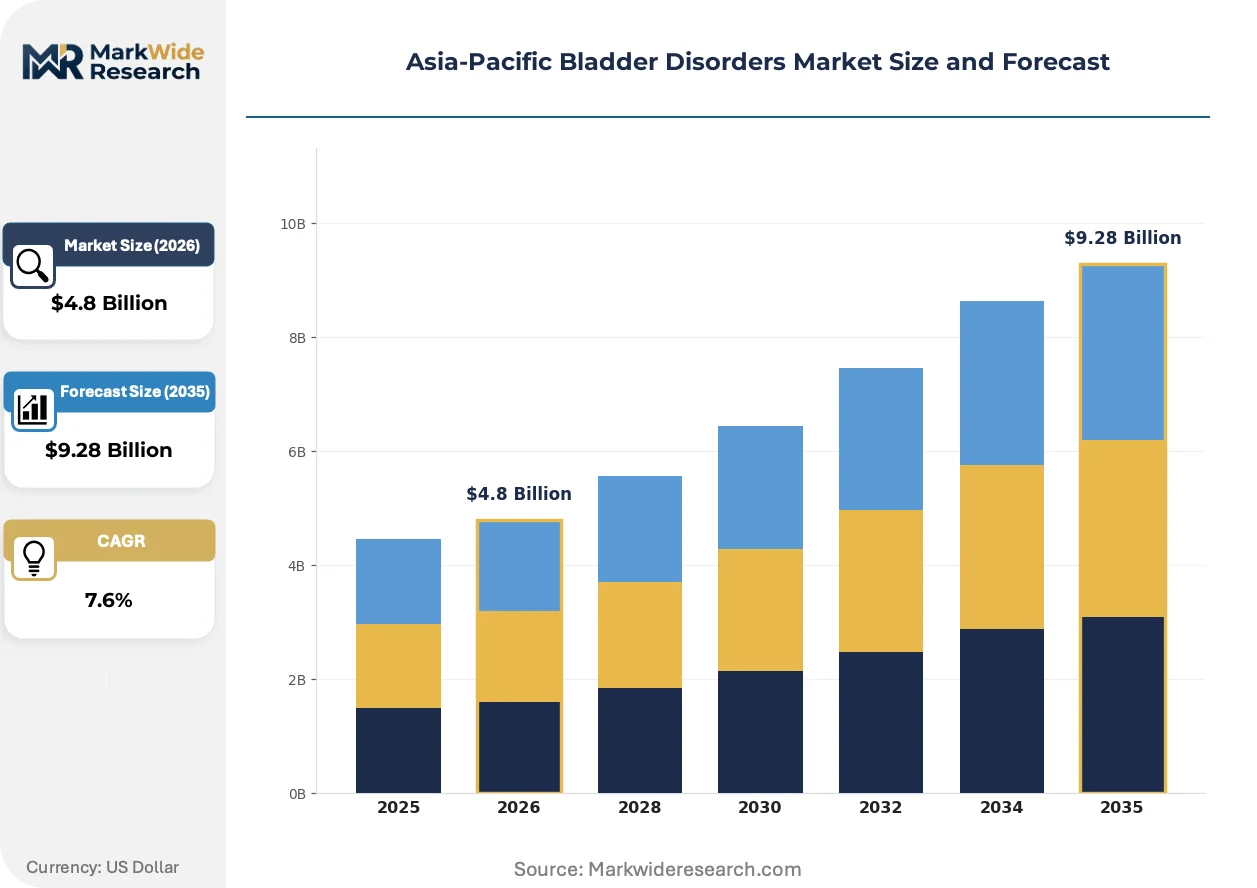
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Medications, Surgical Instruments, Imaging Devices Therapy Area: Overactive Bladder, Bladder Cancer, Urinary Incontinence, Urinary Tract Infections End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Delivery Mode: Injectable, Oral, Topical, Intravesical |
| Companies Covered | Astellas Pharma, Pfizer, AbbVie, AstraZeneca, Johnson & Johnson, Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Endo Pharmaceuticals, Novartis, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bladder Disorders Market Strategic Shifts
Digital bladder diary applications and wearable voiding sensors are capturing real-world evidence that reshapes payer negotiations and clinical trial endpoints. Device manufacturers are embedding connectivity modules to secure recurring revenue streams beyond hardware sales.
Single-use flexible cystoscopes with disposable sheath systems are rendering obsolete capital-intensive reusable endoscope reprocessing infrastructure. Regional hospital procurement coalitions in Australia and Singapore are mandating these platforms for infection control compliance. The shift is compressing capital equipment replacement cycles while elevating consumable revenue per procedure.
China's NMPA has implemented real-world evidence pathways for imported urological devices that previously required domestic clinical trials. The policy change is accelerating registration timelines for established European and Japanese manufacturers. Bladder cancer imaging systems and intravesical delivery catheters are the primary categories benefiting from this regulatory recalibration.
Site-of-care migration is fragmenting traditional hospital-centric distribution models. Specialty pharmacy networks in Japan and primary care physician dispensing in India are capturing overactive bladder medication volumes that previously flowed through hospital outpatient departments. Thailand's universal coverage scheme is piloting home delivery for intermittent catheter supplies, bypassing wholesale pharmaceutical distributors entirely.
Asia-Pacific Bladder Disorders Market Segmentation
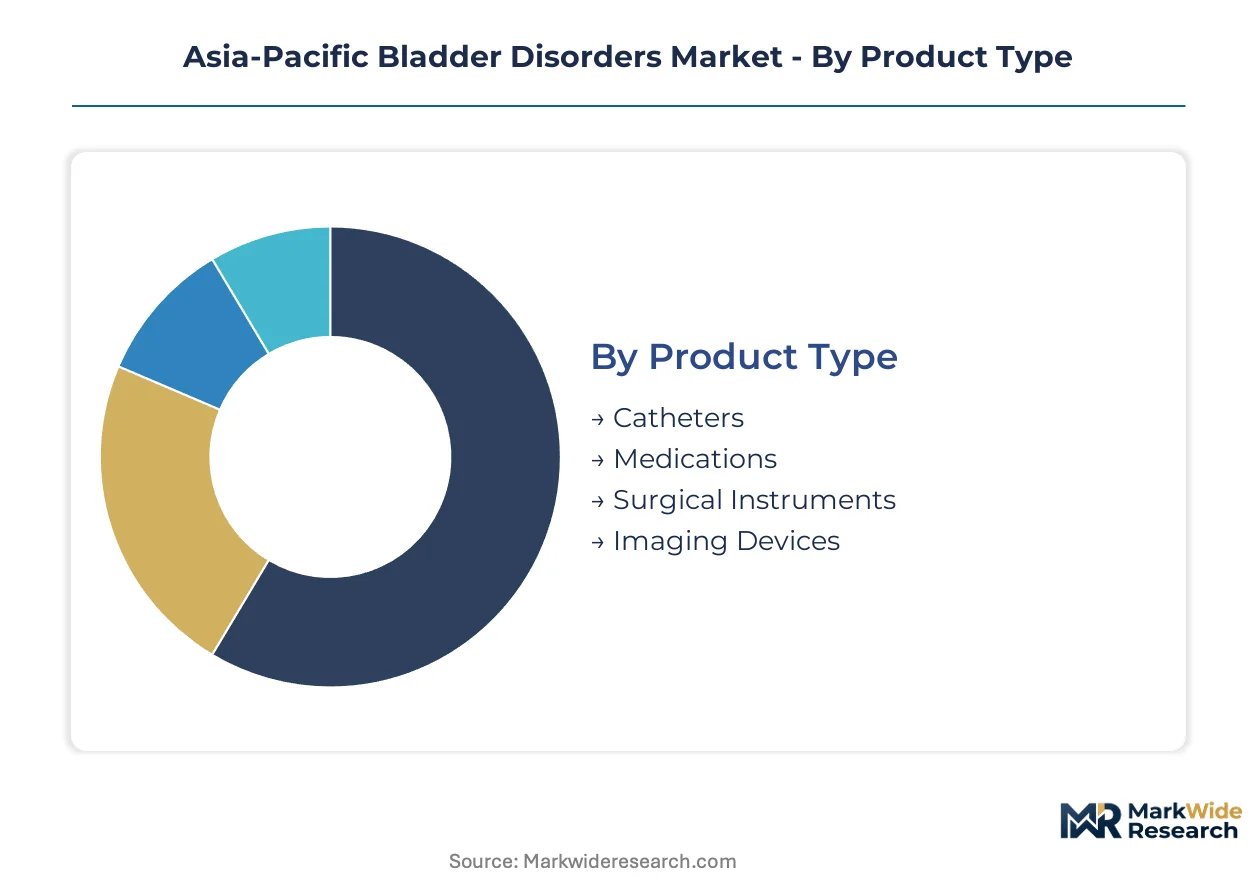
Segmentation in the Asia-Pacific bladder disorders market reveals distinct procurement rhythms and margin profiles across product categories. Hospital procurement networks favor capital-intensive surgical platforms with extended replacement cycles, while homecare channels drive recurring revenue through consumable catheter supplies.
Product Type:
Catheters turn inventory fastest with monthly replenishment cycles, whereas imaging devices lock capital for 7-10 year depreciation schedules.
- Catheters:Intermittent and indwelling silicone-based designs dominate homecare procurement in Australia's aged care infrastructure and India's Ayushman Bharat extensions. Procurement consolidation across Southeast Asian hospital coalitions is elevating infection-control specifications for disposable sheath systems.
- Medications:Oral muscarinic antagonists and beta-3 adrenergic agonists constitute the highest-volume pharmaceutical category, with primary care physician dispensing in India and specialty pharmacy channels in Japan capturing volumes previously flowing through hospital outpatient departments.
- Surgical Instruments:Ho:YAG and thulium fiber laser platforms for transurethral resection command premium positioning in tertiary hospital upgrade cycles across South Korea and Thailand.
- Imaging Devices:Flexible cystoscopy systems with embedded connectivity modules face NMPA-mandated onshore quality audits extending registration timelines.
Catheters anchor the volume base while imaging devices gain share at the steepest rate through 5G-enabled tele-urodynamics integration.
Therapy Area:
Cost tier stratification separates chronic management conditions from acute intervention pathways with diverging reimbursement mechanics.
- Overactive Bladder:Detrusor overactivity with urgency-frequency symptoms represents the largest addressable population pool across aging demographics in China and Japan. Oral beta-3 agonist substitution is compressing intravesical botulinum toxin volumes in mild-to-moderate segments.
- Bladder Cancer:Transurethral resection with intravesical chemotherapy protocols concentrates margin in hospital settings through premium-priced delivery catheters and imaging systems. China's NMPA real-world evidence pathways are accelerating registration for established European and Japanese manufacturers in this category.
- Urinary Incontinence:Stress and mixed incontinence variants drive sling procedure volumes and pelvic floor rehabilitation device demand across Australian private hospital networks.
- Urinary Tract Infections:Recurrent infection management protocols sustain antimicrobial catheter coating specifications and diagnostic test strip volumes.
Overactive bladder commands the widest patient pool while bladder cancer expands most quickly through intravesical delivery mode innovation.
End User:
Site-of-care migration is fragmenting traditional hospital-centric distribution models toward ambulatory and home-based channels.
- Hospitals:Tertiary centers in Tokyo, Seoul, and Melbourne concentrate advanced endourology fellowship training and complex tumor resection volumes. Procurement coalitions in Australia and Singapore are mandating single-use flexible cystoscope platforms.
- Clinics:Ambulatory urology clinics in Vietnam's Vinmec and Hoan My chains are importing complete diagnostic suites, creating first-mover advantages for integrated device suppliers.
- Homecare Settings:Thailand's universal coverage scheme pilots home delivery for intermittent catheter supplies, bypassing wholesale pharmaceutical distributors entirely.
- Rehabilitation Centers:Pelvic floor therapy and voiding retraining programs extend medication adherence monitoring through digital bladder diary applications.
Hospitals retain the capital equipment anchor while homecare settings climb the fastest through reimbursement-driven site-of-care shifts.
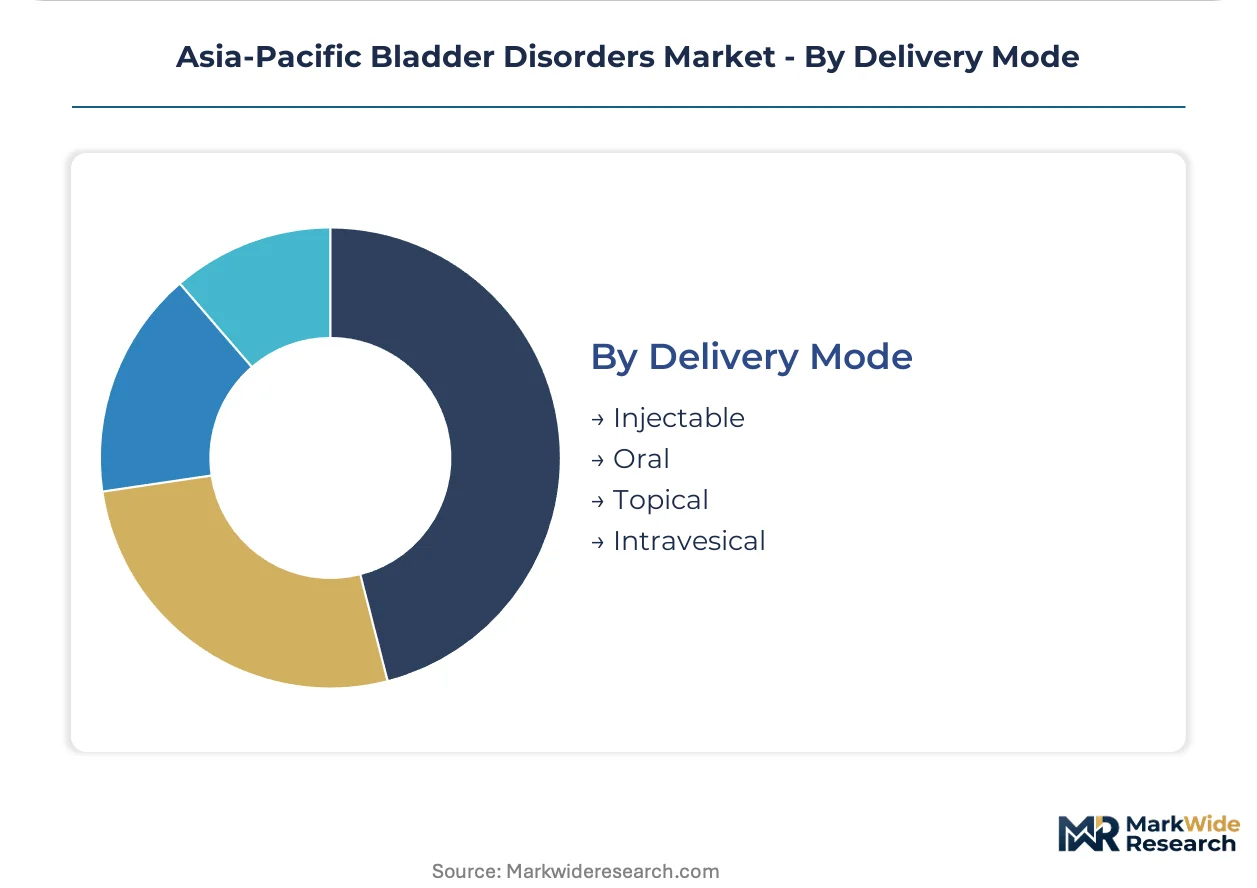
Delivery Mode:
Margin concentration tracks invasiveness gradient, with parenteral and intravesical routes capturing premium positioning over oral generics.
- Injectable:Intravesical botulinum toxin for refractory overactive bladder maintains hospital outpatient department capture in Japan and South Korea despite oral beta-3 agonist erosion in milder segments.
- Oral:Mirabegron and vibegron tablets sustain Pfizer's primary care physician access programs across Australia and India, with Indonesia's JKN-KIS reimbursement expansion widening addressable pools.
- Topical:Estrogen creams and lidocaine patches for post-menopausal urogenital atrophy concentrate in specialty pharmacy and direct-to-patient channels.
- Intravesical:Chemotherapy instillation protocols for non-muscle-invasive bladder cancer command the highest per-procedure revenue through device-drug combination catheters.
Oral formulations anchor volume accessibility while intravesical delivery gains share fastest through combination therapy premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese tertiary centers where PMDA streamlining sustains premium positioning, while Indonesian and Vietnamese markets operate on compressed procurement margins through national insurance schemes.
China
Aging demographics and private healthcare infrastructure expansion drive diagnostic volumes for bladder conditions. NMPA mandates onshore quality management audits for imported imaging and endoscopic devices, extending registration timelines by 12-18 months. Shanghai and Beijing medical device clusters concentrate localization investments by European and Japanese manufacturers seeking real-world evidence pathway benefits.
Japan
Specialty pharmacy channels capture overactive bladder medication volumes through Astellas Pharma's established urology franchise. PMDA's Sakigake designation accelerates review timelines for novel drug-device combinations, pulling multinational trials into Japanese sites earlier. Tokyo, Osaka, and Nagoya tertiary centers concentrate advanced endourology fellowship training and complex tumor resection volumes.
Australia
Aged care infrastructure expansion creates pull-through for intermittent catheter supply chains. TGA enforces clinical evidence standards that fragment product registration timelines relative to other Asia-Pacific regulators. Sydney and Melbourne hospital procurement coalitions mandate single-use flexible cystoscope platforms for infection control compliance.
South Korea
Ho:YAG and thulium fiber laser platforms displace pneumatic ballistic systems in tertiary hospital upgrade cycles. MFDS regulates combination drug-device therapies with standards converging toward PMDA frameworks. Seoul Capital Area medical centers anchor premium surgical instrument procurement despite national insurance reimbursement compression.
Indonesia
JKN-KIS national health insurance coverage expansion widens addressable patient pools for overactive bladder pharmacotherapy beyond cash-pay segments. The country's national pharmaceutical regulator enforces post-market surveillance requirements that elevate compliance costs for imported devices. Jakarta and Surabaya private hospital networks drive initial uptake of integrated urology diagnostic suites.
Asia-Pacific Bladder Disorders Market Competitive Environment
Established pharmaceutical conglomerates and diversified medical device manufacturers split the market across medication and interventional segments. Hospital procurement consolidation across Southeast Asia compresses vendor margins while elevating technical compliance requirements. Three strategic archetypes dominate: urology-focused pharmaceutical specialists, diversified surgical device suppliers, and primary care physician access program operators. Competitive moves center on geographic expansion through localized quality management systems and portfolio diversification into combination drug-device therapies.
Among pharmaceutical specialists, Astellas Pharma exemplifies the urology franchise archetype through its dominance of specialty pharmacy channels in Japan and South Korea. Pfizer occupies a position within primary care physician access programs that sustain oral medication volumes across Australia and India. Johnson & Johnson represents the diversified surgical device archetype, anchoring hospital procurement networks for transurethral resection and imaging platforms.
| Leading Market Players |
|---|
| Astellas Pharma |
| Pfizer |
| AbbVie |
| AstraZeneca |
| Johnson & Johnson |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Endo Pharmaceuticals |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Singapore container freight corridors transmit silicone feedstock cost volatility directly into catheter and stent pricing tiers, compressing margins for manufacturers locked into long-term hospital supply contracts while rewarding agile distributors with spot-market sourcing flexibility across Southeast Asian procurement coalitions.
Pricing Analysis
Configured-to-order pricing for drug-device combination therapies commands spreads of 40-60% above standard catheter catalog pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by infection-control certification grade and connectivity module inclusion. Cost compression in economy-tier intermittent catheters is intensifying because Indonesian and Vietnamese national insurance schemes enforce reference pricing. Hospital procurement coalitions in Australia and Singapore exhibit lowest price sensitivity due to infection-control compliance mandates, while India's Ayushman Bharat extensions drive highest volume-price elasticity.
Supply Chain Analysis
Medical-grade silicone polymer production concentrates in Japan, China, and South Korea, with three chemical conglomerates controlling specification-grade supply for catheter and stent manufacturers. Raw material dependencies extend to thulium fiber for laser lithotripsy platforms and CMOS sensors for flexible cystoscopy systems. Single-source vulnerability in Japanese silicone supply exposes downstream device makers to allocation risk during semiconductor-industry demand spikes. Distribution runs through hospital procurement coalitions in Australia and Singapore, specialty pharmacy networks in Japan, and direct-to-patient home delivery pilots in Thailand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific bladder disorder therapy demand is recovering from pandemic-deferred elective procedure backlogs, with aging demographics in China and Japan providing structural volume support through the mid-2030s.
For Market Incumbents: Insulate market position through backward integration into medical-grade silicone compounding and captive supply of thulium fiber laser components. Secure NMPA quality system localization ahead of competitors to compress registration timelines for imaging devices. Channel control through exclusive hospital procurement coalition memberships in Australia and Singapore defends against single-use flexible cystoscope substitution. For New Entrants and Emerging Players: Build out tele-urodynamics service capabilities targeting Vietnam's Vinmec and Hoan My private hospital chains, where complete urology suite imports create first-mover advantages for integrated diagnostic suppliers. Indonesia's JKN-KIS reimbursement expansion for overactive bladder pharmacotherapy represents the most penetrable volume pool. Go-to-market execution should anchor on 5G infrastructure partnerships with national carriers for remote pressure-flow monitoring deployment. For Investors and Strategic Acquirers: Urology-focused pharmaceutical specialists with established PMDA Sakigake track records and specialty pharmacy channel dominance in Japan offer the strongest acquisition profile for long-term viability across a 5-10 year holding period. Watch for NMPA real-world evidence pathway expansion beyond bladder cancer imaging into overactive bladder digital therapeutics as the inflection indicator signaling regulatory arbitrage opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Sakigake Designation Pursuit | Accelerated review timelines pull multinational trials into Japanese sites earlier in development cycles. |
| NMPA Quality System Localization | Onshore audits compress registration timelines by 12-18 months for established European and Japanese manufacturers. |
| Tele-Urodynamics Platform Development | 5G convergence opens ambulatory diagnostic channels outside metropolitan hospital clusters in Thailand and Indonesia. |
| Single-Use Cystoscope Portfolio Expansion | Infection-control mandates from Australian procurement coalitions render reusable endoscope infrastructure obsolete. |
| Homecare Catheter Supply Chain Integration | Thailand's universal coverage home delivery pilots bypass wholesale pharmaceutical distributors entirely. |
Study Parameters
Cross-validation between hospital procurement database analysis and regulatory filing review anchors the qualitative findings in this study. Primary interviews with urology department heads, biomedical engineers, GPO contracts managers, and specialty pharmacy dispensing operators were combined with secondary validation against PMDA approval databases, NMPA quality system audit records, and hospital capital expenditure disclosures. Bottom-up procedure volume modeling and top-down pharmaceutical consumption analysis were triangulated to establish market sizing.
Calibration against historical reimbursement policy shifts and hospital procurement cycle timing informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, therapy area, end user, and delivery mode, with additional granularity on regulatory pathway clustering by national health insurance scheme. CAGRs were derived from procedure volume growth rates, pharmaceutical consumption trends, and device replacement cycle acceleration patterns. Forecast inputs incorporated PMDA Sakigake designation velocity and NMPA real-world evidence pathway adoption rates.
Stress conditions across silicone raw material allocation disruptions, JKN-KIS reimbursement expansion velocity, and 5G infrastructure deployment timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hospital procurement coalition consolidation and site-of-care migration trajectories. Cross-checking against national health insurance claims data and hospital medical device procurement registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Varicocele Treatment Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
North America Transrectal Ultrasound Market
Urology
Urinary Retention Therapeutics Market
Urology
Transrectal Ultrasound Market
Urology
Suprapubic Catheters Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Pyelonephritis Treatment Market
Urology
Urinary Catheters Market
Urology
Uropathy Treatment Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Prostate Cancer Treatment Market
Urology
Urology Lasers Market
Urology
Penile Cancer Market
Urology
Europe Bladder Disorders Market