
 Surgical Site Infection Control Market | 2026-2036
Surgical Site Infection Control Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Site Infection Control Market Intelligence
Ambulatory surgical centers are unwinding historical hospital-centric procurement patterns for infection control products. 3M Co. leverages its adhesive science portfolio to dominate barrier technology segments across outpatient settings. Becton Dickinson and Co. sustains R&D intensity in antimicrobial coating systems for vascular access devices. STERIS plc anchors sterilization service contracts with multi-year agreements that lock in recurring revenue from surgical centers.
Surgical site infection control encompasses preoperative skin preparation, intraoperative barrier systems, instrument sterilization validation, and postoperative wound monitoring protocols designed to reduce pathogen burden at incision sites. Antimicrobial agents containing chlorhexidine gluconate or povidone-iodine achieve bacterial load reduction exceeding logarithmic thresholds specified by clinical guidelines. Surgical drapes and adhesive barriers command premium positioning in cardiac and orthopedic applications where procedure duration elevates contamination risk. UV sterilization technology competes for adoption in ambulatory settings seeking alternatives to chemical-based terminal cleaning.
FDA enforces premarket notification requirements for antimicrobial devices while EPA regulates hospital disinfectant efficacy claims against specified pathogen panels. EMA's Medical Device Regulation mandates clinical evidence for infection prevention claims across European Economic Area markets. Stakeholders must monitor evolving CMS quality metrics and EU MDR technical documentation requirements to align product development with reimbursement-linked compliance thresholds.
Market Dynamics
CMS reimbursement penalties for hospital-acquired conditions are forcing ambulatory surgical centers to upgrade infection prevention infrastructure faster than historical replacement cycles. This regulatory pressure compresses procurement timelines and elevates validation requirements for barrier technologies and sterilization protocols.
Growth Catalysts
- CMS Hospital-Acquired Condition Reduction Program:Financial penalties tied to SSI rates drive capital allocation toward validated preoperative skin preparation systems and antimicrobial barriers in US outpatient facilities.
- Antimicrobial coating chemistry:Advances in chlorhexidine-impregnated adhesive technologies extend effective bacterial suppression through prolonged orthopedic procedures, expanding addressable procedure volume.
- German hospital consolidation:Large Klinikverbund networks centralize procurement for infection control products, creating volume commitments that favor suppliers with multi-product portfolios and sterilization service capabilities.
Market Restraints
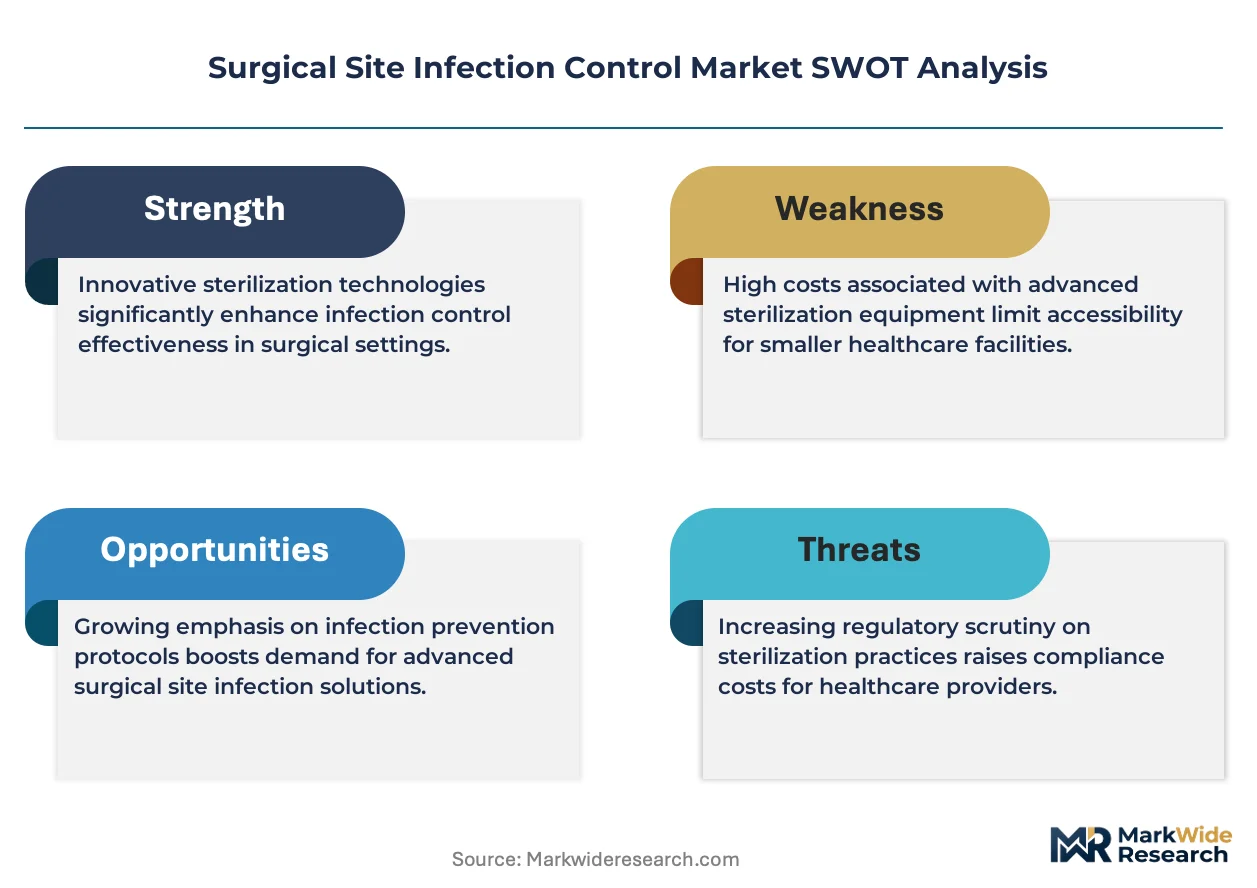
- Isopropyl alcohol feedstock volatility:Preoperative skin preparation formulations depend on petrochemical-derived alcohols, exposing margin structures to energy price swings and supply allocation from pharmaceutical and electronics competitors.
- Single-source sterilization equipment:Ethylene oxide sterilization capacity concentrates in limited geographic zones, creating vulnerability for device manufacturers dependent on terminal sterilization validation.
- UV-C surface disinfection:Terminal cleaning alternatives achieve log reduction claims without consumable chemistry, threatening recurring revenue models built on disinfectant and wipe replenishment cycles.
Strategic Opportunities
- Polish and Romanian surgical center buildouts:EU structural fund investments in Eastern European healthcare infrastructure create first-mover advantages for suppliers establishing service contracts before procurement standardization.
- AI-enabled wound monitoring:Computer vision algorithms analyzing postoperative incision photography enable remote surveillance protocols, converging infection control with telehealth reimbursement frameworks.
- EMA MDR technical documentation mandates:Clinical evidence requirements for infection prevention claims favor established manufacturers with post-market surveillance databases, creating barriers for commodity entrants.
Industry Challenges
- Sterilization process engineering talent:Validating novel low-temperature sterilization cycles requires expertise in microbiology, materials science, and regulatory submission that concentrates in aging specialist workforces.
- Legacy autoclave infrastructure:Retrofitting hospital sterilization departments for hydrogen peroxide vapor or ozone modalities demands physical plant modifications and workflow retraining that extend implementation timelines.
- ISO 17664 documentation harmonization:Inconsistent interpretation of processing instructions across notified bodies creates reprocessing validation delays for reusable surgical instruments with complex geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Site Infection Control Market |
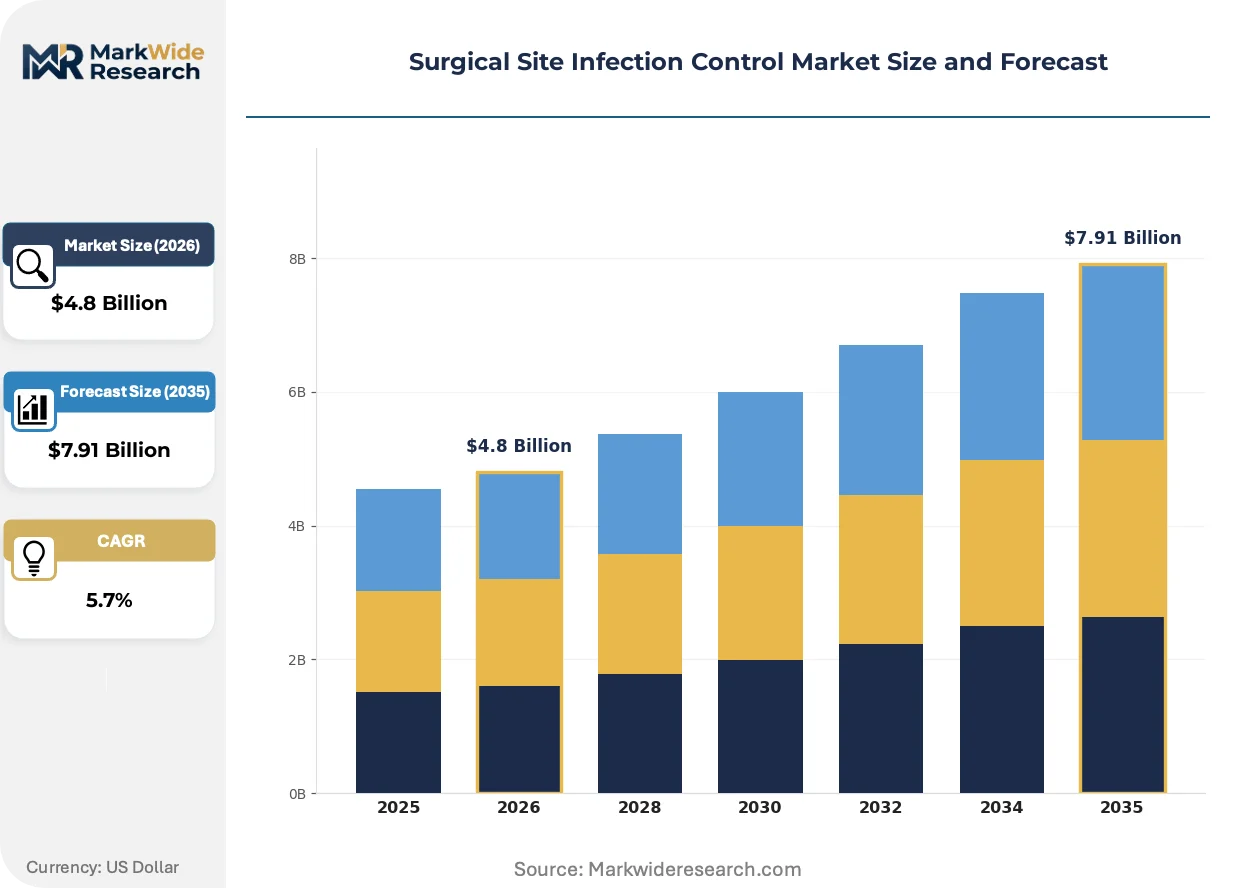
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobial Agents, Surgical Drapes, Adhesive Barriers, Sterile Instruments End User: Hospitals, Surgical Centers, Clinics, Research Institutions Technology: Biofilm Disruption, Surface Coating, Antiseptic Solutions, UV Sterilization Application: Orthopedic Surgery, Cardiac Surgery, General Surgery, Neurosurgery |
| Companies Covered | 3M Co., Becton Dickinson and Co., B. Braun SE, Getinge AB, STERIS plc, Johnson & Johnson, Kimberly-Clark Corp., Molnlycke Health Care AB, Sotera Health Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Site Infection Control Market Strategic Shifts & Innovations
Antimicrobial material science and automated sterilization monitoring are restructuring how surgical facilities validate and document infection prevention protocols. These shifts elevate technical performance thresholds while compressing the acceptable window for human error in critical control points.
Antimicrobial suture coatings containing triclosan or chlorhexidine are bifurcating the wound closure market between premium validated products and commodity alternatives lacking clinical outcome data. Cardiac surgery departments in US academic medical centers are standardizing coated sutures for sternal closure, while cost-constrained community hospitals defer adoption pending additional health economic evidence. This technology is bifurcating supplier tiers, separating manufacturers with published randomized trial data from those reliant on in vitro claims alone.
EMA's Medical Device Regulation implementation tightens clinical evidence requirements for infection prevention claims across European Economic Area markets. Manufacturers must now submit post-market surveillance data and PMCF studies to support antimicrobial efficacy assertions previously accepted on bench testing alone. High-risk device categories including implantable orthopedic hardware and cardiovascular grafts face the steepest documentation burdens, with notified bodies extending review timelines for products lacking prospective clinical data.
Ambulatory surgical centers are consolidating supplier relationships to reduce vendor management overhead and standardize staff training across multi-site networks. Large ASC management companies in Texas and Florida are mandating single-source agreements for preoperative skin preparation and surgical draping systems, displacing the historical site-by-site purchasing autonomy. This concentration is most visible in ophthalmology and gastroenterology specialties where high procedure volumes create negotiating leverage for multi-year committed contracts.
Surgical Site Infection Control Market Segmentation
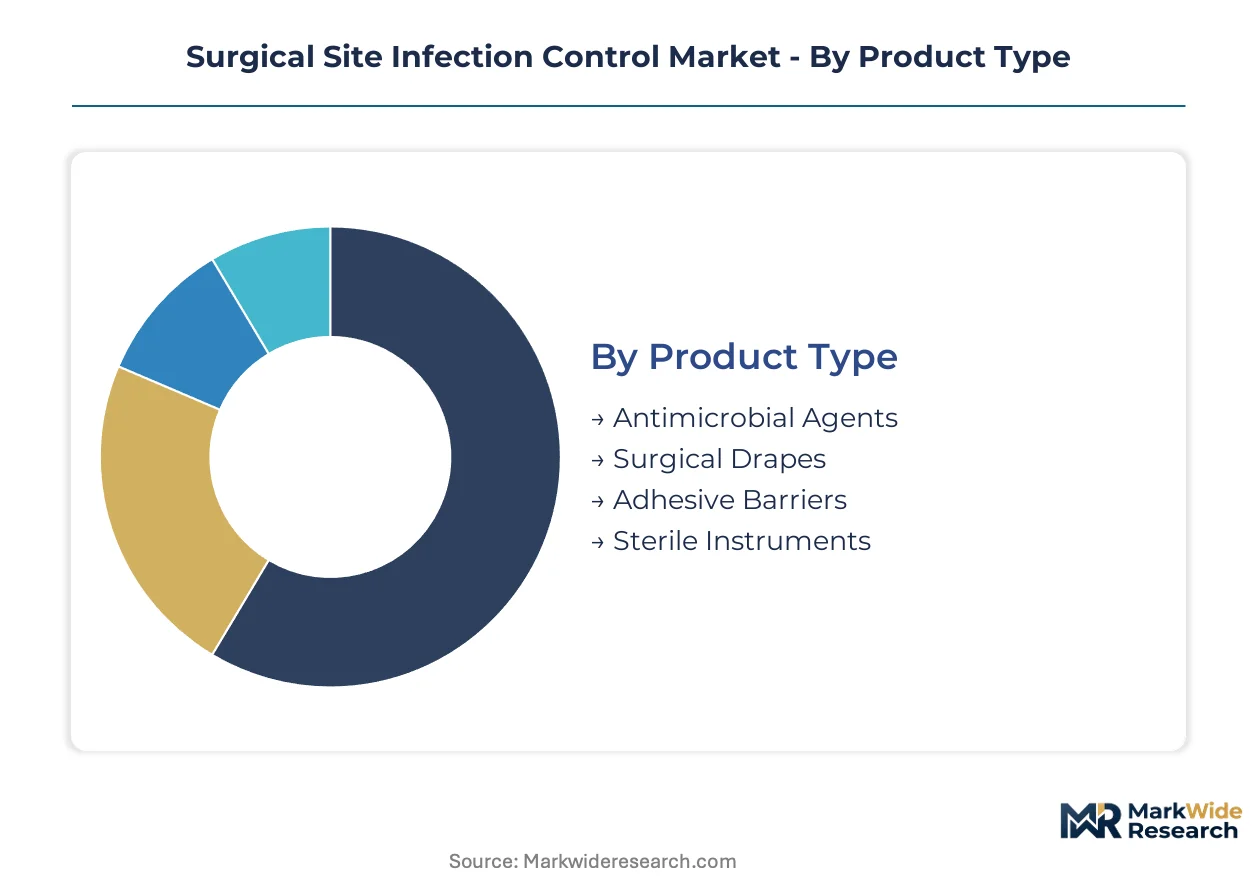
Segmentation in surgical site infection control reveals how regulatory validation requirements, procedure-specific risk profiles, and facility reimbursement structures reshape procurement priorities across product categories and end-use environments.
Product Type:
FDA premarket notification pathways and EPA disinfectant efficacy claims create divergent compliance burdens across product categories, with antimicrobial agents facing the steepest clinical evidence thresholds.
- Antimicrobial Agents:Chlorhexidine gluconate and povidone-iodine formulations achieve logarithmic bacterial load reduction specified by clinical guidelines. Demand concentrates in cardiac and orthopedic settings where procedure duration exceeds three hours, driven by CMS hospital-acquired condition penalties that mandate validated preoperative skin preparation protocols.
- Surgical Drapes:Impermeable barrier systems with adhesive apertures maintain sterile fields during prolonged procedures. Academic medical centers in Germany and the United Kingdom standardize premium draping systems for joint replacement surgeries, responding to EMA MDR documentation requirements for infection prevention claims.
- Adhesive Barriers:Film and foam substrates with antimicrobial impregnation seal incision sites against environmental contamination.
- Sterile Instruments:Reusable and single-use instrument sets validated for terminal sterilization per ISO 17664 processing instructions.
Antimicrobial agents handle the majority of throughput; adhesive barriers are expanding most quickly on share as ambulatory surgical centers adopt simplified application protocols.
End User:
Reimbursement structure and regulatory scrutiny intensity separate facility tiers, with surgical centers facing compressed procurement timelines under CMS quality metrics.
- Hospitals:Integrated delivery networks centralize infection control procurement across inpatient and outpatient surgical departments. Large Klinikverbund systems in Germany negotiate multi-year sterilization service contracts that bundle preoperative preparation, instrument reprocessing, and barrier technologies under single-source agreements.
- Surgical Centers:Freestanding ambulatory facilities in Texas and Florida consolidate supplier relationships to reduce vendor management overhead across multi-site networks. CMS reimbursement penalties for hospital-acquired conditions accelerate capital allocation toward validated barrier systems faster than historical replacement cycles.
- Clinics:Office-based surgical suites in dermatology and ophthalmology adopt disposable barrier technologies to minimize reprocessing infrastructure investment.
- Research Institutions:Academic medical centers pilot novel antimicrobial coatings and sterilization modalities under institutional review board protocols.
Hospitals dominate absolute procurement volume; surgical centers are gaining share fastest as procedure migration accelerates from inpatient to outpatient settings.
Technology:
Technical maturity and capital intensity stratify adoption curves, with chemical-based modalities facing displacement pressure from physical sterilization alternatives.
- Biofilm Disruption:Enzymatic and surfactant formulations penetrate microbial extracellular polymeric substances on implanted devices. Orthopedic departments in US academic medical centers evaluate biofilm-targeting irrigants for revision arthroplasty cases where established infections resist standard antiseptic protocols.
- Surface Coating:Chlorhexidine-impregnated and triclosan-eluting coatings on sutures and implants suppress bacterial colonization through sustained release kinetics. Cardiac surgery units standardize coated sutures for sternal closure while cost-constrained community hospitals defer adoption pending additional health economic evidence.
- Antiseptic Solutions:Alcohol-based and aqueous preparations for preoperative skin preparation and surgical hand antisepsis.
- UV Sterilization:UV-C terminal cleaning systems achieve log reduction claims without consumable chemistry, threatening recurring revenue models built on disinfectant replenishment cycles in ambulatory settings.
Surface coating commands the steepest pricing premium; UV sterilization is climbing the fastest as facilities seek alternatives to ethylene oxide capacity constraints.
Application:
Procedure complexity and implant burden determine infection risk profiles, with high-value interventions justifying premium prevention expenditures.
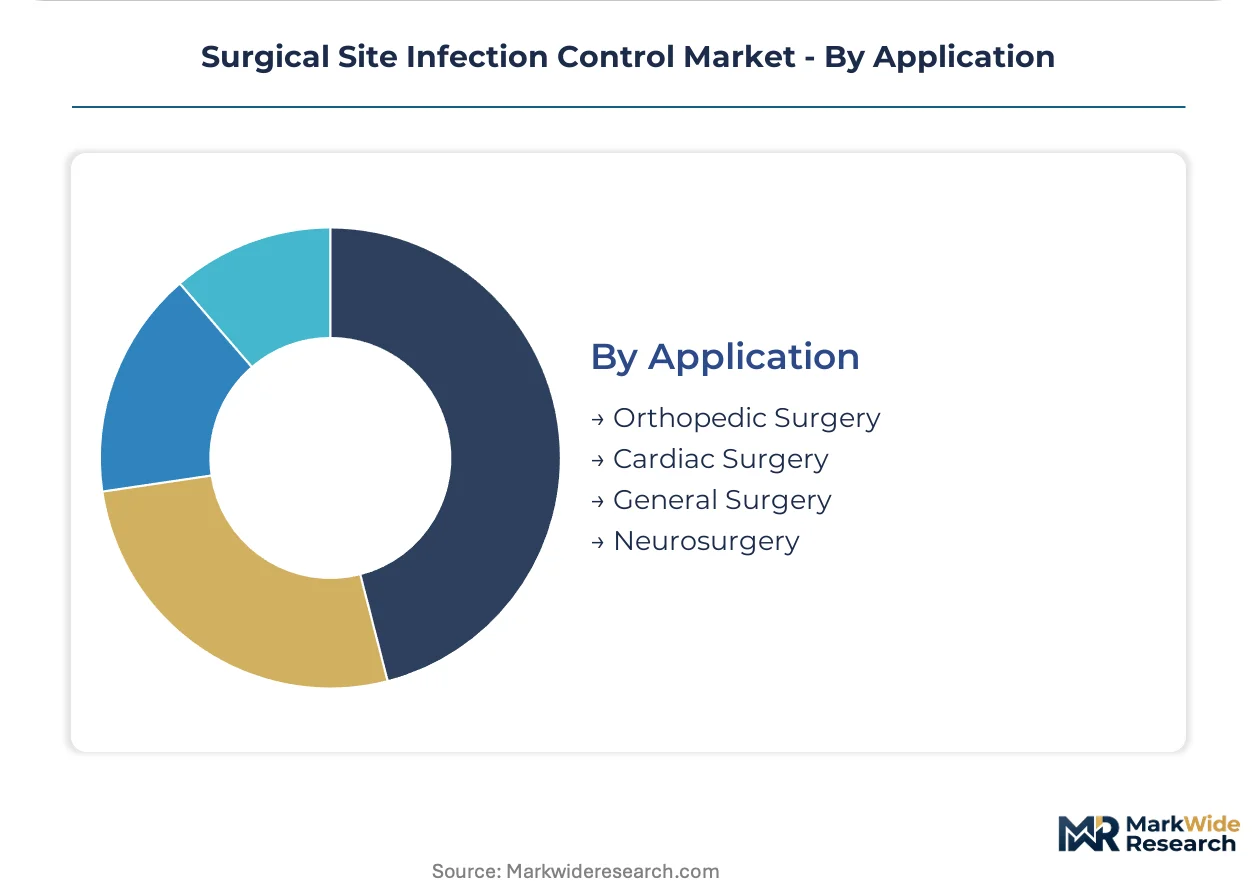
- Orthopedic Surgery:Joint arthroplasty and spinal fusion procedures carry elevated SSI risk due to implant surfaces and prolonged operative times. German hospital networks centralize procurement for antimicrobial-impregnated bone cements and barrier systems, responding to national health technology assessment body tightening of surgical protocol standards.
- Cardiac Surgery:Sternotomy and cardiopulmonary bypass create multiple infection vectors requiring comprehensive barrier protocols. US academic medical centers mandate coated sutures and advanced draping systems, while community hospitals balance cost constraints against CMS quality metric exposure.
- General Surgery:Abdominal and soft tissue procedures utilize standard preoperative preparation and barrier technologies across facility tiers.
- Neurosurgery:Craniotomy and spinal cord procedures demand specialized draping configurations for cranial fixation devices and microscopic instrumentation.
Orthopedic surgery generates the highest absolute expenditure on infection control; cardiac surgery shows the steepest expansion trajectory as valve replacement volumes grow in aging populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics hub underwrites European distribution efficiency for sterilization equipment and antimicrobial formulations moving into German hospital networks and UK surgical centers.
United States
Ambulatory surgical centers in Texas and Florida drive procurement of validated barrier systems as CMS Hospital-Acquired Condition Reduction Program penalties compress replacement cycles. FDA premarket notification requirements for antimicrobial devices elevate clinical evidence thresholds for market entry. The Dallas-Fort Worth metroplex concentrates ASC management company headquarters where multi-site standardization mandates reshape supplier contracting.
Germany
Klinikverbund hospital networks centralize infection control procurement across North Rhine-Westphalia and Bavaria, creating volume commitments favoring multi-product portfolios. EMA Medical Device Regulation mandates clinical evidence for antimicrobial efficacy claims, extending review timelines for orthopedic hardware lacking prospective data. The Rhine-Ruhr industrial corridor anchors sterilization service contract negotiations for reusable surgical instrument reprocessing.
United Kingdom
NHS England quality metrics tie reimbursement to surgical site infection rates, accelerating capital allocation toward preoperative skin preparation systems in cardiac and orthopedic departments. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR documentation standards for infection prevention claims. The Cambridge-Oxford-London golden triangle concentrates academic medical center pilot programs for novel antimicrobial coatings.
France
ANSM national health technology assessment tightening of surgical protocol standards elevates validation requirements for barrier technologies in public hospital networks. HAS reimbursement guidelines increasingly reference ISO 17664 processing instruction compliance for reusable instrument procurement. The Paris-Saclay medical technology cluster hosts sterilization process engineering expertise concentrated in aging specialist workforces.
Poland
EU structural fund investments in Eastern European healthcare infrastructure create first-mover opportunities for infection control suppliers establishing service contracts before procurement standardization. National health fund reimbursement rules increasingly reference EMA MDR technical documentation for imported medical devices. The Warsaw-Kraków corridor concentrates new surgical center buildouts targeting medical tourism from Western European markets.
Surgical Site Infection Control Market Key Industry Players
Concentration sits with diversified medical technology conglomerates possessing adhesive science portfolios, sterilization service capabilities, and multi-year contract structures. Mid-tier specialists in antimicrobial coating chemistry and barrier material science occupy differentiated positions. The competitive landscape stratifies across three archetypes: integrated conglomerates with multi-product infection control portfolios, sterilization service specialists with recurring revenue contracts, and coating technology innovators with R&D-intensive patent positions. Dominant competitive moves include multi-year sterilization service agreements locking in surgical center volumes and portfolio diversification into adjacent antimicrobial material science applications.
Among diversified medical technology conglomerates, 3M Co., Becton Dickinson and Co., and STERIS plc exemplify the integrated archetype. 3M Co. occupies a position representing adhesive science leverage across outpatient barrier technology segments. Becton Dickinson and Co. exemplifies sustained R&D positioning in antimicrobial systems for vascular access applications. STERIS plc anchors the sterilization service contract model with multi-year recurring revenue structures. These three entities collectively represent the tier where regulatory validation capabilities and clinical evidence databases create structural barriers for commodity entrants.
| Leading Market Players |
|---|
| 3M Co. |
| Becton Dickinson and Co. |
| B. Braun SE |
| Getinge AB |
| STERIS plc |
| Johnson & Johnson |
| Kimberly-Clark Corp. |
| Molnlycke Health Care AB |
| Sotera Health Co. |
| Others |
Cost & Logistics Intelligence
Multi-year sterilization service contracts lock in supply access and price visibility for ambulatory surgical centers facing CMS reimbursement penalties. These agreements bundle barrier technologies, instrument reprocessing, and consumable replenishment into predictable cost structures that insulate buyers from isopropyl alcohol feedstock volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers from community hospitals and ambulatory surgical centers. Premium tiers command positioning through EMA MDR clinical evidence documentation and FDA premarket notification validation, while economy tiers compete on per-unit cost for high-volume outpatient procedures. Pricing pressure stems from UV-C terminal cleaning alternatives threatening recurring disinfectant revenue models. Surgical centers exhibit highest price sensitivity due to compressed capital allocation timelines under quality metric penalties.
Supply Chain Analysis
Strategic stockpiling of chlorhexidine gluconate and povidone-iodine formulations dominates procurement strategy among German Klinikverbund networks facing EMA documentation requirements. Manufacturing concentration centers on the United States, Germany, and China for antimicrobial agents and barrier substrates. Raw material dependencies include petrochemical-derived alcohols, medical-grade adhesives, and nonwoven synthetic fabrics. Single-source ethylene oxide sterilization capacity creates vulnerability for device manufacturers. Distribution runs through specialized medical device logistics networks serving hospital systems and surgical center chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMS Hospital-Acquired Condition Reduction Program penalties are accelerating procurement cycle compression, creating structural disruption for suppliers lacking validated clinical evidence databases.
For Market Incumbents: Consolidate sterilization service contract portfolios through multi-year agreements locking in ambulatory surgical center volumes before procurement standardization matures. Deepen backward integration into chlorhexidine-impregnated adhesive manufacturing to capture margin from coating chemistry advances. Defend against UV-C terminal cleaning displacement by bundling consumable chemistry with automated compliance documentation systems. For New Entrants and Emerging Players: Postoperative wound monitoring service gaps in telehealth reimbursement frameworks offer white-space entry points for AI-enabled computer vision platforms. Polish and Romanian surgical center buildouts present first-mover advantages before EU structural fund procurement standardization takes hold. Target sterilization process engineering talent scarcity through specialized consulting and validation service offerings rather than capital-intensive equipment manufacturing. For Investors and Strategic Acquirers: Capital is best deployed toward coating technology innovators with R&D-intensive patent positions in antimicrobial material science. Long-term viability across the projection horizon rests on clinical evidence databases satisfying EMA MDR post-market surveillance mandates. Watch for sterilization capacity constraints triggering acquisition premiums for ethylene oxide alternatives and hydrogen peroxide vapor modality specialists.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Technical Documentation Investment | Clinical evidence requirements extend review timelines for orthopedic hardware lacking prospective data. |
| Multi-Year Sterilization Service Contract | Recurring revenue structures lock in surgical center volumes across Texas and Florida networks. |
| AI-Enabled Wound Monitoring Platform | Computer vision algorithms converge infection control with telehealth reimbursement frameworks. |
| Antimicrobial Coating Chemistry R&D | Chlorhexidine-impregnated adhesives extend bacterial suppression through prolonged cardiac procedures. |
| Eastern European Service Contract Establishment | EU structural fund investments in Poland and Romania create pre-standardization positioning advantages. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA premarket notification databases, EMA MDR submission records, CMS Medicare cost reports, and hospital procurement contract disclosures. Primary interviews engaged infection control officers, ambulatory surgical center purchasing managers, biomedical engineers, GPO contracts specialists, and sterilization process validation consultants. Bottom-up procedure volume modeling triangulates against top-down expenditure analysis across German Klinikverbund networks and US integrated delivery systems.
Segmentation dimensions modeled include product category, end-user facility tier, application specialty, and technology modality across the analysis window. CAGRs derive from regression analysis of historical procurement expenditure patterns and regulatory compliance cost trajectories. Forecast inputs incorporate CMS quality metric penalty schedules, EMA notified body review timeline distributions, and ethylene oxide sterilization capacity utilization assumptions.
Underlying assumptions cover reimbursement rule stability and sterilization modality transition rates, with deviation risk concentrated in EU MDR implementation timing and petrochemical feedstock price volatility. Revision becomes warranted when UV-C terminal cleaning efficacy validation crosses clinical adoption thresholds or when Eastern European procurement standardization accelerates beyond baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Australia Hand Sanitizer Market
Infection Control
Global Dental Infection Control Products Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Asia-Pacific Hand Sanitizer Market
Infection Control
Clinical Hand Hygiene Products Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Sterilization Tunnel Market
Infection Control
Disinfection Equipment Market
Infection Control
Alcohol Wipes Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
Perianal Infection Treatment Market
Infection Control
Peptide-Based Infection Therapeutics Market
Infection Control
UV Disinfection Equipment Market
Infection Control
Medical Activated Carbon Dressing Market
Infection Control
Antimicrobial Suture Market