
 South Africa Minimally Invasive Surgical Devices Market | 2026-2036
South Africa Minimally Invasive Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Minimally Invasive Surgical Devices Market Analytics
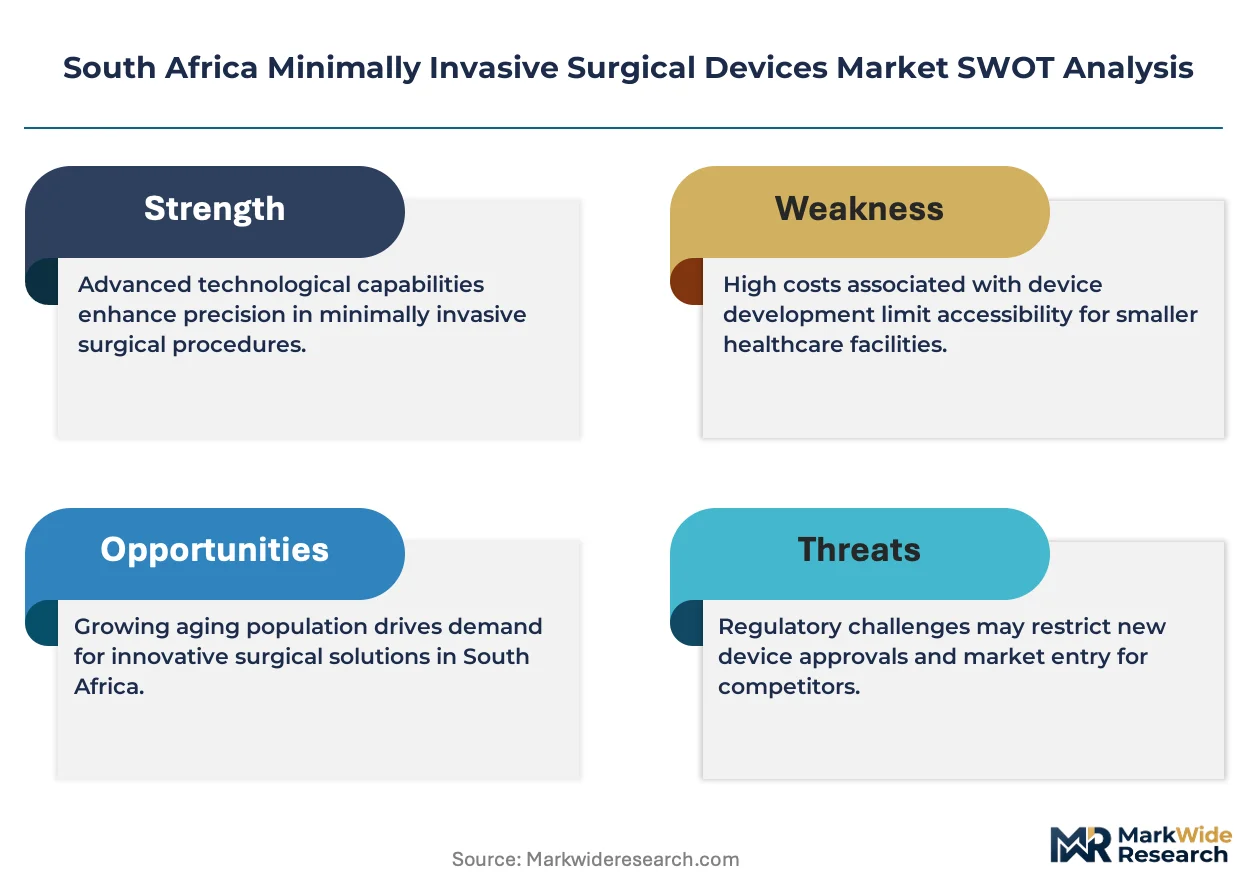
A shortage of trained laparoscopic surgeons is redrawing competitive dynamics across South Africa's private and public hospital tiers. Medtronic leverages its broad instrumentation portfolio to sustain presence across multiple surgical disciplines. Johnson & Johnson anchors its position through advanced energy devices and stapling platforms. Stryker competes in visualization and navigation systems for orthopedic and spinal minimally invasive procedures.
Minimally invasive surgical devices encompass instruments, visualization systems, and robotic platforms designed for procedures through small incisions using trocar access ports typically ranging from 5 mm to 12 mm diameter. These devices enable reduced tissue trauma, shorter recovery periods, and lower postoperative complication rates compared to open surgery. Laparoscopes and endoscopes dominate device-type revenue due to replacement cycles and upgrade demand in South Africa's aging installed base. Robotic-assisted surgery represents the fastest-growing technology segment, though from a narrow base constrained by capital outlay and surgeon training pipelines. Hospitals absorb the majority of end-user spending, while ambulatory surgical centers gain traction for routine cholecystectomy and hernia repair volumes.
SAHPRA governs medical device registration and post-market surveillance, while the South African Bureau of Standards (SABS) administers conformity assessment for imported equipment. These frameworks shape product entry timelines and quality certification requirements for multinational suppliers. The International Organization for Standardization (ISO) 13485 quality management standard further conditions supplier eligibility for public sector procurement. Stakeholders must monitor SAHPRA's alignment with the African Medicines Regulatory Harmonization initiative and its implications for streamlined device approvals across the Southern African Development Community.
Market Dynamics
Private hospital groups in Gauteng and the Western Cape are consolidating procurement power around advanced visualization systems, compressing vendor margins while accelerating replacement cycles for aging laparoscopic equipment.
Growth Catalysts
- SAHPRA Streamlining:South Africa's Health Products Regulatory Authority is reducing registration timelines for advanced visualization systems, enabling faster product entry for multinational suppliers targeting Johannesburg's academic medical centers.
- Robotic Platform Adoption:Cape Town's private surgical hubs are investing in robotic-assisted surgery infrastructure, creating pull-through demand for compatible instrumentation and disposable consumables.
- Academic Center Expansion:University-affiliated hospitals in Pretoria and Durban are scaling laparoscopic training programs, expanding the addressable surgeon base for minimally invasive procedures.
Market Restraints
- Capital Intensity:Robotic surgery platforms require substantial upfront investment, limiting deployment to well-capitalized private hospital groups and excluding smaller regional facilities.
- Import Dependency:South Africa relies on European and US suppliers for advanced energy devices and visualization systems, exposing procurement to currency volatility and extended lead times.
- Surgeon Training Pipeline:The shortage of trained laparoscopic specialists constrains procedure volume growth regardless of equipment availability in both public and private tiers.
Strategic Opportunities
- Eastern Cape Penetration:Underdeveloped minimally invasive surgery infrastructure in Port Elizabeth and East London offers first-mover advantage for equipment suppliers establishing service networks.
- Day Surgery Center Channel:Ambulatory surgical centers for routine cholecystectomy and hernia repair represent an emerging customer segment with distinct procurement preferences and faster decision cycles.
- SADC Harmonization:SAHPRA's alignment with the African Medicines Regulatory Harmonization initiative could unlock streamlined device approvals across neighboring Southern African Development Community markets.
Industry Challenges
- Biomedical Engineering Talent:Maintenance and calibration of complex visualization systems requires specialized technical skills that remain scarce in South Africa's public health sector.
- ISO 13485 Certification Burden:South African Bureau of Standards conformity assessment and quality management certification create extended timelines for local distributors seeking public sector contracts.
- Legacy Equipment Integration:New robotic platforms must interface with existing hospital information systems and surgical workflows, complicating deployment in facilities with heterogeneous technology estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Minimally Invasive Surgical Devices Market |
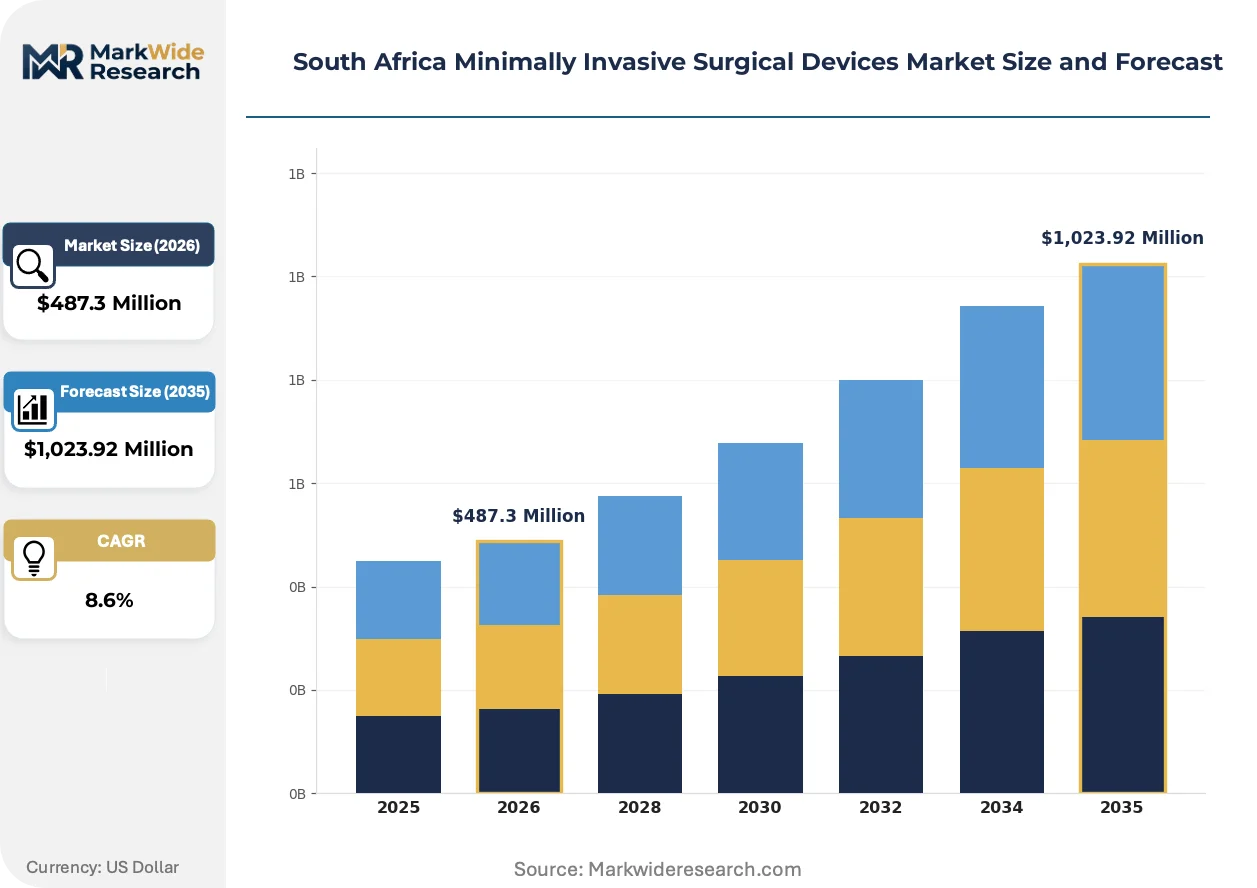
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laparoscopes, Endoscopes, Surgical Staplers, Trocar Systems Application: Cardiothoracic Surgery, Urological Surgery, Gynecological Procedures, General Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Robotic-Assisted Surgery, Visualization Systems, Energy Devices, Instrumentation |
| Companies Covered | Medtronic, Johnson & Johnson, Siemens Healthineers, GE Healthcare, Abbott Laboratories, Intuitive Surgical, Koninklijke Philips, Stryker, Zimmer Biomet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Minimally Invasive Surgical Devices Market Evolving Landscape
Visualization technology is fragmenting the competitive landscape as multiple imaging modalities compete for capital allocation, while regulatory harmonization and procurement centralization reshape how devices reach end-users.
Single-use laparoscopic instruments with integrated energy delivery are fragmenting the traditional reusable device market. Private hospital groups in the Western Cape are adopting these disposable platforms for infection control and operational simplicity. This shift is compressing the service revenue that previously sustained distributors of reusable equipment.
SAHPRA's participation in the African Medicines Regulatory Harmonization initiative is creating mutual recognition pathways for device approvals. Manufacturers registering products in South Africa gain streamlined access to Botswana, Namibia, and Zimbabwe markets. This regulatory convergence favors suppliers with established Johannesburg-based regulatory affairs capabilities.
Centralized procurement consortia operated by large private hospital groups are displacing individual facility purchasing. Netcare and Mediclinic are consolidating vendor negotiations for advanced energy devices and stapling platforms at group level. This concentration is most visible in Gauteng, where three hospital groups control the majority of high-complexity surgical volume.
South Africa Minimally Invasive Surgical Devices Market Segmentation
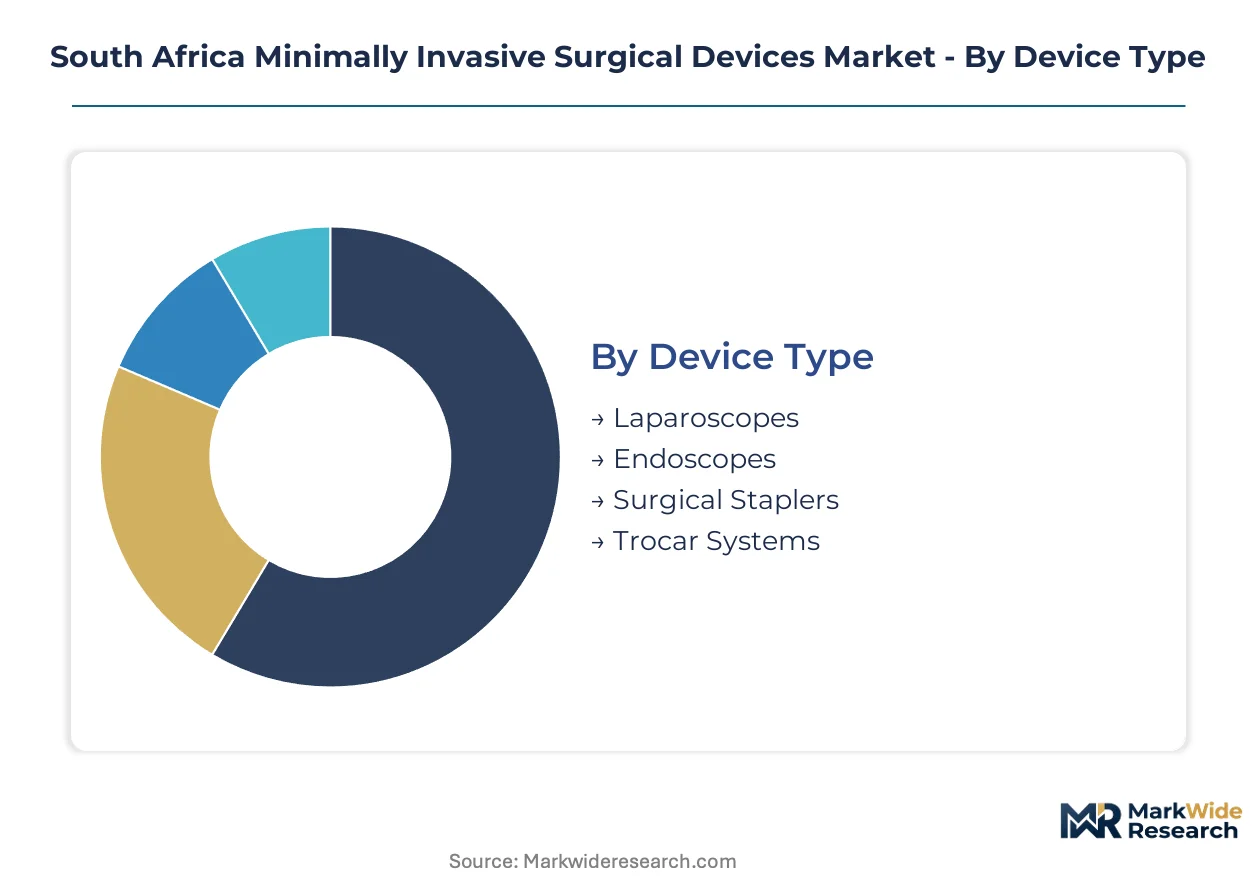
Device categories in South Africa's minimally invasive surgical market follow distinct procurement pathways. Academic medical centers in Johannesburg and private surgical hubs in Cape Town concentrate demand differently across visualization systems, robotic platforms, and disposable instrumentation.
Device Type:
Channel distribution varies sharply by device category, with reusable systems flowing through distributor service networks while single-use platforms bypass traditional supply chains entirely.
- Laparoscopes:Optical systems with rigid or flexible configurations enable abdominal cavity visualization through 5 mm to 10 mm ports. Replacement demand concentrates in Gauteng's private hospital groups where aging fiber-optic installations require upgrade to 4K and 3D imaging capabilities.
- Endoscopes:Flexible insertion tubes with distal camera assemblies access gastrointestinal and respiratory tracts. Durban's public hospital networks drive volume for gastroenterology applications amid constrained capital budgets and extended replacement cycles.
- Surgical Staplers:Linear and circular stapling platforms deploy titanium or polymer staples for tissue approximation and transection.
- Trocar Systems:Access ports with bladed or bladeless obturator designs establish pneumoperitoneum and instrument channels.
Laparoscopes dominate installed base. Endoscopes represent where expansion concentrates.
Application:
Procedure volume distribution reflects South Africa's disease burden patterns and specialist availability across surgical disciplines.
- Cardiothoracic Surgery:Minimally invasive valve repair and coronary bypass procedures demand specialized thoracoscopic instrumentation and cardiopulmonary bypass compatibility. Groote Schuur Hospital in Cape Town anchors demand for advanced thoracoscopic platforms.
- General Surgery:Cholecystectomy, appendectomy, and hernia repair constitute the highest-volume minimally invasive procedures. Ambulatory surgical centers in Pretoria and Johannesburg are displacing hospital-based volumes for routine cases.
- Urological Surgery:Nephrectomy, prostatectomy, and stone retrieval employ laparoscopic and endourological approaches.
- Gynecological Procedures:Hysterectomy, myomectomy, and diagnostic laparoscopy serve reproductive health and oncology indications.
General Surgery commands procedure volume leadership. Cardiothoracic Surgery shows the steepest expansion trajectory.
End User:
Customer procurement sophistication varies from centralized group purchasing in private hospital networks to fragmented individual facility decisions in the public sector.
- Hospitals:Academic medical centers and tertiary facilities absorb capital-intensive robotic platforms and advanced energy systems. Netcare and Mediclinic group procurement offices in Johannesburg negotiate system-wide contracts for visualization infrastructure.
- Ambulatory Surgical Centers:Day surgery facilities prioritize disposable instrumentation and compact laparoscopic towers for cholecystectomy and hernia repair. Cape Town's private surgical hubs are expanding standalone ASC capacity.
- Specialty Clinics:Gastroenterology and urology-focused practices acquire flexible endoscopy systems for diagnostic and interventional procedures.
- Research Institutions:University-affiliated surgical training centers procure simulation platforms and training instrumentation for laparoscopic skills development.
Hospitals retain capital expenditure dominance. Ambulatory Surgical Centers gain share fastest in routine procedure segments.
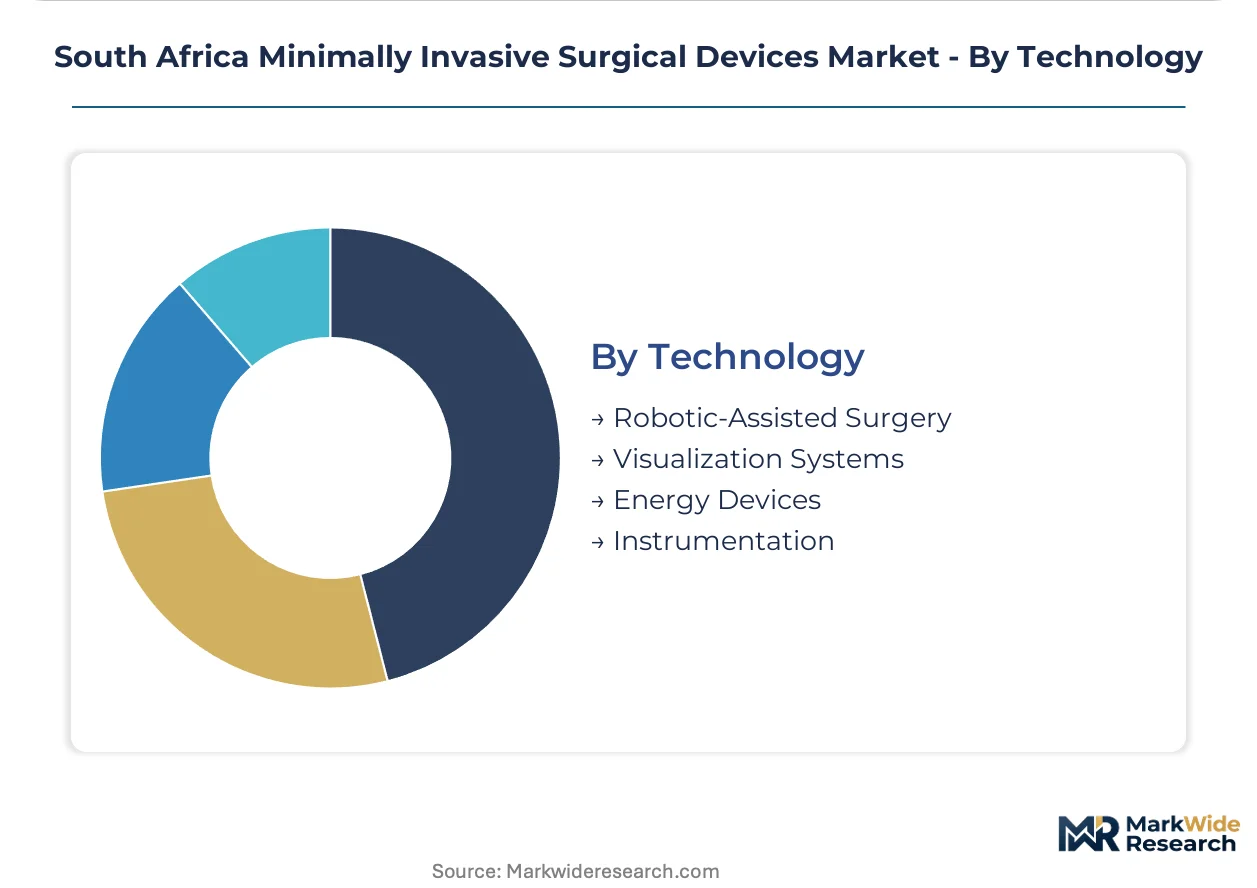
Technology:
Technology tiering separates premium robotic platforms accessible only to well-capitalized private groups from standard laparoscopic systems deployed across broader facility networks.
- Visualization Systems:4K resolution, 3D depth perception, and fluorescence imaging capabilities differentiate premium from standard laparoscopic towers. Western Cape private hospital groups are consolidating procurement around integrated visualization platforms.
- Robotic-Assisted Surgery:Telemanipulator platforms with wristed instruments and tremor filtration enable complex suturing in confined spaces. Cape Town's Christiaan Barnard Memorial Hospital anchors da Vinci system utilization.
- Energy Devices:Ultrasonic and advanced bipolar platforms provide vessel sealing and tissue dissection with minimal thermal spread.
- Instrumentation:Graspers, dissectors, and needle drivers in reusable and single-use configurations complete procedural tool sets.
Visualization Systems anchor replacement demand. Robotic-Assisted Surgery is where capital expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng and the Western Cape deploy minimally invasive surgical devices through divergent procurement models, with academic medical centers driving visualization upgrades while private surgical hubs concentrate robotic platform adoption.
Gauteng
Johannesburg's academic medical centers and Netcare group hospitals anchor demand for advanced laparoscopic towers and energy devices. SAHPRA's streamlined registration pathway accelerates product entry for multinational suppliers targeting Pretoria's university-affiliated training programs. The Pretoria-Johannesburg corridor concentrates replacement demand as aging fiber-optic installations upgrade to 4K imaging capabilities.
Western Cape
Cape Town's private surgical hubs lead robotic-assisted surgery infrastructure investment, creating pull-through demand for compatible instrumentation. Mediclinic's centralized procurement office negotiates group-wide contracts for integrated visualization platforms. Christiaan Barnard Memorial Hospital anchors da Vinci system utilization in the region's premium surgical tier.
KwaZulu-Natal
Durban's public hospital networks drive endoscope volume for gastroenterology applications amid constrained capital budgets. The country's national pharmaceutical regulator shapes extended replacement cycles through post-market surveillance requirements. University-affiliated facilities in Durban are scaling laparoscopic training programs to expand the addressable surgeon base.
Eastern Cape
Port Elizabeth and East London present underdeveloped minimally invasive surgery infrastructure with limited service network coverage. ISO 13485 quality management certification requirements create extended timelines for local distributors seeking public sector contracts. First-mover equipment suppliers are establishing technical support capabilities to capture emerging demand.
South Africa Minimally Invasive Surgical Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in South Africa's minimally invasive surgical devices market. Medtronic, Johnson & Johnson, and Stryker occupy the upper tier through broad instrumentation portfolios and advanced energy platforms. Mid-scale specialists concentrate in visualization systems and disposable consumables. Competitive dynamics center on centralized procurement consolidation by private hospital groups and regulatory alignment with SADC harmonization initiatives.
Among diversified medical technology conglomerates, Medtronic and Johnson & Johnson exemplify the integrated leader archetype through multi-disciplinary presence across surgical disciplines. Stryker occupies a position within the visualization and navigation systems tier for orthopedic and spinal applications. These three companies represent the primary competitive anchors as private hospital groups in Gauteng and the Western Cape consolidate vendor negotiations at group level.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Siemens Healthineers |
| GE Healthcare |
| Abbott Laboratories |
| Intuitive Surgical |
| Koninklijke Philips |
| Stryker |
| Zimmer Biomet |
| Others |
Value Network & Pricing Analysis
Long-term group procurement contracts lock in visualization system access for Netcare and Mediclinic while compressing vendor margins across Gauteng and Western Cape surgical hubs. These multi-year agreements tether price visibility to centralized purchasing volume, forcing distributors to absorb currency risk on imported energy devices and stapling platforms.
Pricing Analysis
Contract-based long-term offtake dominates, with private hospital groups negotiating system-wide agreements for laparoscopic towers and robotic platforms. Price differentiation hinges on ISO 13485 certification tier and after-sales service bundling, with SAHPRA-registered suppliers commanding premiums over parallel-import alternatives. Cost compression in standard laparoscopic instrumentation is intensifying because centralized procurement offices are consolidating vendor panels. Academic medical centers show least price sensitivity due to training program subsidies, while Eastern Cape public hospitals face acute budget constraints.
Supply Chain Analysis
Extended lead times for 4K camera heads and robotic instrument arms expose South African facilities to inventory strain, with European and US suppliers filling backorders on 12-16 week cycles. Manufacturing concentrates in Germany, the United States, and Ireland for advanced energy devices, while optical components draw from Japanese and South Korean sensor fabricators. Single-source vulnerability runs through da Vinci system consumables, which Intuitive Surgical produces exclusively from California facilities. Distribution runs through Johannesburg-based authorized distributors holding SAHPRA import licenses and SABS conformity certificates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trained laparoscopic surgeon scarcity constrains procedure volume growth regardless of capital equipment availability, creating a bottleneck that shapes competitive returns across both private and public tiers.
For Market Incumbents: Fortify service network density in the Eastern Cape before competitors establish technical support footholds in Port Elizabeth and East London. Secure backward integration into single-use instrument manufacturing to offset margin compression from disposable platform adoption. SAHPRA's alignment with African Medicines Regulatory Harmonization threatens to open SADC markets to new entrants, making Johannesburg-based regulatory affairs capabilities a critical defensive asset. For New Entrants and Emerging Players: Lead with disposable laparoscopic instrumentation targeting ambulatory surgical centers in Pretoria and Cape Town, where infection control priorities and faster procurement cycles favor operational simplicity over capital-intensive reusable systems. The day surgery channel offers the most penetrable entry point, with distinct purchasing committees and shorter vendor qualification timelines than hospital group procurement offices. Partner with university-affiliated training programs to embed products within surgical resident education pathways. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale visualization specialists with established ISO 13485 quality systems and existing SAHPRA registration dossiers, positioned for SADC harmonization upside. The five-to-ten year viability window favors suppliers with regulatory infrastructure over pure technology plays. Watch SAHPRA's mutual recognition agreement progress with Botswana and Namibia as the signal for regional expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Netcare and Mediclinic group contracts lock in multi-year visualization system commitments. |
| CE Marking Pathway | European certification accelerates SAHPRA registration through established technical documentation. |
| Reimbursement Strategy | Alignment with South African medical aid tariff codes enables private patient access. |
| Software Companion Development | Integrated imaging analytics differentiate premium laparoscopic towers in academic centers. |
| Biomedical Engineer Training Program | Local technical talent pipelines reduce service response times for visualization systems. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts specialists; and secondary validation through SAHPRA registration databases, hospital procurement records, and SABS conformity assessment filings. The research combined bottom-up equipment shipment tracking with top-down surgical procedure volume estimates across Gauteng, Western Cape, KwaZulu-Natal, and Eastern Cape facilities.
Across the analysis window, the forecasting framework modeled demand by device type, application, technology tier, and end-user channel, with CAGRs derived from procedure volume elasticity to surgeon supply constraints. Inputs included laparoscopic training program graduation rates, private hospital group capital expenditure disclosures, and currency-adjusted import value trends for visualization systems.
The analysis sits within stated boundaries; outcomes outside stable SAHPRA registration timelines and sustained private hospital group investment would require recalibration. Forecasts reflect assumptions about surgeon training pipeline expansion and SADC regulatory harmonization progress. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Oral Controlled Release Drug Delivery Technology Market
Medical Devices
Tattoo Removal Devices Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Sperm Separation Systems Market
Medical Devices
3D Printed Brain Model Market
Medical Devices
Gastric Space-Occupying Devices Market
Medical Devices
Global Wearable Injectors Market
Medical Devices
Europe Renal Denervation Devices Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Global Medical Dynamometer Market
Medical Devices
Testicular Implants (Prosthesis) Market
Medical Devices
Light Therapy Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Biomedical Warming and Thawing Devices Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Global Gynecology Devices Market