
 Global Nephrology and Urology Devices Market | 2026-2036
Global Nephrology and Urology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nephrology and Urology Devices Market Analysis
Germany is tilting toward expanded dialysis machine production as Fresenius Medical Care AG & Co. KGaA leverages its captive component supply chain to dominate European renal device manufacturing. Boston Scientific Corporation anchors its urology portfolio through specialized stent and catheter platforms. Medtronic competes across minimally invasive surgical tools with sustained R&D intensity in robotic-assisted urological systems.
Nephrology and urology devices comprise instruments engineered for renal filtration support, urinary tract intervention, and associated diagnostic procedures, typically manufactured from biocompatible polymers, stainless steel alloys, or silicone composites to withstand repeated sterilization cycles and prolonged physiological contact. These devices serve primary commercial purposes in chronic disease management, acute surgical intervention, and outpatient monitoring of renal function. Dialysis machines command the largest installed base revenue pool among device types, while robotics within the technology dimension captures the fastest margin expansion as hospitals prioritize precision in prostate and kidney procedures. Home care settings within end users represent the most structurally transformative channel as reimbursement shifts incentivize decentralized treatment models.
The FDA enforces 510(k) and PMA pathways that govern urological device clearance timelines, while the EU MDR imposes strengthened clinical evidence requirements for renal stents and catheters entering European markets. China's NMPA accelerates review channels for innovative dialysis equipment under its priority review program. Japan's PMDA maintains stringent biocompatibility testing protocols that filter out lower-quality imports. Stakeholders must weigh regulatory capital requirements against the payoff from pioneering robotics-enabled stone management platforms.
Market Dynamics
Robotic-assisted surgical platforms are compressing procedure times and retraining hospital capital allocation toward integrated operating room ecosystems, forcing device manufacturers to bundle hardware with proprietary software subscriptions rather than sell standalone instruments.
Growth Catalysts
- EU MDR strengthened clinical evidence mandates:Renal stent manufacturers investing in prospective trials gain preferential market access across Germany, France, and Italy as notified bodies prioritize submissions with robust safety datasets.
- Home dialysis reimbursement restructuring:CMS payment adjustments in the United States accelerate patient migration from clinic-based hemodialysis to peritoneal and home hemodialysis modalities, expanding addressable device volume.
- Silicone-nitride biomaterial adoption:Catheter producers incorporating this ceramic composite report reduced bacterial adhesion rates, addressing bloodstream infection protocols in acute care settings.
Market Restraints
- Polymer feedstock volatility:Medical-grade polyurethane and silicone prices fluctuate with petrochemical input costs, squeezing margin stability for disposable catheter manufacturers.
- Single-source component dependence:Precision pump motors for dialysis machines concentrate among Japanese and German suppliers, creating vulnerability to export licensing delays.
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 14-24 month completion timelines, slowing novel material introductions.
Strategic Opportunities
- India's chronic kidney disease detection gap:Diagnostic underpenetration in rural districts creates whitespace for portable creatinine monitoring devices distributed through primary health centers.
- Wearable renal function sensors:Continuous glomerular filtration rate tracking via interstitial fluid analysis converges with smartphone telemetry, enabling preemptive intervention before acute decompensation.
- China NMPA priority review channels:Innovative dialysis equipment submissions receive accelerated 90-day technical reviews, compressing time-to-revenue for breakthrough device designations.
Industry Challenges
- Robotic surgery technician scarcity:Hospital systems struggle to recruit nurses certified on da Vinci and competing platforms, limiting installed base utilization rates.
- Legacy EMR integration friction:New urological devices face interoperability validation against Epic, Cerner, and Meditech systems, extending deployment timelines by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nephrology and Urology Devices Market |
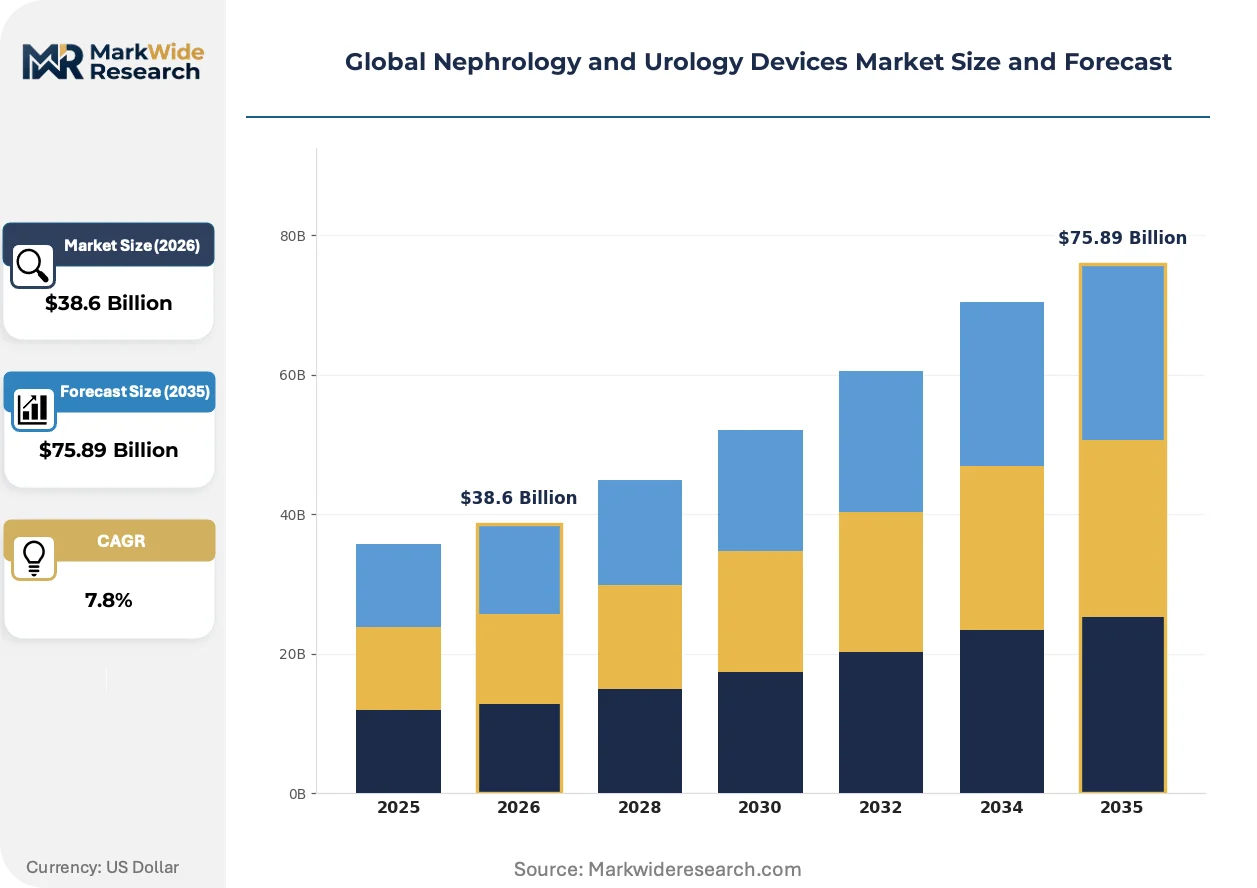
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $75.89 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Dialysis Machines, Renal Stents, Catheters, Urological Forceps End User: Clinics, Hospitals, Home Care Settings, Ambulatory Surgical Centers Technology: Robotics, Minimally Invasive Surgery, Ultrasonography, Imaging Application: Kidney Transplantation, Diagnostic Imaging, Stone Management, Chronic Kidney Disease |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, Boston Scientific Corporation, Medtronic, Coloplast, B. Braun Melsungen AG, Baxter International Inc., ConvaTec Group plc, Hollister Incorporated, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nephrology and Urology Devices Market Emerging Trajectories
Digital twin technology and artificial intelligence are reconstructing how renal function is monitored and how surgical outcomes are predicted, shifting value capture from hardware sales toward predictive analytics subscriptions.
Cloud-based dialysis prescription management is virtualizing treatment protocols across distributed care networks. Fresenius and DaVita clinic operators in North America and Western Europe deploy these platforms to synchronize ultrafiltration targets across home and facility settings. This architecture compresses nephrologist oversight burden while expanding patient census per specialist.
REACH chemical substance restrictions are compelling European manufacturers to reformulate catheter plasticizers and eliminate phthalate-based softening agents from supply chains. Device producers serving EU markets accelerate biobased alternative testing to maintain CE marking validity. Ureteral stent and drainage catheter categories face the steepest compliance recertification costs.
Hospital procurement committees now unbundle capital equipment from disposable supply agreements, reversing historical bundling practices that locked institutions into single-vendor ecosystems. This pattern disrupts traditional dialysis machine leasing structures in the United States and Germany. Independent service organizations gain traction servicing mixed-vendor installed bases.
Global Nephrology and Urology Devices Market Segmentation
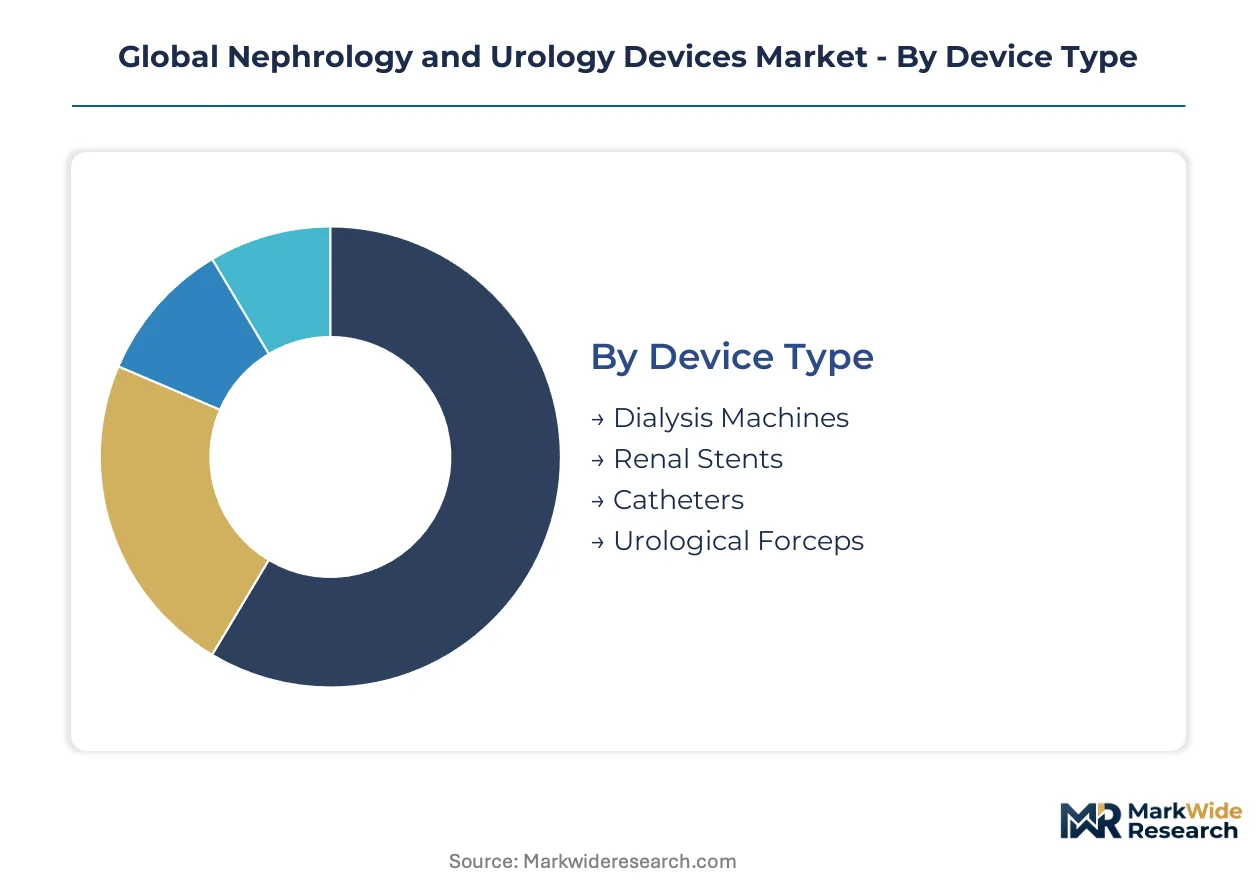
Nephrology and urology devices fragment across four critical dimensions that determine procurement patterns, reimbursement pathways, and competitive intensity. Device type stratification separates capital-intensive installed base equipment from high-velocity disposable consumables. End-user segmentation captures the structural migration from facility-based treatment toward decentralized home administration reshaping volume allocation.
Device Type:
Cost tier differentiation separates capital equipment with decade-long depreciation cycles from single-use disposables replenished in monthly batches.
- Dialysis Machines:Hemodialysis and peritoneal dialysis units integrate blood pumps, dialyzers, and ultrafiltration monitors in sealed console architectures. Fresenius Medical Care AG & Co. KGaA and Baxter concentrate manufacturing in Germany and Sweden to serve European clinic procurement committees. Capital lease structures dominate US hospital acquisitions, compressing upfront payment into multi-year service contracts bundling preventive maintenance.
- Catheters:Double-J ureteral stents, Foley retention catheters, and peritoneal dialysis access devices deploy silicone-nitride coatings to suppress bacterial biofilm formation. Japanese acute care settings drive premium pricing for infection-resistant formulations under PMDA-enforced biocompatibility protocols. Silicone-nitride adoption accelerates as bloodstream infection protocols tighten reimbursement for preventable complications.
- Renal Stents:Metallic mesh tubes maintain ureteral patency following stone extraction or stricture dilation, typically manufactured from nitinol shape-memory alloys.
- Urological Forceps:Grasping instruments for stone retrieval and tissue manipulation feature ergonomic handle designs compatible with rigid and flexible endoscope channels.
Dialysis machines command the established base. The steepest expansion runs through catheters with advanced biomaterial coatings.
End User:
Application setting determines regulatory classification, reimbursement coding, and supply chain fulfillment architecture.
- Home Care Settings:Peritoneal dialysis cycler units and home hemodialysis consoles enable self-administered renal replacement therapy outside clinical supervision. US Medicare payment adjustments accelerate patient migration from clinic-based treatment, expanding addressable device volume for portable systems with simplified user interfaces. Reimbursement restructuring in Germany and France follows similar trajectories, though nursing support infrastructure lags North American deployment.
- Hospitals:Integrated operating room ecosystems deploy robotic-assisted platforms for prostatectomy and nephrectomy alongside conventional laparoscopic towers. Academic medical centers in Boston, Heidelberg, and Tokyo concentrate installed base for da Vinci and competing surgical systems. Capital allocation committees prioritize bundled hardware-software subscriptions over standalone instrument purchases.
- Clinics:Outpatient dialysis centers concentrate hemodialysis chair capacity in high-density urban corridors with nephrologist oversight.
- Ambulatory Surgical Centers:Same-day discharge protocols for stone management and diagnostic cystoscopy drive demand for compact lithotripters and flexible ureteroscopes.
Hospitals anchor the revenue base. Home care settings gain share fastest as reimbursement shifts decentralize treatment delivery.
Technology:
Margin concentration tracks precision enhancement capabilities and proprietary software integration depth.
- Robotics:Teleoperated surgical platforms compress prostatectomy operative times while reducing positive margin rates in radical procedures. Intuitive Surgical and Medtronic compete across US and European hospital capital budgets with differentiated instrument sterilization protocols and surgeon training certification programs. Subscription-based software monetization displaces pure hardware margin capture.
- Minimally Invasive Surgery:Laparoscopic and endourological techniques reduce recovery timelines versus open surgical approaches, sustaining premium pricing for specialized access ports and energy devices.
- Ultrasonography:Portable ultrasound systems enable bedside renal imaging and ultrasound-guided vascular access for dialysis catheter placement.
- Imaging:CT urography and MR urography modalities support stone characterization and renal mass differentiation in diagnostic workups.
Robotics captures the highest margin tier. Minimally invasive platforms expand most quickly across mid-tier hospital systems.
Application:
Clinical indication determines device specification, regulatory pathway intensity, and patient population addressability.
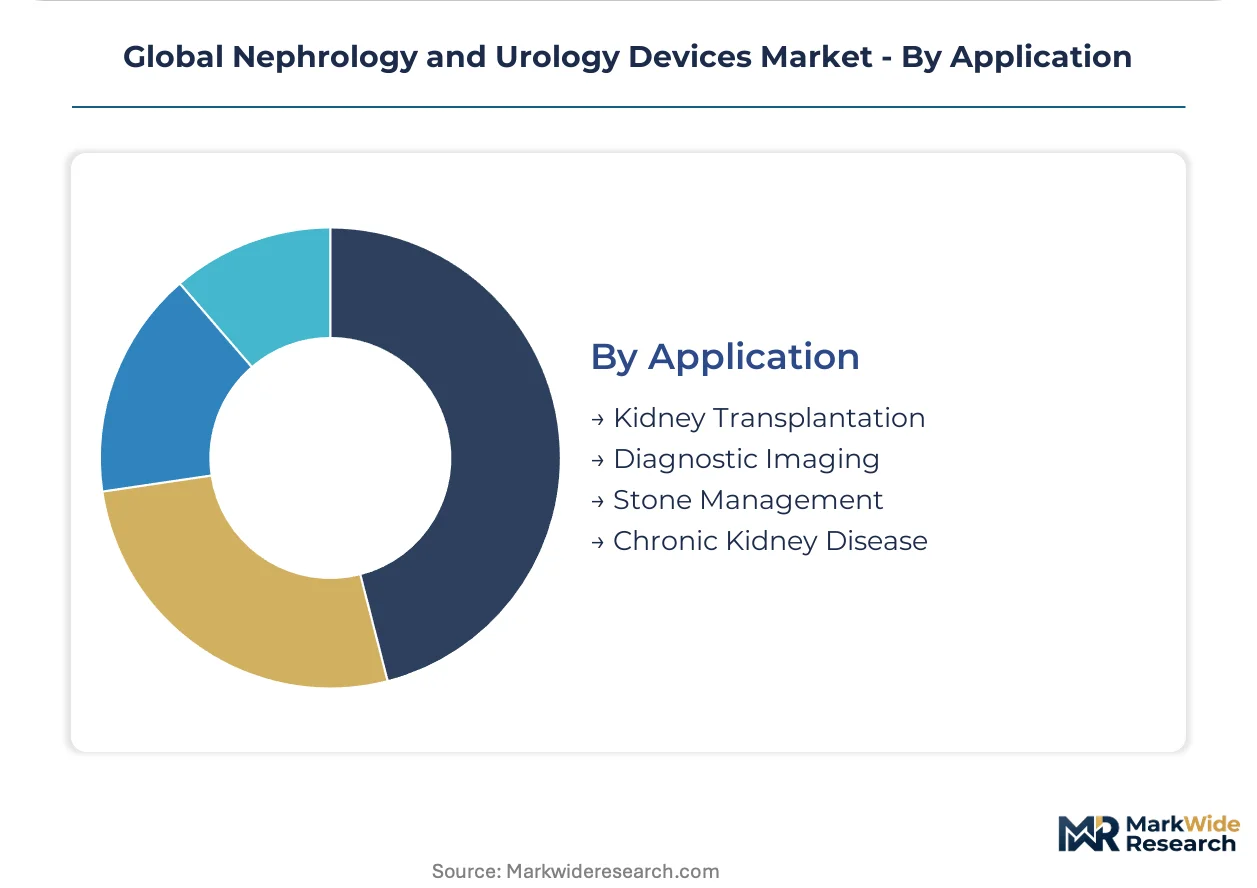
- Chronic Kidney Disease:Sustained renal function decline drives recurring demand for dialysis access maintenance, anemia management devices, and mineral bone disorder monitoring. China's deepening patient pool absorbs disproportionate infrastructure investment as NMPA accelerates priority review for innovative dialysis equipment. Rural district underpenetration in India creates whitespace for portable diagnostic platforms distributed through primary health centers.
- Stone Management:Ureteroscopy, percutaneous nephrolithotomy, and shock wave lithotripsy platforms address calcium oxalate and uric acid calculi with procedure-specific instrument configurations. German and Italian urology departments prioritize dusting laser technologies over fragmentation approaches, shifting fiber optic and holmium laser demand.
- Kidney Transplantation:Organ preservation perfusion devices and immunosuppression monitoring tools support allograft survival optimization.
- Diagnostic Imaging:Contrast injection systems and specialized biopsy needles enable renal mass characterization and histological confirmation.
Chronic kidney disease anchors volume scale. Stone management climbs fastest as dietary shifts expand calculi incidence across aging demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing for dialysis systems clusters in Germany and Japan, while final assembly and distribution networks extend across North American hospital procurement channels. China's NMPA priority review program accelerates domestic infrastructure deployment. India's diagnostic underpenetration creates whitespace for portable renal monitoring platforms.
United States
CMS reimbursement restructuring accelerates patient migration from clinic-based hemodialysis toward home-based modalities, expanding addressable volume for peritoneal dialysis cyclers. FDA 510(k) pathways govern clearance timelines for novel urological instruments entering hospital capital budgets. Boston anchors robotic-assisted surgical system development through academic medical center partnerships.
Germany
Fresenius Medical Care leverages captive component supply chains to dominate European renal device manufacturing output. EU MDR strengthened clinical evidence mandates filter lower-quality imports while privileging submissions with robust safety datasets. Baden-Württemberg precision engineering clusters supply precision pump motors concentrated among specialized Mittelstand suppliers.
China
Deepening chronic kidney disease patient pools absorb disproportionate infrastructure investment as dialysis penetration rates climb from low baselines. NMPA accelerates technical reviews to 90 days for breakthrough device designations, compressing time-to-revenue for innovative equipment. Yangtze River Delta manufacturing corridors concentrate domestic assembly capacity for dialysis consoles.
Japan
PMDA-enforced biocompatibility testing protocols maintain stringent ISO 10993 cytotoxicity standards that filter substandard catheter imports. Tokyo and Osaka academic medical centers concentrate installed base for robotic-assisted prostatectomy platforms. Kanto region precision component suppliers dominate single-source pump motor manufacturing for global dialysis machine producers.
India
Rural district diagnostic underpenetration creates demand whitespace for portable creatinine monitoring devices distributed through primary health centers. CDSCO regulatory pathways govern import licensing for dialysis equipment entering private hospital chains. Maharashtra and Karnataka urban corridors concentrate nephrology specialty clinic expansion.
Global Nephrology and Urology Devices Market Vendor Landscape
Vertically integrated conglomerates and specialized catheter manufacturers split the market across capital equipment and disposable consumable segments. Tiered competitive positioning separates scale-driven dialysis machine producers from biomaterial-focused stent and catheter specialists. Two dominant competitive moves define current rivalry: backward integration into precision component manufacturing and subscription-based software monetization displacing pure hardware sales.
Among Germany-based integrated healthcare conglomerates, Fresenius Medical Care AG & Co. KGaA and B. Braun Melsungen AG occupy positions exemplifying captive supply chain control over dialysis system manufacturing. Boston Scientific Corporation represents the specialized cardiovascular and urological device archetype, while Medtronic sits within the diversified medical technology tier competing across minimally invasive surgical platforms. These three anchors illustrate the strategic divergence between integrated renal therapy providers and precision intervention specialists.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| Boston Scientific Corporation |
| Medtronic |
| Coloplast |
| B. Braun Melsungen AG |
| Baxter International Inc. |
| ConvaTec Group plc |
| Hollister Incorporated |
| Teleflex Incorporated |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg's precision engineering corridor anchors European dialysis machine component manufacturing, where captive supply of precision pump motors translates into pricing power for integrated producers serving hospital procurement committees. This geographic concentration of critical inputs shapes tiered margin structures across device categories, with biomaterial-coated catheters commanding premium positioning against commodity alternatives.
Pricing Analysis
EU MDR dictates the pricing tier structure through strengthened clinical evidence mandates that filter lower-quality imports while privileging submissions with robust safety datasets. Three-tier pricing structure across premium, standard, and economy levels separates silicone-nitride coated infection-resistant formulations from conventional polymer catheters. Cost compression in standard-tier disposables intensifies because polymer feedstock volatility squeezes margin stability for polyurethane and silicone-dependent producers. Price sensitivity concentrates among outpatient dialysis clinic operators leasing chair capacity, while academic medical centers absorb premium robotics hardware with bundled software subscriptions.
Supply Chain Analysis
Extended payment terms from German and Japanese precision component suppliers finance working capital cycles for dialysis machine assemblers serving North American hospital systems. Manufacturing gravity centers on Germany, Japan, and China for pump motors, dialyzer membranes, and console assembly respectively. Raw material dependencies tether production schedules to medical-grade polyurethane, nitinol shape-memory alloys, and silicone-nitride ceramic composites. Single-source vulnerability concentrates in Kanto region pump motor suppliers, exposing global producers to export licensing delays. Distribution runs through GPO contracts managers and hospital procurement committees in the United States, with direct-to-clinic fulfillment expanding across European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue streams are expanding faster than hardware sales as manufacturers bundle preventive maintenance, software subscriptions, and predictive analytics alongside capital equipment. Cloud-based dialysis prescription management platforms exemplify this shift, virtualizing treatment protocols while compressing nephrologist oversight burden.
For Market Incumbents: Build captive component supply moats by securing precision pump motor manufacturing through backward integration into Baden-Württemberg and Kanto region supplier networks. Consolidate position by accelerating CE marking recertification for REACH-compliant catheter formulations before 2026 compliance deadlines. Threat from single-source component dependence creates vulnerability to export licensing delays, while robotic surgery technician scarcity limits installed base utilization rates. For New Entrants and Emerging Players: Rural district diagnostic underpenetration in Maharashtra and Karnataka represents the most penetrable entry point for portable creatinine monitoring devices distributed through India's primary health centers. Home hemodialysis console simplification for patient self-administration captures whitespace as CMS payment adjustments accelerate migration from clinic-based treatment. Go-to-market execution should prioritize direct partnerships with nephrology specialty clinic chains over hospital capital committee channels. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management infrastructure play because sustained renal function decline drives recurring demand for dialysis access maintenance and decentralized treatment delivery. Acquisition targets should concentrate on biomaterial-focused catheter specialists with silicone-nitride coating capabilities and software-enabled remote monitoring platforms. Signal to watch is NMPA priority review channel utilization rates as proxy for breakthrough device designation velocity in China's deepening patient pool.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated premarket review compresses commercialization timelines for novel urological instruments. |
| CE Marking Pathway Under EU MDR | Strengthened clinical evidence mandates filter imports while privileging robust safety datasets. |
| Hospital System Partnership | Academic medical centers in Boston and Heidelberg concentrate installed base for robotic platforms. |
| Software Companion Development | Cloud-based dialysis prescription management virtualizes treatment protocols across distributed networks. |
| Reimbursement Strategy | CMS payment adjustments accelerate patient migration toward home-based peritoneal and hemodialysis modalities. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nephrologists, hospital purchasing committees, biomedical engineers, GPO contracts managers, and dialysis clinic operators. Secondary validation drew from FDA 510(k) filings, NMPA priority review disclosures, CMS Medicare reimbursement data, EU MDR notified body submissions, and hospital procurement databases. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation anchored volume and value estimates.
Calibration against historical installed base data and procedure volume trends informed CAGR derivation across the analysis window. Segmentation dimensions modeled include device type, end-user setting, technology platform, and clinical application indication. Forecast inputs incorporated dialysis penetration rate trajectories, robotic surgery adoption curves, and home care reimbursement policy shifts without specifying timeline endpoints.
Practitioners should monitor regulatory pathway delays, polymer feedstock volatility, and robotic technician certification bottlenecks for early signals of forecast deviation. Assumptions underlying projections reflect current reimbursement structures, supply chain configurations, and technology adoption patterns. Macroeconomic contraction, regulatory pathway restructuring, or breakthrough biomaterial disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
North America Transrectal Ultrasound Market
Urology
Renal Cyst Treatment Market
Urology
Complicated Urinary Tract Infections Treatment Market
Urology
Primary Aldosteronism Market
Urology
Voiding Cystourethrogram Market
Urology
Global Hydronephrosis Market
Urology
Hematuria Treatment Market
Urology
North America Bladder Disorders Market
Urology
Cystectomy Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Europe Bladder Disorders Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Asia-Pacific Bladder Disorders Market
Urology
Global Lithotripsy Market
Urology
Ureteral Catheters Market
Urology
Global Prostate Cancer Market