
 Urinary Tract Infection Testing Market | 2026-2036
Urinary Tract Infection Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Urinary Tract Infection Testing Market Intelligence
China is fragmenting as domestic manufacturers scale point-of-care capacity while multinational suppliers defend hospital laboratory contracts. Siemens Healthineers leverages its installed base of automated urinalysis systems to sustain service revenue streams. bioMérieux anchors European demand with specialized microbiological culture media and susceptibility testing workflows. Thermo Fisher Scientific competes through vertical integration into PCR reagent manufacturing and thermal cycler distribution.
Urinary Tract Infection Testing encompasses diagnostic methods that detect pathogenic bacteria, white blood cells, nitrites, or leukocyte esterase in clinical specimens, typically urine, using culture-based incubation, chromogenic dipstick chemistry, nucleic acid amplification, or immunoassay platforms with sensitivity thresholds ranging from 10² to 10⁵ colony-forming units per milliliter. These tests guide antimicrobial selection, differentiate uncomplicated from complicated infections, and prevent inappropriate antibiotic prescribing in outpatient and inpatient settings. PCR Test platforms capture expanding margin pools as resistance gene detection commands premium pricing over conventional culture. Point-of-Care delivery mode segments are displacing laboratory-based workflows in ambulatory settings where same-day prescribing decisions reduce follow-up costs. Automated systems dominate volume economics in integrated health networks processing thousands of specimens daily.
FDA 510(k) pathways and CLIA complexity classifications determine which platforms reach physicians' offices versus centralized laboratories in the United States. EMA In Vitro Diagnostic Regulation compliance costs are restructuring competitive access across European Union member states, favoring larger manufacturers with dedicated regulatory affairs teams. Health Canada and TGA recognition of FDA-cleared devices accelerates parallel market entry for North American suppliers in Commonwealth markets. Stakeholders must monitor antimicrobial stewardship mandates that increasingly tie reimbursement to resistance-aware diagnostic testing protocols.
Market Dynamics
Antimicrobial stewardship mandates are compressing reimbursement timelines for resistance-aware diagnostics, forcing laboratories to consolidate testing workflows onto automated platforms that deliver same-day susceptibility results.
Growth Catalysts
- CLIA-waived complexity:Simplified regulatory pathways in the United States enable molecular point-of-care platforms to reach physicians' offices previously restricted to centralized laboratories.
- Urinalysis automation:High-throughput integrated health networks in Germany are replacing manual microscopy with automated particle analysis, reducing labor costs per specimen.
- Resistance gene panels:Multiplex PCR detection of ESBL and carbapenemase genes commands premium reimbursement over conventional culture methods in hospital settings.
Market Restraints
- Reagent supply concentration:PCR master mix production concentrates among three specialty chemical suppliers, creating vulnerability to input cost volatility.
- Culture confirmation requirements:Definitive diagnosis still requires 24-48 hour incubation, limiting same-day closure rates for uncomplicated infections.
- Reimbursement compression:CMS physician fee schedule adjustments are narrowing margins on established dipstick chemistry panels.
Strategic Opportunities
- Home-based specimen collection:Telehealth platforms in the United States are piloting mail-in nucleic acid preservation kits for asymptomatic screening programs.
- AI-augmented microscopy:Deep learning algorithms trained on urinalysis particle recognition are reducing technician certification requirements.
- EMA MDR transition:Dedicated regulatory affairs capabilities create competitive moats for larger manufacturers seeking CE-IVDR certification.
Industry Challenges
- LIS integration complexity:Point-of-care devices must interface with legacy laboratory information systems that lack HL7 FHIR compatibility.
- Microbiologist training gaps:Consolidated health systems are losing specialized staff capable of interpreting mixed culture results.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urinary Tract Infection Testing Market |
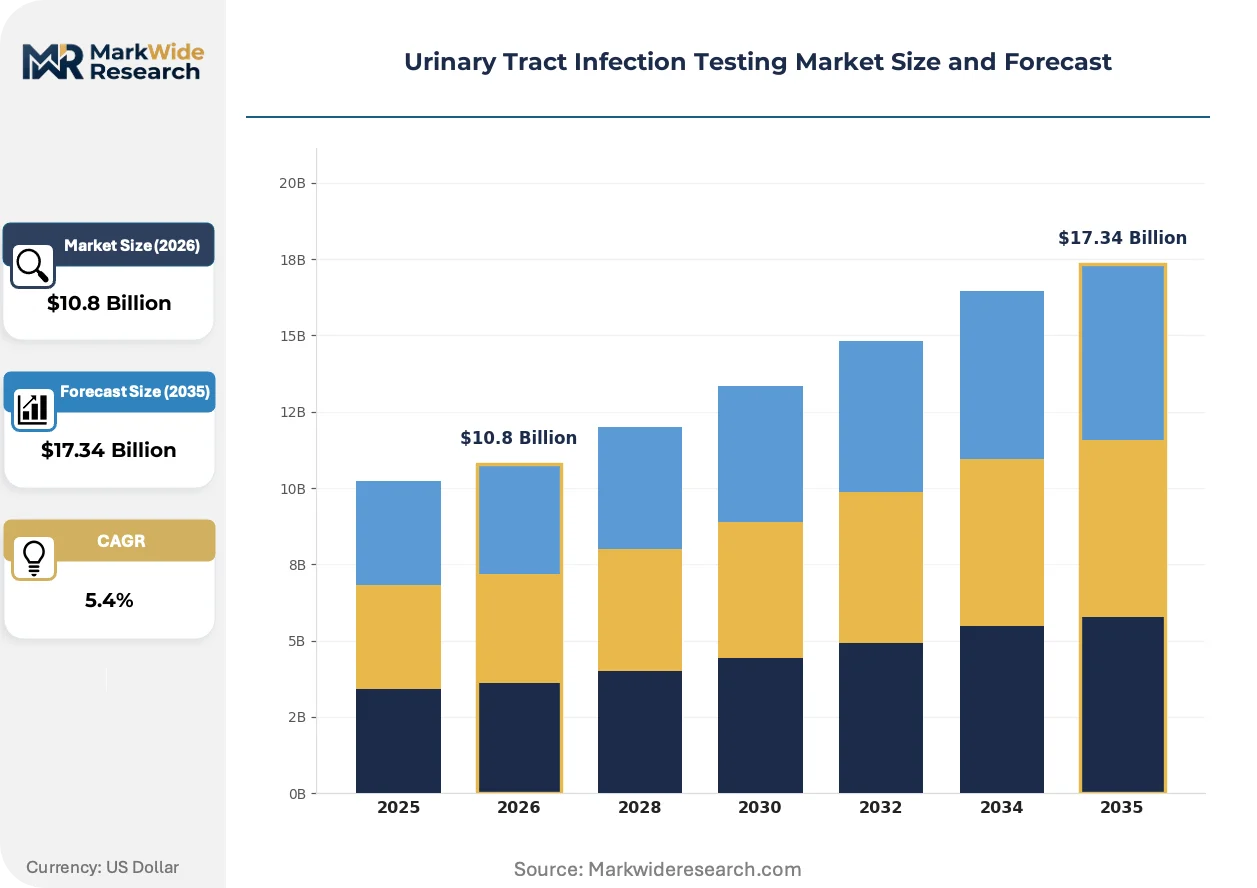
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.34 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urine Culture, Dipstick Test, PCR Test, Blood Test Delivery Mode: Lateral Flow, Automated, Laboratory-Based, Point-of-Care End User: Hospitals, Urgent Care Centers, Clinics, Homecare Technology: Microbiological, Molecular, Immunological, Biochemical |
| Companies Covered | Thermo Fisher Scientific, Siemens Healthineers, F. Hoffmann-La Roche, Randox Laboratories, Labcorp, Becton Dickinson and Company, Abbott Laboratories, bioMérieux, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urinary Tract Infection Testing Market Strategic Shifts & Innovations
Molecular and culture-based workflows are converging through automation, while regulatory frameworks on both sides of the Atlantic rewrite market access rules.
Multiplex PCR platforms are hybridizing with antimicrobial resistance databases to deliver organism identification and susceptibility prediction within two hours. Urgent care chains in the United States are deploying these systems to capture same-day prescribing revenue. The compression of diagnostic-to-treatment timelines is displacing reference laboratory send-out models.
EMA's In Vitro Diagnostic Regulation is restructuring competitive access across European Union member states by imposing clinical evidence requirements that favor established manufacturers with dedicated post-market surveillance infrastructure. Smaller developers are withdrawing from the CE-marking process. Germany and France are experiencing the most pronounced supplier consolidation.
Subscription-based reagent procurement is replacing capital purchase models for mid-sized hospital laboratories. Device manufacturers are bundling instruments with per-test consumable commitments. This shift is most visible in the United States, where health system consolidation creates volume guarantees that justify placement risk.
Urinary Tract Infection Testing Market Segmentation
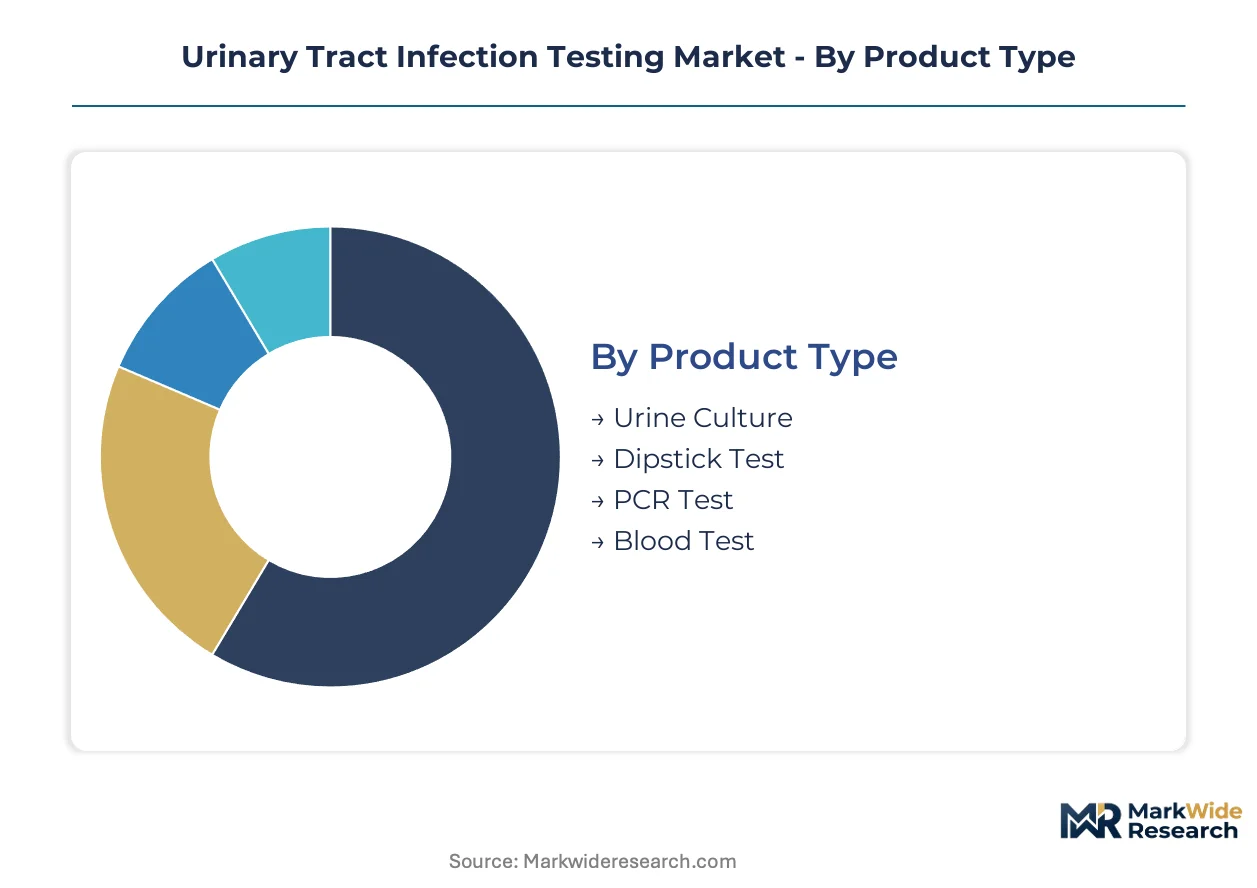
Segmentation in UTI testing reveals divergent margin structures across product architectures and care settings. Cycle times vary dramatically—from two-hour molecular turnaround to 48-hour culture confirmation—creating distinct competitive arenas with separate pricing power and regulatory pathways.
Product Type:
Urine Culture turns over slowest with 24-48 hour incubation cycles, while Dipstick and PCR platforms compress diagnostic windows to minutes or hours, reshaping where each technology competes.
- PCR Test:Nucleic acid amplification platforms detect pathogen DNA with sensitivity thresholds reaching 10² CFU/mL. Demand concentrates in US hospital laboratories where antimicrobial stewardship mandates require rapid resistance gene detection, though reagent supply concentration among specialty chemical suppliers creates input cost vulnerability.
- Dipstick Test:Chromogenic chemistry strips detect leukocyte esterase, nitrites, and blood through colorimetric reaction. Urgent care centers in Germany deploy these for same-day prescribing decisions, but CMS physician fee schedule adjustments are narrowing margins on established panels.
- Urine Culture:Gold-standard incubation method requiring 24-48 hours for definitive diagnosis with 10⁵ CFU/mL sensitivity threshold.
- Blood Test:Sepsis screening adjunct for complicated infections with bacteremia suspicion, primarily hospital-based.
Dipstick anchors the volume base while PCR gains share at the steepest rate.
Delivery Mode:
Cost tiers separate capital-intensive automated systems from disposable lateral flow devices, with subscription reagent procurement now displacing instrument purchase in mid-sized laboratories.
- Point-of-Care:CLIA-waived molecular platforms and lateral flow devices enable testing at urgent care centers and physicians' offices. US urgent care chains deploy these systems to capture same-day prescribing revenue, though LIS integration complexity with legacy laboratory information systems creates deployment friction.
- Automated:High-throughput integrated health networks in Germany replace manual microscopy with automated particle analysis, reducing labor costs per specimen while delivering standardized results across consolidated laboratory operations.
- Laboratory-Based:Centralized reference laboratory workflows with comprehensive susceptibility testing capabilities.
- Lateral Flow:Single-use immunochromatographic devices for rapid visual result interpretation without instrumentation.
Laboratory-Based anchors the volume base while Point-of-Care climbs the fastest.
End User:
Application urgency varies across settings—hospitals manage complicated infections with sepsis risk, while homecare addresses asymptomatic screening through telehealth-integrated specimen collection.
- Hospitals:Inpatient and emergency departments processing high-acuity specimens with resistance gene panel requirements. German hospital networks favor automated platforms that integrate with laboratory information systems, though microbiologist training gaps in consolidated health systems threaten interpretation quality.
- Urgent Care Centers:Ambulatory settings demanding same-day results to close prescribing loops and reduce follow-up costs. US chains are deploying multiplex PCR platforms to displace reference laboratory send-out models.
- Clinics:Outpatient primary care settings with moderate specimen volumes and mixed complexity.
- Homecare:Emerging telehealth-integrated specimen collection with mail-in nucleic acid preservation kits for asymptomatic screening programs.
Hospitals anchors the volume base while Homecare expands most quickly.
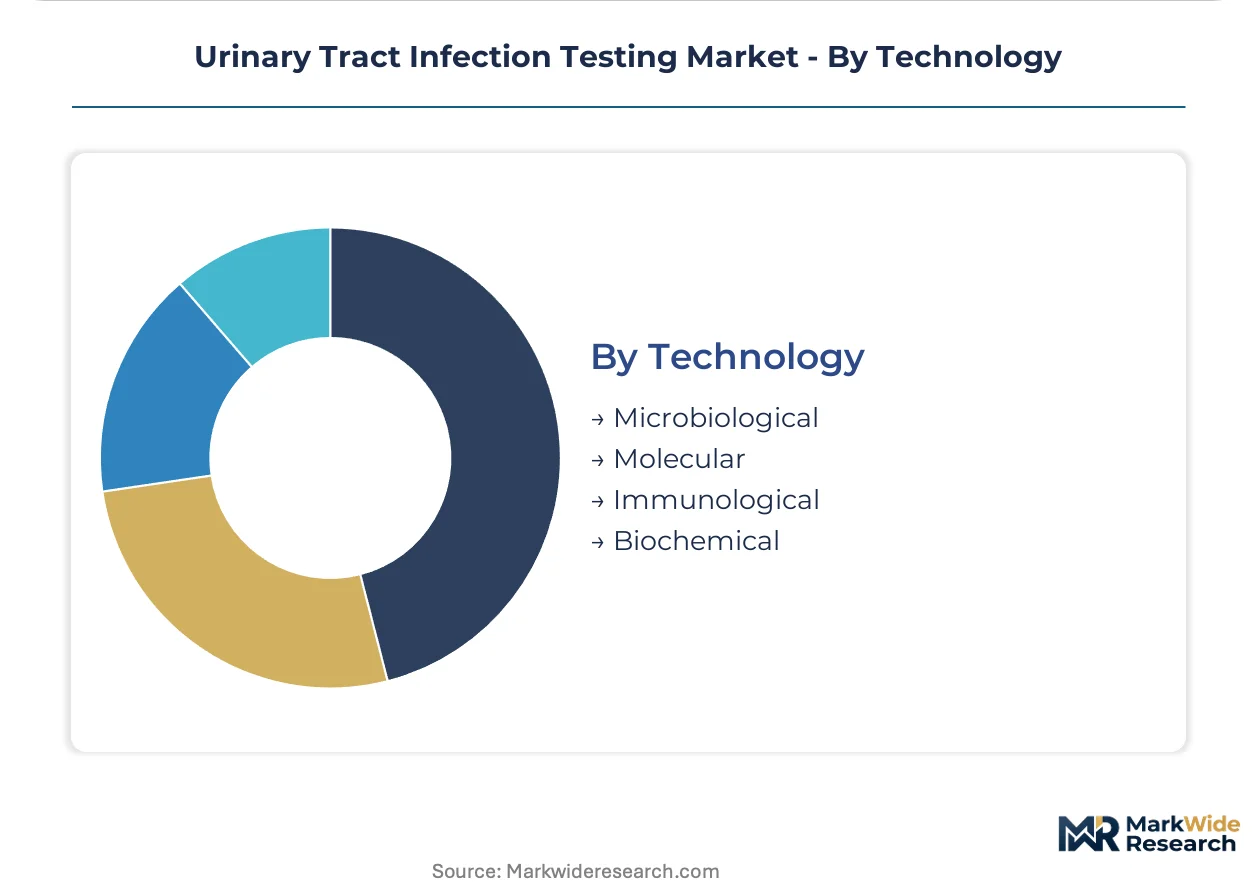
Technology:
Maturity curves separate established microbiological methods from rapidly evolving molecular platforms, with regulatory compliance costs restructuring competitive access across European Union member states.
- Molecular:PCR and nucleic acid amplification technologies with resistance gene detection capabilities. EMA In Vitro Diagnostic Regulation compliance costs favor larger manufacturers with dedicated regulatory affairs teams, while smaller developers withdraw from CE-marking processes.
- Microbiological:Culture-based incubation with antimicrobial susceptibility testing workflows. bioMérieux anchors European demand with specialized culture media, though 24-48 hour turnaround limits same-day closure rates.
- Immunological:Antigen-antibody detection platforms including lateral flow and enzyme immunoassay formats.
- Biochemical:Enzymatic and colorimetric detection methods underlying dipstick chemistry.
Microbiological anchors the volume base while Molecular shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic platform supply concentrates among automated system manufacturers in Germany, molecular specialists in the United States, and point-of-care scale-ups in China. National reimbursement frameworks and regulatory pathways determine which testing modalities achieve dominant share in each market.
United States
Urgent care chains deploy multiplex PCR platforms to capture same-day prescribing revenue previously captured by reference laboratories. FDA 510(k) pathways and CLIA-waived complexity classifications determine platform placement in physicians' offices versus centralized labs. The Texas Medical Center cluster in Houston anchors hospital laboratory consolidation with automated high-throughput installations.
Germany
Laboratory consolidation across integrated health networks favors automated urinalysis systems that reduce labor costs per specimen. EMA In Vitro Diagnostic Regulation compliance costs restructure competitive access, favoring manufacturers with dedicated post-market surveillance infrastructure. The Rhine-Ruhr metropolitan region concentrates diagnostic service provider headquarters and automated platform deployment.
China
Domestic manufacturers scale point-of-care capacity while multinational suppliers defend hospital laboratory contracts through installed base service agreements. NMPA regulatory pathways for molecular diagnostics reshape product development timelines for local and foreign developers. The Yangtze River Delta cluster around Shanghai anchors reagent manufacturing scale and distribution logistics.
United Kingdom
NHS antimicrobial stewardship mandates compress reimbursement timelines for resistance-aware diagnostics, forcing laboratory consolidation onto automated platforms. MHRA recognition of FDA-cleared devices accelerates parallel market entry for North American suppliers. The Cambridge-Oxford-London life sciences triangle concentrates molecular diagnostics R&D and clinical validation partnerships.
Japan
PMDA regulatory requirements sustain premium pricing for automated systems with integrated susceptibility testing workflows. Aging demographics drive demand for rapid point-of-care solutions in community care settings. The Kansai region around Osaka anchors specialized microbiological culture media manufacturing and distribution.
Urinary Tract Infection Testing Market Key Industry Players
Automated platform specialists and molecular diagnostics developers split the market between high-throughput laboratory installations and rapid point-of-care deployment. Siemens Healthineers leverages its installed base of automated urinalysis systems to sustain service revenue streams, while bioMérieux anchors European demand with specialized microbiological workflows. Thermo Fisher Scientific competes through in-house production of PCR reagents and thermal cycler distribution. Strategic moves concentrate on subscription-based reagent procurement replacing capital purchase models, and EMA MDR transition capabilities creating regulatory moats.
Among diversified laboratory conglomerates, Thermo Fisher Scientific and Siemens Healthineers exemplify scale-driven archetypes with integrated instrument-reagent-service portfolios. bioMérieux occupies a position within the specialized microbiology tier, representing European-centric regulatory sophistication and culture-based workflow dominance. These three anchors illustrate how competitive positioning stratifies across automated platform penetration, molecular assay breadth, and geographic regulatory specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Siemens Healthineers |
| F. Hoffmann-La Roche |
| Randox Laboratories |
| Labcorp |
| Becton Dickinson and Company |
| Abbott Laboratories |
| bioMérieux |
| Bio-Rad Laboratories |
| Others |
Cost & Logistics Intelligence
Single-source dependency on PCR master mix production concentrates among three specialty chemical suppliers, determining both the spread between premium molecular platforms and economy dipstick tiers and the geographic configuration of reagent manufacturing networks.
Pricing Analysis
FDA 510(k) pathways and CLIA complexity classifications dictate the pricing tier structure across the Urinary Tract Infection Testing landscape. Three-tier pricing structure across premium, standard, and economy levels separates multiplex PCR resistance panels from automated urinalysis systems and disposable dipstick chemistry. Price differentiation rests on certification grade and volume scale, with hospital networks commanding contract discounts unavailable to independent urgent care centers. Cost compression in the dipstick segment is intensifying because CMS physician fee schedule adjustments narrow reimbursement margins. Independent clinics exhibit highest price sensitivity, while integrated health networks with guaranteed volume commitments show least sensitivity to per-test pricing.
Supply Chain Analysis
Export-control restrictions on nucleic acid amplification thermal cyclers and specialized optical detection components limit technology flows from US and German manufacturers to certain end markets. Geographic supply concentration centers on Germany for automated particle analysis systems, the United States for PCR reagent manufacturing, and China for point-of-care lateral flow device assembly. Raw material dependencies include specialized polymerases, fluorescence resonance energy transfer probes, and chromogenic substrate chemicals. Single-source vulnerability threatens continuity for esoteric resistance gene detection panels. Distribution runs through hospital GPO contracts, urgent care chain procurement consortia, and laboratory service provider networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
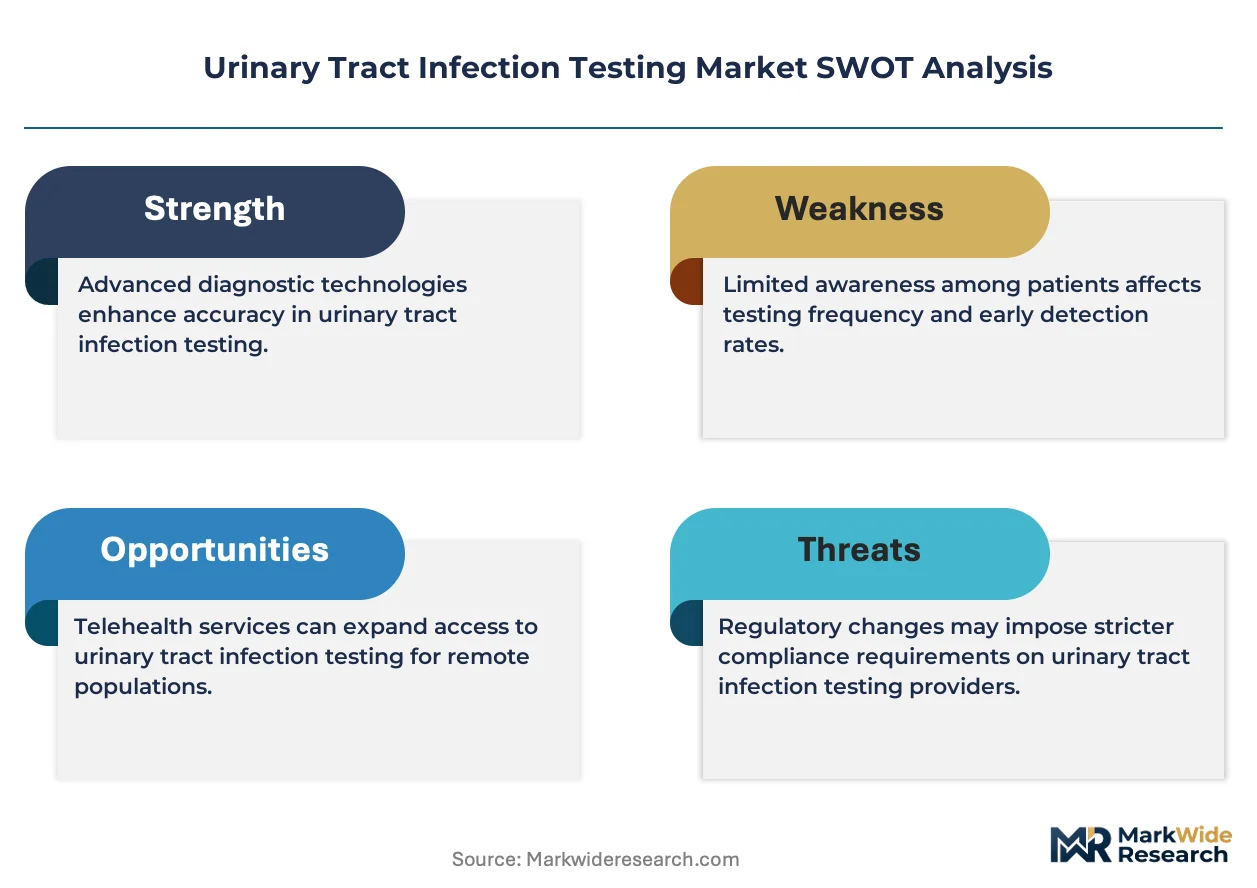
The Urinary Tract Infection Testing market is entering a cyclical recovery phase as antimicrobial stewardship mandates force laboratory infrastructure refresh cycles and consolidate procurement decisions.
For Market Incumbents: Build regulatory affairs moats through dedicated EMA MDR transition capabilities and FDA 510(k) pathway expertise. Consolidate service revenue streams by extending automated urinalysis system maintenance contracts into multi-year subscription arrangements. Emerging domestic Chinese manufacturers threaten installed base retention in Asia-Pacific hospital networks. Vertical integration into captive PCR reagent production secures margin control against specialty chemical supplier concentration. For New Entrants and Emerging Players: Establish a beachhead in homecare telehealth-integrated specimen collection, the least penetrated end-user segment with minimal incumbent lock-in. Target urgent care chain procurement consortia seeking CLIA-waived molecular platforms to displace reference laboratory send-out models. Prioritize AI-augmented urinalysis microscopy as a certification-reduction value proposition for technician-constrained health systems. For Investors and Strategic Acquirers: EMA In Vitro Diagnostic Regulation full implementation reshapes the acquisition landscape by elevating post-market surveillance infrastructure from cost center to competitive barrier. Five-to-ten year viability favors manufacturers with integrated instrument-reagent-service portfolios over pure-play assay developers. Acquisition target archetype: mid-sized European diagnostics firms with CE-IVDR certification progress and established hospital laboratory relationships. Signal to watch: NMPA regulatory pathway acceleration for molecular diagnostics in China as indicator of geographic expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA-Waived Molecular Platform Development | Unlocks physician office placement previously restricted to centralized laboratories under FDA complexity classifications. |
| Automated Urinalysis System Integration | Reduces labor costs per specimen for German integrated health networks processing thousands of daily samples. |
| Resistance Gene Panel Expansion | Commands premium reimbursement over conventional culture through ESBL and carbapenemase detection capabilities. |
| Subscription Reagent Procurement Model | Replaces capital purchase economics with per-test consumable commitments from consolidated US health systems. |
| EMA MDR Compliance Infrastructure | Creates regulatory moats favoring larger manufacturers with dedicated post-market surveillance teams. |
Research Approach
The analysis maps molecular diagnostics, automated urinalysis, culture-based microbiology, and point-of-care lateral flow segments, each validated through hospital laboratory directors, urgent care chain procurement officers, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA CE-marking databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up instrument placement counts and top-down healthcare expenditure allocations were triangulated to anchor volume estimates.
Assumptions held fixed include antimicrobial stewardship mandate enforcement intensity, CLIA complexity classification frameworks, and EMA MDR implementation timelines, while reimbursement rate trajectories and health system consolidation pace were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product architecture, delivery mode, end-user setting, and technology maturity curve. CAGRs were derived from fitted adoption curves calibrated to historical platform replacement cycles and resistance gene detection penetration patterns. Industry-specific forecast inputs include PCR reagent cost trajectories and automated microscopy technician substitution rates.
Stress conditions across CMS fee schedule adjustment magnitude, specialty chemical supply disruption duration, and EMA MDR compliance cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and the stated segmentation logic. Material shifts in FDA CLIA-waived pathway expansion or NMPA molecular diagnostic approval acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urology Lasers Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Global Nephrology and Urology Devices Market
Urology
Global Hydronephrosis Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Uraemia Treatment Market
Urology
Benign Prostatic Hyperplasia (BPH) Prostate Treatment Market
Urology
Urology Devices Market
Urology
Cystoscope Market
Urology
Global Bladder Scanner Market
Urology
Transrectal Ultrasound Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Urinary Catheters Market
Urology
Ureteral Catheters Market