
 Uraemia Treatment Market | 2026-2036
Uraemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Uraemia Treatment Market Analytics
Home healthcare is restructuring patient flow across the Uraemia Treatment landscape as payors push cost-efficient renal replacement outside institutional walls. Fresenius Medical Care dominates in-center hemodialysis infrastructure across North America and Europe. Baxter International leverages its peritoneal dialysis portfolio to anchor home-based therapy growth. Nipro Corporation specializes in dialyzer manufacturing and competes on equipment cost structures in Asia.
Uraemia treatment encompasses renal replacement therapies and pharmacological interventions that clear nitrogenous wastes, correct electrolyte imbalances, and manage fluid overload when kidney function declines below critical thresholds; hemodialysis employs semipermeable membranes with blood flow rates of 200-500 mL/min while peritoneal dialysis exploits the peritoneal membrane as a natural filter through dialysate exchange cycles. Hemodialysis equipment captures the largest installed base and replacement revenue pool, though peritoneal dialysis sustains faster growth in markets prioritizing outpatient cost containment. Medications targeting secondary hyperparathyroidism and anemia in chronic kidney disease occupy mature margin pools with biosimilar pressure rising.
FDA clearance pathways shape device commercialization timelines for dialysis machines in the United States, while EMA's Medical Device Regulation imposes clinical evidence requirements on European equipment approvals. India's CDSCO accelerates import licensing for dialysis consumables under expanded chronic disease programs. Stakeholders must monitor reimbursement parity between home and institutional modalities as regulatory frameworks evolve.
Market Dynamics
Home-based dialysis reimbursement parity is restructuring patient flow away from institutional settings, compressing hospital-linked revenue pools while expanding ambulatory and residential service networks across developed markets.
Growth Catalysts
- Medicare ESRD bundled payment reforms:United States reimbursement adjustments now compensate home dialysis at rates approaching in-center modalities, accelerating patient migration toward peritoneal and home hemodialysis alternatives.
- Peritoneal dialysis technology maturation:Automated cycler systems with remote monitoring capabilities reduce nursing burden and enable elderly patients with limited mobility to self-administer therapy.
- India's dialysis infrastructure expansion:CDSCO accelerated licensing pathways for imported dialyzers and consumables under national chronic kidney disease programs multiply treatment access points beyond tier-one cities.
Market Restraints
- Concentrated dialyzer membrane supply:Polysulfone and polyethersulfone hollow-fiber manufacturing clusters in Germany and Japan create single-source vulnerabilities for equipment OEMs.
- Water treatment infrastructure capex:Reverse osmosis systems and ultrapure water loops required for hemodialysis impose facility-level capital barriers in resource-constrained settings.
- Anticoagulant cost volatility:Heparin and regional citrate anticoagulant pricing fluctuations directly compress per-treatment margins for independent dialysis operators.
Strategic Opportunities
- Brazil's underpenetrated interior states:Minas Gerais, Ceará, and Pernambuco present whitespace for satellite dialysis clinics with mobile water treatment units serving dispersed chronic kidney disease populations.
- Remote patient monitoring integration:Cloud-connected wearable sensors tracking fluid status and electrolyte trends enable preemptive intervention before acute decompensation.
- EMA Medical Device Regulation clinical evidence pathways:Streamlined equivalence demonstrations for dialysis machine iterations reduce European commercialization timelines versus full PMA-equivalent submissions.
Industry Challenges
- Nephrology nurse workforce constraints:Specialized vascular access cannulation and ultrafiltration management skills face supply shortages in Japan, Germany, and the United States.
- Legacy EMR integration complexity:Home dialysis platforms must interface with hospital-centric electronic medical record architectures that lack standardized data exchange protocols for ambulatory renal replacement.
- Water quality certification timelines:ISO 13959 ultrapure water validation and AAMI RD62 compliance documentation extend facility commissioning by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uraemia Treatment Market |
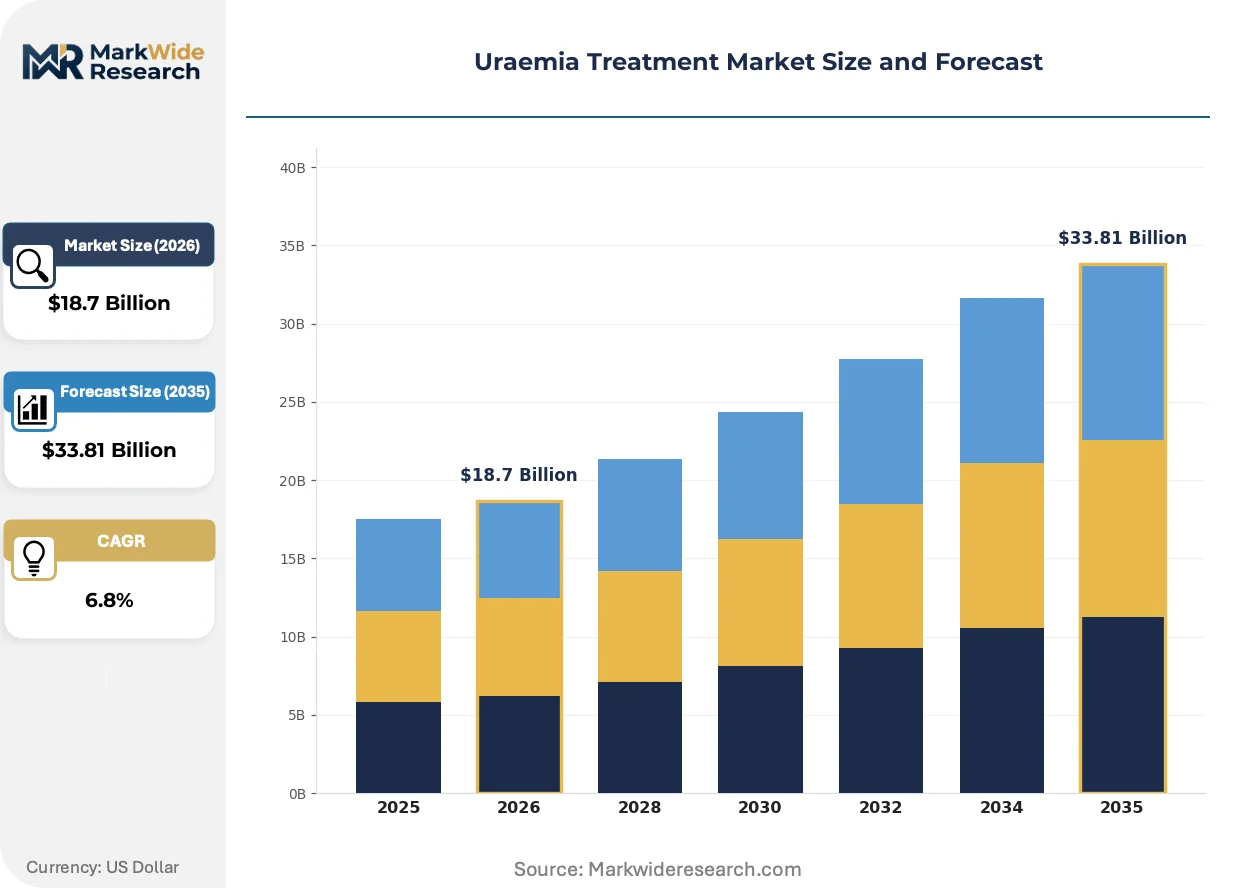
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis, Peritoneal Dialysis, Medications, Dialysis Machines Delivery Mode: In-Hospital, Home Care, Outpatient, Transplant Centers Patient Type: Chronic Kidney Disease, Acute Kidney Injury, Elderly Patients, Pediatric Patients End User: Healthcare Providers, Dialysis Centers, Hospitals, Home Healthcare |
| Companies Covered | AstraZeneca, Novartis, Roche, Fresenius Medical Care, SYNLAB, Satellite Healthcare, Baxter International, Nipro Corporation, Dialysis Clinic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uraemia Treatment Market Evolving Landscape
Digital telemetry and wearable sensing are compressing the feedback loop between treatment delivery and clinical adjustment, shifting monitoring burden from scheduled clinic visits to continuous remote surveillance.
Artificial intelligence-driven ultrafiltration prediction algorithms are converging with conventional dialysis machine architectures. Fresenius Medical Care and Baxter International deploy machine learning models that anticipate intradialytic hypotension episodes thirty minutes before hemodynamic collapse. Hospital systems in Germany and Japan pilot these predictive overlays to reduce nursing intervention frequency and shorten treatment recovery times.
EMA's Medical Device Regulation imposes post-market surveillance obligations on dialysis equipment manufacturers that exceed prior MDD requirements. European OEMs now maintain active implantable device-style vigilance systems for hemodialysis machines, including mandatory serious incident reporting within twenty-four hours. This regulatory compression favors larger manufacturers with established quality management systems over mid-tier Asian competitors seeking CE marking.
Patient self-management platforms displace traditional nurse-led training models for peritoneal dialysis initiation. Smartphone applications with video-guided catheter connection protocols and automated supply reordering reduce home nursing visit frequency by half. Elderly populations in the United States and United Kingdom demonstrate fastest uptake, driven by Medicare and NHS reimbursement incentives that reward modality switches with bundled payment bonuses.
Uraemia Treatment Market Segmentation
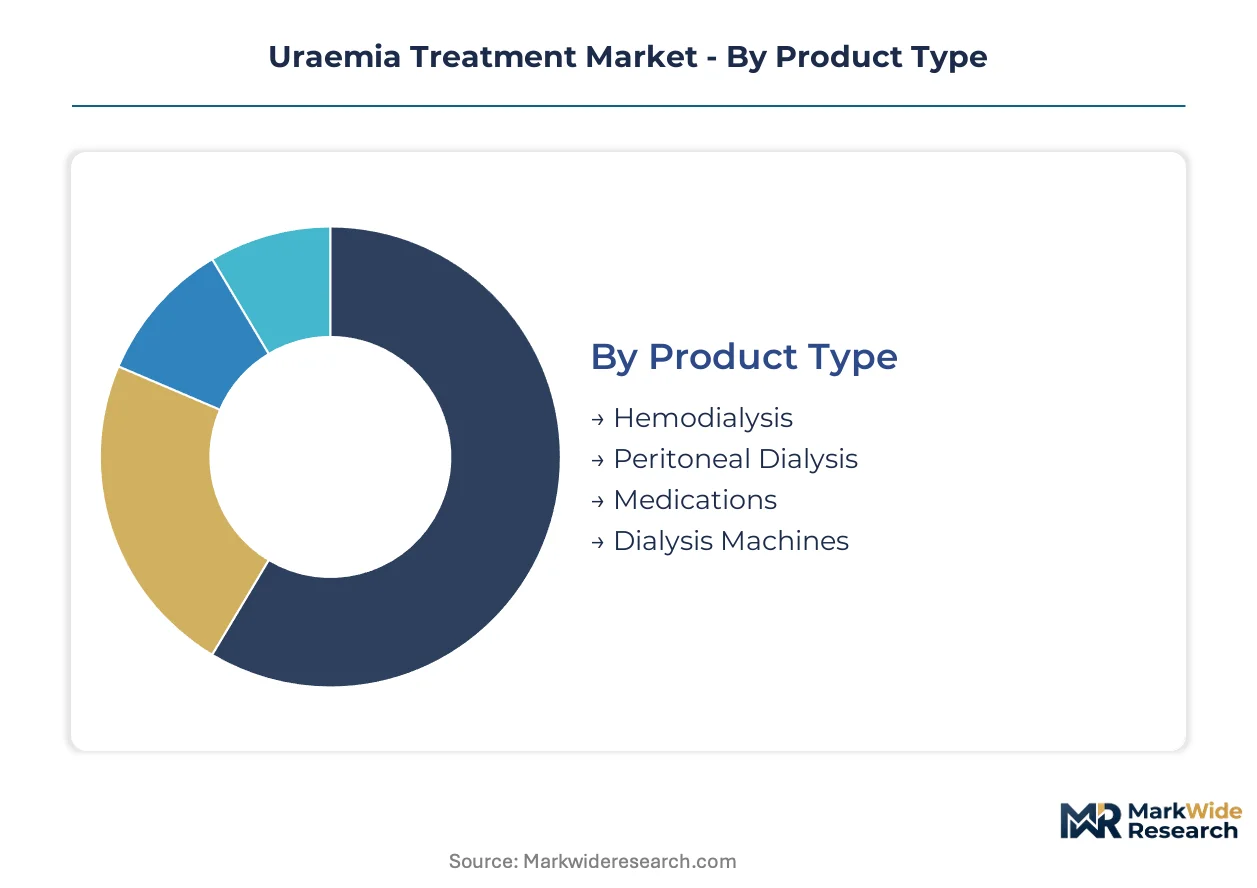
Segmentation in uraemia treatment reveals how capital deployment, reimbursement design, and patient acuity reshape competitive boundaries across modalities. Understanding these divisions exposes where infrastructure investment concentrates versus where service margins compress.
Product Type:
Capital intensity varies sharply across this category, with equipment manufacturing demanding the heaviest upfront commitment while pharmaceutical production spreads fixed costs across broader therapeutic portfolios.
- Hemodialysis:Blood purification through extracorporeal circuits employing hollow-fiber dialyzers with blood flow rates of 200-500 mL/min. Demand clusters in hospital-linked networks across Germany, Japan, and Brazil where Fresenius Medical Care dominates installed base maintenance. Medicare bundled payment reforms in the United States accelerate modality migration toward cost-efficient alternatives.
- Peritoneal Dialysis:Peritoneal membrane exploitation via dialysate exchange cycles, enabled by automated cycler systems with remote monitoring capabilities. Baxter International anchors home-based therapy growth in developed markets prioritizing outpatient cost containment. Elderly patient populations demonstrate fastest uptake where reimbursement parity reduces institutional dependency.
- Medications:Pharmacological interventions targeting secondary hyperparathyroidism and anemia in chronic kidney disease. Biosimilar pressure compresses mature margin pools across calcimimetics and erythropoiesis-stimulating agents.
- Dialysis Machines:Electromechanical systems integrating ultrafiltration control, conductivity monitoring, and heparin delivery modules. FDA and EMA regulatory pathways shape commercialization timelines for equipment OEMs.
Most installed capacity flows through Hemodialysis. Expansion is steepest in Peritoneal Dialysis.
Delivery Mode:
Patient flow restructuring follows reimbursement parity shifts, with institutional settings losing volume to residential and ambulatory alternatives where nursing burden reduction justifies technology investment.
- In-Hospital:Acute renal replacement in intensive care settings managing hemodynamic instability and multi-organ failure. Tertiary medical centers in Japan and Germany maintain highest admission thresholds for critical care dialysis.
- Home Care:Self-administered therapy with remote clinical oversight via cloud-connected wearable sensors. Medicare ESRD bundled payment reforms in the United States compensate home modalities at rates approaching in-center alternatives.
- Outpatient:Satellite clinic delivery with reduced nursing ratios and streamlined vascular access protocols. India's dialysis infrastructure expansion under CDSCO accelerated licensing multiplies treatment access points beyond tier-one cities.
- Transplant Centers:Pre- and post-transplant renal support bridging patients toward graft function or back to maintenance dialysis. Specialized immunosuppression management distinguishes this delivery tier.
Volume concentration remains in In-Hospital settings. Home Care gains share fastest where reimbursement design rewards modality switches.
Patient Type:
Disease trajectory and demographic profile determine therapy intensity, with chronic populations requiring sustained infrastructure commitment versus acute cases demanding surge capacity flexibility.
- Chronic Kidney Disease:Progressive nephron loss requiring maintenance renal replacement over years to decades. Population-scale prevalence drives installed base economics for dialysis equipment manufacturers.
- Acute Kidney Injury:Sudden filtration decline from sepsis, contrast exposure, or hypoperfusion requiring temporary support. Hospital throughput pressure shapes demand volatility in this segment.
- Elderly Patients:Age-related nephron attrition compounded by cardiovascular comorbidity and frailty. Automated peritoneal dialysis systems with video-guided training protocols reduce nursing visit frequency by half in United States and United Kingdom markets.
- Pediatric Patients:Congenital anomaly and acquired nephropathy management requiring specialized catheter designs and growth-adjusted dosing protocols. Concentrated treatment volume in quaternary children's hospitals limits addressable market scale.
Chronic Kidney Disease carries the dominant patient load. Elderly Patients expand most quickly as demographic aging intersects with home therapy enablement.
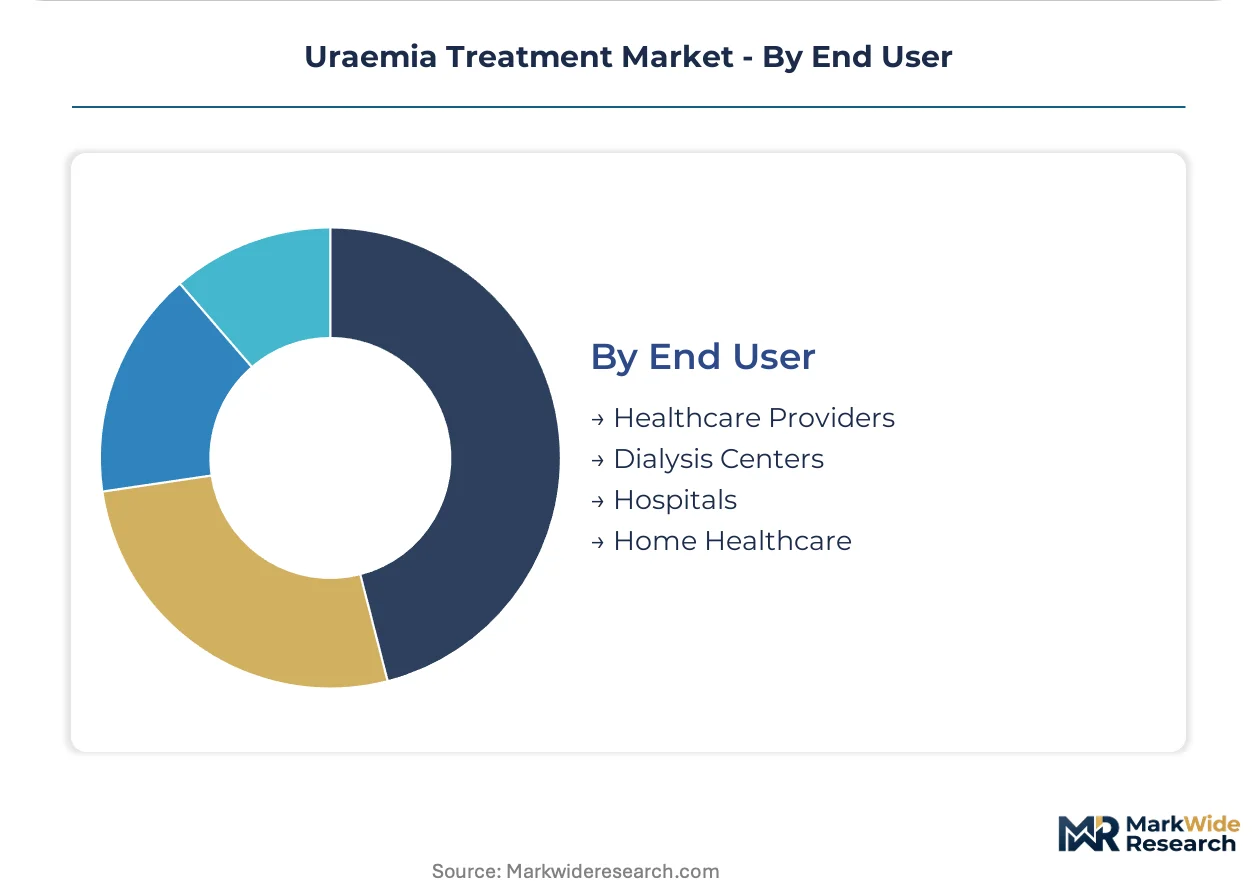
End User:
Procurement authority and reimbursement capture determine account value, with integrated health systems consolidating purchasing leverage against fragmented independent operators.
- Healthcare Providers:Physician practice networks and accountable care organizations managing total cost of care across modalities. Risk-bearing entities in the United States drive patient migration toward lower-intensity settings.
- Dialysis Centers:Dedicated renal replacement facilities with concentrated nursing expertise and economies of scale in consumables procurement. Fresenius Medical Care and Baxter International compete for network exclusivity agreements.
- Hospitals:Acute care institutions with captive nephrology services and emergency dialysis capability. Water treatment infrastructure capex for reverse osmosis systems and ultrapure water loops imposes facility-level capital barriers.
- Home Healthcare:Residential service networks deploying mobile nursing and remote patient monitoring for peritoneal dialysis patients. Smartphone applications with automated supply reordering displace traditional training models.
Dialysis Centers command the largest revenue pool. Home Healthcare climbs the fastest as payors push cost-efficient renal replacement outside institutional walls.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fresenius Medical Care's manufacturing footprint in Bad Homburg anchors dialysis equipment supply chains serving hospital-linked networks across Germany, Japan, and Brazil. Medicare reimbursement reforms in the United States and CDSCO licensing acceleration in India are restructuring patient flow toward home-based modalities.
United States
Medicare ESRD bundled payment reforms now compensate home dialysis at rates approaching in-center modalities, accelerating patient migration toward peritoneal alternatives. FDA clearance pathways shape commercialization timelines for dialysis machine manufacturers seeking 510(k) or PMA designations. Hospital-linked dialysis networks in Texas, Florida, and California maintain the highest concentration of maintenance hemodialysis capacity.
Germany
Polysulfone and polyethersulfone hollow-fiber dialyzer manufacturing clusters create single-source vulnerabilities for equipment OEMs dependent on membrane supply. EMA's Medical Device Regulation imposes post-market surveillance obligations exceeding prior MDD requirements, favoring larger manufacturers with established quality management systems. Fresenius Medical Care dominates installed base maintenance across North Rhine-Westphalia and Bavaria.
Japan
Specialized vascular access cannulation and ultrafiltration management skills face supply shortages, constraining expansion of dialysis center networks. PMDA regulatory frameworks align with MDR-equivalent clinical evidence requirements for equipment approvals. METI industrial policy supports domestic dialyzer production in the Kansai and Chubu regions.
India
CDSCO accelerated licensing pathways for imported dialyzers and consumables under national chronic kidney disease programs multiply treatment access points beyond tier-one cities. Reverse osmosis systems and ultrapure water loops impose facility-level capital barriers in resource-constrained settings. Maharashtra and Karnataka host the fastest-growing outpatient dialysis clinic deployments.
Brazil
Minas Gerais, Ceará, and Pernambuco present whitespace for satellite dialysis clinics with mobile water treatment units serving dispersed chronic kidney disease populations. ANVISA regulatory harmonization with IMDRF standards streamlines import licensing for dialysis equipment. São Paulo and Rio de Janeiro maintain concentrated nephrology specialist networks.
Uraemia Treatment Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment manufacturers align with pharmaceutical developers to bundle renal replacement therapies with disease-modifying agents. The vendor base organizes around three tiers: integrated dialysis service operators controlling captive equipment supply, standalone device manufacturers competing on cost structures, and pharmaceutical developers targeting secondary complications of chronic kidney disease. Consolidation pressures intensify as reimbursement parity between home and institutional modalities compresses margins for independent operators. Technology licensing agreements and backward integration into dialyzer membrane production represent the dominant competitive vectors.
Among integrated service operators, Fresenius Medical Care and Baxter International exemplify contrasting modality strategies, with the former anchoring in-center hemodialysis infrastructure and the latter leveraging peritoneal dialysis portfolios for home-based growth. Nipro Corporation occupies a position within the standalone device manufacturing tier, competing on equipment cost structures in Asian markets.
| Leading Market Players |
|---|
| AstraZeneca |
| Novartis |
| Roche |
| Fresenius Medical Care |
| SYNLAB |
| Satellite Healthcare |
| Baxter International |
| Nipro Corporation |
| Dialysis Clinic |
| Others |
Value Network & Pricing Analysis
Dialysis center networks in the United States and Germany command substantial procurement leverage, compressing equipment margins while rewarding suppliers with captive membrane production and multi-year service contracts. Pricing stratifies across premium, standard, and economy tiers based on regulatory certification grade and after-sales bundling intensity.
Pricing Analysis
Distributor margins on dialyzers and consumables typically absorb 15-25 percent of landed cost before reaching independent clinic operators. Three-tier pricing structure across premium, standard, and economy levels reflects FDA versus CE marking differentiation and volume commitment scale. Cost compression in the economy tier intensifies as Indian and Brazilian procurement authorities consolidate tender awards. Hospital systems demonstrate lowest price sensitivity due to bundled reimbursement capture, while independent dialysis operators in resource-constrained settings face acute margin pressure from anticoagulant cost volatility.
Supply Chain Analysis
Refurbishment flows for hemodialysis machines extend asset lifecycles and create secondary revenue pools for service-integrated OEMs. Manufacturing concentration in Germany, Japan, and the United States draws from polysulfone resin feedstocks and precision hollow-fiber spinning equipment. Single-source vulnerability in membrane supply creates structural risk for equipment assemblers lacking backward integration into polymer production. Distribution runs through hospital procurement consortia and GPO contracts in developed markets, with direct government tender channels dominating emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
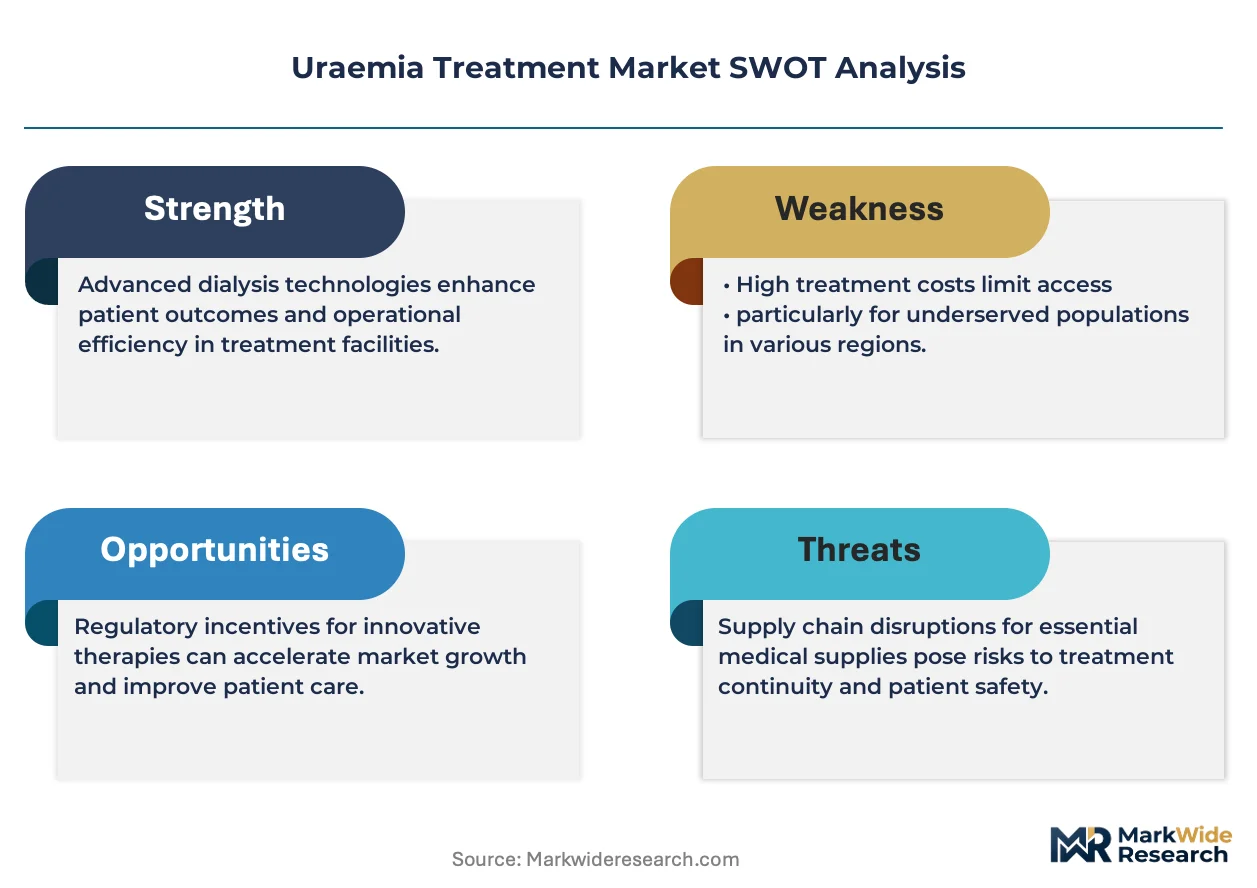
The Uraemia Treatment Market functions as a stable compounder anchored by irreversible disease progression and recurring therapy consumption. Medicare reimbursement parity and aging demographics sustain predictable revenue visibility across the analysis window.
For Market Incumbents: Extend remote patient monitoring capabilities to defend against technology-enabled challengers entering the home dialysis space. Deepen backward integration into dialyzer membrane production to insulate margins from polymer supply shocks. Prioritize certification investment under EMA MDR post-market surveillance requirements to maintain European market access against mid-tier Asian competitors. For New Entrants and Emerging Players: Launch via mobile water treatment unit leasing models to penetrate Brazil's interior states where infrastructure gaps block incumbent expansion. Target elderly patient populations in the United Kingdom and United States where reimbursement bonuses reward modality switches. Deploy smartphone-guided peritoneal dialysis training platforms to reduce nursing dependency and accelerate patient onboarding. For Investors and Strategic Acquirers: Integrated dialysis service operators are the most active acquirer in this space, consolidating independent clinic networks to capture economies of scale in consumables procurement. The 5-10 year viability window favors targets with established home therapy platforms and reimbursement strategy expertise. Monitor FDA clearance timelines for AI-driven ultrafiltration prediction algorithms as an inflection indicator for technology-enabled margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Patient Monitoring Integration | Cloud-connected wearable sensors enable preemptive clinical intervention before acute decompensation episodes. |
| Backward Integration into Membrane Production | In-house polysulfone hollow-fiber manufacturing insulates equipment OEMs from German and Japanese supply concentration. |
| EMA MDR Certification Pathway | Streamlined equivalence demonstrations reduce European commercialization timelines versus full PMA-equivalent submissions. |
| Mobile Water Treatment Unit Deployment | Satellite clinic penetration in Brazil's interior states bypasses fixed infrastructure capex barriers. |
| AI-Driven Ultrafiltration Prediction | Machine learning models anticipating intradialytic hypotension reduce nursing intervention frequency in German hospital pilots. |
Research Methodology
Direct dialogue with nephrology clinic operators, biomedical engineering directors, hospital purchasing committee members, and GPO contracts managers grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and CDSCO import licensing records. Bottom-up patient volume modeling and top-down equipment installed base estimates were triangulated to constrain forecast variance.
Segmentation outputs across product type, delivery mode, patient type, and end user were projected across the analysis window. CAGRs were derived from historical modality migration patterns and reimbursement policy elasticity estimates. Forecast inputs incorporated nephrology nurse workforce supply constraints, water treatment infrastructure deployment rates, and biosimilar penetration trajectories in anemia and hyperparathyroidism pharmacotherapy.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt reimbursement parity reversal or concentrated membrane supply disruption. Practitioners should monitor Medicare ESRD bundled payment adjustment announcements and polysulfone resin pricing indices for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urology Devices Market
Urology
Suprapubic Catheters Market
Urology
Urinary Incontinence Treatment Drugs Market
Urology
Urinary Retention Therapeutics Market
Urology
Non-Metastatic Castration-Resistant Prostate Cancer (NMCRPC) Therapeutics Market
Urology
Single Use Cystoscope Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Urology Surgery Supplies Market
Urology
Pyelonephritis Treatment Market
Urology
Ureter Cancer Treatment Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Urinary Bag Market
Urology
Disposable Ureteroscope Market
Urology
Uropathy Treatment Market
Urology
Urinary Tract Infection (UTI) Treatment Market