
 Global Benign Prostatic Hyperplasia Treatment Market | 2026-2036
Global Benign Prostatic Hyperplasia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Benign Prostatic Hyperplasia Treatment Market Foresight
The capital-intensity divergence between device manufacturers and pharmaceutical developers is unwinding competitive boundaries in this space. Pfizer Inc. leverages its established urology portfolio to sustain formulary access across hospital systems. Boston Scientific Corporation anchors its position through endoscopic platform integration that reduces operative complexity. Astellas Pharma Inc. differentiates via sustained-release formulations that extend dosing intervals for chronic management.
Benign prostatic hyperplasia treatment encompasses pharmacological and interventional modalities designed to relieve lower urinary tract symptoms caused by prostate gland enlargement, with alpha blockers achieving onset within hours through smooth muscle relaxation and 5-alpha reductase inhibitors requiring six months for measurable volume reduction. The therapy area segment shows alpha blockers occupying the largest prescription volume while phosphodiesterase inhibitors capture expanding off-label use for concurrent erectile dysfunction. In the procedure type dimension, laser therapy represents the fastest-growing surgical category as outpatient migration reduces catheterization duration and recovery timelines.
FDA clearance pathways and the EU Medical Device Regulation shape device commercialization timelines, while the FDA's Office of Generic Drugs accelerates therapeutic competition through abbreviated new drug application reviews. Japan's PMDA maintains distinct clinical trial requirements that delay multinational launch synchronization. Stakeholders must monitor reimbursement recalibration for outpatient prostate artery embolization as real-world evidence accumulates against traditional transurethral resection benchmarks.
Market Dynamics
The outpatient migration of surgical procedures is compressing hospital revenue per case while expanding addressable volume for ambulatory surgical centers equipped with laser platforms.
Growth Catalysts
- EU Medical Device Regulation:Updated MDR requirements for Class IIa/IIb surgical devices are accelerating quality system investments that favor scaled manufacturers with established notified body relationships.
- Medicare reimbursement expansion:CMS coverage determinations for photoselective vaporization procedures in freestanding surgery centers are pulling case volume away from inpatient settings.
- Holmium laser technology:Fiber-optic delivery systems with improved hemostasis are reducing transfusion rates and enabling same-day discharge protocols.
Market Restraints
- Input cost volatility:Rare earth elements in solid-state laser crystals face supply concentration from Chinese processing facilities, creating margin pressure on device manufacturers.
- Technical limitation:Tissue retrieval capabilities for histopathological examination remain inferior to transurethral resection, constraining adoption in populations with elevated prostate cancer risk profiles.
- Regulatory friction:Japan's PMDA requires domestic clinical trials for laser devices even with FDA clearance, delaying multinational launch synchronization by 18-24 months.
Strategic Opportunities
- Underpenetrated geography:India's tier-2 and tier-3 cities present white space for mobile lithotripsy units repurposed for BPH procedures, given urologist concentration in metropolitan centers.
- Technology convergence:Integration of real-time pressure-flow urodynamics with laser ablation systems enables intraoperative customization of tissue removal depth.
- Regulatory tailwind:The EU Green Deal's medical device circular economy requirements favor reusable fiber technologies over single-use disposable alternatives.
Industry Challenges
- Skill acquisition timelines:Laser enucleation techniques require 40-60 supervised cases for proficiency, creating training bottlenecks as community urologists transition from resection.
- Certification complexity:Dual ISO 13485 and MDR quality management system audits impose 6-9 month delays on product line extensions for established manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Benign Prostatic Hyperplasia Treatment Market |
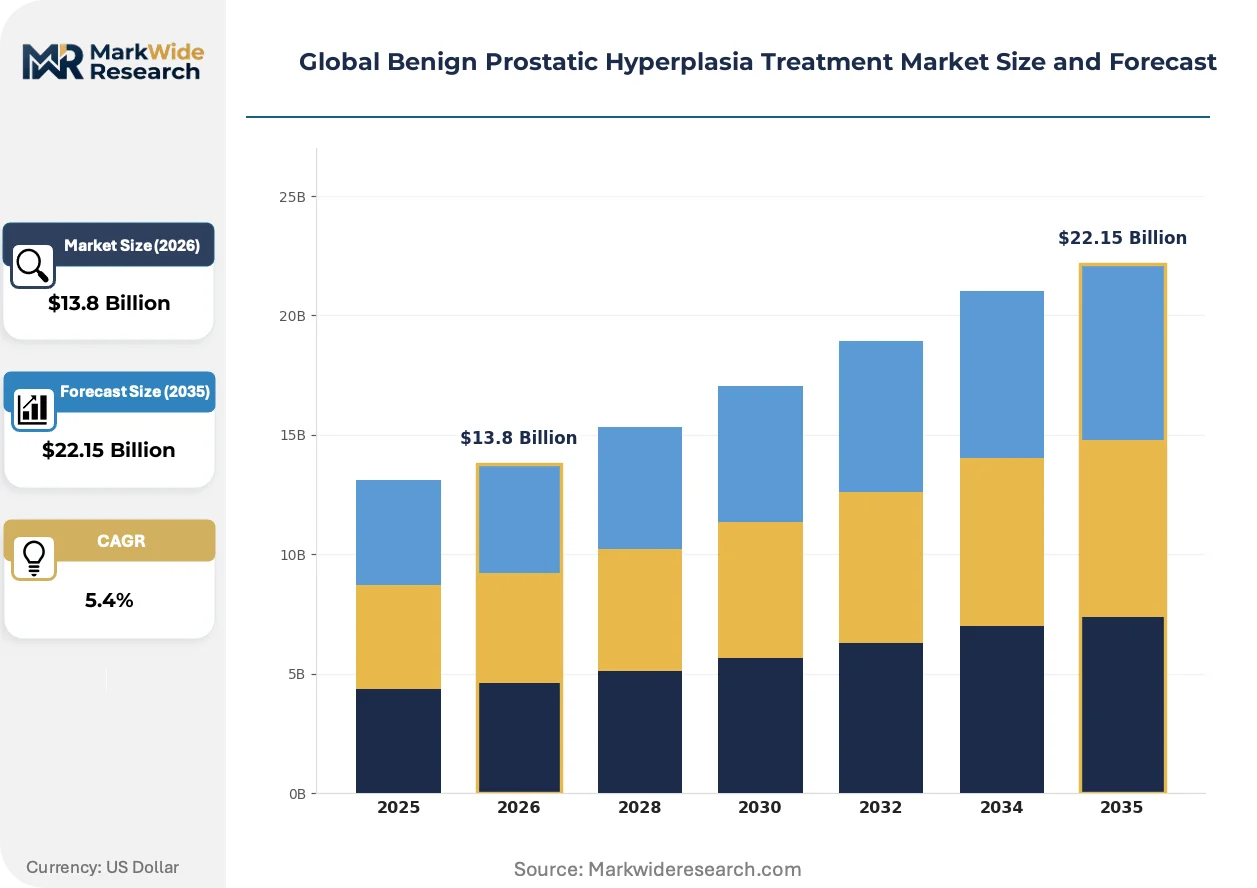
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Alpha Blockers, 5-Alpha Reductase Inhibitors, Phosphodiesterase Inhibitors, Herbal Supplements Dosage Form: Oral Tablets, Transurethral Devices, Injectable Solutions, Topical Gels Care Setting: Urology Clinics, Ambulatory Surgery Centers, Diagnostic Laboratories, Specialized Hospitals Procedure Type: Transurethral Resection, Prostate Artery Embolization, Laser Therapy, Microwave Therapy |
| Companies Covered | Pfizer Inc., GlaxoSmithKline plc, Astellas Pharma Inc., Boston Scientific Corporation, Teleflex Incorporated, Olympus Corporation, Eli Lilly and Company, AbbVie Inc., Boehringer Ingelheim GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Benign Prostatic Hyperplasia Treatment Market Shifts & Advancements
Digital integration and energy platform diversification are redefining capital equipment procurement criteria across urology practices.
Thulium fiber laser systems are fragmenting the surgical energy market previously dominated by holmium platforms. Outpatient surgery chains in Germany and the United States are adopting thulium technology for its continuous-wave cutting efficiency and reduced fiber degradation. The technology is fragmenting purchasing decisions away from bundled platform commitments toward modular energy-source flexibility.
REACH regulation amendments on fluorinated greenhouse gases are constraining coolant options for solid-state laser cooling systems. Device manufacturers are redesigning thermal management architectures to accommodate hydrofluorocarbon alternatives with higher global warming potential thresholds. European urology clinics face 12-18 month equipment refresh cycles as legacy systems lose service support.
Subscription-based service models are displacing traditional capital purchase arrangements for high-value laser platforms. Hospital procurement departments in France and the United Kingdom are negotiating per-procedure leasing structures that transfer obsolescence risk to manufacturers. This shift concentrates negotiating leverage with multi-site health systems while marginalizing independent practice purchasers.
Global Benign Prostatic Hyperplasia Treatment Market Segmentation
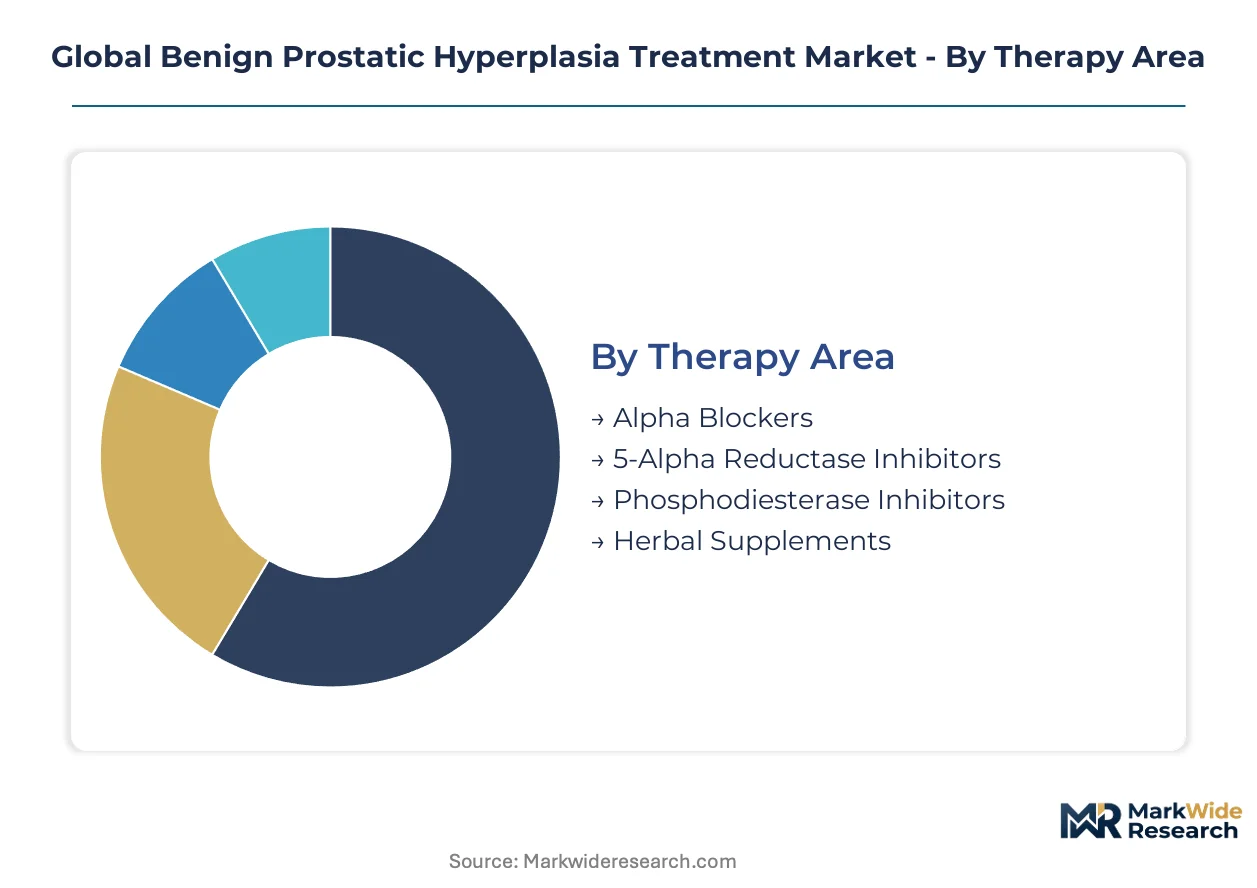
Segmentation in benign prostatic hyperplasia treatment reveals divergent margin structures across pharmacological and interventional modalities. Therapy area and procedure type categories command distinct reimbursement profiles, while care setting segmentation tracks the outpatient migration reshaping capital deployment.
Therapy Area:
Margin pools concentrate in chronic maintenance regimens with extended patent protection and limited generic substitution.
- Alpha Blockers:These agents achieve symptomatic relief within hours through selective alpha-1 adrenergic receptor antagonism in prostatic smooth muscle. Demand clusters in the United States, where Medicare Part D formulary placement and urologist prescribing habits sustain volume leadership despite generic commoditization.
- 5-Alpha Reductase Inhibitors:Long-acting enzyme inhibitors reduce dihydrotestosterone-mediated prostate volume over six-month treatment horizons. Germany's statutory health insurance reimbursement for combination therapy with alpha blockers preserves premium pricing for enlarged prostate indications.
- Phosphodiesterase Inhibitors:Off-label expansion for concurrent erectile dysfunction management drives prescription growth in Japan and South Korea.
- Herbal Supplements:Saw palmetto and pygeum extracts capture self-pay demand in markets with limited pharmaceutical reimbursement.
The dominant share belongs to Alpha Blockers, while Phosphodiesterase Inhibitors is closing the gap fastest.
Procedure Type:
Technology differentiation determines equipment utilization rates and per-procedure profitability across surgical modalities.
- Laser Therapy:Photoselective vaporization and holmium laser enucleation enable same-day discharge through superior hemostasis and reduced irrigation requirements. Ambulatory surgery centers in the United States and Germany are expanding platform capacity as CMS and German sickness funds extend outpatient reimbursement coverage.
- Transurethral Resection:Monopolar and bipolar electrosurgical resection remains the histopathological gold standard for tissue retrieval. India's metropolitan hospital systems maintain high utilization for cancer-risk populations where specimen examination is mandatory.
- Prostate Artery Embolization:Interventional radiology procedures gain traction in France and the United Kingdom through per-procedure payment models that bypass surgical facility fees.
- Microwave Therapy:Transurethral microwave thermotherapy occupies a narrowing niche for patients ineligible for anesthesia.
Transurethral Resection retains volume leadership, yet Laser Therapy is expanding most quickly as outpatient protocols mature.
Care Setting:
Capital intensity and reimbursement differentials segment patient flow across facility types.
- Ambulatory Surgery Centers:Freestanding facilities equipped with laser platforms capture migrating case volume from inpatient settings. United States-based chains negotiate bundled payment rates with commercial insurers that exceed hospital outpatient department reimbursement.
- Urology Clinics:Office-based practices concentrate initial diagnosis and medical management. Germany's Kassenärztliche Vereinigung regional associations determine physician fee schedules that incentivize clinic-based conservative therapy.
- Specialized Hospitals:Academic medical centers retain complex cases requiring multidisciplinary management.
- Diagnostic Laboratories:PSA testing and urodynamic assessment support referral decisions.
Ambulatory Surgery Centers command the steepest expansion trajectory, while Urology Clinics anchor prescription volume.
Dosage Form:
Patient compliance and administration convenience shape formulation development priorities.
- Oral Tablets:Once-daily extended-release formulations dominate chronic therapy. Astellas Pharma's sustained-release tamsulosin technology extends dosing intervals and improves adherence metrics in Japan's aging population.
- Transurethral Devices:Drug-eluting stents and intraurethral inserts address acute urinary retention. FDA 510(k) clearance pathways accelerate commercialization for devices with predicate equivalence.
- Injectable Solutions:Depot formulations enable quarterly administration for patients with polypharmacy challenges.
- Topical Gels:Transdermal delivery remains investigational for BPH-specific indications.
Oral Tablets maintain dominant share, though Transurethral Devices are gaining share fastest through minimally invasive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates demand for minimally invasive laser procedures, whereas Germany and Japan maintain stronger pharmaceutical prescribing volumes for chronic BPH management.
United States
Medicare reimbursement for photoselective vaporization in ambulatory surgery centers drives outpatient migration from inpatient settings. FDA 510(k) clearance pathways accelerate commercialization timelines for predicate-equivalent laser devices. Urology practice chains in Texas and Florida expand laser platform capacity to capture bundled payment rates exceeding hospital outpatient department reimbursement.
Germany
Statutory health insurance funds sustain premium pricing for combination therapy with alpha blockers and 5-alpha reductase inhibitors. Updated EU Medical Device Regulation requirements accelerate quality system investments among Class IIa/IIb surgical device manufacturers. Urology clinics in Bavaria and North Rhine-Westphalia expand holmium laser enucleation capacity following notified body recertification cycles.
Japan
Aging demographics and sustained-release formulation demand from Astellas Pharma anchor prescription volume for chronic medical management. PMDA domestic clinical trial requirements delay multinational launch synchronization for laser devices by 18-24 months even with prior FDA clearance. Tokyo and Osaka metropolitan medical centers concentrate interventional radiology expertise for prostate artery embolization procedures.
India
Metropolitan hospital systems in Mumbai and Delhi maintain high transurethral resection utilization for cancer-risk populations requiring histopathological specimen examination. CDSCO regulatory pathways for medical devices prioritize predicate equivalence reviews for laser platform registrations. Tier-2 cities present white space for mobile lithotripsy units repurposed for BPH procedures given urologist concentration in metropolitan centers.
United Kingdom
Per-procedure payment models for prostate artery embolization bypass surgical facility fees and pull case volume toward interventional radiology departments. NHS England coverage determinations for outpatient laser therapy expand same-day discharge protocols. Hospital procurement departments in London and Manchester negotiate subscription-based leasing structures for high-value laser platforms that transfer obsolescence risk to manufacturers.
Global Benign Prostatic Hyperplasia Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this market. Pharmaceutical developers with established urology portfolios compete against device manufacturers integrating endoscopic platforms with energy delivery systems. Three archetypes dominate: diversified pharmaceutical conglomerates with chronic disease franchises, surgical device specialists with laser platform expertise, and interventional urology equipment providers with endoscopic integration capabilities. Competitive moves concentrate on strategic partnerships for technology convergence and geographic licensing arrangements to bypass PMDA trial requirements.
Among pharmaceutical developers, Pfizer Inc. and Eli Lilly and Company exemplify the diversified conglomerate archetype with established formulary access across hospital systems. Within the surgical device tier, Boston Scientific Corporation and Olympus Corporation occupy positions anchored by endoscopic platform integration that reduces operative complexity. Astellas Pharma Inc. represents the sustained-release formulation specialist segment with extended dosing interval technologies for chronic BPH management.
| Leading Market Players |
|---|
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Astellas Pharma Inc. |
| Boston Scientific Corporation |
| Teleflex Incorporated |
| Olympus Corporation |
| Eli Lilly and Company |
| AbbVie Inc. |
| Boehringer Ingelheim GmbH |
| Others |
Supply & Pricing Matrix
Thulium fiber laser systems displacing legacy holmium platforms simultaneously concentrate sourcing requirements around Chinese rare earth processing and fragment equipment purchasing decisions across modular energy-source configurations. This substitution dynamic redistributes pricing power toward fiber manufacturers while compressing margins for integrated platform vendors locked into long-term service commitments.
Pricing Analysis
Long-term per-procedure leasing contracts dominate hospital procurement in France and the United Kingdom, displacing traditional capital purchase arrangements. Three-tier pricing structure across premium laser platforms, standard bipolar systems, and economy microwave units reflects after-sales service bundling and training inclusion. Pricing pressure stems from subscription models transferring obsolescence risk to manufacturers. Independent urology practices exhibit highest price sensitivity; multi-site health systems leverage volume concentration for preferential rates.
Supply Chain Analysis
China anchors rare earth element supply for solid-state laser crystals, while Germany and Japan concentrate precision optics manufacturing and fiber-optic delivery system production. Yttrium-aluminum-garnet crystals, thulium-doped fibers, and holmium laser rods constitute critical component dependencies. Single-source vulnerability around Chinese rare earth processing creates exposure to export restriction scenarios. Distribution runs through specialized medical device distributors holding notified body certifications for EU MDR compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring revenue from fiber replacement cycles and preventive maintenance contracts expands faster than hardware unit sales, transforming capital equipment vendors into service-anchored platforms. This service-attach opportunity rewards stakeholders who embed consumable lock-in and training certification into initial deployment structures.
For Market Incumbents: Secure exclusive supply agreements for thulium-doped fiber from Japanese specialty manufacturers before emerging laser entrants replicate platform architecture. Consolidate position through backward integration into rare earth element sourcing partnerships that insulate against Chinese export volatility. Prioritize ISO 13485 and MDR dual certification investments to accelerate product line extension timelines relative to notified body-constrained competitors. For New Entrants and Emerging Players: FDA 510(k) predicate equivalence pathways offer fastest commercialization velocity for photoselective vaporization devices referencing cleared holmium platforms. India's tier-2 cities present accessible white space given metropolitan urologist concentration and limited laser platform penetration. Deploy mobile lithotripsy units repurposed for BPH procedures through equipment-leasing partnerships with regional diagnostic chains. For Investors and Strategic Acquirers: EU MDR recertification deadlines reshape the acquisition landscape toward scaled manufacturers with established notified body relationships and quality system infrastructure. Five-to-ten year viability favors surgical device specialists with endoscopic platform integration capabilities over standalone laser component vendors. Monitor reimbursement determinations for prostate artery embolization as signal for interventional radiology capture versus surgical modality retention.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates market access for Class IIb laser devices ahead of notified body bottlenecks. |
| Hospital System Partnership | Bundled payment negotiations with United States urology chains secure preferred vendor status for outpatient migration. |
| Software Companion Development | Real-time pressure-flow urodynamics integration differentiates laser ablation platforms from commodity energy sources. |
| Reimbursement Strategy | CMS coverage expansion for ambulatory surgery centers pulls case volume from inpatient settings toward freestanding facilities. |
| Reusable Fiber Technology | EU Green Deal circular economy requirements favor service-based revenue models over single-use disposable alternatives. |
Research Methodology
Initial hypotheses were tested against primary input from urology practice administrators, hospital purchasing committee members, biomedical equipment specialists, and GPO contracts managers and refined through secondary validation against FDA 510(k) clearance databases, EU MDR notified body certification records, CMS Medicare reimbursement determinations, and hospital procurement transaction data. Bottom-up procedure volume estimates triangulated with top-down pharmaceutical prescription analytics across the analysis window.
Variance-decomposition across therapy area, procedure type, care setting, and regional regulatory cluster dimensions structured the analytical framework. CAGRs derived from segmented volume projections and pricing trajectory assumptions. Forecast inputs incorporated laser platform installation base expansion rates, generic substitution timelines for alpha blocker formulations, and outpatient migration velocity by geography.
Decision-makers should treat outputs as directional under assumptions of stable Medicare reimbursement policy and EU MDR implementation timelines; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in CMS coverage determinations and notified body capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Genitourinary Cancers Treatment Market
Urology
India Urology Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
Uraemia Treatment Market
Urology
Urethral Stricture Market
Urology
Urology Laser Fibers Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Global Urinary Tract Infections Therapeutics Market
Urology
Catheter-Associated Urinary Tract Infections Treatment Market
Urology
Self-Intermittent Catheters Market
Urology
Nephrology and Urology Incontinence Devices Market
Urology
Asia-Pacific Bladder Disorders Market
Urology
Cystectomy Market
Urology
Global Castrate Resistant Prostate Cancer Market