
 Transrectal Ultrasound Market | 2026-2036
Transrectal Ultrasound Market Size, Share, and Industry Trends Forecast 2026-2036
Transrectal Ultrasound Market Analysis
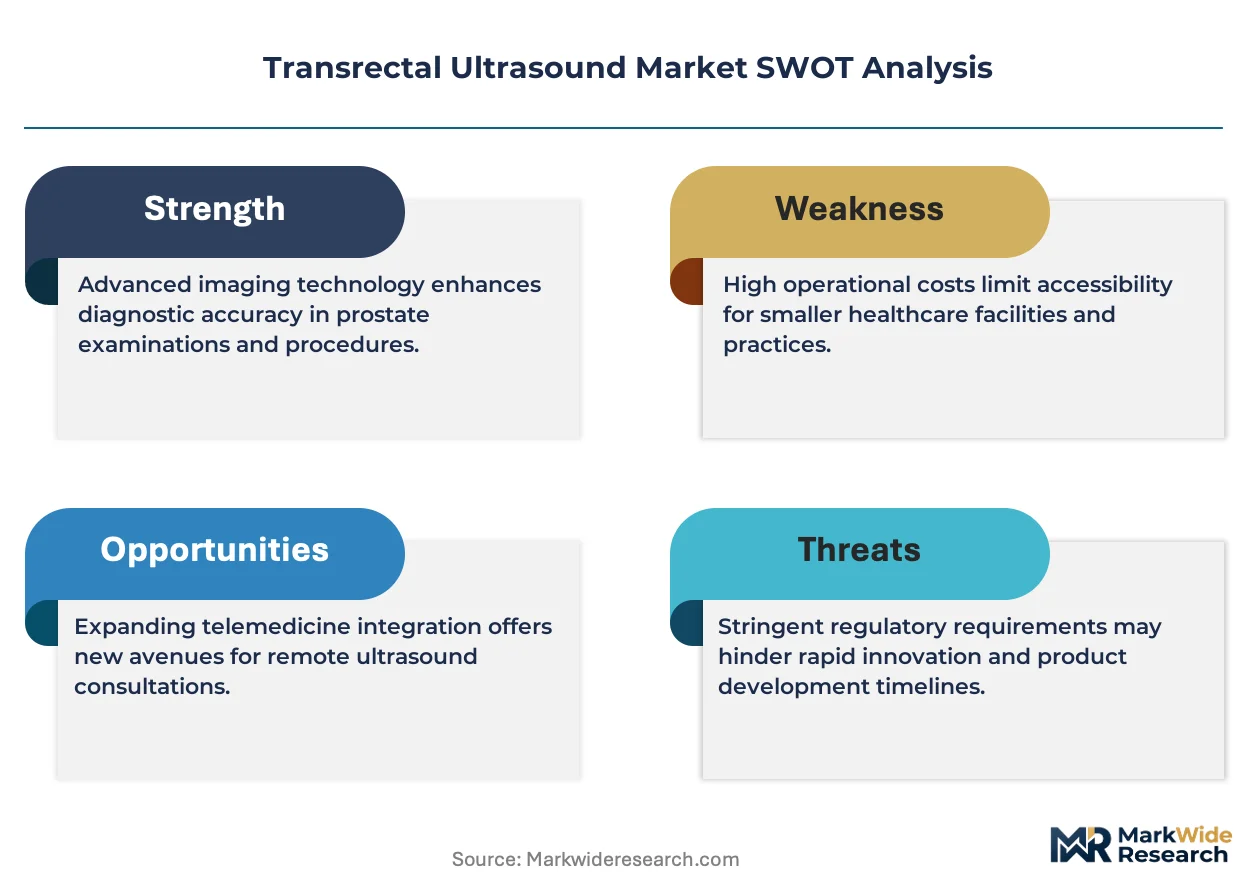
The EU Medical Device Regulation is restructuring procurement criteria across European urology practices, compelling manufacturers to demonstrate enhanced clinical validation. GE Healthcare leverages its installed base of imaging platforms to sustain service revenue streams. Koninklijke Philips N.V. anchors its position through integrated diagnostic workflows. KOELIS differentiates via robotic biopsy guidance systems that merge ultrasound with MR data.
Transrectal ultrasound deploys high-frequency sound waves through a probe inserted into the rectum to generate real-time images of the prostate gland, typically operating at 5–10 MHz for optimal tissue resolution. The modality serves primarily for prostate cancer detection, biopsy targeting, and treatment monitoring in clinical urology. 3D ultrasound captures expanding share as clinicians demand volumetric reconstruction for lesion characterization, while elastography remains nascent with concentrated uptake in academic medical centers. Doppler ultrasound maintains stable utilization for vascular assessment during active surveillance protocols.
FDA 510(k) pathways govern device clearance in the United States, while the EU MDR imposes stricter post-market surveillance and clinical evidence requirements for prostate imaging systems. Japan's PMDA maintains distinct technical standards for harmonic imaging capabilities that influence product configurations. Stakeholders must monitor evolving reimbursement codes for fusion biopsy procedures and AI-assisted detection across these jurisdictions.
Market Dynamics
AI-enhanced imaging algorithms are restructuring product development priorities across prostate diagnostic platforms, compelling manufacturers to reallocate R&D budgets toward software validation pathways.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:Accelerated clearance timelines for software-as-medical-device submissions are shortening commercialization cycles for AI-integrated ultrasound systems.
- 3D Volumetric Reconstruction:Academic medical centers in Germany and Japan are expanding adoption of volumetric biopsy targeting to improve Gleason score prediction accuracy.
- Active Surveillance Protocols:Urology departments in the United States are doubling monitoring frequency for low-risk prostate cancer patients, sustaining device utilization rates.
Market Restraints
- EU MDR Compliance Burden:Stricter post-market surveillance requirements for prostate imaging systems are extending certification timelines and inflating clinical evidence costs.
- Semiconductor Component Concentration:High-frequency transducer manufacturing depends on specialized piezoelectric materials sourced from concentrated Asian supply bases.
- Magnetic Resonance Substitution:Multiparametric MRI is capturing biopsy-naïve patient referrals in tertiary care settings, compressing addressable volume for standalone ultrasound.
Strategic Opportunities
- Japan PMDA Harmonization:Alignment of technical standards for harmonic imaging capabilities is enabling single-platform configurations across North American and Japanese markets.
- Point-of-Care Integration:Ambulatory urology clinics are demanding compact systems with cloud-connected image archiving to reduce capital footprint.
- Fusion Biopsy Reimbursement Expansion:CMS coding updates for ultrasound-MR fusion procedures are creating financial incentives for dual-modality platform investments.
Industry Challenges
- Sonographer Specialization Gap:Prostate elastography interpretation requires advanced training that outpaces current fellowship program output in community hospital settings.
- Legacy PACS Integration:DICOM conformance testing for AI-annotated image overlays is prolonging deployment timelines in hospital networks with heterogeneous IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transrectal Ultrasound Market |
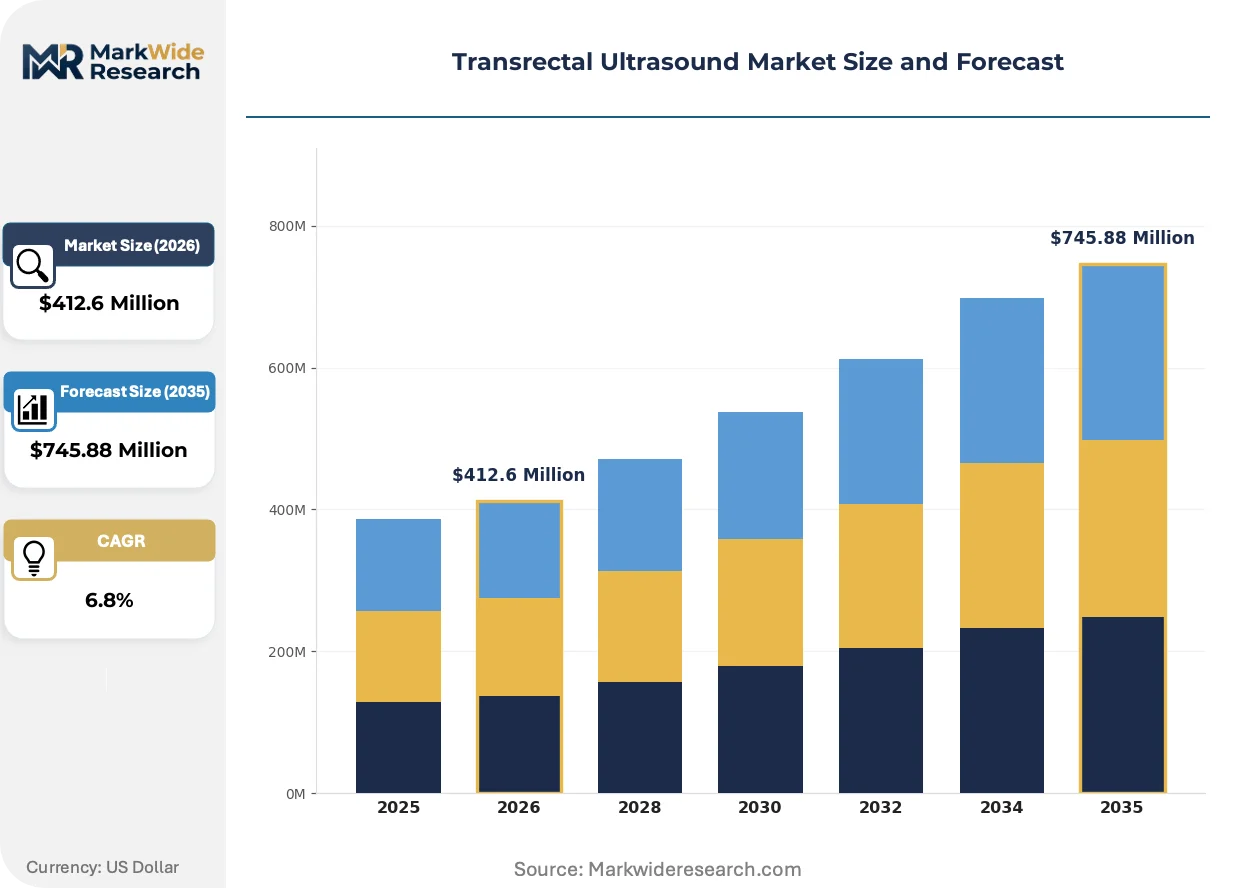
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Ultrasound, 3D Ultrasound, Doppler Ultrasound, Elastography End User: Hospitals, Clinics, Research Institutions, Diagnostic Centers Technology: Analog, Digital, Software-Enhanced, Hybrid Application: Prostate Cancer Diagnosis, Biopsy Guidance, Fertility Assessment, Others |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., KOELIS, FUJIFILM Corporation, Exact Imaging, Siemens Healthineers AG, BK Medical, Telemed Medical Systems, Mindray Medical International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transrectal Ultrasound Market Emerging Trajectories
Real-time tissue characterization capabilities are displacing static imaging workflows across prostate diagnostic pathways, with software-defined functionality overtaking hardware-centric platform differentiation.
Shear wave elastography is decentralizing lesion stiffness assessment from centralized radiology departments into urology procedure suites. Community-based practices in Texas and Florida are adopting compact elastography modules to retain biopsy referrals locally. This capability compression is reducing dependency on tertiary center consultations for indeterminate cases.
The EU MDR's clinical evidence requirements for Class IIa imaging devices are forcing manufacturers to sponsor prospective validation studies across multiple member states. German notified bodies are applying heightened scrutiny to AI algorithm training datasets. Smaller OEMs are withdrawing legacy SKUs rather than absorbing retrospective clinical trial costs.
Hospital procurement committees are bundling transrectal ultrasound with MR fusion systems under single-vendor enterprise contracts. Integrated diagnostic workflows are displacing standalone device purchasing in the United States and Germany. Academic medical centers in Japan are piloting subscription-based software licensing to reduce capital expenditure volatility.
Transrectal Ultrasound Market Segmentation
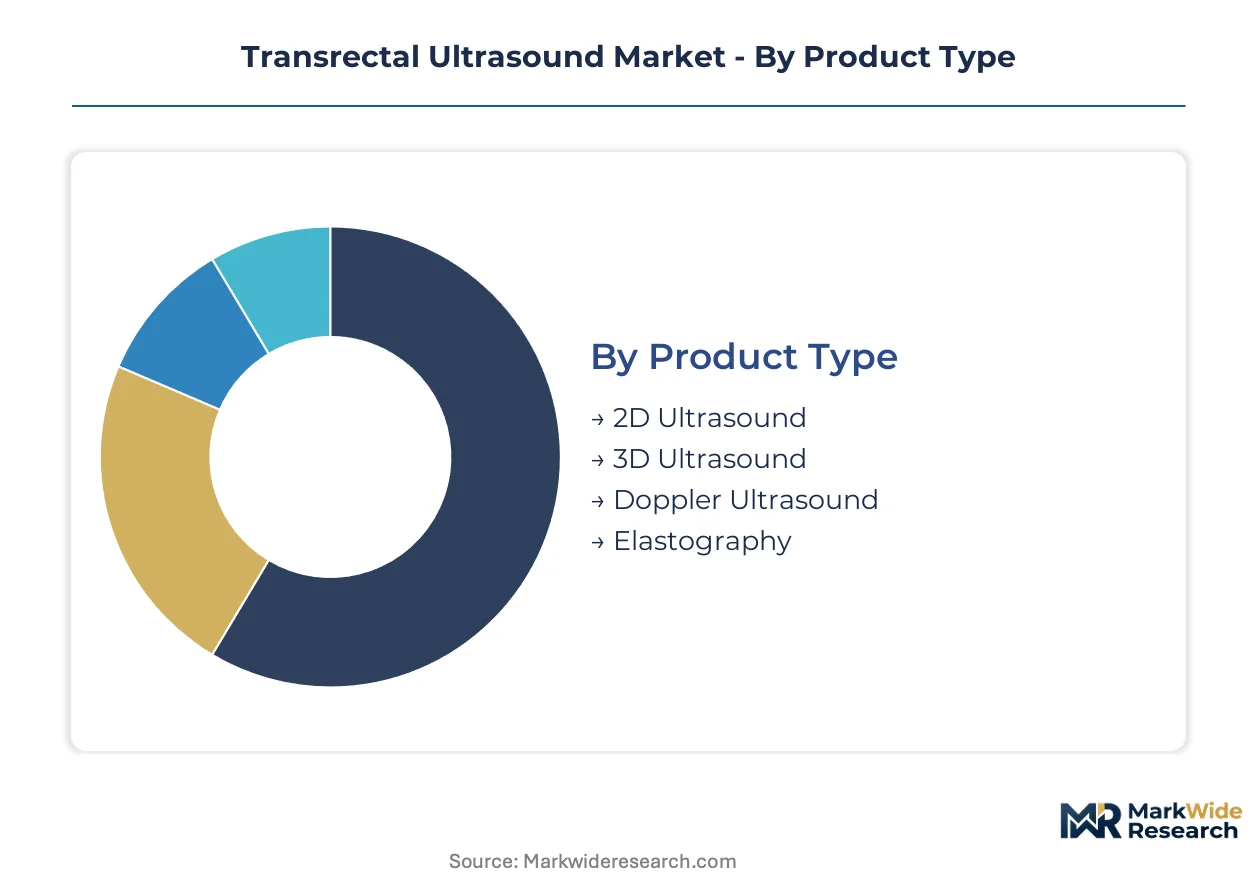
Segmentation reveals how prostate imaging demand fragments across technical specifications, clinical settings, and diagnostic workflows. Manufacturers configure platform architectures differently for academic medical centers versus ambulatory clinics. Procurement patterns vary sharply between institutions prioritizing volumetric reconstruction capabilities and those optimizing for point-of-care accessibility.
Product Type:
Technical specifications define platform differentiation in prostate ultrasound, with frequency range and reconstruction algorithms determining clinical utility across urology departments.
- 2D Ultrasound:Conventional B-mode imaging operates at 5–10 MHz through end-fire or side-fire probe configurations. Community hospitals in the United States deploy these systems for routine screening protocols where capital constraints limit equipment refresh cycles.
- 3D Ultrasound:Volumetric acquisition enables multiplanar reconstruction and precise lesion localization for targeted biopsy. Academic medical centers in Germany and Japan are expanding adoption to improve Gleason score prediction accuracy through spatial mapping of suspicious regions.
- Doppler Ultrasound:Vascular flow assessment supports active surveillance monitoring by tracking neovascularization patterns in indeterminate lesions.
- Elastography:Tissue stiffness quantification remains concentrated in tertiary referral centers with specialized sonographer training programs.
2D ultrasound leads on scale; 3D ultrasound leads on momentum.
End User:
Procurement authority and reimbursement pathways shape demand concentration across institutional categories with diverging capital allocation timelines.
- Hospitals:Integrated health systems command enterprise purchasing leverage for bundled imaging platforms. Urology departments in United States hospital networks are doubling monitoring frequency for low-risk prostate cancer patients under active surveillance protocols.
- Clinics:Ambulatory urology practices prioritize compact footprints and cloud-connected archiving to reduce infrastructure overhead. Texas and Florida community practices are adopting elastography modules to retain biopsy referrals locally rather than transferring to tertiary centers.
- Research Institutions:Prospective validation studies for AI algorithms and novel biomarkers drive demand for research-grade systems with open architecture.
- Diagnostic Centers:Independent imaging facilities focus on throughput optimization and rapid report turnaround for referring urologists.
Hospitals dominate procurement volume; clinics are expanding most quickly as point-of-care capabilities compress referral patterns.
Technology:
Signal processing architecture determines image quality, workflow integration, and regulatory pathway complexity for prostate imaging systems.
- Analog:Legacy beamforming architectures persist in installed bases where replacement cycles extend beyond typical depreciation schedules.
- Digital:Fully digital signal chains enable software-defined functionality upgrades without hardware replacement. FDA 510(k) pathway streamlining for software-as-medical-device submissions is shortening commercialization cycles for digital platforms.
- Software-Enhanced:AI-integrated detection and measurement tools require extensive validation datasets. EU MDR clinical evidence requirements for Class IIa devices are forcing manufacturers to sponsor prospective studies across multiple member states.
- Hybrid:Combined analog-digital architectures balance cost and performance for mid-tier installations in regional medical centers.
Digital platforms command the largest installed base; software-enhanced systems show the steepest expansion trajectory as AI validation matures.
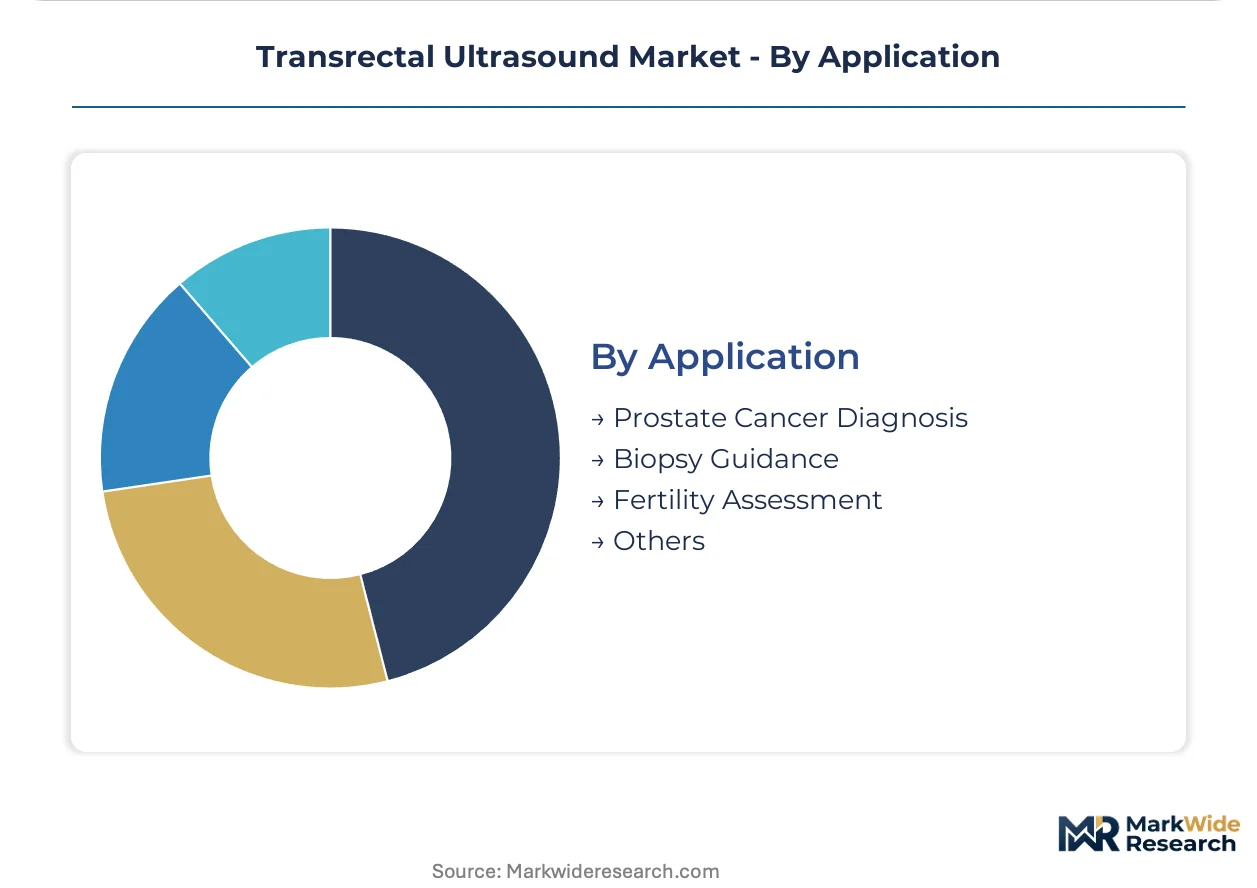
Application:
Clinical indication determines probe configuration, workflow design, and reimbursement coding for prostate ultrasound utilization.
- Prostate Cancer Diagnosis:Initial detection protocols drive the highest examination volumes. Screening programs in Japan leverage harmonic imaging capabilities with distinct PMDA technical standards influencing product configurations.
- Biopsy Guidance:Targeted tissue acquisition demands precise spatial registration. CMS coding updates for ultrasound-MR fusion procedures are creating financial incentives for dual-modality platform investments in United States facilities.
- Fertility Assessment:Seminal vesicle and ejaculatory duct evaluation supports male infertility workups in specialized andrology practices.
- Others:Post-treatment monitoring and benign prostatic hyperplasia assessment round out utilization patterns.
Prostate cancer diagnosis generates the highest procedure volume; biopsy guidance is gaining share fastest as fusion techniques standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transrectal ultrasound technology first achieved clinical scale in the United States during the 1980s, with academic medical centers in Baltimore and Houston pioneering systematic prostate biopsy protocols. The modality subsequently diffused through German urology departments and Japanese screening programs, establishing the tripartite geographic foundation that persists today.
United States
Academic medical centers in Texas and Florida are expanding active surveillance protocols for low-risk prostate cancer patients. FDA 510(k) pathway streamlining for software-as-medical-device submissions is accelerating commercialization timelines for AI-integrated platforms. The Greater Boston cluster anchors validation studies for elastography algorithms.
Germany
University hospitals in Munich and Heidelberg are driving adoption of volumetric biopsy targeting to improve Gleason score prediction accuracy. EU MDR notified bodies are applying heightened scrutiny to AI algorithm training datasets for Class IIa imaging devices. The Baden-Württemberg medical technology corridor concentrates notified body expertise.
Japan
Screening programs in Tokyo and Osaka leverage harmonic imaging capabilities with distinct PMDA technical standards influencing product configurations. METI harmonization initiatives are enabling single-platform configurations across North American and Japanese markets. The Kansai region hosts specialized sonographer training programs for elastography interpretation.
United Kingdom
NHS procurement frameworks are bundling transrectal ultrasound with MR fusion systems under single-vendor enterprise contracts. MHRA post-Brexit regulatory pathways are diverging from EU MDR timelines for prostate imaging systems. The Oxford-Cambridge arc pilots subscription-based software licensing to reduce capital expenditure volatility.
China
Tertiary hospitals in Shanghai and Beijing are expanding multiparametric MRI capacity, compressing addressable volume for standalone ultrasound in biopsy-naïve referrals. NMPA technical standards for high-frequency transducers are influencing domestic manufacturing investments. The Yangtze River Delta concentrates piezoelectric material supply relationships.
Transrectal Ultrasound Market Vendor Landscape
Capital-heavy imaging conglomerates compete with asset-light software specialists across the transrectal ultrasound value chain. The vendor base stratifies between integrated diagnostic platform providers and modular biopsy guidance innovators. Three archetypes dominate: full-stack imaging OEMs sustaining service revenue through installed base leverage; robotic fusion specialists merging ultrasound with MR data; and compact point-of-care developers targeting ambulatory clinic expansion. Dominant competitive moves include enterprise contract bundling and AI validation pathway acceleration.
Among full-stack imaging OEMs, GE Healthcare and Koninklijke Philips N.V. occupy positions defined by installed base scale and integrated workflow architecture. KOELIS represents the robotic fusion specialist archetype, with its corporate structure reflecting concentrated R&D allocation toward software-hardware integration. These three entities exemplify the competitive tension between platform breadth and targeted application depth that characterizes procurement negotiations in academic medical centers.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| KOELIS |
| FUJIFILM Corporation |
| Exact Imaging |
| Siemens Healthineers AG |
| BK Medical |
| Telemed Medical Systems |
| Mindray Medical International Limited |
| Others |
Supply Flow & Price Mechanics
EU MDR-mandated clinical evidence requirements for Class IIa imaging devices are forcing manufacturers to absorb retrospective validation costs, compressing margins on legacy platforms and shifting procurement toward bundled enterprise contracts that amortize compliance overhead across larger installed bases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transrectal ultrasound procurement, with premium tiers commanding 40-60% markups for AI-integrated detection modules and robotic biopsy guidance capabilities. Price differentiation rests on FDA 510(k) clearance status and EU MDR certification tier, with academic medical centers in Germany and Japan showing lowest price sensitivity for research-grade systems. Pricing pressure stems from multiparametric MRI substitution in tertiary care settings, compressing standalone ultrasound margins. Community hospitals in the United States exhibit highest price sensitivity, driving demand for refurbished digital platforms and extended service contracts.
Supply Chain Analysis
Freight costs for high-frequency transducer assemblies have risen substantially as specialized piezoelectric materials draw from concentrated Asian supply bases in China, Japan, and South Korea. Raw material dependencies center on lead zirconate titanate ceramics, precision-machined probe housings, and application-specific integrated circuits for beamforming. Single-source vulnerability in harmonic imaging component sourcing creates exposure to Japan METI export licensing delays. Distribution runs through direct sales forces for hospital systems and specialized medical device distributors for ambulatory clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The transrectal ultrasound market functions as a stable compounder, with active surveillance protocol expansion in prostate cancer management sustaining replacement cycles and software upgrade revenue streams across mature installed bases.
For Market Incumbents: Deepen vertical integration into high-frequency transducer manufacturing to reduce dependency on Asian piezoelectric suppliers and defend margin position against modular biopsy guidance entrants. Prioritize CE marking pathway acceleration for AI-enhanced platforms ahead of EU MDR notified body backlogs. Consolidate service revenue through enterprise contract bundling with MR fusion systems. For New Entrants and Emerging Players: Capture point-of-care clinic expansion in Texas and Florida by offering compact elastography modules with cloud-connected archiving that eliminates PACS integration friction. Target ambulatory urology practices seeking to retain biopsy referrals locally rather than transferring to tertiary centers. Pursue subscription-based software licensing models to reduce capital expenditure barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with asset-light software specialists holding validated AI detection algorithms and FDA 510(k) clearances for prostate lesion characterization. Long-term viability favors platforms with demonstrated reimbursement traction for fusion biopsy procedures. Watch CMS coding updates for ultrasound-MR fusion as the primary inflection signal for dual-modality platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerated clearance timelines for AI-integrated detection algorithms shorten commercialization cycles in the United States. |
| CE Marking Pathway | EU MDR clinical evidence requirements for Class IIa devices force prospective validation studies across German notified bodies. |
| Hospital System Partnership | Enterprise contract bundling with MR fusion systems displaces standalone device purchasing in academic medical centers. |
| Software Companion Development | Real-time tissue characterization capabilities displace static imaging workflows across prostate diagnostic pathways. |
| Reimbursement Strategy | CMS coding updates for ultrasound-MR fusion procedures create financial incentives for dual-modality platform investments. |
Methodological Framework
Bottom-up urology department modeling reconciled against top-down imaging platform shipment tracking forms the analytical core of this study. Primary interviews with urology department heads, hospital procurement committee members, biomedical engineers, and GPO contracts managers were combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, CMS Medicare reimbursement data, and hospital procurement records. Triangulation across stakeholder perspectives and regulatory filings ensures segmentation integrity.
Input-output matrices map transducer manufacturing capacity, software development cycles, and regulatory pathway timelines against procedure volume projections across the analysis window. Segmentation dimensions include product type, end user institution category, signal processing architecture, and clinical application. CAGRs were derived from installed base refresh rates, active surveillance protocol expansion, and fusion biopsy adoption curves. Forecast inputs incorporate PMDA harmonization initiatives and EU MDR compliance cost trajectories.
Regulatory pathway delays, semiconductor supply disruptions, and multiparametric MRI substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding reimbursement stability and sonographer training program output. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Single Use Cystoscope Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Disposable Ureteroscope Market
Urology
Uraemia Treatment Market
Urology
Global Prostate Health Market
Urology
Nocturia Market
Urology
Urology Lasers Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Pyelonephritis Treatment Market
Urology
Global Bladder Scanner Market
Urology
Cystoscope Market
Urology
Urinary Retention Therapeutics Market
Urology
North America Transrectal Ultrasound Market
Urology
US Urology Devices Market
Urology
Urinary Catheters Market
Urology
North America Bladder Disorders Market