
 Global Bladder Scanner Market | 2026-2036
Global Bladder Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bladder Scanner Market Foresight
Hospital procurement for bladder scanners is fragmenting as group purchasing organizations lose leverage to specialized urology distributors and direct manufacturer contracts. Verathon sustains strong brand recognition in North American acute care settings through dedicated clinical training programs. Laborie Medical Technologies leverages its urology-focused portfolio to anchor premium positioning in European hospital networks. Mindray competes aggressively on automated measurement algorithms and cost-engineered hardware for emerging clinical markets.
A bladder scanner is a non-invasive diagnostic instrument that employs ultrasound transducers to calculate bladder volume through automated signal processing, typically operating at frequencies between 2-5 MHz for tissue penetration adequate to measure volumes from 0-999 mL. The device eliminates catheter-associated urinary tract infections by enabling post-void residual assessment without urethral instrumentation, serving urology, rehabilitation, and obstetric departments. Portable scanners dominate installed base economics due to ward-level mobility and lower capital commitment, while console scanners concentrate in dedicated urology suites where measurement precision and EMR integration justify higher equipment spend. Cloud-connected delivery modes represent the fastest-expanding configuration as health systems prioritize remote monitoring infrastructure and automated data archiving.
FDA 510(k) clearance requirements shape device validation protocols and clinical evidence thresholds for US market entry, while EU MDR technical documentation demands intensify post-market surveillance obligations for European distribution. Japan's PMDA enforces distinct electromagnetic compatibility and software lifecycle standards that extend registration timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement codes for non-invasive bladder volume assessment and anticipate harmonization pressures between FDA breakthrough device pathways and EU notified body consolidation.
Market Dynamics
Hospital catheterization reduction mandates are compressing bladder scanner procurement cycles as infection control committees gain direct capital allocation authority over traditional biomedical engineering departments. This governance shift elevates clinical outcome metrics above equipment cost in vendor selection protocols.
Growth Catalysts
- EU MDR post-market surveillance mandates:Manufacturers accelerating technical documentation investments are capturing notified body priority queue positions for 2025-2026 certificate renewals.
- Japan's aging institutional population:PMDA reimbursement alignment for point-of-care urological diagnostics sustains replacement demand across Tokyo and Osaka metropolitan hospital networks.
- Cloud-connected device architectures:Automated bladder volume data streaming into electronic medical record systems reduces nursing documentation burden by eliminating manual transcription steps.
Market Restraints
- Piezoelectric ceramic supply concentration:Ultrasound transducer manufacturing depends on Chinese rare earth processing facilities subject to export quota volatility.
- FDA 510(k) clinical evidence thresholds:Predicate device equivalence requirements extend validation timelines for algorithm-enhanced measurement systems.
- Manual palpation persistence in resource-constrained settings:Low-cost physical assessment techniques limit scanner penetration in sub-Saharan African and South Asian primary care facilities.
Strategic Opportunities
- German rehabilitation clinic networks:Post-acute care facilities managing neurogenic bladder populations represent underpenetrated demand for portable measurement systems.
- Home health monitoring integration:Telehealth reimbursement codes for remote urological assessment create channel expansion potential beyond institutional procurement.
- ISO 13485:2016 quality management harmonization:Unified audit standards reduce duplicate certification costs for multi-regional manufacturers seeking FDA and EU MDR parallel approvals.
Industry Challenges
- Ultrasound physicist staffing scarcity:Specialized clinical engineering expertise for device calibration and training program deployment concentrates in tertiary academic medical centers.
- Legacy EMR interoperability gaps:Proprietary data formats from installed base scanners require middleware investments for health system-wide analytics integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bladder Scanner Market |
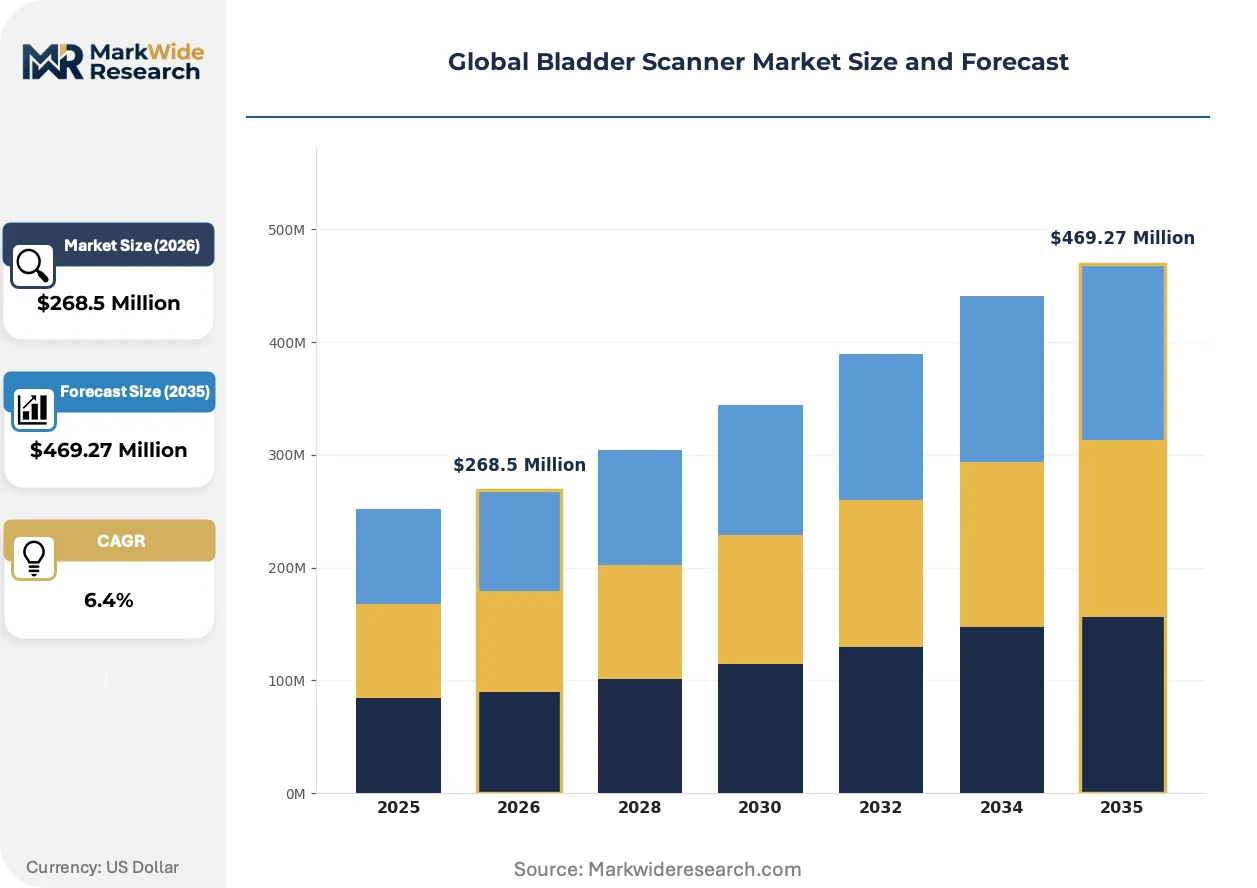
| Market Size in 2026 | $268.5 Million |
| Market Size in 2035 | $469.27 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Scanners, Console Scanners, Handheld Devices, Fixed Systems Technology: Ultrasound, Electromagnetic, Laser, Infrared End User: Hospitals, Clinics, Home Care, Urgent Care Centers Delivery Mode: Manual, Automated, Cloud-Connected, Software Solutions |
| Companies Covered | Laborie Medical Technologies, Vitacon, Verathon, Infinium Medical, Caresono Technology, GE Healthcare, Mindray, Siemens Healthineers, Philips Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bladder Scanner Market Shifts & Advancements
Artificial intelligence inference at the edge is compressing measurement cycle times while reducing operator dependency in high-turnover clinical environments. Three convergent developments are restructuring competitive positioning and procurement criteria.
Deep learning algorithms trained on multi-center bladder volume datasets are rendering obsolete manual probe positioning techniques that required extensive sonographer training. Rehabilitation departments and obstetric wards with rotating nursing staff are adopting these automated systems fastest. Equipment vendors without embedded AI capabilities face displacement in North American group purchasing organization contract renewals.
EU MDR technical documentation demands intensify post-market surveillance obligations for European distribution, compelling manufacturers to restructure quality management systems around risk-classification matrices. This regulatory friction disproportionately burdens mid-tier device producers lacking dedicated regulatory affairs infrastructure. German and French notified bodies are extending review timelines for software-as-medical-device components, forcing portfolio prioritization toward hardware-centric submissions.
Specialized urology distributors are displacing broadline medical device group purchasing organizations in contract negotiation leverage. Hospital infection control committees now source bladder scanners through direct manufacturer relationships that bundle clinical training with equipment procurement. This channel restructuring is most visible in United States acute care networks where catheter-associated urinary tract infection penalties have elevated urological diagnostic capital to strategic priority status.
Global Bladder Scanner Market Segmentation
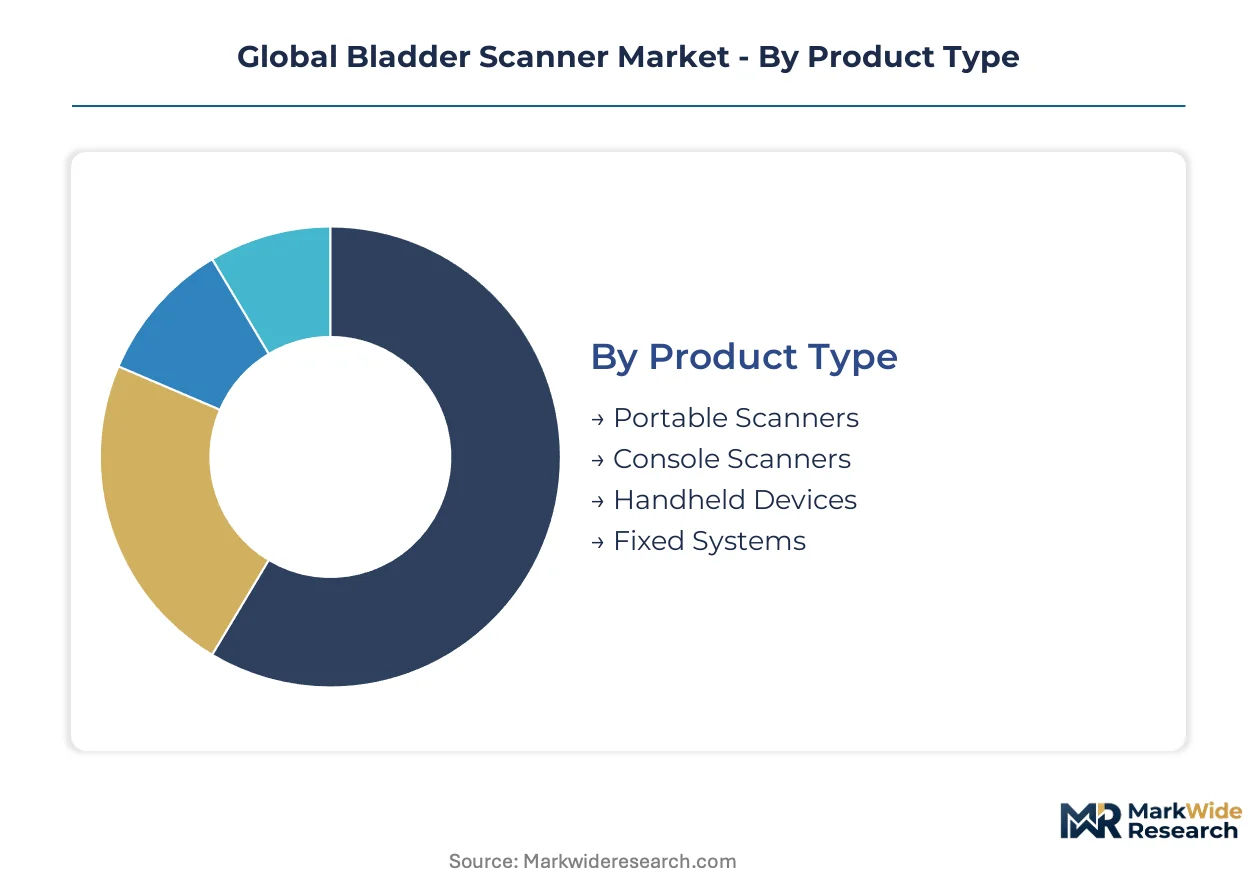
Bladder scanner procurement patterns diverge sharply across clinical settings and technical configurations. Product architecture, measurement modality, and connectivity infrastructure each create distinct competitive battlegrounds with separate margin profiles and vendor qualification criteria.
Product Type:
Cost tier stratification determines capital commitment thresholds and replacement cycles across acute and post-acute care environments.
- Portable Scanners:Battery-powered units weighing under 2.5 kg deploy 2-5 MHz phased array transducers for ward-level mobility. German rehabilitation clinics and Japanese long-term care facilities prioritize these systems for neurogenic bladder monitoring where equipment transport between patient rooms dominates workflow efficiency.
- Console Scanners:Cart-mounted platforms integrate high-resolution displays and automated probe calibration for dedicated urology suites. United States academic medical centers concentrate procurement here, driven by EMR integration requirements and measurement precision demands for surgical planning.
- Handheld Devices:Smartphone-connected probes reduce per-unit cost below institutional procurement floors.
- Fixed Systems:Wall-mounted installations serve high-throughput emergency departments with dedicated catheterization reduction protocols.
Console scanners hold installed capacity. Portable scanners are rotating up the share rankings.
Technology:
Measurement modality selection reflects tissue penetration requirements, operator training availability, and electromagnetic compatibility constraints in multi-device clinical environments.
- Ultrasound:Piezoelectric transducers operating at 2-5 MHz calculate bladder volume through automated signal processing algorithms. This modality dominates hospital procurement across the United States, Germany, and Japan due to established reimbursement codes for non-invasive post-void residual assessment and extensive clinical validation literature.
- Electromagnetic:Coil-based detection systems measure bladder bioimpedance without acoustic coupling gel, reducing consumable costs and cleaning protocols. Demand concentrates in United States Veterans Health Administration facilities and United Kingdom National Health Service trusts where infection control standardization outweighs absolute measurement precision.
- Laser:Optical triangulation methods remain experimental for urological applications with limited regulatory clearance pathways.
- Infrared:Thermal detection approaches lack sufficient clinical evidence for institutional procurement committees.
Ultrasound technology anchors current procurement volumes. Electromagnetic systems are gaining share fastest in cost-constrained health systems.
End User:
Customer type segmentation reveals divergent purchasing authority structures, from infection control committee capital allocation to patient-directed retail acquisition.
- Hospitals:Acute care networks with catheter-associated urinary tract infection penalty exposure drive premium equipment procurement. United States hospital systems bundle bladder scanners into comprehensive urological diagnostic contracts that include clinical training and preventive maintenance.
- Clinics:Outpatient urology practices and rehabilitation centers prioritize portable systems with rapid measurement cycles for high patient throughput. German post-acute care networks represent underpenetrated demand for automated volume assessment in neurogenic bladder populations.
- Home Care:Direct-to-patient sales channels expand as telehealth reimbursement codes mature for remote urological monitoring.
- Urgent Care Centers:Rapid diagnostic protocols for urinary retention drive demand for intuitive operator interfaces with minimal training requirements.
Hospitals retain procurement volume leadership. Home care channels are climbing the fastest as reimbursement frameworks adapt to remote monitoring infrastructure.
Delivery Mode:
Connectivity architecture determines data integration depth, nursing documentation burden, and cybersecurity compliance obligations for networked medical devices.
- Cloud-Connected:Automated bladder volume data streams into electronic medical record systems through HL7 FHIR interfaces, eliminating manual transcription and enabling predictive analytics for catheterization timing. United States health systems with mature digital infrastructure prioritize these configurations for nursing efficiency gains.
- Automated:Edge-based AI inference compresses measurement cycle times while reducing operator dependency in high-turnover clinical environments. Japanese metropolitan hospital networks adopt these systems fastest where sonographer staffing scarcity constrains traditional ultrasound deployment.
- Manual:Standalone devices without network connectivity persist in resource-constrained settings and backup redundancy roles.
- Software Solutions:Algorithm licensing for third-party hardware integration represents emerging commercial models for AI-enabled measurement vendors.
Manual delivery modes hold legacy installed base. Cloud-connected architectures are expanding most quickly as health systems prioritize remote monitoring infrastructure and automated data archiving.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's medical device logistics corridor underwrites Germany's distribution dominance for bladder scanner equipment across Central European hospital networks.
United States
Catheter-associated urinary tract infection penalties drive acute care procurement at scale. FDA 510(k) clearance pathways compress product validation timelines for algorithm-enhanced systems. The Boston-Cambridge medical technology cluster concentrates regulatory affairs expertise and clinical trial infrastructure for market entrants.
Germany
Post-acute rehabilitation networks generate sustained demand for portable neurogenic bladder monitoring. EU MDR technical documentation mandates accelerate notified body queue competition among manufacturers. The Rhine-Ruhr metropolitan hospital system anchors procurement volume for console-based urology suite installations.
Japan
Aging institutional populations in Tokyo and Osaka sustain replacement cycles for point-of-care diagnostics. PMDA electromagnetic compatibility standards extend registration timelines for foreign device manufacturers. The Nagoya medical device manufacturing corridor supplies precision transducer components to domestic and regional OEMs.
China
Hospital infrastructure expansion in tier-2 cities creates procurement pull for cost-engineered portable systems. NMPA Class II medical device registration reforms streamline market entry for ultrasound-based diagnostics. The Yangtze River Delta medical equipment cluster concentrates final assembly capacity and domestic supply chain integration.
United Kingdom
National Health Service infection control standardization elevates non-invasive diagnostic priority in trust procurement frameworks. MHRA post-Brexit regulatory autonomy diverges from EU MDR timelines for certain software-as-medical-device classifications. The Oxford-Cambridge healthcare innovation arc hosts clinical validation partnerships for emerging measurement technologies.
Global Bladder Scanner Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Premium positioning depends on clinical training bundling and EMR integration depth. Mid-tier competition centers on automated measurement algorithms and cost-engineered hardware configurations. Value-tier pressure concentrates in emerging markets with price-sensitive procurement committees. Dominant competitive moves include direct hospital contracting bypassing traditional distributors and AI-enabled feature differentiation in contract renewals.
Within the premium-tier vector, Verathon and Laborie Medical Technologies exemplify positioning through dedicated clinical education infrastructure and urology-focused portfolio depth. Mindray occupies a scale-driven position competing on automated measurement algorithms and hardware cost engineering for high-volume procurement channels. Siemens Healthineers and GE Healthcare anchor diversified medical technology conglomerates where bladder scanners represent modular components within comprehensive diagnostic imaging contracts.
| Leading Market Players |
|---|
| Laborie Medical Technologies |
| Vitacon |
| Verathon |
| Infinium Medical |
| Caresono Technology |
| GE Healthcare |
| Mindray |
| Siemens Healthineers |
| Philips Healthcare |
| Others |
Supply & Pricing Matrix
Rare earth processing concentration in Chinese Jiangxi and Inner Mongolia provinces feeds directly into transducer cost structures, concentrating margin capture upstream while downstream OEMs compete on algorithm differentiation and clinical training bundling. Piezoelectric ceramic supply tightness propagates through contract renegotiation cycles, forcing hardware manufacturers to absorb input volatility or push pricing adjustments through GPO contract renewals.
Pricing Analysis
Volume-discount tiering structures separate console-based urology suite installations from portable ward-level units and handheld smartphone-connected probes. Premium console scanners command pricing power through EMR integration depth and dedicated clinical education programs, while portable segments face cost compression from Mindray's automated measurement algorithms and hardware cost engineering. Japanese and German hospital networks exhibit lowest price sensitivity due to PMDA and EU MDR compliance investments that elevate total cost of ownership considerations above per-unit acquisition cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Taiwanese and Chinese EMS providers holding final assembly capacity for ultrasound transducer modules and handheld probe housings. Precision transducer components draw from Nagoya-based Japanese suppliers and Yangtze River Delta domestic Chinese manufacturers, with rare earth magnet sourcing anchored in Jiangxi processing facilities. Single-source vulnerability concentrates in piezoelectric ceramic supply, where export quota volatility from Chinese state planners creates inventory planning uncertainty. Distribution runs through specialized urology distributors displacing broadline GPOs in United States acute care networks, while European hospital procurement flows through Hamburg's medical device logistics corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach economics now exceed hardware growth trajectories as cloud-connected device architectures expand recurring revenue from automated data streaming, remote calibration, and predictive maintenance contracts. Clinical training program subscriptions and EMR integration middleware represent the fastest-expanding margin pools for vendors with installed base scale.
For Market Incumbents: Harden defensive positioning through captive control over piezoelectric ceramic supply chains via long-term offtake agreements with Chinese rare earth processors. Deepen algorithm moats by embedding edge-based AI inference that compresses measurement cycle times below what emerging competitors can replicate without multi-center clinical validation datasets. Prioritize direct hospital contracting relationships that bundle preventive maintenance with capital equipment procurement, neutralizing specialized urology distributor leverage in United States acute care networks. For New Entrants and Emerging Players: Build out telehealth reimbursement infrastructure for home health monitoring channels where regulatory frameworks remain unsettled and incumbent clinical training bundling offers weaker protection. German rehabilitation clinic networks managing neurogenic bladder populations represent the most penetrable white-space target, with post-acute care facilities underserved by console-centric incumbent portfolios. Pursue ISO 13485:2016 quality management harmonization early to reduce duplicate certification costs for parallel FDA and EU MDR approval pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier device producers lacking dedicated regulatory affairs infrastructure to absorb EU MDR technical documentation demands and software-as-medical-device component review timeline extensions. Five-to-ten year viability hinges on cloud-connected device architecture penetration rates and the shift from transactional equipment sales toward recurring service revenue models. Monitor FDA 510(k) clinical evidence threshold evolution for algorithm-enhanced measurement systems as the critical inflection signal for competitive displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation investments capture notified body priority queue positions for certificate renewals. |
| Hospital System Partnership | Direct contracting with infection control committees elevates clinical outcome metrics above equipment cost in vendor selection. |
| Software Companion Development | Cloud-connected architectures with HL7 FHIR interfaces eliminate nursing documentation burden through automated EMR streaming. |
| Reimbursement Strategy | Telehealth code alignment for remote urological assessment expands channel potential beyond institutional procurement. |
| Backward Integration | Captive supply of piezoelectric ceramics insulates margin from Chinese rare earth export quota volatility. |
Research Methodology
A spread of perspectives from hospital infection control committee chairs, biomedical engineering directors, urology department heads, GPO contracts managers, and regulatory affairs specialists converged on the working assumptions underlying demand forecasts. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR notified body submission records, PMDA registration filings, hospital procurement contract repositories, and CMS reimbursement code updates. Bottom-up installed base estimates and top-down healthcare capital expenditure projections were triangulated to anchor volume assumptions.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation modeled by product architecture, measurement modality, connectivity infrastructure, and clinical setting procurement authority. CAGRs were derived from regression analysis of historical replacement cycles, aging demographic trajectories, and regulatory compliance timeline compression effects. Forecast inputs incorporated catheter-associated urinary tract infection penalty exposure curves, cloud-connected device adoption rates, and AI-enabled measurement algorithm validation timelines.
Sensitivities concentrate around FDA 510(k) predicate device equivalence requirement evolution, EU MDR software-as-medical-device classification interpretation, and Chinese rare earth export policy shifts. Forecasts reflect documented assumptions regarding reimbursement code stability and health system digital infrastructure maturity. Quarterly review of notified body queue positions, PMDA electromagnetic compatibility standard updates, and telehealth reimbursement code expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Urology Forceps Market
Urology
Single Use Cystoscope Market
Urology
Urology Robotic Surgery Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
Urology Lasers Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
Urinary Incontinence Therapeutics Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Urinary Bag Market
Urology
North America Bladder Disorders Market
Urology
Ureter Cancer Treatment Market
Urology
Benign Prostatic Hyperplasia Market
Urology
India Urology Device Market
Urology
Europe Bladder Disorders Market
Urology
Global Urinary Tract Infections Therapeutics Market