
 Dental Fluorescence Analyzer Market | 2026-2036
Dental Fluorescence Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Fluorescence Analyzer Market Outlook
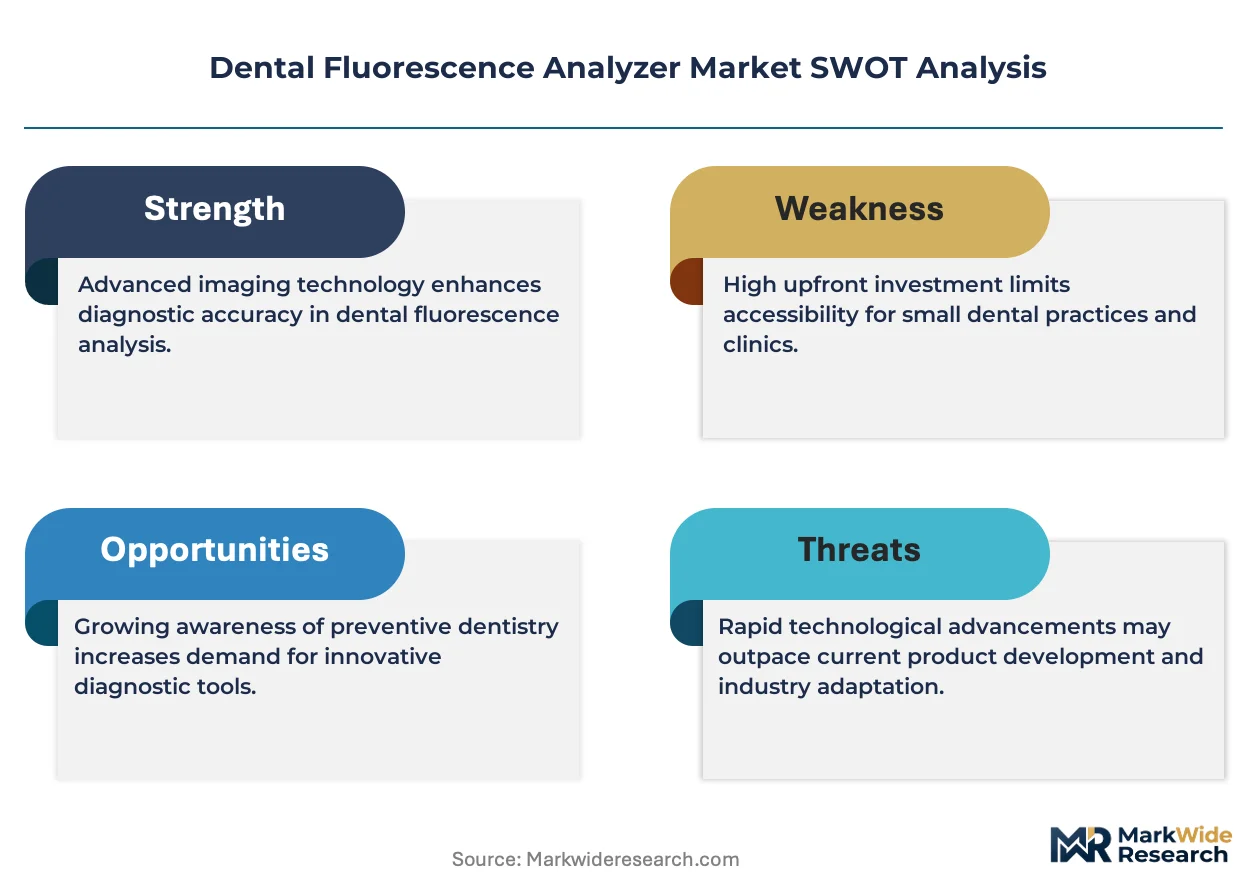
German precision optics manufacturing is rebalancing toward dental diagnostic subsystems as medical device export quotas tighten. Olympus Corporation leverages its heritage in fluorescence microscopy to anchor premium benchtop analyzer lines. Thermo Fisher Scientific competes through spectroscopy module standardization that sustains cross-platform compatibility. Bruker Corporation specializes in laser-induced fluorescence architectures that dominate research laboratory procurement cycles.
A dental fluorescence analyzer detects demineralization and bacterial metabolic byproducts through excitation-emission wavelength mapping, typically operating at 405–450 nm excitation with real-time spectral readout for enamel and soft-tissue assessment. Handheld devices command the widest installed base among dental clinics seeking immediate chairside screening, while portable systems represent the fastest-expanding segment as mobile dentistry programs proliferate. Spectroscopy technology leads revenue contribution due to its quantitative output reliability, though laser-induced fluorescence differentiates in early caries sensitivity where optical imaging remains cost-constrained.
FDA 510(k) clearance pathways and PMDA quality management system audits shape device commercialization timelines and clinical claim substantiation requirements. ISO 13485 certification and IEC 60601 electrical safety standards further govern manufacturing scale-up and market access for new entrants. Stakeholders must monitor evolving MDR technical documentation requirements in Europe and alignment with dual carbon goals affecting semiconductor laser sourcing.
Market Dynamics
Fluorescence spectroscopy miniaturization is compressing device form factors while preserving diagnostic fidelity, forcing incumbent optical subsystem suppliers to retool for portable architectures that dental clinics now specify in procurement tenders.
Growth Catalysts
- MDR technical documentation mandates:European manufacturers accelerating ISO 13485 certification upgrades to maintain CE marking access, creating replacement demand for compliant analyzer generations.
- Mobile dentistry expansion:Rural health programs in Brazil and India deploying battery-operated fluorescence screening units to bypass fixed infrastructure limitations.
- Laser diode cost curves:Semiconductor fabrication scale in East Asia reducing 405 nm excitation source pricing, enabling handheld unit margin expansion for mid-tier device vendors.
Market Restraints
- Precision optics supply concentration:German and Japanese lens foundries controlling high-NA objective manufacturing, creating single-source vulnerability for fluorescence module assemblers.
- FDA 510(k) pathway duration:Clinical claim substantiation requirements extending clearance timelines for novel wavelength configurations, delaying commercialization by 18-24 months.
- Optical imaging substitution:Low-cost intraoral cameras capturing visible-light caries indicators, pressuring fluorescence analyzer pricing in budget-sensitive clinic segments.
Strategic Opportunities
- Teledentistry integration:Cloud-connected fluorescence analyzers enabling remote specialist consultation, opening subscription revenue streams for device-software bundles.
- Preventive care reimbursement codes:Japanese Ministry of Health expanding coverage for early caries detection, incentivizing analyzer placement in general dental practices.
- AI-assisted spectral interpretation:Machine learning algorithms reducing operator training requirements, expanding addressable market to non-specialist practitioners.
Industry Challenges
- Photonics engineering talent scarcity:Cross-disciplinary expertise in fluorescence microscopy and medical device regulation commanding premium compensation, constraining R&D team scaling.
- IEC 60601-1 third edition compliance:Electrical safety testing for laser-equipped handheld units requiring specialized certification laboratory access, creating bottlenecks for market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Fluorescence Analyzer Market |
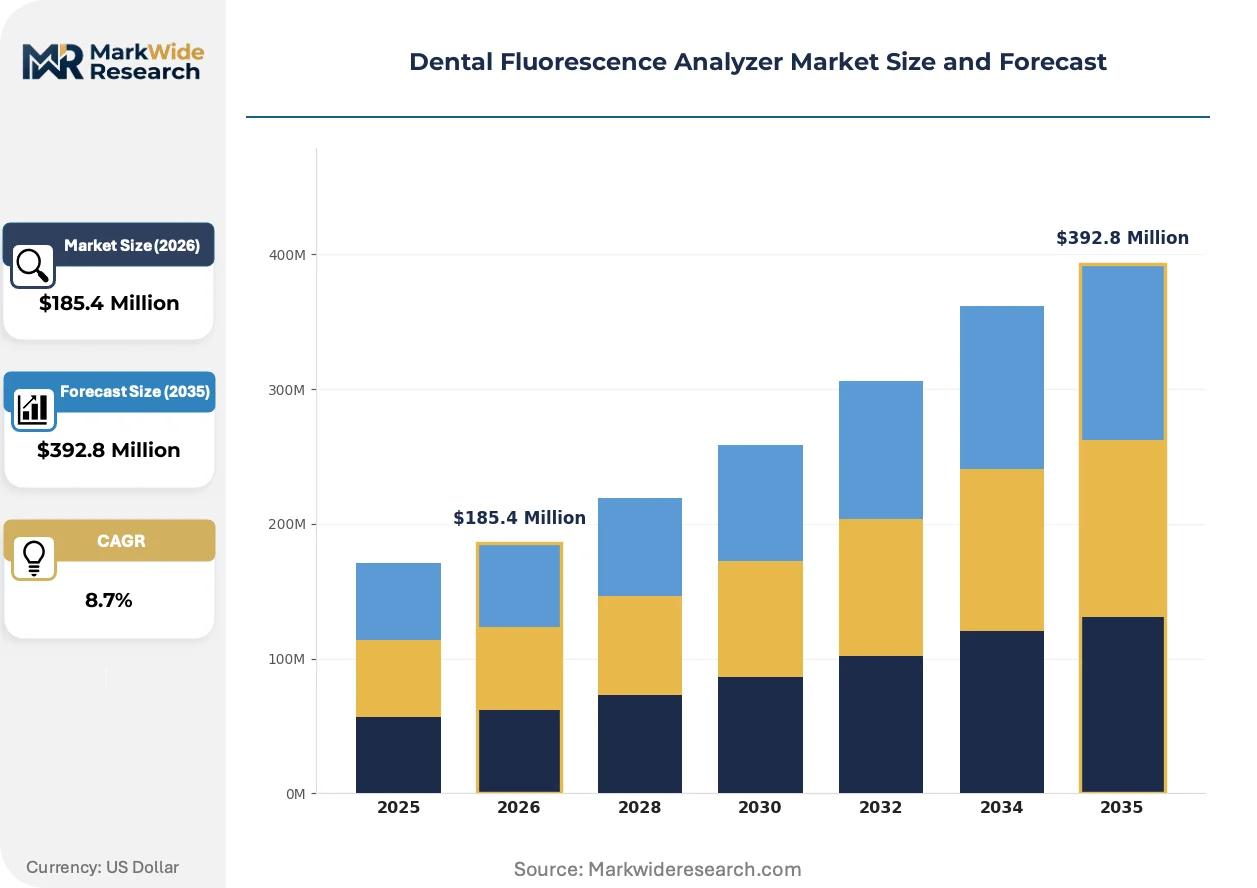
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $392.8 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Benchtop Analyzers, Portable Systems, Tabletop Units Technology: Optical Imaging, Spectroscopy, Laser Induced Fluorescence, Fluorescence Microscopy End User: Dental Clinics, Research Laboratories, Hospitals, Academic Institutions Application: Caries Detection, Oral Cancer Screening, Periodontal Assessment, Diagnostics |
| Companies Covered | Olympus Corporation, SPECTRO Analytical Instruments GmbH, Thermo Fisher Scientific, FAST ComTec, Helmut Fischer GmbH, Bruker Corporation, Rigaku Corporation, Analytical X-Ray Systems Co. Ltd., HORIBA, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Fluorescence Analyzer Market Strategic Shifts
Spectral analysis hardware is merging with computational diagnostics, compressing the gap between raw fluorescence capture and clinically actionable output. This convergence is redrawing competitive boundaries between optical component suppliers and software-enabled device integrators.
Time-resolved fluorescence detection is converging with single-photon counting electronics to resolve nanosecond-scale decay kinetics that distinguish healthy from demineralized enamel. Research laboratories in Germany and Japan are adopting these architectures for longitudinal caries progression studies. The technology is converging with portable form factors through application-specific integrated circuit miniaturization, enabling chairside deployment without sacrificing temporal resolution.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for fluorescence analyzers with quantitative output claims. Device manufacturers must now maintain vigilance systems that track diagnostic accuracy in real-world settings. Benchtop analyzer vendors serving European dental schools are restructuring quality management systems to accommodate this documentation burden, while handheld manufacturers limit quantitative claims to avoid triggering equivalent obligations.
After-sales service contracts are unbundling from hardware purchase, with clinics in the United States negotiating per-procedure calibration and software update fees rather than comprehensive maintenance agreements. Independent service organizations are capturing this disintermediated revenue stream, fragmenting vendor-customer relationships. Dental service organizations with multi-site footprints are consolidating analyzer fleets under centralized procurement and maintenance arrangements, compressing vendor margins in exchange for volume commitments.
Dental Fluorescence Analyzer Market Segmentation
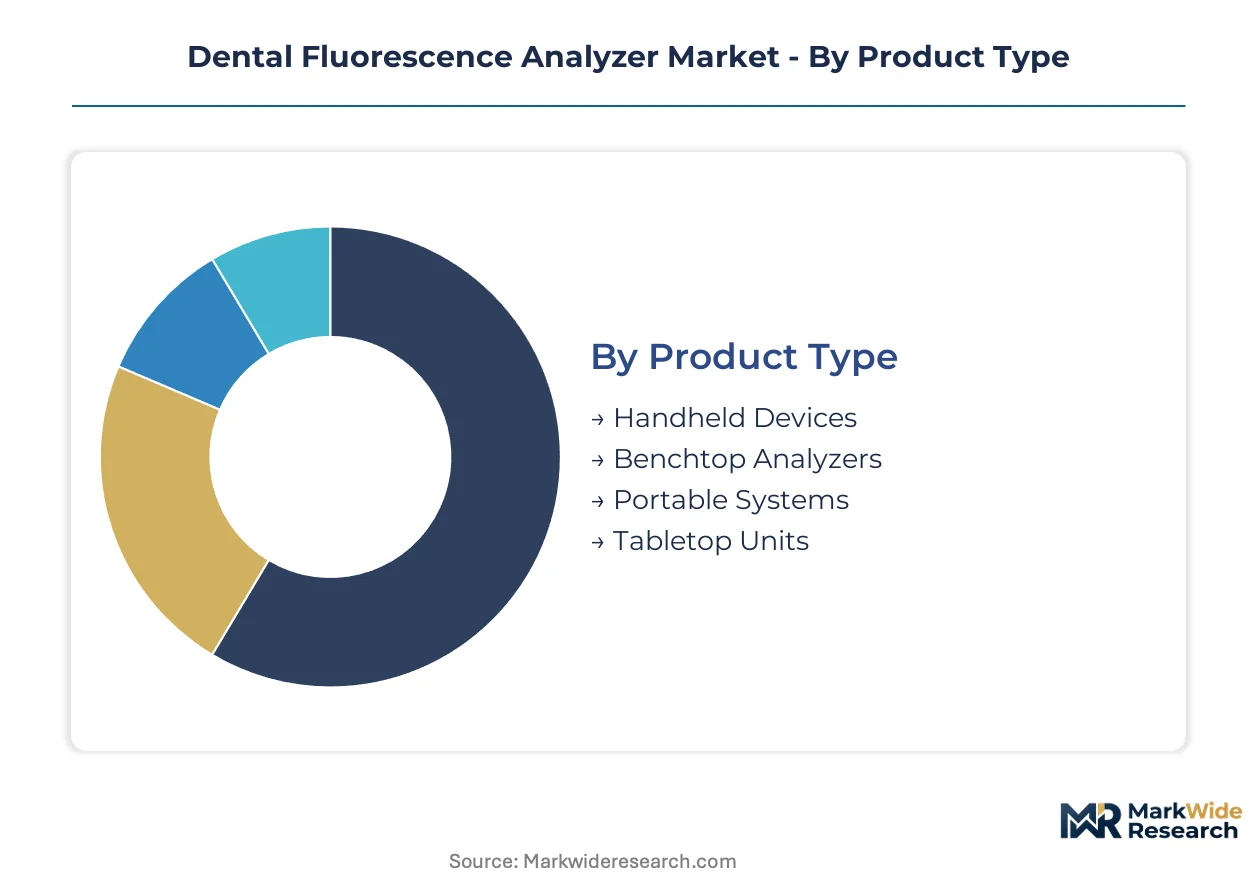
Dental fluorescence analyzer procurement varies sharply by clinical setting and diagnostic intensity. Segment-specific requirements for portability, spectral resolution, and regulatory compliance create distinct vendor-customer dynamics across the installed base.
Product Type:
Capital intensity escalates from battery-operated handheld units to precision-engineered benchtop systems requiring climate-controlled installation environments.
- Handheld Devices:Battery-powered units with integrated 405 nm diode excitation and CMOS detection arrays dominate chairside screening workflows. German dental clinics specify these for high-throughput preventive practices where space constraints limit fixed equipment.
- Benchtop Analyzers:Laboratory-grade systems with tunable excitation sources and photomultiplier detection command premium pricing for research-caliber quantitative output. Japanese dental schools anchor procurement volume for longitudinal caries studies requiring archival spectral databases.
- Portable Systems:Mobile cart configurations bridging handheld convenience with benchtop sensitivity.
- Tabletop Units:Fixed-position clinical analyzers for dedicated diagnostic bays.
Handheld devices absorb the bulk of installed capacity; portable systems are expanding most quickly.
Technology:
Technical sophistication determines reimbursement eligibility and clinical claim defensibility across detection modalities.
- Spectroscopy:Quantitative wavelength-resolved detection with calibrated intensity standards supports FDA 510(k) submissions for diagnostic specificity claims. United States dental service organizations prioritize this technology for centralized fleet standardization across multi-site practices.
- Laser Induced Fluorescence:Pulsed excitation with time-gated detection captures nanosecond-scale decay kinetics distinguishing early demineralization. Research laboratories in Germany deploy these architectures for pre-cavitated lesion monitoring where optical imaging lacks sensitivity.
- Optical Imaging:Two-dimensional fluorescence capture for qualitative screening applications.
- Fluorescence Microscopy:High-magnification cellular-level assessment for histopathological correlation.
Spectroscopy commands the dominant revenue share; laser induced fluorescence is climbing the fastest among academic procurement segments.
End User:
Procurement authority and usage intensity diverge between revenue-generating clinical settings and grant-funded research environments.
- Dental Clinics:Private and group practices driving volume procurement of handheld and portable units for fee-for-service preventive screening. Japanese Ministry of Health reimbursement expansion for early caries detection is accelerating analyzer placement in general dental practices.
- Research Laboratories:University and institutional facilities requiring calibrated, auditable spectral output for publication-grade data. German precision optics manufacturers prioritize this segment for premium benchtop configurations with extended warranty terms.
- Hospitals:Integrated health systems with centralized biomedical engineering support.
- Academic Institutions:Dental schools training next-generation practitioners on diagnostic technology.
Dental clinics absorb the bulk of installed capacity; research laboratories are expanding most quickly among technology-leading segments.
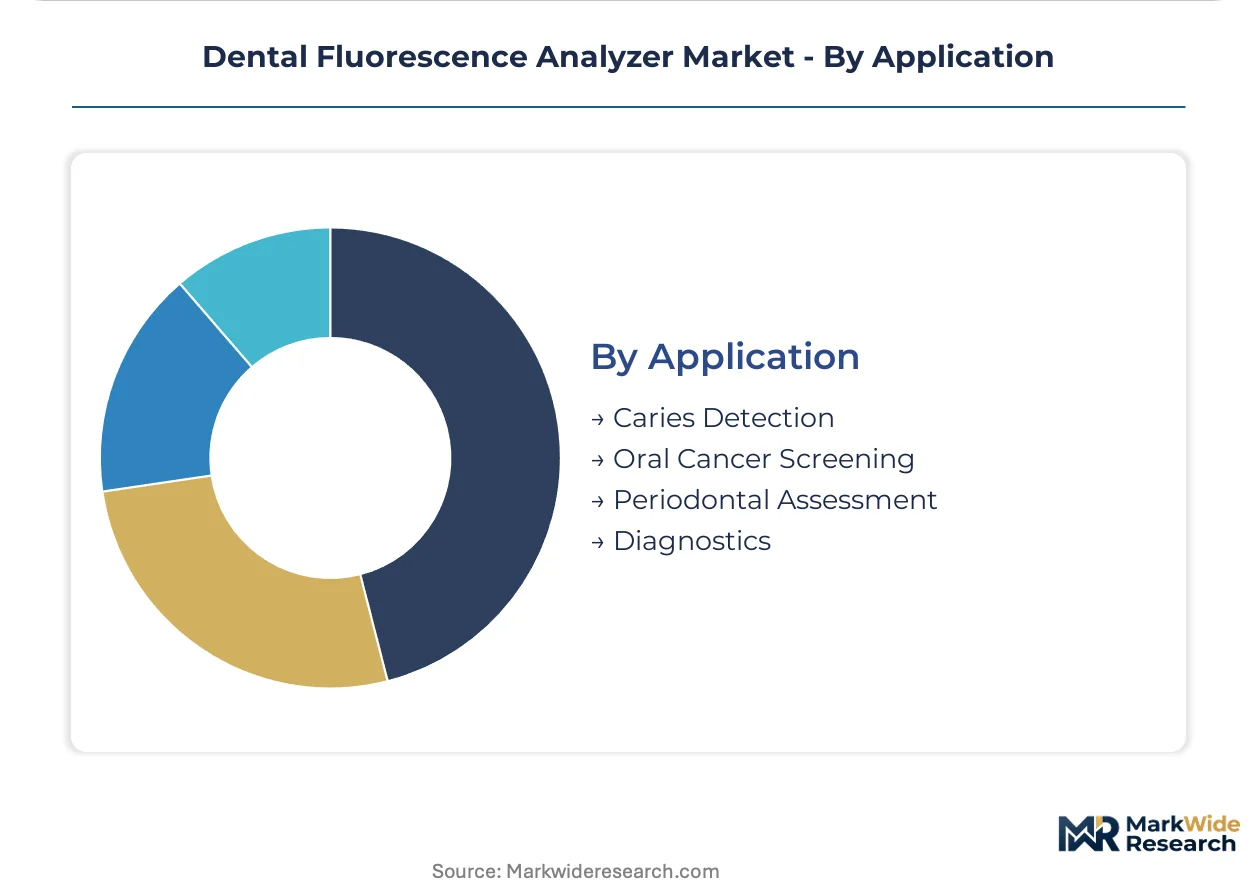
Application:
Clinical utility and regulatory classification vary by whether detection targets hard tissue pathology or soft tissue malignancy.
- Caries Detection:Enamel demineralization assessment through bacterial metabolic byproduct fluorescence remains the core volume application. FDA 510(k) clearance pathways for caries-specific claims are well-established, shortening commercialization timelines for compliant device submissions.
- Oral Cancer Screening:Mucosal fluorescence visualization for dysplasia detection requires higher-wavelength excitation configurations and specialized operator training. United States oral surgery practices are piloting these applications ahead of anticipated reimbursement code expansion.
- Periodontal Assessment:Gingival inflammation and subgingival bacterial load evaluation.
- Diagnostics:General screening applications spanning multiple pathological indicators.
Caries detection absorbs the bulk of installed capacity; oral cancer screening is gaining share fastest among specialty practice segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics manufacturing anchors the dental fluorescence analyzer supply chain, with lens foundries in Jena and Oberkochen feeding module assemblers worldwide. Demand concentrates in three major economies where regulatory frameworks and reimbursement policies shape procurement velocity.
United States
FDA 510(k) clearance pathways govern commercialization timelines for fluorescence analyzers seeking diagnostic specificity claims. Dental service organizations in Texas and Florida are consolidating multi-site analyzer fleets under centralized procurement arrangements. The Boston-Cambridge corridor hosts spectroscopy module developers supplying handheld device integrators.
Germany
MDR technical documentation mandates are accelerating ISO 13485 certification upgrades among precision optics manufacturers. Bavarian dental clinics specify handheld fluorescence units for high-throughput preventive practices where space constraints limit fixed equipment. The Jena optical cluster is retooling for portable architectures that dental clinics now specify in procurement tenders.
Japan
PMDA quality management system audits shape device commercialization timelines and clinical claim substantiation requirements. METI reimbursement expansion for early caries detection is accelerating analyzer placement in general dental practices across Kanto and Kansai regions. Osaka-based dental schools anchor procurement volume for longitudinal caries studies requiring archival spectral databases.
China
NMPA medical device registration pathways are tightening documentation requirements for fluorescence-based diagnostic systems. Mobile dentistry programs in Sichuan and Guangdong provinces are deploying battery-operated screening units to bypass fixed infrastructure limitations. The Yangtze River Delta semiconductor fabrication base is reducing 405 nm excitation source pricing for handheld unit assemblers.
Brazil
ANVISA medical device registration protocols govern importation timelines for fluorescence analyzers from European and Asian manufacturers. Rural health programs in Minas Gerais and São Paulo states are piloting portable fluorescence screening units for community dentistry outreach. São Paulo's dental equipment distribution hub is consolidating service contracts for disaggregated after-sales revenue streams.
Dental Fluorescence Analyzer Market Competitive Environment
Global majors compete with regional champions across precision optics and spectroscopy module supply. The vendor base stratifies between diversified analytical instrument conglomerates and specialized photonics subsystem suppliers. Three archetypes dominate: precision optics heritage players, spectroscopy platform standardizers, and laser-induced fluorescence specialists. Competitive moves center on M&A for optical subsystem control and strategic partnerships for regulatory pathway acceleration.
Within the precision optics heritage tier, Olympus Corporation exemplifies Japanese conglomerate positioning anchored in fluorescence microscopy legacy. Among German analytical instrument fabricators, SPECTRO Analytical Instruments GmbH and Helmut Fischer GmbH occupy positions reflecting Mittelstadt engineering specialization. Thermo Fisher Scientific represents the diversified platform standardizer archetype, competing through cross-platform compatibility rather than vertical subsystem integration.
| Leading Market Players |
|---|
| Olympus Corporation |
| SPECTRO Analytical Instruments GmbH |
| Thermo Fisher Scientific |
| FAST ComTec |
| Helmut Fischer GmbH |
| Bruker Corporation |
| Rigaku Corporation |
| Analytical X-Ray Systems Co. Ltd. |
| HORIBA, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA 510(k) cleared systems and uncertified screening devices bifurcates both pricing power and sourcing complexity across the dental fluorescence analyzer value chain. Premium benchtop configurations command sustained margins through photomultiplier detection subsystems sourced from German precision optics clusters, while handheld assemblers face margin compression from commoditized 405 nm diode arrays.
Pricing Analysis
Warranty and calibration bundling separates premium benchtop vendors from handheld competitors pursuing unbundled service revenue. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and spectral resolution specifications. Pricing pressure stems from low-cost intraoral camera substitution in budget-sensitive Brazilian and Indian clinic segments. Dental service organizations exhibit lowest price sensitivity due to centralized fleet standardization requirements, while independent rural practitioners drive hardest bargain negotiations.
Supply Chain Analysis
High-NA objective lens supply rests on German and Japanese foundries in Jena, Oberkochen, and Tokyo metropolitan manufacturing zones. Fluorescence module assemblers draw from gallium nitride laser diode wafers fabricated in South Korea and Taiwan, plus precision-machined aluminum housings from Chinese Yangtze River Delta metalworking clusters. Single-source vulnerability concentrates in photomultiplier tube production anchored to Hamamatsu-area Japanese suppliers. Distribution runs through dental equipment distributors in São Paulo, Frankfurt, and Osaka before reaching clinic procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 10 post-market surveillance mandates erect a cost-of-compliance barrier that favors incumbent vendors with established vigilance systems, filtering out undercapitalized entrants lacking quality management infrastructure.
For Market Incumbents: Deepen backward integration into 405 nm laser diode sourcing through partnerships with Yangtze River Delta semiconductor fabricators, reducing exposure to East Asian supply concentration. Fortify ISO 13485 certification moats against emerging Chinese handheld competitors by accelerating EU MDR technical documentation completion ahead of notified body audit backlogs.
For New Entrants and Emerging Players: Mobile dentistry operators in Brazil's Minas Gerais and São Paulo rural outreach programs represent the most penetrable buyer archetype, bypassing entrenched distributor relationships that dominate fixed clinic procurement. Target battery-operated portable configurations with cloud connectivity features that incumbent benchtop vendors underserve. Pursue ANVISA registration pathway acceleration through São Paulo-based regulatory consulting specialists.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision optics subsystem acquisitions by diversified analytical instrument conglomerates seeking fluorescence microscopy capability. Long-term viability favors vendors with dual FDA 510(k) and PMDA clearance portfolios spanning United States and Japanese reimbursement expansion. Monitor Japanese Ministry of Health preventive care code expansion as inflection signal for early caries detection market acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Completion | Secures CE marking access for European dental school and clinic procurement tenders. |
| AI-Assisted Spectral Interpretation Development | Reduces operator training barriers for non-specialist practitioner market expansion. |
| Mobile Dentistry Distribution Partnership | Captures Brazil and India rural health program fluorescence screening unit deployment. |
| Photonics Engineering Talent Acquisition | Addresses cross-disciplinary expertise scarcity constraining R&D team scaling. |
| Cloud-Connected Teledentistry Platform Launch | Enables remote specialist consultation subscription revenue for device-software bundles. |
Study Parameters
Multi-period observation of FDA 510(k) clearance timelines, PMDA audit completion rates, and Japanese Ministry of Health reimbursement code expansions anchored the trend analysis, supplemented by interviews with dental clinic procurement managers, biomedical engineering directors at dental service organizations, precision optics manufacturing executives in Jena and Oberkochen, and regulatory affairs specialists navigating EU MDR Article 10 requirements. Secondary validation drew from FDA 510(k) database filings, PMDA quality management system audit disclosures, METI reimbursement bulletins, and ISO 13485 certification registry data. Bottom-up device shipment tracking across handheld, portable, and benchtop categories triangulated against top-down fluorescence analyzer market value estimates.
Segment-weighting approaches modeled product type, technology modality, end-user setting, and application intensity dimensions across the projection horizon. CAGRs derived from installed base growth trajectories, replacement cycle compression, and mobile dentistry program expansion rates. Forecast inputs incorporated laser diode cost curve trajectories from East Asian semiconductor fabrication scale and MDR compliance cost burdens affecting European manufacturer pricing power.
Revisions become necessary when FDA 510(k) pathway durations extend beyond historical baselines, German precision optics export quotas tighten unexpectedly, or Japanese reimbursement code expansion stalls. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Europe Immunoassay-Gamma Counters Market
Diagnostic Instruments
Ultrasound-Guided Breast Biopsy Market
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Global Point of Care Ultrasound Market
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market