
 Europe Ovarian Cancer Diagnostics Market | 2026-2036
Europe Ovarian Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ovarian Cancer Diagnostics Market Foresight
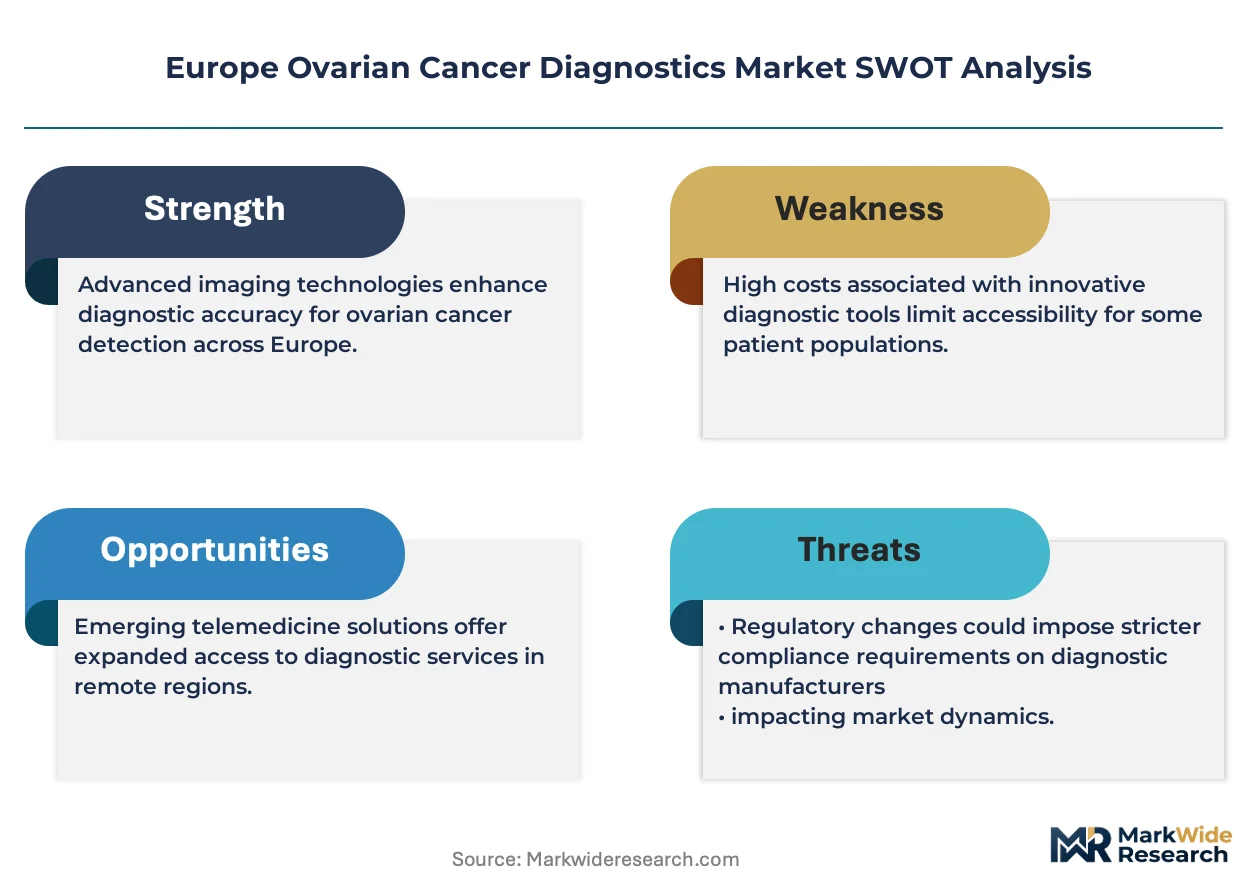
Outpatient clinics is restructuring referral patterns across Europe's ovarian cancer diagnostics landscape, shifting volume from inpatient settings toward community-based specialist centers. F. Hoffmann-La Roche Ltd anchors its position through extensive companion diagnostic alliances with pharmaceutical developers. AstraZeneca PLC leverages its PARP inhibitor portfolio to sustain demand for BRCA mutation testing across European treatment pathways. Thermo Fisher Scientific competes through integrated next-generation sequencing workflows that span sample preparation to clinical reporting.
Europe ovarian cancer diagnostics encompasses imaging modalities, biomarker assays, genetic testing platforms, and computed tomography protocols designed to detect, classify, and monitor epithelial ovarian malignancies with sensitivity thresholds typically exceeding 85 percent for advanced-stage identification. The primary commercial purpose centers on enabling gynecologic oncologists to distinguish benign adnexal masses from malignant lesions prior to surgical intervention. Biomarker segments, particularly CA-125 and HE4 combinations, dominate current revenue pools across European reference laboratories. Liquid biopsy technology represents the fastest-expanding category, as circulating tumor DNA assays reduce dependence on tissue acquisition in recurrent disease monitoring. Imaging maintains mature penetration in initial staging protocols, though contrast-enhanced ultrasound is displacing traditional CT-first approaches in several Nordic health systems.
The EU In Vitro Diagnostic Regulation, enforced through notified bodies in Germany, France, and the Netherlands, imposes clinical evidence requirements that reshape product registration timelines and post-market surveillance obligations for assay manufacturers. EMA guidelines on companion diagnostics further condition market access, linking biomarker test approval to targeted therapy authorization across member states. National health technology assessment bodies in England, France, and Germany determine reimbursement thresholds that directly influence laboratory procurement decisions. Stakeholders must monitor evolving evidence requirements under the EU AI Act as machine learning algorithms enter image interpretation workflows in ovarian mass characterization.
Market Dynamics
The EU In Vitro Diagnostic Regulation is compressing product registration timelines and forcing assay manufacturers to restructure clinical evidence generation, creating a bifurcation between compliant and non-compliant portfolios across European reference laboratories.
Growth Catalysts
- Liquid biopsy platforms:Circulating tumor DNA assays reduce tissue acquisition dependence in recurrent disease monitoring, expanding addressable testing volume in community oncology settings.
- EMA companion diagnostic guidelines:Biomarker test approval linkage to targeted therapy authorization creates mandatory demand pull for BRCA and HRD testing across member states.
- University hospital consolidation:Germany's centralized pathology networks achieve economies of scale in high-throughput biomarker panel processing, lowering per-test costs.
Market Restraints
- Notified body capacity constraints:Germany, France, and the Netherlands face certification backlog for novel assay platforms, extending time-to-market by 12-18 months.
- Reagent supply concentration:Polymerase and nucleotide raw material sourcing clusters in Switzerland and southern Germany, creating single-source vulnerability.
- CA-125 specificity ceiling:The biomarker's false-positive rate in premenopausal women limits standalone diagnostic utility, constraining reimbursement in primary care pathways.
Strategic Opportunities
- Nordic health system imaging protocols:Contrast-enhanced ultrasound adoption in Sweden, Norway, and Denmark displaces CT-first staging, opening modality substitution revenue.
- EU AI Act algorithmic interpretation:Machine learning-based ovarian mass characterization tools gain accelerated pathway status, reducing regulatory friction for imaging AI developers.
- Outpatient clinic channel expansion:Community-based specialist centers in France and Italy capture referral volume from inpatient settings, requiring point-of-care assay miniaturization.
Industry Challenges
- Molecular pathologist workforce scarcity:Germany and the United Kingdom report insufficient trained personnel to operate expanded next-generation sequencing workflows in district hospitals.
- Legacy LIS integration complexity:Laboratory information systems in France's public hospital networks require custom middleware development to accommodate cloud-based reporting platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ovarian Cancer Diagnostics Market |
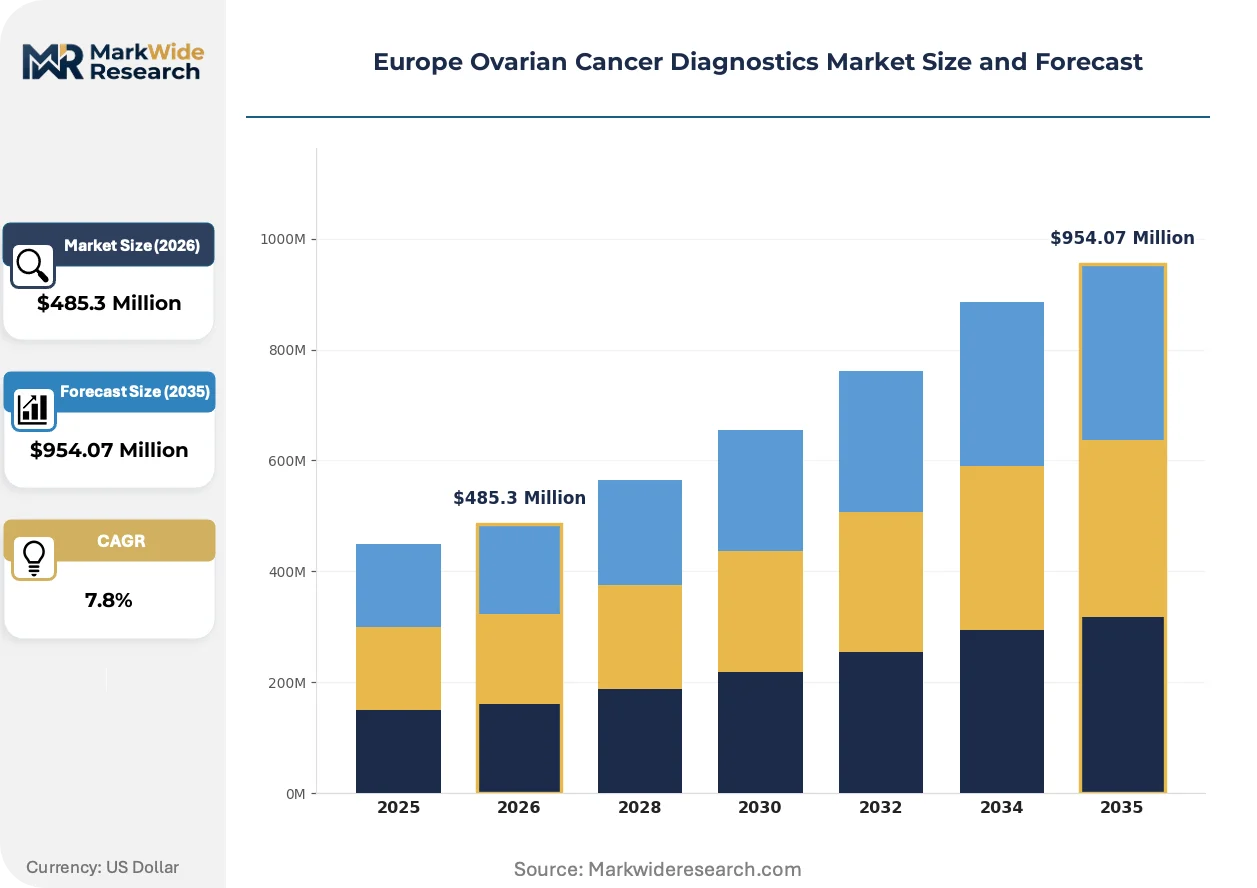
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $954.07 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging, Biomarkers, Genetic Testing, CT Scans Technology: Ultrasound, MRI, Liquid Biopsy, Immunohistochemistry End User: Hospitals, Diagnostic Laboratories, Cancer Research Institutes, Outpatient Clinics Application: Screening, Diagnosis, Treatment Monitoring, Prognosis |
| Companies Covered | Eli Lilly and Company, AstraZeneca PLC, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, Abbott, Siemens Healthineers AG, GlaxoSmithKline PLC, Quest Diagnostics Incorporated, Johnson & Johnson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ovarian Cancer Diagnostics Market Shifts & Advancements
Technology convergence between imaging AI and liquid biopsy workflows is restructuring diagnostic pathways, with regulatory frameworks struggling to keep pace with assay complexity.
Multiplex biomarker panels combining CA-125, HE4, and novel protein signatures are decentralizing testing authority from centralized reference laboratories toward regional hospital networks. Gynecologic oncology departments in the United Kingdom and the Netherlands are adopting these platforms to reduce sample transit times. This shift is compressing the competitive advantage of high-volume academic pathology centers.
The EU AI Act's risk classification framework for medical device software is imposing clinical validation requirements on machine learning algorithms used in ovarian mass characterization. Developers must demonstrate performance across diverse European patient populations to achieve CE marking. Imaging AI vendors are responding by establishing validation partnerships with university hospitals in Germany, France, and Spain.
Hospital procurement committees are unbundling diagnostic service contracts from pharmaceutical companion diagnostic alliances. This separation enables independent laboratory selection based on turnaround time and quality metrics rather than therapeutic bundling. The trend is most visible in England's NHS trusts, where pathology networks now tender NGS services separately from oncology drug procurement.
Europe Ovarian Cancer Diagnostics Market Segmentation
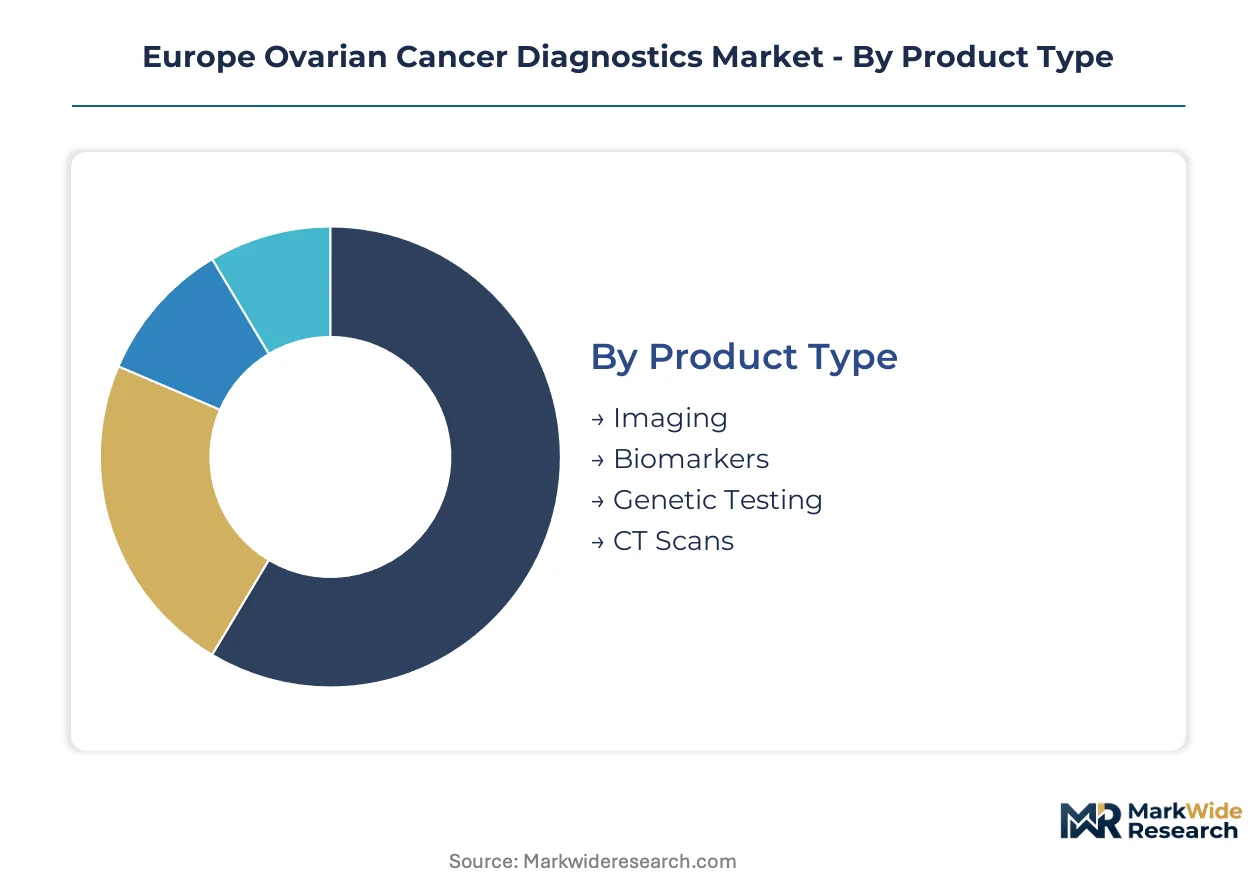
Diagnostic pathway selection in Europe's ovarian cancer market hinges on staging requirements, biomarker accessibility, and regulatory compliance under the EU In Vitro Diagnostic Regulation. Segmentation reveals where capital investment concentrates and which modalities face displacement pressure from emerging technologies.
Product Type:
Equipment refresh cycles accelerate as laboratories replace legacy analyzers with integrated platforms capable of multiplex biomarker detection and automated reporting.
- Imaging:Contrast-enhanced ultrasound and magnetic resonance systems dominate initial adnexal mass evaluation across Nordic health systems. German university hospitals are consolidating procurement around vendor-neutral archiving platforms that integrate AI-assisted interpretation tools.
- Biomarkers:CA-125 and HE4 combinations anchor routine diagnostic panels in France's public hospital networks, though specificity limitations in premenopausal populations constrain standalone deployment. The EMA's companion diagnostic guidelines are mandating BRCA and HRD testing expansion across member states.
- Genetic Testing:Next-generation sequencing workflows process germline and somatic mutation panels in England's NHS genomic laboratory hubs.
- CT Scans:Staging protocols in Italy and Spain retain computed tomography for distant metastasis detection despite radiation exposure concerns.
Biomarkers sit at the top of the volume ranking, with genetic testing climbing the fastest.
Technology:
Cost tier differentiation separates capital-intensive imaging installations from consumable-heavy molecular assays, with hybrid platforms capturing intermediate budget allocations.
- Ultrasound:Transvaginal and contrast-enhanced modalities deliver first-line characterization in community gynecology settings. Sweden's county councils have standardized equipment specifications to enable remote specialist consultation via telemedicine links.
- MRI:Pelvic magnetic resonance imaging resolves indeterminate adnexal masses with superior soft-tissue contrast. Netherlands cancer centers deploy dedicated protocols for borderline tumor differentiation, reducing unnecessary surgical staging procedures.
- Liquid Biopsy:Circulating tumor DNA assays enable minimally invasive recurrence monitoring in outpatient settings.
- Immunohistochemistry:Automated staining platforms process p53, WT1, and CK7/CK20 panels in high-throughput pathology laboratories.
Immunohistochemistry maintains the highest test frequency, while liquid biopsy platforms are expanding most quickly.
End User:
Customer type stratification reflects divergent priorities: academic centers prioritize research collaboration, while community settings demand rapid turnaround and simplified workflows.
- Hospitals:Gynecologic oncology departments in Germany's university hospital networks consolidate molecular profiling capabilities. Centralized pathology laboratories achieve economies of scale in biomarker panel processing that district hospitals cannot replicate.
- Diagnostic Laboratories:Reference laboratories in France and the United Kingdom compete on turnaround time and accreditation breadth. Independent providers are capturing volume from hospital-based services through dedicated courier networks and extended operating hours.
- Cancer Research Institutes:Translational research programs in the Netherlands and Denmark drive early adoption of novel assay platforms.
- Outpatient Clinics:Community-based specialist centers in Italy are restructuring referral patterns from inpatient settings.
Hospitals command the largest installed base, with outpatient clinics gaining share fastest.
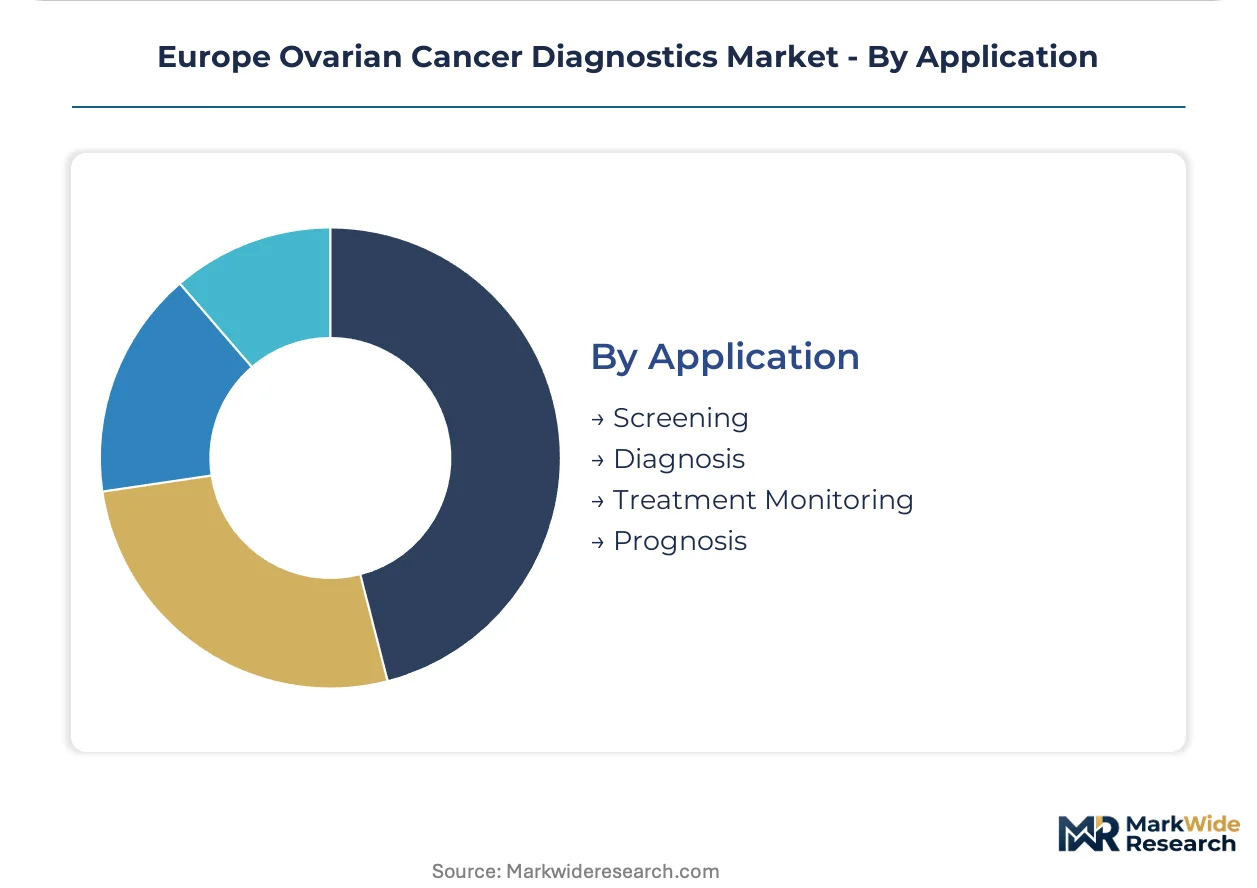
Application:
Volume concentration varies by disease stage: early detection programs generate screening volume, while advanced disease drives monitoring frequency and test complexity.
- Screening:Population-level programs remain limited by CA-125 specificity constraints and cost-effectiveness thresholds set by England's National Screening Committee. Risk stratification algorithms combining biomarkers with ultrasound are under evaluation in Nordic pilot studies.
- Diagnosis:Definitive characterization of adnexal masses requires multimodal integration across imaging, biomarker, and histopathological findings. France's HAS evaluates diagnostic accuracy data to inform reimbursement decisions for novel assay platforms.
- Treatment Monitoring:Serial CA-125 measurements track therapeutic response in platinum-sensitive recurrence.
- Prognosis:Molecular subtyping guides adjuvant therapy selection and clinical trial enrollment.
Diagnosis accounts for the greatest test volume, with treatment monitoring showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's university hospital networks anchor molecular diagnostics capacity across Europe, processing high-throughput biomarker panels through centralized pathology laboratories in Berlin, Munich, and Heidelberg. National reimbursement frameworks and EMA companion diagnostic guidelines shape procurement decisions in each market.
Germany
Bavaria's university hospital clusters drive demand for integrated NGS workflows and automated immunohistochemistry platforms. The EU In Vitro Diagnostic Regulation, enforced through German notified bodies, compresses registration timelines for novel assay manufacturers. Berlin-Brandenburg's pathology networks achieve economies of scale that district hospitals cannot replicate, consolidating regional testing volume.
United Kingdom
England's NHS genomic laboratory hubs process germline and somatic mutation panels at scale, with Greater London and Manchester anchoring national capacity. NICE technology appraisals determine reimbursement thresholds for BRCA and HRD testing across NHS trusts. The Midlands and North England pathology networks now tender NGS services separately from oncology drug procurement, unbundling diagnostic contracts.
France
Île-de-France's public hospital networks deploy CA-125 and HE4 combinations in routine diagnostic panels, though HAS evaluations constrain novel assay adoption. ANSM oversight of companion diagnostic platforms links biomarker approval to targeted therapy authorization. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur regions are expanding outpatient clinic capacity to capture referral volume from inpatient settings.
Netherlands
Dutch cancer centers in Amsterdam and Rotterdam deploy dedicated MRI protocols for borderline tumor differentiation, reducing unnecessary surgical staging. EMA guidelines on companion diagnostics mandate BRCA testing expansion through national health insurance frameworks. Translational research programs in Utrecht and Leiden drive early adoption of circulating tumor DNA assays for recurrence monitoring.
Sweden
Stockholm's county councils have standardized contrast-enhanced ultrasound specifications, enabling remote specialist consultation via telemedicine links to regional gynecology units. Sweden's national screening committee evaluates risk stratification algorithms combining biomarkers with imaging for population-level pilot studies. Gothenburg and Malmö university hospitals are validating machine learning algorithms for ovarian mass characterization under EU AI Act frameworks.
Europe Ovarian Cancer Diagnostics Market Competitive Landscape
Strategic partnerships dominate the current landscape, with pharmaceutical-diagnostic alliances restructuring procurement authority across European hospital networks. The vendor base clusters around three archetypes: integrated life science conglomerates with companion diagnostic portfolios, specialized reference laboratories competing on turnaround time, and imaging equipment manufacturers embedding AI interpretation tools. M&A activity and technology licensing agreements represent the primary competitive vectors, as laboratories seek vendor-neutral platforms and cloud-based reporting capabilities.
Among Switzerland-based diagnostics specialists, F. Hoffmann-La Roche Ltd occupies a position exemplifying the integrated conglomerate archetype through extensive companion diagnostic alliances. AstraZeneca PLC represents the pharmaceutical-led demand generator, leveraging its PARP inhibitor portfolio to sustain mandatory testing requirements. Thermo Fisher Scientific, a US-based life science corporation, anchors the workflow integration tier with platforms spanning sample preparation to clinical reporting.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| AstraZeneca PLC |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| Abbott |
| Siemens Healthineers AG |
| GlaxoSmithKline PLC |
| Quest Diagnostics Incorporated |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up diagnostic laboratory networks across Germany and France are consolidating procurement authority, compressing vendor margins while demanding extended payment terms that strain reagent manufacturer working capital cycles.
Pricing Analysis
Distributor margin layers in European IVD supply chains typically capture 15-25 percent before hospital procurement committees apply volume-based clawbacks. Three-tier pricing structure across premium, standard, and economy levels separates CE-IVD certified companion diagnostic platforms from research-use-only reagent bundles and unbranded consumables. Pricing pressure stems from NHS England's unbundled tendering of NGS services, which forces reference laboratories to compete on per-test cost rather than therapeutic bundling. Community-based outpatient clinics exhibit highest price sensitivity due to fixed reimbursement ceilings, while university hospital networks prioritize turnaround time and accreditation breadth over unit cost.
Supply Chain Analysis
Domestic-content mandates under the EU In Vitro Diagnostic Regulation are reshaping sourcing patterns, requiring notified body certification for polymerase and nucleotide reagents manufactured outside member states. Geographic supply concentration centers on Switzerland and southern Germany for enzyme production, with nucleotide raw materials drawing from Netherlands-based chemical synthesis facilities and Irish pharmaceutical manufacturing zones. Single-source vulnerability persists in CRISPR guide RNA synthesis, where two specialized providers serve the majority of European research and clinical markets. Distribution runs through dedicated cold-chain logistics networks operated by pan-European healthcare distributors, with hospital procurement committees increasingly mandating vendor-neutral inventory management systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where laboratory consolidation and regulatory complexity favor scaled players with established companion diagnostic alliances and automated workflow platforms.
For Market Incumbents: Extend companion diagnostic partnership portfolios to capture mandatory testing demand under EMA guidelines, while consolidating cloud-based reporting capabilities to defend against independent reference laboratories competing on turnaround time. Invest in CE-IVD certification for liquid biopsy platforms ahead of EU AI Act algorithmic validation requirements. Molecular pathologist workforce scarcity in district hospitals creates vulnerability to centralized academic pathology networks.
For New Entrants and Emerging Players: Machine learning-based ovarian mass characterization tools offer a technology-first wedge into Nordic health systems already adopting contrast-enhanced ultrasound protocols. Target outpatient clinic channels in France and Italy, where referral volume is restructuring from inpatient settings and point-of-care assay miniaturization remains underdeveloped. Pursue validation partnerships with university hospitals in Germany and Spain to satisfy EU AI Act clinical evidence requirements.
For Investors and Strategic Acquirers: Pharmaceutical companies with PARP inhibitor portfolios are the most active acquirer in this space, seeking captive diagnostic capabilities to secure therapy-linked testing mandates. Long-term viability hinges on regulatory navigation capacity under evolving EU IVD and AI Act frameworks. Watch for notified body certification backlog resolution as inflection indicator for novel assay platform time-to-market compression.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU IVD Regulation compliance enables market access across Germany, France, and Netherlands notified body jurisdictions. |
| Hospital System Partnership | England's NHS genomic laboratory hubs unbundle diagnostic contracts from pharmaceutical procurement, opening independent vendor selection. |
| Software Companion Development | Machine learning algorithms for ovarian mass characterization gain accelerated pathway status under EU AI Act risk classification frameworks. |
| Reimbursement Strategy | NICE technology appraisals and France's HAS evaluations determine BRCA and HRD testing coverage thresholds across national health systems. |
| Platform Integration | Vendor-neutral archiving systems consolidate imaging AI and liquid biopsy workflows in German university hospital networks. |
Research Methodology
Coverage spans Germany, France, the United Kingdom, the Netherlands, and Sweden, with primary inputs from each market informing demand calibration and regulatory pathway assessment. The research combines structured interviews with gynecologic oncologists, hospital procurement managers, pathology laboratory directors, and regulatory affairs specialists at IVD manufacturers with secondary validation from EMA companion diagnostic guidelines, EU IVD Regulation notified body filings, NICE technology appraisals, and hospital procurement database extracts. Bottom-up test volume modeling and top-down market sizing triangulate against national health expenditure statistics and laboratory accreditation registries.
Granularity-level modeling distinguishes product type segments by regulatory certification tier, technology platforms by automation integration depth, and end users by procurement authority concentration. Segmentation dimensions include diagnostic modality, biomarker panel complexity, and companion diagnostic linkage to targeted therapy authorization. CAGRs derive from test volume trajectories and unit price evolution assumptions, with inputs from liquid biopsy adoption curves, imaging AI validation timelines, and outpatient clinic channel expansion rates across the analysis window.
The model holds under stable EU regulatory enforcement and continued pharmaceutical companion diagnostic alliance structures; deviation in notified body capacity or reimbursement policy fragmentation would shift competitive positioning and entry economics. Forecasts reflect documented assumptions regarding test menu expansion, workforce availability, and technology substitution rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Mycoplasma Diagnostics Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
Rapid Influenza Diagnostic Tests (RIDT) Market
Diagnostics
Blood Ketone Test Meter Market
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Asia-Pacific Thyroid Cancer Diagnostics Market
Diagnostics
Global Non-Small Cell Lung Cancer Diagnostics Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
Pathogen Detection Market
Diagnostics
Diabetes Testing System Market
Diagnostics
Sperm Density Testing Market
Diagnostics
D-Dimer Market
Diagnostics
Global Oral Cancer Rapid Test Kit Market