
 Urothelial Carcinoma Treatment Market | 2026-2036
Urothelial Carcinoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Urothelial Carcinoma Treatment Market Intelligence
The divergence between novel, high-cost checkpoint inhibitors and established chemotherapy regimens is realigning the urothelial carcinoma treatment landscape. Merck & Co., Inc. leverages its leadership in immuno-oncology with its portfolio of checkpoint inhibitors. Bristol-Myers Squibb Company competes intensely in this high-margin segment. In contrast, UroGen Pharma Ltd. specializes in non-surgical, intravesical treatments for low-grade disease, targeting a different patient population.
Urothelial carcinoma treatment encompasses medical interventions designed to eradicate or control malignant cells originating in the urothelium. These therapies target cancers of the bladder, ureter, and renal pelvis using pharmacological agents. Checkpoint inhibitors represent the fastest-growing product type, driven by superior efficacy in specific patient cohorts. Within therapy areas, treatments for metastatic disease command higher price points, while non-muscle invasive bladder cancer constitutes the largest volume of cases.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) dictate clinical trial requirements and marketing authorizations for new drugs. China's NMPA is also streamlining its approval processes, influencing market access strategies for multinational firms. The key decision for developers now centers on balancing investment between broad-spectrum therapies and highly targeted, biomarker-driven treatments.
Market Dynamics
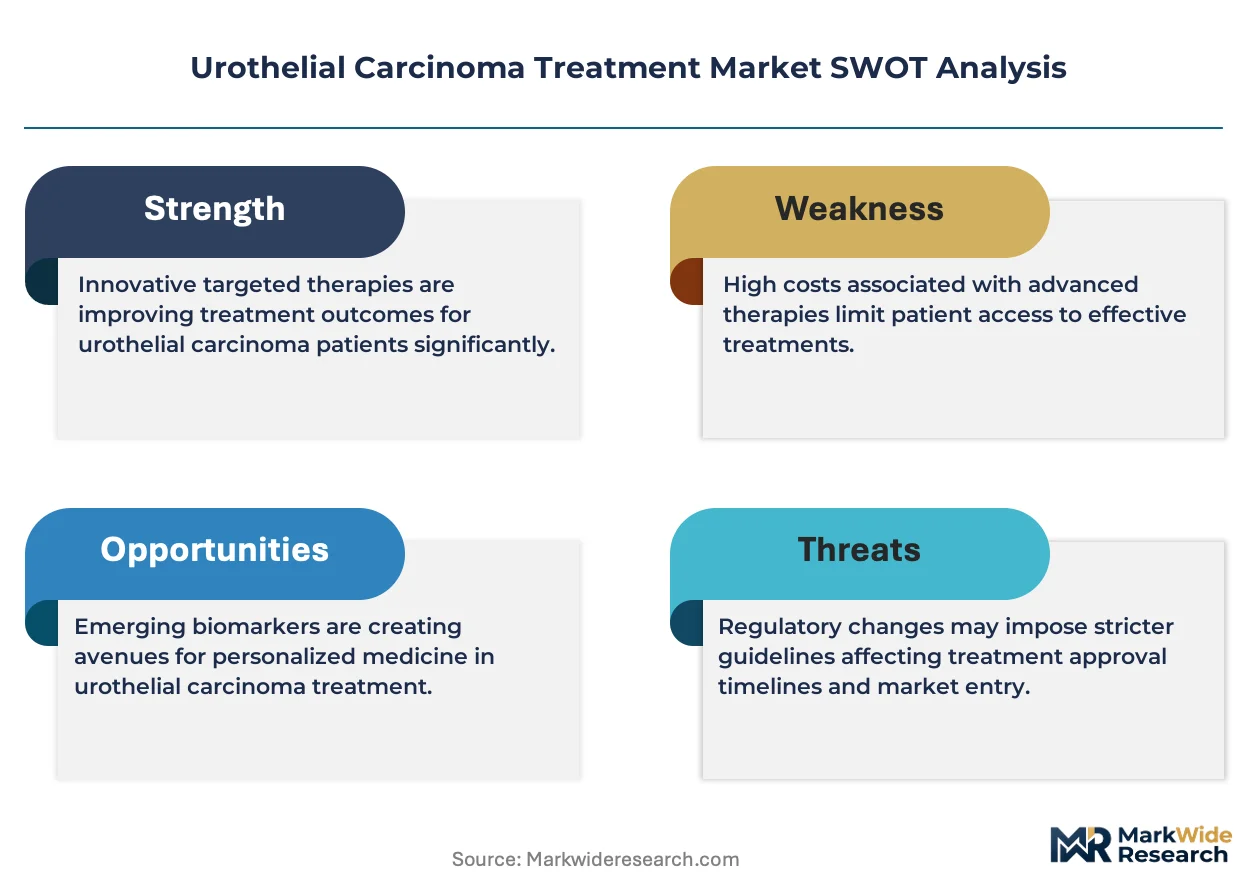
The accelerated approval pathway for novel biologics is the central force reshaping the urothelial carcinoma treatment market. This regulatory mechanism, championed by agencies like the FDA, allows for faster market entry of high-efficacy drugs, intensifying the competitive pressure on established chemotherapy regimens.
Growth Catalysts
- Antibody-Drug Conjugates (ADCs):This technology class enables highly targeted delivery of cytotoxic agents directly to cancer cells, improving therapeutic outcomes while minimizing systemic toxicity. Their adoption is expanding for patients who have failed prior therapies.
- FDA Accelerated Approval Pathway:This regulatory framework significantly shortens the time to market for therapies addressing unmet needs in metastatic urothelial carcinoma, incentivizing investment in innovative drug development for specific, hard-to-treat patient populations.
- Aging Demographics:The rising incidence of bladder cancer in aging populations across developed nations, particularly in the United States and Europe, provides a sustained expansion of the underlying patient pool requiring treatment.
Market Restraints
- High Cost of Biologics:The substantial price points of checkpoint inhibitors and antibody-drug conjugates create significant reimbursement challenges and limit patient access in healthcare systems without comprehensive coverage for specialty oncology drugs.
- Biomarker Heterogeneity:The absence of a single, universally predictive biomarker for response to immuno-oncology agents complicates patient selection, restricting the optimal use of these targeted therapies to smaller, defined cohorts.
- Divergent Payer Requirements:Inconsistent evidence standards and cost-effectiveness thresholds among national payers, especially within the European Union, fragment the market and create significant hurdles for achieving broad reimbursement.
Strategic Opportunities
- Neoadjuvant and Adjuvant Settings:Expanding the clinical application of novel therapies into earlier disease stages, such as before or after surgery for muscle-invasive bladder cancer, offers a substantial avenue for market growth and improved patient outcomes.
- Combination Therapy Regimens:Investigating synergistic combinations of checkpoint inhibitors with ADCs, targeted agents, or chemotherapy presents an opportunity to overcome treatment resistance and enhance efficacy beyond current monotherapy standards.
- China's Regulatory Streamlining:The NMPA's faster review process for oncology drugs creates a major opportunity for multinational firms to access the large and growing patient population in China, a previously challenging market.
Industry Challenges
- Complex Clinical Trial Design:Developing and executing clinical trials for combination therapies and biomarker-specific populations requires sophisticated statistical plans, increased patient screening, and higher operational costs, extending development timelines.
- Payer Evidence Demands:Health technology assessment (HTA) bodies increasingly require long-term survival data and real-world evidence to justify the high cost of new therapies, creating a post-approval evidence-generation burden for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urothelial Carcinoma Treatment Market |
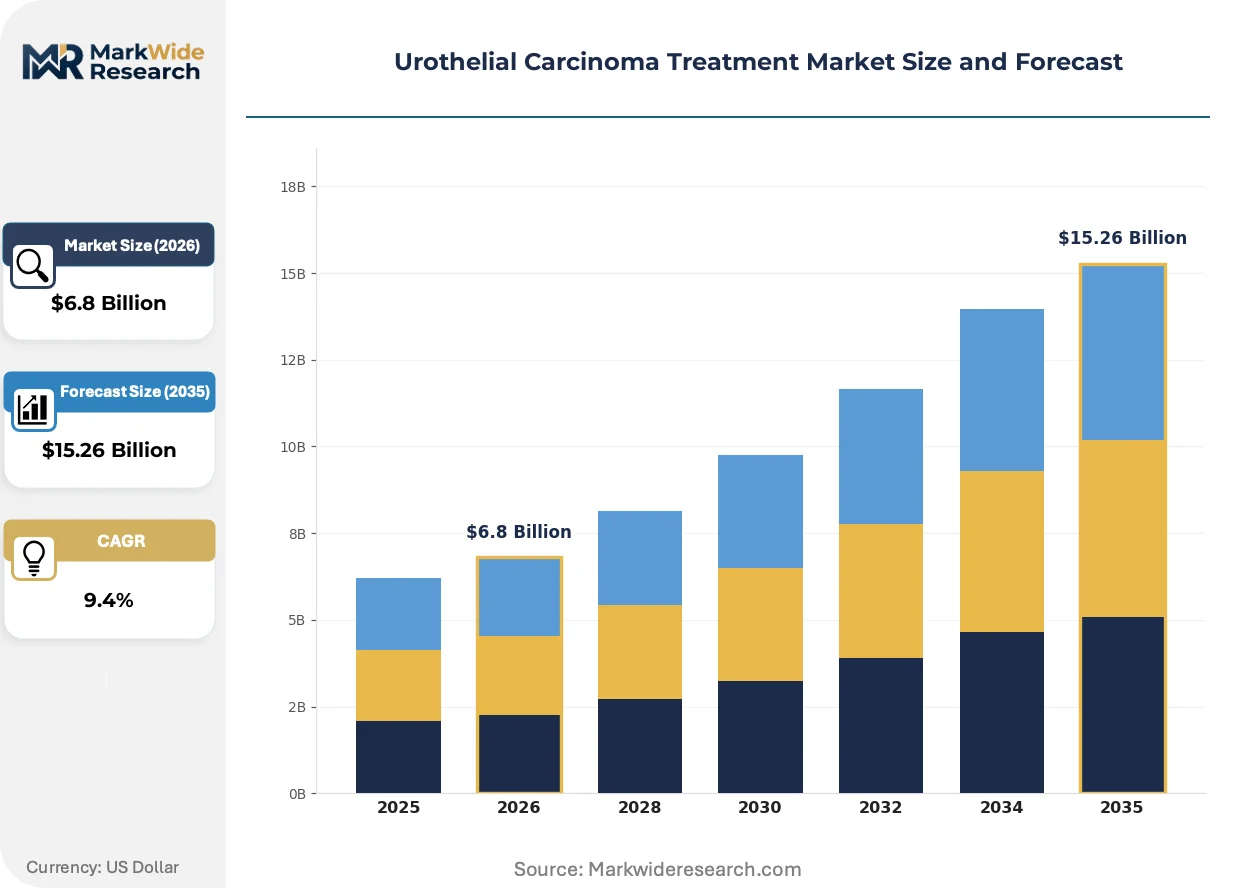
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Checkpoint Inhibitors, Chemotherapy, Targeted Therapy, Immunotherapy, Bacillus Calmette-Guerin Therapy Area: Non-Muscle Invasive, Muscle Invasive, Metastatic, Recurrent Care Setting: Oncology Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories, Cancer Research Centers Administration Route: Intravesical, Intravenous, Oral, Subcutaneous |
| Companies Covered | Merck & Co., Inc., F. Hoffmann-La Roche AG, Bristol-Myers Squibb Company, AstraZeneca PLC, Pfizer Inc., Novartis AG, Johnson & Johnson, Sanofi S.A., UroGen Pharma Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urothelial Carcinoma Treatment Market Strategic Shifts & Innovations
The market is pivoting from broad-spectrum cytotoxic chemotherapy toward a more personalized and biologically informed treatment paradigm. This evolution is driven by advanced diagnostic technologies and regulatory frameworks that support targeted therapeutic development for specific patient subgroups.
Companion diagnostics, particularly next-generation sequencing (NGS) panels, identify specific genetic alterations and protein expression levels like PD-L1. Oncologists in major cancer centers are rapidly adopting these tools for treatment planning in advanced disease. This technology is automating the patient stratification process, enabling a more precise match between a patient's tumor biology and a targeted therapy.
The European Medicines Agency's (EMA) adaptive pathways framework facilitates earlier and more frequent interaction between regulators and drug developers. This approach enables iterative evidence generation, supporting conditional marketing authorization for therapies that address high unmet medical needs. This shift particularly benefits developers of treatments for rare urothelial carcinoma subtypes, who can now pursue approval with more targeted clinical data.
A notable shift toward value-based care models is influencing how treatments are selected and reimbursed. This trend disrupts traditional fee-for-service payment, introducing risk-sharing agreements where financial remuneration is linked to clinical outcomes like progression-free survival. This model is most prominent within integrated health systems in the United States and certain European countries, forcing a focus on demonstrable cost-effectiveness for high-priced oncology agents.
Urothelial Carcinoma Treatment Market Segmentation
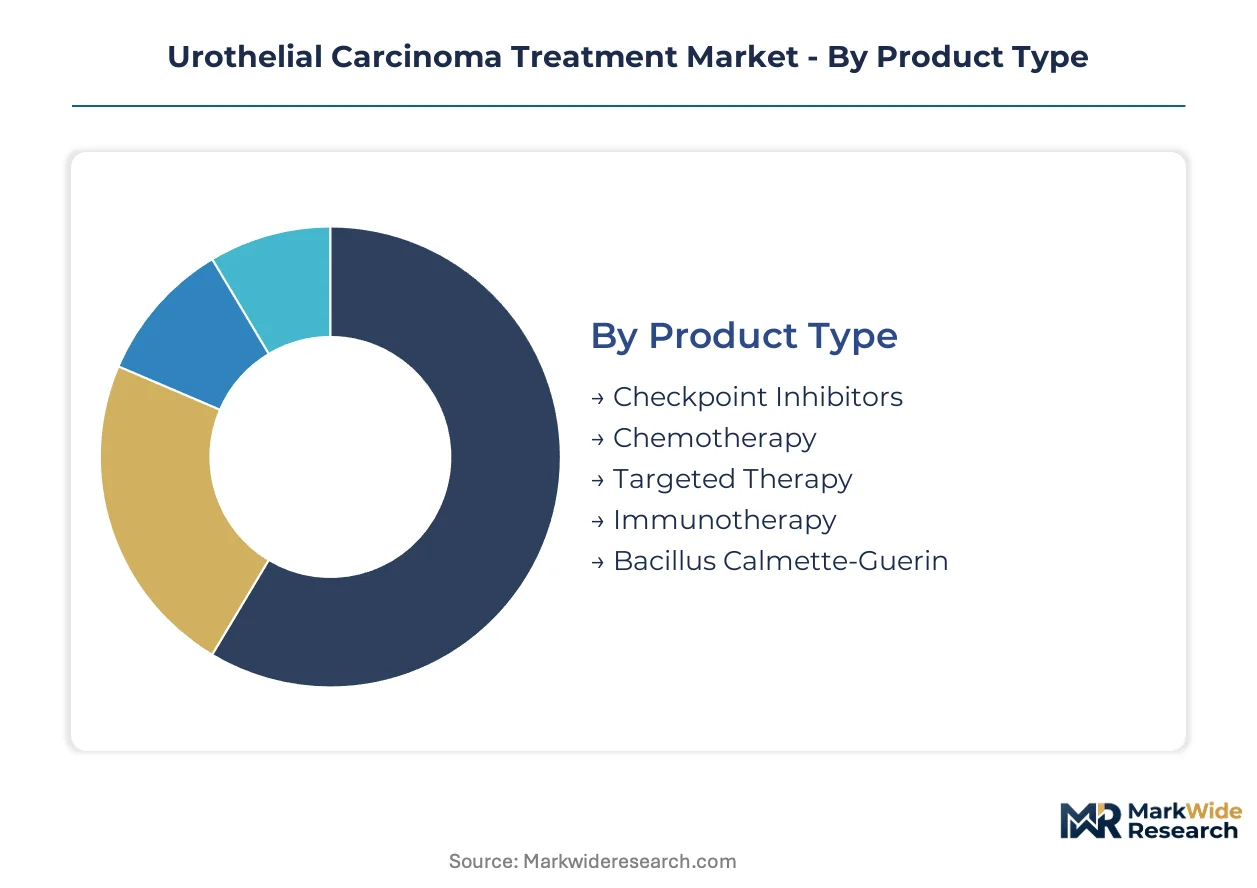
The urothelial carcinoma treatment market segments reflect diverse therapeutic approaches and patient needs across disease stages. Understanding these distinct segments allows pharmaceutical developers and healthcare providers to tailor interventions, optimizing both patient outcomes and resource allocation. This granular classification highlights areas of high clinical urgency and established treatment protocols.
Product Type:
The market for urothelial carcinoma treatments shows a clear divergence between high-volume, established therapies and premium, novel biologics.
- Checkpoint Inhibitors:These immunotherapeutic agents block specific proteins on immune cells or cancer cells, enabling the immune system to recognize and attack tumor cells. Demand concentrates in the United States and European Union, driven by FDA and EMA accelerated approvals for metastatic disease.
- Chemotherapy:Cytotoxic drugs target rapidly dividing cells, including cancer cells, to reduce tumor burden or prevent recurrence. This segment sees widespread adoption in both muscle-invasive and metastatic settings due to its long-standing efficacy and established reimbursement pathways.
- Targeted Therapy:These drugs specifically target molecular pathways involved in cancer growth and progression, offering a more precise treatment approach for specific genetic mutations.
- Immunotherapy:This broad category of treatments stimulates or restores the body's immune system to fight cancer, encompassing various mechanisms beyond checkpoint inhibition.
- Bacillus Calmette-Guerin:An attenuated strain of Mycobacterium bovis used as an intravesical immunotherapy for non-muscle invasive bladder cancer, stimulating a localized immune response.
Mature deployment sits with Chemotherapy. Newer deployment is concentrated in Checkpoint Inhibitors.
Therapy Area:
Treatment modalities for urothelial carcinoma are precisely adapted to the extent and invasiveness of the disease, guiding therapeutic choices for different patient populations.
- Metastatic:This segment addresses advanced disease where cancer has spread beyond the bladder, ureter, or renal pelvis to distant sites. Treatments for metastatic disease command higher price points due to the severity of the condition and the need for systemic therapies.
- Non-Muscle Invasive:Characterized by tumors confined to the bladder lining without invading the muscle layer, this therapy area constitutes the largest volume of cases. Management often involves local therapies to prevent recurrence and progression.
- Muscle Invasive:This stage involves cancer that has grown into the bladder muscle wall, requiring more aggressive treatment strategies such as radical cystectomy or systemic chemotherapy.
- Recurrent:This category covers cases where urothelial carcinoma returns after initial treatment, necessitating re-evaluation and often a shift to alternative therapeutic approaches.
The market share is significantly influenced by the prevalence of non-muscle invasive cases, while metastatic disease drives innovation and premium pricing.
Care Setting:
The delivery of urothelial carcinoma treatments varies across different healthcare environments, reflecting the continuum of patient care from diagnosis to advanced therapy.
- Oncology Clinics:These specialized outpatient facilities provide comprehensive cancer care, including chemotherapy, immunotherapy, and targeted therapy administration, for a large volume of patients across all disease stages. Oncology clinics serve as primary hubs for long-term patient management and follow-up.
- Ambulatory Surgical Centers:These facilities perform outpatient surgical procedures, including transurethral resections for non-muscle invasive bladder cancer. Their operational model supports cost-effective procedural care for suitable patients, particularly in the United States.
- Diagnostic Laboratories:These facilities perform essential biomarker testing, such as PD-L1 expression and gene sequencing, crucial for guiding treatment decisions for targeted therapies and immunotherapies.
- Cancer Research Centers:These institutions focus on developing novel therapies and conducting clinical trials, playing a vital role in advancing treatment options for urothelial carcinoma patients.
Oncology Clinics manage the broadest range of patient treatments, while Diagnostic Laboratories underpin precision medicine approaches.
Administration Route:
The method of drug delivery for urothelial carcinoma treatments is critical for maximizing therapeutic effect while minimizing systemic toxicity, depending on the disease location and stage.
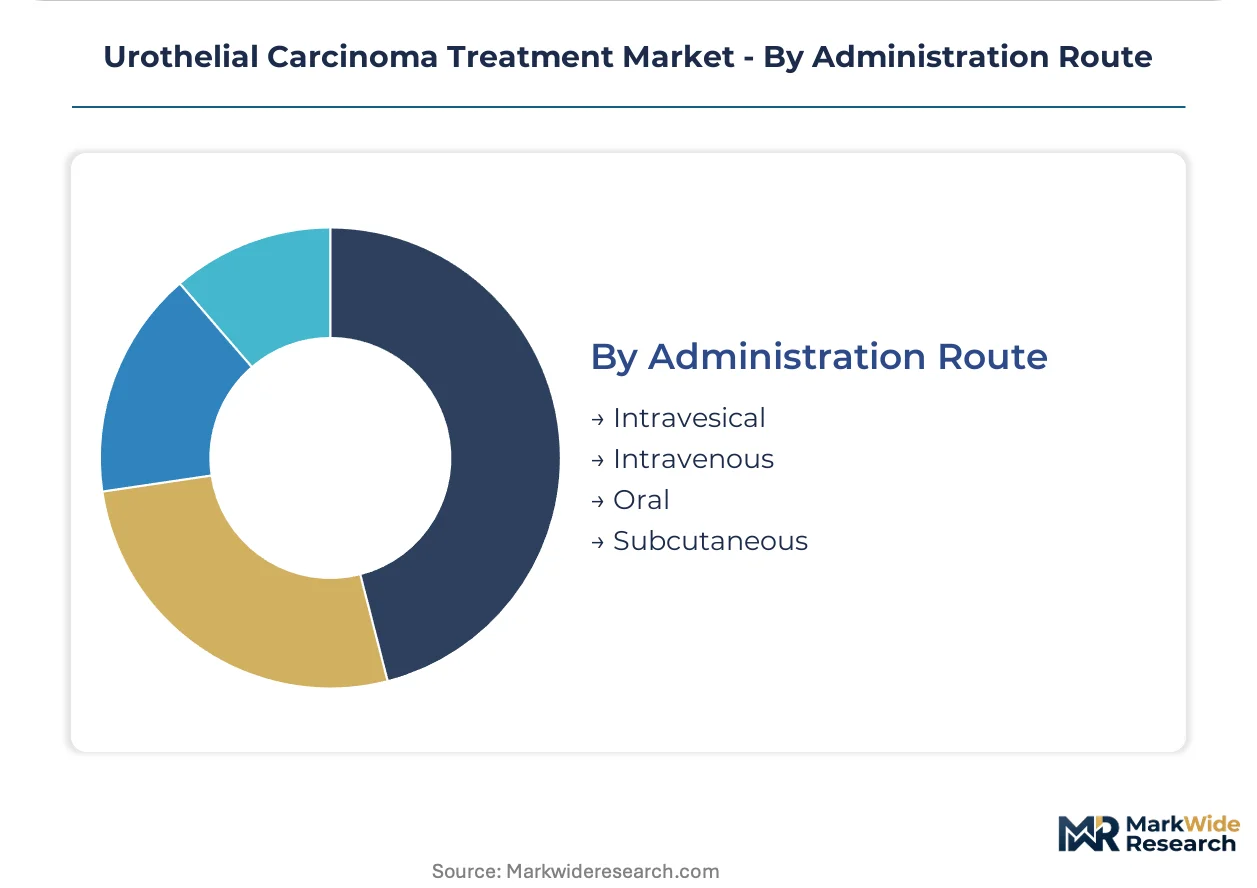
- Intravesical:This route involves direct instillation of therapeutic agents into the bladder, primarily for non-muscle invasive bladder cancer. Intravesical administration reduces systemic side effects by concentrating the drug at the tumor site.
- Intravenous:Systemic delivery of drugs directly into the bloodstream, this route is essential for treating muscle-invasive and metastatic urothelial carcinoma. Intravenous administration ensures widespread drug distribution to target distant cancer cells.
- Oral:Oral formulations provide patient convenience and allow for at-home administration, primarily for specific targeted therapies or maintenance treatments.
- Subcutaneous:This injection route delivers drugs under the skin, offering an alternative to intravenous administration for certain biologics, improving patient comfort and reducing clinic visits.
Intravesical administration is foundational for early-stage disease, while Intravenous delivery remains critical for advanced urothelial carcinoma.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and Cambridge in the United States anchor significant innovation in urothelial carcinoma treatment. This region drives research into novel biologics and targeted therapies. The evolving regulatory landscape and advanced healthcare infrastructure influence global market dynamics.
United States
Demand for advanced urothelial carcinoma treatments is high, driven by a large aging population and comprehensive insurance coverage. The FDA's accelerated approval pathway significantly speeds market entry for new oncology drugs. Major pharmaceutical companies concentrate research and development in regions like the Northeast corridor.
Germany
Germany exhibits strong demand for high-value urothelial carcinoma therapies, supported by a robust healthcare system. The European Medicines Agency (EMA) influences drug approvals across the EU, impacting market access. Academic medical centers in cities like Heidelberg contribute significantly to clinical trial advancements.
Japan
Japan's market for urothelial carcinoma treatment benefits from an aging demographic and a focus on precision medicine. The Pharmaceuticals and Medical Devices Agency (PMDA) streamlines approvals for innovative oncology agents. Tokyo and Osaka host major pharmaceutical research hubs, fostering drug development.
China
China's market is expanding rapidly due to increasing healthcare access and a large patient base. The National Medical Products Administration (NMPA) is expediting review processes for oncology drugs, attracting multinational firms. Shanghai and Beijing are emerging as key centers for clinical research and pharmaceutical manufacturing.
India
India presents a growing market for urothelial carcinoma treatments, particularly for more affordable options and biosimilars. The Central Drugs Standard Control Organization (CDSCO) regulates drug approvals and manufacturing standards. Major metropolitan areas like Mumbai and Hyderabad serve as pharmaceutical industry centers.
Urothelial Carcinoma Treatment Market Key Industry Players
Premium-margin players sit above commodity-margin players across the urothelial carcinoma treatment spectrum. The market structure exhibits a tiered consolidation, with large pharmaceutical companies dominating high-value segments. Strategic archetypes include immuno-oncology leaders, targeted therapy specialists, and established chemotherapy providers. Dominant competitive moves involve portfolio diversification and strategic partnerships to expand therapeutic reach.
On the premium-tier vector, Merck & Co., Inc. and Bristol-Myers Squibb Company represent major forces in immuno-oncology, leveraging their extensive portfolios of checkpoint inhibitors. UroGen Pharma Ltd. exemplifies a specialist archetype, focusing on non-surgical, intravesical treatments for low-grade disease. These companies anchor innovation across distinct patient populations, influencing treatment paradigms.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| F. Hoffmann-La Roche AG |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Pfizer Inc. |
| Novartis AG |
| Johnson & Johnson |
| Sanofi S.A. |
| UroGen Pharma Ltd. |
| Others |
Cost & Logistics Intelligence
Specialized biologic manufacturing inputs, including cell culture media and recombinant proteins, drive upstream production costs that directly influence the premium pricing of novel urothelial carcinoma therapies downstream. This cost structure is particularly evident in high-value checkpoint inhibitors and antibody-drug conjugates.
Pricing Analysis
Clinical outcome achievement for advanced disease anchors value-based pricing models for novel urothelial carcinoma treatments. The dominant pricing structure is a hybrid of value-based and per-unit transactional, often with tiered reimbursement. Price differentiation stems from demonstrated efficacy in specific patient cohorts and the therapy's regulatory approval status. Upward pricing pressure stems from the significant R&D investment required for innovative biologics. Healthcare systems and payers exhibit high price sensitivity, while patients with limited treatment options for metastatic disease are less sensitive.
Supply Chain Analysis
Direct-to-oncology clinic distribution models handle the primary flow of urothelial carcinoma treatments, ensuring specialized handling and administration. Geographic supply concentration for advanced biologics rests in the United States, Germany, and Japan due to specialized manufacturing capabilities. Raw material dependencies include complex active pharmaceutical ingredients and sterile single-use components. Single-source vulnerability for proprietary biologics represents a structural supply chain risk. Distribution runs through a highly controlled network of pharmaceutical distributors and hospital pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urothelial carcinoma treatment market is undergoing a technology-transition phase, with advanced biologics like checkpoint inhibitors and antibody-drug conjugates steadily displacing legacy chemotherapy regimens.
For Market Incumbents: Anchor existing market share by diversifying product pipelines into next-generation antibody-drug conjugates and gene therapies. Strategic partnerships for combination therapy development can mitigate the threat of emerging monotherapy specialists. Investment in R&D for biomarker-driven diagnostics and therapies will solidify market leadership. Control over specialized manufacturing capacity for biologics is a critical lever against supply chain disruptions.
For New Entrants and Emerging Players: Capture market share by targeting unmet needs in rare urothelial carcinoma subtypes or non-muscle invasive bladder cancer with novel intravesical delivery methods. Biomarker-defined patient cohorts with high unmet medical needs represent the most penetrable segment. A compelling go-to-market angle involves leveraging accelerated approval pathways with strong clinical data for targeted therapies.
For Investors and Strategic Acquirers: Phase 3 trial success for novel ADCs in specific urothelial carcinoma indications is the leading indicator that signals significant market potential. The long-term viability of the market remains strong for companies developing innovative, targeted therapies with clear clinical advantages. Biotech firms with late-stage asset candidates in immuno-oncology or gene therapy represent an attractive acquisition target archetype. Investors should monitor shifts in national reimbursement policies for high-cost oncology agents for early signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Diversification into ADCs | Expands therapeutic reach into new patient populations and enhances competitive differentiation. |
| Strategic Partnerships for Combination Therapies | Accelerates clinical development and broadens treatment options for resistant disease. |
| Focus on Accelerated Approval Pathways | Expedites market entry for therapies addressing high unmet needs in specific patient cohorts. |
| Investment in Biomarker-Driven Diagnostics | Enables precise patient selection, optimizing treatment efficacy and resource allocation. |
| Control over Specialized Biologic Manufacturing | Ensures supply stability and maintains quality standards for complex, high-value therapies. |
Research Approach
Regulatory agency filings, clinical trial registries, and pharmaceutical company disclosures anchored secondary inputs, complemented by primary interviews with oncology key opinion leaders and hospital formulary managers. This approach ensured comprehensive data collection, cross-referencing information from diverse sources. Primary research involved discussions with pharmaceutical R&D executives and payer reimbursement specialists. A robust bottom-up and top-down triangulation process validated all market estimates.
Market segmentation by product type, therapy area, and administration route defined the modeling granularity, reflecting clinical practice and patient needs. The analytical framework projected market dynamics across the analysis window, incorporating historical trends and anticipated shifts. Compound Annual Growth Rates were derived from a synthesis of market volume, value, and pricing trends. Key forecast inputs included incidence rates in aging populations, new drug approvals, and evolving reimbursement policy changes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to clinical trial results and regulatory shifts. These forecasts reflect assumptions about the pace of innovation and market adoption. Practitioners should monitor unforeseen clinical trial failures or major shifts in payer coverage policies for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Urology Forceps Market
Urology
Global Bladder Cancer Market
Urology
Urethral Stricture Market
Urology
Urology Lasers Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Ureterorenoscopes Market
Urology
Urology Surgery Supplies Market
Urology
Ureteral Catheters Market
Urology
Urology Disposables Market
Urology
Urinary Incontinence Market
Urology
Hematuria Treatment Market
Urology
Global Lithotripsy Market
Urology
LAMEA Transrectal Ultrasound Market
Urology
India Urology Device Market
Urology
Acute Pyelonephritis Treatment Market
Urology
Botulinum Toxin in Urology Market