
 Grand Mal Seizure Treatment Market | 2026-2036
Grand Mal Seizure Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Grand Mal Seizure Treatment Market Analytics
Digital biomarker integration and closed-loop neurostimulation algorithms are rewriting therapeutic protocols for seizure management. UCB Pharma leverages its deep heritage in epilepsy biologics to sustain leadership across European and North American prescribing networks. Novartis AG anchors its position through high R&D intensity in next-generation sodium channel modulators. Johnson & Johnson competes via its diversified neurotechnology portfolio spanning pharmaceuticals and implantable devices.
Grand mal seizure treatment encompasses pharmacological, surgical, and neuromodulation interventions designed to terminate or prevent generalized tonic-clonic seizures, with anticonvulsant plasma concentration monitoring serving as a critical therapeutic parameter for dose optimization. The primary purpose is to reduce seizure frequency, prevent status epilepticus, and restore functional capacity in patients with epilepsy or acute provoked seizures. Anticonvulsants dominate current prescribing volumes but face margin compression from generic penetration, while vagus nerve stimulators represent the fastest-growing hardware category as implantable therapy gains traction for drug-resistant populations. Hospitals capture the largest share of end-user value given their role in emergency stabilization and surgical candidacy assessment, though home care delivery modes are expanding with sublingual rescue formulations.
FDA orphan drug designations and EMA's priority medicines scheme shape development incentives for novel anticonvulsant entities, while the EU Medical Device Regulation imposes escalating clinical evidence requirements on implantable neurostimulation systems. HIPAA in the United States and GDPR in Europe constrain how digital seizure monitoring data flows between patients, providers, and device manufacturers. Stakeholders must monitor how reimbursement authorities weigh pharmacoeconomic evidence against clinical outcomes when positioning combination therapies against standalone surgical or device-based alternatives.
Market Dynamics
Closed-loop neurostimulation systems are compressing the therapeutic window between pharmacological failure and surgical intervention, forcing device manufacturers and pharmaceutical developers to coordinate clinical evidence strategies across previously siloed regulatory pathways.
Growth Catalysts
- FDA orphan drug designations:Accelerated approval timelines for rare epilepsy subtypes incentivize biotech investment in precision anticonvulsants targeting genetic channelopathies.
- Tertiary hospital EMU expansion:Dedicated epilepsy monitoring units in academic medical centers create captive demand for long-term video-EEG telemetry and responsive neurostimulation implants.
- Sodium channel modulator pipelines:Next-generation small molecules with improved CNS penetration profiles address refractory populations underserved by first-generation broad-spectrum agents.
Market Restraints
- Generic anticonvulsant saturation:Patent cliffs on established AEDs compress branded pricing power and erode R&D recovery timelines for follow-on compounds.
- Implantable device reimbursement lag:CMS and national health technology assessment bodies impose extended evidence requirements before covering vagus nerve and deep brain stimulation systems.
- Plasma concentration monitoring infrastructure gaps:Therapeutic drug monitoring capabilities concentrate in urban referral centers, limiting dose optimization in community settings.
Strategic Opportunities
- Home-based rescue therapy channels:Sublingual and intranasal benzodiazepine formulations bypass emergency department dependency for breakthrough seizure management.
- EMA priority medicines scheme alignment:Early engagement with adaptive licensing pathways compresses time-to-market for novel mechanisms addressing drug-resistant epilepsy.
- Digital biomarker convergence:Wearable seizure detection algorithms paired with automated therapy delivery create closed-loop systems outside institutional settings.
Industry Challenges
- Electrophysiology technician scarcity:Specialized expertise for intraoperative cortical mapping and device programming concentrates in major metropolitan clusters.
- Legacy EMR integration friction:Seizure detection devices generate high-frequency data streams that overwhelm standard hospital information architecture.
- Multisite clinical trial coordination:Rare disease trial networks require alignment across FDA, EMA, and PMDA evidentiary standards for neurostimulation endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grand Mal Seizure Treatment Market |
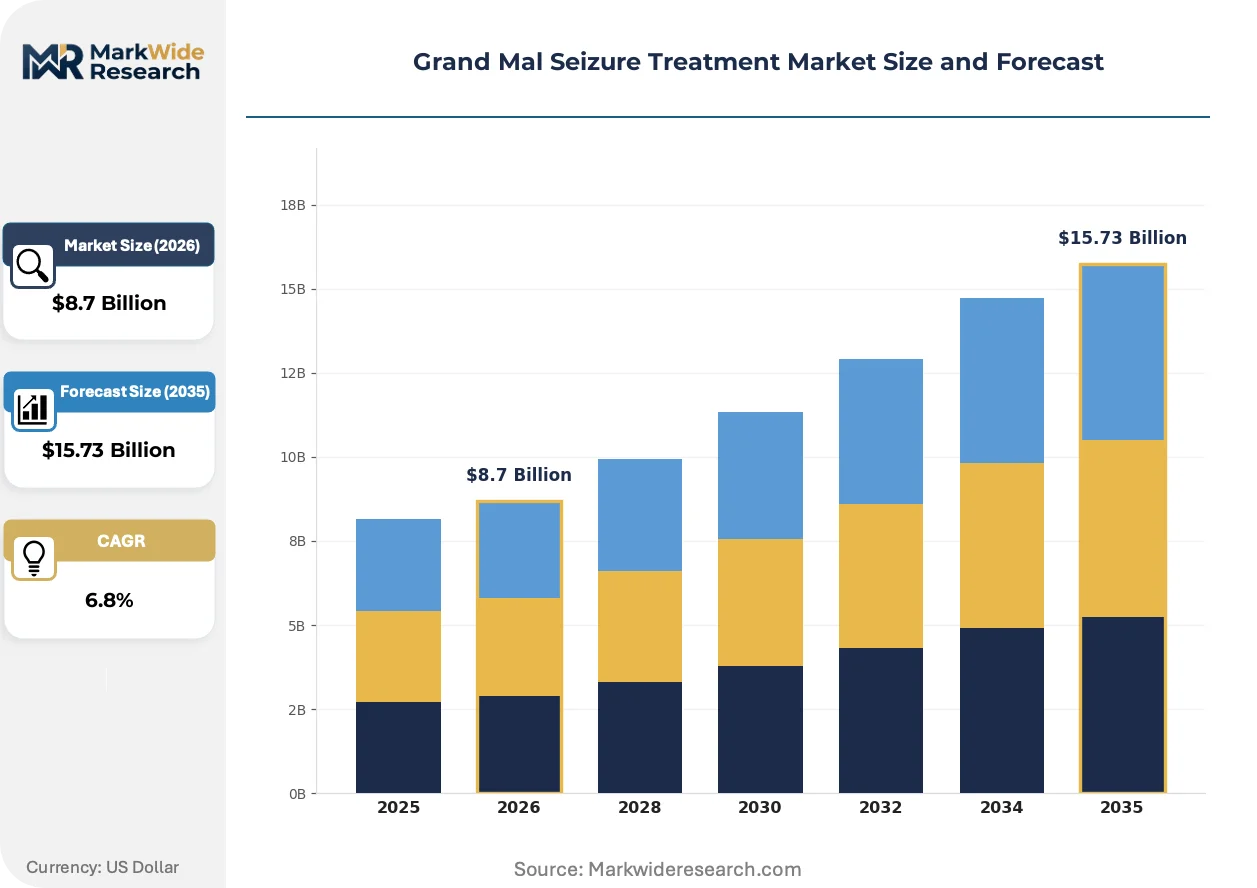
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticonvulsants, Surgical Interventions, Vagus Nerve Stimulators, Dietary Therapies End User: Hospitals, Outpatient Clinics, Rehabilitation Centers, Home Care Delivery Mode: Oral, Intravenous, Sublingual, Injectable Age Group: Pediatrics, Adults, Geriatrics, Others |
| Companies Covered | UCB Pharma, Novartis AG, Johnson & Johnson, Teva Pharmaceutical Industries Ltd., Pfizer Inc., Sanofi S.A., GlaxoSmithKline plc., Eisai Co. Ltd., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grand Mal Seizure Treatment Market Evolving Landscape
Algorithmic seizure prediction and automated therapy delivery are redrawing the boundary between acute intervention and chronic disease management in epilepsy care.
Responsive neurostimulation systems that detect electrical precursors and deliver targeted counter-stimulation are rendering obsolete the binary choice between chronic medication and irresective surgery. Pediatric and young adult populations with focal-onset generalized seizures drive early adoption in comprehensive epilepsy centers. Device manufacturers now compete on prediction latency and battery longevity rather than stimulation output alone.
EMA's Medical Device Regulation imposes escalating post-market surveillance obligations on implantable neurostimulation systems, compelling manufacturers to fund decade-long registries. Clinical evidence requirements now extend beyond safety to demonstrate sustained quality-of-life metrics against optimized medical management. European notified bodies prioritize cybersecurity validation for devices with wireless programming capabilities.
Hospital procurement committees increasingly bundle device implantation with multi-year remote monitoring service contracts, displacing traditional capital equipment purchasing. Academic medical centers in Germany and Japan pilot subscription models covering hardware, surgical placement, and algorithm updates. This shift compresses vendor selection criteria toward longitudinal service reliability and data interoperability.
Grand Mal Seizure Treatment Market Segmentation
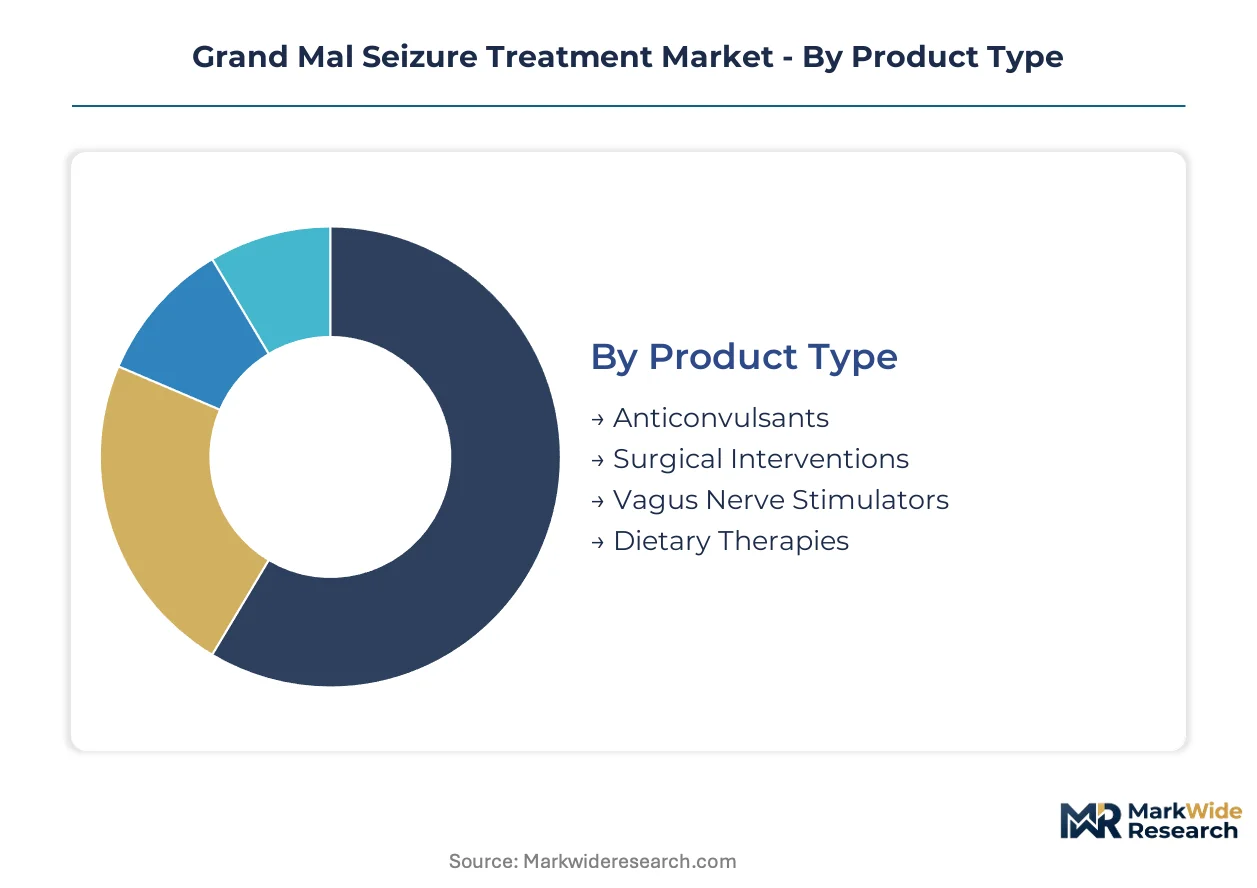
Grand mal seizure treatment markets fragment across therapeutic modality, care setting, and patient physiology, with each axis demanding distinct regulatory evidence and reimbursement negotiation. Understanding these segment boundaries enables manufacturers to align pipeline investments with addressable patient populations and provider procurement priorities.
Product Type:
Use-case spectrum spans acute termination, chronic prevention, and device-mediated neuromodulation for drug-resistant cases.
- Anticonvulsants:Small-molecule AEDs with established plasma concentration monitoring protocols dominate prescribing volumes across emergency and maintenance settings. Tertiary hospitals in the United States and Germany concentrate demand for branded next-generation sodium channel modulators as generic first-generation agents saturate community practice.
- Vagus Nerve Stimulators:Implantable pulse generators with closed-loop detection algorithms address refractory populations failing two or more drug regimens. Japan's PMDA and the FDA have compressed approval timelines for responsive neurostimulation systems, accelerating hospital EMU adoption for pediatric and young adult candidates.
- Surgical Interventions:Anterior temporal lobectomy and corpus callosotomy serve highly selected candidates with identifiable seizure foci.
- Dietary Therapies:Ketogenic and modified Atkins protocols supplement pharmacological management in pediatric epilepsy centers.
The dominant share belongs to anticonvulsants, while vagus nerve stimulators are closing the gap fastest.
End User:
Care delivery economics concentrate value capture where emergency stabilization capability intersects with surgical candidacy assessment.
- Hospitals:Academic medical centers with dedicated epilepsy monitoring units command premium reimbursement for video-EEG telemetry and intraoperative cortical mapping. CMS and Germany's national hospital reimbursement frameworks favor bundled payments covering device implantation with multi-year remote monitoring.
- Home Care:Sublingual benzodiazepine rescue formulations and wearable seizure detection systems bypass emergency department dependency for breakthrough events. HIPAA and GDPR compliance requirements constrain how patient-generated data flows to manufacturers and clinicians.
- Outpatient Clinics:Community neurology practices manage stable patients with therapeutic drug monitoring.
- Rehabilitation Centers:Post-surgical recovery and cognitive rehabilitation services address functional restoration.
Hospitals retain the value concentration, though home care is expanding most quickly as rescue therapy formulations mature.
Delivery Mode:
Route selection balances onset speed against patient autonomy and administration setting constraints.
- Intravenous:Fosphenytoin and levetiracetam infusions achieve therapeutic plasma levels within minutes for status epilepticus. Emergency departments in the United States and Japan maintain standardized protocols with pharmacy-driven dosing algorithms.
- Sublingual:Midazolam and diazepam orodispersible tablets enable caregiver-administered rescue without vascular access. EMA's priority medicines scheme has accelerated approvals for pediatric formulations, expanding addressable populations beyond institutional settings.
- Oral:Extended-release tablets and capsules support maintenance therapy with improved adherence profiles.
- Injectable:Intramuscular and subcutaneous depot formulations address adherence gaps in community settings.
Intravenous routes dominate acute intervention value, yet sublingual formats are gaining share fastest among outpatient and home-based protocols.
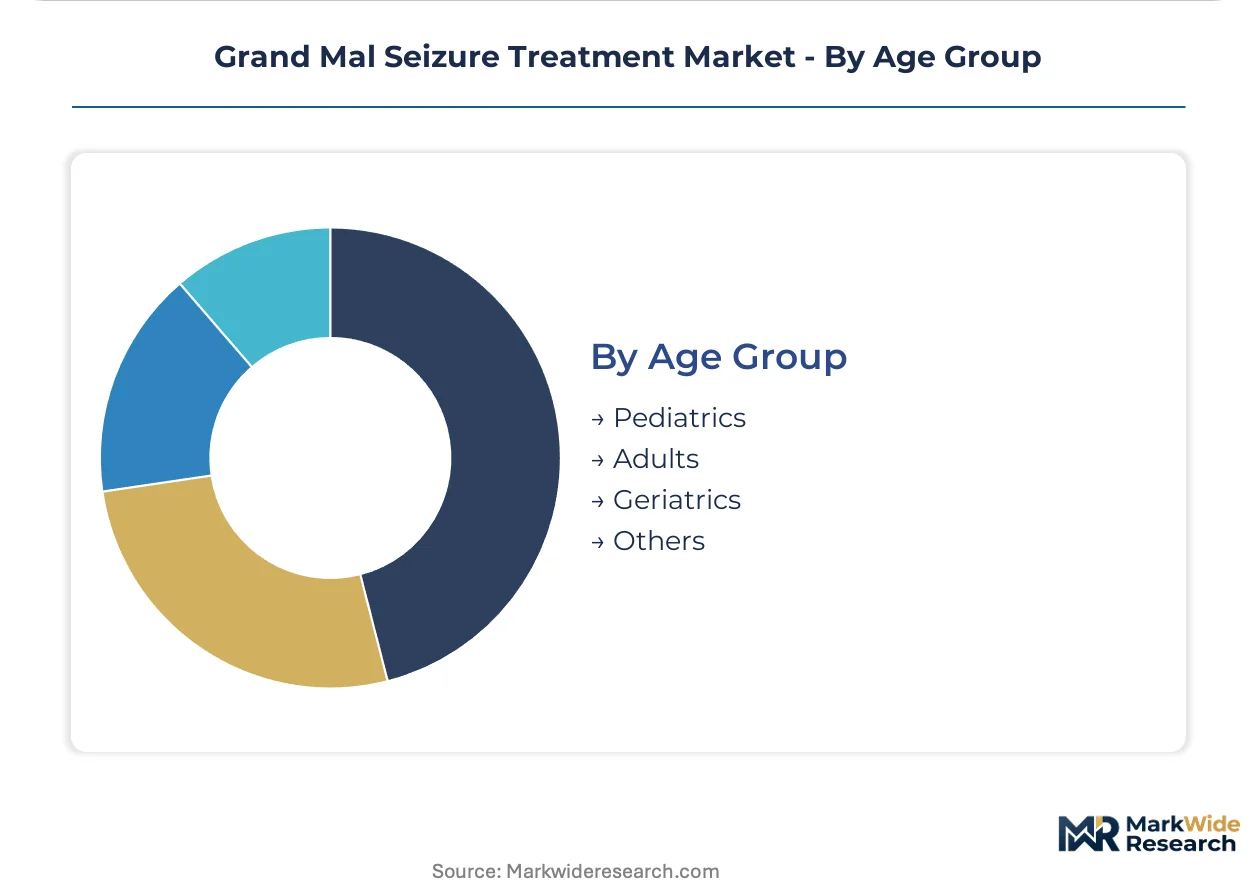
Age Group:
Developmental neurobiology and comorbidity burden reshape therapeutic risk-benefit calculations across the lifespan.
- Pediatrics:Genetic channelopathies and early-onset epileptic encephalopathies drive demand for precision anticonvulsants with orphan drug designations. FDA and EMA accelerated pathways have compressed development timelines for Dravet syndrome and Lennox-Gastaut syndrome indications.
- Geriatrics:Polypharmacy interactions and altered pharmacokinetics complicate AED selection in nursing home and assisted-living populations. Medicare Part D formularies and Japan's long-term care insurance schemes influence prescribing patterns for this expanding demographic.
- Adults:Occupational and driving restrictions create quality-of-life pressures favoring seizure freedom over medication minimization.
- Others:Pregnancy and perioperative categories require specialized teratogenicity and drug-interaction surveillance.
Pediatrics captures the innovation premium, while geriatrics is climbing the fastest as population aging reshapes prevalence demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, Germany, and Japan import specialized neurostimulation hardware while exporting anticonvulsant formulations and clinical trial expertise. Trade flows concentrate high-value device assembly in manufacturing clusters near regulatory agencies, with active pharmaceutical ingredients sourced from contract manufacturers across multiple jurisdictions.
United States
Academic medical centers in Boston and Baltimore operate the highest density of epilepsy monitoring units per capita. FDA orphan drug designations compress development timelines for precision anticonvulsants targeting Dravet syndrome and Lennox-Gastaut syndrome. The Mayo Clinic in Rochester anchors a referral network spanning forty states for surgical candidacy assessment.
Germany
University hospitals in Munich and Berlin maintain Europe's largest installed base of responsive neurostimulation systems. EMA's Medical Device Regulation imposes decade-long post-market surveillance obligations on implantable pulse generators. The Rhine-Ruhr metropolitan corridor concentrates electrophysiology technician training programs and device programming expertise.
Japan
PMDA accelerated approval pathways for pediatric epilepsy indications attract multinational trial investment. Tokyo and Osaka academic centers pioneer closed-loop algorithms for seizure prediction in geriatric populations. The country's long-term care insurance scheme expands reimbursement for home-based rescue therapy formulations.
United Kingdom
NHS England's specialized commissioning framework concentrates vagus nerve stimulator implantation in fifteen designated epilepsy surgery centers. GDPR compliance requirements constrain how wearable seizure detection data flows to manufacturers from patients in Greater London and Manchester. The National Institute for Health and Care Excellence evaluates pharmacoeconomic evidence for combination therapies against standalone device alternatives.
Switzerland
Swissmedic maintains alignment with EMA accelerated pathways while offering distinct pediatric trial incentives. Basel and Zurich host headquarters operations for firms developing next-generation sodium channel modulators. The country's hospital procurement committees increasingly bundle device implantation with multi-year remote monitoring service contracts.
Grand Mal Seizure Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around integrated neurotechnology portfolios that span pharmaceuticals and implantable devices. Large-cap diversified health conglomerates compete with mid-cap epilepsy specialists for prescribing network access. Two strategic archetypes dominate: biologics-focused developers with deep heritage in anticonvulsant mechanisms, and device manufacturers engineering closed-loop detection algorithms. Competitive moves center on clinical evidence coordination across previously siloed regulatory pathways and subscription-based service contracts displacing capital equipment purchasing.
Within the biologics heritage tier, UCB Pharma and Novartis AG exemplify firms leveraging decades of epilepsy therapeutic development to sustain leadership across European and North American prescribing networks. Johnson & Johnson occupies a diversified position spanning both pharmaceutical and implantable device segments. Eisai Co. Ltd. anchors Japanese-origin development with concentration in pediatric and geriatric indications. These three represent distinct geographic and modality strategies without overlapping core therapeutic focus.
| Leading Market Players |
|---|
| UCB Pharma |
| Novartis AG |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| Pfizer Inc. |
| Sanofi S.A. |
| GlaxoSmithKline plc. |
| Eisai Co. Ltd. |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Active pharmaceutical ingredient synthesis for sodium channel modulators clusters in contract manufacturers across India and China, concentrating margin capture with finished-dose formulators in the United States and Germany who command premium pricing for branded anticonvulsants. This upstream concentration amplifies pricing power for downstream innovators while exposing generic manufacturers to volatile input costs.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through multi-year bundled contracts covering device implantation, surgical placement, and algorithm updates. Three-tier pricing structure across premium, standard, and economy levels separates responsive neurostimulation systems from conventional vagus nerve stimulators and generic anticonvulsant portfolios. Cost compression in first-generation AED categories is intensifying because patent cliffs have eroded exclusivity periods. Community neurology practices exhibit the highest price sensitivity, while academic medical centers with dedicated epilepsy monitoring units prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Upstream feedstock for implantable pulse generators draws from specialized semiconductor foundries in Taiwan, precision battery cell manufacturers in South Korea, and biocompatible polymer suppliers in Germany. Raw material dependencies center on lithium-ion cells for device power management, platinum-iridium alloys for electrode contacts, and medical-grade silicone for encapsulation. Single-source vulnerability in responsive neurostimulation algorithm licensing creates concentration risk for device manufacturers. Distribution runs through hospital procurement committees and group purchasing organizations that aggregate demand across health system networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital systems and integrated delivery networks that command volume-based discounts across pharmaceutical and device categories. This consolidation fragments negotiating leverage for standalone manufacturers.
For Market Incumbents: Harden formulary defense through captive supply of active pharmaceutical ingredients and backward integration into therapeutic drug monitoring infrastructure. Deepen clinical evidence coordination across FDA and EMA regulatory pathways to compress competitor approval timelines. The priority lever rests on subscription-based service contracts that displace capital equipment purchasing and lock in multi-year revenue visibility. For New Entrants and Emerging Players: Home-based rescue therapy channels in Japan and Germany represent the most penetrable entry point for sublingual benzodiazepine formulations bypassing emergency department dependency. Pediatric genetic channelopathies with orphan drug designation pathways offer accelerated regulatory access with premium pricing potential. A direct-to-clinician digital marketing approach paired with wearable seizure detection integration provides the most viable go-to-market angle against entrenched hospital sales forces. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed neuromodulation device platforms seeking algorithmic capability additions. The five-to-ten year viability window favors developers with responsive neurostimulation regulatory clearances and established hospital EMU relationships. Acquisition targets with closed-loop detection patents and pediatric indication expansions command strategic premium. Watch FDA breakthrough device designations for seizure prediction algorithms as the inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA accelerated pathways compress development timelines for Dravet syndrome indications. |
| Responsive Neurostimulation Algorithm Licensing | Closed-loop seizure prediction capabilities differentiate device portfolios in EMU procurement. |
| Hospital System Partnership | Academic medical centers in Boston and Munich anchor referral networks for surgical candidacy. |
| Reimbursement Strategy Development | CMS bundled payment frameworks favor multi-year remote monitoring service contracts. |
| Software Companion Development | Wearable seizure detection algorithms paired with therapy delivery expand addressable populations. |
Research Methodology
A standing panel of epilepsy monitoring unit directors, neurostimulation device programming specialists, hospital formulary directors, and anticonvulsant regulatory affairs leads provided ongoing calibration across primary research phases. Secondary validation drew from FDA 510(k) filings, EMA priority medicines scheme decisions, ClinicalTrials.gov pediatric epilepsy entries, and CMS Medicare reimbursement databases. Bottom-up prescribing volume estimates triangulated against top-down manufacturer revenue disclosures.
Scenario-bracketing around generic anticonvulsant saturation rates and neurostimulation implant adoption curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include therapeutic modality, care setting, delivery route, and patient age group, with regional regulatory clusters capturing FDA, EMA, and PMDA pathway differentiation. CAGRs derived from patient prevalence projections, treatment penetration assumptions, and pricing trajectory scenarios. Forecast inputs incorporated tertiary hospital EMU expansion plans and orphan drug designation approval velocities.
Practitioners should monitor FDA breakthrough device designations and EMA accelerated assessment outcomes for early signals of competitive timeline compression. Forecasts reflect assumptions regarding reimbursement continuity for implantable systems and generic substitution rates for maintenance anticonvulsants. Cross-checking against hospital procurement database trends and GPO contract award patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Occipital Nerve Block Treatment Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Asia-Pacific Neurology Monitoring Market
Neurology
Pediatric Neurology Device Market
Neurology
Traumatic Brain Injuries (TBI) Treatment Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
Olivopontocerebellar Atrophy Treatment Market
Neurology
Italy Neurology Devices Market
Neurology
United States Neurology Devices Market
Neurology
Tourette Syndrome Market
Neurology
Hepatic Encephalopathy Market
Neurology
Mexico Neurology Devices Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Arachnoiditis Treatment Market
Neurology
Neurological Biomarkers Market
Neurology
CNS Therapeutics Market