
 Global Hydronephrosis Market | 2026-2036
Global Hydronephrosis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydronephrosis Market Foresight
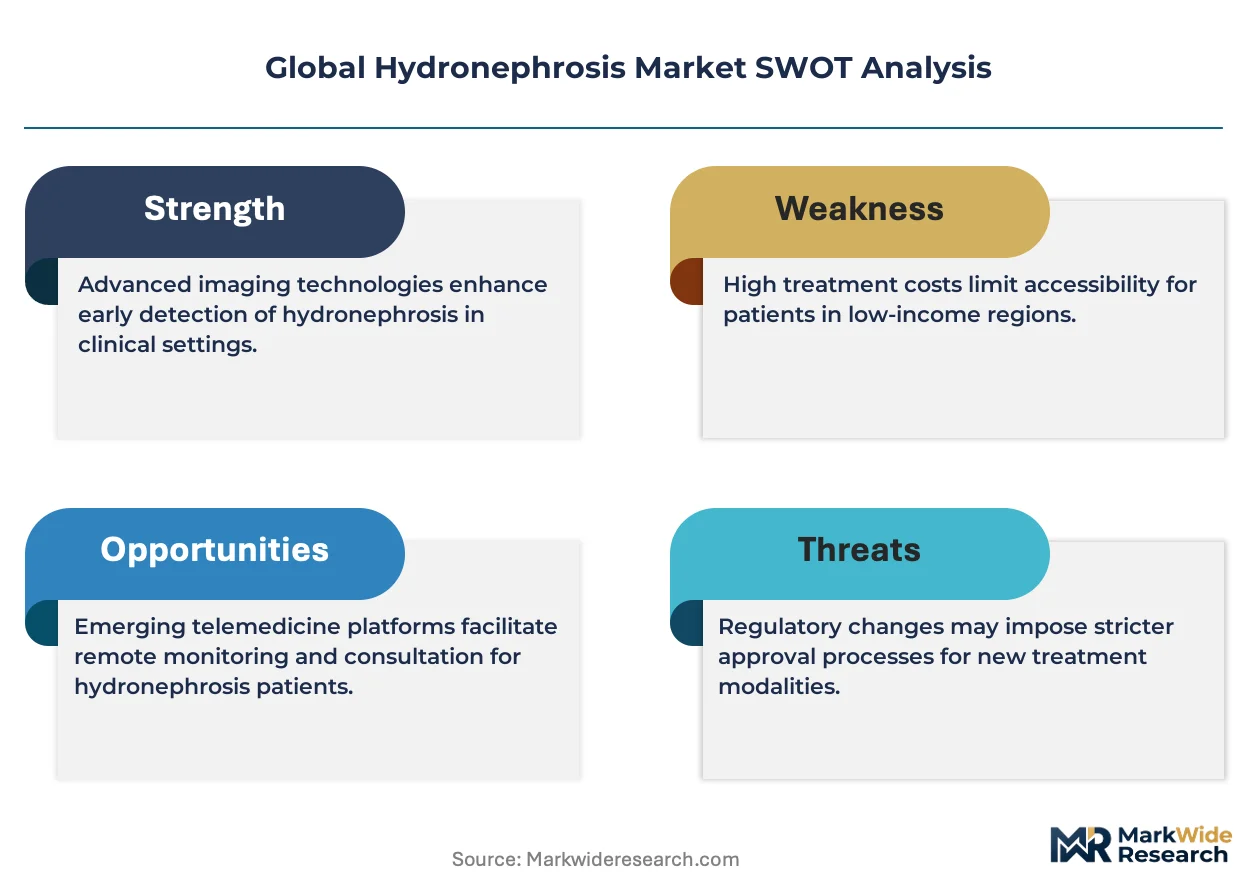
Multi-source procurement of ureteral stents and nephrostomy tubes is recalibrating how hospital systems manage infection risk and supply continuity. Boston Scientific Corporation leverages its endourology portfolio breadth to anchor contracted supply relationships with large urology service networks. Medtronic PLC competes through sustained manufacturing scale in balloon catheter platforms across North American and European acute care settings. Baxter International Inc. differentiates via specialized fluid management systems that integrate with percutaneous drainage workflows in tertiary centers.
Hydronephrosis denotes pathological dilation of the renal pelvis and calyces due to impaired urine outflow, typically quantified by anteroposterior pelvic diameter exceeding 10 millimeters on ultrasound or cross-sectional imaging. The condition demands intervention to preserve glomerular filtration rate and prevent cortical thinning through decompression of the collecting system. Diagnostic ultrasound systems occupy the largest installed base among product categories given their role in first-line screening across emergency and obstetric settings. Ureteral stents represent the fastest-expanding segment as metal and biodegradable platforms displace polymer-only designs in complex obstructive uropathy. Ambulatory surgical centers are capturing disproportionate procedure volume growth as same-day ureteroscopic and percutaneous interventions displace inpatient admissions.
FDA quality system regulation and EU MDR conformity requirements are elevating biocompatibility testing burdens and clinical evidence thresholds for nephrostomy tube and stent manufacturers seeking market access. ISO 13485 certification has become a baseline procurement filter for health system tenders across Japan, Germany, and the United States rather than a competitive differentiator. WHO prequalification pathways are expanding relevance for manufacturers targeting public procurement in lower-middle-income health systems. Stakeholders must monitor how reimbursement coding refinements for telemedicine-integrated hydronephrosis monitoring reshape site-of-care economics and device selection criteria.
Market Dynamics
EU MDR biocompatibility mandates and FDA quality system tightening are forcing synchronized product refresh cycles across nephrostomy tube and ureteral stent portfolios, compressing development timelines while elevating clinical evidence thresholds.
Growth Catalysts
- Ambulatory surgical center expansion:Same-day ureteroscopic and percutaneous interventions are capturing procedure volume from inpatient admissions across United States health systems. CMS reimbursement coding refinements for outpatient obstructive uropathy management accelerate this shift.
- REACH-compliant polymer innovation:Biodegradable stent platforms incorporating polycaprolactone and polylactic acid copolymers are displacing permanent polymer implants in complex cases. EU MDR substance restriction protocols favor these compositions.
- Telemedicine-integrated monitoring:Remote renal pelvis dilation tracking via connected ultrasound systems is expanding post-intervention surveillance capacity. Japan's METI digital health reimbursement pilots validate this care model.
Market Restraints
- Silicone raw material concentration:Medical-grade silicone supply chains cluster in Northeast Asian chemical manufacturing zones, exposing stent and catheter producers to input volatility and logistics disruption.
- ISO 13485 certification timeline:Extended audit backlogs at notified bodies under EU MDR implementation delay market entry for mid-tier manufacturers by 12-18 months.
- Metal stent substitution pressure:Resorbable polymer platforms threaten cobalt-chromium and nitinol ureteral stent segments in non-malignant obstruction cases.
Strategic Opportunities
- India CDSCO fast-track pathways:Accelerated approval mechanisms for devices with prior US FDA or EU MDR clearance open public procurement access in lower-middle-income health systems.
- AI-integrated ultrasound diagnostics:Machine learning algorithms for automated anteroposterior pelvic diameter measurement are converging with portable imaging hardware. WHO prequalification expansion creates procurement channels.
- Single-use nephrostomy kits:Procedure-specific disposable bundles reduce sterilization infrastructure dependence. Brazil's ANVISA simplified registration for sterile procedure kits enables market entry.
Industry Challenges
- Interventional urology fellowship pipeline:Training program capacity constraints in Germany and Japan limit deployment of advanced endourology techniques despite device availability.
- Legacy EHR integration:Percutaneous drainage workflow data from Baxter and Medtronic systems requires custom middleware to interface with Epic and Cerner installations, extending sales cycles.
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization study queues at contract research organizations delay regulatory submission timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydronephrosis Market |
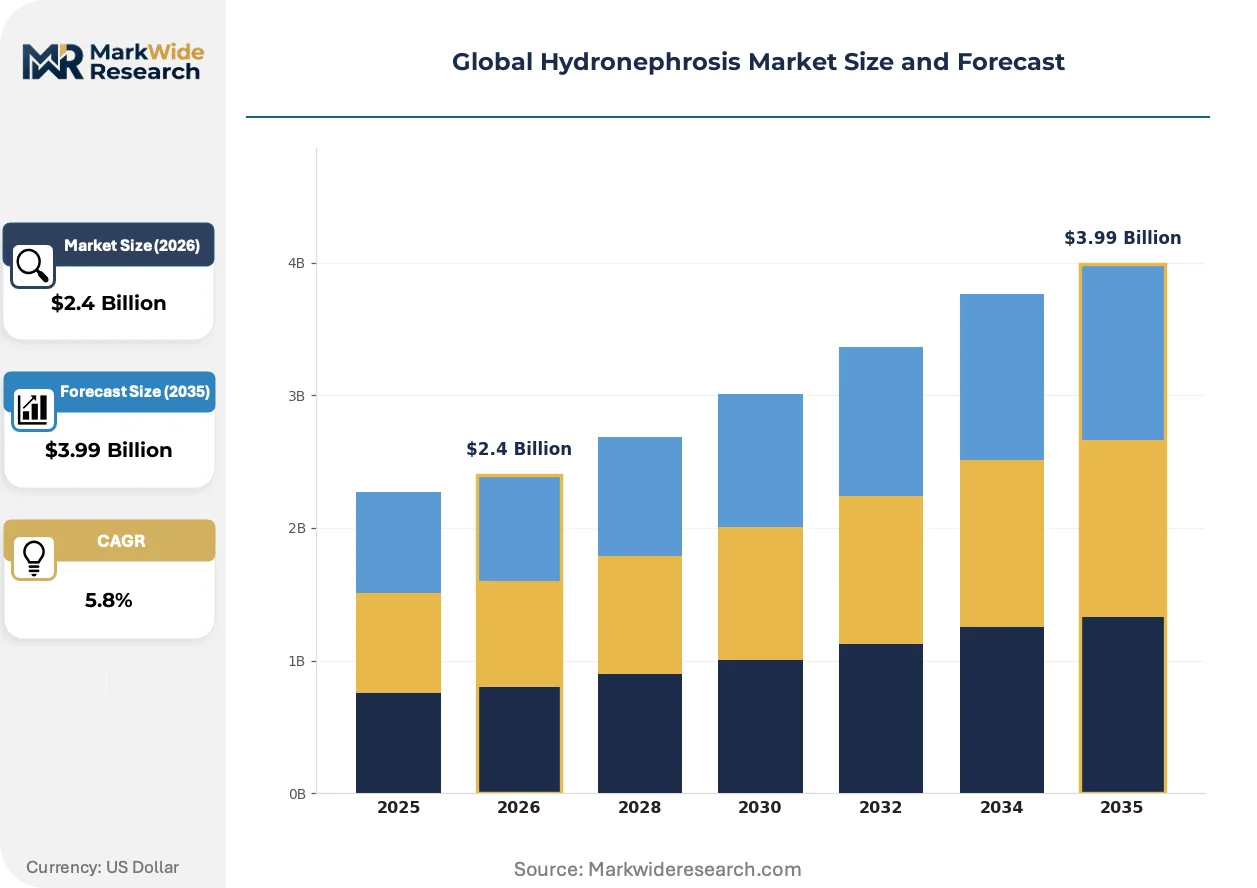
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Ultrasound Systems, Ureteral Stents, Nephrostomy Tubes, Balloon Catheters Therapy Area: Obstructive Uropathy, Urinary Tract Infection, Kidney Stone Complications, Congenital Anomalies End User: Specialty Clinics, Urology Centers, Diagnostic Laboratories, Ambulatory Surgical Centers Deployment: Inpatient Facilities, Outpatient Clinics, Home Healthcare Settings, Telemedicine Platforms |
| Companies Covered | Boston Scientific Corporation, Medtronic PLC, Novartis AG, Amgen Inc., F. Hoffmann-La Roche Ltd, Baxter International Inc., Stryker Corporation, B. Braun Melsungen AG, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydronephrosis Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization pressures are compressing product development cycles while redrawing competitive boundaries across drainage intervention portfolios.
Bioresorbable ureteral stents incorporating tyrosine-derived polycarbonates are electrifying clinical trial pipelines for complex obstructive uropathy. Tertiary urology centers in Germany and Japan are piloting these platforms for malignant stricture cases where retrieval risks exceed polymer degradation timelines. The technology is electrifying stent selection criteria by eliminating secondary retrieval procedures and their associated anesthesia exposures.
FDA's updated guidance on biocompatibility testing for permanent implants requires expanded cytotoxicity panels and systemic toxicity studies for nitinol-containing devices. This elevates preclinical investment thresholds for metal stent manufacturers while creating compliance differentiation for polymer-only portfolios. United States market access timelines for cobalt-chromium platforms now extend 8-12 months beyond comparable polymer submissions.
Hospital system value analysis committees are consolidating ureteral stent and nephrostomy tube contracts under single-source agreements with infection rate guarantees. Integrated delivery networks in the United States are displacing multi-vendor purchasing with outcome-linked supply partnerships. Germany's university hospital clusters demonstrate this pattern most visibly, where procurement centralization reduced vendor counts by 40 percent across drainage intervention categories.
Global Hydronephrosis Market Segmentation
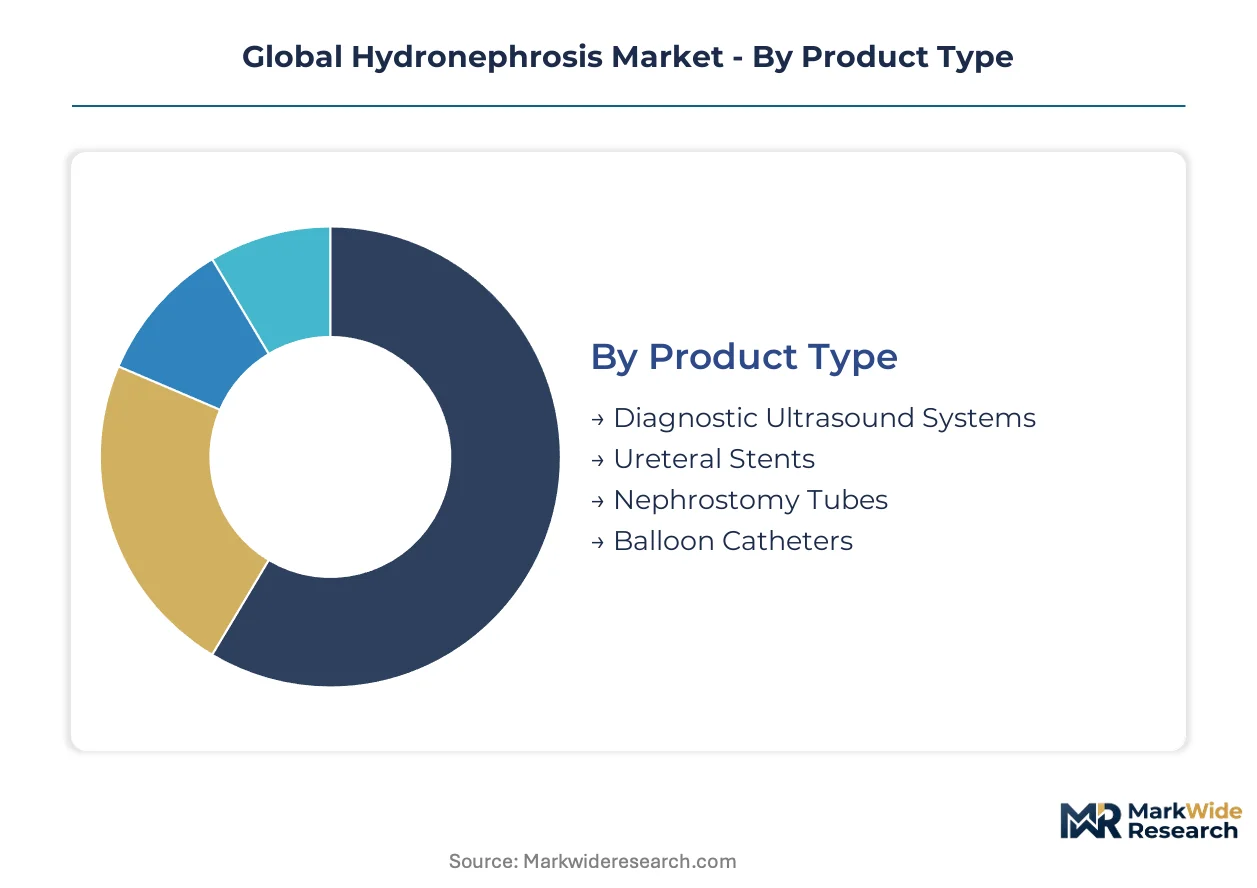
Segmentation in hydronephrosis interventions reveals how technology specifications, clinical settings, and reimbursement pathways fragment procurement decisions across health systems. Device selection criteria diverge sharply between emergency decompression scenarios and elective obstructive uropathy management.
Product Type:
Material composition and biocompatibility certification status differentiate competitive positioning across drainage intervention portfolios.
- Diagnostic Ultrasound Systems:Portable and cart-based imaging platforms with automated anteroposterior pelvic diameter measurement algorithms dominate first-line screening workflows. Emergency departments in the United States and obstetric units in Germany represent the largest installed base, constrained by radiologist staffing shortages that favor AI-assisted interpretation.
- Ureteral Stents:Double-J polymer designs, metal mesh platforms, and emerging biodegradable compositions compete for placement in malignant and benign stricture cases. Ambulatory surgical centers in Japan are displacing polymer-only selections with resorbable alternatives that eliminate retrieval anesthesia exposures.
- Nephrostomy Tubes:Percutaneous drainage catheters with locking loop mechanisms and radiopaque markers enable fluoroscopy-guided placement in interventional radiology suites.
- Balloon Catheters:High-pressure dilatation platforms address ureteral stricture recanalization alongside primary drainage functions in tertiary urology centers.
Mature deployment sits with diagnostic ultrasound systems. Newer deployment is concentrated in biodegradable ureteral stent platforms.
Therapy Area:
Procedure reimbursement coding and intervention urgency shape device selection intensity across clinical indications.
- Obstructive Uropathy:Benign prostatic hyperplasia, pelvic malignancy compression, and retroperitoneal fibrosis drive stent and nephrostomy tube utilization. United States CMS coding for malignant obstruction carries higher reimbursement tiers than benign etiologies, influencing site-of-care decisions.
- Urinary Tract Infection:Pyonephrosis and infected hydronephrosis demand urgent decompression with antibiotic-impregnated catheter materials. German hospital antibiotic stewardship protocols favor silver-alloy nephrostomy tubes in sepsis-risk presentations.
- Kidney Stone Complications:Staghorn calculus obstruction and post-lithotripsy steinstrasse generate temporary stent placements.
- Congenital Anomalies:Ureteropelvic junction obstruction and vesicoureteral reflux in pediatric populations require size-adapted device platforms.
Volume concentration aligns with obstructive uropathy. Steepest expansion trajectory appears in infection-complicated interventions with antimicrobial device coatings.
End User:
Capital equipment requirements and sterilization infrastructure availability determine addressable market boundaries.
- Specialty Clinics:Urology-focused outpatient facilities without inpatient admitting privileges rely on referral networks for complex drainage procedures. India's tier-2 cities are witnessing clinic consolidation into multi-specialty platforms with basic endourology capabilities.
- Urology Centers:Dedicated surgical facilities with fluoroscopy suites and flexible ureteroscope inventories capture complex stone and stricture cases. Japan's metropolitan hospital clusters demonstrate highest per-capita utilization of metal stent platforms.
- Diagnostic Laboratories:Imaging-only facilities without interventional capability generate ultrasound referrals to procedural sites.
- Ambulatory Surgical Centers:Same-day discharge protocols and lower facility fees attract elective stent placements from hospital outpatient departments.
Revenue density clusters in urology centers. Gaining share fastest are ambulatory surgical centers capturing migration from inpatient settings.
Deployment:
Reimbursement parity and remote monitoring infrastructure maturity dictate site-of-care evolution.
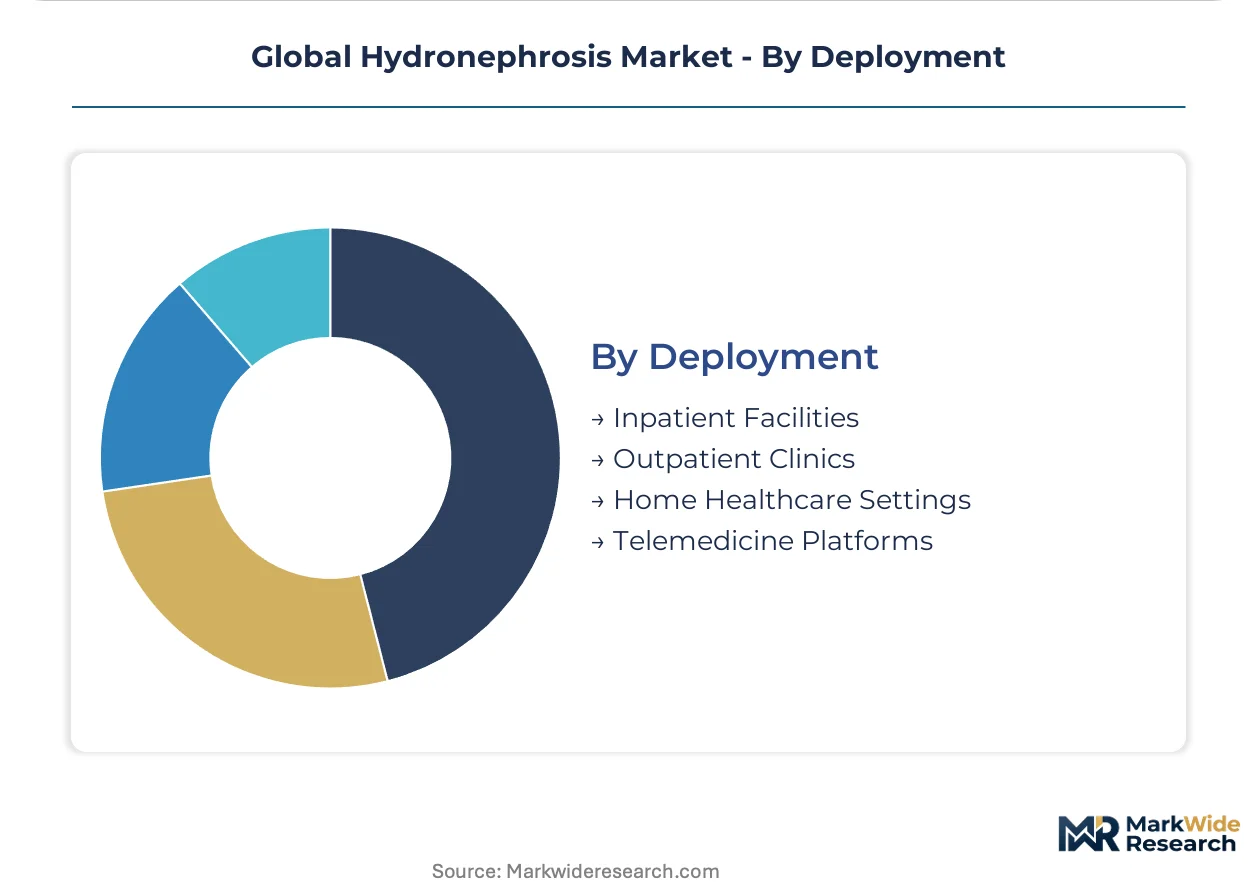
- Inpatient Facilities:Acute care hospitals manage sepsis, anuria, and complex multi-system presentations requiring anesthesia-supported interventions. Germany's DRG-based reimbursement preserves inpatient preference for high-comorbidity patients.
- Outpatient Clinics:Office-based cystoscopy and stent exchange procedures reduce total episode cost. United States commercial payer prior authorization requirements increasingly favor outpatient site selection.
- Home Healthcare Settings:Long-term indwelling nephrostomy tube management and irrigation protocols extend care beyond facility walls.
- Telemedicine Platforms:Remote renal pelvis dilation monitoring and post-intervention symptom triage expand surveillance capacity.
Procedure volume remains anchored in inpatient facilities. Emerging deployment concentrates in telemedicine-integrated monitoring pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where reimbursement pathways for obstructive uropathy interventions have matured. These markets anchor procedure volume and device procurement intensity across the forecast window. Each geography presents distinct regulatory and infrastructure configurations.
United States
CMS reimbursement coding refinements for outpatient obstructive uropathy management accelerate ambulatory surgical center expansion. FDA quality system regulation elevates biocompatibility testing burdens for nephrostomy tube and stent manufacturers. Integrated delivery networks in metropolitan hospital clusters displace multi-vendor purchasing with outcome-linked supply partnerships.
Germany
University hospital clusters demonstrate procurement centralization that reduced vendor counts by 40 percent across drainage intervention categories. EU MDR conformity requirements compress development timelines while elevating clinical evidence thresholds. Tertiary urology centers in metropolitan regions pilot bioresorbable stent platforms for malignant stricture cases.
Japan
Metropolitan hospital clusters demonstrate highest per-capita utilization of metal stent platforms. METI digital health reimbursement pilots validate telemedicine-integrated renal pelvis dilation monitoring. PMDA regulatory pathways favor devices with established EU MDR or US FDA clearance for accelerated market access.
India
Tier-2 cities witness clinic consolidation into multi-specialty platforms with basic endourology capabilities. CDSCO fast-track pathways for devices with prior US FDA or EU MDR clearance open public procurement access. Maharashtra and Karnataka host emerging urology service networks capturing domestic demand.
Brazil
ANVISA simplified registration for sterile procedure kits enables market entry for single-use nephrostomy bundles. Southeast regional hospital systems expand minimally invasive drainage intervention capacity. São Paulo anchors diagnostic ultrasound system deployment for first-line hydronephrosis screening.
Global Hydronephrosis Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers synchronize product refresh cycles across nephrostomy tube and ureteral stent portfolios. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with endourology breadth, specialized interventional urology device manufacturers, and fluid management system integrators. M&A activity and strategic partnerships represent the dominant competitive moves as firms address EU MDR biocompatibility mandates and FDA quality system tightening.
Within the diversified conglomerate tier, Boston Scientific Corporation and Medtronic PLC exemplify scale-driven positioning through sustained manufacturing presence across North American and European acute care settings. Baxter International Inc. occupies a specialized position via fluid management system integration with percutaneous drainage workflows. These three entities anchor competitive dynamics as health system value analysis committees consolidate contracts under single-source agreements with infection rate guarantees.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic PLC |
| Novartis AG |
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd |
| Baxter International Inc. |
| Stryker Corporation |
| B. Braun Melsungen AG |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Medical-grade silicone feedstock originating from Northeast Asian chemical manufacturing zones cascades through polymer compounding, extrusion molding, and sterilization validation stages before reaching hospital procurement tiers. This input concentration grants pricing leverage to compounders with captive silicone supply, while device assemblers without backward integration face margin compression during raw material volatility episodes.
Pricing Analysis
High-volume contract purchasers extract per-unit discounts exceeding smaller health system buyers, while premium-tier manufacturers command price premiums through ISO 13485 certification and EU MDR conformity documentation. Pricing stratifies across premium, standard, and economy tiers based on biocompatibility testing depth and after-sales clinical support bundling. Cost compression in economy-tier polymer stents intensifies because of Indian and Brazilian manufacturers expanding export capacity. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, whereas German university hospital clusters prioritize infection-rate guarantees over unit cost.
Supply Chain Analysis
Medical-grade silicone supply rests on Japanese and South Korean specialty chemical producers, with compounding operations concentrated in China and Malaysia for cost-optimized tiers. Nitinol wire drawing for metal stent platforms draws from United States and European shape-memory alloy specialists, while biodegradable polymer resins feed from German and Dutch biopolymer innovators. Single-source vulnerability concentrates in silicone precursor manufacturing, where three producers control majority capacity. Distribution runs through regional medical device distributors with sterilization infrastructure, bypassing direct-to-hospital models for mid-tier manufacturers lacking logistics scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydronephrosis intervention landscape sits in a material-science transition, with bioresorbable polymer platforms displacing permanent metal and polymer implants across complex obstructive uropathy indications.
For Market Incumbents: Deploy manufacturing scale leverage to absorb EU MDR biocompatibility testing cost inflation while accelerating biodegradable stent platform launches. Boston Scientific Corporation and Medtronic PLC should consolidate polymer resin supply through long-term offtake agreements with German biopolymer specialists, insulating against silicone raw material volatility. Incumbents must defend metal stent revenue streams by emphasizing malignant stricture durability data where resorbable alternatives underperform. For New Entrants and Emerging Players: CDSCO fast-track pathways in India open a window for mid-tier manufacturers with prior FDA or MDR clearance to capture public procurement share in Maharashtra and Karnataka urology networks. Target ambulatory surgical center supply partnerships in United States metropolitan markets, where same-day discharge protocols favor innovative stent platforms eliminating retrieval anesthesia. Pursue WHO prequalification for AI-integrated ultrasound diagnostics to access lower-middle-income health system tenders. For Investors and Strategic Acquirers: FDA submission of bioresorbable stent platforms with tyrosine-derived polycarbonate compositions is the leading indicator that material-science differentiation is reaching commercial inflection. Focus acquisition screening on specialized interventional urology device manufacturers with EU MDR technical documentation already compiled, avoiding 12-18 month certification timeline penalties. Watch Japan METI digital health reimbursement pilot expansion as the signal for telemedicine-integrated monitoring monetization viability.| Strategic Initiative | Industry Significance |
|---|---|
| Bioresorbable Stent Platform Launch | Eliminates secondary retrieval procedures, reducing anesthesia exposure in Japanese and German tertiary centers. |
| EU MDR Technical Documentation Investment | Accelerates market access timelines by 12-18 months versus competitors without notified body engagement. |
| Silicone Resin Backward Integration | Insulates margin structure against Northeast Asian chemical manufacturing zone supply disruptions. |
| AI-Integrated Ultrasound WHO Prequalification | Unlocks procurement channels in lower-middle-income health systems with radiologist staffing shortages. |
| Ambulatory Surgical Center Supply Partnership | Captures volume migration from inpatient settings under United States CMS outpatient reimbursement coding. |
Research Methodology
Regulatory filings with FDA and EMA, hospital procurement databases, and GPO contract repositories formed the secondary backbone for device utilization and pricing intelligence. Primary interviews with interventional urologists, biomedical engineers, hospital purchasing committee members, and GPO contracts managers validated secondary estimates across United States, German, and Japanese health systems. Bottom-up and top-down triangulation reconciled procedure volume estimates with manufacturer shipment data.
Bottom-up modeling anchored forecast outputs, with top-down macroeconomic and demographic cross-checks applied across the analysis window. Segmentation dimensions included material composition, therapy area severity, end-user facility type, and deployment site-of-care. CAGRs derived from procedure volume growth rates, reimbursement pathway maturation, and technology substitution curves for biodegradable versus permanent stent platforms.
The model assumes a particular technology adoption path; alternative pathways for bioresorbable polymer degradation kinetics would alter the outlook for metal stent displacement timelines. Forecasts reflect assumptions regarding EU MDR implementation pace, silicone supply chain stability, and ambulatory surgical center reimbursement parity. A small set of named triggers—FDA biocompatibility guidance updates, Japan METI digital health pilot expansion, and Indian CDSCO fast-track pathway modifications—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Asia-Pacific Bladder Disorders Market
Urology
Urinary Incontinence Therapeutics Market
Urology
India Urology Device Market
Urology
Europe Urology Devices Market
Urology
Urinary Bag Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Global Bladder Cancer Therapeutics Market
Urology
Prostate Cancer Treatment Market
Urology
Urinary Tract Infection (UTI) Market
Urology
Global Benign Prostatic Hyperplasia Treatment Market
Urology
Male Urinary Incontinence Market
Urology
Prostate Cancer Minimally Invasive Surgery Market
Urology
Urinary Incontinence Market
Urology
Single Use Cystoscope Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Hematuria Treatment Market